
 Heat-Stable Fruit Fillings Market | 2026-2036
Heat-Stable Fruit Fillings Market Size, Share, and Industry Trends Forecast 2026-2036
Heat-Stable Fruit Fillings Market Foresight
Pectin is repositioning heat-stable fruit fillings away from modified starch systems across premium bakery lines. Puratos Group leverages its global R&D network to sustain formulation leadership in reduced-sugar fruit preparations. Dawn Food Products anchors North American supply through its specialized bakery ingredient distribution infrastructure. Agrana Group differentiates via vertical control over fruit sourcing and processing.
Heat-stable fruit fillings are thermally processed fruit preparations engineered to withstand baking temperatures exceeding 180°C without syneresis or structural collapse, typically incorporating pectin, starch, or gum stabilizers at 15-35% soluble solids to maintain viscosity and water-binding capacity during oven exposure. Their primary commercial purpose is to deliver consistent fruit identity, color retention, and shelf stability in finished goods subjected to thermal processing. Ready-to-use formulations command the largest volume share as industrial bakeries prioritize labor reduction and batch consistency. Concentrated variants represent the fastest-growing product type where freight cost reduction and dilution flexibility drive procurement decisions. Bakery applications generate the dominant revenue pool, though confectionery and dairy segments are expanding as manufacturers seek cross-category fruit ingredient platforms.
FDA GRAS standards govern stabilizer and preservative use in U.S. fruit filling formulations, while EU F-Gas Regulation and REACH compliance constrain thermal processing equipment and chemical inputs for European production. EFSA additive evaluations periodically restrict specific hydrocolloid applications, forcing reformulation investments across export-oriented suppliers. Stakeholders must monitor evolving clean-label certification requirements and thermal processing energy standards as dual constraints on formulation flexibility and manufacturing cost structures.
Market Dynamics
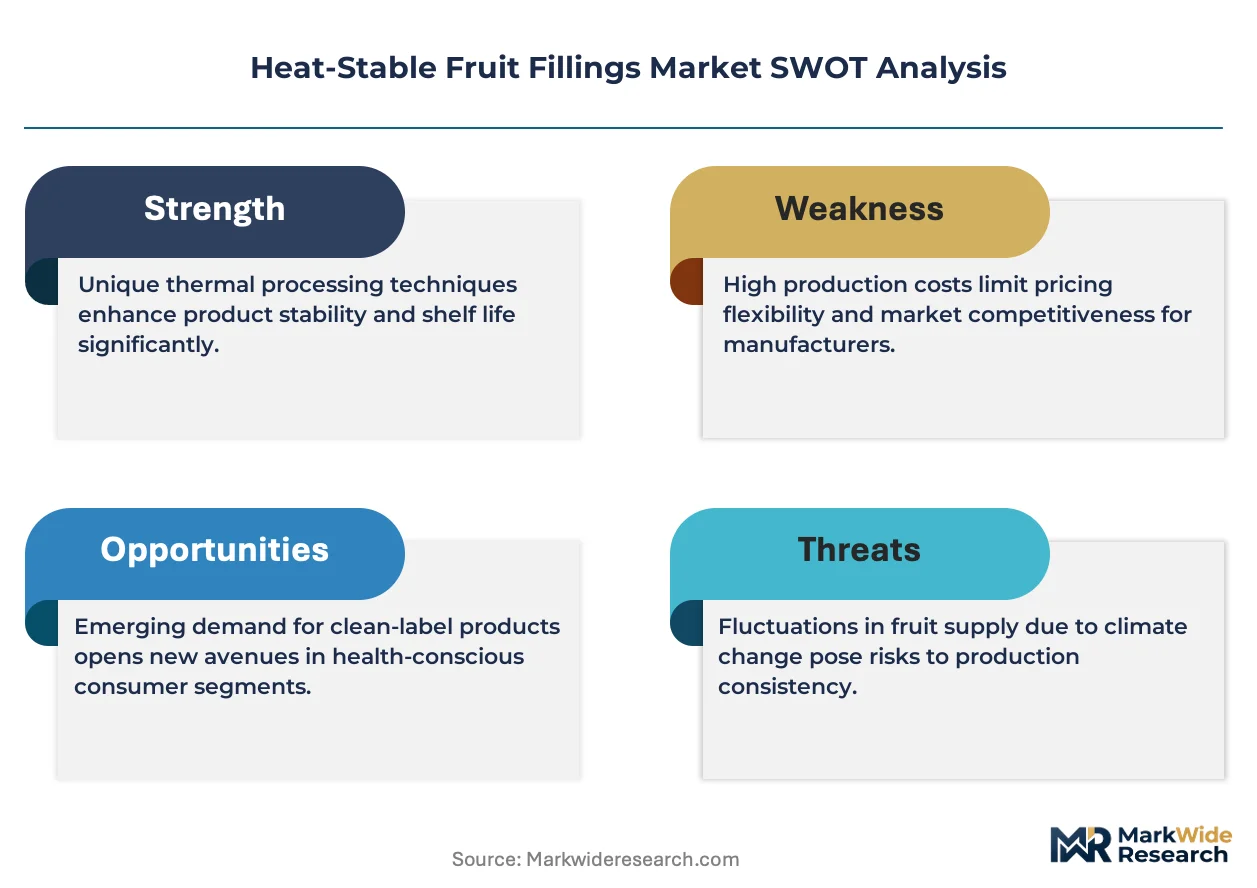
Pectin-based stabilization systems are displacing modified starch formulations across premium bakery lines, compressing formulation margins while forcing ingredient suppliers to recalibrate R&D priorities around clean-label compliance and thermal performance benchmarks.
Growth Catalysts
- EU F-Gas Regulation:Thermal processing equipment upgrades in European facilities are accelerating adoption of energy-efficient retort systems that improve filling stability during high-temperature exposure.
- Industrial Bakery Procurement:Labor reduction mandates across automated production lines are pulling ready-to-use formulations into mainstream adoption, displacing in-house preparation.
- Pectin Technology Maturation:Low-methoxyl pectin systems with enhanced calcium reactivity are expanding application windows into reduced-sugar formulations previously dominated by starch.
Market Restraints
- Input Cost Volatility:Citrus peel supply concentration in Brazil and Mexico creates pectin price instability that compresses margin structures for mid-tier suppliers.
- Technical Limitation:Current pectin systems exhibit viscosity breakdown below pH 3.2, constraining formulation flexibility in high-acid fruit varieties.
- Regulatory Friction:EFSA additive evaluations periodically restrict hydrocolloid applications, forcing reformulation investments across export-oriented suppliers.
Strategic Opportunities
- Underpenetrated Dairy Segment:Heat-stable fruit preparations for yogurt bake-on applications represent white space in Germany where industrial dairies seek cross-category ingredient platforms.
- Regulatory Tailwind:EU Green Deal thermal efficiency mandates are creating procurement preference for suppliers with certified low-energy processing infrastructure.
- Technology Convergence:Integration of high-pressure processing with traditional thermal stabilization is opening clean-label pathways without synthetic preservative dependency.
Industry Challenges
- Formulation Skill Gap:Shortage of hydrocolloid rheology specialists constrains supplier technical service capacity during customer onboarding.
- Capex Intensity:Retort system upgrades for F-Gas compliance require capital deployment that strains mid-cap manufacturer balance sheets.
- Certification Timeline:Clean-label certification delays from bodies like BRCGS and IFS extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat-Stable Fruit Fillings Market |
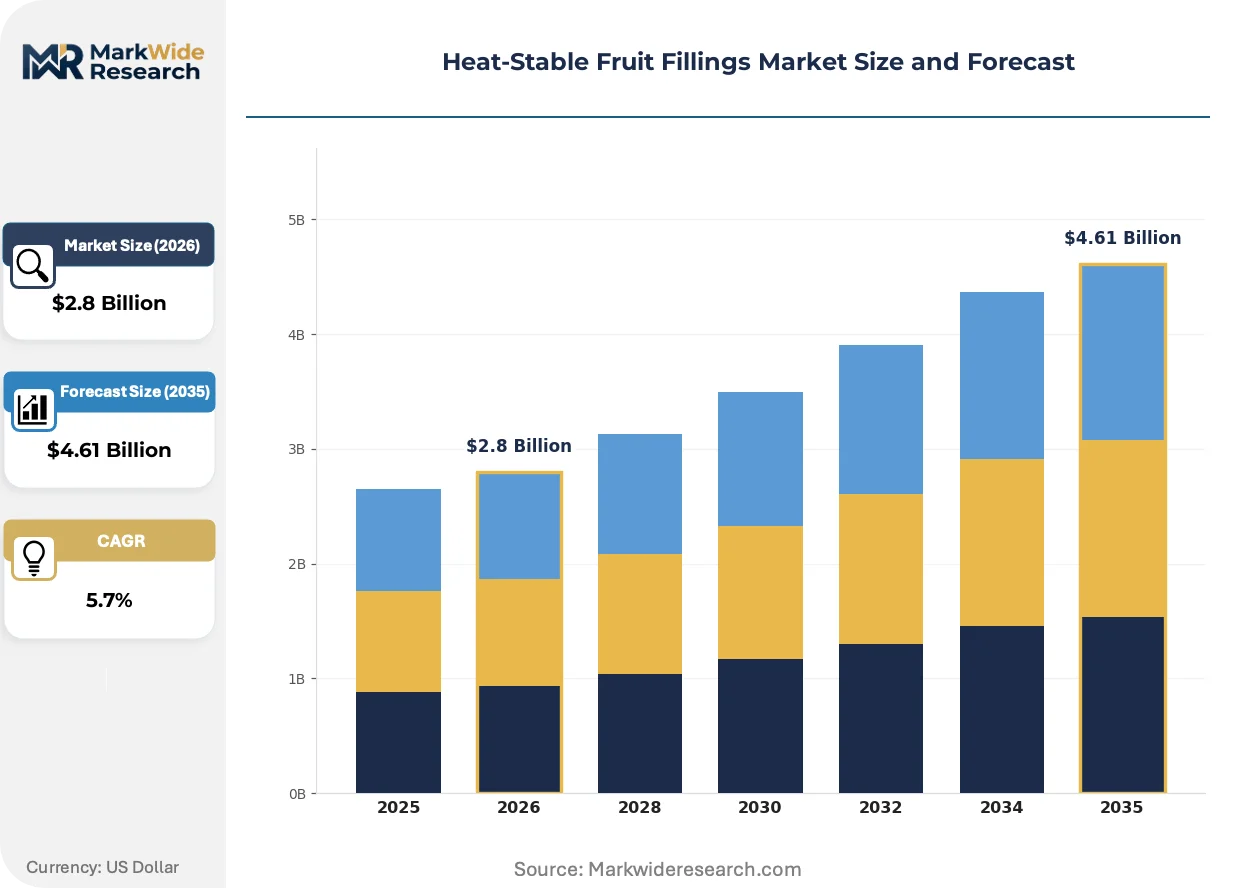
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Use, Concentrated, Sweetened, Unsweetened Application: Bakery, Confectionery, Dairy, Spreads End User: Food Manufacturers, Retailers, Foodservice Providers, Bakers Packaging Type: Bulk Containers, Jars, Pouches, Tubs |
| Companies Covered | Puratos Group, Dawn Food Products Inc., Agrana Group, Fruit Crown, Bakels Worldwide, Döhler Group, Tree Top Inc., The Barry Callebaut Group, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat-Stable Fruit Fillings Market Shifts & Advancements
Clean-label formulation pressure is compressing the viable stabilizer palette while thermal processing efficiency mandates reshape capital deployment patterns across European production facilities.
Low-methoxyl amidated pectin is consolidating its position as the preferred stabilization backbone for reduced-sugar heat-stable fillings. Premium industrial bakeries in Germany and France are adopting these systems at accelerated rates to meet retailer clean-label requirements. This technology is consolidating supplier market share around firms with captive pectin production and proprietary amidation processes.
EU F-Gas Regulation Phase-down is forcing thermal processing equipment replacement across filling production facilities. Manufacturers must install low-global-warming-potential refrigeration systems for post-process cooling, adding capital intensity to facility upgrades. Bakery-focused suppliers in Italy and Spain are responding by consolidating production into fewer, larger retort lines to amortize compliance costs.
Direct procurement relationships between industrial bakeries and fruit filling specialists are displacing traditional ingredient distributor intermediaries. Large-scale bakery groups in Germany are negotiating volume commitments with pectin-based formulation leaders, extracting price concessions and technical service prioritization. This channel compression is most visible in the ready-to-use segment where batch consistency requirements favor supplier-buyer operational integration.
Heat-Stable Fruit Fillings Market Segmentation
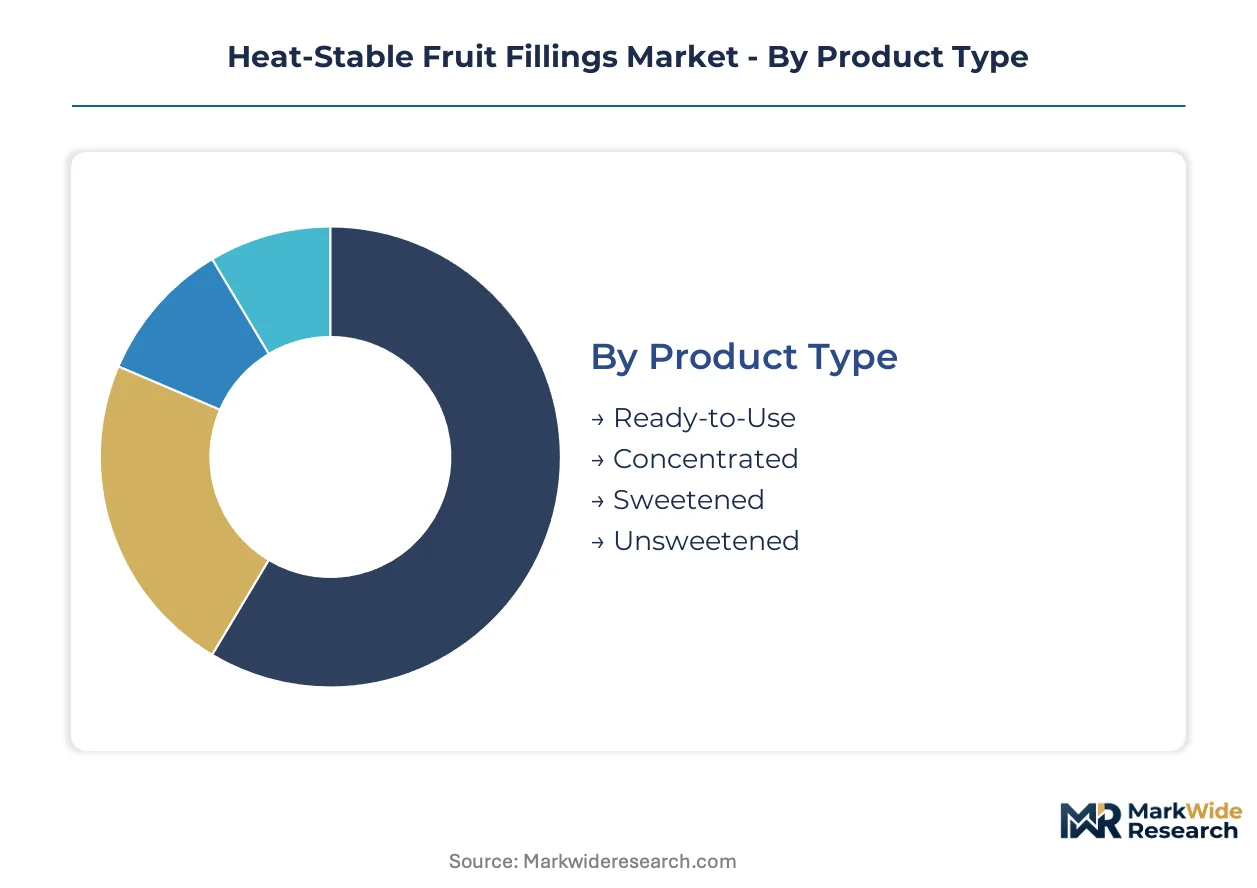
Segmentation in heat-stable fruit fillings reflects divergent buyer priorities across formulation complexity, thermal processing requirements, and supply chain integration depth. Procurement patterns vary sharply between industrial bakeries seeking batch consistency and foodservice operators prioritizing portion flexibility.
Product Type:
Cost tier differentiation separates buyers optimizing for labor reduction versus those managing freight expenditure and formulation control.
- Ready-to-Use:Pre-formulated preparations at standardized 15-35% soluble solids require no additional processing before application. Industrial bakeries in Germany anchor procurement volumes here, prioritizing batch-to-batch consistency and reduced labor headcount across automated production lines.
- Concentrated:Reduced-water formulations dilute at point of use, cutting transport costs by 40-60% versus ready-to-use equivalents. Freight cost reduction and dilution flexibility are pulling procurement decisions toward this segment among multi-facility bakery groups with central commissary operations.
- Sweetened:Sugar-standardized preparations at fixed Brix levels simplify formulation mathematics for high-volume producers.
- Unsweetened:Base preparations allow end-users to control sweetness profiles and meet clean-label sugar reduction targets.
Ready-to-Use leads volumes today; Concentrated is expanding most quickly.
Application:
Application segmentation tracks thermal stress tolerance requirements and finished goods margin structures across end-use categories.
- Bakery:Fillings engineered for oven exposure exceeding 180°C incorporate pectin or modified starch stabilizers to prevent syneresis during thermal shock. Pastry and Danish applications in France and Germany concentrate procurement volumes, with clean-label pectin systems displacing synthetic stabilizers under retailer pressure.
- Dairy:Yogurt bake-on and thermal dessert applications demand pH-stable formulations below 4.6 for dairy compatibility. German industrial dairies are testing cross-category fruit platforms here, creating procurement pull for pectin suppliers with dairy formulation expertise.
- Confectionery:High-solids preparations for enrobed and deposited candies require extended heat stability without Maillard browning.
- Spreads:Spoonable fruit preparations for bread and cracker applications prioritize cold viscosity over thermal resilience.
Bakery commands the dominant revenue pool; Dairy is climbing the fastest as manufacturers seek ingredient platform consolidation.
End User:
Customer type segmentation captures divergence between formulation capability in-house and reliance on external technical service.
- Food Manufacturers:Industrial-scale producers with captive R&D facilities negotiate direct supplier relationships, extracting technical service prioritization and volume pricing. Large bakery groups in Germany and France are consolidating procurement through sole-source agreements with pectin formulation leaders.
- Bakers:Artisan and mid-scale operations depend on distributor intermediaries for technical support and smaller batch sizes.
- Retailers:Private-label program managers specify clean-label certifications and audit-compliant supply chains.
- Foodservice Providers:Contract caterers and bakery chains prioritize portion-control packaging and thaw-and-use convenience.
Food Manufacturers lead volumes today; Retailers are gaining share fastest as private-label fruit programs expand.
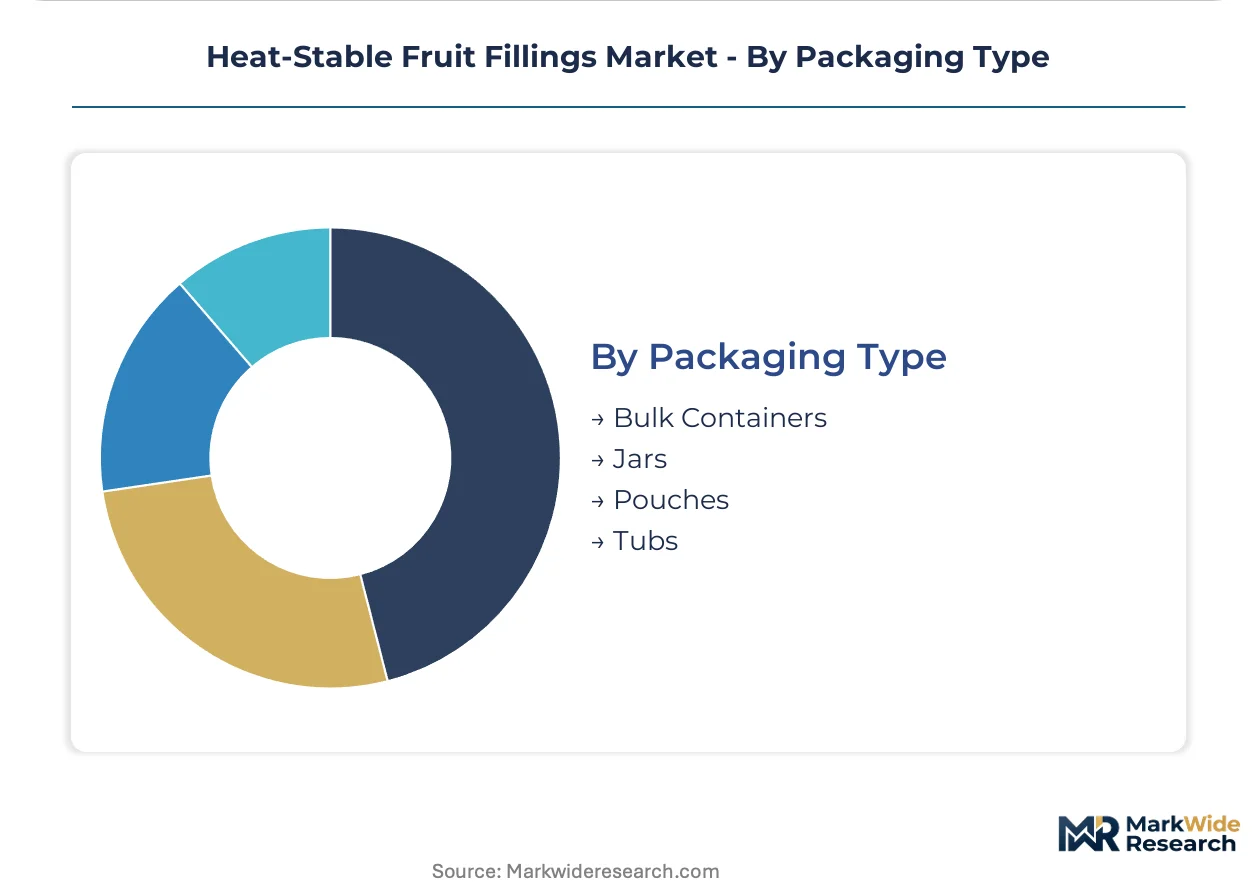
Packaging Type:
Packaging segmentation reflects supply chain integration depth and handling automation requirements across buyer segments.
- Bulk Containers:Tote and drum formats for high-volume industrial users minimize per-unit packaging cost and waste disposal burden. Automated bakery lines in Germany and Italy specify aseptic bag-in-box configurations for direct pump-to-mixer integration.
- Pouches:Flexible formats with fitment closures serve foodservice portion control and retail squeeze applications.
- Jars:Retail-ready glass and PET formats target consumer and small commercial accounts requiring visual product inspection.
- Tubs:Polypropylene containers balance stackability with scoop access for mid-scale bakery and foodservice operations.
Bulk Containers lead volumes today; Pouches are expanding most quickly in foodservice and retail convenience segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial bakeries anchor procurement volumes across the heat-stable fruit fillings landscape, with clean-label pectin systems displacing synthetic stabilizers under retailer pressure. France and Italy concentrate premium pastry formulation demand. Brazil and Mexico supply citrus peel feedstock for pectin extraction. The United States maintains specialized distribution infrastructure for North American bakery chains.
Germany
Industrial bakery procurement concentrates in North Rhine-Westphalia and Bavaria, where automated production lines pull ready-to-use formulations into mainstream adoption. EU F-Gas Regulation compliance is reshaping thermal processing requirements, forcing retort system upgrades across filling production facilities. The greater Munich and Cologne industrial clusters host formulation specialists negotiating direct volume commitments with pectin-based suppliers.
France
Premium pastry and Danish applications in Paris Basin and Rhône-Alpes drive demand for pectin-stabilized heat-stable preparations with enhanced calcium reactivity. EFSA additive evaluations periodically restrict hydrocolloid applications, forcing reformulation investments among export-oriented suppliers. Lyon and Lille anchor regional procurement networks serving artisan and mid-scale bakery operations.
Italy
Bakery-focused suppliers in Lombardy and Emilia-Romagna are consolidating production into fewer, larger retort lines to amortize EU Green Deal thermal efficiency compliance costs. Concentrated variants gain traction where freight cost reduction and dilution flexibility drive procurement decisions among multi-facility bakery groups. Milan and Bologna industrial zones concentrate formulation technical service capacity.
United States
FDA GRAS standards govern stabilizer and preservative use in fruit filling formulations across industrial bakeries in the Midwest and Southeast. Dawn Food Products anchors North American supply through specialized bakery ingredient distribution infrastructure. Chicago and Atlanta metropolitan areas concentrate food manufacturer procurement with captive R&D facilities negotiating direct supplier relationships.
Brazil
Citrus peel supply concentration in São Paulo state creates pectin price volatility that compresses margin structures for mid-tier suppliers dependent on Brazilian raw material sourcing. The country's national agricultural regulator monitors pesticide residue thresholds in fruit processing inputs. Campinas and São Paulo city industrial corridors host pectin extraction facilities serving global formulation houses.
Heat-Stable Fruit Fillings Market Competitive Landscape
Global majors compete with regional champions across formulation technology and fruit sourcing integration. The supplier base organizes around three tiers: integrated pectin producers with captive stabilization science, fruit processors with backward integration into raw material control, and specialized bakery ingredient distributors with technical service networks. Consolidation pressure intensifies as clean-label certification requirements and thermal processing energy standards strain mid-cap balance sheets. Dominant competitive moves include sole-source procurement agreements with industrial bakery groups and retort line consolidation to amortize regulatory compliance costs.
Among European-based formulation leaders, Puratos Group and Agrana Group occupy positions reflecting divergent strategic archetypes. Puratos exemplifies the global R&D network model, sustaining formulation leadership through distributed innovation infrastructure. Agrana represents vertical control over fruit sourcing and processing, differentiating via upstream integration into raw material supply. Dawn Food Products anchors North American positioning through specialized distribution infrastructure rather than captive manufacturing, sitting within the technical service and logistics tier. These three patterns—R&D-led, sourcing-integrated, and distribution-anchored—capture the competitive structure compressing mid-tier suppliers without scale in any single vector.
| Leading Market Players |
|---|
| Puratos Group |
| Dawn Food Products Inc. |
| Agrana Group |
| Fruit Crown |
| Bakels Worldwide |
| Döhler Group |
| Tree Top Inc. |
| The Barry Callebaut Group |
| ADM |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation Phase-down gates both qualified supply and premium-tier pricing access by forcing retort system upgrades that disqualify smaller processors while concentrating procurement power among industrial bakeries with certified low-energy infrastructure. This environmental mandate compresses mid-tier margins as compliance costs amortize across larger production volumes, rewarding pectin-based formulation leaders with the capital depth to absorb thermal processing equipment replacement.
Pricing Analysis
Input-cost pass-through from Brazilian and Mexican citrus peel supply concentration determines pectin-based formulation pricing, with three-tier pricing structure across premium, standard, and economy levels separating clean-label certified preparations from conventional starch-stabilized alternatives. Price differentiation hinges on certification grade and volume scale, with EU Green Deal thermal efficiency compliance adding a premium tier for low-energy processed fillings. Pricing pressure stems from EFSA additive evaluation cycles forcing reformulation investments. Food manufacturers with sole-source agreements exhibit lowest price sensitivity; artisan bakers through distributor channels face highest.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian citrus peel feedstock for pectin extraction, where Campinas industrial corridors host extraction facilities serving global formulation houses. Geographic supply concentration centers on Brazil, Mexico, and Germany for raw material processing, with fruit sourcing dependencies spanning citrus peel, apple pomace, and tropical fruit purees. Supply chain risk manifests as commodity price volatility from weather-driven citrus harvest variation. Distribution runs through specialized bakery ingredient distributors in North America and direct procurement relationships in European industrial bakery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Heat-Stable Fruit Fillings Market reads as a late-cycle quality story justified by industrial bakery procurement shifting toward clean-label pectin systems with enhanced calcium reactivity for reduced-sugar formulations.
For Market Incumbents: Anchor formulation leadership through captive pectin production and proprietary amidation processes that lock in clean-label certification ahead of EFSA additive evaluation cycles. Consolidate retort line capacity into fewer, larger facilities to amortize EU F-Gas compliance costs while defending margin position against mid-tier suppliers without scale. Prioritize sole-source procurement agreements with German and French industrial bakery groups to extract volume commitments and technical service prioritization. For New Entrants and Emerging Players: Enter via dairy segment white space in Germany, where industrial dairies seek cross-category fruit platforms for yogurt bake-on applications with pH-stable formulations below 4.6. Target concentrated variant production for multi-facility bakery groups with central commissary operations, leveraging freight cost reduction as the primary value proposition. Pursue go-to-market angles through high-pressure processing integration with traditional thermal stabilization for clean-label positioning without synthetic preservatives. For Investors and Strategic Acquirers: Roll-up economics work for regional fruit processors with backward integration into raw material control because supply concentration in Brazilian citrus peel creates margin volatility that favors scaled sourcing operations. Long-term viability over a multi-year horizon depends on acquisition targets with EU Green Deal thermal efficiency certification and established pectin formulation expertise. Watch for inflection signals in EFSA additive evaluation outcomes that restrict specific hydrocolloid applications and force consolidation among reformulation-constrained suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Line Consolidation | Amortizes EU F-Gas compliance costs across larger production volumes in Italian and Spanish facilities. |
| Backward Integration into Citrus Sourcing | Secures pectin feedstock supply against Brazilian harvest volatility for formulation leaders. |
| Clean-Label Certification Investment | Accelerates BRCGS and IFS approval timelines that currently extend product launches by 8-14 months. |
| Direct Procurement Relationship Development | Displaces distributor intermediaries for German industrial bakery volume commitments. |
| High-Pressure Processing Integration | Opens preservative-free pathways meeting retailer clean-label requirements without synthetic additives. |
Research Methodology
Direct dialogue with plant managers at European filling production facilities, procurement leads at industrial bakery groups, technical R&D directors at pectin suppliers, and distribution channel partners anchored qualitative findings. Secondary validation drew from EU F-Gas Regulation implementation documents, EFSA additive evaluation records, customs and trade data for citrus peel imports, and SEC filings from listed ingredient suppliers. Bottom-up volume estimates from facility-level capacity and top-down demand calibration from bakery production statistics were triangulated to ensure convergence.
Segmented projections across product type, application, end user, and packaging format dimensions were generated over the projection horizon. CAGRs were derived from regression analysis against historical thermal processing equipment deployment and clean-label certification adoption curves. Industry-specific forecast inputs included EU Green Deal thermal efficiency mandate compliance timelines and pectin technology maturation rates for reduced-sugar applications.
The model holds under stable regulatory enforcement of EU F-Gas Phase-down schedules; deviation in EFSA additive evaluation stringency or Brazilian citrus harvest shocks would shift volume and value trajectories. Forecasts reflect documented assumptions regarding industrial bakery automation adoption and clean-label procurement preference evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Hot Pot Market
Specialty Foods
United States Tofu Market
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
Free-From Food Market
Specialty Foods
Moringa Products Market
Specialty Foods
Sweet Spreads Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Saw Palmetto Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Huoxiangzhengqi Market
Specialty Foods
Edible Mushroom Market
Specialty Foods
Wet Grain-Free Pet Food Market
Specialty Foods
Reishi Mushroom Market
Specialty Foods
Coconut Butter Market