
 Bergamot Extract Market | 2026-2036
Bergamot Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Bergamot Extract Market Analysis
The EU Green Deal is shifting procurement standards across European cosmetics and food manufacturers, forcing suppliers to document sustainable sourcing and reduced chemical inputs. Robertet Group leverages its vertical integration from Calabrian orchards to finished extracts, securing supply continuity for premium fragrance clients. Givaudan SA anchors its bergamot portfolio through long-term grower partnerships in southern Italy. Symrise AG competes on analytical rigor, with in-house chromatography capabilities that verify bergapten-free specifications for phototoxicity-sensitive applications.
Bergamot extract comprises volatile and non-volatile fractions steam-distilled or cold-pressed from Citrus bergamia Risso peel, with essential oil containing linalyl acetate, limonene, and gamma-terpinene as dominant terpenoids alongside trace furanocoumarins. Manufacturers deploy it as a natural flavoring agent, fragrance modifier, and bioactive compound carrier across food, cosmetic, and therapeutic formulations. Essential oil dominates value capture due to concentrated aroma intensity and higher per-kilogram pricing, while flavonoid fractions represent the fastest-growing structural category as nutraceutical buyers seek standardized polyphenol content for cardiovascular and metabolic health positioning. The food and beverage application segment sustains mature volume demand through traditional Italian confectionery and liqueur production, whereas pharmaceutical and aromatherapy channels are expanding as clinical research on bergamot polyphenol efficacy advances.
REACH registration requirements and EFSA novel food evaluations govern European market access, with the F-Gas Regulation indirectly pressuring solvent-based extraction methods toward supercritical CO2 alternatives. Italy's Ministry of Agricultural Policies enforces Calabrian Protected Geographical Indication standards that restrict bergamot origin labeling to specified coastal provinces. Stakeholders must monitor evolving EU botanical extract monographs and invest in substitution-ready processing technologies before tightened contaminant thresholds disrupt existing supply qualifications.
Market Dynamics
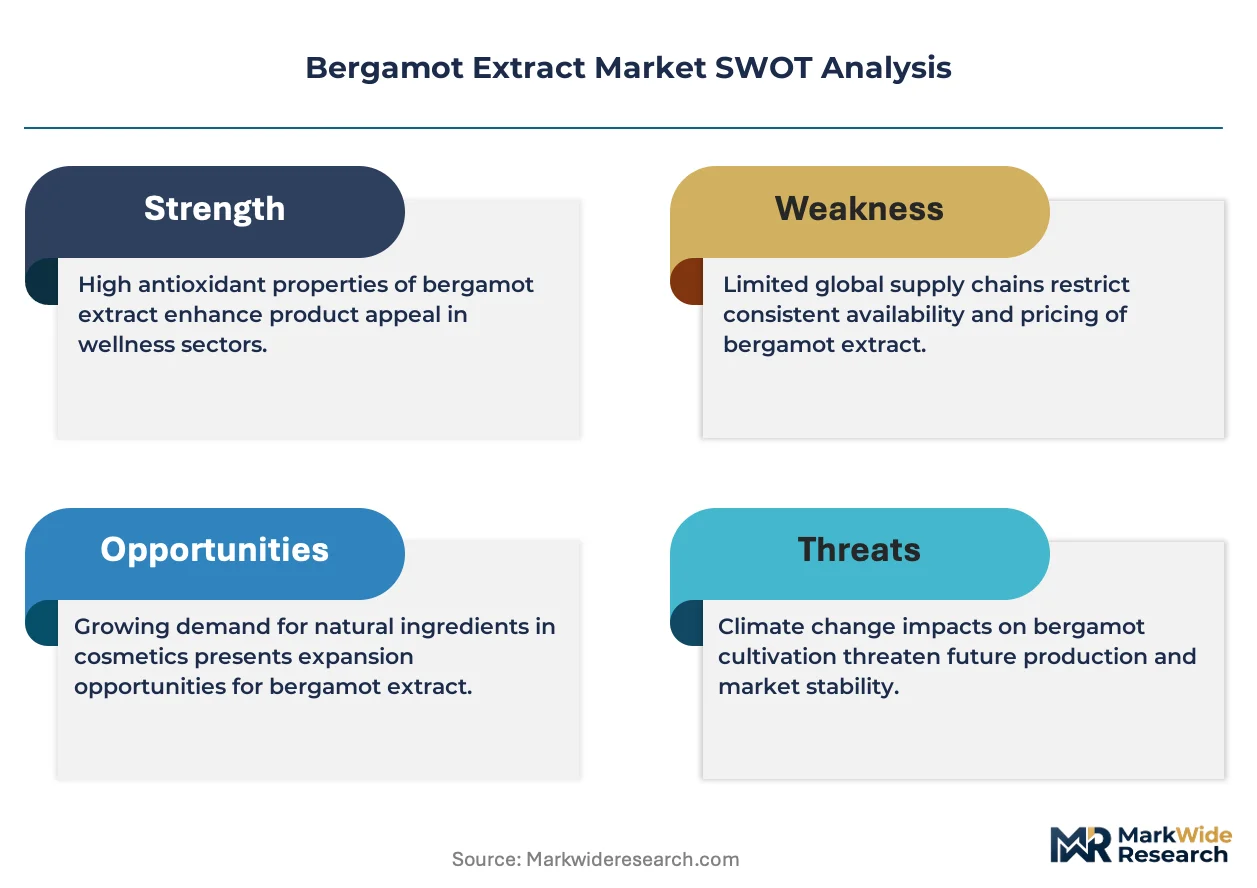
REACH solvent limits and EU Green Deal sourcing mandates are compressing legacy extraction operations while concentrating procurement around Calabrian PGI-certified supply chains. Formulators now face qualification barriers that favor integrated producers with captive orchards and verified bergapten-free processing.
Growth Catalysts
- EFSA novel food pathways:Standardized bergamot flavonoid extracts gain approval for cardiovascular health positioning, opening pharmaceutical and nutraceutical channels previously restricted to traditional applications.
- Supercritical CO2 extraction:This solvent-free technology satisfies tightening residual limits while preserving heat-sensitive terpenoid profiles that steam distillation degrades.
- Calabrian orchard consolidation:Protected Geographical Indication enforcement concentrates premium raw material sourcing in Italy's coastal provinces, creating supply scarcity that commands price premiums.
Market Restraints
- Input cost volatility:Bergamot peel supply fluctuates with Mediterranean climate stress and citrus greening disease pressure, compressing processor margins during poor harvest cycles.
- Phototoxicity liability:Furanocoumarin content in unrefined oils triggers regulatory scrutiny and limits cosmetic applications without costly bergapten-removal processing.
- Substitution threat:Synthetic linalyl acetate and alternative citrus extracts from Brazil and Spain displace bergamot in cost-sensitive fragrance formulations.
Strategic Opportunities
- Underpenetrated Asian nutraceutical markets:Japan's PMDA and South Korea's MFDS are evaluating bergamot polyphenol health claims, creating first-mover advantages for standardized extract suppliers.
- Clean-label flavor convergence:Food manufacturers seeking natural alternatives to artificial citrus flavors are expanding bergamot procurement for beverage and confectionery applications.
- Carbon accounting integration:EU CSRD reporting requirements favor suppliers with documented orchard-to-extract carbon footprints, rewarding vertically integrated Calabrian operations.
Industry Challenges
- Analytical chemistry skill scarcity:Chromatographic verification of bergapten-free specifications and flavonoid standardization requires specialized talent that smaller processors struggle to recruit.
- Certification timeline compression:REACH registration dossiers and novel food safety studies demand 18-36 month lead times that outpace customer qualification schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bergamot Extract Market |
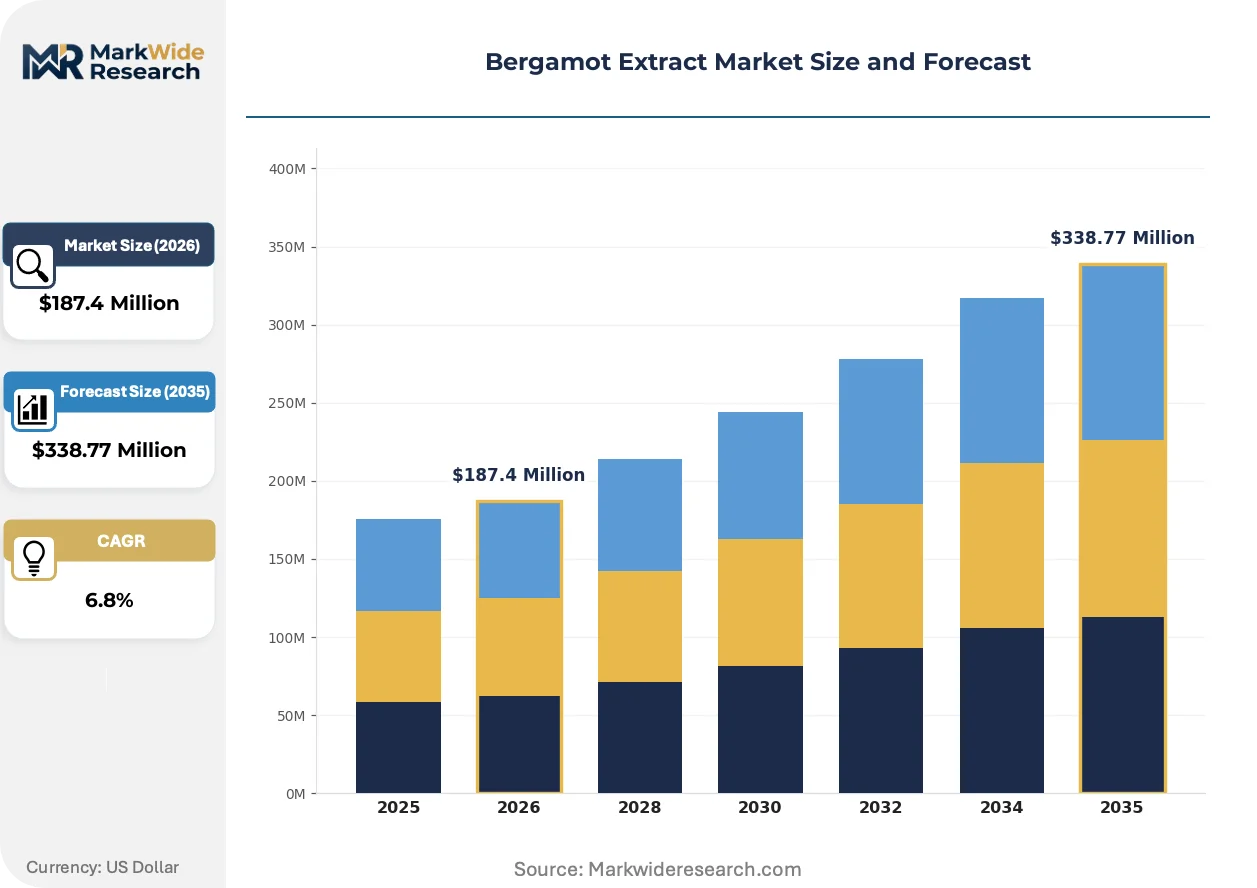
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oil, Bitter Orange Oil, Bergapten, Flavonoids Application: Cosmetics, Pharmaceuticals, Food & Beverage, Aromatherapy End User: Manufacturers, Retailers, Wholesalers, Distributors Form: Liquid, Powder, Capsule, Extract |
| Companies Covered | Robertet Group, HP Ingredients, H&AD s.r.l., Citroglobe, BergaMet N.A., Bontoux S.A.S., Givaudan SA, Berje Inc., Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bergamot Extract Market Emerging Trajectories
Extraction technology and regulatory chemistry are converging to reshape competitive qualification requirements. Processors must now demonstrate solvent-free methods and phototoxicity-compliant outputs simultaneously.
Supercritical CO2 extraction systems are rewriting technical standards for premium-grade bergamot oil production. Cosmetic and therapeutic formulators in France and Switzerland are adopting CO2-derived extracts at accelerated rates to preempt REACH enforcement actions. This technology is compressing market access for traditional steam-distilled products that carry higher residual solvent risk.
The EU F-Gas Regulation is accelerating solvent substitution mandates across botanical extract processing. Industrial consequence includes capital reallocation toward closed-loop CO2 systems and away from hexane-based extraction infrastructure. Italian processors with existing supercritical capacity are capturing qualification advantages in German and Dutch flavor house supply chains.
Direct contracting between fragrance houses and Calabrian grower cooperatives is displacing spot-market procurement through Mediterranean trading houses. This channel consolidation concentrates volume commitments among three to five integrated suppliers while marginalizing independent processors lacking orchard ownership. The shift is most visible in Paris and Grasse, where Givaudan and Robertet procurement teams have established exclusive supply agreements.
Bergamot Extract Market Segmentation
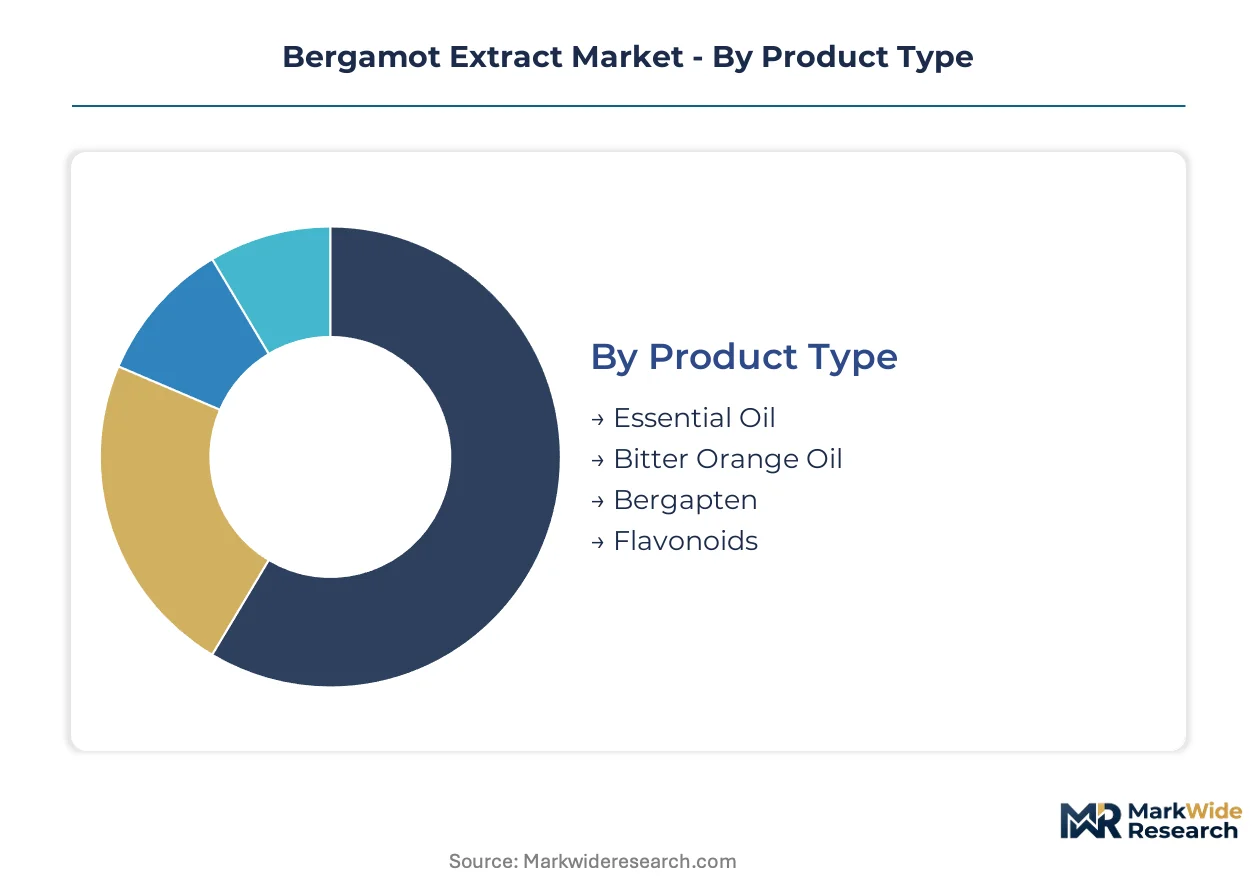
Segmentation in the bergamot extract market determines which regulatory pathways apply and where margin concentration occurs. Product form and application channel dictate whether REACH solvent limits, EFSA novel food evaluations, or cosmetic safety dossiers govern market access.
Product Type:
Certification burden varies sharply across product types: essential oil faces REACH registration and residual solvent scrutiny, while flavonoid fractions trigger EFSA novel food pathways for health claim positioning.
- Essential Oil:Steam-distilled or cold-pressed volatile fraction containing linalyl acetate, limonene, and gamma-terpinene. Fragrance houses in Grasse and Geneva concentrate procurement here, driven by concentrated aroma intensity and premium per-kilogram pricing that justifies supercritical CO2 extraction investment.
- Flavonoids:Non-volatile polyphenol fraction standardized for naringin, neoeriocitrin, and brutieridin content. Nutraceutical formulators in Switzerland and Germany are expanding offtake for cardiovascular and metabolic health applications, constrained by EFSA safety study timelines.
- Bitter Orange Oil:Adjacent citrus extract with overlapping terpenoid profile, often blended with bergamot in fragrance formulations.
- Bergapten:Furanocoumarin compound isolated for phototoxicity research and specialized therapeutic applications.
Leading the category by volume: Essential Oil. Growing fastest: Flavonoids.
Application:
Application channel determines customer qualification depth and pricing power, with pharmaceutical and therapeutic segments demanding the most extensive analytical documentation.
- Cosmetics:Fragrance and skincare formulations requiring bergapten-free specifications verified by HPLC analysis. Formulators in France face strict phototoxicity liability thresholds.
- Pharmaceuticals:Standardized extracts for clinical research and therapeutic positioning, subject to EMA quality guidelines and national pharmacopoeia standards.
- Food & Beverage:Natural flavoring for Italian confectionery, liqueurs, and premium beverages. Mature volume demand concentrates in traditional production clusters.
- Aromatherapy:Therapeutic-grade oils for inhalation and topical applications, expanding as clinical research on anxiolytic effects advances.
Highest margin capture: Pharmaceuticals. Steepest expansion trajectory: Aromatherapy.
End User:
End user type shapes contract structure and volume commitment, with integrated manufacturers capturing supply chain efficiencies unavailable to trading intermediaries.
- Manufacturers:Fragrance houses, flavor companies, and finished goods producers with direct Calabrian orchard contracts. Procurement concentrates around Robertet, Givaudan, and Symrise supply agreements.
- Retailers:Specialty cosmetic and wellness brands sourcing packaged extracts for consumer distribution.
- Wholesalers:Mediterranean trading houses facing margin compression as direct contracting displaces spot-market intermediation.
- Distributors:Regional logistics providers serving smaller formulators lacking import capabilities.
Dominant volume share: Manufacturers. Most vulnerable to channel consolidation: Wholesalers.
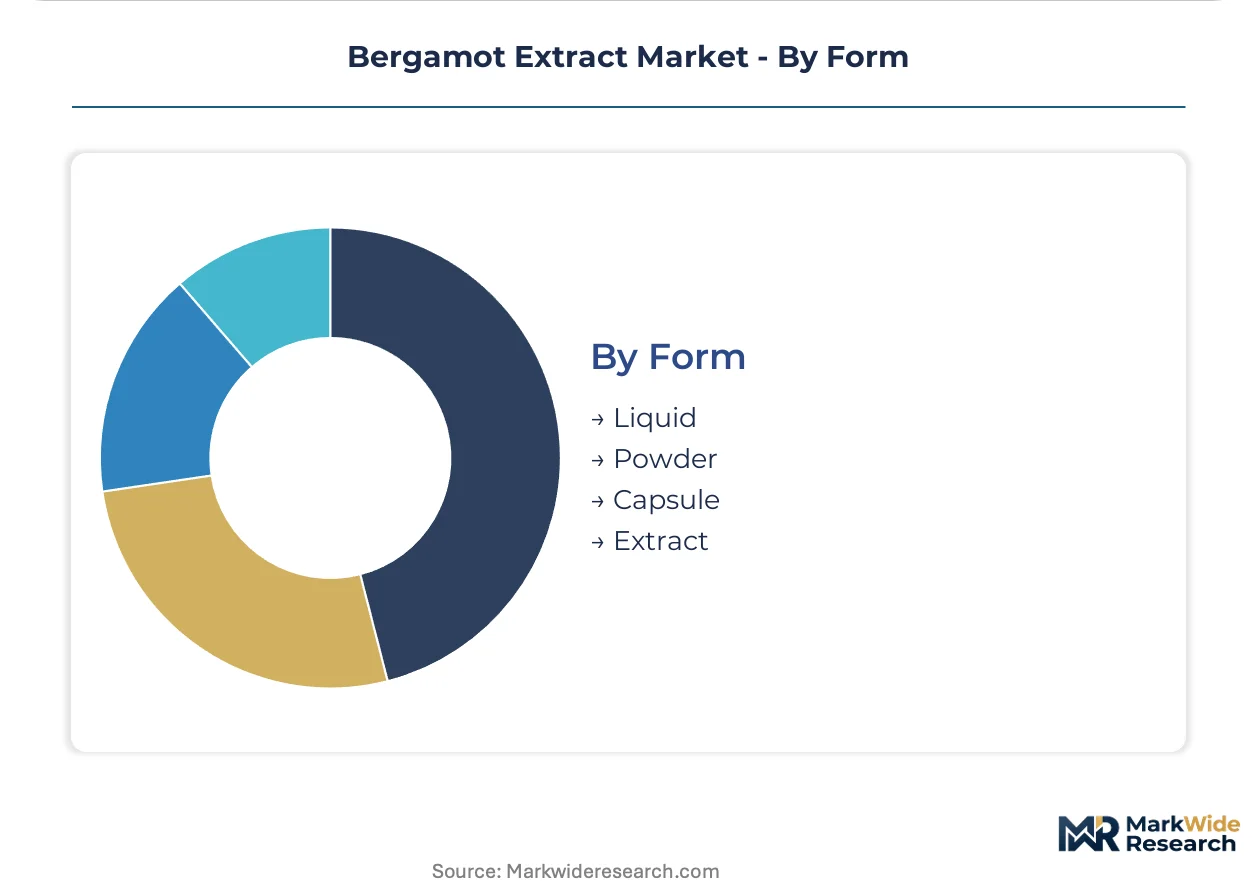
Form:
Physical form dictates stability requirements, packaging economics, and suitability for specific formulation integration.
- Liquid:Standard presentation for essential oils and alcoholic extracts, dominant in fragrance and flavor applications.
- Powder:Spray-dried or encapsulated formats for nutraceutical tablets and powder blends, enabling precise dosing.
- Capsule:Pre-dosed unit for direct consumer supplementation, expanding in standardized polyphenol products.
- Extract:Concentrated non-volatile fraction for pharmaceutical and therapeutic compounding.
Volume leadership: Liquid. Fastest format innovation: Powder.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy produces nearly all commercial bergamot supply from its Calabrian orchards, while consumption concentrates in French fragrance houses, German nutraceutical formulators, and Swiss therapeutic brands. This geographic asymmetry shapes trade flows, regulatory exposure, and pricing power across the value chain.
Italy
Calabria's Protected Geographical Indication enforces origin labeling to coastal provinces of Reggio Calabria, Catanzaro, and Cosenza. The Ministry of Agricultural Policies inspects orchards for chemical input compliance. Vertical integration from cultivation to extraction dominates in the Crotone industrial corridor, where captive supply secures batch traceability for premium fragrance clients.
France
Grasse-based fragrance houses drive demand for bergapten-free essential oil specifications. ANSM enforces strict phototoxicity thresholds for cosmetic applications. Parisian procurement teams have displaced Mediterranean trading intermediaries through direct grower contracts in Calabria, compressing spot-market margins.
Germany
Nutraceutical formulators in Baden-Württemberg expand offtake of standardized flavonoid fractions for cardiovascular health positioning. EFSA novel food evaluations govern market access, with safety study timelines stretching 18-36 months. REACH registration requirements from ECHA tighten residual solvent limits, favoring suppliers with supercritical CO2 capacity.
Switzerland
Swissmedic guidelines govern therapeutic-grade extract imports for clinical research applications. Basel-based pharmaceutical clusters source bergamot polyphenols for metabolic health trials. Geneva fragrance laboratories specify chromatographic verification of furanocoumarin content, rewarding suppliers with in-house analytical capabilities.
United States
Flavor houses in New Jersey and California procure bergamot oil for natural citrus flavoring in premium beverages. FDA oversight of botanical ingredients requires New Dietary Ingredient notifications for polyphenol extracts. Clean-label convergence in organic confectionery channels expands procurement from Calabrian PGI-certified supply chains.
Bergamot Extract Market Vendor Landscape
The competitive structure tilts toward integrated specialists with captive orchard assets and verified processing capabilities. Three to five vertically aligned producers capture disproportionate volume commitments from fragrance and nutraceutical formulators. Strategic archetypes include Calabrian orchard-owners with extraction assets, European fragrance houses with backward integration into cultivation, and analytical-technology specialists with bergapten-removal expertise. Dominant competitive moves center on exclusive supply agreements with grower cooperatives and capital reallocation toward supercritical CO2 infrastructure.
Among French integrated specialists, Robertet Group exemplifies the orchard-to-extract archetype through its Calabrian cultivation assets. Givaudan SA anchors the fragrance-house integration model with long-term grower partnerships in southern Italy. Symrise AG occupies the analytical-specialist position, with in-house chromatography capabilities that verify phototoxicity-compliant specifications for cosmetic applications.
| Leading Market Players |
|---|
| Robertet Group |
| HP Ingredients |
| H&AD s.r.l. |
| Citroglobe |
| BergaMet N.A. |
| Bontoux S.A.S. |
| Givaudan SA |
| Berje Inc. |
| Symrise AG |
| Others |
Supply Flow & Price Mechanics
Calabrian bergamot peel procurement costs cascade through three distinct pricing tiers determined by certification grade and extraction method. PGI-certified raw material commands premium positioning for fragrance house contracts, while non-certified peel feeds standard-grade essential oil production at compressed margins.
Pricing Analysis
Value-based pricing anchored to phototoxicity compliance and terpenoid concentration stratifies the market. Three-tier pricing structure across premium, standard, and economy levels separates bergapten-free CO2 extracts from steam-distilled oils and unrefined commodity grades. Pricing pressure stems from synthetic linalyl acetate substitution in cost-sensitive fragrance formulations. Small independent processors exhibit highest price sensitivity due to lacking captive orchard supply, while integrated producers with Calabrian PGI holdings maintain pricing power through batch traceability guarantees.
Supply Chain Analysis
Regional distribution centers in Milan and Rotterdam consolidate bergamot extract shipments before downstream dispersal to fragrance laboratories and nutraceutical formulators. Raw material supply concentrates in Italy's Calabrian coastal provinces, with secondary processing capacity in France and Germany. The supply chain draws from citrus peel feedstock, supercritical CO2 equipment, and chromatographic testing services. Single-source vulnerability runs through Calabrian orchard concentration exposed to Mediterranean climate stress. Distribution runs through direct contracting between integrated producers and end-user formulators, displacing Mediterranean trading intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bergamot extract market sits in a technology-transition phase as supercritical CO2 extraction displaces legacy steam-distillation infrastructure. This solvent-free technology satisfies tightening REACH residual limits while preserving heat-sensitive terpenoid profiles.
For Market Incumbents: Anchor supply continuity through exclusive grower cooperative agreements in Reggio Calabria and Catanzaro provinces. Synthetic citrus substitution from Brazil threatens traditional fragrance applications; defend positioning by accelerating supercritical capacity deployment and securing EFSA novel food dossiers for standardized flavonoid fractions ahead of competitor timelines. For New Entrants and Emerging Players: Enter via analytical-specialist positioning targeting bergapten-removal processing and chromatographic verification services. Japan's PMDA and South Korea's MFDS evaluation of bergamot polyphenol health claims represents the most penetrable geography-application intersection. Pursue toll-processing partnerships with established Calabrian orchard-owners lacking in-house analytical capabilities. For Investors and Strategic Acquirers: EFSA novel food approval timelines compressing to 18-month cycles is the leading indicator that standardized flavonoid extract suppliers will command acquisition premiums. Long-term viability favors vertically integrated Calabrian operations with captive PGI-certified supply and supercritical infrastructure already deployed. Monitor REACH enforcement actions against residual solvent non-compliance as the primary signal for distressed asset opportunities among legacy steam-distillation processors.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | REACH solvent limits favor processors with closed-loop extraction systems in Calabria. |
| EFSA Novel Food Dossier Investment | Standardized flavonoid extracts unlock pharmaceutical and nutraceutical channel access. |
| Exclusive Grower Cooperative Agreements | Direct contracting secures PGI-certified raw material traceability for premium fragrance clients. |
| In-House Chromatography Capability Buildout | Bergapten-free verification meets ANSM phototoxicity thresholds for cosmetic applications. |
| Asian Regulatory Pre-Submission Engagement | Early PMDA and MFDS dialogue creates first-mover positioning for polyphenol health claims. |
Methodological Framework
Trade databases, EFSA novel food submission records, and REACH registration dossiers formed the secondary backbone for supply-side mapping. Primary interviews with extraction plant managers, fragrance house procurement directors, nutraceutical formulators, and Calabrian grower cooperative representatives combined with secondary validation. Bottom-up volume estimates from processor capacity utilization and top-down demand triangulation from end-user offtake patterns were cross-referenced for convergence.
Historical trendline analysis of bergamot peel harvest volumes, essential oil export flows, and flavonoid fraction pricing established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, application channel, end-user category, and physical form dimensions. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity constraints. Climate stress indices for Mediterranean citrus cultivation and EFSA evaluation pipeline status served as industry-specific forecast inputs.
Revisions become necessary when EFSA novel food approval timelines accelerate, REACH solvent thresholds tighten beyond current supercritical compliance capabilities, or synthetic substitution rates in fragrance formulations exceed modeled assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
United States Food Flavor Market
Flavorings and Food Additives
Beef Flavors Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
North America Food Colorants Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
Carvone Market
Flavorings and Food Additives
FTNF Flavors Market
Flavorings and Food Additives
Food Texturizers Market
Flavorings and Food Additives
1-Decanol Market
Flavorings and Food Additives
Tangerine Essential Oil Market
Flavorings and Food Additives
Dairy Flavors Market
Flavorings and Food Additives
Basil Oil Market
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
Vanillin Market