
 Flavanones Market | 2026-2036
Flavanones Market Size, Share, and Industry Trends Forecast 2026-2036
Flavanones Market Analysis
Ingredient purification margins is narrowing as standardized extracts replace commodity-grade flavanone powders in pharmaceutical and nutraceutical contracts. Merck KGaA leverages its analytical standards portfolio to anchor premium positioning in research-grade naringenin supply. Indena S.p.A. specializes in phytosome delivery systems that sustain higher bioavailability claims for hesperetin formulations. Layn Natural Ingredients controls large-scale citrus-derived extraction capacity, competing on volume for food and beverage fortification programs.
Flavanones constitute a subclass of flavonoids characterized by a 2-phenylchroman-4-one backbone with a saturated C2-C3 bond, typically extracted from citrus fruits via solvent extraction or supercritical CO2 methods yielding 80-98% purity grades for commercial applications. These compounds function primarily as antioxidant, anti-inflammatory, and metabolic modulating agents across nutraceutical, pharmaceutical, and cosmetic formulations. The naringenin and hesperetin product types occupy established positions in cardiovascular health applications, while eriocitrin extracts from lemon sources are gaining traction in cosmeceutical antioxidant serums. Dietary supplements represents the most structurally dynamic end-use channel, with powder and liquid forms dominating bulk ingredient procurement and extract formulations commanding premium positioning in finished goods.
EMA guidelines on botanical drug substance characterization and FDA GRAS notification requirements for new dietary ingredients shape product development timelines and clinical substantiation investments for flavanone suppliers. REACH registration obligations for imported botanical extracts into the European Union add compliance layers that favor suppliers with established dossier capabilities. Stakeholders must monitor evolving EFSA health claim opinions on polyphenol-specific benefits, as positive determinations would unlock direct-to-consumer positioning previously restricted by general function claims.
Market Dynamics
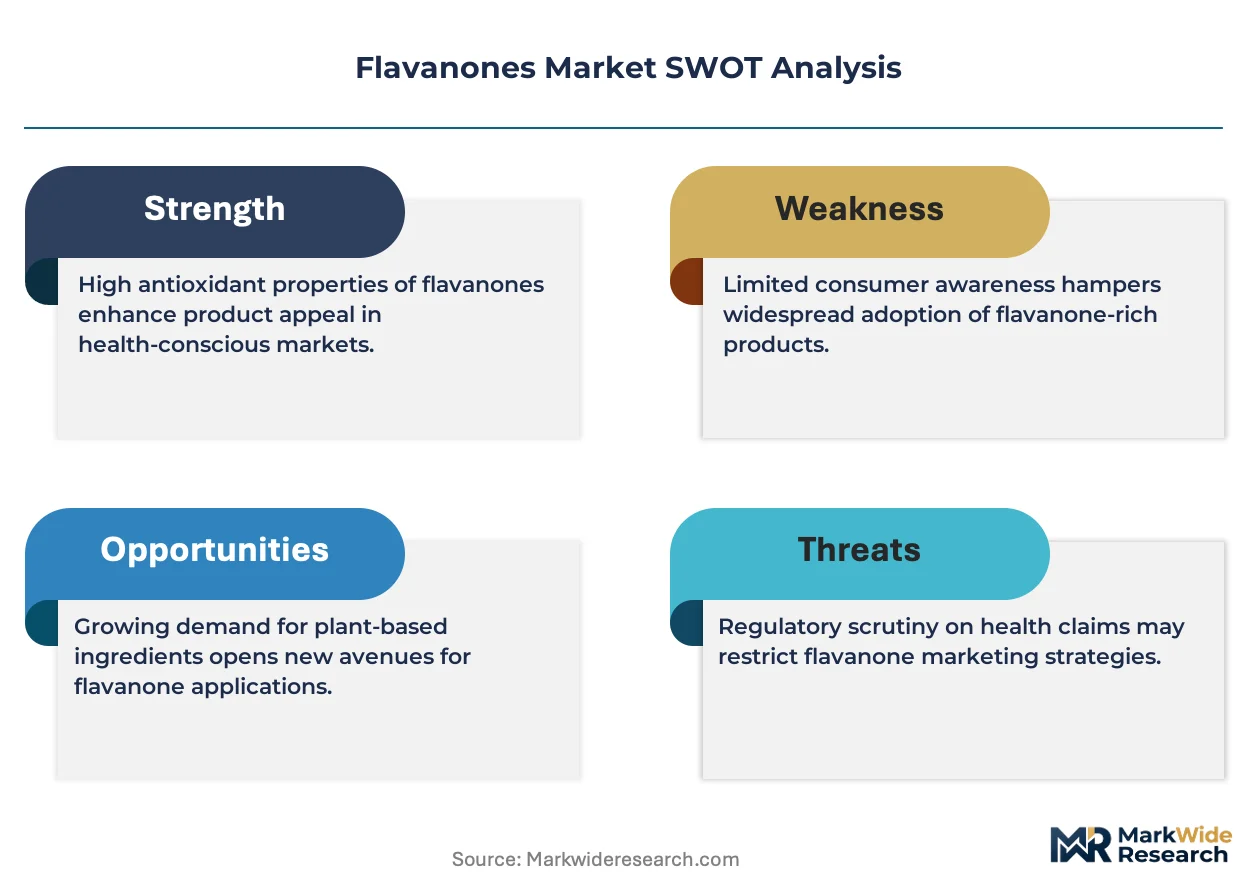
Pharmaceutical formulators in Germany and the United States are expanding procurement of naringenin and hesperetin for cardiovascular and metabolic health applications. The EU Nutrition and Health Claims Regulation continues to reshape product positioning across member states.
Growth Catalysts
- EMA botanical drug guidelines:Characterization requirements for flavanone extracts are accelerating clinical substantiation investments and favoring suppliers with established dossier capabilities.
- Dietary supplement channel expansion:Evidence-based polyphenol consumption patterns are pulling standardized hesperetin and naringenin into premium positioning.
- Supercritical CO2 extraction technology:Adoption of solvent-free methods yielding 95-98% purity grades is collapsing cost barriers for pharmaceutical-grade procurement.
Market Restraints
- Citrus raw material concentration:Dependence on Mediterranean and Florida citrus belt harvests exposes supply to climate volatility and agricultural input cost swings.
- REACH registration burdens:Imported botanical extracts face layered compliance obligations that disadvantage smaller suppliers without in-house regulatory affairs functions.
- Phytosome delivery system patents:Proprietary encapsulation technologies held by specialized extract houses create licensing friction for generic formulation development.
Strategic Opportunities
- Emerging cosmeceutical applications:Eriocitrin extracts from lemon sources are penetrating antioxidant serum formulations targeting dermal inflammation modulation.
- EFSA positive opinion pathway:Pending determinations on polyphenol-specific benefits would unlock direct-to-consumer health claims previously restricted to general function positioning.
- Japan's functional food regulatory framework:Foods with Function Claims system offers a template for evidence-based flavanone positioning in East Asian markets.
Industry Challenges
- GRAS notification timelines:FDA new dietary ingredient submissions for novel flavanone sources extend product development cycles by 18-24 months.
- Analytical standard scarcity:Qualified reference material availability constrains batch-to-batch consistency verification for high-purity extract contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavanones Market |
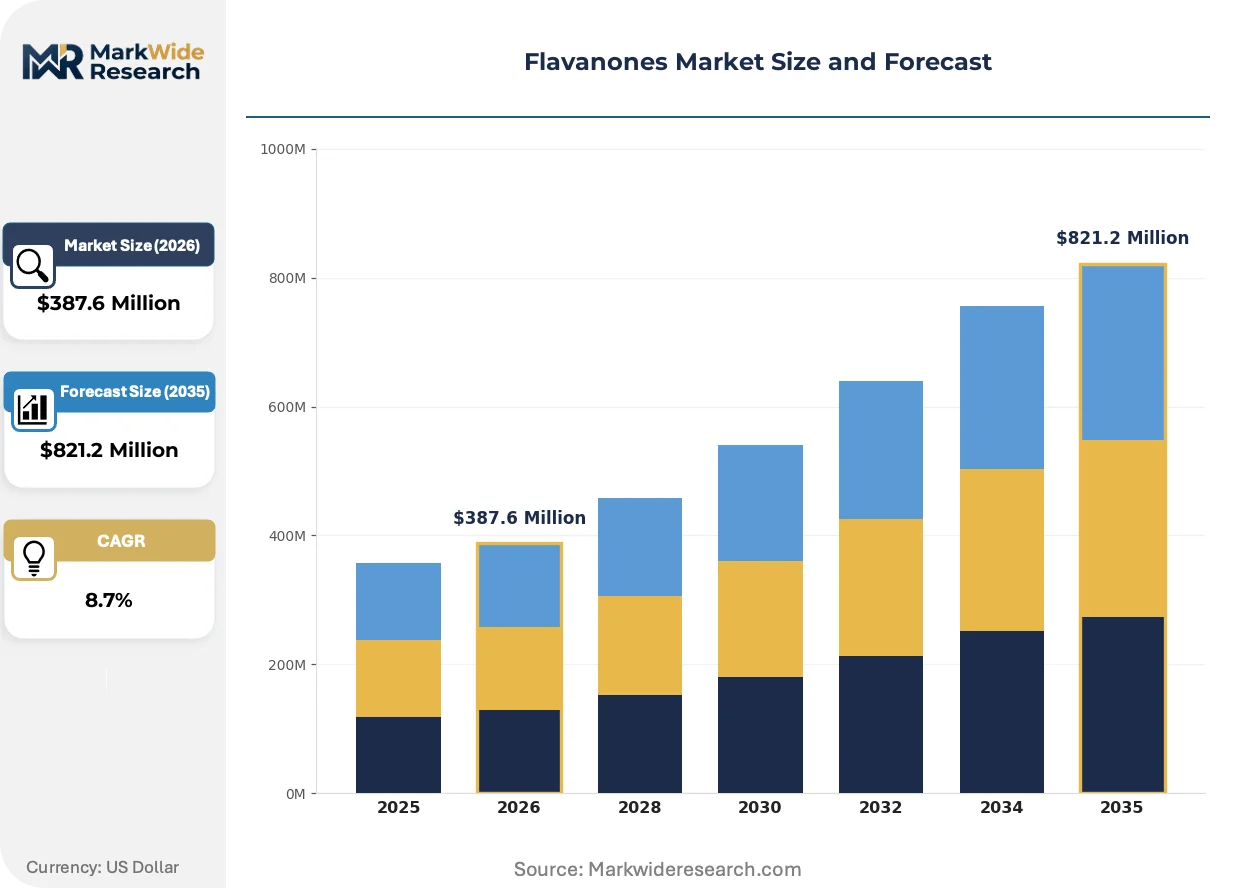
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Naringenin, Hesperetin, Eriocitrin, Naringin End Use Industry: Cosmetics, Food & Beverages, Dietary Supplements, Pharmaceuticals Form: Powder, Liquid, Extract, Granule Source: Citrus Fruits, Herbs, Vegetables, Others |
| Companies Covered | Merck KGaA, Indena S.p.A., Cayman Chemical Company, Layn Natural Ingredients, Archer-Daniels-Midland Company, DSM Nutritional Products, Ingredion Incorporated, Givaudan, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavanones Market Emerging Trajectories
Ingredient purification margins are narrowing as standardized extracts replace commodity-grade flavanone powders in pharmaceutical and nutraceutical contracts. Bioavailability enhancement technologies and regulatory-driven clinical substantiation are compressing competitive differentiation around dossier depth.
Supercritical CO2 extraction systems are collapsing the cost structure for 95-98% purity naringenin production. Pharmaceutical formulators in Germany and the United States are adopting these solvent-free methods at accelerating pace. The technology is collapsing premium pricing spreads between research-grade and commercial-grade flavanone supply tiers.
EFSA health claim opinions on polyphenol-specific benefits are reshaping permissible marketing language across EU member states. Positive determinations would enable direct cardiovascular health claims previously restricted to general antioxidant positioning. Dietary supplement manufacturers are front-loading clinical substantiation investments to capture first-mover advantage in claim-enabled product launches.
Buyer concentration among multinational pharmaceutical formulators is compressing procurement cycles and unbundling technical service components from bulk ingredient contracts. Standardized extract suppliers now compete on dossier completeness rather than volume pricing alone. This pattern is most visible in German and United States procurement offices where cardiovascular health applications dominate flavanone sourcing decisions.
Flavanones Market Segmentation
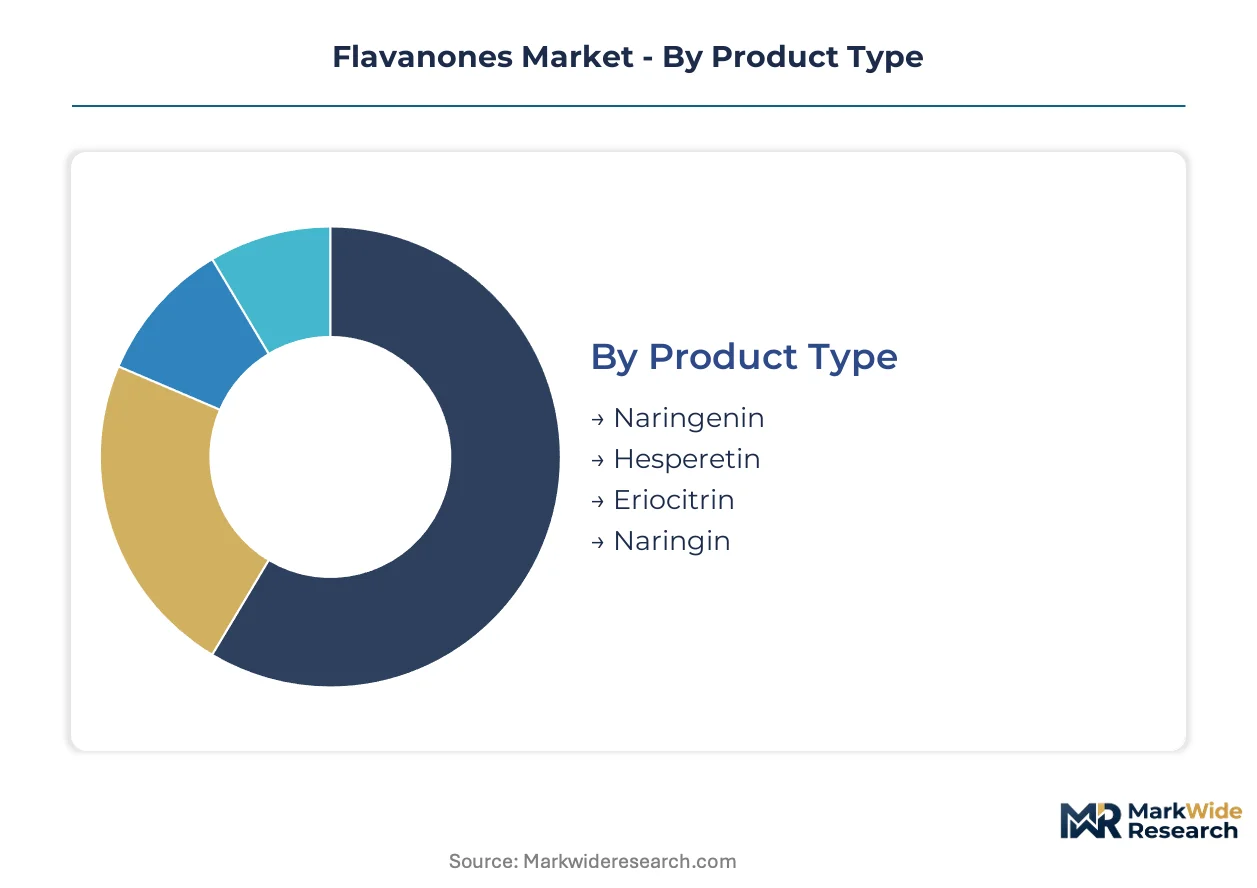
Flavanone suppliers differentiate through purity grades, delivery formats, and regulatory dossier depth rather than commodity volume. Segmentation reflects the tension between pharmaceutical-grade standardization and food-grade cost optimization.
Product Type:
After-sales technical service intensity peaks with naringenin and hesperetin due to EMA botanical drug characterization requirements and FDA GRAS substantiation demands.
- Naringenin:A 2-phenylchroman-4-one flavanone extracted primarily from grapefruit and oranges, typically standardized to 95-98% purity for cardiovascular health applications. Pharmaceutical formulators in Germany and the United States anchor procurement volumes here, driven by clinical substantiation investments for metabolic syndrome indications.
- Hesperetin:The aglycone form of hesperidin, characterized by superior bioavailability when delivered via phytosome encapsulation systems. Dietary supplement manufacturers in the United States concentrate demand for this segment, pulled by evidence-based polyphenol consumption trends and pending EFSA health claim opinions.
- Eriocitrin:Lemon-derived flavanone glycoside gaining traction in cosmeceutical antioxidant serums targeting dermal inflammation.
- Naringin:Bitter citrus flavanone neohesperidoside concentrated in grapefruit peel extracts for food and beverage bitterness modulation.
Naringenin holds the largest share; momentum sits with hesperetin as bioavailability enhancement technologies mature.
End Use Industry:
Cost tier stratification separates pharmaceutical-grade dossier investments from food-grade commodity procurement.
- Pharmaceuticals:EMA botanical drug guidelines and FDA new dietary ingredient notifications demand batch-to-batch analytical standard verification. German and United States formulators dominate procurement, with cardiovascular and metabolic health applications driving naringenin and hesperetin uptake.
- Dietary Supplements:The most structurally dynamic channel, where standardized extracts displace commodity powders. Powder and liquid forms dominate bulk procurement, while extract formulations command premium positioning through bioavailability claims.
- Food & Beverages:Citrus-derived extracts for fortification programs compete on volume pricing, with Layn Natural Ingredients and comparable suppliers anchoring large-scale extraction capacity.
- Cosmetics:Eriocitrin from lemon sources penetrates antioxidant serum formulations, with dermal inflammation modulation claims reshaping permissible marketing language under EU Cosmetics Regulation.
Dietary supplements capture the steepest expansion trajectory; pharmaceuticals retain the highest margin profile.
Form:
Volume concentration in powder and liquid formats contrasts with premium extract positioning in finished goods.
- Powder:Bulk ingredient procurement standard for food fortification and commodity nutraceutical applications, with 80-90% purity grades dominating.
- Liquid:Preferred format for beverage fortification and liquid dietary supplements, offering formulation flexibility but demanding stability testing.
- Extract:Standardized to 95-98% purity via supercritical CO2 methods, commanding premium pricing in pharmaceutical and research-grade contracts.
- Granule:Emerging format for direct-compression tablet manufacturing, reducing excipient load in high-dose flavanone formulations.
Powder holds the largest share; extract is climbing the fastest as pharmaceutical-grade procurement accelerates.
Source:
Supply concentration in Mediterranean and Florida citrus belts exposes procurement to climate volatility and agricultural input cost swings.
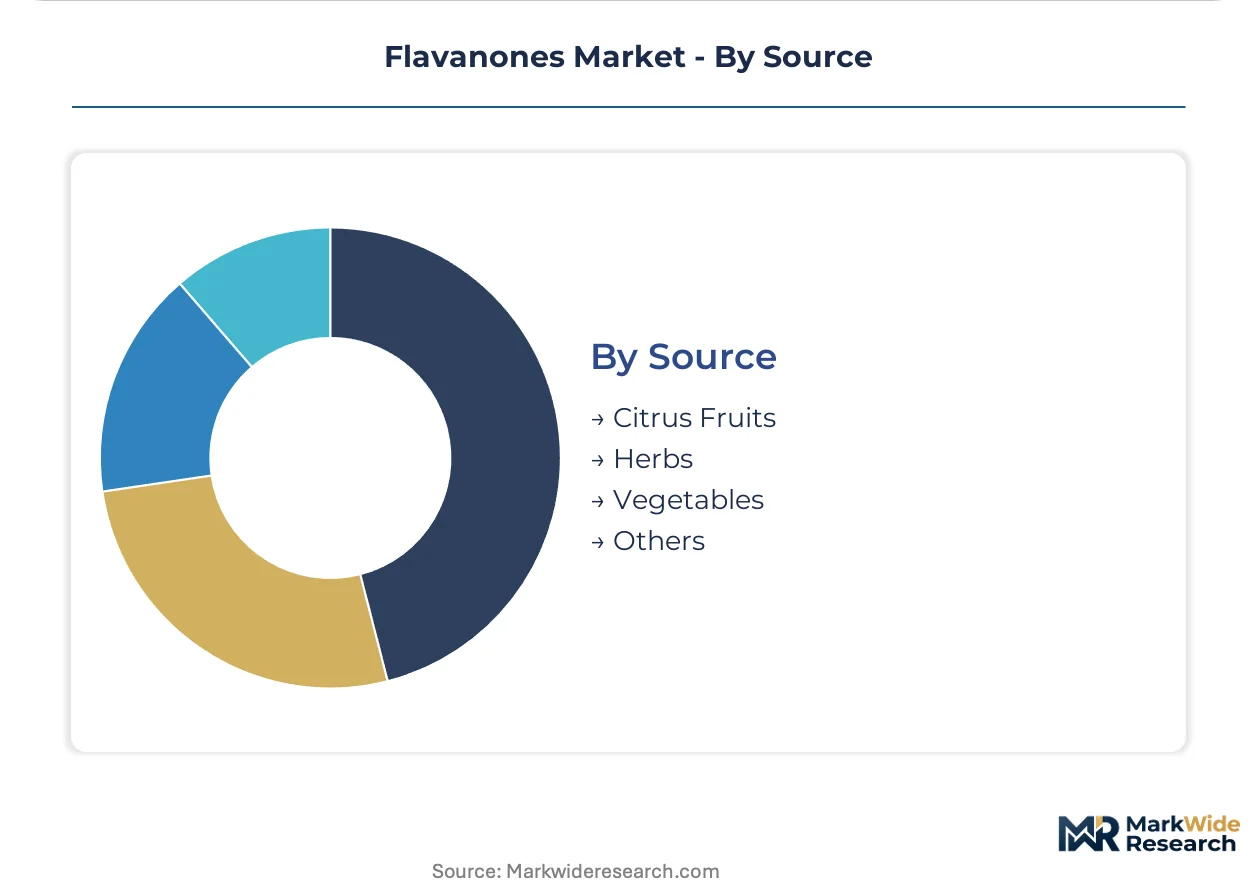
- Citrus Fruits:Grapefruit, orange, and lemon peels yield naringenin, hesperetin, and eriocitrin through solvent extraction or supercritical CO2 methods. Harvest concentration in Spain, Italy, and Florida creates geographic supply risk.
- Herbs:Mint and rosemary sources provide alternative flavanone profiles, though commercial scale remains limited relative to citrus.
- Vegetables:Tomato and artichoke extracts contain minor flavanone concentrations, primarily serving research applications.
- Others:Fermentation-derived and synthetic biology approaches under development for supply chain diversification.
Citrus fruits hold the largest share; herbs are gaining share fastest as suppliers seek climate-resilient alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade buyers in Germany and the United States absorb price premiums with minimal elasticity, while food-grade procurement in China and India operates under acute cost sensitivity. Dietary supplement formulators in Japan occupy a middle tier, balancing bioavailability claims against volume pricing.
United States
FDA GRAS notification requirements for new dietary ingredients shape naringenin and hesperetin product development timelines. The agency's 18-24 month review cycles extend commercialization pathways for novel flavanone sources. New Jersey and California clusters host pharmaceutical formulators expanding cardiovascular health applications.
Germany
EMA botanical drug substance characterization guidelines accelerate clinical substantiation investments for standardized extract suppliers. REACH registration obligations for imported botanical extracts favor dossier-capable suppliers with established regulatory affairs functions. Bavaria's pharmaceutical manufacturing corridor anchors procurement decisions for metabolic health formulations.
China
NMPA oversight of botanical drug extracts creates parallel compliance tracks for domestic and export-bound production. Supercritical CO2 extraction technology adoption concentrates in coastal provinces with established fine chemical infrastructure. Zhejiang and Jiangsu provinces house citrus-derived extraction capacity serving both pharmaceutical and food-grade channels.
Japan
METI's Foods with Function Claims system offers a regulatory template for evidence-based flavanone positioning in functional foods. PMDA consultation pathways for quasi-drug applications attract hesperetin suppliers targeting dermal inflammation claims. The Kanto region's supplement manufacturing base drives demand for bioavailability-enhanced formulations.
India
FSSAI standards for nutraceutical ingredients create compliance differentiation between import-dependent and domestic extraction operations. CDSCO botanical drug guidance remains under development, creating uncertainty for pharmaceutical-grade suppliers. Maharashtra and Gujarat host contract manufacturers serving export markets with cost-optimized powder grades.
Flavanones Market Vendor Landscape
Specialized extract houses and diversified ingredient conglomerates split the market along purity-grade and application-depth lines. The vendor base stratifies into three tiers: research-grade analytical standard suppliers, phytosome delivery system specialists, and volume-driven citrus processors. Consolidation pressure concentrates among mid-scale European extract houses facing REACH registration cost escalation. Capacity expansion and strategic technology licensing represent the dominant competitive moves as suppliers seek bioavailability differentiation.
Within the analytical standard tier, Merck KGaA exemplifies premium positioning through research-grade naringenin supply. Indena S.p.A. occupies a specialized position in phytosome delivery systems for hesperetin formulations. Layn Natural Ingredients represents the volume-driven archetype, anchoring large-scale citrus-derived extraction capacity for food and beverage fortification programs.
| Leading Market Players |
|---|
| Merck KGaA |
| Indena S.p.A. |
| Cayman Chemical Company |
| Layn Natural Ingredients |
| Archer-Daniels-Midland Company |
| DSM Nutritional Products |
| Ingredion Incorporated |
| Givaudan |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Zhejiang province's supercritical CO2 extraction capacity expansion is compressing pharmaceutical-grade naringenin premiums as 95-98% purity output scales. This coastal cluster's cost structure directly determines downstream pricing power for European and North American formulators.
Pricing Analysis
After-sales technical service contracts now generate disproportionate lifetime value as EMA botanical drug dossier requirements extend supplier engagement timelines. Three-tier pricing structure across premium, standard, and economy levels separates research-grade analytical standards from commercial extracts and commodity powders. Price differentiation rests on certification depth and bioavailability enhancement technology licensing. Cost compression in food-grade channels is intensifying because Layn Natural Ingredients and comparable volume players compete on citrus extraction scale. Dietary supplement manufacturers show acute price sensitivity; pharmaceutical formulators in Germany absorb premiums with minimal elasticity.
Supply Chain Analysis
Climate exposure across Spain, Italy, and Florida dominates supply chain risk assessment for citrus-derived flavanone procurement. Raw material sourcing draws from grapefruit peel, orange peel, and lemon peel concentrates with limited geographic diversification. Single-source vulnerability in Mediterranean harvests threatens naringenin and hesperetin contract fulfillment during adverse weather cycles. Distribution runs through specialized extract houses and diversified ingredient distributors, with direct pharmaceutical procurement gaining share in high-purity tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service and regulatory dossier development now expand faster than bulk ingredient sales, transforming flavanone supply into a service-attach business model. Recurring revenue from batch-to-batch consistency verification and EMA submission support outpaces commodity powder growth.
For Market Incumbents: Pre-empt margin erosion from supercritical CO2 technology diffusion by locking long-term offtake agreements with German pharmaceutical formulators. Patent-protected phytosome delivery systems for hesperetin represent a defensible lever against generic encapsulation entrants. Backward integration into Spanish and Italian citrus processing secures raw material preference ahead of climate volatility.
For New Entrants and Emerging Players: Build out fermentation-derived flavanone capacity as climate-resilient supply alternatives gain traction with sustainability-focused buyers. Japan's Foods with Function Claims system offers the most penetrable regulatory pathway for evidence-based positioning. Cosmeceutical eriocitrin formulations targeting dermal inflammation present an underserved application with lower incumbent concentration.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors extract houses with established REACH dossier capabilities and supercritical CO2 infrastructure. Long-term viability across the analysis window hinges on regulatory compliance depth rather than volume scale. Watch EFSA polyphenol-specific health claim determinations as the inflection signal for direct-to-consumer marketing expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Enables 95-98% purity naringenin supply for EMA-compliant pharmaceutical contracts. |
| Phytosome Delivery System Licensing | Secures bioavailability differentiation for hesperetin formulations in dietary supplements. |
| REACH Dossier Investment | Unlocks EU pharmaceutical procurement for imported botanical extract suppliers. |
| Fermentation-Derived Supply Development | Diversifies raw material base beyond climate-exposed citrus belt harvests. |
| EFSA Health Claim Submission | Positions standardized extracts for direct cardiovascular benefit marketing. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pharmaceutical formulators, dietary supplement manufacturers, citrus extraction plant managers, and regulatory affairs specialists at EMA-notified bodies. Secondary validation incorporated FDA GRAS notification databases, EMA botanical drug submission records, REACH registration dossiers, and customs trade data for citrus-derived extracts. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Calibration against historical purity-grade pricing spreads and technology adoption curves informed projections across the modeling period. Segmentation dimensions included product type, end-use industry, form, and geographic regulatory cluster. CAGRs were derived from supply-side capacity buildout trajectories and demand-pull indicators in cardiovascular health applications. Supercritical CO2 extraction technology diffusion rates and EFSA opinion timelines served as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese fine chemical conglomerates or rapid EFSA claim approvals would shift outcomes materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Global Chicory Market
Flavorings and Food Additives
Feed Flavors and Sweeteners Market
Flavorings and Food Additives
Feed Flavors, Sweeteners and Natural Enhancers Market
Flavorings and Food Additives
US Essential Oil Market
Flavorings and Food Additives
Caralluma Extract Market
Flavorings and Food Additives
Flavor Masking Agents Market
Flavorings and Food Additives
Blueberry Extract Market
Flavorings and Food Additives
Yeast Based Savory Flavors Market
Flavorings and Food Additives
Flavoring Oil Market
Flavorings and Food Additives
Food Colorants Market
Flavorings and Food Additives
1-Decanol Market
Flavorings and Food Additives
Beverage Flavoring Agent Market
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
Flavor Emulsions Market
Flavorings and Food Additives
Coloring Foodstuffs Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market