
 EVA Resins and Films Market | 2026-2036
EVA Resins and Films Market Size, Share, and Industry Trends Forecast 2026-2036
EVA Resins and Films Market Analysis
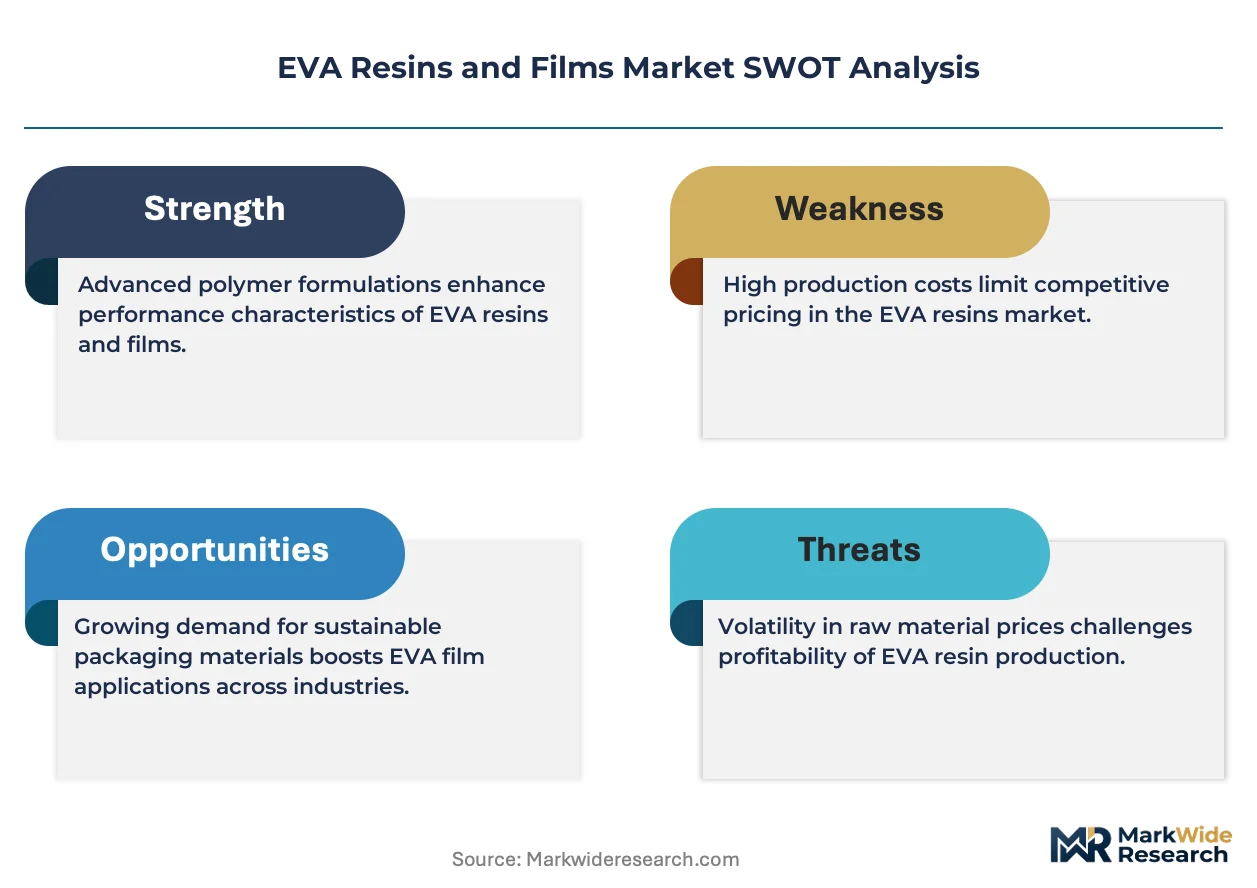
Asian petrochemical complexes is expanding EVA copolymer output to serve photovoltaic encapsulant demand. Dow Inc. leverages integrated ethylene feedstock positions across the US Gulf Coast to sustain cost-advantaged resin supply. Hanwha Solutions Corporation anchors downstream film production through captive demand from its solar module operations. ExxonMobil Corporation competes on high-pressure tubular reactor technology that yields specialized low-density grades for premium encapsulant applications.
EVA resins and films comprise ethylene-vinyl acetate copolymers containing 18-40% vinyl acetate by weight, produced via high-pressure autoclave or tubular reactor processes at 1,000-3,000 bar and 150-300°C. These materials function as thermoplastic sealants, adhesives, and encapsulants distinguished by optical clarity, low-temperature flexibility, and UV stability. Low Density EVA dominates photovoltaic encapsulant films due to its balance of light transmission and damp-heat resistance, while Modified EVA represents the fastest-growing product category as perovskite-silicon tandem cells drive formulation innovation. Packaging applications remain the largest volume segment though margin pools have shifted toward solar-grade films where certification barriers protect qualified suppliers.
The US EPA oversees volatile organic compound emissions from EVA hot-melt adhesive formulations under Clean Air Act standards, while China's MEE enforces GB standards for plastic product recyclability that affect film waste streams. The EU REACH regulation restricts phthalate plasticizer content in consumer-contact EVA articles, compelling reformulation across footwear and toy segments. Stakeholders must monitor evolving module certification protocols from IEC and evolving national carbon border adjustments that will requalify resin sourcing decisions.
Market Dynamics
Photovoltaic encapsulant certification requirements are compressing supplier qualification timelines as module manufacturers consolidate procurement around pre-approved resin-film integrators with captive polymerization capacity.
Growth Catalysts
- China's dual carbon goals:National mandates for renewable energy deployment are accelerating utility-scale solar farm construction, pulling EVA film demand through module assembly expansion in Jiangsu and Zhejiang provinces.
- Perovskite-silicon tandem commercialization:Next-generation cell architectures require modified EVA formulations with enhanced moisture barrier properties, creating premium formulation opportunities for qualified compounders.
- East Asian manufacturing clusters:Integrated EVA-to-module production corridors along China's coastal provinces concentrate demand pull and reduce logistics friction for resin suppliers.
Market Restraints
- Ethylene feedstock volatility:Naphtha-cracker economics tie EVA resin costs to crude oil price swings, compressing margin predictability for non-integrated compounders without upstream ethylene positions.
- High-pressure reactor concentration:Tubular and autoclave polymerization capacity clusters among a limited set of petrochemical complexes, creating supply concentration risk during planned maintenance cycles.
- Cross-linked EVA substitution:Polyolefin elastomer alternatives with enhanced damp-heat resistance threaten standard EVA encapsulant share in premium module segments.
Strategic Opportunities
- India's solar manufacturing PLI scheme:Production-linked incentives for domestic module assembly are attracting EVA film extrusion investment to Gujarat and Tamil Nadu, opening new demand geography.
- EU F-Gas Regulation alignment:Carbon border adjustment mechanisms favor low-emission resin sourcing, rewarding suppliers with verified Scope 3 reductions in their ethylene supply chains.
- Building-integrated photovoltaics:Architectural solar glass applications require optically graded EVA with precise haze control, expanding addressable market beyond standard module encapsulation.
Industry Challenges
- Polymerization process engineering talent:High-pressure reactor operation and safety management expertise resides with a narrow cohort of specialists, constraining capacity expansion timelines.
- IEC 62788 certification cycles:Extended damp-heat and UV-aging test protocols delay new formulation commercialization, locking out unqualified suppliers from utility-scale procurement.
- Legacy adhesive formulation reformulation:REACH phthalate restrictions in consumer-contact applications force footwear and toy segment compounders to rebuild plasticizer packages without supply disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EVA Resins and Films Market |
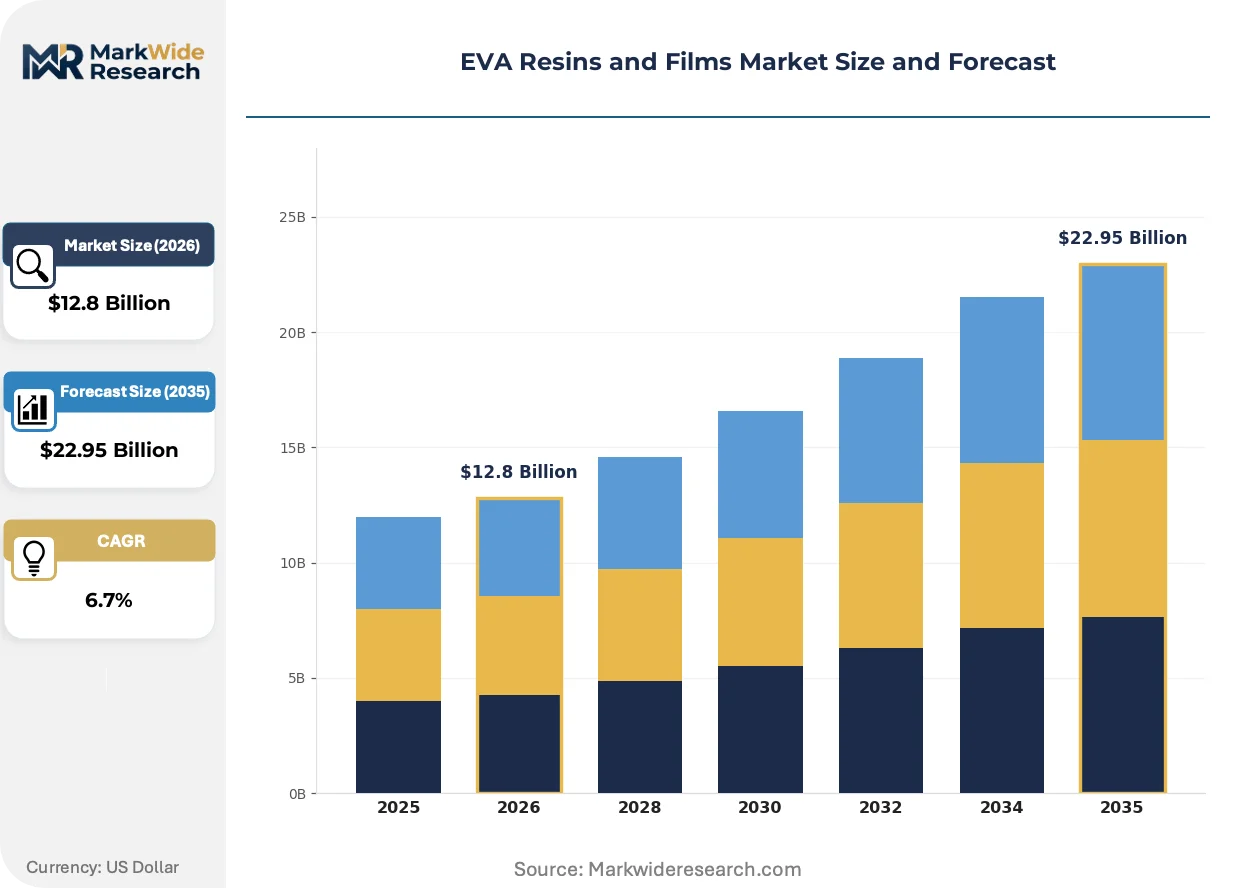
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Density EVA, High Density EVA, Ethylene Co-Polymer, Modified EVA Application: Packaging, Automotive, Footwear, Construction End User: Manufacturers, Retailers, Distributors, Importers Form: Films, Sheets, Granules, Compounds |
| Companies Covered | Hanwha Solutions Corporation, Celanese Corporation, 3M Company, Dow Inc., ExxonMobil Corporation, Arkema S.A., LyondellBasell Industries, Kuraray Co., Ltd., Hangzhou First Applied Material Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EVA Resins and Films Market Emerging Trajectories
Photovoltaic cell technology roadmaps are fragmenting encapsulant specifications as perovskite tandems, heterojunction architectures, and bifacial module designs each demand tailored EVA optical and barrier properties.
Modified EVA copolymers with silane-grafted crosslinking chemistry are decentralizing the traditional encapsulant supply hierarchy. Tier-two module manufacturers in Southeast Asia are adopting these formulations to bypass incumbent supplier qualification bottlenecks. The technology is decentralizing procurement decisions from centralized engineering teams to regional plant managers with formulation flexibility.
The EU F-Gas Regulation and accompanying carbon border adjustment mechanisms are tightening embodied carbon tracking requirements for imported EVA films. Module assemblers serving European markets now require resin sourcing documentation from ethylene cracker to final extrusion. Solar-grade film suppliers with integrated European polymerization assets are capturing preference share from Asia-origin competitors facing documentation friction.
Buyer concentration among vertically integrated solar module manufacturers is compressing spot market liquidity for standard EVA resins. Long-term offtake agreements with fixed volume floors now dominate procurement in the photovoltaic segment. This shift is most visible in China where state-owned energy developers bundle resin-film-module procurement through centralized tender platforms, squeezing independent compounders without captive downstream demand.
EVA Resins and Films Market Segmentation
EVA resin and film specifications diverge sharply across photovoltaic encapsulation, footwear cushioning, and packaging sealant applications. Each end-use imposes distinct vinyl acetate content ranges, melt flow indices, and crosslinking requirements that fragment supplier qualification pathways. Understanding these segment boundaries clarifies where formulation premiums concentrate versus where commodity competition dominates.
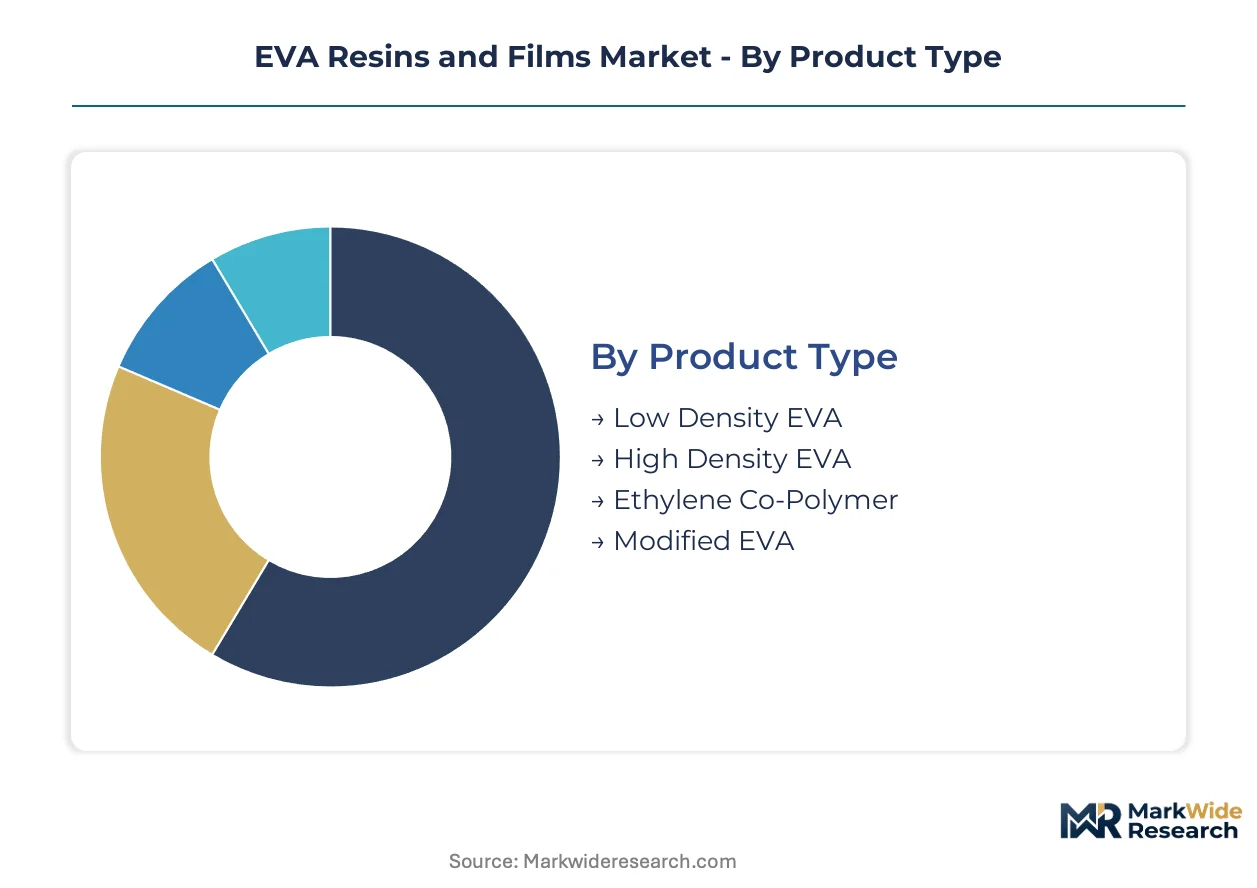
Product Type:
Volume production clusters in standard-density grades, while specialty modified formulations command disproportionate margin pools in next-generation solar applications.
- Low Density EVA:Contains 18-28% vinyl acetate with melt flow indices of 2-30 g/10min, optimized for optical clarity and UV stability. Photovoltaic module manufacturers in Jiangsu and Zhejiang provinces concentrate procurement here, driven by IEC 62788 certification requirements that lock out unqualified compounders.
- Modified EVA:Incorporates silane-grafting, acid copolymer, or barrier additive chemistries for perovskite-silicon tandem cells and bifacial modules. Perovskite commercialization timelines are pulling demand toward moisture-resistant formulations with enhanced damp-heat performance, expanding most quickly among product categories.
- High Density EVA:28-40% vinyl acetate content delivers Shore A hardness above 90 for rigid industrial applications. Construction adhesive and automotive interior panel demand centers on this grade.
- Ethylene Co-Polymer:Blends EVA with ethylene-acrylic acid or ethylene-methyl acrylate for modified sealant properties. Hot-melt adhesive compounders utilize these intermediates for packaging and bookbinding applications.
Today's leader: Low Density EVA. Tomorrow's challenger: Modified EVA.
Application:
Photovoltaic encapsulation has displaced packaging as the primary margin driver, though footwear and construction retain distinct formulation specifications.
- Packaging:Hot-melt adhesives and shrink films utilize 18-25% VA grades for food and consumer goods sealing. EU REACH phthalate restrictions are forcing reformulation of legacy adhesive packages without supply disruption.
- Automotive:Interior trim bonding and acoustic dampening applications specify low-odor, low-fogging EVA grades. China's MIIT fuel efficiency standards are expanding lightweight material adoption in vehicle assembly.
- Footwear:Midsole cushioning and outsole bonding require 28-33% VA content with specific rebound resilience metrics. Southeast Asian contract manufacturers dominate procurement for athletic and casual shoe production.
- Construction:Waterproofing membranes and flooring adhesives specify high-density grades with enhanced filler acceptance. Building-integrated photovoltaics are creating hybrid demand for optically graded construction films.
Solar-grade encapsulation now commands pricing premiums that packaging volumes cannot match.
End User:
Procurement authority concentrates with integrated manufacturers, while distributor channels face margin compression from direct resin-film arrangements.
- Manufacturers:Solar module assemblers, footwear factories, and automotive tier-one suppliers specify resin grades directly. China's state-owned energy developers bundle resin-film-module procurement through centralized tender platforms.
- Retailers:Big-box chains and specialty distributors stock standard adhesive and film products for maintenance and repair markets. Inventory turns favor commodity grades with predictable specification ranges.
- Distributors:Regional chemical distributors aggregate small-lot demand from compounders and converters. Qualification documentation requirements from European carbon border adjustments are raising compliance costs for cross-border trade.
- Importers:Trading houses arbitrage regional price differentials for standard EVA resins. Spot market liquidity is compressing as long-term offtake agreements dominate photovoltaic procurement.
Direct manufacturer relationships now determine supplier viability more than distributor network breadth.
Form:
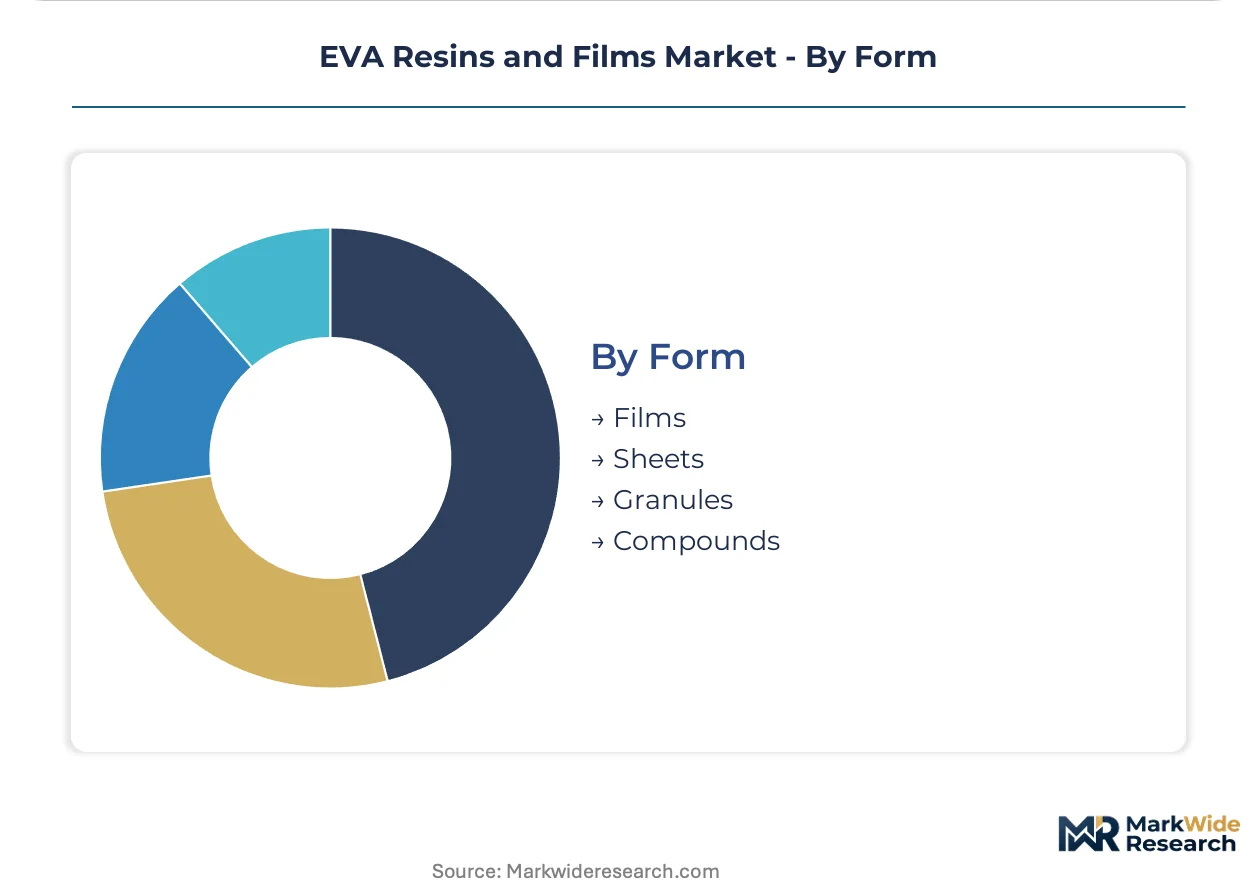
Film extrusion captures value-added processing margins, while granule and compound forms serve formulation flexibility needs.
- Films:Calendered and blown films for photovoltaic encapsulation specify precise thickness tolerance and haze control. Integrated EVA-to-film production lines in China's coastal provinces concentrate supply.
- Sheets:Thick-gauge extruded sheets serve footwear sole molding and automotive interior lamination. Thickness consistency requirements are tighter than film applications.
- Granules:Pelletized resin for downstream compounding and masterbatch production. Compounders in India's Gujarat and Tamil Nadu are expanding granule processing capacity under PLI scheme incentives.
- Compounds:Pre-formulated blends with crosslinking agents, stabilizers, and fillers for specific end-use performance. Modified EVA compounds with silane-grafting chemistry are decentralizing traditional supply hierarchies.
Film form factors absorb disproportionate capital investment as module certification requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing EVA resin and film production toward jurisdictions with lower carbon-accounting burdens and streamlined certification pathways, particularly as the EU F-Gas Regulation and carbon border adjustment mechanisms raise compliance costs for Asian exporters.
China
State-owned energy developers bundle resin-film-module procurement through centralized tender platforms, concentrating demand pull in Jiangsu and Zhejiang provinces. The Ministry of Ecology and Environment enforces GB standards for plastic product recyclability that reshape film waste stream economics. Integrated EVA-to-module production corridors along coastal provinces dominate supply, with tubular reactor capacity expanding to serve photovoltaic encapsulant qualification requirements.
United States
Dow Inc. leverages integrated ethylene feedstock positions across the Gulf Coast to sustain cost-advantaged resin supply for domestic module assembly. The EPA oversees volatile organic compound emissions from hot-melt adhesive formulations under Clean Air Act standards. Houston and Corpus Christi anchor high-pressure autoclave and tubular reactor operations that supply both solar-grade films and packaging adhesives.
Germany
The EU F-Gas Regulation and REACH phthalate restrictions compel reformulation of legacy adhesive packages for footwear and consumer goods segments. ECHA documentation requirements for embodied carbon tracking favor suppliers with verified Scope 3 reductions. The Rhine-Ruhr industrial corridor hosts compounders serving building-integrated photovoltaic applications with optically graded films.
India
Production-linked incentives for domestic module assembly under the PLI scheme are attracting EVA film extrusion investment to Gujarat and Tamil Nadu. The Bureau of Indian Standards enforces certification protocols that delay new supplier entry. Ahmedabad and Chennai emerging as alternative demand geography as procurement shifts from China-origin supply.
South Korea
Hanwha Solutions Corporation anchors downstream film production through captive demand from its solar module operations, concentrating procurement authority with integrated manufacturers. METI-aligned standards influence regional qualification timelines for damp-heat and UV-aging performance. The Ulsan petrochemical complex maintains high-pressure reactor expertise that constrains competitor capacity expansion.
EVA Resins and Films Market Vendor Landscape
East Asian producers anchor the volume tier; US Gulf Coast specialists hold feedstock-integrated positions. The market structures around three tiers: integrated petrochemical majors with captive ethylene supply, regional compounders serving qualified film extruders, and specialty formulation houses addressing perovskite-silicon tandem requirements. Strategic moves concentrate on backward integration into polymerization capacity and long-term offtake contracting with state-backed solar developers.
Within the integrated-major tier, Hanwha Solutions Corporation exemplifies captive demand strategies, while Dow Inc. and ExxonMobil Corporation occupy positions defined by feedstock access and reactor technology differentiation. These three anchors represent distinct competitive archetypes: Korean conglomerate vertical integration, American Gulf Coast feedstock economics, and high-pressure tubular reactor specialization for premium encapsulant grades.
| Leading Market Players |
|---|
| Hanwha Solutions Corporation |
| Celanese Corporation |
| 3M Company |
| Dow Inc. |
| ExxonMobil Corporation |
| Arkema S.A. |
| LyondellBasell Industries |
| Kuraray Co., Ltd. |
| Hangzhou First Applied Material Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between IEC 62788-qualified solar encapsulants and commodity packaging resins manifests in divergent margin structures and procurement channel configurations across the EVA value chain. Premium film extruders with verified damp-heat performance capture long-term offtake premiums from state-backed developers in Jiangsu, while standard-grade compounders face spot-market compression without captive polymerization assets.
Pricing Analysis
Distributor margin layers compress as direct resin-film arrangements dominate photovoltaic procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and volume commitment scale, with solar-grade films commanding sustained premiums over packaging adhesives. Cost compression in standard EVA resins intensifies because ethylene feedstock volatility transfers margin risk to non-integrated compounders. State-owned energy developers exhibit lowest price sensitivity due to bundled tender platforms, while independent distributors face margin erosion from documentation-heavy cross-border trade.
Supply Chain Analysis
Freight cost differentials favor integrated EVA-to-module production corridors along China's coastal provinces over Asia-Europe container routes for European market supply. High-pressure tubular and autoclave reactor capacity clusters in China, South Korea, and the United States, with ethylene feedstock sourcing anchored in Gulf Coast naphtha crackers and Asian petrochemical complexes. Supply chain risk centers on single-source vulnerability during planned maintenance cycles at limited reactor facilities. Distribution runs through long-term offtake agreements with fixed volume floors rather than spot market liquidity for qualified solar-grade films.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EVA resins and films market reads as a late-cycle quality story where perovskite-silicon tandem commercialization pulls procurement toward moisture-barrier formulations with enhanced damp-heat specifications.
For Market Incumbents: To counter polyolefin elastomer substitution threats in premium module segments, backward integration into high-pressure reactor capacity secures feedstock cost positions while silane-grafting R&D investments lock in perovskite encapsulant formulation leadership. Captive film extrusion assets in Gujarat and Tamil Nadu defend geographic share against PLI-scheme entrants. For New Entrants and Emerging Players: Modified EVA compounds with barrier additive chemistries offer a technology-first wedge into tier-two Southeast Asian module manufacturers bypassing incumbent qualification bottlenecks. India's solar manufacturing PLI scheme presents the most penetrable geography, with BIS certification pathways as the critical go-to-market angle for resin-film integrators. For Investors and Strategic Acquirers: Consolidation pressure builds where high-pressure reactor safety expertise resides with narrow specialist cohorts constraining capacity expansion timelines. Long-term viability favors compounders with verified Scope 3 documentation serving EU carbon border adjustment mechanisms. Watch IEC 62788 certification cycle durations as the signal for supplier lock-in intensity and margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymerization | Gulf Coast ethylene feedstock positions sustain cost-advantaged resin supply against naphtha-cracker volatility. |
| Perovskite-Grade Formulation Development | Silane-grafting chemistry investments capture premium margins from tandem cell commercialization timelines. |
| EU Carbon Documentation Compliance | Verified Scope 3 reductions from ethylene cracker to extrusion secure preference share under F-Gas Regulation alignment. |
| India PLI Scheme Manufacturing Buildout | Gujarat and Tamil Nadu film extrusion capacity addresses procurement shifts from China-origin supply. |
| Long-Term Offtake Contracting | Fixed volume floors with state-owned developers compress spot market exposure and stabilize utilization rates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with high-pressure reactor operators, solar module procurement leads, EVA film extrusion plant managers, and chemical distribution channel partners with secondary validation from customs trade data, SEC petrochemical division filings, IEC certification registries, and national solar deployment statistics. Bottom-up resin demand modeling and top-down encapsulant film value triangulation cross-checked segment outputs.
Segment-weighting approaches applied vinyl acetate content tiers, end-use industry splits, and regional production hub concentrations across the projection horizon. CAGRs derived from damp-heat performance adoption curves and perovskite commercialization timelines, with ethylene feedstock cost indices and module certification protocol evolution as industry-specific forecast inputs.
The model holds under sustained utility-scale solar deployment and stable naphtha-cracker economics; deviation in ethylene feedstock volatility or IEC protocol acceleration would shift resin-grade demand mix and margin distribution. Stakeholders should weight assumptions against their own operating context and captive supply positions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermoplastics Market
Polymers & Resins
Ethylene-Vinyl Alcohol Copolymer (EVOH) Market
Polymers & Resins
Global Ethylene Vinyl Acetate Resins Market
Polymers & Resins
Polyisoprene Latex Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
France Engineering Plastics Market
Polymers & Resins
Global Polymeric Adsorbents Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Expanded Polypropylene Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Polycarbonate Market
Polymers & Resins
US Polymethyl Methacrylate Market
Polymers & Resins
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market
Polymers & Resins
Global Amino Resin Market