
 Sustainable Polymers Market | 2026-2036
Sustainable Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Polymers Market Analytics
Market Context
Subscription-grade material traceability is repositioning how resin suppliers contract with brand owners, shifting transactions from spot-volume to certified-tonnage agreements. Braskem leverages its Brazilian sugarcane ethanol pipeline to anchor global bio-polyethylene supply. BASF competes through specialty compostable grades for food-contact films. NatureWorks dominates North American polylactic acid output with in-house lactic acid fermentation.
Technical Definition and Segments
Sustainable polymers comprise macromolecular materials derived from renewable biomass, post-consumer recycling streams, or designed biodegradation pathways, typically exhibiting melt flow indices between 2 and 50 g/10 min and tensile strengths spanning 20 to 70 MPa depending on filler loading and processing history. These materials serve as drop-in or performance-advantaged substitutes for fossil-derived plastics across packaging, automotive, and textile value chains. Bio-based polymers command premium positioning where brand sustainability commitments require mass-balance certification, while recycled plastics capture volume in non-food packaging as mechanical recycling yields improve. Compostable polymers remain niche, concentrated in food-service disposables where industrial composting infrastructure exists.
Regulatory Framework
The EU Green Deal and REACH constrain virgin petrochemical content in consumer-facing applications, while the FDA and EPA shape US food-contact and environmental release standards for novel biopolymer chemistries. EMA and EFSA evaluations further govern pharmaceutical and food-grade material approvals, creating multi-jurisdictional compliance burdens for cross-border suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and carbon border adjustment mechanisms to anticipate feedstock cost shifts and certification requirements.
Market Dynamics
Mass-balance certification systems are restructuring supplier-brand relationships, converting polymer procurement from commodity spot transactions to audited chain-of-custody contracts that lock in multi-year feedstock allocations.
Growth Catalysts
- EU Green Deal carbon intensity benchmarks:Packaging converters across Germany, France, and Italy now mandate bio-based feedstocks for single-use applications, accelerating certified polymer demand.
- Automotive interior specifications:German OEMs under ECHA REACH protocols require recycled and bio-based polymers for dashboard components, door panels, and seating substrates.
- Industrial composting infrastructure expansion:Netherlands and Belgium are deploying centralized composting facilities that enable food-service disposables to complete certified biodegradation cycles.
Market Restraints
- Sugar ethanol feedstock volatility:Brazilian sugarcane harvest fluctuations directly compress bio-polyethylene margin structures for European importers.
- Mechanical recycling yield ceilings:PET and polyolefin reprocessing tops out at 60-70% purity retention, limiting food-contact applications without downstream purification investments.
- REACH registration burdens:Novel biopolymer chemistries face 18-24 month ECHA evaluation timelines that delay commercial launch in EU consumer markets.
Strategic Opportunities
- India PLI scheme for bioplastics:Domestic fermentation capacity investments under production-linked incentives could capture Asian packaging demand currently served by European imports.
- Pharmaceutical primary packaging:Bio-based barrier films for blister packs and sachets remain underpenetrated versus food packaging, with EMA approval pathways now clarifying.
- Chemical recycling at scale:Pyrolysis and gasification integration with refinery infrastructure enables mixed-waste polymer recovery beyond mechanical sorting limits.
Industry Challenges
- Mass-balance auditor scarcity:ISO 22095-compliant certification bodies number under twenty globally, creating 6-9 month queue delays for supplier onboarding.
- Composting facility interoperability:Industrial composters in Germany operate at 55°C while Italian systems run at 50°C, producing inconsistent biodegradation validation for pan-European food-service brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Polymers Market |
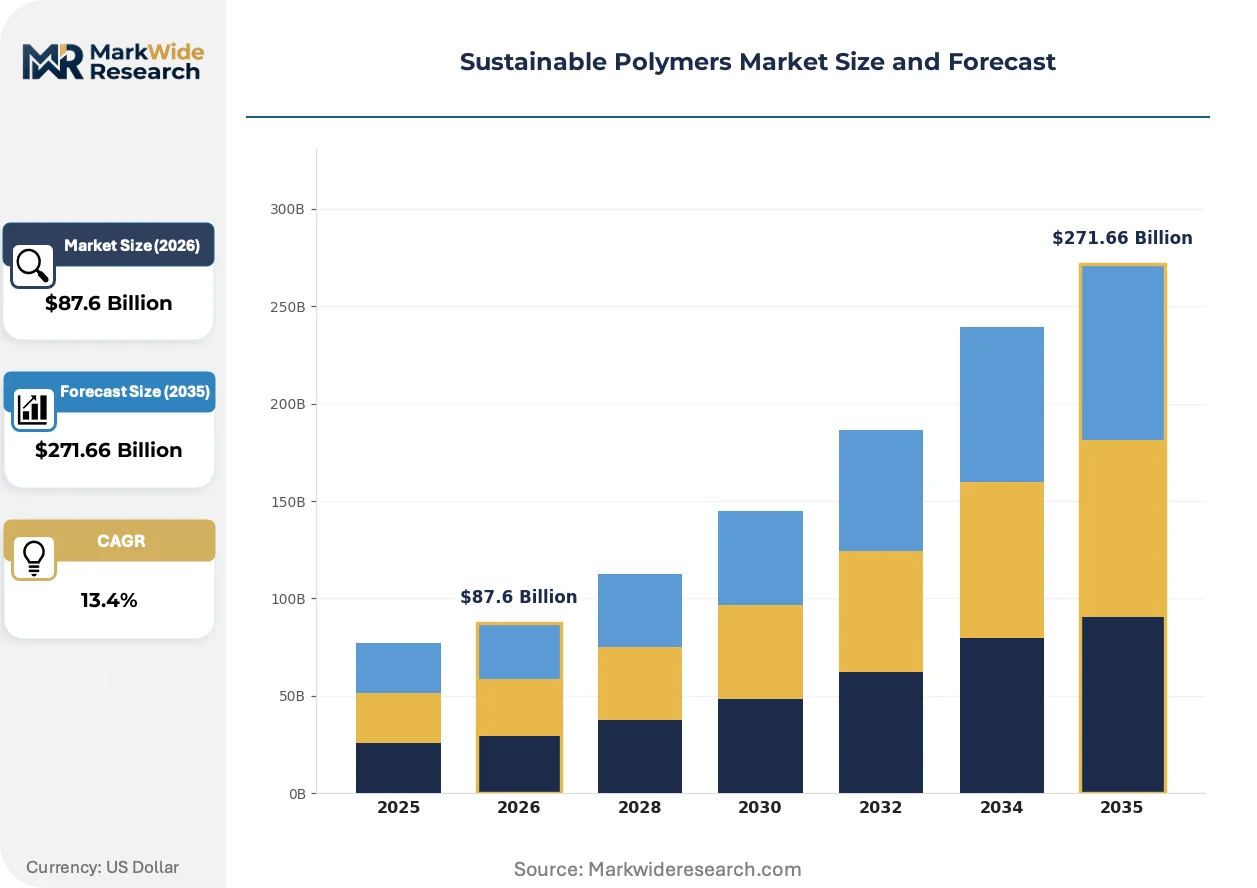
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $271.66 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioplastics, Bio-based Polymers, Recycled Plastics, Compostable Polymers Application: Packaging, Automotive, Textiles, Consumer Goods End User: Manufacturers, Retailers, Brands, Distributors Distribution Channel: Online Sales, Brick-and-Mortar, Wholesale, Direct Sales |
| Companies Covered | Mitsubishi Chemical Corporation, Braskem, NatureWorks, Covestro, DuPont, BASF, Novamont, Arkema, Corbion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Polymers Market Evolving Landscape
Advanced recycling technologies and blockchain-tracked supply chains are converging to resolve the traceability gaps that have long constrained brand-owner confidence in circular polymer claims.
Enzymatic depolymerization is absorbing contaminated and multi-layer plastic waste streams that mechanical processes reject, with European chemical recyclers scaling pilot units to 10,000-tonne annual capacity. Food packaging brands in France and Germany are pre-booking offtake volumes two years forward. The technology is absorbing stranded feedstock costs and compressing reliance on virgin naphtha pricing.
REACH authorization requirements for persistent organic pollutants are tightening impurity thresholds in recycled content, forcing recyclers to deploy advanced spectroscopic sorting. German packaging converters now reject mechanically recycled lots exceeding 100 ppm hazardous substance limits. Automotive suppliers in Stuttgart and Wolfsburg are accelerating chemical recycling partnerships to secure compliant feedstock.
Brand sustainability commitments are converting procurement departments into certification-driven buyers who audit supplier mass-balance documentation before price negotiation. Retailers in the Netherlands and Scandinavia now require ISCC PLUS or RSB certification for private-label packaging. This behavioral shift concentrates contract volumes with vertically integrated resin producers who control feedstock origin documentation.
Sustainable Polymers Market Segmentation
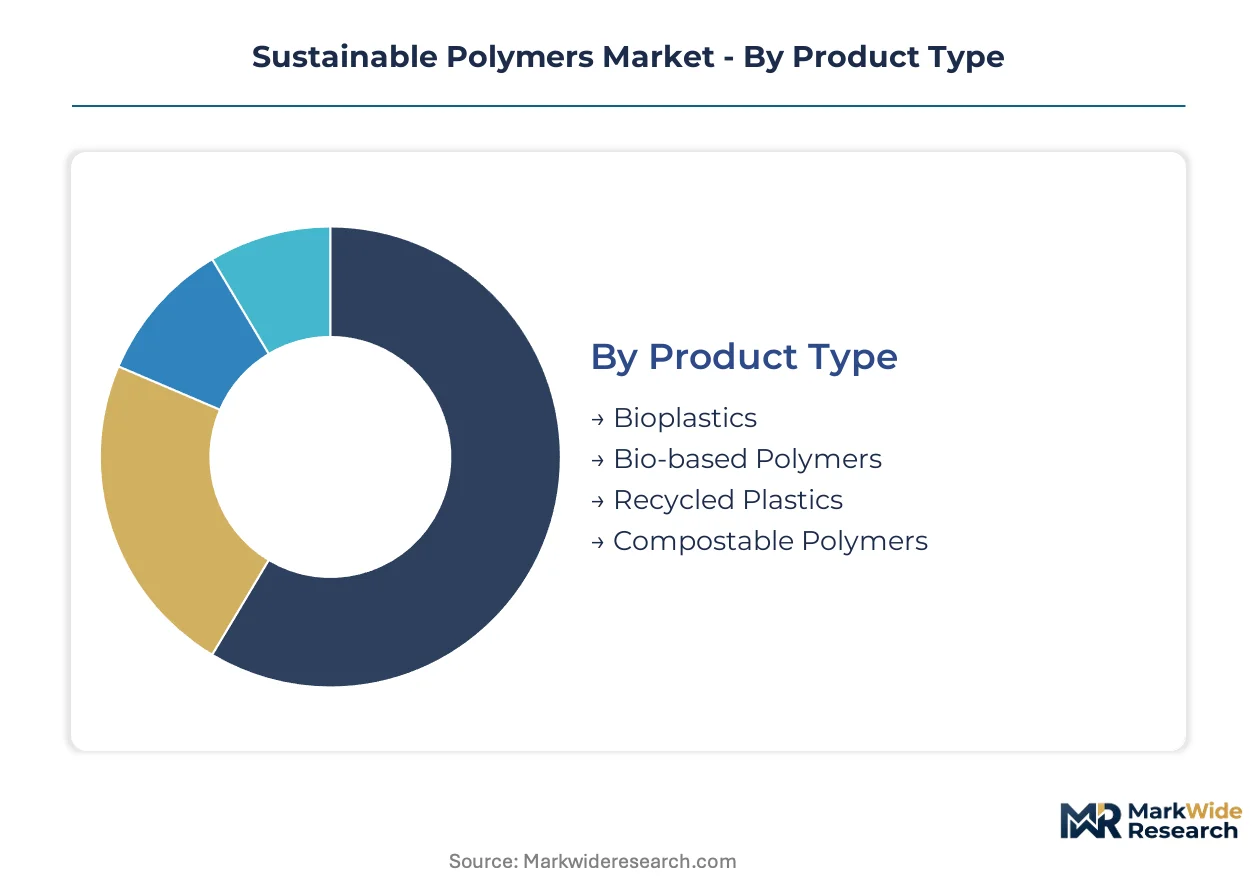
Sustainable polymer procurement now hinges on certification tier rather than commodity pricing alone. Brand owners audit mass-balance documentation before negotiating volume, making segment boundaries increasingly defined by traceability infrastructure rather than chemical composition.
Product Type:
ECHA REACH registrations, FDA food-contact approvals, and EU Green Deal carbon intensity benchmarks impose divergent compliance burdens across material categories.
- Bioplastics:Materials derived from renewable biomass feedstocks such as sugarcane starch or corn ethanol, typically requiring ISCC PLUS or RSB certification for European market access. German packaging converters under EU Green Deal protocols now mandate certified bioplastics for single-use applications, compressing spot-market volumes in favor of multi-year offtake contracts with documented chain-of-custody.
- Recycled Plastics:Post-consumer mechanically reprocessed polymers with melt flow indices adjusted through extrusion compounding. REACH authorization thresholds for persistent organic pollutants now limit mechanically recycled content to non-food packaging in Germany unless downstream purification investments achieve sub-100 ppm hazardous substance compliance.
- Bio-based Polymers:Drop-in petrochemical replacements with identical performance profiles to virgin resins, sourced from biomass via mass-balance allocation methods.
- Compostable Polymers:Materials engineered for industrial biodegradation pathways, concentrated in food-service disposables where Netherlands and Belgium infrastructure enables certified end-of-life cycles.
Recycled plastics sits at the top of the volume ranking, with compostable polymers climbing the fastest.
Application:
Cost tier stratification separates premium certified grades from commodity uncertified volumes across end-use markets.
- Packaging:Films, rigid containers, and flexible pouches serving food-contact and non-food segments. French and German retailers now require ISCC PLUS certification for private-label packaging, converting procurement departments into documentation-driven buyers who audit supplier mass-balance records before price negotiation.
- Automotive:Interior components including dashboard substrates, door panels, and seating materials. ECHA REACH compliance protocols in Germany specify recycled and bio-based polymer content for OEM interior specifications, with Stuttgart and Wolfsburg suppliers accelerating chemical recycling partnerships to secure compliant feedstock.
- Textiles:Fiber applications spanning apparel and industrial nonwovens.
- Consumer Goods:Durable products and electronics housings with lower certification burdens than food-contact or automotive segments.
Packaging commands the dominant revenue share, while automotive applications gain share fastest as OEM sustainability targets tighten.
End User:
Customer type determines contract structure, with integrated manufacturers locking in multi-year allocations while distributors remain exposed to spot volatility.
- Manufacturers:Converters and compounders with in-house extrusion and molding capabilities. These stakeholders under EMA and EFSA pharmaceutical packaging pathways drive demand for bio-based barrier films in blister packs and sachets, a segment where food packaging certification experience now transfers to underpenetrated medical applications.
- Retailers:Private-label brand owners with direct consumer-facing sustainability commitments. Netherlands and Scandinavian retailers now reject uncertified resin lots, concentrating contract volumes with vertically integrated producers who control feedstock origin documentation.
- Brands:CPG companies with published plastic reduction targets.
- Distributors:Intermediary traders without certification infrastructure, increasingly marginalized as procurement shifts to audited chain-of-custody contracts.
Manufacturers anchor contract volume, with retailers expanding their share fastest as sustainability commitments harden into procurement mandates.
Distribution Channel:
Supply concentration in certified-tonnage agreements favors direct relationships over intermediary channels.
- Online Sales:Digital procurement platforms for standardized resin grades with published technical data sheets. These channels serve small-batch buyers without dedicated sourcing teams, though mass-balance certification documentation typically requires direct supplier contact.
- Brick-and-Mortar:Physical distribution points for regional converters.
- Wholesale:Volume aggregation for commodity grades without certification requirements, losing share as branded procurement shifts to audited allocations.
- Direct Sales:Supplier-brand relationships with embedded certification auditing and multi-year feedstock locking. Braskem's Brazilian sugarcane ethanol pipeline and NatureWorks' in-house lactic acid fermentation exemplify this channel's integration with captive feedstock control.
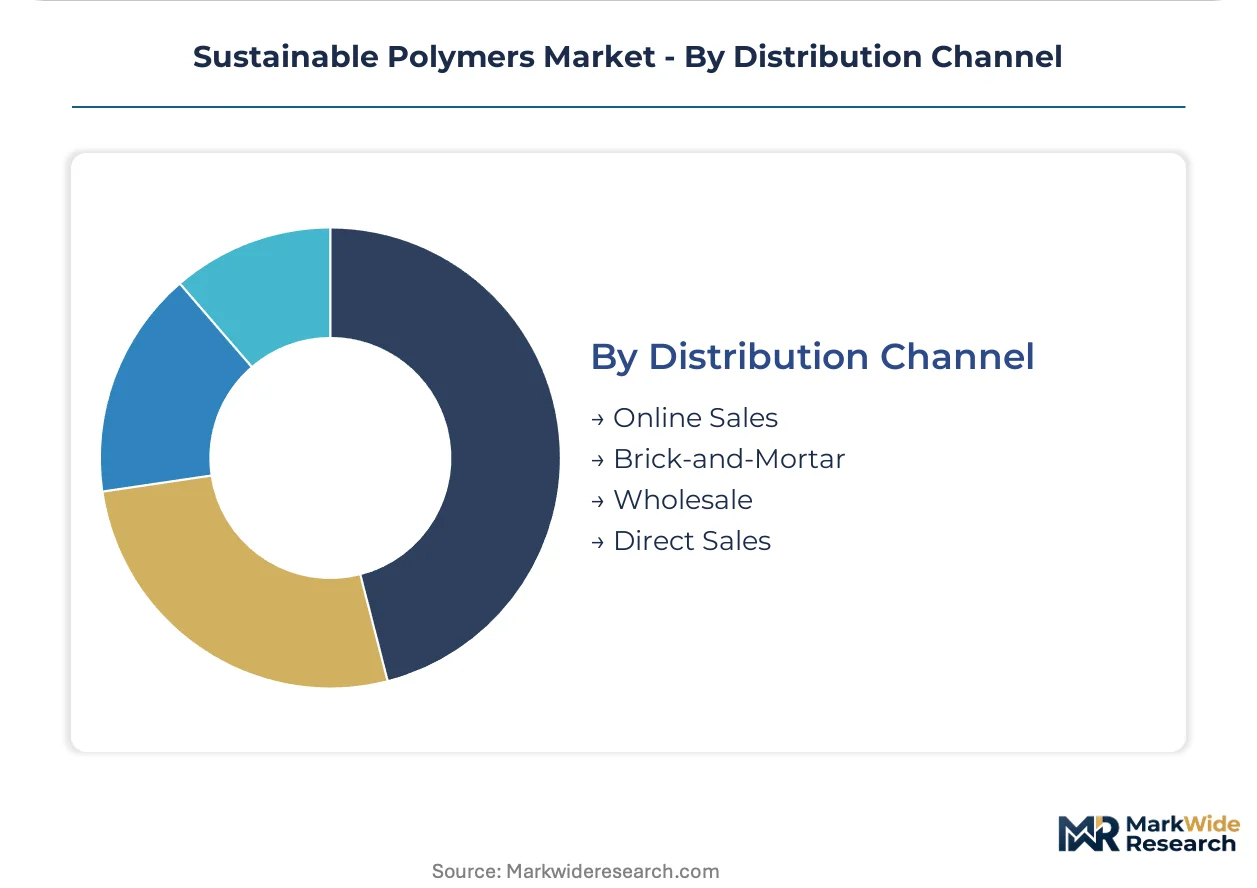
Direct sales dominates certified polymer volume, with online channels expanding fastest for standardized technical grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands certified polymer procurement volume through automotive and packaging mandates, while the United States concentrates investment in chemical recycling scale-up. Brazil anchors bio-based feedstock supply through sugarcane ethanol infrastructure. India and the Netherlands represent contrasting growth vectors through production incentives and composting infrastructure deployment.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify recycled and bio-based polymers for interior components under ECHA REACH protocols. The EU Green Deal carbon intensity benchmarks tighten quarterly, forcing packaging converters to lock multi-year certified feedstock contracts. Bavaria and Baden-Württemberg host the densest concentration of mass-balance audited suppliers.
United States
FDA food-contact approvals and EPA environmental release standards shape novel biopolymer commercialization timelines. Chemical recyclers scale pyrolysis units to 10,000-tonne annual capacity, with Gulf Coast petrochemical infrastructure enabling mixed-waste polymer recovery. Houston and Chicago clusters absorb pre-booked offtake volumes from French and German packaging brands.
Brazil
Braskem leverages the Paulista sugarcane belt to anchor global bio-polyethylene supply through captive ethanol fermentation. Harvest volatility compresses margin structures for European importers during El Niño cycles. São Paulo state concentrates 70% of certified bio-based resin export capacity.
India
The PLI scheme for bioplastics incentivizes domestic fermentation capacity investments targeting Asian packaging demand. Maharashtra and Gujarat host pilot polylactic acid facilities seeking ISCC PLUS certification. CDSCO pharmaceutical packaging pathways remain underpenetrated versus food-contact segments.
Netherlands
Centralized industrial composting facilities at 55°C enable certified biodegradation cycles for food-service disposables. Rotterdam polymer traders audit mass-balance documentation before price negotiation, marginalizing uncertified distributors. Randstad retailers require RSB certification for private-label packaging procurement.
Sustainable Polymers Market Competitive Landscape
Top-tier vendors anchor certified-tonnage contracting, while commodity spot traders lose share to audited chain-of-custody suppliers. The vendor base stratifies across three archetypes: vertically integrated feedstock controllers, specialty compostable grade developers, and regional mechanical recyclers. Capacity expansion and strategic partnerships dominate competitive moves as producers secure multi-year allocations with brand owners.
Within the bio-based polymer tier, Braskem and NatureWorks exemplify feedstock-integrated positioning. Braskem represents the sugarcane ethanol-to-polyethylene archetype through its Brazilian pipeline control. NatureWorks occupies the North American polylactic acid position with in-house lactic acid fermentation. BASF anchors the specialty compostable grade segment for food-contact film applications. Mitsubishi Chemical Corporation, Covestro, and Arkema sit within the diversified chemical conglomerate tier, leveraging existing polymer science infrastructure to enter certified sustainable grades.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Braskem |
| NatureWorks |
| Covestro |
| DuPont |
| BASF |
| Novamont |
| Arkema |
| Corbion |
| Others |
Value Network & Pricing Analysis
Brazilian sugarcane ethanol spot prices transmit directly through bio-polyethylene cost curves, compressing margins for European converters when harvest volatility strikes. This feedstock dependency stratifies pricing power between captive-ethanol producers and import-dependent compounders.
Pricing Analysis
Capacity additions in India under PLI scheme incentives are reshaping price floors for Asian bio-based polymer procurement. Three-tier pricing structure across ISCC PLUS-certified premium, mechanically recycled standard, and uncertified economy grades separates contract volumes. Cost compression in European bio-polyethylene is intensifying because Brazilian ethanol import exposure remains unhedged. Automotive OEMs in Germany exhibit lowest price sensitivity due to REACH-mandated specification requirements, while commodity distributors face margin erosion from spot-market volatility.
Supply Chain Analysis
Direct-to-brand channels handle certified-tonnage demand from Netherlands and Scandinavian retailers requiring mass-balance documentation. Supply concentrates in Brazil for bio-ethylene, Germany for automotive-grade compounds, and India for emerging fermentation capacity. Feedstock dependencies rest on sugarcane harvests, pyrolysis oil from chemical recyclers, and post-consumer bale supply from municipal collection systems. Single-source vulnerability in Brazilian ethanol exposes European converters to El Niño-driven supply shocks. Distribution runs through audited chain-of-custody contracts rather than spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal carbon intensity benchmarks compound procurement urgency quarterly, converting sustainability commitments into enforceable feedstock mandates with material cost implications.
For Market Incumbents: Acquire mass-balance certification infrastructure to lock multi-year automotive and retail contracts before auditor queue delays extend. Defend position by securing captive ethanol supply through Brazilian partnership structures or backward integration into lactic acid fermentation. Chemical recycling capacity additions in Germany and the United States anchor compliant feedstock for REACH-authorized recycled content specifications. For New Entrants and Emerging Players: CDSCO pharmaceutical packaging pathways in India open a window for bio-based barrier films in blister packs and sachets, a segment where food-contact certification experience transfers to underpenetrated medical applications. Target Maharashtra and Gujarat polylactic acid production with ISCC PLUS certification as the anchor credential. Go-to-market through direct technical sales to CDMOs seeking EMA-aligned primary packaging materials. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 22095-compliant certification bodies number under twenty globally, creating six-to-nine month onboarding queues that strand uncertified capacity. Vertically integrated fermentation-to-resin producers with captive feedstock documentation represent the viable acquisition archetype across a five-to-ten year window. Monitor REACH authorization timelines for novel biopolymer chemistries as the inflection signal for commercial launch viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive Brazilian sugarcane ethanol or in-house lactic acid fermentation secures mass-balance documentation. |
| Chemical Recycling Scale-Up | Pyrolysis unit integration with Gulf Coast refinery infrastructure enables mixed-waste polymer recovery beyond mechanical limits. |
| ISCC PLUS Certification Investment | Audited chain-of-custody credentials unlock multi-year offtake contracts from Netherlands and Scandinavian retailers. |
| Pharmaceutical Packaging Pivot | EMA-aligned bio-based barrier films for blister packs access underpenetrated medical segments with higher margin profiles. |
| India PLI Scheme Participation | Domestic fermentation capacity investments capture Asian packaging demand currently served by European imports. |
Research Methodology
Coverage spans Germany, the United States, Brazil, India, and the Netherlands, with primary inputs from each market cluster. Conversations with polymer procurement managers at automotive OEMs, packaging converters, and retail sustainability officers combined with technical discussions at chemical recyclers and fermentation plant operators. Secondary validation drew from ECHA REACH registration databases, EU Green Deal implementation reports, FDA food-contact approval filings, and customs trade data for bio-based resin imports. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Rate-of-change decomposition across the analysis window isolates volume drivers by product type, application end-use, certification tier, and regional regulatory cluster. CAGRs were derived from segmented growth trajectory analysis incorporating feedstock cost pass-through elasticity, REACH authorization timeline probabilities, and composting infrastructure deployment rates. Industry-specific inputs included Brazilian sugarcane harvest yield projections and German automotive OEM specification refresh cycles.
Revisions become necessary when ECHA REACH authorization timelines extend beyond baseline assumptions or when EU Green Deal carbon intensity benchmarks tighten ahead of schedule. Forecasts reflect documented assumptions regarding certification body capacity expansion and chemical recycling yield improvements. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
BPA-Free Epoxy Resins Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Co-Polymer Resin Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Polycyclohexylenedimethylene Terephthalate (PCT) Market
Polymers & Resins
Polyester Polyol Market
Polymers & Resins
Silane-Modified Polymers Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
Polymer Excipients Market
Polymers & Resins
Rosin Resin Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Silicone Resins Market