
 Asia-Pacific Polyethylene Wax Market | 2026-2036
Asia-Pacific Polyethylene Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Polyethylene Wax Market Outlook
Paraffin wax is consolidating share in cost-sensitive coating formulations across Southeast Asia, forcing polyethylene wax suppliers to emphasize performance differentiation. Mitsui Chemicals leverages its integrated refinery-to-specialty chemicals footprint to sustain margin stability in high-density grades. SCG Chemicals anchors its position through captive ethylene supply from Thai petrochemical complexes. Qingdao Haihao Chemical competes on customized melt-point specifications for domestic plastics processors.
Asia-Pacific polyethylene wax comprises low- and high-density homopolymers or oxidized derivatives with melt viscosities typically ranging from 10 to 10,000 mPa·s, manufactured via ethylene polymerization or thermal cracking of polyethylene resin, serving primarily as lubricants, dispersants, and surface modifiers in polymer processing and industrial coatings. High-density polyethylene wax dominates volume flows into plastics processing where thermal stability requirements are most stringent, while synthetic grades command premium positioning in electronics-grade applications where ultra-low ash content is mandatory. The coatings application segment channels substantial demand from waterborne architectural paint producers reformulating for lower VOC emissions.
China's SAMR enforces GB standards for chemical additives in food-contact materials, directly conditioning market access for food-grade polyethylene wax imports. Japan's METI chemical substance classification framework shapes product registration burdens for suppliers serving automotive tier-ones. India's BIS mandatory certification scheme for industrial-grade waxes filters import competition and elevates compliance costs for uncertified traders. Stakeholders must monitor divergence between national chemical inventories as regulatory fragmentation across the region complicates pan-Asia product standardization strategies.
Market Dynamics
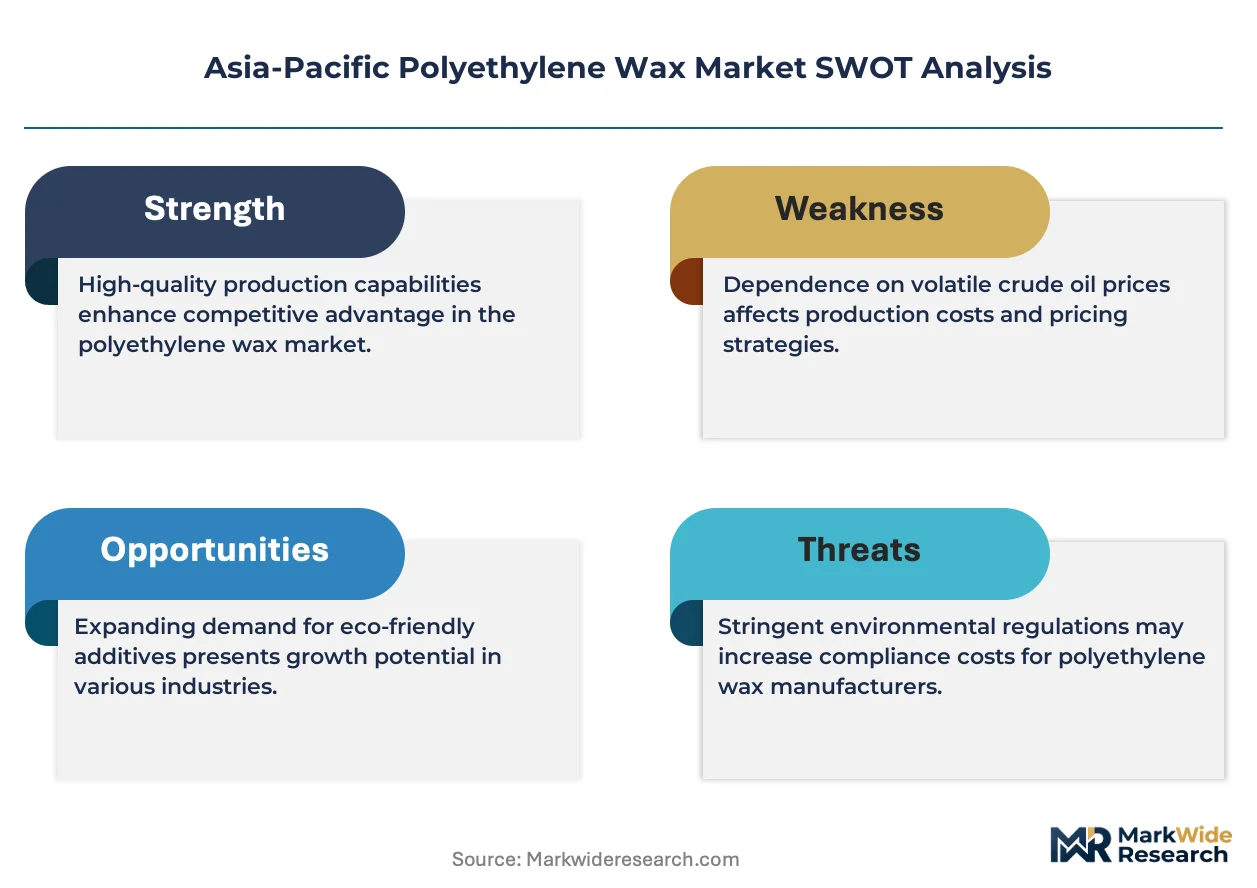
Polyethylene wax supply chains across Asia-Pacific are compressing around captive ethylene sources as coastal polymer compounding clusters scale capacity and tighten specification requirements for food-contact and electronics-grade material.
Growth Catalysts
- Food-contact compliance mandates:China's SAMR enforcement of GB standards for chemical additives in packaging materials is disqualifying uncertified imports and redirecting converter procurement toward certified-grade regional suppliers.
- Polymer compounding cluster expansion:Eastern China's coastal manufacturing zones have scaled high-density polyethylene compounding capacity, creating concentrated demand nodes for thermal-stability waxes in automotive and appliance molding.
- Waterborne coating reformulation:Architectural paint producers across Southeast Asia are substituting solvent-borne systems with low-VOC alternatives, pulling oxidized polyethylene wax demand for surface modifier applications.
Market Restraints
- Naphtha-ethylene cost volatility:Cracker feedstock fluctuations in Northeast Asian petrochemical complexes transmit directly to polyethylene wax production economics, compressing margin stability for non-integrated formulators.
- Paraffin wax substitution pressure:Cost-sensitive coating formulators in Indonesia and Vietnam are consolidating around refined paraffin alternatives, forcing polyethylene wax suppliers into performance-differentiation positioning.
- BIS certification friction:India's mandatory certification scheme for industrial-grade waxes filters import competition and elevates compliance timelines for uncertified traders seeking market access.
Strategic Opportunities
- Electronics-grade ultra-pure segments:Synthetic polyethylene wax with sub-10 ppm ash content is capturing premium positioning in semiconductor molding compounds and capacitor encapsulants across South Korea and Taiwan.
- Vietnam packaging converter base:Underpenetrated demand from food-export-oriented flexible packaging producers offers expansion vectors for suppliers with FSSAI-aligned certification capabilities.
- Dual carbon alignment in China:MEE enforcement of carbon intensity benchmarks is favoring thermal-cracking process routes with lower Scope 2 emissions profiles in coastal manufacturing zones.
Industry Challenges
- Multi-jurisdiction inventory divergence:Formulators must maintain separate product registrations across China's NMPA chemical inventory, Japan's METI classification framework, and India's BIS schemes, fragmenting pan-Asia standardization efforts.
- Melt-viscosity customization complexity:Plastics processors demand narrower specification bands for dispersant applications, requiring compounding-line reconfiguration and extended qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Polyethylene Wax Market |
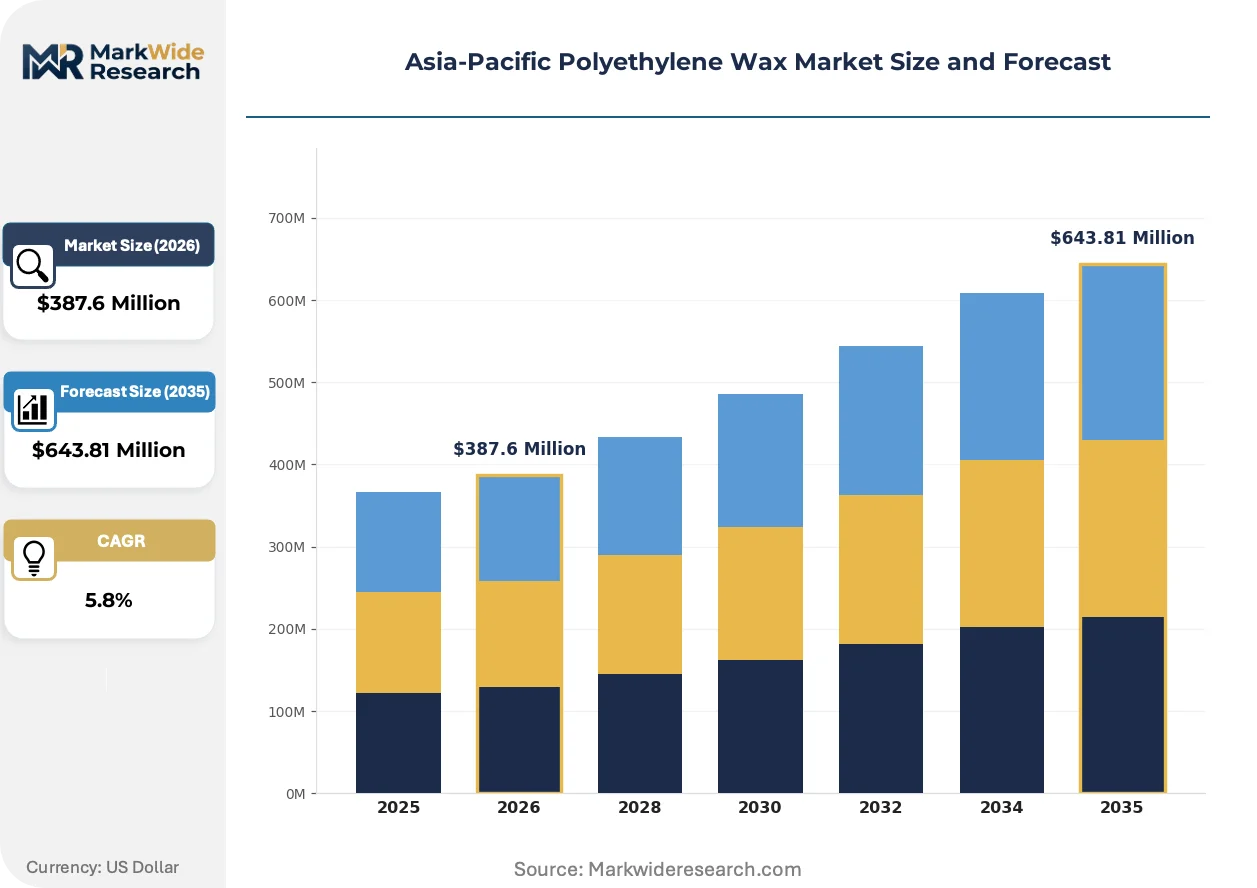
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Density, High Density, Natural, Synthetic Application: Coatings, Adhesives, Plastics, Inks Grade: Food, Industrial, Cosmetic, Pharmaceutical End User: Packaging, Automotive, Construction, Electronics |
| Companies Covered | Mitsui Chemicals Inc, BASF SE, Clariant AG, Honeywell International Inc, Baker Hughes Co, SCG Chemicals, Trecora Resources, DEUREX AG, Qingdao Haihao Chemical Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Polyethylene Wax Market Strategic Shifts
Product differentiation is pivoting from commodity melt-point specifications toward application-engineered grades as regional converters consolidate procurement and tighten incoming material certification requirements.
Advanced oxidation process technology is integrating controlled functional group density into polyethylene wax molecular architecture. Waterborne coating formulators in Thailand and Malaysia are adopting these grades at accelerating qualification rates. This capability compression is enabling direct substitution for imported specialty ester waxes in architectural paint surface modifier applications.
Japan's METI chemical substance classification framework is tightening registration burdens for suppliers serving automotive tier-one molding compounders. The revised notification thresholds are extending lead times for new grade introductions by twelve to eighteen months. Electronics-grade synthetic wax producers are responding by pre-registering ultra-low ash variants ahead of tier-one qualification cycles.
Specification-driven procurement consolidation is compressing supplier bases around certified-grade regional producers. Large polymer compounders in eastern China are unbundling spot purchases from framework agreements with audited compliance documentation. This behavioral shift is most visible in food-contact packaging verticals where incoming material traceability requirements now extend to ethylene cracker source documentation.
Asia-Pacific Polyethylene Wax Market Segmentation
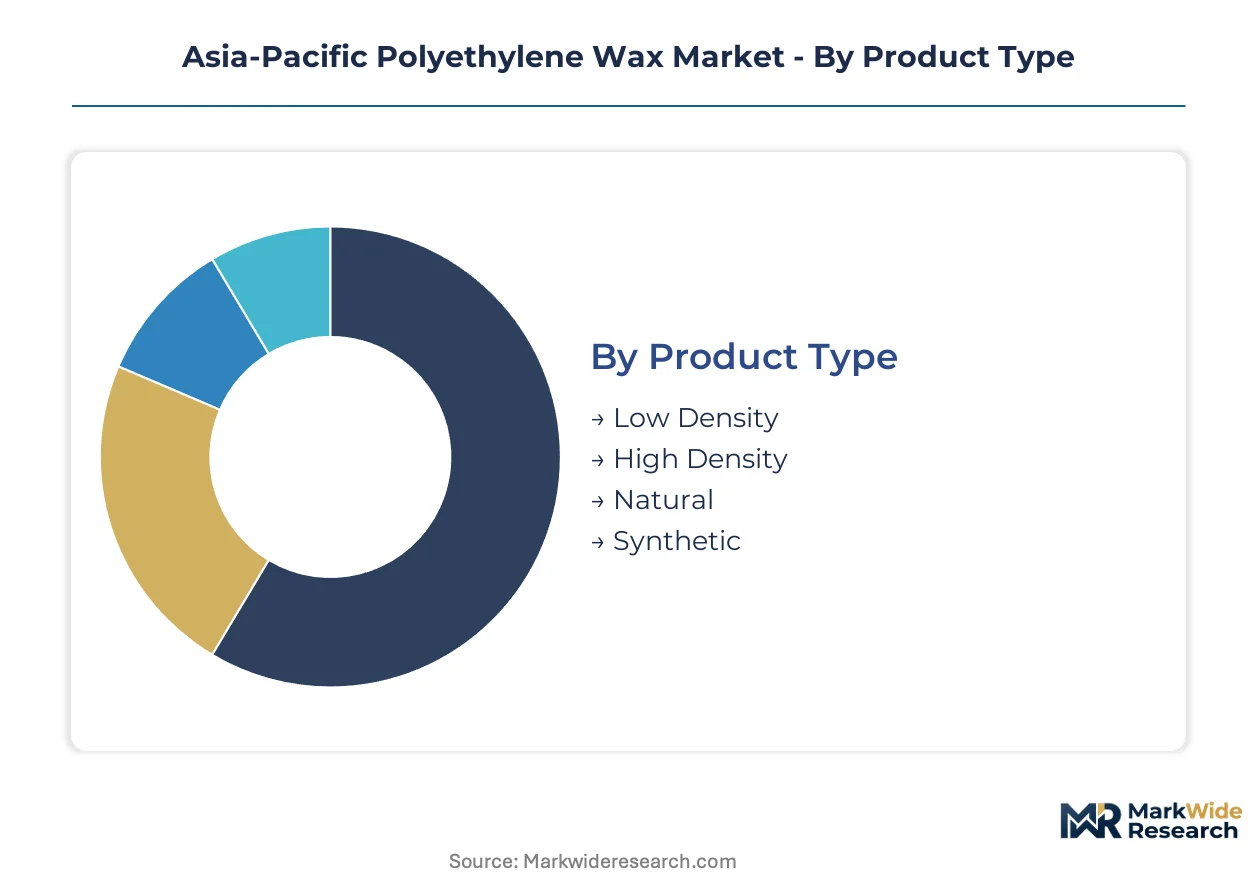
Polyethylene wax specifications diverge sharply across the Asia-Pacific region as food-contact mandates from China's SAMR and India's BIS certification schemes reshape procurement requirements. Segmentation reveals how technical parameters align with end-use compliance burdens and coastal manufacturing cluster demands.
Product Type:
Density and molecular architecture define performance ceilings in polymer processing and coating applications across eastern China's compounding zones.
- High Density:Linear polyethylene chains with crystallinity exceeding 70% deliver thermal stability above 140°C for automotive injection molding compounds. Demand concentrates in Jiangsu and Zhejiang province clusters where appliance and automotive tier-ones operate integrated compounding lines. SAMR food-contact documentation requirements now extend to cracker-source traceability for these grades.
- Synthetic:Polymerized ethylene feedstock yields ash content below 10 ppm mandatory for semiconductor encapsulants and capacitor compounds. South Korean electronics molders in Gyeonggi-do and Taiwanese packaging substrate producers drive qualification timelines stretching eighteen to twenty-four months.
- Low Density:Branched molecular structures with lower crystallinity suit flexible packaging film processing where melt viscosity below 500 mPa·s enables uniform dispersion.
- Natural:Thermal cracking of polyethylene resin produces cost-competitive grades for construction adhesive applications with less stringent purity thresholds.
High Density leads on scale; Synthetic leads on momentum.
Application:
End-use performance requirements fragment procurement specifications across waterborne coating reformulation and polymer compounding verticals.
- Plastics:Lubricant and dispersant functions in high-throughput compounding lines demand narrow melt-viscosity bands between 50 and 500 mPa·s. Thailand's automotive parts cluster around Rayong and Indonesia's appliance molding sector in Bekasi specify thermal stability exceeding 130°C for polypropylene masterbatch production.
- Coatings:Oxidized polyethylene wax with controlled acid values between 15 and 30 mg KOH/g enables surface modifier performance in low-VOC architectural paints. Malaysian and Thai producers reformulating from solvent-borne systems are qualifying these grades at accelerating rates.
- Adhesives:Hot-melt formulations for packaging assembly require compatibility with EVA and polyolefin substrates.
- Inks:Grinding and dispersion applications in flexographic and gravure printing demand specific particle size distributions below 20 microns.
Plastics commands the largest volume position; Coatings exhibits the steepest expansion trajectory.
Grade:
Regulatory certification tiers determine market access velocity and margin structure across national chemical inventories.
- Food:GB standards compliance for chemical additives in packaging materials requires comprehensive ethylene source documentation and migration testing. China's SAMR enforcement has disqualified uncertified imports, redirecting converter procurement toward regional suppliers with audited supply chains.
- Industrial:India's BIS mandatory certification scheme filters import competition and elevates compliance timelines for uncertified traders seeking access to Mumbai and Ahmedabad processing hubs.
- Cosmetic:Purity specifications for personal care applications require heavy metal content below 10 ppm.
- Pharmaceutical:USP and EP compliance for tablet coating and controlled-release matrices demands batch-level analytical documentation.
Food grade leads on compliance premium capture; Industrial grade leads on volume throughput.
End User:
Downstream consolidation patterns concentrate demand around audited suppliers with multi-jurisdiction registration capabilities.
- Packaging:Flexible film converters serving food-export markets in Vietnam and Thailand require FSSAI-aligned certification for materials contacting dairy and meat products. Procurement is unbundling spot purchases toward framework agreements with full traceability documentation.
- Electronics:Semiconductor molding compounders in South Korea and Taiwan specify synthetic grades with sub-10 ppm ash content for capacitor encapsulants. METI registration burdens in Japan extend lead times for new grade introductions.
- Automotive:Interior and under-hood applications demand thermal stability for polypropylene and engineering resin compounds.
- Construction:Adhesive and sealant formulators prioritize cost-positioned natural grades for non-structural applications.
Packaging dominates procurement volume; Electronics commands the highest specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Eastern China's coastal manufacturing clusters anchor polyethylene wax procurement across the Asia-Pacific, with Jiangsu and Zhejiang provinces concentrating polymer compounding capacity that drives specification-grade demand. Food-contact compliance mandates from China's SAMR and India's BIS certification schemes are redirecting procurement toward audited regional suppliers with full supply chain traceability.
China
Jiangsu and Zhejiang province clusters generate concentrated demand for high-density grades in automotive and appliance molding applications. SAMR enforcement of GB standards for chemical additives in food-contact packaging now requires cracker-source documentation extending to ethylene feedstock origins. Coastal manufacturing zones around Shanghai and Ningbo are scaling thermal-cracking capacity with lower Scope 2 emissions profiles to align with MEE carbon intensity benchmarks.
India
Flexible packaging converters in Mumbai and Ahmedabad processing hubs are consolidating procurement around BIS-certified suppliers as mandatory certification filters import competition. FSSAI-aligned documentation requirements for materials contacting dairy and meat products are extending qualification timelines for food-grade grades. Western Maharashtra and Gujarat industrial corridors are attracting regional suppliers establishing certified warehousing and technical service capabilities.
Japan
Automotive tier-one molding compounders in the Chubu region around Nagoya specify thermal stability exceeding 140°C for polypropylene compounds in under-hood applications. METI's revised chemical substance classification framework extends lead times for new grade introductions by twelve to eighteen months. Electronics-grade synthetic wax demand from semiconductor packaging substrate producers in Kyushu commands premium positioning for sub-10 ppm ash content material.
South Korea
Semiconductor molding compounders in Gyeonggi-do province drive eighteen to twenty-four month qualification cycles for ultra-pure synthetic grades in capacitor encapsulant applications. The country's national chemical regulator maintains stringent notification thresholds for new substance introductions serving electronics verticals. Coastal petrochemical complexes around Ulsan provide captive ethylene integration for high-density polyethylene wax production serving domestic plastics processors.
Vietnam
Food-export-oriented flexible packaging producers in Ho Chi Minh City and Binh Duong province represent underpenetrated demand for FSSAI-aligned certified grades. Cost-sensitive coating formulators are consolidating around refined paraffin alternatives, forcing polyethylene wax suppliers into performance-differentiation positioning. Northern industrial zones around Hai Phong are attracting regional suppliers establishing distribution infrastructure for polymer compounding customers.
Asia-Pacific Polyethylene Wax Market Competitive Environment
Global majors compete with regional champions across certification capabilities and captive feedstock integration. The vendor base organizes into three tiers: integrated petrochemical conglomerates with refinery-to-specialty chemicals footprints, mid-scale regional compounders with customized specification expertise, and import-dependent traders facing compliance friction from national certification schemes. Dominant competitive moves include backward integration into ethylene supply and pre-registration of ultra-low ash variants ahead of tier-one qualification cycles.
Within the integrated petrochemical tier, Mitsui Chemicals and SCG Chemicals exemplify players leveraging captive ethylene from coastal refinery complexes to sustain margin stability in high-density grades. Among China-based specialists, Qingdao Haihao Chemical Co., Ltd. occupies a position emphasizing customized melt-point specifications for domestic plastics processors. These three companies represent distinct strategic archetypes: Japanese integrated conglomerate, Thai refinery-anchored regional champion, and Chinese specification-focused mid-scale compounder.
| Leading Market Players |
|---|
| Mitsui Chemicals Inc |
| BASF SE |
| Clariant AG |
| Honeywell International Inc |
| Baker Hughes Co |
| SCG Chemicals |
| Trecora Resources |
| DEUREX AG |
| Qingdao Haihao Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Naphtha-ethylene spread volatility cascades through polyethylene wax production economics, compressing margin stability for non-integrated formulators while amplifying pricing power for refinery-anchored suppliers with captive feedstock control across Thai and Northeast Asian petrochemical complexes.
Pricing Analysis
Input-cost pass-through from cracker feedstock fluctuations dominates pricing formation, with naphtha-indexed contracts resetting quarterly. Three-tier pricing structure across food-grade certified, industrial BIS-compliant, and natural thermal-cracked grades separates premium capture by compliance tier. Cost compression in standard industrial grades intensifies because Indonesian and Vietnamese coating formulators consolidate around refined paraffin alternatives. Spot buyers in eastern China exhibit highest price sensitivity; semiconductor molders in South Korea and Taiwan demonstrate lowest sensitivity due to eighteen-to-twenty-four-month qualification lock-ins.
Supply Chain Analysis
India's BIS mandatory certification scheme and China's SAMR GB standards enforcement are reshaping sourcing toward audited regional suppliers with full ethylene cracker traceability. Manufacturing concentrates in China, Thailand, and South Korea where coastal petrochemical complexes provide captive ethylene integration. Raw material flows draw from naphtha crackers, polymer resin thermal cracking, and synthetic ethylene polymerization routes. Single-source vulnerability persists for electronics-grade sub-10 ppm ash content material where South Korean and Taiwanese qualification cycles create switching friction. Distribution runs through direct technical-service relationships with polymer compounders and coating formulators, supplemented by certified warehousing in Mumbai, Shanghai, and Ho Chi Minh City processing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific polyethylene wax functions as a regulatory compounder where SAMR food-contact compliance mandates and BIS certification schemes are accelerating demand concentration around certified-grade suppliers with audited supply chain documentation.
For Market Incumbents: Hedge against paraffin wax substitution pressure in Southeast Asian coating markets by deepening captive ethylene integration and pre-registering ultra-low ash variants ahead of Japan METI notification threshold revisions. Anchor margin stability through backward integration into coastal refinery complexes while building technical-service capabilities in Vietnam's underpenetrated flexible packaging corridor. For New Entrants and Emerging Players: Vietnam's food-export-oriented flexible packaging producers represent the most penetrable buyer archetype for FSSAI-aligned certification capabilities. Target white-space expansion through customized melt-point specifications for domestic plastics processors in eastern China's coastal manufacturing zones. Accelerate market entry via partnership with established regional distributors holding BIS-certified warehousing infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale specification compounders possessing SAMR-compliant food-grade documentation and existing relationships with Jiangsu and Zhejiang province automotive tier-ones. Long-term viability favors suppliers with dual carbon alignment and lower Scope 2 emissions profiles as MEE enforcement tightens across coastal manufacturing zones. Monitor divergence between national chemical inventories as the inflection signal for pan-Asia standardization complexity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Supply | Captive feedstock from Thai and Northeast Asian crackers insulates margin compression from naphtha volatility. |
| Food-Grade Certification Pre-Registration | SAMR GB standards compliance opens access to China's packaging converter procurement consolidation. |
| Ultra-Low Ash Synthetic Capacity Expansion | Sub-10 ppm grades capture premium positioning in South Korean semiconductor molding compounds. |
| Technical Service Infrastructure Buildout | Direct compounding-line support in Vietnam and India accelerates qualification cycle compression. |
| Dual Carbon Process Route Transition | MEE carbon intensity benchmarks favor thermal-cracking investments with lower Scope 2 emissions. |
Study Parameters
Direct dialogue with polymer compounding plant managers, procurement leads at flexible packaging converters, distribution channel partners, and technical R&D directors grounded qualitative findings in operational reality. Secondary validation drew from customs and trade data, ACC and Cefic regional reports, SEC 10-K chemical segment disclosures, and national chemical inventory filings. Bottom-up demand modeling across end-use applications triangulated against top-down ethylene derivative consumption estimates.
Segmented outputs across product density tier, application vertical, regulatory certification grade, and regional manufacturing hub fed into analytical framework construction over the projection horizon. CAGRs emerged from weighted-average growth contributions by segment, incorporating polymer compounding capacity expansion schedules, coating reformulation adoption curves, and electronics-grade qualification pipeline visibility. Naphtha-ethylene spread trajectories and carbon intensity benchmark enforcement timelines shaped scenario-weighted outcomes.
Underlying measurement precision varies by segment; food-grade certified and electronics-grade synthetic categories carry tighter precision than commodity natural thermal-cracked material due to concentrated supplier bases and documented qualification cycles. Forecasts reflect assumptions around regulatory enforcement continuity, cracker feedstock cost normalization, and paraffin substitution elasticity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Chlorinated Polyethylene Market
Polymers & Resins
Polypropylene Filler Sheet Market
Polymers & Resins
Polyetherketoneketone (PEKK) Market
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Polylysine Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Asia-Pacific Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
High-Purity Epoxy Resin Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
Global Cyclic Olefin Copolymers Market