
 Global Polymethyl Methacrylate Market | 2026-2036
Global Polymethyl Methacrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polymethyl Methacrylate Market Foresight
A shortage of specialized polymer chemists and process engineers is unwinding capacity expansion timelines at several PMMA producers. Röhm GmbH leverages backward integration into methyl methacrylate monomer supply to protect margin stability across European extrusion operations. Mitsubishi Chemical Corporation anchors its position through captive technology leadership in optical-grade cast sheet formulations for display laminates. Chi Mei Corporation dominates bulk commodity PMMA supply to Asian electronics fabricators with scale-driven cost positioning.
Polymethyl methacrylate is a transparent thermoplastic synthesized from methyl methacrylate monomer via bulk or suspension polymerization, yielding amorphous sheets or pellets with light transmission exceeding 92% and density roughly half that of optical glass. The material serves as a glass replacement where impact resistance, UV stability, and thermoformability outweigh scratch hardness limitations. Extruded sheets command the largest volume share across the product type dimension, though molding compounds are gaining share as automotive interior component specifications tighten. Within end use industry segmentation, medical applications exhibit the fastest trajectory as sterilizable PMMA grades displace polycarbonate in device housings and surgical visualization products.
EPA oversight of air emissions from MMA monomer production shapes plant siting and abatement investment for US-based manufacturers, while REACH registration requirements in Europe constrain non-compliant import volumes from smaller Asian suppliers. China's GB standards for building material flammability directly determine which PMMA sheet grades qualify for high-rise signage and facade applications in domestic construction. Stakeholders must track regulatory divergence between jurisdictions on recycled content mandates, as mechanically recycled PMMA faces divergent acceptance thresholds across FDA, EMA, and NMPA medical device material guidelines.
Market Dynamics
Automotive OEMs are systematically replacing mineral glass with PMMA glazing to meet fleet-weight reduction mandates, forcing resin suppliers to certify optical-grade formulations against NHTSA and ECE R43 safety standards simultaneously.
Growth Catalysts
- EU Green Deal compliance pressure:REACH registration deadlines for methyl methacrylate monomer are accelerating investment in bio-based MMA production routes across European extrusion operations.
- LED display manufacturing concentration:China's domestic panel fabrication capacity is absorbing specialty cast sheet grades for backlighting diffusers and light-guide plates.
- Surgical visualization device demand:Sterilizable PMMA grades are displacing polycarbonate in autoclave-compatible medical housings due to superior moisture resistance.
Market Restraints
- Acetone cyanohydrin feedstock volatility:MMA monomer production costs fluctuate with hydrogen cyanide availability, compressing margins at non-integrated sheet extruders.
- Asian supply concentration:Bulk commodity PMMA pellet capacity clusters in China and Thailand, exposing buyers to shipping rate spikes and customs processing delays.
- Scratch hardness limitation:PMMA surfaces score at Mohs 3-4 versus glass at 5.5, restricting adoption in high-touch automotive interior applications without hardcoat treatment.
Strategic Opportunities
- Indian construction signage:BIS certification for flame-retardant PMMA grades remains sparse, creating first-mover advantage for compliant sheet suppliers in Mumbai and Delhi high-rise markets.
- Mechanical recycling infrastructure:Pyrolysis-based MMA recovery from end-of-life PMMA is scaling in Germany and Japan, enabling circular material claims under EU CSRD disclosure rules.
- Optical-grade 3D printing filament:Fused deposition modeling of transparent PMMA for dental surgical guides merges additive manufacturing with medical device sterilization requirements.
Industry Challenges
- Polymer chemist scarcity:Specialized expertise in suspension polymerization kinetics is retiring faster than universities replenish graduates, extending pilot plant commissioning timelines.
- FDA 510(k) material equivalency:Medical device OEMs face 18-24 month validation cycles when switching PMMA suppliers, freezing procurement decisions during shortage periods.
- Legacy extrusion line retrofit costs:Cast sheet producers must upgrade cooling roll configurations to achieve the thickness uniformity demanded by next-generation display laminates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polymethyl Methacrylate Market |
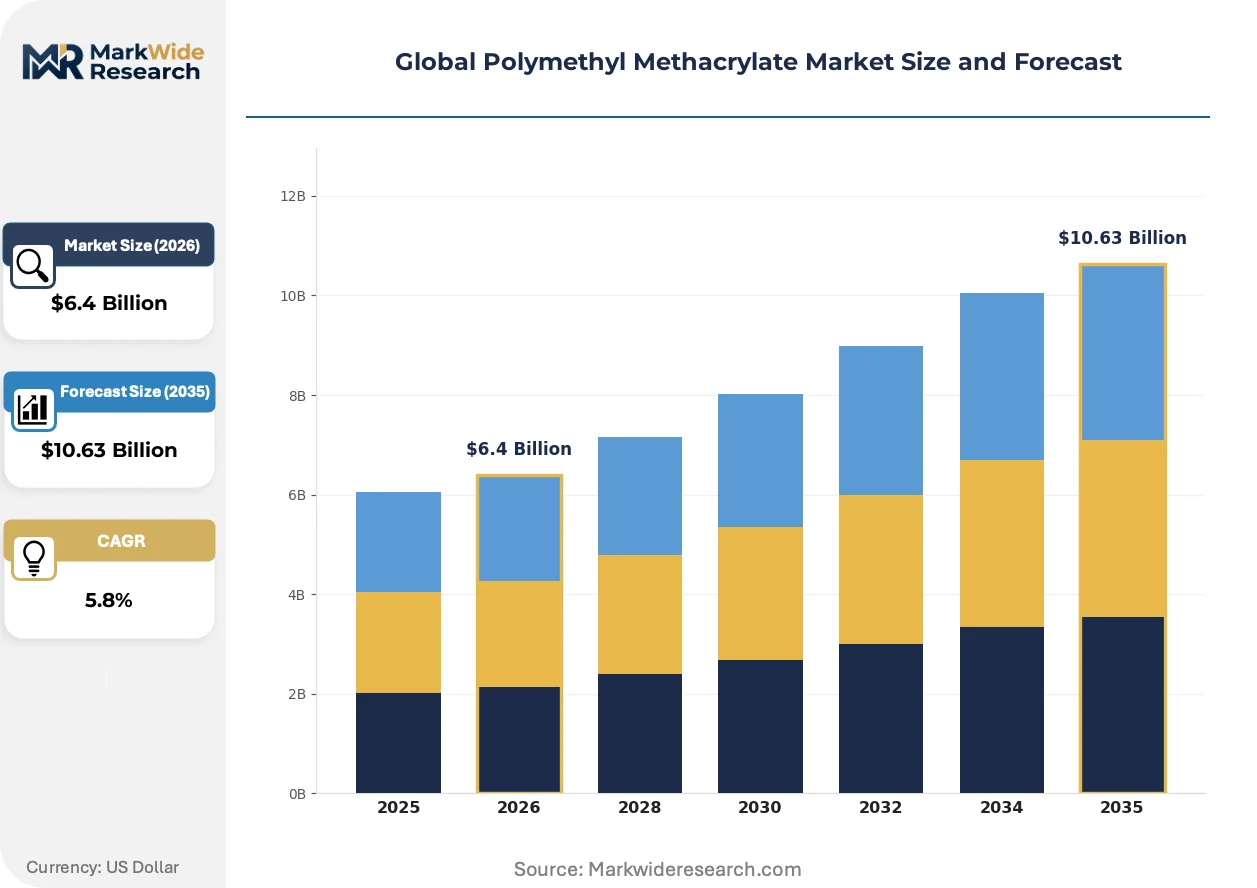
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.63 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded Sheets, Molding Compounds, Cast Sheets, Beads End Use Industry: Automotive, Electronics, Construction, Medical Application: Signage, Windows, Lighting, Display Packaging Type: Bags, Drums, Containers, Bulk |
| Companies Covered | Röhm GmbH, Mitsubishi Chemical Corporation, Sumitomo Chemical Co., Ltd., Chi Mei Corporation, Trinseo, LG MMA Corp., Lotte Chemical Corporation, Asahi Kasei Corporation, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polymethyl Methacrylate Market Shifts & Advancements
Formulation chemistry and manufacturing process control are diverging sharply between commodity construction grades and precision optical applications, fragmenting equipment investment strategies across the supplier base.
Continuous bulk polymerization technology is bifurcating the supplier landscape. Extrusion-grade PMMA pellet production now favors large-scale continuous reactors for automotive compounders, while batch cast cell processes retain dominance for display-optical sheet. Tier-one automotive glazing suppliers are qualifying continuous-cast material for windscreen replacements, compressing lead times from eight weeks to ten days. This technology divide is forcing mid-scale producers to choose between capital-intensive reactor upgrades or niche specialty positioning.
REACH authorization requirements for methacrylic acid derivatives are tightening impurity thresholds in monomer supply chains. ECHA's 2023 updated guidance on Substances of Very High Concern classification is redirecting investment toward closed-loop monomer recovery systems. European sheet extruders are responding by demanding certified mass-balance documentation from MMA suppliers, with German automotive OEMs leading procurement contract renegotiations.
Medical device OEMs are consolidating qualified material suppliers to reduce regulatory audit burden. Procurement teams at surgical visualization equipment manufacturers now require ISO 13485 certification plus FDA master file cross-reference for all PMMA grades, displacing spot-market purchasing. This concentration is most visible in Minnesota and Massachusetts medical device clusters, where three suppliers now capture the majority of optical-grade PMMA volume for endoscopic housings.
Global Polymethyl Methacrylate Market Segmentation
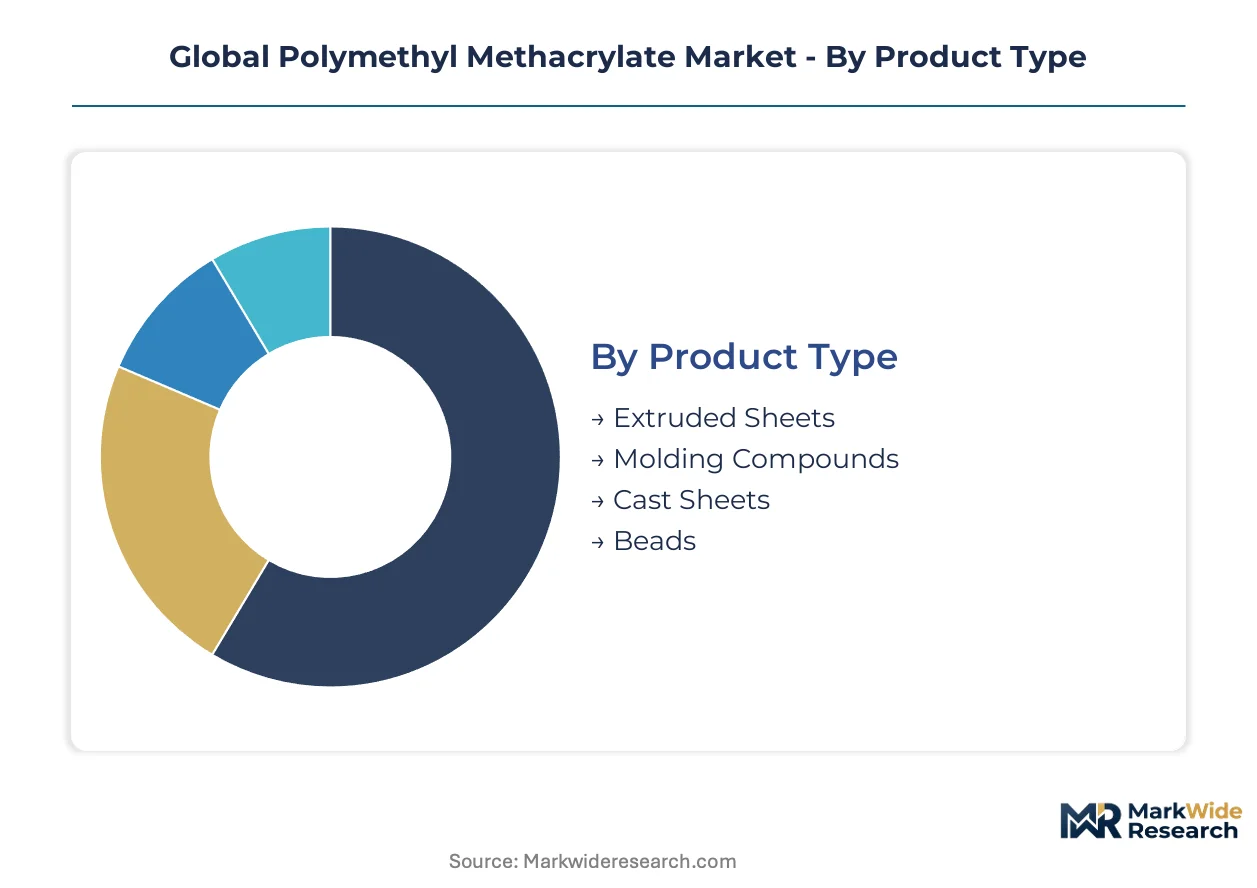
PMMA market segmentation reveals divergent supply chain configurations across product types and end uses. Extruded sheet production clusters near construction demand centers, while optical-grade cast sheet concentrates near display manufacturing clusters in East Asia.
Product Type:
Geographic spread varies sharply: extruded sheets serve domestic construction markets with short logistics loops, whereas cast optical grades ship globally to concentrated electronics fabrication zones.
- Extruded Sheets:Continuous production yields amorphous thermoplastic with 92% light transmission and half the density of glass. Demand concentrates in Chinese construction signage and Indian high-rise facade applications driven by GB and BIS flammability certification requirements. Extruded sheets hold the largest share; momentum sits with cast sheets.
- Molding Compounds:Pelletized formulations enable injection molding of complex automotive interior components. German and Japanese automotive OEMs specify these grades for instrument cluster lenses and center console trim where impact resistance outweighs scratch sensitivity. Molding compounds hold the largest share; momentum sits with cast sheets.
- Cast Sheets:Batch cell polymerization delivers superior optical clarity for precision applications. LED backlighting diffusers in Chinese panel fabs and surgical visualization housings in Minnesota medical device clusters absorb specialty volumes.
- Beads:Spherical pellet forms serve coating and adhesive compounding. European paint manufacturers incorporate PMMA beads for weatherable exterior finishes.
Cast sheets command premium positioning; extruded sheets dominate volume.
End Use Industry:
Cost tier stratification separates commodity construction grades from certified medical and optical segments requiring ISO 13485 and FDA master file documentation.
- Automotive:Glazing substitution accelerates as NHTSA and ECE R43 safety certifications expand approved applications beyond side windows to windscreen replacements. OEMs in Stuttgart and Detroit drive qualification timelines for weight reduction mandates.
- Electronics:Display laminates and light-guide plates absorb specialty cast sheet production. Chinese panel fabs in Shenzhen and Suzhou concentrate demand for sub-millimeter thickness uniformity.
- Construction:Signage and architectural glazing specifications vary by jurisdiction. Indian high-rise markets lack BIS-certified flame-retardant suppliers, creating entry barriers.
- Medical:Sterilizable grades displace polycarbonate in autoclave-compatible surgical devices. Massachusetts and Minnesota device clusters consolidate qualified supplier bases to reduce regulatory audit burden. Medical represents the steepest expansion trajectory; automotive retains the largest volume position.
Automotive consumes the most tonnage; medical applications climb fastest.
Application:
Volume concentration differs from value concentration: signage moves through distributed fabrication networks while display applications concentrate near panel manufacturing.
- Signage:Thermoformed letters and illuminated fascia dominate urban commercial construction. Mumbai and Delhi high-rise markets specify flame-retardant grades where BIS certification remains sparse.
- Windows:Architectural glazing and automotive transparency applications split between extruded commodity grades and optical-certified formulations. German automotive OEMs lead windscreen replacement qualification.
- Lighting:LED backlighting diffusers and luminaire covers demand precise light transmission control. Chinese GB standards determine which grades qualify for domestic installation.
- Display:Optical-grade cast sheet serves LCD and OLED panel lamination. Japanese and Korean display manufacturers specify thickness tolerances below 50 microns. Display commands premium pricing; signage moves the most volume.
Signage leads in tonnage; display leads in margin per kilogram.
Packaging Type:
Customer type determines packaging configuration: bulk railcar delivery serves integrated automotive compounders while bagged formats reach distributed signage fabricators.
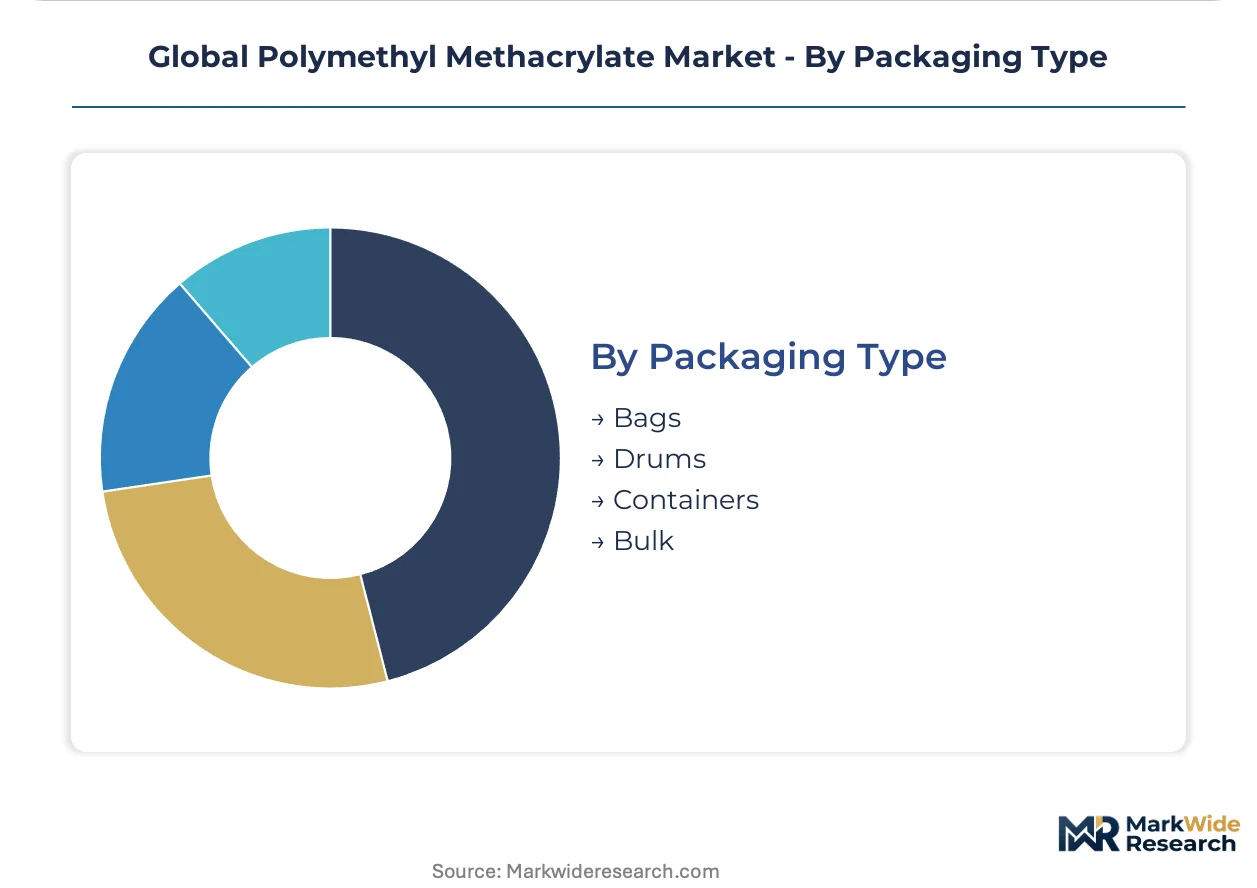
- Bags:25-kilogram woven polypropylene sacks serve small-batch processors and distant export markets. Southeast Asian sheet extruders favor bagged pellet delivery for operational flexibility.
- Drums:Fiber and steel drums protect optical-grade pellets from moisture contamination. Medical device manufacturers in Massachusetts require drum packaging for cleanroom transfer protocols.
- Containers:Intermediate bulk containers balance handling efficiency with lot traceability. European extrusion operations specify containerized delivery for REACH mass-balance documentation.
- Bulk:Pneumatic railcar and truck delivery minimizes unit costs for high-volume automotive and construction compounders. German automotive glazing suppliers receive bulk MMA monomer for captive polymerization. Bulk dominates procurement economics; drums dominate medical compliance.
Bulk packaging captures the largest volume; drum formats retain medical segment loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration deadlines for methyl methacrylate monomer are redirecting investment flows across European extrusion operations, while Chinese domestic panel fabrication absorbs specialty cast sheet grades at expanding scale.
China
Domestic LED display manufacturing concentrates demand for optical-grade cast sheet in Shenzhen and Suzhou panel fabs. GB standards for building material flammability determine which PMMA sheet grades qualify for high-rise signage and facade applications. Yangtze River Delta extrusion operations serve both local construction markets and export-oriented electronics fabricators.
Germany
Automotive OEMs in Stuttgart drive qualification timelines for PMMA windscreen replacements under ECE R43 safety standards. ECHA's updated SVHC classification redirects investment toward closed-loop monomer recovery systems. Bavarian sheet extruders demand certified mass-balance documentation from MMA suppliers to satisfy EU Green Deal compliance pressure.
United States
EPA oversight of air emissions from MMA monomer production shapes plant siting and abatement investment for domestic manufacturers. Minnesota and Massachusetts medical device clusters consolidate qualified supplier bases for sterilizable PMMA grades. NHTSA safety certifications expand approved automotive glazing applications beyond side windows.
Japan
METI industrial policy supports pyrolysis-based MMA recovery from end-of-life PMMA, enabling circular material claims. Kanto region display manufacturers specify thickness tolerances below 50 microns for optical-grade cast sheet. Japanese automotive OEMs anchor demand for molding compounds in instrument cluster lenses and center console trim.
India
BIS certification for flame-retardant PMMA grades remains sparse, creating first-mover advantage for compliant sheet suppliers. Mumbai and Delhi high-rise construction markets specify thermoformed signage where domestic fabrication capacity lags demand. Maharashtra-based extruders face extended procurement cycles due to customs processing delays from Asian supply concentration.
Global Polymethyl Methacrylate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into methyl methacrylate monomer supply distinguishing margin-stable operators from exposed sheet extruders. The supplier base fragments across continuous bulk polymerization reactors for automotive compounders and batch cast cell processes for display-optical applications. Two strategic archetypes dominate: captive monomer producers protecting margin stability, and specialty cast sheet fabricators serving medical and optical segments. Competitive moves concentrate on capacity expansion for automotive glazing qualification and technology licensing for bio-based MMA production routes.
Among European integrated producers, Röhm GmbH exemplifies the captive monomer archetype through backward integration into methyl methacrylate supply. Mitsubishi Chemical Corporation anchors the specialty optical tier, with Chi Mei Corporation representing scale-driven positioning in bulk commodity PMMA supply to Asian electronics fabricators.
| Leading Market Players |
|---|
| Röhm GmbH |
| Mitsubishi Chemical Corporation |
| Sumitomo Chemical Co., Ltd. |
| Chi Mei Corporation |
| Trinseo |
| LG MMA Corp. |
| Lotte Chemical Corporation |
| Asahi Kasei Corporation |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
REACH registration deadlines for methyl methacrylate monomer simultaneously gate supplier qualification and stratify price tiers across European extrusion operations. German automotive OEMs now demand certified mass-balance documentation that only backward-integrated producers can furnish, compressing margins at non-integrated sheet extruders while rewarding captive monomer suppliers with pricing power.
Pricing Analysis
Asian-origin commodity pellets trade at persistent discounts to European optical-grade cast sheet, with freight differentials and customs processing delays widening spreads during peak demand periods. Pricing stratifies across premium, standard, and economy tiers driven by certification grade and volume scale, with ISO 13485-certified medical grades commanding substantial premiums over construction signage material. Cost compression in extruded sheet grades is intensifying because acetone cyanohydrin feedstock volatility transmits directly to non-integrated processors. Automotive compounders exhibit lowest price sensitivity due to long-term offtake contracts, while Indian signage fabricators face acute margin pressure from spot-market pellet procurement.
Supply Chain Analysis
Malacca Strait transit underwrites methyl methacrylate monomer flows from Thai and Singaporean production hubs to Chinese extrusion operations, exposing buyers to piracy risk and port congestion during monsoon seasons. Supply concentrates in China, Thailand, and Germany, with bulk commodity pellet capacity clustering in East Asia while optical-grade cast sheet production anchors in Japan and Germany. The chain draws from hydrogen cyanide, acetone, and sulfuric acid feedstocks, with hydrogen cyanide availability proving most volatile. Single-source vulnerability pervades medical-grade supply, as Minnesota and Massachusetts device clusters qualify only three suppliers for sterilizable PMMA grades. Distribution runs through bulk railcar for integrated automotive compounders, bagged formats for distributed signage fabricators, and drum packaging for cleanroom medical protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical device OEM consolidation in Minnesota and Massachusetts has concentrated procurement power among fewer buyers, forcing suppliers to absorb certification costs and extend payment terms. This buyer-power shift demands strategic repositioning across stakeholder categories.
For Market Incumbents: Secure captive methyl methacrylate monomer supply through backward integration or long-term offtake agreements to defend margin stability against acetone cyanohydrin feedstock volatility. Invest in ISO 13485 certification and FDA master file cross-referencing to lock in surgical visualization device contracts before procurement teams further consolidate qualified supplier bases. Capacity expansion in Germany and Japan preserves proximity to automotive glazing qualification programs and display manufacturing clusters.
For New Entrants and Emerging Players: Lead with BIS-certified flame-retardant PMMA grades in Mumbai and Delhi high-rise construction markets, where domestic fabrication capacity lags demand and incumbent certification remains sparse. Target pyrolysis-based MMA recovery operations in Germany and Japan to claim circular material positioning under EU CSRD disclosure rules. A technical partnership with established European extruders accelerates REACH compliance without greenfield capital deployment.
For Investors and Strategic Acquirers: ECHA's updated SVHC classification reshapes the acquisition landscape by redirecting investment toward closed-loop monomer recovery systems and mass-balance documentation capabilities. Over a multi-year horizon, vertically integrated producers with captive MMA supply and medical-grade certification infrastructure represent the most defensible acquisition targets. Monitor German automotive OEM procurement contract renegotiations as an inflection signal for pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MMA Monomer | Röhm GmbH protects margin stability across European extrusion operations through captive supply. |
| Medical Device Certification Investment | ISO 13485 plus FDA master file cross-reference locks in Minnesota surgical visualization contracts. |
| Pyrolysis-Based Recycling Scale-Up | German and Japanese operations enable circular material claims under EU CSRD disclosure rules. |
| Automotive Glazing Qualification | NHTSA and ECE R43 certifications expand PMMA applications beyond side windows to windscreens. |
| Optical-Grade Cast Sheet Capacity | Sub-50 micron thickness uniformity captures Chinese panel fab demand in Shenzhen and Suzhou. |
Research Methodology
A standing panel of polymer plant managers, automotive Tier 1 procurement leads, medical device GPO contracts managers, and distribution channel partners provided ongoing calibration across primary fieldwork. Secondary validation drew from customs and trade data, Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up modeling of extrusion capacity, monomer production, and end-use consumption triangulated against top-down macroeconomic indicators to ensure consistency.
Output consistency was checked against external benchmarks including automotive production databases, hospital procurement records, and display panel shipment data. The analytical framework modeled product type, end-use industry, application, and regional production hub dimensions across the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-kilogram trends, with specific inputs including LED display manufacturing capacity expansion, automotive fleet-weight reduction mandates, and medical device sterilization protocol evolution.
Forecasts assume regulatory continuity in REACH, FDA 510(k), and GB standards regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as hydrogen cyanide feedstock availability, shipping rate volatility, and medical device supplier consolidation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
Silicone Resins Market
Polymers & Resins
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market
Polymers & Resins
Vinyl Acetate Homopolymer Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Global PEEK Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Global Resin Market
Polymers & Resins
Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
Global Acrylic Solid Surface Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market