
 North America Thermoplastics Market | 2026-2036
North America Thermoplastics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Thermoplastics Market Analytics
ISO 10993 biocompatibility certification is redrawing competitive boundaries in medical-grade thermoplastics. DuPont sustains polymer science leadership through fluoropolymer specialization for implantable device housings. BASF SE anchors North American supply with integrated polyamide production at its Wyandotte, Michigan complex. LyondellBasell Industries Holdings B.V. controls propylene feedstock access across the Gulf Coast, leveraging steam cracker proximity.
Thermoplastics are polymers that soften upon heating and solidify when cooled, enabling repeated melt-processing via injection molding, extrusion, or thermoforming without cross-linking degradation; their molecular structure consists of linear or branched chains held by intermolecular forces rather than covalent bonds, with melt flow indices typically ranging from 0.3 to 60 g/10 min depending on grade. Polypropylene dominates automotive underhood applications for its heat deflection temperature above 100°C, while polyethylene film grades capture margin pools in food packaging barrier layers. Medical Devices represents the fastest-growing application segment as OEMs convert metal instrument housings to sterilizable polysulfone and PEEK alternatives.
FDA 21 CFR material contact regulations and EPA TSCA Section 5 premanufacture notification requirements shape resin approval timelines and new chemistry investment thresholds. NHTSA CAFE standards accelerate thermoplastic composite substitution for metal body-in-white structures across Detroit Three supplier networks. Stakeholders must monitor state-level extended producer responsibility legislation in California and New York for signals on recycled content mandates before committing to virgin capacity expansions.
Market Dynamics
Automotive lightweighting mandates and medical device metal-to-polymer conversion are compressing specification cycles across resin grades, forcing compounders to recalibrate thermal stability and sterilization compatibility portfolios simultaneously.
Growth Catalysts
- NHTSA CAFE Standards:Fleet efficiency targets above 50 mpg by 2031 compel Detroit Three suppliers to substitute glass-reinforced polyamide for steel in structural brackets and battery enclosures.
- FDA 21 CFR Material Contact Regulations:Expanded device clearance pathways for implantable-grade PEEK and polysulfone accelerate OEM conversion from titanium instrument housings.
- Querétaro-Monterrey Packaging Belt:Mexico's flexible film export concentration draws polyethylene investment toward multilayer barrier coextrusion lines serving US food brands.
Market Restraints
- Propylene Feedstock Volatility:Gulf Coast steam cracker outages and ethane-propane spread compression inject margin instability into polypropylene homopolymer pricing.
- ISO 10993 Certification Timelines:Biocompatibility testing protocols extending 18-24 months delay new medical-grade compound launches and freeze smaller compounders from premium segments.
- Recycled Polyethylene Contamination Limits:FDA post-consumer recyclate guidance for food contact maintains strict purity thresholds that constrain mechanical recycling scale economics.
Strategic Opportunities
- California Extended Producer Responsibility:SB 54 mandates 30% recycled content in single-use packaging by 2028, creating offtake certainty for advanced recycling pyrolysis ventures.
- Bio-Based Polypropylene Scale-Up:Braskem's sugarcane-derived propylene pathway and emerging agricultural waste feedstocks offer carbon-intensity reductions for brand sustainability commitments.
- EV Battery Thermal Management:Polyphenylene sulfide and liquid crystal polymer demand for cell module housings and busbar insulation outpaces current specialty resin capacity.
Industry Challenges
- Polymer Rheology Expertise Gap:Injection molders struggle to recruit engineers capable of optimizing long-fiber thermoplastic flow patterns for complex automotive geometries.
- Legacy Equipment Retrofit Costs:Converting extrusion lines from fossil-based to bio-based feedstock requires screw design modifications and downstream cooling system upgrades.
- Multi-Standard Harmonization:Simultaneous compliance with EPA TSCA Section 5, FDA 510(k), and ISO 13485 quality management fragments quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Thermoplastics Market |
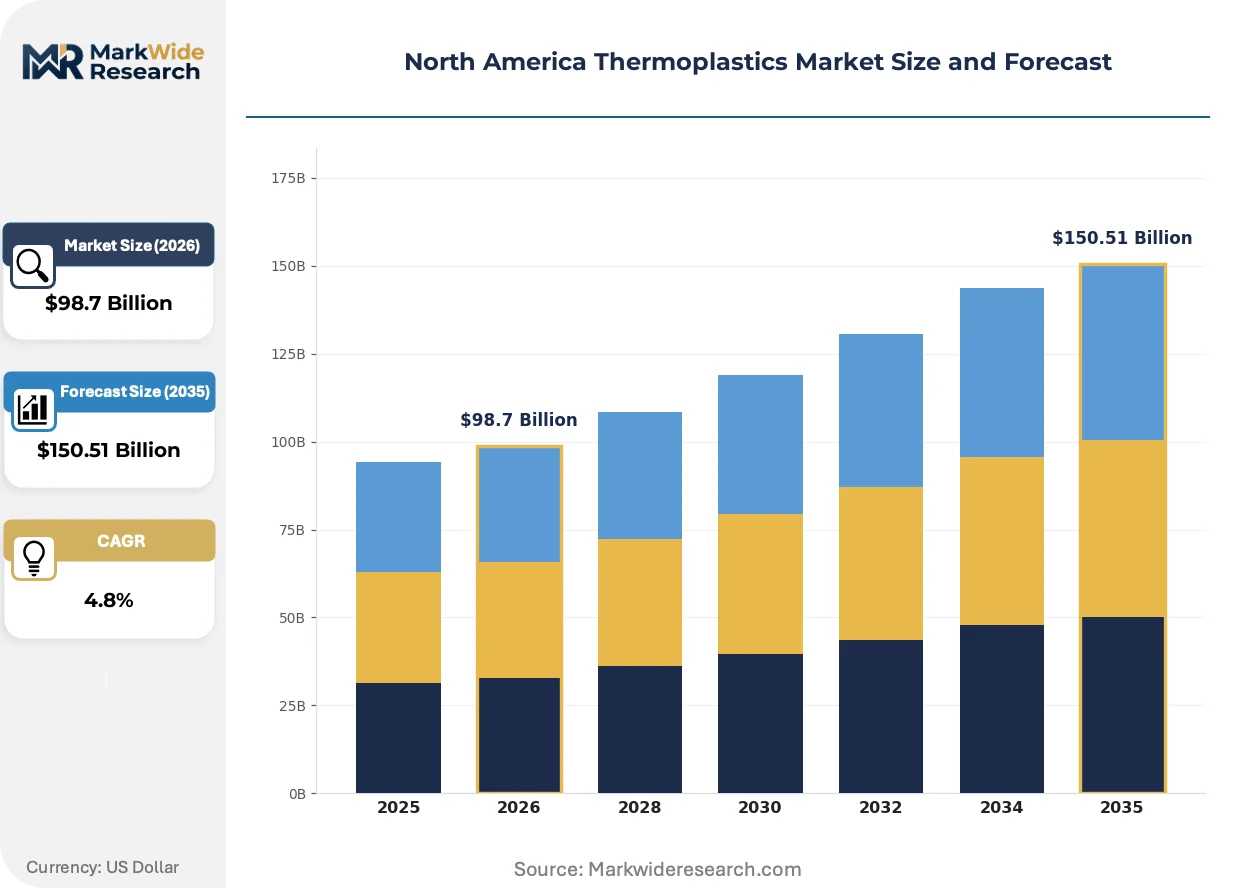
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $150.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride Application: Automotive Components, Consumer Goods, Packaging Solutions, Medical Devices End User: Manufacturers, Retailers, Wholesalers, Distributors Form: Films, Sheets, Foam, Beads |
| Companies Covered | 3M, Celanese Corporation, DuPont, BASF SE, LyondellBasell Industries Holdings B.V., Arkema, Covestro AG, LANXESS, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Thermoplastics Market Evolving Landscape
Material science convergence with digital manufacturing and circularity infrastructure is redefining value capture points across the thermoplastics value chain.
Advanced recycling pyrolysis is bifurcating polyethylene waste streams into food-grade circular feedstock and lower-specification industrial applications. Fast-moving consumer goods brands in Michigan and Ohio now specify mass-balance-certified resins for premium packaging lines. This technology is compressing virgin resin premiums in flexible film grades while creating parallel certification tiers.
EPA TSCA Section 5 premanufacture notification requirements are lengthening new chemistry commercialization timelines and elevating incumbent compounders with established substance inventories. Specialty resin introductions now face 180-day review windows that favor incremental modifications over novel polymer architectures. Medical device OEMs are responding by consolidating supplier bases toward vertically integrated compounders with regulatory dossier depth.
Automotive procurement teams are compressing resin qualification cycles through digital twin simulation of injection molding fill patterns and warpage prediction. Tier-One suppliers in Ontario and Michigan now require compounders to deliver molded part performance data before pellet sampling. This behavioral shift concentrates specification authority with resin producers possessing in-house CAE capabilities and accelerates displacement of trial-and-error mold validation.
North America Thermoplastics Market Segmentation
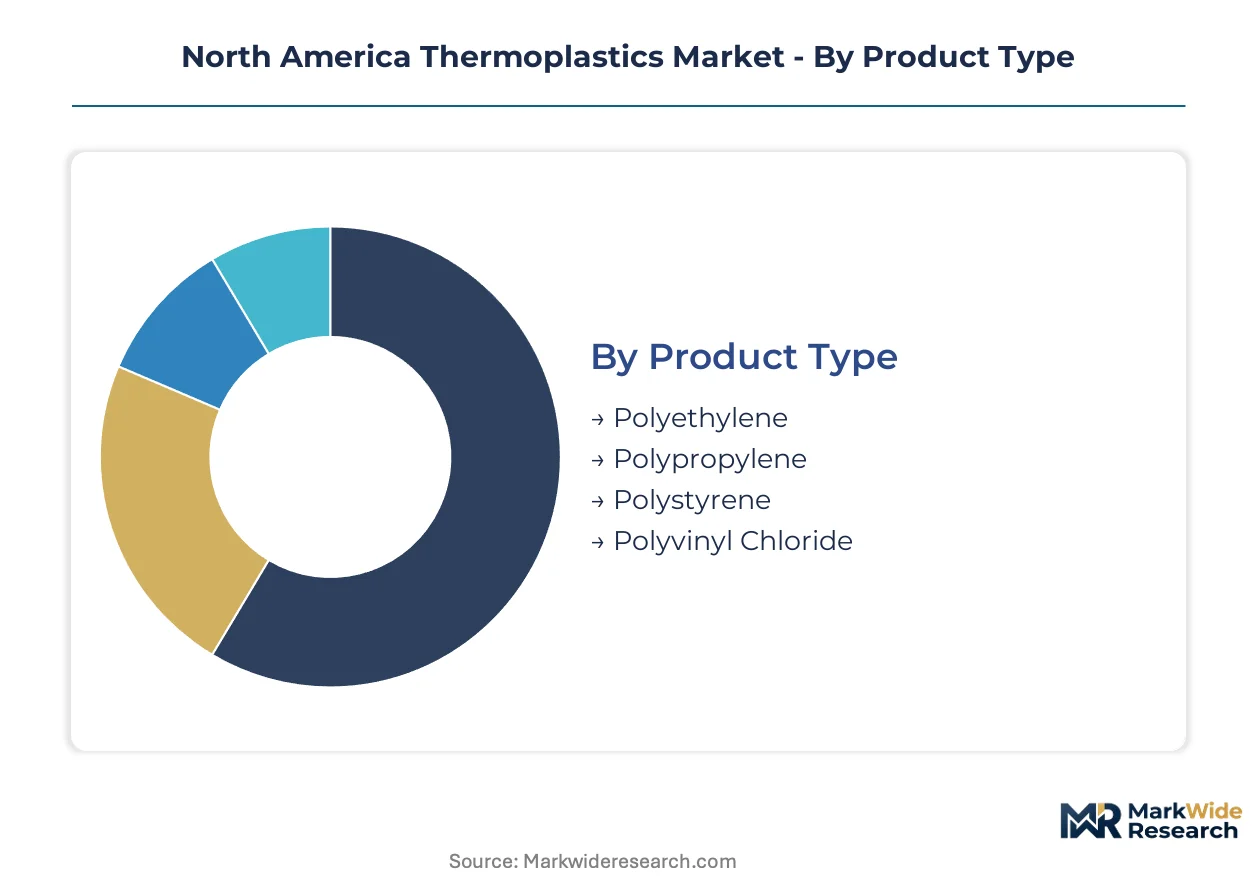
Thermoplastics specification cycles compress across North America as automotive lightweighting and medical metal-to-polymer conversion force compounders to serve divergent thermal and sterilization requirements simultaneously. Segment boundaries blur where polypropylene grades must satisfy both underhood heat deflection and implantable biocompatibility protocols.
Product Type:
Polyethylene faces intensifying substitution pressure from bio-based alternatives and advanced recycling pyrolysis streams as brand sustainability commitments reshape procurement criteria across Michigan and Ohio packaging corridors.
- Polyethylene:Linear low-density and high-density grades dominate flexible film multilayer structures for food barrier applications. Querétaro-Monterrey export belt concentration draws coextrusion investment toward metallocene-catalyzed grades with enhanced puncture resistance.
- Polypropylene:Homopolymer and copolymer variants sustain automotive underhood demand through heat deflection temperatures exceeding 100°C. Glass-reinforced polyamide substitution for steel brackets in Detroit Three supplier networks elevates specification authority toward compounders with in-house CAE capabilities.
- Polystyrene:Crystal and high-impact grades serve disposable medical device housings and consumer electronics packaging. FDA 21 CFR material contact regulations constrain foam expansion agent chemistries in food service applications.
- Polyvinyl Chloride:Rigid and plasticized formulations capture construction piping and medical tubing demand. EPA TSCA Section 5 premanufacture notification requirements lengthen plasticizer substitution timelines.
Polyethylene retains volume leadership; polypropylene holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-intensive medical and automotive segments from price-sensitive packaging and consumer goods categories.
- Automotive Components:Structural brackets, battery enclosures, and interior trim rely on long-fiber thermoplastic injection molding. NHTSA CAFE standards above 50 mpg compel glass-reinforced polyamide substitution for steel across Ontario and Michigan assembly corridors.
- Medical Devices:Implantable-grade PEEK and polysulfone housings displace titanium instrument enclosures. ISO 10993 biocompatibility certification timelines extending 18-24 months freeze smaller compounders from premium segments.
- Packaging Solutions:Flexible films, rigid containers, and foam cushioning serve food and consumer goods distribution. California SB 54 mandates 30% recycled content by 2028, creating offtake certainty for pyrolysis ventures.
- Consumer Goods:Durable appliances, electronics housings, and furniture components utilize commodity-grade resins. Retailer sustainability scorecards redirect formulation priorities toward mass-balance-certified streams.
Packaging Solutions commands absolute volume; Medical Devices climbs the fastest.
End User:
Customer type fragmentation concentrates procurement leverage with tier-one automotive suppliers and consolidated medical device OEMs while dispersing power across fragmented retail channels.
- Manufacturers:Tier-One automotive suppliers and medical device OEMs compress resin qualification cycles through digital twin simulation requirements. Compounders must deliver molded part performance data before pellet sampling.
- Retailers:Fast-moving consumer goods brands in Michigan and Ohio specify mass-balance-certified resins for premium packaging lines. Sustainability commitments compress virgin resin premiums in flexible film grades.
- Wholesalers:Regional distribution networks aggregate demand from mid-sized processors and custom molders. Inventory positioning responds to Gulf Coast propylene feedstock volatility.
- Distributors:Technical resin specialists bridge specification gaps between compounders and injection molders lacking polymer rheology expertise. Value-added services include color matching and small-lot rapid delivery.
Manufacturers retain volume leadership; Retailers hold the steepest expansion curve.
Form:
Supply concentration in extrusion and molding equipment shapes form-specific margin structures across the value chain.
- Films:Multilayer coextrusion and biaxial orientation lines serve food barrier and industrial packaging demand. Querétaro-Monterrey belt concentration draws polyethylene investment toward seven-layer and nine-layer structures.
- Sheets:Thermoforming feedstock for medical trays, food containers, and automotive interior panels. FDA post-consumer recyclate guidance maintains strict purity thresholds constraining mechanical recycling scale economics.
- Foam:Expanded polystyrene and polyethylene foam cushion protective packaging and construction insulation. Legacy equipment retrofit costs for bio-based feedstock conversion require screw design modifications.
- Beads:Expandable polystyrene and specialty polymer microspheres serve molders of complex geometries. Pre-expanded bead processing demands precise density control for automotive seat cushion applications.
Films retains volume leadership; Sheets gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Colonial Pipeline and Gulf Coast petrochemical corridor underwrites North American resin supply security, connecting Texas steam crackers to Midwest automotive assembly and Eastern packaging converters.
United States
EPA TSCA Section 5 premanufacture notification requirements lengthen new chemistry commercialization timelines, favoring incumbent compounders with established substance inventories. Michigan and Ohio packaging corridors concentrate demand for mass-balance-certified polyethylene resins. The Wyandotte, Michigan polyamide complex anchors integrated supply for Detroit Three lightweighting programs.
Canada
Health Canada medical device regulations align with FDA 21 CFR standards, streamlining cross-border approval for implantable-grade thermoplastics. Ontario's automotive supplier network processes glass-reinforced polyamide for battery enclosures serving US electric vehicle platforms. Toronto-Windsor corridor injection molders recruit polymer rheology specialists to optimize long-fiber thermoplastic flow patterns.
Mexico
NHTSA CAFE compliance requirements for US-bound vehicle exports compel Querétaro-Monterrey suppliers to substitute thermoplastic composites for steel structural brackets. Mexico's flexible film export sector draws multilayer coextrusion investment toward metallocene-catalyzed polyethylene grades. Monterrey compounders serve US food brands with seven-layer barrier structures.
North America Thermoplastics Market Competitive Landscape
Listed leaders compete with private specialists across regulatory dossier depth and feedstock integration. The North American thermoplastics sector consolidates around Gulf Coast propylene access and FDA-established substance inventories. Three archetypes dominate: integrated petrochemical majors with steam cracker proximity, specialty compounders with ISO 10993 certification depth, and regional distributors bridging specification gaps for mid-sized processors. Capacity expansion and strategic partnerships represent the dominant competitive vectors as compounders seek to secure recycled feedstock offtake.
Within the integrated major tier, BASF SE and LyondellBasell Industries Holdings B.V. exemplify scale-driven positioning through captive feedstock access and polyamide production integration. DuPont occupies a position among specialty-focused players with fluoropolymer specialization for implantable device applications. These three anchors represent divergent strategic postures: European-headquartered multinationals leveraging North American manufacturing presence versus US-origin science-driven compounders concentrating premium medical-grade segments.
| Leading Market Players |
|---|
| 3M |
| Celanese Corporation |
| DuPont |
| BASF SE |
| LyondellBasell Industries Holdings B.V. |
| Arkema |
| Covestro AG |
| LANXESS |
| Dow Chemical Company |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Gulf Coast steam cracker operators and Detroit Three supplier networks lock in propylene feedstock access and price visibility across polypropylene grades, insulating compounders from spot market volatility while embedding volume commitments into automotive lightweighting programs.
Pricing Analysis
Volume-discount tiering structures separate automotive OEM direct contracts from distributor spot purchases. Three-tier pricing structure across medical-grade certified, automotive specification, and commodity packaging levels reflects ISO 10993 biocompatibility premiums and NHTSA CAFE compliance requirements. Pricing pressure stems from recycled polyethylene contamination limits constraining mechanical recycling scale economics. Tier-One automotive suppliers exhibit lowest price sensitivity due to qualification lock-in, while mid-sized packaging converters face margin compression from sustainability mandate compliance costs.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive supplier networks, while strategic stockpiling persists among medical device OEMs navigating ISO 10993 certification timelines. Feedstock concentration centers on Texas and Louisiana steam cracker corridors, with Ontario and Querétaro compounders drawing from Gulf Coast propylene pipelines. Raw material dependencies include ethane-propane feedstock spreads, metallocene catalyst supply, and FDA-cleared additive packages. Single-source vulnerability concentrates around LyondellBasell Gulf Coast propylene access. Distribution runs through integrated petrochemical majors, specialty compounders, and technical resin distributors serving fragmented injection molding bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastics incumbents face substitution defense against metal-to-polymer conversion acceleration and bio-based feedstock displacement threats that reshape specification authority across automotive and medical segments.
For Market Incumbents: Secure captive recycled feedstock offtake through advanced recycling pyrolysis partnerships before California SB 54 mandates tighten virgin resin premiums. Backward integration into Gulf Coast propylene supply hedges against ethane-propane spread compression eroding polypropylene margins. ISO 10993 certification depth defends medical-grade positioning against emerging specialty compounders. For New Entrants and Emerging Players: Differentiate on bio-based polypropylene carbon intensity metrics to capture brand sustainability procurement shifts in Michigan and Ohio packaging corridors. White-space targets include EV battery thermal management resin supply to Ontario assembly networks and mass-balance-certified polyethylene grades for fast-moving consumer goods brands. Go-to-market leverage rests on agricultural waste feedstock partnerships bypassing fossil-based incumbent supply. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty compounders with established FDA substance inventories and ISO 10993 dossier depth serving implantable device OEMs. Long-term viability favors vertically integrated players with Gulf Coast feedstock access and medical-grade certification assets. Acquisition targets include regional distributors bridging specification gaps for mid-sized processors lacking polymer rheology expertise. Watch for NHTSA CAFE standard tightening as inflection signal accelerating thermoplastic composite substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | Gulf Coast steam cracker proximity secures margin stability against ethane-propane spread volatility. |
| ISO 10993 Certification Investment | Biocompatibility dossier depth freezes smaller compounders from premium medical device segments. |
| Advanced Recycling Pyrolysis Scale-Up | California SB 54 compliance creates offtake certainty for food-grade circular polyethylene supply. |
| Digital Twin Simulation Capability | CAE-enabled compounders compress automotive qualification cycles before pellet sampling requirements. |
| Bio-Based Feedstock Partnership | Agricultural waste propylene pathways capture brand carbon-intensity reduction commitments. |
Research Methodology
Initial hypotheses were tested against primary input from polymer plant managers, Tier 1 automotive procurement leads, medical device OEM material scientists, and technical resin distribution channel partners and refined through secondary validation against SEC 10-K filings, American Chemistry Council trade data, FDA 510(k) submission databases, and customs import records. Bottom-up resin volume modeling triangulated with top-down automotive production and packaging demand forecasts.
Variance decomposition across product type, application, end user, and form segmentation dimensions isolates growth contribution by grade tier and regional production hub. CAGRs were derived from elasticity-adjusted demand projections incorporating NHTSA CAFE compliance timelines, FDA material contact regulation expansion, and state-level extended producer responsibility adoption curves across the projection horizon. Industry-specific inputs include Detroit Three lightweighting program commitments and Querétaro-Monterrey packaging belt coextrusion capacity expansion.
Material uncertainties — Gulf Coast steam cracker outage frequency, ISO 10993 protocol revision timelines, and pyrolysis yield consistency — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory stability and feedstock price mean-reversion. Revision becomes warranted when recycled content mandate thresholds exceed mechanical recycling capacity or bio-based propylene scale economics cross fossil parity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
India Engineering Plastics Market
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Foamed Plastics Market
Polymers & Resins
Nylon 66 Market
Polymers & Resins
Copolyesters Market