
 APAC Polyethylene Terephthalate Market | 2026-2036
APAC Polyethylene Terephthalate Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Polyethylene Terephthalate Market Insights
China's dual carbon goals is decoupling energy-intensive PET production from legacy cost structures. Indorama Ventures Public Company Limited anchors its regional position through integrated PTA-PET complexes in Thailand and India. Reliance Industries Limited leverages its Jamnagar refining complex to sustain captive paraxylene supply for downstream polymer units. Jiangsu Sanfangxiang Group dominates bottle-grade resin output in the Yangtze River Delta.
Polyethylene terephthalate is a thermoplastic polyester polymerized from purified terephthalic acid and monoethylene glycol, exhibiting intrinsic viscosity between 0.70 and 0.84 dL/g for bottle-grade applications. The material functions as a barrier packaging substrate, a textile feedstock for melt-spun polyester fibers, and an engineering resin for automotive and industrial components. Virgin PET still commands the largest volume share across APAC, though recycled PET is gaining structural momentum as brand owners commit to post-consumer content targets. Films and fibers represent contrasting margin profiles: biaxially oriented PET film carries premium pricing for electronics and photovoltaic backsheet applications, while fiber-grade PET competes on scale in China's Zhejiang and Jiangsu provinces.
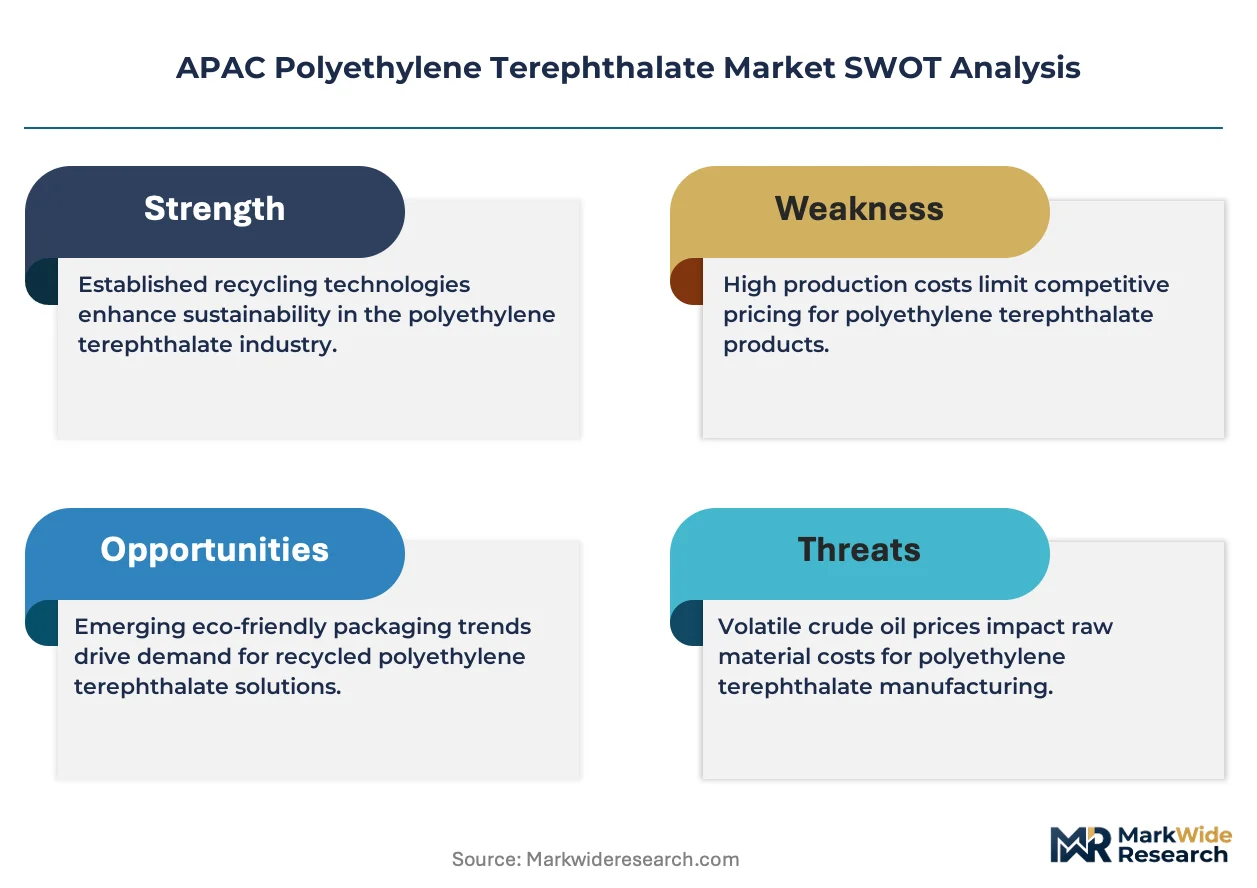
BIS certification requirements in India, China's GB standards for food-contact plastics, and Japan's JIS quality benchmarks collectively shape product specifications and cross-border trade flows. These frameworks elevate compliance costs for smaller extruders while rewarding producers with in-house testing laboratories and regulatory affairs capabilities. Stakeholders must track how extended producer responsibility schemes in Indonesia, Vietnam, and Thailand redirect procurement budgets toward verified recycled content streams.
Market Dynamics
China's dual carbon goals are restructuring feedstock approval pathways, forcing virgin PET producers to decouple from coal-based paraxylene and absorb higher compliance costs while Southeast Asian converters scale food-grade resin purchases.
Growth Catalysts
- Extended Producer Responsibility Schemes:Indonesia, Vietnam, and Thailand are redirecting procurement budgets toward verified recycled content streams, creating structural demand pull for r-PET flake and pellet.
- India's Western Industrial Corridor:Demand concentration from Gujarat to Maharashtra is drawing fresh capacity investments in bottle-grade resin extrusion and preform molding.
- Photovoltaic Backsheet Applications:Biaxially oriented PET film for solar module encapsulation is commanding premium pricing as renewable energy deployment accelerates across the region.
Market Restraints
- Feedstock Volatility:Purified terephthalic acid and monoethylene glycol prices fluctuate with crude oil derivatives, compressing margin predictability for non-integrated converters.
- Supply Concentration Risk:Yangtze River Delta producers dominate bottle-grade output, creating geographic vulnerability to riverine transport disruptions and regional energy rationing.
- Technical Limitation:Recycled PET exhibits intrinsic viscosity degradation after multiple thermal cycles, limiting closed-loop applications in pressure-sensitive packaging.
Strategic Opportunities
- Underpenetrated Geographies:The Philippines and Bangladesh remain underserved for food-grade PET sheet extrusion, offering first-mover positioning for r-PET certified converters.
- Regulatory Tailwind:India's BIS certification requirements for food-contact plastics are elevating compliance costs for smaller extruders, rewarding producers with in-house testing laboratories.
- Technology Convergence:Chemical recycling via glycolysis and methanolysis is converging with mechanical reprocessing to expand feedstock flexibility for bottle-to-bottle applications.
Industry Challenges
- Certification Timeline Compression:China's GB standards for food-contact plastics and Japan's JIS quality benchmarks require extended validation periods that delay product commercialization.
- Capex Intensity:Solid-state polymerization units for raising intrinsic viscosity in recycled flake demand capital commitments that strain mid-scale reprocessors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Polyethylene Terephthalate Market |
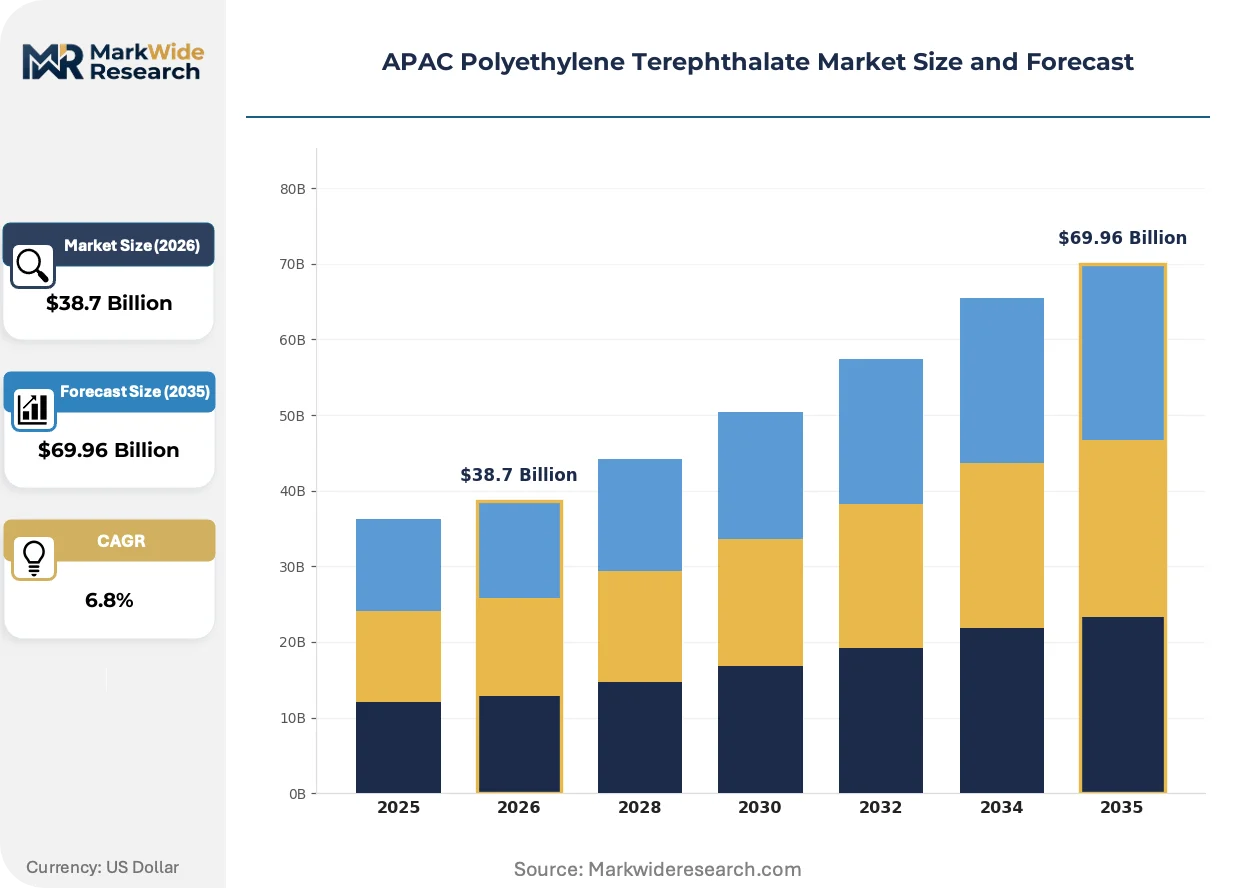
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virgin PET, Recycled PET, Food-Grade PET, Industrial PET Application: Bottles, Containers, Films, Fibers End User: Food & Beverage, Consumer Goods, Automotive, Textile Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | China Petroleum & Chemical Corporation, Indorama Ventures Public Company Limited, Far Eastern New Century Corporation, Reliance Industries Limited, Jiangsu Sanfangxiang Group, Nan Ya Plastics Corporation, Zhejiang Hengyi Group, JBF Industries Limited, Sinopec, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Polyethylene Terephthalate Market Trends and Innovations
Active pharmaceutical ingredient packaging and e-commerce fulfillment are reshaping material specifications, while regulatory tightening on carbon intensity forces process reinvention across the value chain.
Chemical recycling via depolymerization to bis(2-hydroxyethyl) terephthalate is overtaking mechanical regrinding for food-contact applications. Brand owners in beverage and personal care are adopting mass-balance certified resins at accelerated pace. This technology is overtaking conventional flake-washing operations by enabling bottle-to-bottle loops without viscosity loss penalties.
China's GB standards for food-contact plastics are tightening migration limits for antimony catalyst residues and acetaldehyde content. The industrial consequence is accelerated reactor metallurgy upgrades and catalyst substitution toward titanium-based systems. Bottle-grade resin producers in Jiangsu and Zhejiang provinces are responding with dedicated regulatory affairs capabilities and third-party testing partnerships.
Direct procurement relationships between brand owners and resin producers are compressing distributor intermediation in Southeast Asia. Regional packaging converters are consolidating purchase volumes to secure long-term offtake agreements with integrated PTA-PET complexes. This pattern is most visible in Thailand's Eastern Economic Corridor where beverage bottlers are bypassing traditional compounders for virgin and recycled pellet supply.
APAC Polyethylene Terephthalate Market Segmentation
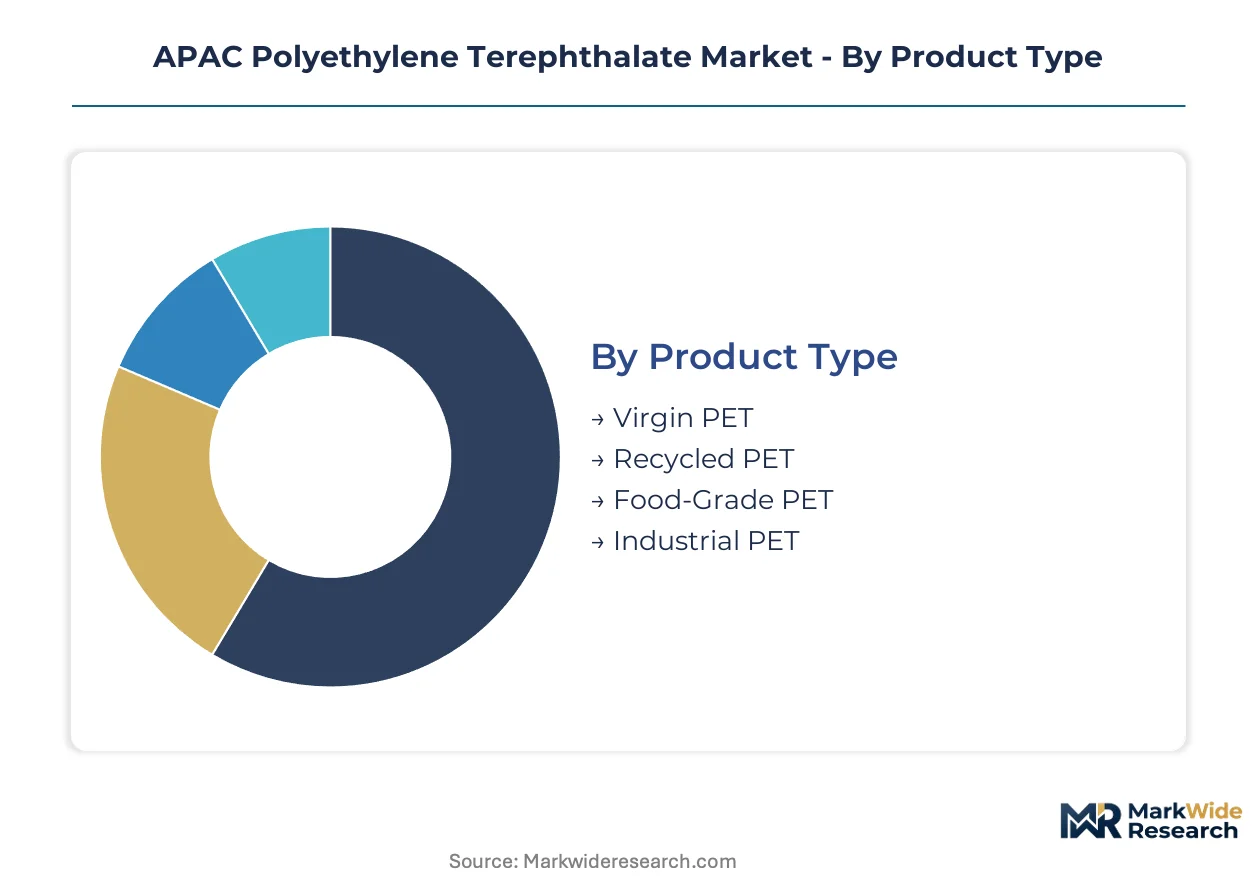
Segmentation in the APAC Polyethylene Terephthalate market reveals how regulatory divergence and end-use performance requirements fragment procurement strategies across resin grades and conversion technologies.
Product Type:
Buyer decisions here pivot on carbon intensity credentials and food-contact certification timelines.
- Virgin PET:Polymerized from purified terephthalic acid and monoethylene glycol to intrinsic viscosity specifications of 0.70-0.84 dL/g for bottle-grade applications. Demand concentrates in China's Yangtze River Delta beverage bottling clusters, though tightening GB standards for antimony catalyst residues are forcing metallurgy upgrades at Jiangsu and Zhejiang production lines.
- Recycled PET:Derived from post-consumer flake through mechanical regrinding or chemical depolymerization to bis(2-hydroxyethyl) terephthalate. Procurement budgets across Indonesia, Vietnam, and Thailand are redirecting toward verified r-PET streams under extended producer responsibility schemes, with chemical recycling overtaking mechanical washing for food-contact loops.
- Food-Grade PET:Resin meeting BIS certification requirements in India, GB standards in China, and JIS benchmarks in Japan for migration limits and acetaldehyde content. Compliance costs favor producers with in-house testing laboratories.
- Industrial PET:Engineering-grade resin for automotive components and industrial applications where intrinsic viscosity tolerances are less stringent than packaging grades. Captive consumption dominates procurement patterns.
Volume sits with virgin PET; growth tilts toward recycled PET.
Application:
Margin profiles diverge sharply between commodity-scale fiber production and premium film extrusion.
- Bottles:Preform molding and stretch-blow molding for beverage, personal care, and pharmaceutical packaging. India's western industrial corridor from Gujarat to Maharashtra is drawing fresh capacity investments in bottle-grade resin extrusion.
- Containers:Thermoformed sheet applications for food trays, clamshells, and blister packs. The Philippines and Bangladesh remain underserved for food-grade PET sheet extrusion, offering positioning opportunities for r-PET certified converters.
- Films:Biaxially oriented PET film commands premium pricing for electronics and photovoltaic backsheet applications as renewable energy deployment accelerates. Solar module encapsulation demand is climbing fastest.
- Fibers:Melt-spun polyester feedstock competing on scale in China's Zhejiang and Jiangsu provinces. Fiber-grade PET operates on compressed margins relative to specialty film grades.
Revenue concentrates in films; expansion is steepest in bottles.
End User:
Performance specifications and regulatory exposure determine contract structures across buyer categories.
- Food & Beverage:The largest consumption category spanning carbonated soft drinks, bottled water, edible oils, and ready-to-eat meals. Brand owners are adopting mass-balance certified resins and compressing distributor intermediation through direct procurement relationships with integrated PTA-PET complexes.
- Consumer Goods:Personal care, household cleaning, and cosmetic packaging where aesthetic clarity and barrier properties drive resin selection. Extended producer responsibility schemes are elevating post-consumer content targets.
- Automotive:Engineering resin applications for interior trim, electrical connectors, and under-hood components. Demand tracks vehicle production volumes and lightweighting initiatives.
- Textile:Polyester fiber feedstock for apparel, home furnishings, and industrial yarns. China's dual carbon goals are decoupling energy-intensive production from legacy cost structures.
Procurement volume centers on food and beverage; sustainability-driven reformulation is advancing most quickly in consumer goods.
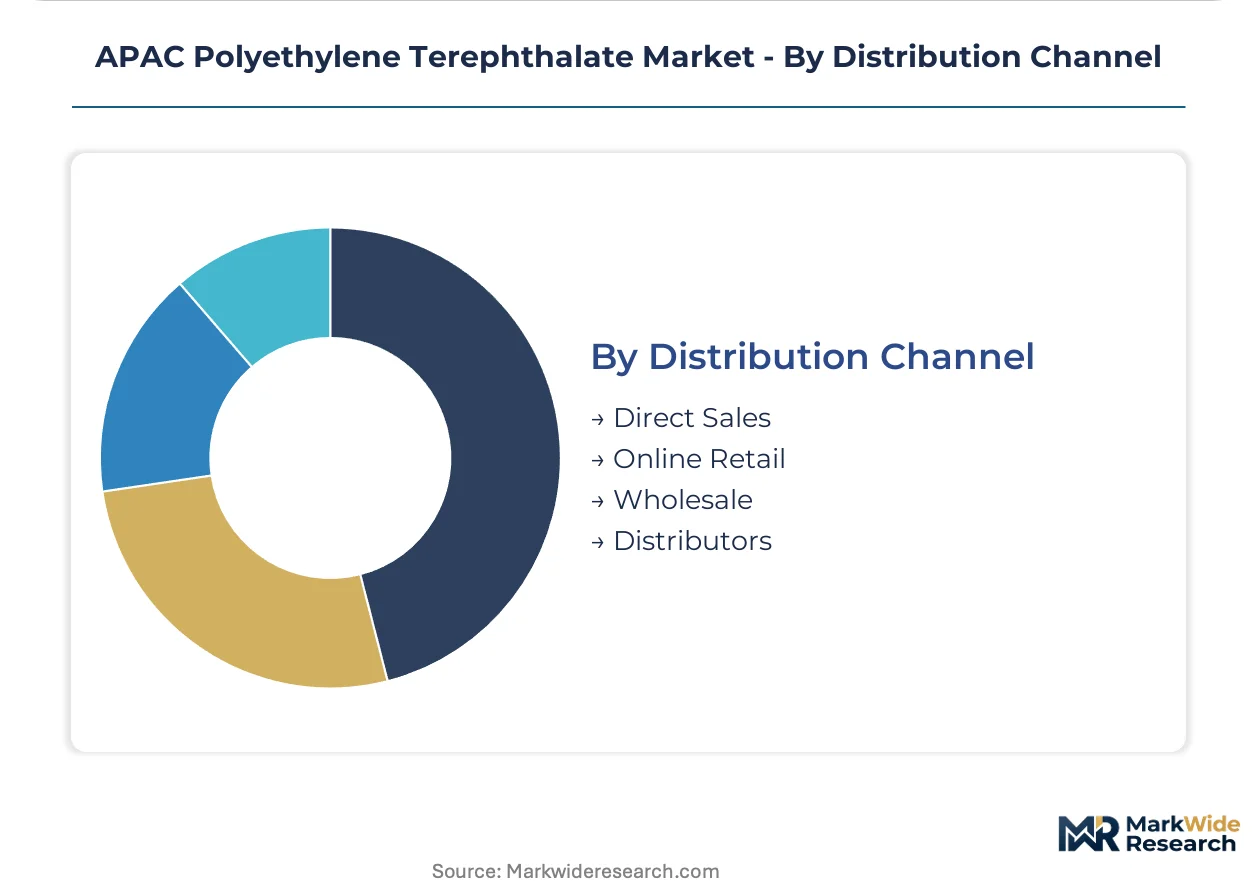
Distribution Channel:
Supply chain configuration reflects resin grade standardization and buyer scale concentration.
- Direct Sales:Long-term offtake agreements between integrated PTA-PET producers and large-scale packaging converters. Thailand's Eastern Economic Corridor exhibits this pattern most visibly as beverage bottlers bypass traditional compounders.
- Wholesale:Bulk resin distribution to mid-scale extruders and preform molders lacking volume leverage for direct producer contracts. Price volatility in purified terephthalic acid and monoethylene glycol compresses margin predictability for non-integrated buyers.
- Distributors:Intermediated supply for smaller converters and geographically dispersed end-users. Geographic concentration risk in Yangtze River Delta production creates vulnerability to riverine transport disruptions.
- Online Retail:Emerging channel for specialty grades, recycled flake, and small-lot engineering resin procurement. Digital platforms are gaining traction for r-PET certified material verification.
Transaction volume flows through wholesale; channel structure is evolving fastest through direct sales consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Eastern Economic Corridor anchors foreign direct investment in integrated PTA-PET complexes, drawing beverage bottlers into direct procurement relationships that bypass traditional distribution channels across Southeast Asia.
China
Jiangsu and Zhejiang provinces concentrate bottle-grade resin output along the Yangtze River Delta, where Jiangsu Sanfangxiang Group maintains dominant production capacity. GB standards for food-contact plastics are tightening migration limits for antimony catalyst residues, forcing metallurgy upgrades and titanium-based catalyst substitution. Zhengzhou Shuli Machinery Co., Ltd. exemplifies equipment suppliers serving this regulatory transition.
India
Demand concentrates in the western industrial corridor from Gujarat to Maharashtra, where Reliance Industries Limited leverages its Jamnagar refining complex for captive paraxylene supply. BIS certification requirements for food-contact plastics elevate compliance costs, rewarding producers with in-house testing laboratories and regulatory affairs capabilities. JBF Industries Limited occupies a position within this certification-intensive environment.
Thailand
The Eastern Economic Corridor hosts Indorama Ventures Public Company Limited's integrated PTA-PET complexes, serving as a regional supply anchor for Southeast Asian packaging converters. Extended producer responsibility schemes across Indonesia, Vietnam, and Thailand redirect procurement toward verified recycled content streams. Direct sales relationships between resin producers and beverage bottlers compress distributor intermediation.
Japan
JIS quality benchmarks for food-contact plastics shape product specifications and cross-border trade flows, particularly for high-barrier pharmaceutical and cosmetic packaging applications. METI oversight ensures stringent acetaldehyde content controls that exceed regional norms. Technical collaboration between Japanese converters and Taiwanese film extruders supports premium photovoltaic backsheet supply chains.
Taiwan
Far Eastern New Century Corporation and Nan Ya Plastics Corporation exemplify integrated producers spanning fiber-grade, film-grade, and bottle-grade resin categories. The island's petrochemical infrastructure feeds biaxially oriented PET film production for electronics and solar module encapsulation. Cross-strait trade dynamics influence feedstock sourcing flexibility for downstream extrusion operations.
APAC Polyethylene Terephthalate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across resin grades and conversion technologies. The market structure exhibits tiered concentration: state-affiliated energy majors control upstream paraxylene and PTA feedstock, mid-scale integrated producers dominate bottle-grade extrusion, and specialized converters capture premium film and fiber niches. Strategic archetypes include captive refinery-linked producers, standalone polymer specialists, and brand-direct recycling operators. Competitive moves center on backward integration into purified terephthalic acid production and chemical recycling capacity additions for bottle-to-bottle loops.
Among Thailand-based integrated producers, Indorama Ventures Public Company Limited anchors regional supply through PTA-PET complex operations. Reliance Industries Limited represents refinery-linked conglomerate strategy with captive feedstock integration from its Jamnagar complex. Jiangsu Sanfangxiang Group exemplifies focused bottle-grade specialists concentrated in China's Yangtze River Delta manufacturing corridor.
| Leading Market Players |
|---|
| China Petroleum & Chemical Corporation |
| Indorama Ventures Public Company Limited |
| Far Eastern New Century Corporation |
| Reliance Industries Limited |
| Jiangsu Sanfangxiang Group |
| Nan Ya Plastics Corporation |
| Zhejiang Hengyi Group |
| JBF Industries Limited |
| Sinopec |
| Others |
Pricing and Supply Chain Analysis
Refinery-linked conglomerates with captive paraxylene supply anchor pricing discipline across APAC, while independent converters absorb margin volatility from purified terephthalic acid and monoethylene glycol spot markets. This ownership structure concentrates pricing power with integrated producers in China's Yangtze River Delta and India's western industrial corridor.
Pricing Analysis
Premium pricing for short lead times distinguishes contract structures, with beverage bottlers in Thailand's Eastern Economic Corridor paying above-spot rates for guaranteed offtake while spot buyers in Vietnam face inventory risk. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, where BIS-certified food-grade resin commands sustained premiums over industrial-grade alternatives. Cost compression in fiber-grade PET is intensifying because Zhejiang and Jiangsu producers compete on scale rather than barrier properties. Small-scale extruders lacking volume leverage exhibit highest price sensitivity, while integrated PTA-PET complexes with captive feedstock show greatest pricing resilience.
Supply Chain Analysis
Skilled technician availability constraints in Jiangsu and Zhejiang provinces limit expansion velocity for bottle-grade resin extrusion lines, while Thailand's Eastern Economic Corridor draws engineering talent through Board of Investment incentives. Supply concentrates in China, India, and Thailand, with purified terephthalic acid, monoethylene glycol, and antimony catalyst systems as critical input dependencies. Single-source vulnerability runs through Yangtze River Delta production clusters exposed to riverine transport disruptions and seasonal energy rationing. Distribution runs through direct sales relationships between integrated producers and large-scale converters, compressing traditional wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where India's BIS certification requirements for food-contact plastics erect barrier-to-entry moats favoring producers with in-house testing laboratories and regulatory affairs capabilities.
For Market Incumbents: Deploy titanium-based catalyst substitution programs to preempt China's tightening GB standards for antimony migration limits. Consolidate position through backward integration into purified terephthalic acid production, neutralizing feedstock volatility that erodes converter margins. Chemical recycling capacity additions for bottle-to-bottle loops represent the critical defensive lever against mechanical reprocessing competitors. For New Entrants and Emerging Players: Launch via direct procurement relationships with brand owners in the Philippines and Bangladesh, where food-grade PET sheet extrusion remains underpenetrated. Target r-PET certified container applications for ready-to-eat meal packaging, leveraging extended producer responsibility scheme tailwinds across Indonesia and Vietnam. White-space positioning in photovoltaic backsheet film offers premium pricing capture absent from commodity fiber-grade competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale integrated producers with idled solid-state polymerization units in India's western industrial corridor, where BIS compliance costs have strained non-integrated extruders. Long-term viability hinges on chemical recycling technology maturation and mass-balance certification adoption across beverage and personal care brand owners. Watch for policy acceleration in China's dual carbon goals implementation as the inflection signal for coal-based paraxylene displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTA | Reliance Industries Limited's Jamnagar refining complex exemplifies captive feedstock insulation from purified terephthalic acid volatility. |
| Chemical Recycling Capacity Addition | Glycolysis and methanolysis installations enable bottle-to-bottle loops without intrinsic viscosity degradation penalties. |
| Regulatory Affairs Capability Buildout | In-house testing laboratories accelerate BIS, GB, and JIS certification timelines for food-contact resin commercialization. |
| Direct Procurement Relationship Formation | Thailand's Eastern Economic Corridor demonstrates bypass of distributor intermediation between integrated producers and beverage bottlers. |
| Photovoltaic Backsheet Film Expansion | Biaxially oriented PET film commands premium pricing from solar module encapsulation demand acceleration. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with plant managers at integrated PTA-PET complexes, procurement leads at downstream packaging converters, distribution channel partners, and technical R&D directors specializing in catalyst systems. Bottom-up resin grade volume estimates and top-down regional consumption aggregates were reconciled through iterative validation against China Petroleum & Chemical Corporation and Indorama Ventures Public Company Limited capacity disclosures.
Data-stream reconciliation across supply-side capacity announcements, demand-side preform molding expansion, and trade flow patterns shaped the analytical framework. Segmentation dimensions modeled include virgin versus recycled grade tiers, bottle versus film versus fiber end-use applications, and regional production hub clusters. CAGRs were derived from slope analysis of year-over-year volume trajectories, with feedstock cost pass-through elasticity and extended producer responsibility scheme implementation pace as industry-specific forecast inputs.
Feedstock price volatility, regulatory timeline slippage, and chemical recycling technology maturation delays are the dominant revision risks to projection assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyisobutene Market
Polymers & Resins
High-Density Polyethylene (HDPE) Resins Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
South America Engineering Plastics Market
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
Global Amino Resin Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Europe Polyurethane Market
Polymers & Resins
Renewable PVDF Market
Polymers & Resins
Global Emulsion Polymer Market
Polymers & Resins
Europe Super Absorbent Polymers (SAP) Market
Polymers & Resins
Polyphenylene Sulfide Market
Polymers & Resins
Polybutylene Succinate (PBS) Market