
 China Protective Coatings Market | 2026-2036
China Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
China Protective Coatings Market Outlook
Performance-based maintenance contracts is recalibrating how coating value gets captured in China. PPG Industries Inc. anchors its position through captive supply of resin intermediates and direct technical service teams at major shipyards. Jotun differentiates via marine specification dominance at Dalian and Shanghai port complexes. AkzoNobel N.V. leverages powder coating technology leadership to penetrate appliance and automotive OEM channels.
China protective coatings are formulated systems—typically 40-60% solids content comprising binders, pigments, extenders, and additives—engineered to prevent substrate degradation from corrosion, chemical attack, or mechanical wear in industrial environments. Epoxy formulations occupy the dominant volume position in marine and heavy industrial maintenance due to superior adhesion and chemical resistance. Polyurethane growth accelerates in automotive refinishing and transportation infrastructure where UV stability and aesthetic durability command premium positioning. Aqueous technology advances fastest among technology categories as MEE enforcement tightens VOC discharge permits.
MEE air quality standards, GB national standards for VOC content in coatings, and the dual carbon policy framework collectively mandate reformulation timelines and factory emission controls. SAMR product quality certification creates compliance barriers for imported formulations lacking localized testing documentation. Stakeholders must monitor provincial enforcement variance between Jiangsu's accelerated VOC reduction schedule and inland province implementation lags.
Market Dynamics
Waterborne coating substitution is compressing solvent-based capacity across China's coastal manufacturing belt as MEE enforcement tightens VOC discharge thresholds. This technology transition is redrawing competitive advantage toward formulators with captive resin synthesis and localized technical service infrastructure.
Growth Catalysts
- Dual carbon policy framework:MEE-mandated carbon intensity targets are accelerating factory-level adoption of low-VOC aqueous systems in Jiangsu and Zhejiang shipyards. Reformulation timelines now drive replacement demand across marine maintenance cycles.
- Infrastructure spending concentration:Yangtze River Delta port expansion is generating sustained specification pull for high-performance marine coatings at Dalian and Shanghai complexes. Heavy industrial maintenance contracts are lengthening in duration.
- Epoxy formulation dominance:Superior adhesion and chemical resistance properties anchor specification preference in offshore platform and chemical processing environments. Technical validation protocols favor proven binder systems.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin and isocyanate precursor costs fluctuate with naphtha cracking margins, compressing formulation margin stability for mid-tier producers.
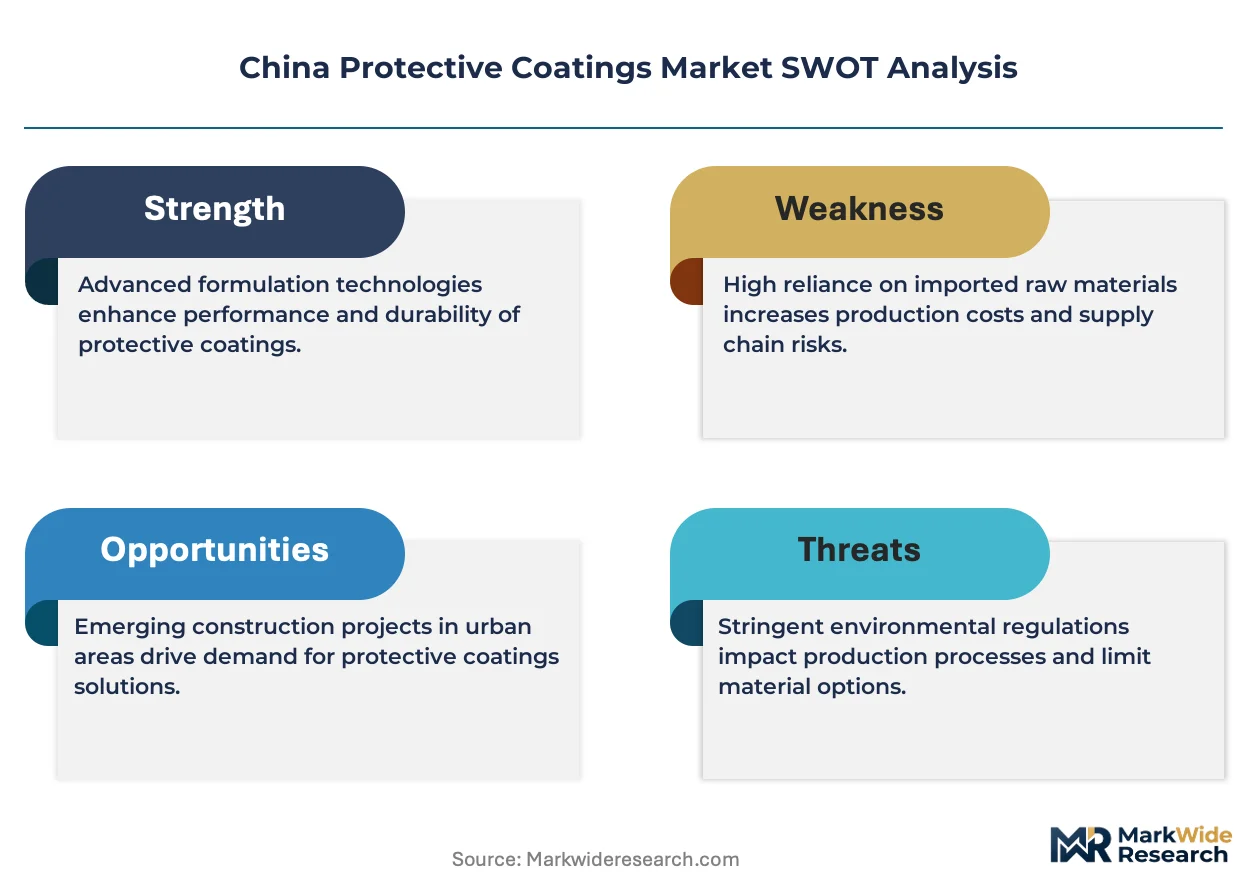
- Import dependency in specialty additives:Defoamer and rheology modifier supply concentrates among European and Japanese chemical specialists, creating procurement bottlenecks during logistics disruptions.
- Aqueous performance gaps:Waterborne systems exhibit inferior humidity tolerance and extended cure times versus solvent-based alternatives in high-salt marine environments, limiting specification penetration.
Strategic Opportunities
- Inland province enforcement lag:Sichuan and Henan implementation schedules trail coastal provinces by 18-24 months, creating temporary regulatory arbitrage for solvent-based capacity relocation.
- Powder coating convergence:Appliance and automotive OEM channels are integrating powder systems with pre-treatment automation lines, opening specification entry points for heat-curable technologies.
- Performance-based contracting:Shipyard operators are piloting coating lifecycle cost models that transfer technical risk to applicators, rewarding predictive maintenance capabilities.
Industry Challenges
- Formulation chemist scarcity:Waterborne technology transition demands expertise in colloidal stability and film formation kinetics that legacy solvent-based technicians lack, widening talent acquisition gaps.
- SAMR certification timelines:Imported formulations require 12-18 month localized testing documentation cycles, delaying market entry for foreign suppliers lacking established Chinese testing partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Protective Coatings Market |
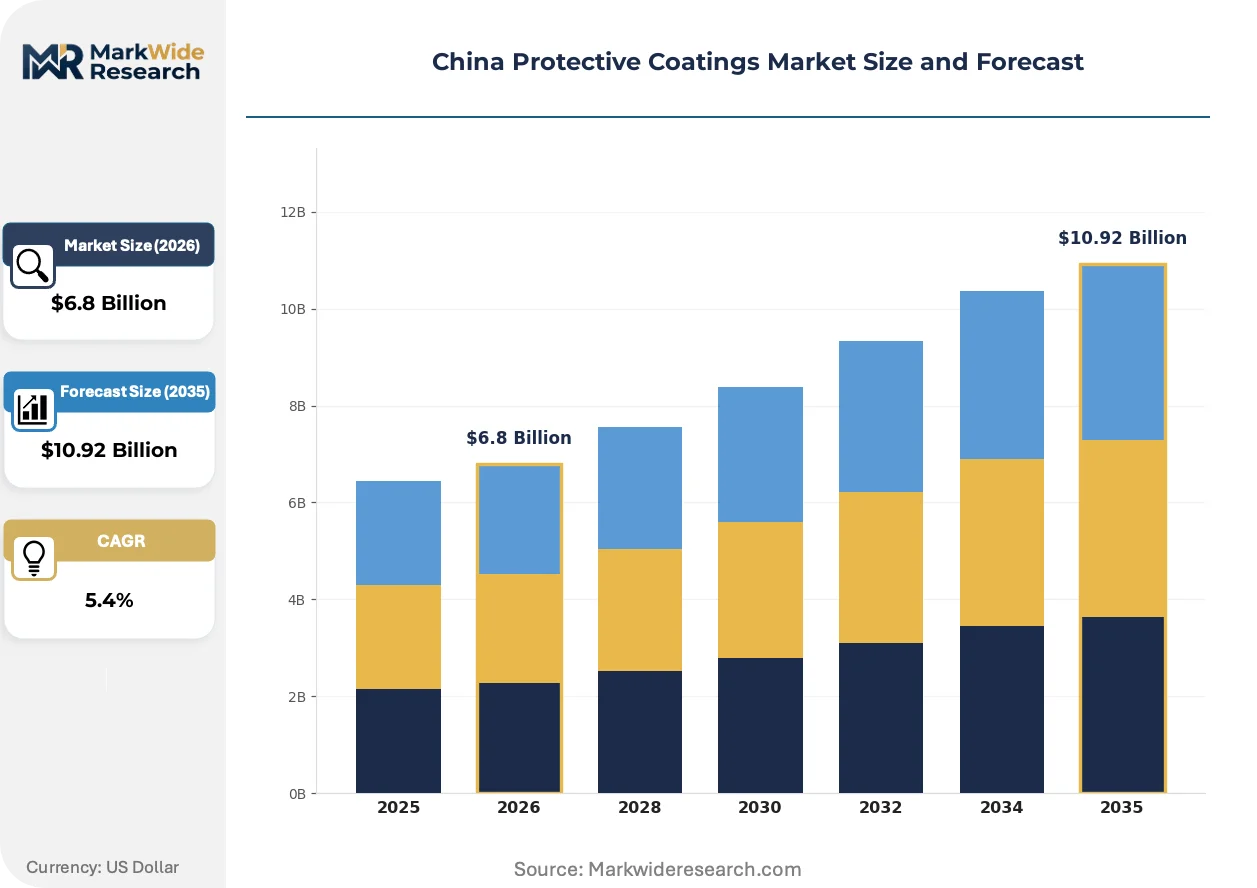
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Alkyd Application: Marine, Automotive, Industrial, Construction End User: Manufacturing, Transportation, Infrastructure, Aerospace Technology: Aqueous, Solvent-Based, Powder Coating, Nano Coating |
| Companies Covered | Jotun, Hempel A/S, AkzoNobel N.V., Axalta Coating Systems, Nippon Paint China, PPG Industries Inc., RPM International Inc., FUXI, The Sherwin-Williams Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Protective Coatings Market Strategic Shifts
Hybrid resin architectures are dissolving traditional technology boundaries as formulators pursue single-coat solutions spanning corrosion protection and aesthetic durability. This convergence is compressing specification complexity while elevating performance validation requirements.
Polyurethane-epoxy hybrid systems are unifying chemical resistance and UV stability in a single applied film, eliminating multi-coat process steps. Automotive refinishing shops and transportation infrastructure contractors are adopting these formulations to compress application cycle times. The technology is unifying previously separate coating procurement decisions into integrated specification packages.
MEE air quality standards and GB national VOC content limits are mandating factory-level emission control investments that favor centralized, large-scale production facilities. Provincial enforcement variance between Jiangsu's accelerated schedule and inland lag creates compliance complexity for national distributors. Marine and heavy industrial segments are responding by consolidating supplier relationships toward formulators with demonstrated regulatory navigation capabilities.
Specification authority is migrating from procurement departments to engineering and EHS functions as total cost of ownership models displace unit price evaluation. Shipyard operators and chemical plant maintenance teams now dominate coating selection decisions, compressing traditional distributor influence. This shift is most visible in Guangdong province manufacturing clusters where multinational OEMs enforce centralized technical standards.
China Protective Coatings Market Segmentation
China's protective coatings market fragments across formulation chemistry, application environment, and compliance technology. Specification decisions increasingly hinge on MEE enforcement timelines and dual carbon alignment rather than historical cost preferences.
Product Type:
Buyers prioritize chemical resistance and cure speed when selecting binder systems for harsh industrial environments.
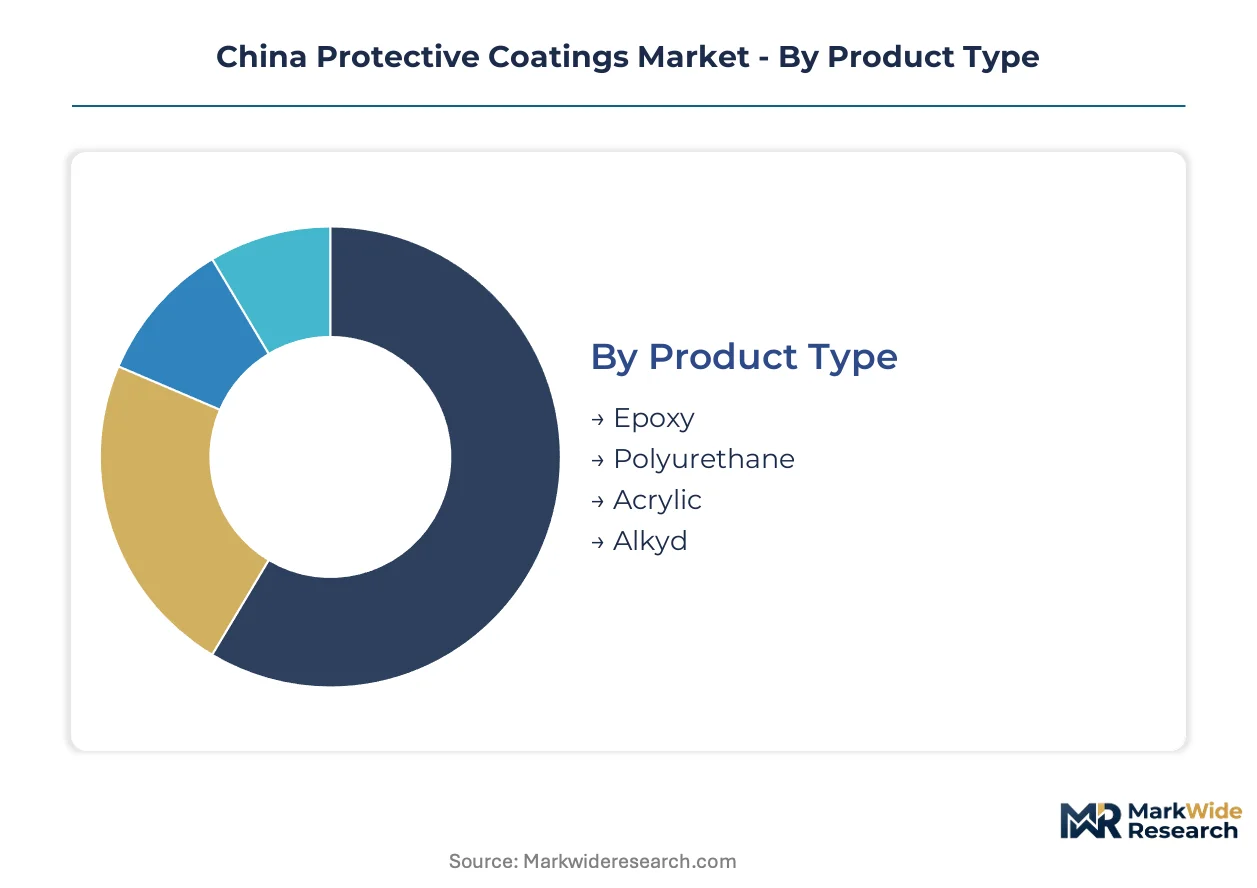
- Epoxy:Two-part thermosetting systems deliver superior adhesion to steel substrates and resistance to chemical attack in chemical processing and offshore platform maintenance. Dalian and Shanghai shipyards specify epoxy primers for immersion service despite longer cure schedules. Volume sits with epoxy formulations across marine and heavy industrial maintenance contracts.
- Polyurethane:Aliphatic isocyanate-cured films combine UV stability with aesthetic retention for transportation infrastructure and automotive refinishing. Guangdong province automotive OEMs specify polyurethane topcoats where color durability commands premium positioning. Growth tilts toward polyurethane as infrastructure projects emphasize lifecycle appearance.
- Acrylic:Thermoplastic emulsions serve decorative-protective applications in construction and light industrial settings where cost sensitivity dominates.
- Alkyd:Oil-modified polyester resins retain position in maintenance painting of existing industrial equipment where solvent tolerance persists.
Epoxy anchors current procurement volumes; polyurethane climbs fastest on infrastructure durability requirements.
Application:
End-use environment dictates performance specifications and compliance intensity.
- Marine:Immersion-zone and atmospheric-zone coatings for hulls, decks, and ballast tanks face the strictest MEE VOC enforcement. Jiangsu and Zhejiang shipyards are converting specification portfolios to aqueous epoxy systems under compressed reformulation timelines. Volume concentrates in marine applications driven by Yangtze River Delta port expansion.
- Industrial:Chemical processing, power generation, and manufacturing facility coatings demand chemical resistance and thermal cycling tolerance. Sichuan and Henan provinces lag coastal enforcement, preserving solvent-based specification windows temporarily. Expansion tilts toward industrial maintenance as facility age accumulates.
- Automotive:OEM and refinishing coatings emphasize appearance retention and process efficiency. Powder coating integration with pre-treatment lines is reshaping procurement specifications.
- Construction:Structural steel and concrete protection applications balance cost against weathering performance in building and civil infrastructure projects.
Marine commands the largest specification volume; industrial maintenance offers the steepest expansion trajectory.
End User:
Capital intensity and regulatory exposure differentiate buyer procurement sophistication.
- Manufacturing:Chemical, electronics, and heavy machinery producers specify coatings for equipment protection and cleanroom environments. MEE factory-level emission audits are accelerating aqueous system conversions among Jiangsu electronics manufacturers.
- Transportation:Shipbuilding, rail, and automotive OEMs enforce centralized technical standards through engineering-led procurement. Dalian port complex operators now require coating lifecycle cost documentation.
- Infrastructure:Bridge, highway, and utility operators are piloting performance-based contracts transferring technical risk to applicators. Yangtze River Delta infrastructure spending generates sustained demand for high-durability systems.
- Aerospace:Military and commercial aviation maintenance demands specialized corrosion protection with rigorous qualification protocols.
Manufacturing absorbs the greatest coating volume; infrastructure procurement is gaining share fastest on performance contracting models.
Technology:
Regulatory compliance timelines are compressing technology transition windows.
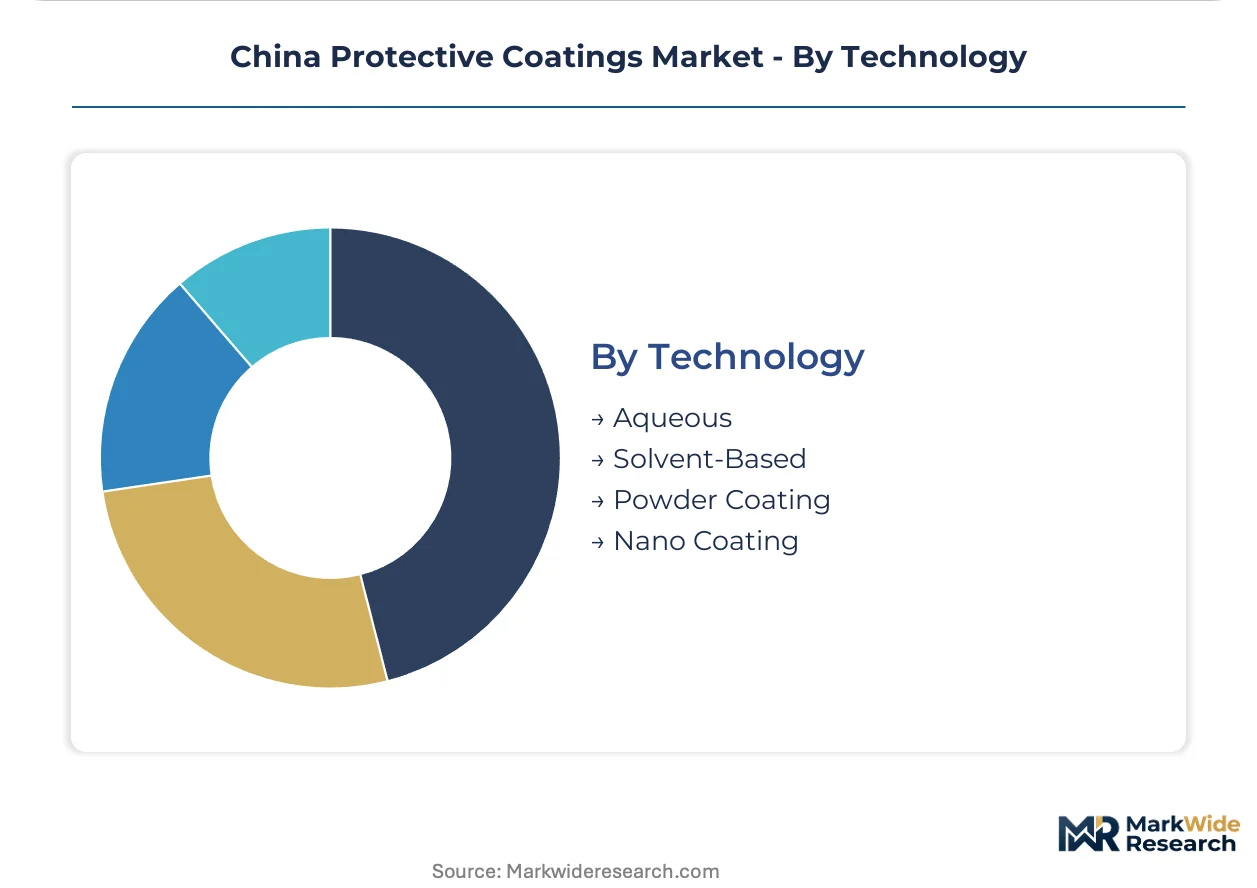
- Aqueous:Waterborne epoxy and acrylic emulsions are displacing solvent systems under MEE VOC discharge permit tightening. SAMR certification requirements and humidity tolerance limitations constrain specification penetration in high-salt marine environments.
- Solvent-Based:Traditional high-solids and conventional solvent systems retain performance advantages in humidity-critical applications. Coastal enforcement is compressing capacity utilization while inland provinces offer temporary regulatory arbitrage.
- Powder Coating:Heat-curable thermoset powders are integrating with appliance and automotive OEM pre-treatment automation lines. Guangdong manufacturing clusters favor powder systems for zero-VOC compliance and material efficiency.
- Nano Coating:Engineered nanoparticle-enhanced films offer self-cleaning and barrier properties in emerging specialty applications.
Aqueous technology captures the fastest adoption trajectory; solvent-based retains residual volume in enforcement-lag provinces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters along China's eastern seaboard while consumption extends inland through distribution networks. The Yangtze River Delta and Pearl River Delta absorb the majority of high-performance coating volumes. Provincial enforcement variance creates distinct operating environments across sub-regional markets.
Yangtze River Delta
Jiangsu and Zhejiang shipyards drive specification demand for marine-grade epoxy systems under compressed MEE reformulation timelines. The dual carbon policy framework mandates aqueous technology conversion at Dalian and Shanghai port complexes. Ningbo and Zhoushan manufacturing clusters are consolidating supplier relationships toward formulators with captive resin synthesis capabilities.
Pearl River Delta
Guangdong province automotive OEMs specify polyurethane topcoats where color durability commands premium positioning. SAMR certification requirements and GB national VOC content limits accelerate factory-level emission control investments. Shenzhen and Dongguan electronics manufacturers are converting coating specifications to aqueous systems under MEE factory audit pressure.
Beijing-Tianjin-Hebei
Heavy industrial maintenance contracts in chemical processing and power generation sustain epoxy formulation demand. MEE air quality standards enforce stricter VOC discharge thresholds than inland provinces. Tianjin port infrastructure expansion generates specification pull for high-performance marine coatings in ballast tank and hull applications.
Sichuan-Chongqing
Chemical processing and manufacturing facility coatings demand chemical resistance and thermal cycling tolerance. Provincial enforcement schedules trail coastal provinces by 18-24 months, preserving temporary solvent-based specification windows. Chengdu and Chongqing industrial clusters attract solvent-based capacity relocation from compressed coastal markets.
Shandong Peninsula
Petrochemical feedstock volatility in naphtha cracking margins affects regional formulation margin stability. GB national standards for VOC content in coatings mandate reformulation timelines for existing industrial equipment maintenance. Qingdao and Yantai shipyards balance aqueous technology adoption against humidity tolerance requirements in high-salt marine environments.
China Protective Coatings Market Competitive Environment
Top-tier vendors anchor specification authority at major port complexes and automotive OEM channels, while mid-tier domestic producers compete on reformulation agility and inland distribution reach. The vendor base stratifies across multinational formulators with captive resin synthesis, regional specialists with localized technical service teams, and commodity producers serving enforcement-lag provinces. Three archetypes dominate: technology leaders with hybrid resin architectures, service-intensive operators with shipyard-embedded technical staff, and scale-driven manufacturers with centralized powder coating facilities. Competitive moves concentrate on strategic partnerships with pre-treatment automation line integrators and geographic expansion into Sichuan and Henan enforcement windows.
Among multinational coating specialists, PPG Industries Inc., Jotun, and AkzoNobel N.V. occupy positions exemplifying distinct competitive vectors. PPG represents the captive supply archetype through resin intermediate control and direct technical service deployment. Jotun anchors marine specification dominance at coastal port complexes. AkzoNobel exemplifies technology leadership in heat-curable powder systems penetrating appliance and automotive OEM channels. These three sit within the premium tier where specification authority has migrated from procurement departments to engineering and EHS functions.
| Leading Market Players |
|---|
| Jotun |
| Hempel A/S |
| AkzoNobel N.V. |
| Axalta Coating Systems |
| Nippon Paint China |
| PPG Industries Inc. |
| RPM International Inc. |
| FUXI |
| The Sherwin-Williams Company |
| Others |
Value Chain & Pricing Dynamics
Formulation chemist scarcity in Jiangsu province widens labor-cost spreads between aqueous technology specialists and legacy solvent-based technicians, compressing mid-tier pricing bands while premium technical service commands sustained margin premiums.
Pricing Analysis
Margin tightening in standard-grade epoxy formulations reflects naphtha cracking volatility feeding through epoxy resin precursor costs. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade marine systems with SAMR certification from commodity maintenance coatings and inland enforcement-lag solvent products. Price differentiation hinges on MEE compliance tier and captive resin synthesis capability. Procurement departments at Dalian shipyards exhibit highest price sensitivity; engineering-led transportation OEMs prioritize lifecycle cost over unit price.
Supply Chain Analysis
Dual-sourcing mandates from Yangtze River Delta shipyards require qualified suppliers for both epoxy resin intermediates and specialty rheology modifiers. Supply concentrates in China, Germany, and Japan for binder systems and performance additives. Raw material dependencies rest on bisphenol-A, isocyanate precursors, and European-sourced defoamers. Single-source vulnerability concentrates in Japanese specialty additive suppliers. Distribution runs through captive technical service teams at major port complexes and regional distributor networks inland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's protective coatings market functions as a cost-of-compliance story where MEE VOC discharge thresholds erect formidable barrier-to-entry moats favoring formulators with established SAMR certification infrastructure.
For Market Incumbents: Extend aqueous technology leadership through captive resin synthesis investments in Zhejiang manufacturing clusters. Consolidate specification authority at Dalian and Shanghai port complexes before mid-tier domestic competitors achieve SAMR certification parity. Defensive priority rests on locking marine maintenance contract renewals with embedded technical service teams. For New Entrants and Emerging Players: The mid-tier price-point gap between PPG-Jotun premium positioning and inland commodity producers offers white-space entry. Target Sichuan and Henan enforcement-lag provinces where solvent-based specification windows persist 18-24 months. Penetrate via reformulation agility for industrial maintenance contractors seeking temporary regulatory arbitrage. For Investors and Strategic Acquirers: Re-rating potential sits with domestic formulators possessing SAMR certification infrastructure and aqueous technology portfolios given MEE enforcement acceleration. Long-term viability favors acquisition targets with demonstrated regulatory navigation capabilities and coastal manufacturing footprint. Watch Jiangsu province VOC reduction schedule acceleration as inflection signal for technology transition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Intermediates | Captive epoxy synthesis secures margin stability against naphtha cracking volatility. |
| SAMR Certification Infrastructure Investment | Localized testing documentation compresses 12-18 month market entry timelines for imported formulations. |
| Shipyard Technical Service Embedding | Dalian and Shanghai port complex presence transfers specification authority from procurement to engineering functions. |
| Aqueous Technology Reformulation Partnerships | Colloidal stability expertise acquisition addresses formulation chemist scarcity constraining waterborne adoption. |
| Inland Province Distribution Expansion | Sichuan and Henan enforcement-lag windows preserve solvent-based capacity utilization before MEE compliance deadlines. |
Study Parameters
Independent corroboration across formulation R&D directors, shipyard procurement managers, and MEE regional enforcement officers underwrites the qualitative findings. Primary interviews with coating applicators, resin intermediate suppliers, and industrial maintenance contractors combined with secondary validation from customs trade data, SAMR certification registries, and GB standard documentation. Bottom-up volume estimates triangulate against top-down spending analysis from Yangtze River Delta infrastructure project disclosures.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation modeling incorporates formulation chemistry, application environment, compliance technology, and provincial enforcement schedule variance. CAGRs derive from regression analysis against MEE policy implementation timelines and dual carbon intensity targets. Forecast inputs include naphtha cracking margin correlations and aqueous technology adoption curves from Jiangsu shipyard specifications.
Inputs from SAMR certification databases and MEE regional enforcement calendars were available through the study window; gaps in proprietary formulation performance data from mid-tier domestic producers introduce uncertainty bands. Forecasts reflect assumptions around MEE implementation consistency across provincial jurisdictions. Deviation in dual carbon policy enforcement velocity or petrochemical feedstock cost trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Waterborne Coatings Market
Coatings
Acrylic Coating Market
Coatings
Global Sputter Coatings Market
Coatings
Global Low Friction Coatings Market
Coatings
Sol-Gel Coatings Market
Coatings
Self-Cleaning Coatings Market
Coatings
Solar Reflective Film Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
Polysiloxane Coatings Market
Coatings
Europe Protective Coatings Market
Coatings
Process Pipe Coating Market
Coatings
Transportation Coating Market
Coatings
In-Mold Coatings Market
Coatings
Coating Market
Coatings
2K Protective Coatings Market
Coatings
Anti-Corrosion Nanocoatings Market