
 Polyamide 11 & 12 Market | 2026-2036
Polyamide 11 & 12 Market Size, Share, and Industry Trends Forecast 2026-2036
Polyamide 11 & 12 Market Analytics
China is fragmenting as domestic compounders expand PA 12 resin capacity to serve local automotive and electronics molding demand. Arkema sustains its bio-based PA 11 leadership through backward integration into castor oil supply chains. Evonik Industries differentiates via high-purity PA 12 grades for powder bed fusion additive manufacturing. BASF competes across reinforced compounds for under-the-hood automotive applications.
Polyamide 11 and 12 are long-chain aliphatic polyamides synthesized from renewable castor oil (PA 11) or petrochemical laurolactam (PA 12), offering low moisture absorption, superior chemical resistance, and dimensional stability from -40°C to 150°C. These properties make them indispensable for fuel handling systems, pneumatic controls, and cable jacketing where hydrocarbon contact and thermal cycling occur. Granule and powder forms dominate volume flows, with powder grades capturing premium pricing in selective laser sintering feedstock. Reinforced and high-performance grades command the widest margin pools as automotive OEMs specify glass-filled variants for engine bay components requiring creep resistance.
EPA fuel permeation standards and EU REACH restrictions on per- and polyfluoroalkyl substances tighten material substitution timelines for hose and tubing manufacturers. FDA food contact regulations and EU MDR biocompatibility requirements open medical device pathways for PA 12 in catheter components and surgical instruments. Stakeholders must monitor regulatory equivalency negotiations between the EU Green Deal framework and emerging Chinese GB standards to anticipate qualification cost shifts.
Market Dynamics
Automotive lightweighting mandates and fluoropolymer phase-outs are compressing qualification timelines for polyamide tubing in fuel and pneumatic systems, forcing specification shifts across European and North American OEM supply chains.
Growth Catalysts
- EPA fuel permeation standards:Tier 3 vehicle emission rules in the United States mandate ultra-low permeation fuel lines, redirecting hose manufacturers toward PA 11 and PA 12 barrier layers.
- EU F-Gas Regulation restrictions:The European phasedown of hydrofluorocarbon-based refrigerants accelerates adoption of polyamide hoses in mobile air conditioning systems.
- Selective laser sintering feedstock demand:Powder bed fusion additive manufacturing in medical device prototyping consumes high-purity PA 12 grades at expanding volumes.
Market Restraints
- Castor oil supply concentration:Over 90% of global castor bean cultivation clusters in India, exposing PA 11 producers to monsoon-dependent crop volatility and export policy shifts.
- Laurolactam feedstock oligopoly:Petrochemical-derived PA 12 remains tethered to cyclododecatriene supply chains concentrated among European chemical majors.
- Polyether ether ketone substitution:High-temperature engine bay applications above 150°C increasingly specify PEEK where thermal budgets permit cost absorption.
Strategic Opportunities
- Chinese domestic compounding expansion:Local resin capacity build-out in Jiangsu and Zhejiang provinces creates captive supply for automotive Tier 1 molders serving BYD and NIO.
- EU Medical Device Regulation biocompatibility pathways:MDR Class IIa certification for long-term implantable devices opens catheter and surgical instrument applications for PA 12.
- Hydrogen fuel cell infrastructure:High-pressure hydrogen distribution systems require chemically resistant tubing, converging with existing polyamide qualification expertise in pneumatic brake systems.
Industry Challenges
- OEM material qualification protocols:Volkswagen, BMW, and Ford each maintain distinct 18-36 month validation cycles for under-hood components, fragmenting R&D resource allocation.
- Biobased content verification complexity:ISCC PLUS mass balance certification for PA 11 requires supply chain documentation down to individual castor bean cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyamide 11 & 12 Market |
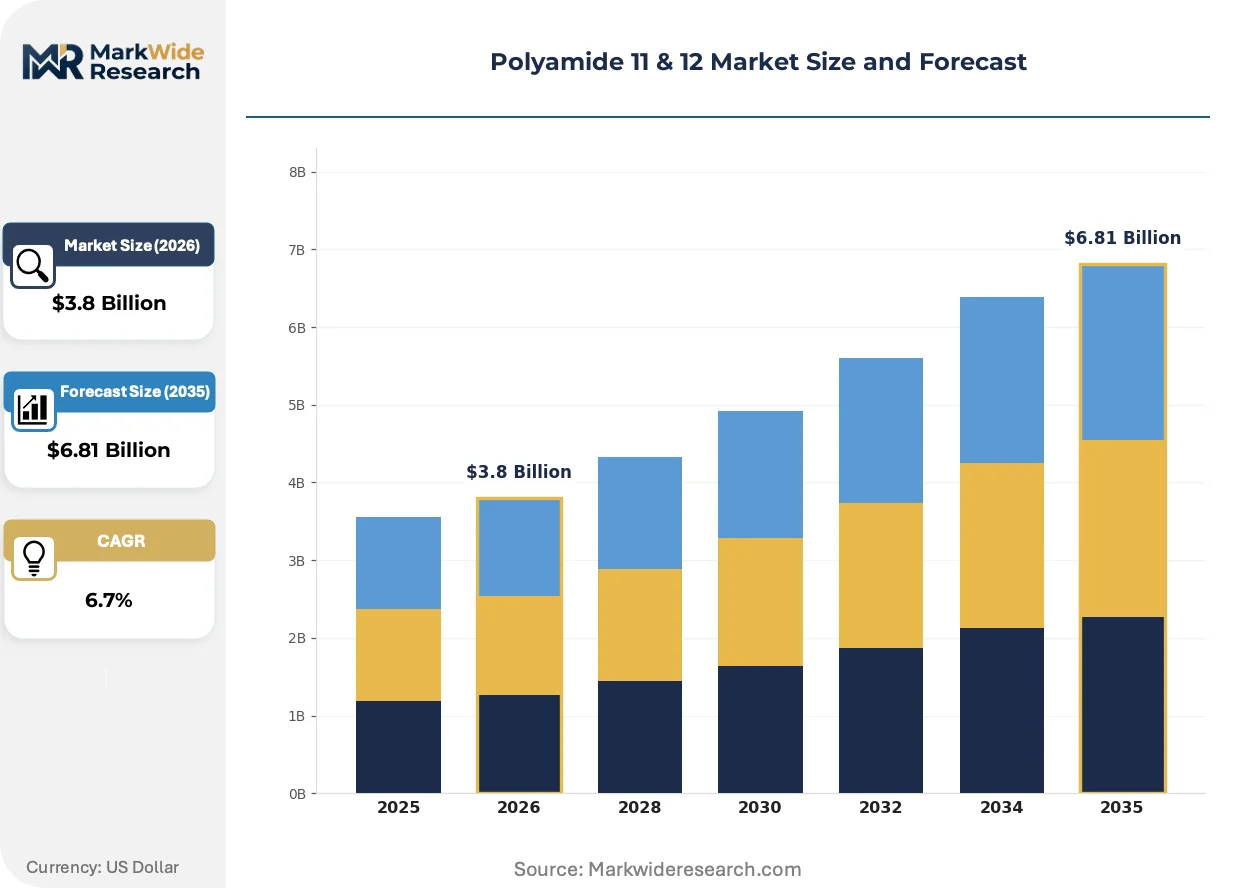
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PA 11, PA 12, Blends, Compounds End Use Industry: Automotive, Electronics, Aerospace, Industrial Form: Granules, Powders, Films, Fibers Grade: Standard, Reinforced, High-Performance, Others |
| Companies Covered | BASF, Evonik Industries, Arkema, INVISTA, Envalior, Mitsubishi Chemical, UBE Industries, Ascend Performance Materials, Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyamide 11 & 12 Market Evolving Landscape
Material substitution dynamics and additive manufacturing maturation are rewriting competitive boundaries between petroleum-derived and bio-based polyamide grades.
High-performance powder grades for laser sintering is collapsing the traditional injection molding monopoly in medical device prototyping. Dental laboratories and orthopedic implant developers in Germany and Switzerland now specify PA 12 powder for patient-specific surgical guides, compressing lead times from weeks to days while eliminating tooling costs.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluoropolymer options from fuel line specifications. The European Chemicals Agency's 2023 PFAS restriction proposal forces hose manufacturers to requalify entire product families using PA 11 and PA 12 barrier layers, with German OEMs leading the transition timeline.
Consolidated procurement by automotive platform engineering teams is displacing decentralized material selection. Volkswagen's unified sourcing for MEB-platform electric vehicles now mandates single-supplier polyamide specifications across multiple assembly plants, concentrating volume with qualified compounders in Wolfsburg and Chattanooga.
Polyamide 11 & 12 Market Segmentation
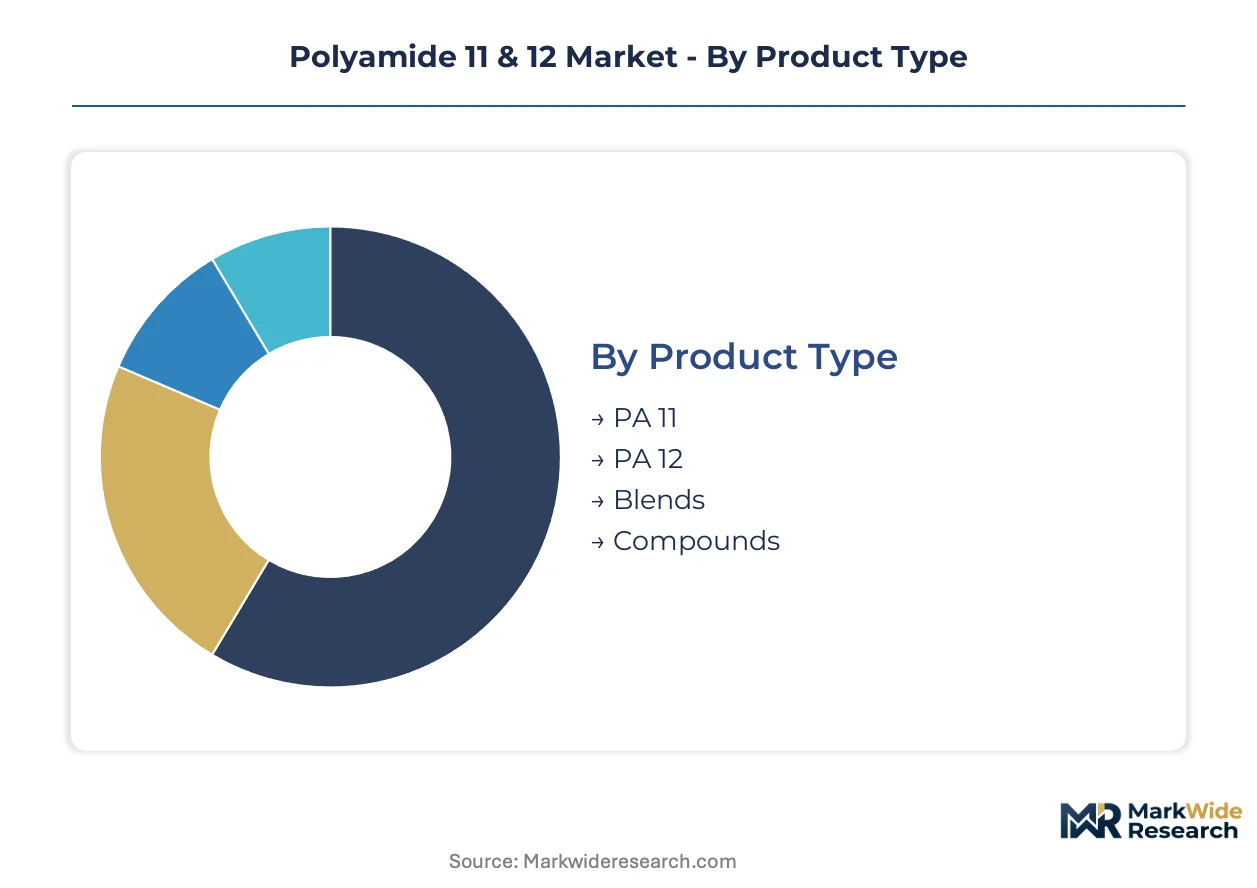
Polyamide 11 and 12 markets fragment across four critical dimensions that govern procurement behavior. Product chemistry determines bio-based versus petroleum feedstock exposure. End-use concentration in automotive tubing versus medical additive manufacturing creates divergent margin profiles. Physical form and performance grade specifications dictate qualification timelines and supplier switching costs.
Product Type:
Cycle times vary dramatically across chemistry types, with petroleum-derived grades turning inventory faster than bio-based alternatives subject to agricultural harvest schedules.
- PA 11:Synthesized from castor oil monomers, this bio-based polyamide delivers superior flexibility and chemical resistance for fuel line applications. Demand clusters in European automotive OEMs sourcing from Arkema's backward-integrated supply chains in India, where monsoon-dependent crop yields create 12-18 month pricing visibility challenges.
- PA 12:Petroleum-derived from laurolactam, this grade dominates powder bed fusion feedstock markets with tighter dimensional tolerances and lower moisture absorption. German medical device prototypers in Munich and Stuttgart specify high-purity PA 12 powders for surgical guide production, driving premium pricing over injection molding grades.
- Blends:Alloy formulations combining PA 11 and PA 12 optimize cost-performance ratios for pneumatic tubing manufacturers.
- Compounds:Mineral-filled and impact-modified variants serve under-hood automotive specifications requiring heat deflection above 120°C.
PA 12 anchors the volume base while PA 11 gains share at the steepest rate as EU Green Deal procurement mandates expand.
End Use Industry:
Application concentration determines margin tier, with medical and aerospace commanding 3-4x automotive commodity pricing.
- Automotive:Fuel line systems, pneumatic brake tubing, and vapor recovery hoses consume reinforced grades where EPA Tier 3 permeation standards mandate barrier layer specifications. Volkswagen's MEB platform consolidation in Wolfsburg and Chattanooga concentrates volume with qualified compounders.
- Electronics:Cable jacketing and connector housings exploit low moisture absorption properties for outdoor infrastructure. Chinese domestic compounders in Jiangsu province serve BYD and NIO supply chains with locally produced resin.
- Aerospace:Lightweight pneumatic ducting and interior components specify high-performance grades meeting FAA flammability requirements.
- Industrial:Hydraulic hoses and process equipment components prioritize chemical resistance over thermal performance.
Automotive procurement anchors volume while medical additive manufacturing climbs the fastest as laser sintering adoption accelerates.
Form:
Physical state dictates supply chain configuration, with powders requiring inert atmosphere handling versus granule bulk shipping.
- Granules:Standard injection molding feedstock serving high-volume automotive and industrial applications with conventional melt processing.
- Powders:Selective laser sintering feedstock for additive manufacturing, where particle size distribution and sphericity determine build chamber yields. Evonik Industries supplies high-purity PA 12 powders to German dental laboratories and Swiss orthopedic implant developers.
- Films:Extruded barrier layers for multi-layer fuel hoses requiring coextrusion compatibility with fluoropolymer replacements.
- Fibers:Specialized textile applications in filtration and industrial belting with limited volume penetration.
Granule shipments anchor volume while powder grades expand most quickly as medical prototyping displaces conventional tooling.
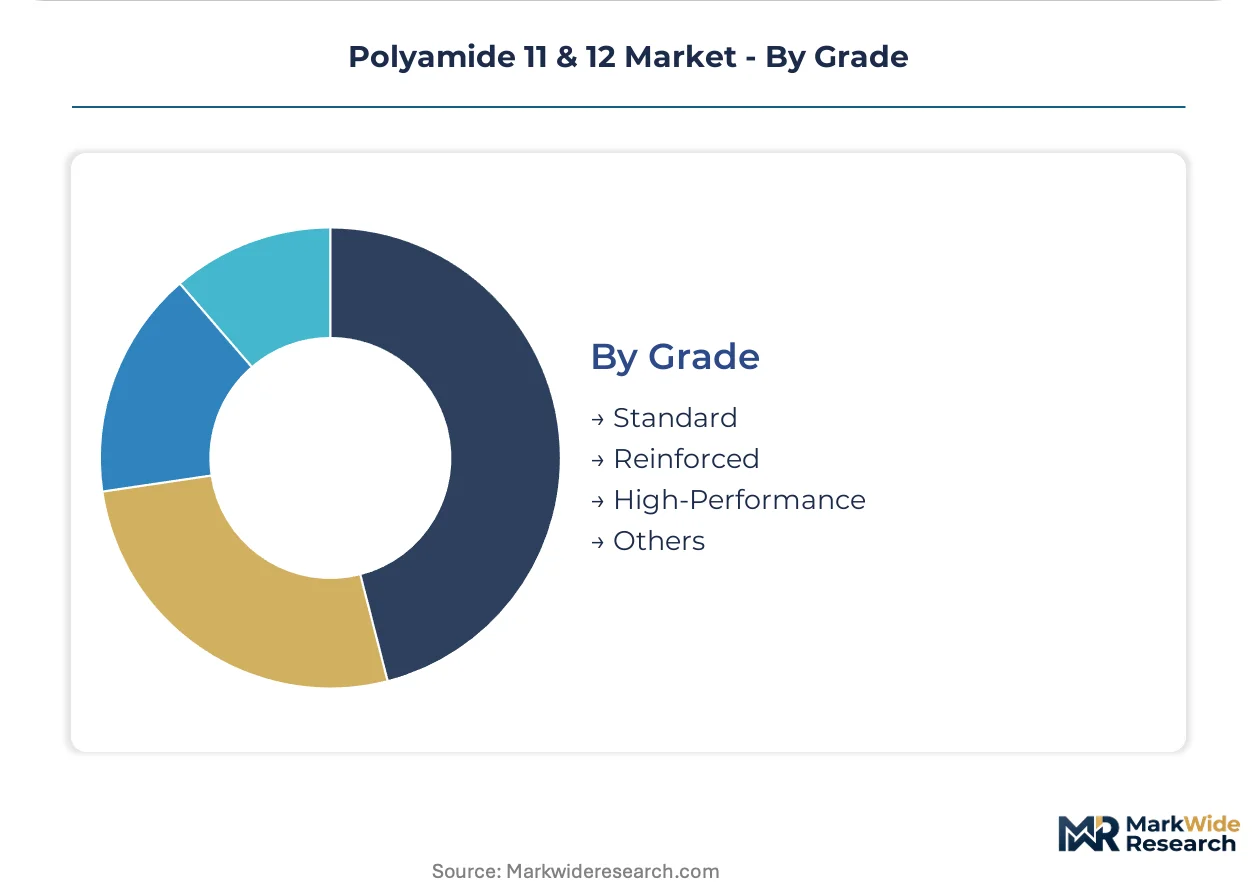
Grade:
Performance tier alignment with OEM qualification protocols creates sticky supplier relationships and 18-36 month validation cycles.
- Standard:Unfilled base resins for general-purpose injection molding where cost minimization dominates specification.
- Reinforced:Glass fiber and mineral-filled compounds delivering creep resistance for engine bay components. BASF competes across this segment for under-hood applications at BMW and Ford.
- High-Performance:Heat-stabilized and chemically resistant grades for extreme service conditions, capturing widest margin pools.
- Others:Custom formulations and masterbatch concentrates for niche processing requirements.
Reinforced grades anchor volume while high-performance formulations gain share fastest as thermal and chemical specification thresholds tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Castor oil cultivation clusters in India feed bio-based PA 11 production, while petrochemical PA 12 capacity concentrates among European and Asian chemical majors. Automotive OEM qualification protocols in Germany, the United States, and China drive specification divergence across regional supply chains.
Germany
Volkswagen's MEB platform consolidation and BMW's under-hood component specifications consume reinforced polyamide grades for electric vehicle architectures. EU REACH restrictions on PFAS compounds accelerate fluoropolymer substitution in fuel line barrier layers. Industrial clusters in Wolfsburg and Stuttgart host qualified compounders serving Tier 1 automotive suppliers.
United States
EPA Tier 3 fuel permeation standards mandate ultra-low emission fuel lines for light-duty vehicles, redirecting hose manufacturers toward PA 11 and PA 12 barrier specifications. Ford and General Motors maintain distinct 18-36 month material validation cycles for engine bay components. Manufacturing concentration in Michigan and Tennessee supports regional automotive supply chain integration.
China
Domestic compounders in Jiangsu and Zhejiang provinces expand PA 12 resin capacity to serve BYD and NIO demand for cable jacketing and connector housings. GB standards development for bio-based materials creates regulatory uncertainty for imported PA 11 qualifications. Local automotive Tier 1 molders increasingly source from captive resin supply rather than European imports.
India
Over 90% of global castor bean cultivation concentrates in Gujarat and Rajasthan, exposing PA 11 feedstock supply to monsoon-dependent crop volatility. Export policy shifts and cooperative pricing structures create 12-18 month pricing visibility challenges for European processors. Arkema maintains backward-integrated supply chain control through direct sourcing relationships with regional agricultural cooperatives.
Japan
Mitsubishi Chemical and UBE Industries anchor domestic PA 12 production for electronics cable jacketing and industrial hose applications. METI carbon neutrality roadmaps incentivize bio-based material adoption in automotive supply chains. Manufacturing clusters in Nagoya and Osaka serve precision electronics and automotive component export markets.
Polyamide 11 & 12 Market Competitive Landscape
Backward-integrated bio-based specialists and petrochemical-scale producers split the market into divergent margin structures. European majors dominate high-performance grades with 18-36 month OEM qualification timelines creating sticky supplier relationships. Three archetypes define competitive positioning: castor oil-integrated bio-based leaders, laurolactam-based petrochemical scale players, and regional compounders serving captive automotive demand. Capacity expansion in China and strategic partnerships for hydrogen fuel cell tubing represent the dominant competitive moves across the forecast window.
Among the integrated petrochemical tier, BASF and Evonik Industries exemplify scale-driven positioning across reinforced compounds and powder bed fusion feedstock respectively. Arkema occupies a distinct position as the bio-based PA 11 anchor through upstream control over Indian castor oil supply chains. These three European entities represent the dominant competitive anchors against which regional Asian compounders define market entry strategies.
| Leading Market Players |
|---|
| BASF |
| Evonik Industries |
| Arkema |
| INVISTA |
| Envalior |
| Mitsubishi Chemical |
| UBE Industries |
| Ascend Performance Materials |
| Huntsman Corporation |
| Others |
Value Network & Pricing Analysis
Undercapacity in European laurolactam production is tightening supplier pricing power while Indian castor oil harvest volatility feeds through to PA 11 contract negotiations. Automotive OEMs face extended allocation periods as capacity utilization rates above 85% at German chemical majors enable margin expansion across reinforced compound grades.
Pricing Analysis
EPA Tier 3 fuel permeation standards dictate the pricing tier structure across automotive tubing specifications, separating UL-certified barrier layers from standard injection molding grades. Price differentiation hinges on ISCC PLUS mass balance certification and glass fiber loading percentages. Cost compression in unreinforced base resins is intensifying because Chinese domestic compounders are expanding captive supply for BYD and NIO cable jacketing. Tier 1 automotive suppliers exhibit the highest price sensitivity due to platform engineering consolidation, while medical device prototypers in Munich and Stuttgart absorb premium powder pricing for surgical guide applications.
Supply Chain Analysis
Extended payment terms from Volkswagen's MEB platform procurement teams are reshaping working capital requirements for qualified compounders in Wolfsburg and Chattanooga. Geographic supply concentration centers on Germany for high-purity PA 12 powders, India for castor oil-derived PA 11 monomers, and China for electronics-grade cable jacketing compounds. Raw material dependencies rest on laurolactam from cyclododecatriene crackers, castor bean harvests from Gujarat and Rajasthan cooperatives, and glass fiber from specialty mineral processors. Single-source vulnerability in Indian castor oil export policies creates 12-18 month pricing visibility gaps. Distribution runs through automotive Tier 1 molders with direct mill relationships and medical device powder distributors serving German dental laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Volkswagen's unified MEB platform sourcing and Ford's consolidated engine bay specifications displace decentralized material selection. Tier 1 automotive procurement teams now dictate single-supplier qualifications across multiple assembly plants.
For Market Incumbents: Harden backward integration into Indian castor oil cooperatives to secure PA 11 feedstock against monsoon-dependent crop volatility and DGFT export policy shifts. Expand high-purity powder capacity for selective laser sintering feedstock to capture medical device prototyping margins. Arkema's existing upstream control over Gujarat agricultural supply chains provides the defensive template for bio-based positioning.
For New Entrants and Emerging Players: Hydrogen fuel cell high-pressure tubing in German and Japanese automotive supply chains represents the most penetrable entry point, converging with existing pneumatic brake system qualification expertise. Chinese domestic electronics molding for BYD and NIO cable jacketing offers second-mover advantage through GB standards alignment rather than EU REACH equivalency. Target captive supply agreements with Jiangsu province compounders lacking in-house resin production.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among powder-grade specialists serving medical device prototyping workflows with 18-36 month OEM validation cycles creating sticky supplier relationships. Long-term viability across the analysis window favors compounders with dual PA 11 and PA 12 production capability spanning bio-based and petroleum feedstocks. Monitor EPA fuel permeation standard enforcement intensity and EU PFAS restriction implementation timelines as demand inflection indicators for fluoropolymer substitution volumes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Castor Oil Supply | Arkema's Gujarat cooperative relationships secure bio-based PA 11 feedstock against Indian monsoon volatility. |
| High-Purity Powder Capacity Expansion | Evonik's medical-grade PA 12 powders capture premium pricing from German dental laboratory demand. |
| Platform Standardization Partnerships | Volkswagen's MEB consolidation concentrates volume with qualified compounders in Wolfsburg and Chattanooga. |
| Hydrogen Fuel Cell Tubing Qualification | BASF leverages existing pneumatic brake expertise for high-pressure hydrogen distribution infrastructure. |
| ISCC PLUS Mass Balance Certification | EU Green Deal procurement mandates drive bio-based content verification down to individual castor bean cooperatives. |
Research Methodology
A standing panel of automotive platform engineers, Tier 1 supplier procurement leads, medical device R&D directors, and chemical distribution channel partners provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation from SEC 10-K filings, Cefic industry reports, customs trade data, and FDA medical device registration databases. Bottom-up volume modeling from individual OEM specifications triangulated against top-down chemical industry capacity assessments.
Scenario-bracketing around EPA enforcement intensity and EU PFAS restriction timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include chemistry type, physical form, performance grade tier, end-use industry concentration, and regional production hub. CAGRs derived from installed base growth in automotive tubing and additive manufacturing feedstock adoption curves. Industry-specific forecast inputs incorporated monsoon-dependent castor oil yield variance and OEM qualification cycle duration assumptions.
Practitioners should monitor Indian monsoon patterns, DGFT export policy shifts, and EU-GB regulatory equivalency negotiations for early signals of supply constraint or qualification cost inflation. Forecasts reflect assumptions regarding continued fluoropolymer phase-out momentum and powder bed fusion medical prototyping adoption. Macroeconomic automotive production contraction, abrupt castor oil supply disruption, or hydrogen fuel cell infrastructure delays would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Liquid Polybutadiene [LPBD] Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Smart Polymers Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
Sodium Polyacrylate Market
Polymers & Resins
North America Linear Low-Density Polyethylene Market
Polymers & Resins
Global Linear Low Density Polyethylene Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Transparent Polyamides Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Resin Market
Polymers & Resins
Water Soluble Polymers Market
Polymers & Resins
Polymer Seals Market
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
Polyvinyl Alcohol Resins Market