

Epoxy Casting Potting Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Casting Potting Resin Market Insights
The epoxy casting potting resin market is pivoting on a widening gap between high-purity semiconductor-grade formulations and cost-optimized industrial grades. Henkel leverages its adhesive chemistry heritage to dominate electronics-grade potting systems with tight ionic purity controls. Dow anchors the commodity transformer segment through backward integration into bisphenol-A epichlorohydrin feedstocks. Huntsman differentiates via specialized anhydride curing systems for high-voltage renewable energy applications.
Epoxy casting potting resin comprises thermosetting polymers formed from epoxide monomers and amine or anhydride hardeners, typically achieving glass transition temperatures of 120-180°C and dielectric strengths exceeding 15 kV/mm to protect sensitive components from moisture, thermal cycling, and mechanical shock. Flame retardant formulations lead volume in industrial equipment and aerospace wire harness applications where UL 94 V-0 compliance is mandatory. High thermal conductivity grades represent the fastest-expanding product category as power electronics in electric vehicles and wind turbines generate escalating heat flux densities. Semiconductor protection applications command premium margins due to low-alpha particle emission requirements and sub-ppm ionic contamination thresholds.
EPA regulations on volatile organic compound emissions constrain solvent-borne formulation practices in the United States, while REACH substance restrictions in Europe drive substitution of brominated flame retardants with phosphorus-nitrogen synergists. China's GB standards on hazardous substances in electrical products, administered by SAMR, mandate disclosure of restricted substance content across supply chains. Stakeholders must monitor evolving halogen-free certification schemes and thermal conductivity benchmarking protocols as qualification criteria tighten for next-generation wide-bandgap semiconductor packaging.
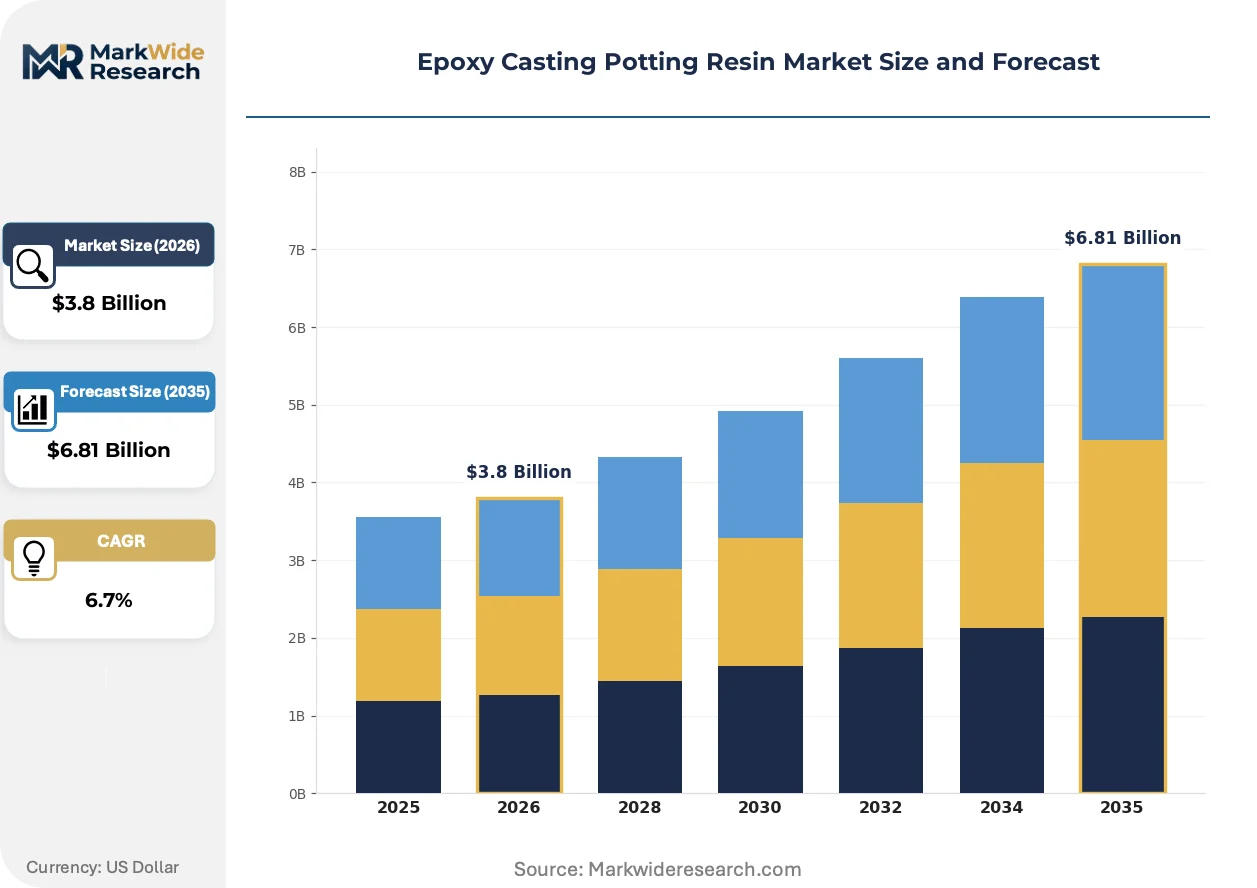
Market Dynamics
The epoxy casting potting resin market is bifurcating around thermal conductivity requirements, as silicon carbide power modules in electric vehicles and wind turbines push legacy formulations toward obsolescence while semiconductor packaging demands simultaneously tighten ionic purity thresholds.
Growth Catalysts
- Wide-bandgap semiconductor proliferation:Silicon carbide and gallium nitride devices in EV inverters and renewable energy converters require potting resins with thermal conductivity above 2.0 W/mK, creating specification upgrades across automotive and wind energy supply chains.
- RoHS and REACH substance restrictions:European halogen-free mandates are accelerating phosphorus-nitrogen flame retardant adoption, forcing reformulation investments that lock in supplier relationships and raise technical barriers to entry.
- China's renewable energy buildout:Domestic wind turbine and solar inverter manufacturing absorbs high volumes of transformer-grade potting compounds, with State Grid procurement specifications driving standardization toward 155°C thermal class systems.
Market Restraints
- Bisphenol-A epichlorohydrin feedstock concentration:Dow and Hexion control upstream epichlorohydrin capacity in the US Gulf Coast, creating margin squeeze risks for independent compounders during chlorine supply disruptions.
- Anhydride curing agent technical ceiling:High-voltage renewable applications above 66 kV face glass transition temperature limitations around 180°C, constraining service life in desert solar installations with sustained 150°C operating temperatures.
- Silicone resin substitution in aerospace:Boeing and Airbus wire harness specifications increasingly specify addition-cure silicones for flame retardancy, displacing epoxy systems in premium aerospace segments despite higher material costs.
Strategic Opportunities
- India electronics manufacturing expansion:PLI scheme incentives for semiconductor packaging and mobile phone assembly are creating demand for low-alpha particle potting grades previously imported from China and Taiwan.
- Dual carbon policy alignment in China:SAMR carbon footprint disclosure requirements for electrical products favor domestically produced bio-based epoxy precursors, advantaging local compounders with glycidyl ether from lignin or epoxidized vegetable oils.
- Direct-to-turbine OEM supply contracts:Vestas and Siemens Gamesa are consolidating potting resin procurement through single-source technical partnerships, bypassing traditional distributor channels and capturing formulation co-development IP.
Industry Challenges
- Formulation chemist scarcity:Expertise in anhydride-amine hybrid curing systems for high-voltage applications concentrates among retiring specialists at German and Japanese compounders, constraining new product development timelines.
- UL 94 V-0 certification backlog:Testing laboratory capacity constraints in North America and Europe extend qualification cycles to 14-18 months, delaying new halogen-free product launches and freezing specification decisions.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Casting Potting Resin Market Trends and Innovations
Thermal management requirements are compressing the performance gap between commodity transformer grades and premium semiconductor formulations, forcing compounders to develop intermediate product tiers with modular additive packages.
Aluminum nitride and boron nitride filler technologies are consolidating around surface-treated spherical particle morphologies that achieve 3.0+ W/mK thermal conductivity while maintaining pumpable viscosity for automated dispensing. Automotive inverter manufacturers in Germany and Japan are qualifying these grades for 800V silicon carbide platforms, compressing the traditional separation between automotive and industrial resin specifications into a unified high-thermal product category.
REACH Annex XIV authorization procedures for bisphenol-A derivatives are compelling European electrical equipment OEMs to accelerate bio-based epoxy trials ahead of potential restriction timelines. ECHA's 2023-2024 substance evaluation priorities specifically flagged diglycidyl ether of bisphenol-A for endocrine disruption assessment, pushing ABB, Siemens, and Schneider Electric to qualify epoxidized novolac and aliphatic glycidyl ether alternatives in transformer and switchgear applications.
Long-term service contracts with guaranteed thermal performance degradation rates are displacing spot resin purchases among wind turbine OEMs. Vestas and Goldwind now procure potting materials through 10-year agreements incorporating accelerated aging test protocols and field performance guarantees, transferring technical risk from operators to compounders and locking out smaller suppliers lacking predictive modeling capabilities.
Epoxy Casting Potting Resin Market Segmentation
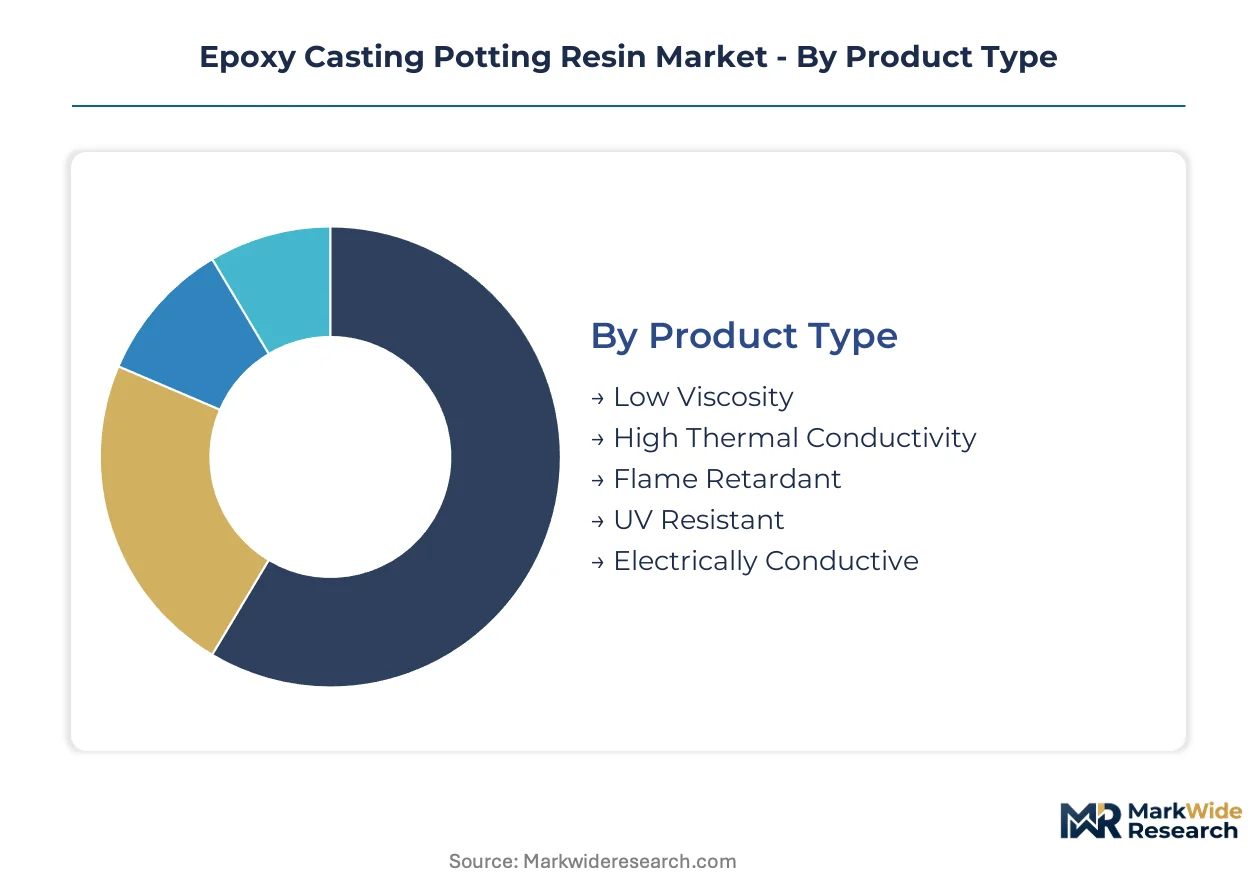
Epoxy casting potting resin segmentation reflects divergent technical requirements across power electronics, semiconductor packaging, and industrial equipment. Specification tiers separate commodity transformer grades from ionic-purity-controlled semiconductor formulations, with thermal conductivity emerging as the primary axis of product differentiation.
Product Type:
Customization intensity spans from standardized transformer grades to application-engineered semiconductor formulations, with filler loading and curing chemistry driving performance segmentation.
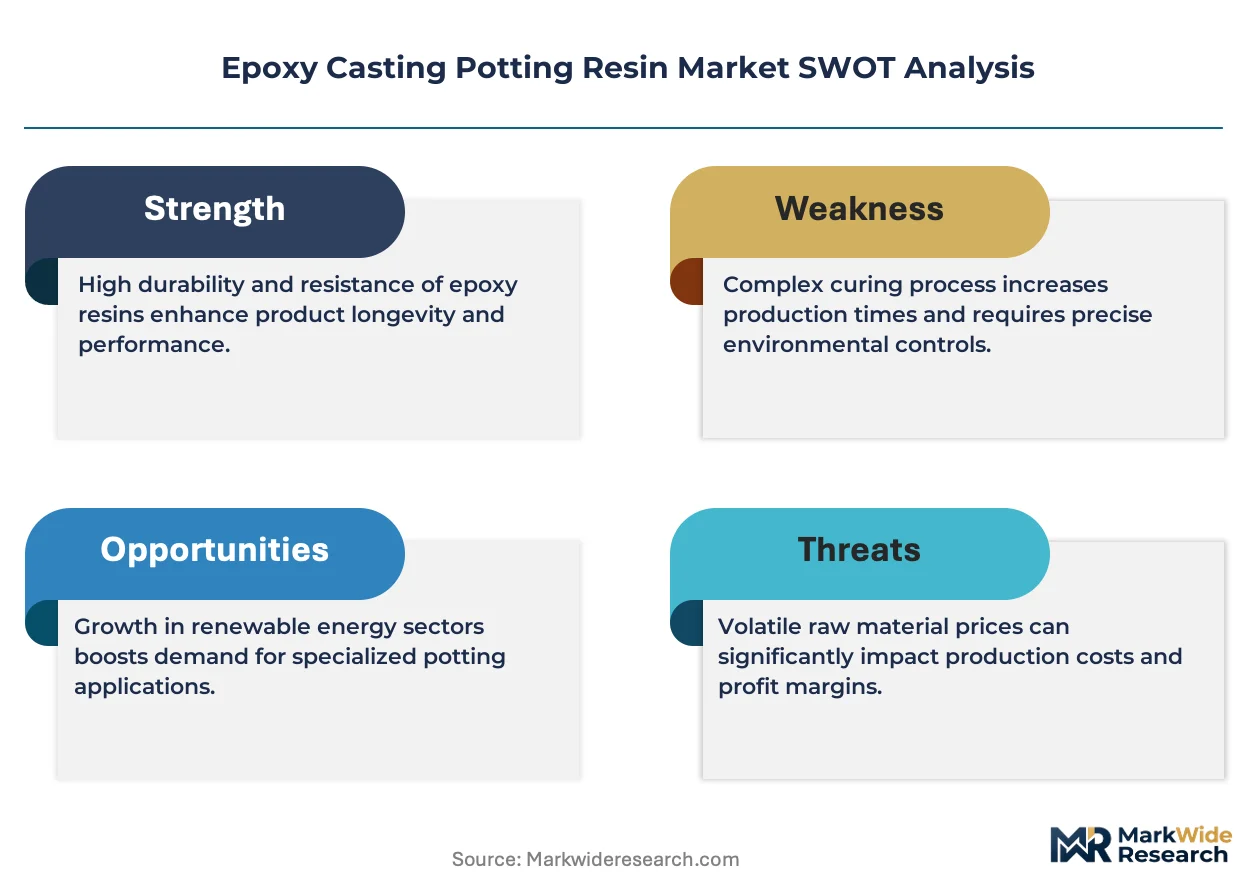
- High Thermal Conductivity:Aluminum nitride and boron nitride filler loadings achieve 2.0-3.5 W/mK thermal conductivity for silicon carbide power module packaging. Automotive inverter manufacturers in Germany and Japan specify these grades for 800V platforms, displacing legacy transformer resins in electrification supply chains.
- Flame Retardant:Phosphorus-nitrogen synergist systems meet UL 94 V-0 without halogenated additives, driven by REACH substance restrictions and aerospace wire harness specifications. UL certification backlogs of 14-18 months constrain new product qualification timelines.
- Low Viscosity:Optimized for automated dispensing in high-volume consumer electronics assembly.
- UV Resistant:Hindered amine light stabilizers protect outdoor LED encapsulation from photodegradation.
- Electrically Conductive:Silver or carbon filler loadings for electromagnetic shielding in telecommunications infrastructure.
Most installed capacity flows through Flame Retardant formulations. Expansion is steepest in High Thermal Conductivity grades.
Application:
Volume concentration versus margin capture separates utility-scale transformer encapsulation from premium semiconductor protection applications.
- Semiconductor Protection:Sub-ppm ionic purity and low-alpha particle emission specifications protect memory and logic devices from soft errors. Taiwan and South Korea packaging houses command premium pricing for these qualifications, with ionic contamination thresholds tightening for advanced node chips.
- Transformer Encapsulation:155°C thermal class systems dominate wind turbine and grid infrastructure applications. China's State Grid procurement specifications standardize domestic supply toward this thermal rating, absorbing significant resin volumes in renewable energy buildout.
- LED Encapsulation:Optical clarity and yellowing resistance for solid-state lighting modules.
- Sensor Sealing:Moisture barrier protection for automotive and industrial IoT devices.
- Automotive Electronics:Vibration resistance and thermal cycling durability for under-hood applications.
Transformer Encapsulation commands the largest volume share. Semiconductor Protection delivers the steepest margin expansion trajectory.
End User Industry:
Customer technical sophistication ranges from price-sensitive industrial equipment buyers to specification-locked semiconductor packaging houses.
- Renewable Energy:Wind turbine OEMs procure through 10-year service contracts with guaranteed thermal degradation rates. Vestas and Goldwind specifications incorporate accelerated aging protocols that transfer technical risk to compounders.
- Consumer Electronics:High-volume, low-margin demand from mobile phone and laptop manufacturers concentrates in China and Vietnam assembly operations.
- Industrial Equipment:Motor drive and power supply manufacturers specify standard thermal class systems.
- Aerospace & Defense:Boeing and Airbus wire harness specifications increasingly favor silicone alternatives despite higher costs.
- Telecommunications:Base station and data center power supply encapsulation requirements.
Industrial Equipment represents the most mature demand base. Renewable Energy is gaining share fastest through OEM direct procurement consolidation.
Packaging Type:
Delivery format selection tracks customer scale and dispensing automation requirements across the value chain.
- Drum:Standard 200-liter containers for transformer and industrial compounders with bulk handling infrastructure.
- Cartridge:Pre-metered dual-component systems for field repair and prototype applications.
- Pail:Mid-volume packaging for contract electronics manufacturers.
- Bulk Tank:Direct pipeline delivery to high-volume automotive and wind turbine OEMs.
- Syringe:Precision dispensing for semiconductor packaging cleanroom environments.
Most formulated resin moves through Drum packaging. Syringe formats are climbing the fastest on semiconductor automation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists with anhydride-amine hybrid expertise concentrate in German and Japanese industrial clusters, anchoring high-voltage application development. These technical workforces support regional specialization in semiconductor-grade and renewable energy resin systems.
United States
Silicon carbide power module packaging for 800V automotive platforms drives specification upgrades across Michigan and Tennessee manufacturing corridors. EPA volatile organic compound regulations constrain solvent-borne formulation practices in industrial coating applications. Houston-Gulf Coast petrochemical complexes house Dow and Hexion epichlorohydrin capacity that feeds domestic compounder networks.
Germany
Automotive inverter manufacturers in Bavaria and Baden-Württemberg qualify high-thermal-conductivity grades for electrification supply chains. ECHA REACH Annex XIV authorization procedures for bisphenol-A derivatives accelerate bio-based epoxy trials at ABB and Siemens transformer divisions. Frankfurt-Rhine-Main chemical clusters host specialized anhydride curing agent production for wind turbine OEM specifications.
China
State Grid procurement standardizes 155°C thermal class systems for domestic wind turbine and solar inverter buildout. SAMR carbon footprint disclosure requirements under dual carbon policy favor bio-based epoxy precursors from lignin-derived glycidyl ether. Yangtze River Delta electronics manufacturing absorbs significant resin volumes for semiconductor packaging and consumer electronics assembly.
Japan
Packaging houses in Kyushu and Kansai regions command premium pricing for sub-ppm ionic purity qualifications on advanced node chips. METI industrial standards guide flame retardant formulation shifts away from legacy halogenated systems. Chubu-Nagoya automotive supplier networks integrate high-thermal-conductivity potting into hybrid vehicle inverter platforms.
South Korea
Memory and logic device manufacturers in Seoul Capital Area and Gyeonggi Province tighten low-alpha particle emission thresholds for soft error protection. MFDS hazardous substance tracking aligns with export market REACH compliance requirements. Busan-Ulsan chemical complexes supply specialized hardener systems to domestic electronics packaging houses.
Epoxy Casting Potting Resin Market Competitive Landscape
Top-tier vendors anchor semiconductor-grade and high-voltage renewable formulations, while mid-tier compounders serve commodity transformer and industrial equipment segments. The market structure reflects feedstock concentration around Gulf Coast epichlorohydrin capacity and formulation expertise clustering in German and Japanese technical centers. Strategic archetypes include vertically integrated petrochemical players, specialized curing system compounders, and electronics-grade purity specialists. Dominant competitive moves center on backward integration into bisphenol-A epichlorohydrin feedstocks and long-term service contracts with guaranteed thermal performance degradation rates.
Within the premium-tier vector, Henkel and Dow occupy positions that exemplify divergent strategic anchors. Henkel represents the electronics-grade purity specialist archetype, leveraging adhesive chemistry heritage toward ionic contamination-controlled potting systems. Dow anchors the commodity-scale tier through upstream control over bisphenol-A epichlorohydrin feedstocks in US Gulf Coast manufacturing. Huntsman sits within the specialized curing system compounder category, with anhydride-based formulations serving high-voltage renewable energy applications. These three entities collectively illustrate how technical specialization, feedstock access, and curing chemistry expertise segment competitive positioning across specification tiers.
| Leading Market Players |
|---|
| Henkel |
| 3M |
| Dow |
| Huntsman |
| Momentive |
| BASF |
| ELANTAS |
| H.B. Fuller |
| Dymax |
| Others |
Pricing and Supply Chain Analysis
REACH halogen-free mandates gate qualified supply and premium-tier pricing access, as European electrical equipment OEMs now demand phosphorus-nitrogen flame retardant systems that only certified compounders can deliver. This regulatory filter concentrates pricing power among incumbents with UL 94 V-0 certification and ionic purity controls, while pushing uncertified competitors toward commoditized transformer grades.
Pricing Analysis
Bundled long-term service contracts with guaranteed thermal degradation rates now command 15-25% premiums over unbundled spot resin purchases. Three-tier pricing structure across premium semiconductor grades, mid-tier automotive thermal conductivity formulations, and economy transformer resins reflects ionic purity certification and filler loading intensity. Cost compression in industrial equipment grades intensifies because Chinese State Grid procurement standardizes 155°C thermal class specifications, squeezing compounder margins. Consumer electronics assemblers in Vietnam and India exhibit highest price sensitivity, whereas wind turbine OEMs accept premium pricing for 10-year performance guarantees.
Supply Chain Analysis
Formulation chemist scarcity in German and Japanese industrial clusters constrains new product development timelines for high-voltage anhydride-amine hybrid systems. Raw material supply draws from US Gulf Coast epichlorohydrin capacity controlled by Dow and Hexion, Chinese bisphenol-A derivatives manufacturing, and Frankfurt-Rhine-Main anhydride hardener production. Single-source vulnerability around chlorine supply disruptions threatens independent compounder feedstock security. Distribution runs through direct pipeline delivery to automotive and wind turbine OEMs, bypassing traditional distributor channels for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epoxy casting potting resin functions as a stable compounder market, with semiconductor protection and renewable energy buildout delivering steady specification-upgrade cycles that resist cyclical downturns.
For Market Incumbents: Anticipate silicone resin substitution in aerospace wire harness applications by accelerating qualification of halogen-free phosphorus-nitrogen systems for Boeing and Airbus specifications. Backward integration into bisphenol-A epichlorohydrin feedstocks defends margin position against Gulf Coast supply concentration risks. For New Entrants and Emerging Players: Capture India's PLI scheme-driven semiconductor packaging demand for low-alpha particle potting grades previously imported from China and Taiwan. Bio-based epoxy precursors from lignin-derived glycidyl ether align with China's SAMR carbon footprint disclosure requirements, creating a differentiated entry vector for domestic compounders. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier industrial equipment compounders lacking semiconductor-grade certification or long-term OEM service contracts. Five-to-ten year viability hinges on thermal conductivity formulation capabilities for silicon carbide power modules. Watch for UL 94 V-0 certification backlog resolution as inflection signal for new product launch velocity and specification capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epichlorohydrin Feedstocks | Dow and Hexion's Gulf Coast capacity anchors domestic compounder cost structures against chlorine supply volatility. |
| Long-term Service Contract Structuring | Vestas and Goldwind's 10-year agreements with thermal degradation guarantees transfer technical risk and lock out smaller suppliers. |
| Halogen-free Flame Retardant Reformulation | REACH Annex XIV authorization procedures for bisphenol-A derivatives accelerate phosphorus-nitrogen system adoption at ABB and Siemens. |
| High Thermal Conductivity Grade Qualification | Automotive inverter manufacturers in Germany and Japan specify 2.0-3.5 W/mK aluminum nitride filler systems for 800V silicon carbide platforms. |
| Bio-based Epoxy Precursor Development | SAMR carbon footprint disclosure requirements under China's dual carbon policy favor lignin-derived glycidyl ether alternatives. |
Research Methodology
Bottom-up semiconductor packaging and transformer encapsulation modeling reconciled against top-down epichlorohydrin feedstock and curing agent production tracking forms the analytical core. Primary interviews with epoxy formulation chemists, procurement leads at wind turbine OEMs, UL certification laboratory directors, and automotive inverter platform engineers combined with secondary validation through ECHA REACH substance registration databases, US EPA volatile organic compound emission filings, and China SAMR hazardous substance disclosure records. Triangulation across these sources calibrated segment-level volume estimates.
Input-output matrices mapped resin consumption to installed power electronics capacity, wind turbine buildout pipelines, and semiconductor packaging cleanroom throughput across the projection horizon. Segmentation dimensions modeled include thermal conductivity tier, flame retardant chemistry type, ionic purity grade, end-use industry, and regional manufacturing hub. CAGRs derived from regression analysis against historical specification upgrade cycles and regulatory mandate implementation timelines. Forecast inputs incorporated silicon carbide power module adoption curves and REACH authorization procedure schedules.
Underlying measurement precision varies by segment; semiconductor protection grades with sub-ppm ionic purity thresholds carry tighter precision than commodity transformer formulations. Forecasts reflect assumptions on wide-bandgap semiconductor penetration rates, halogen-free certification backlog resolution, and anhydride curing agent technical workforce availability. Material deviation in chlorine supply security or ECHA bisphenol-A restriction timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.