
 Polyisobutylene (PIB) Market | 2026-2036
Polyisobutylene (PIB) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyisobutylene (PIB) Market Analytics
Aftermarket lubricant reformulation revenue is tilting toward high-molecular-weight grades that command premium positioning in extended-drain applications. BASF SE leverages its Ludwigshafen integrated base to sustain captive isobutylene feedstock economics. INEOS anchors European supply through its Antwerp polymerization assets, while TPC Group dominates North American butene-derived PIB output from its Houston corridor.
Polyisobutylene is a synthetic elastomer produced via cationic polymerization of isobutylene, yielding viscous liquids or rubbery solids with molecular weights spanning two to four orders of magnitude and near-zero gas permeability. Its primary industrial purpose centers on imparting tack, flexibility, and chemical stability across fuel additives, sealants, and roofing membranes. High-molecular-weight grades capture the dominant margin pool in medical stoppers and primary pharmaceutical closures, whereas low-molecular-weight variants penetrate fastest into lubricant dispersant and viscosity-index-improver formulations. Medium-molecular-weight material occupies a mature position in butyl rubber compounding for tire inner liners.
EPA fuel additive registration requirements under 40 CFR Part 79 constrain market entry for new PIB-derived detergent formulations in the United States. REACH registration obligations and the EU Green Deal's decarbonization benchmarks for chemical manufacturing reshape European producer investment timelines. Stakeholders must monitor bio-based isobutylene pilot projects and their compatibility with existing cationic polymerization infrastructure.
Market Dynamics
The Polyisobutylene market is restructuring around sulfur-content regulations in marine fuels and the phasing of automotive emission standards, which are compressing reformulation cycles and elevating specification premiums for high-purity grades.
Growth Catalysts
- IMO 2020 Sulfur Caps:The International Maritime Organization's 0.5% sulfur limit on bunker fuels is forcing fleet operators to adopt fuel additives that stabilize low-sulfur distillates and prevent injector deposits.
- Extended-Drain Lubricants:Commercial vehicle fleets in Germany and the United States are specifying longer service intervals, which concentrates demand for high-molecular-weight PIB viscosity modifiers.
- Butyl Rubber Compounding:Tire manufacturers are expanding inner-liner capacity to accommodate air-retention specifications for electric vehicles, which run higher axle loads and require more robust inflation pressure maintenance.
Market Restraints
- Isobutylene Feedstock Volatility:Cracker operating rates and refinery utilization swings in the United States Gulf Coast directly compress PIB producer margins during ethylene cycle downturns.
- REACH Registration Burden:The European Chemicals Agency's substance evaluation timelines and data requirements for polymer registration are extending market entry barriers for new formulation suppliers.
- Silicone Sealant Substitution:Construction and automotive glazing applications are migrating toward room-temperature-vulcanizing silicones where temperature resistance exceeds PIB performance envelopes.
Strategic Opportunities
- Bio-Based Isobutylene Pilots:Fermentation-derived isobutylene from agricultural waste streams offers a pathway to reduce Scope 3 emissions for European producers under the EU Green Deal carbon benchmarks.
- Medical Closure Migration:Pharmaceutical packaging regulations in the United States and Germany are tightening extractables testing, which advantages halobutyl-PIB laminates in serum vial and syringe plunger applications.
- Aviation Fuel Additive Certification:The ASTM D1655 jet fuel specification revision process is creating entry points for PIB-based detergents that address thermal stability in hydrotreated renewable blendstocks.
Industry Challenges
- Cationic Polymerization Expertise Scarcity:The specialized reaction engineering and catalyst handling knowledge required for controlled molecular-weight distribution is concentrating among a narrow technical workforce in Ludwigshafen and Antwerp production clusters.
- EPA 40 CFR Part 79 Registration Timelines:Fuel additive manufacturers face multi-year toxicology and emissions testing protocols before commercializing new PIB-derived detergent packages in the United States market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyisobutylene (PIB) Market |
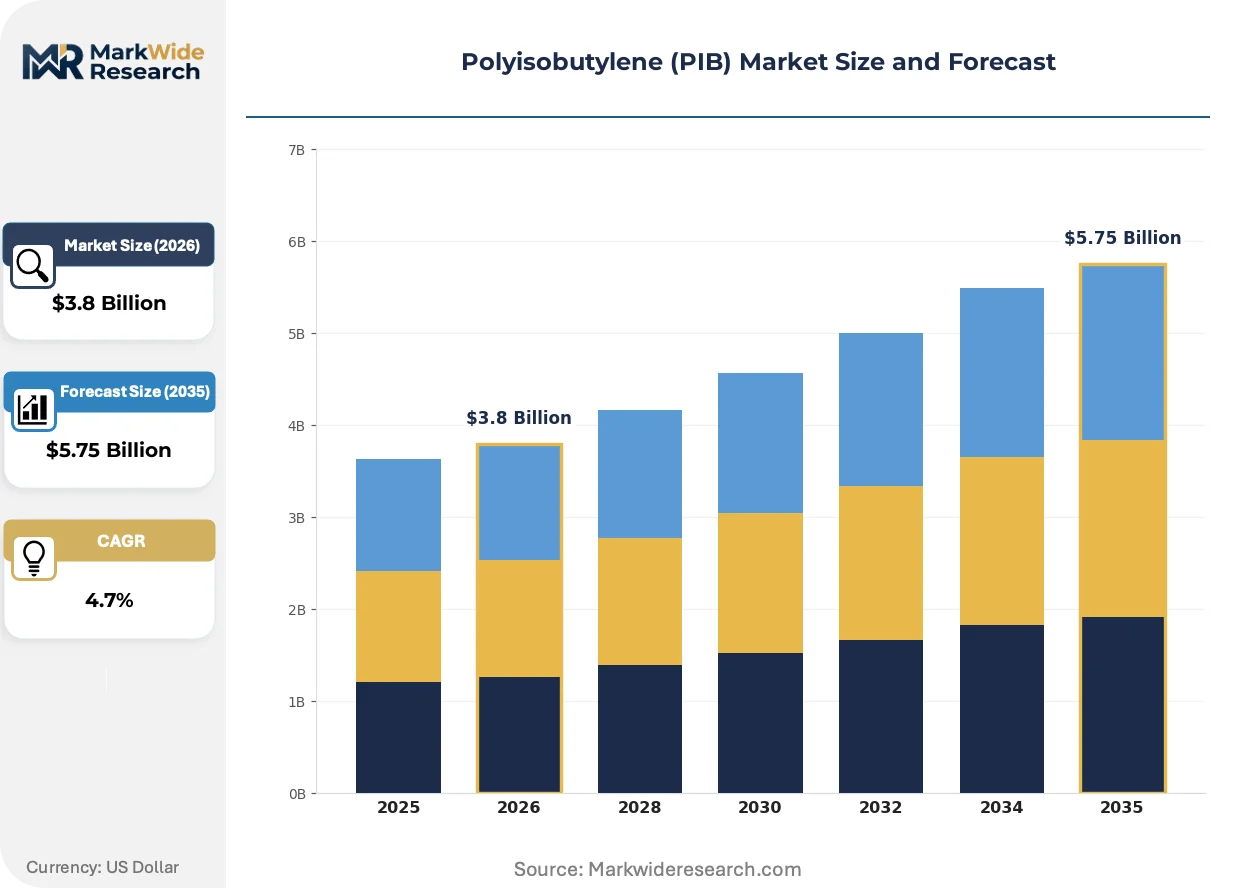
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Performance, Low-Molecular-Weight, Medium-Molecular-Weight, High-Molecular-Weight End Use Industry: Automotive, Adhesives, Coatings, Sealants Formulation Type: Rubber, Plastics, Lubricants, Additives Application: Fuel Additives, Waterproofing, Insulation, Medical |
| Companies Covered | Lubrizol Corporation, Daelim Co., Ltd., BASF SE, Chevron Oronite Company LLC, Braskem, TPC Group, ExxonMobil Corporation, Dowpol Corporation, INEOS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyisobutylene (PIB) Market Evolving Landscape
Reactor design advances and catalysis improvements are compressing the capital-intensity gap between batch and continuous PIB production, while regulatory pressure on fuel cleanliness is accelerating specification fragmentation across end-use segments.
Metallocene-based cationic polymerization catalysts are enabling tighter molecular-weight distribution control in high-molecular-weight PIB production. Medical device manufacturers in Germany and Switzerland are qualifying these grades for pharmaceutical closures ahead of revised USP Class VI testing protocols. Conventional Ziegler-Natta batch processes are rendering obsolete for premium sealant applications where polydispersity indices below two are now mandatory.
The EU Green Deal's decarbonization benchmarks for chemical manufacturing are imposing carbon-border-adjustment exposure on imported PIB derivatives. European producers are responding with integrated energy optimization at steam-cracker adjoined polymerization units. Medium-molecular-weight grades destined for butyl rubber compounding face the most acute cost pressure from renewable power purchase obligations.
Fleet procurement departments are consolidating lubricant supplier relationships around full-service fluid management contracts that bundle extended-drain synthetics with used-oil analytics. Independent distributors in the United States are losing share to direct mill relationships as national trucking chains centralize specification authority at headquarters level. This concentration is most visible in the Class 8 long-haul segment where total cost of ownership modeling dominates vendor selection.
Polyisobutylene (PIB) Market Segmentation
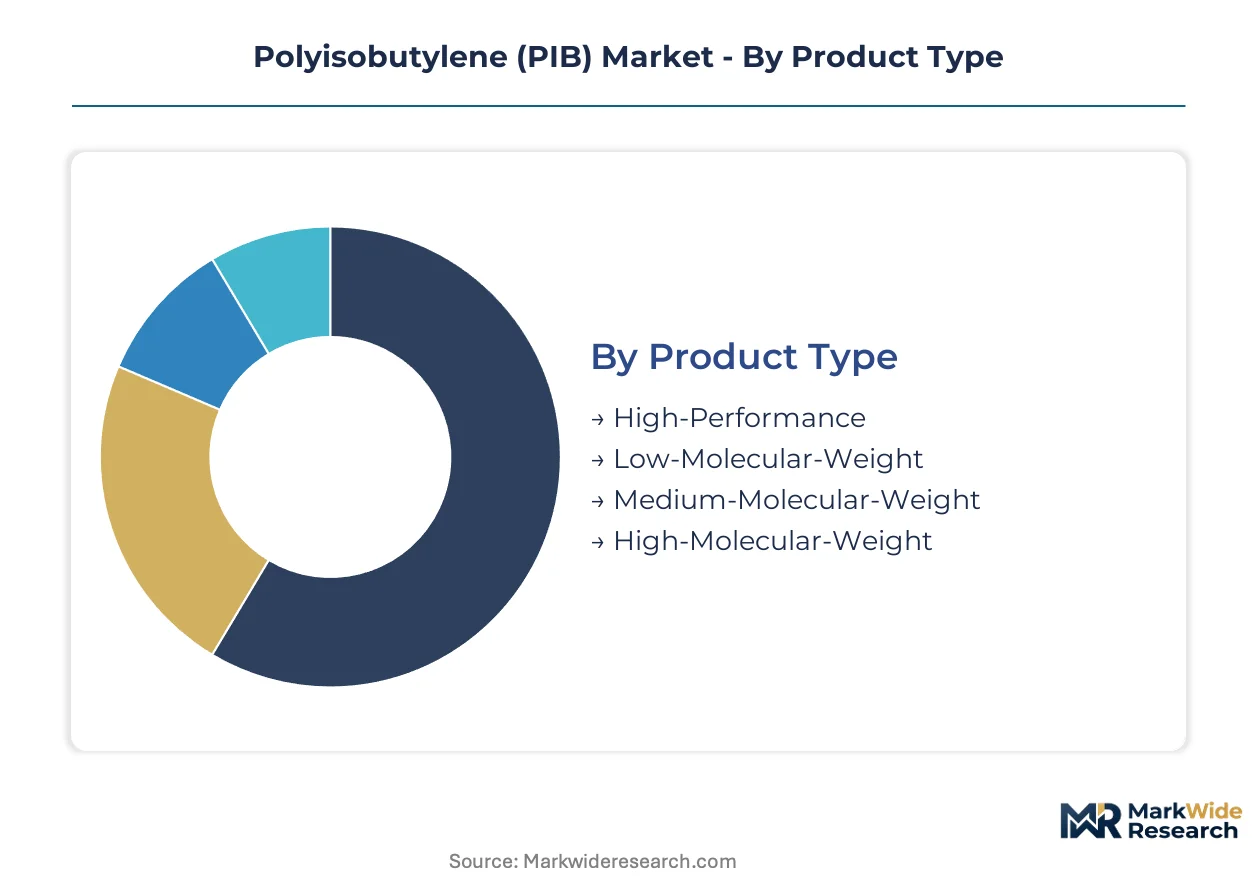
Molecular weight distribution determines margin capture in polyisobutylene, with viscosity-index improvers and pharmaceutical closures pulling from opposite ends of the specification spectrum. End-use fragmentation across fuel additives, butyl rubber compounding, and medical packaging forces producers to maintain parallel reactor trains with distinct catalyst systems.
Product Type:
Cost tier stratification in PIB production separates commodity lubricant feedstocks from premium pharmaceutical grades commanding formulation premiums.
- High-Performance:Ultra-low polydispersity grades synthesized via metallocene catalysis achieve molecular-weight distributions below 1.5. Medical device manufacturers in Germany and Switzerland are qualifying these materials for serum vial stoppers ahead of revised USP Class VI protocols.
- High-Molecular-Weight:Viscous elastomers with molecular weights exceeding 500,000 g/mol dominate butyl rubber inner-liner compounding. Tire producers serving electric vehicle platforms specify these grades for air-retention layers handling elevated axle loads.
- Medium-Molecular-Weight:Standard butyl rubber compounding feedstock with balanced processability.
- Low-Molecular-Weight:Liquid polymers penetrating lubricant dispersant formulations for extended-drain intervals.
High-Molecular-Weight holds installed capacity. High-Performance is rotating up the share rankings.
End Use Industry:
Application pull varies sharply by performance requirement, with fuel cleanliness regulations and electric vehicle tire specifications driving divergent specification intensity.
- Automotive:Lubricant formulators specify PIB viscosity modifiers for Class 8 long-haul fleets centralizing procurement around total-cost-of-ownership contracts. Extended-drain synthetics concentrate demand in Germany and the United States where fleet consolidation accelerates.
- Adhesives:Pressure-sensitive tape manufacturers exploit PIB's tack and oxidative stability for outdoor construction applications. Formulation shifts toward solvent-free systems are compressing polydispersity tolerances.
- Coatings:Protective membrane applications for roofing and waterproofing.
- Sealants:Primary glazing and construction joint applications facing silicone substitution in high-temperature environments.
Automotive commands the dominant volume position. Adhesives is climbing the fastest on specification upgrades.
Formulation Type:
Customer type differentiation separates integrated rubber producers from independent lubricant blenders with divergent supply security requirements.
- Additives:Fuel detergent packages for marine and aviation sectors carry the steepest regulatory burden. EPA 40 CFR Part 79 registration timelines and ASTM D1655 jet fuel certification create multi-year barriers that concentrate supply among established registrants.
- Lubricants:Viscosity-index improvers and dispersant backbones for commercial vehicle synthetics. Fleet procurement consolidation favors direct mill relationships over independent distributors.
- Rubber:Butyl rubber compounding for tire inner liners.
- Plastics:Modifier applications in packaging and film.
Additives holds the regulatory moat. Lubricants is rotating up the share rankings.
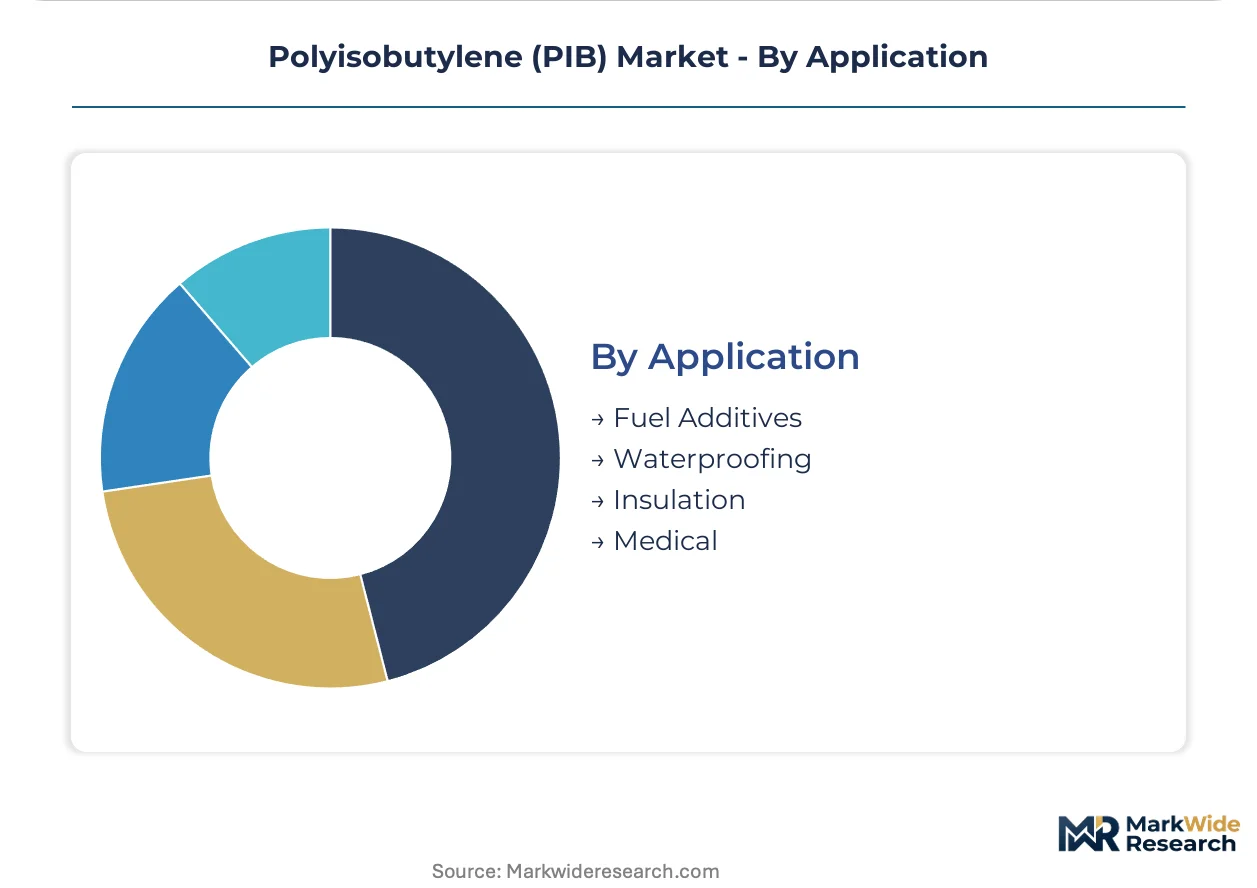
Application:
Volume concentration in mature construction end-uses contrasts with emerging medical and aviation specifications carrying premium positioning.
- Fuel Additives:Marine bunker fuel stabilizers and aviation thermal stability improvers. IMO 2020 sulfur caps and evolving ASTM hydrotreated renewable blendstock specifications are fragmenting demand across low-sulfur distillate compatibility tiers.
- Medical:Pharmaceutical closures and syringe plunger laminates. Extractables testing tightening in the United States and Germany advantages halobutyl-PIB coformulations with demonstrated inertness profiles.
- Waterproofing:Roofing membrane and construction sealant applications.
- Insulation:Electrical and thermal barrier applications.
Fuel Additives holds installed capacity. Medical is expanding most quickly on regulatory tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States absorb specification premiums with minimal elasticity, while price sensitivity concentrates in Asian markets where commodity-grade sourcing dominates procurement decisions.
Germany
Extended-drain lubricant specifications from Class 8 fleet operators drive demand for high-molecular-weight viscosity modifiers. The EU Green Deal's carbon-border-adjustment mechanism pressures importers while rewarding integrated Ludwigshafen production complexes. BASF SE anchors supply through captive isobutylene feedstock from adjoining steam cracker operations.
United States
Commercial vehicle fleet consolidation around total-cost-of-ownership contracts concentrates procurement authority at headquarters level. EPA 40 CFR Part 79 fuel additive registration creates multi-year barriers that protect established registrants. TPC Group dominates butene-derived output from Houston corridor assets serving marine and aviation detergent formulators.
China
Tire inner-liner capacity expansion for electric vehicle platforms pulls medium-molecular-weight grades into rubber compounding applications. The country's national chemical regulator enforces GB standards for fuel additive quality that parallel ASTM specifications. Yangtze River Delta polymerization assets serve domestic lubricant blenders facing import substitution mandates.
Japan
Pharmaceutical closure manufacturers qualify ultra-low-polydispersity grades ahead of revised USP Class VI testing protocols. METI guidelines on medical device extractables tighten faster than European or American benchmarks. Kanto region specialty chemical producers supply halobutyl-PIB laminates to serum vial and syringe plunger markets.
South Korea
Pressure-sensitive adhesive formulators exploit PIB tack properties for outdoor construction tape applications. The national industrial standards body enforces solvent-free system specifications that compress polydispersity tolerances. Daegu-Gyeongbuk chemical clusters serve domestic electronics and automotive component manufacturers with medium-molecular-weight feedstocks.
Polyisobutylene (PIB) Market Competitive Landscape
Capability concentration sits with integrated petrochemical majors possessing captive isobutylene supply; scale advantage sits with independent polymer specialists operating merchant feedstock positions. The market structures around three tiers: cracker-adjoined producers with backward integration, standalone polymerization specialists with catalyst expertise, and regional distributors serving formulation customers. Dominant competitive moves include capacity rationalization at legacy assets and technology licensing agreements for metallocene catalysis systems.
Within the integrated petrochemical tier, BASF SE and INEOS occupy positions defined by Ludwigshafen and Antwerp production cluster adjacency to steam cracker complexes. TPC Group exemplifies the North American specialist archetype through Houston corridor butene-derived output. Among lubricant additive formulators, Lubrizol Corporation and Chevron Oronite Company LLC represent the downstream integration pattern that internalizes PIB derivative consumption within fuel detergent and viscosity modifier portfolios.
| Leading Market Players |
|---|
| Lubrizol Corporation |
| Daelim Co., Ltd. |
| BASF SE |
| Chevron Oronite Company LLC |
| Braskem |
| TPC Group |
| ExxonMobil Corporation |
| Dowpol Corporation |
| INEOS |
| Others |
Value Network & Pricing Analysis
Ludwigshafen and Antwerp production clusters anchor isobutylene supply for European PIB manufacturers, concentrating margin capture in high-molecular-weight grades where extended-drain lubricant formulators absorb specification premiums with minimal price elasticity.
Pricing Analysis
Aftermarket service contracts and fluid management bundles now drive lifetime value for lubricant additive suppliers. Three-tier pricing structure across premium metallocene-catalyzed, standard Ziegler-Natta, and economy solvent-based grades separates pharmaceutical closures from construction sealants. Cost compression in medium-molecular-weight butyl rubber feedstocks is intensifying because electric vehicle tire capacity expansion outpaces specialty grade differentiation. Fleet procurement departments in Germany exhibit the lowest price sensitivity, while Asian construction distributors negotiate commodity spot positions aggressively.
Supply Chain Analysis
Extended payment terms from integrated petrochemical majors to merchant isobutylene buyers are compressing working capital for standalone polymerization specialists. Supply concentrates in Germany, the United States, and China, with cracker-adjoined assets in Ludwigshafen and Houston drawing from captive ethylene co-product streams. Feedstock hinges on refinery utilization cycles and steam cracker operating rates. Single-source vulnerability concentrates in metallocene catalyst supply, where patent-protected systems tether production to licensed technology providers. Distribution runs through direct mill relationships with national fleet operators and regional distributors serving independent lubricant blenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended-drain lubricant service contracts and used-oil analytics bundles are expanding faster than base chemical sales, reframing PIB as a recurring-revenue platform rather than commodity feedstock.
For Market Incumbents: Pre-empt silicone sealant substitution in high-temperature construction applications by accelerating halobutyl-PIB laminate certification for pharmaceutical closures. Backward integration into bio-based isobutylene pilot production secures EU Green Deal compliance before carbon-border-adjustment mechanisms harden. Capacity rationalization at legacy batch assets in favor of continuous metallocene trains protects margin pools in medical-grade segments. For New Entrants and Emerging Players: Build out fermentation-derived isobutylene supply partnerships with agricultural waste processors to serve European producers facing Scope 3 emission benchmarks. Aviation fuel additive certification under ASTM D1655 specifications offers the most penetrable entry point, as EPA 40 CFR Part 79 timelines have concentrated incumbent registrants in marine and automotive detergents. A go-to-market angle targeting hydrotreated renewable blendstock compatibility differentiates against legacy PIB formulations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed standalone polymerization specialists lacking cracker adjacency. The five-to-ten-year viability window favors targets with metallocene licensing agreements and established REACH registrations. Watch bio-based isobutylene pilot project yields as the inflection indicator for European producer cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstock | Fermentation-derived isobutylene from agricultural waste reduces EU Green Deal carbon exposure for Antwerp and Ludwigshafen complexes. |
| Metallocene Catalyst Licensing Agreement | Ultra-low polydispersity production capability unlocks pharmaceutical closure margins ahead of revised USP Class VI protocols. |
| Long-Term Supply Agreement with Fleet Operators | Direct mill relationships with Class 8 long-haul chains consolidate procurement authority away from independent distributors. |
| Capacity Expansion in High-Molecular-Weight Grades | Electric vehicle tire inner-liner demand pulls viscous elastomers for air-retention layers handling elevated axle loads. |
| Joint Venture for Aviation Fuel Additive Certification | ASTM D1655 jet fuel specification revision creates entry points for thermal stability improvers in hydrotreated renewable blendstocks. |
Research Methodology
Cross-validation between primary interviews with lubricant formulators, tire compounders, and pharmaceutical packaging engineers and secondary sources including customs data, SEC filings from integrated petrochemical majors, and ECHA registration databases anchors the qualitative findings. Plant managers at cracker-adjoined complexes, procurement leads at commercial vehicle fleet operators, and technical R&D directors at adhesive formulators provided operational perspective. Bottom-up capacity modeling and top-down demand segmentation by molecular weight tier and end-use application were reconciled to establish volume baselines.
Calibration against historical price spreads between high-performance and commodity grades, cracker margin cycles, and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include molecular weight tier, end-use industry, formulation type, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization assumptions. Forecast inputs incorporated REACH evaluation timelines and EPA registration completion rates for fuel additive categories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by merchant feedstock-dependent specialists or breakthrough yields in bio-based isobutylene pilots would shift outcomes. Macroeconomic downturns in commercial vehicle procurement, accelerated silicone substitution in construction sealants, or regulatory deviation in marine sulfur enforcement would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Co-Polymer Resin Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
Global Polymer Chameleons Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Ionomer Resins Market
Polymers & Resins
Global Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Asia-Pacific Super Absorbent Polymers (SAP) Market
Polymers & Resins
Middle East Polymer Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Hair Styling Biopolymers Market
Polymers & Resins
Polyisobutene Market