
 Polyolefin Wax Market | 2026-2036
Polyolefin Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Polyolefin Wax Market Analytics
China is reshaping polyolefin wax supply dynamics through large-scale ethylene-alpha olefin capacity additions along its eastern seaboard. Mitsui Chemicals leverages integrated cracker-to-wax operations to sustain cost leadership in high-density polyethylene wax grades. BASF SE anchors European supply through specialized metallocene catalyst systems that differentiate output for premium coatings applications. Sasol Limited competes from Fischer-Tropsch integration, while Clariant specializes in micronized powder forms for personal care end users.
Polyolefin wax comprises low molecular weight polyethylene and polypropylene homopolymers or copolymers, typically manufactured via high-pressure polymerization, Ziegler-Natta catalysis, or thermal degradation of higher molecular weight resins, with melt viscosities ranging from 50 to 10,000 mPa·s and congealing points between 80°C and 140°C. These materials function primarily as processing aids, lubricants, and surface modifiers in plastics extrusion, ink formulations, and polishes. High density polyethylene wax occupies the largest volume share across coatings and adhesives applications where hardness and abrasion resistance command premium positioning. Polypropylene wax represents the fastest-expanding category, driven by automotive interior compounds requiring high heat deflection and compatibility with polyolefin substrates. Metallocene wax captures concentrated margin pools in personal care and food packaging segments where narrow polydispersity enables regulatory-compliant, low-extractable formulations.
EPA regulations in the United States restrict volatile organic compound content in architectural coatings, directly elevating demand for low-emission polyolefin wax additives that reduce solvent dependence. REACH registration requirements and ECHA substance evaluation in the European Union enforce comprehensive toxicological dossiers, favoring established suppliers with compliance infrastructure over import-dependent traders. China's MEE enforcement of dual carbon goals pressures domestic producers toward lower-energy thermal cracking routes. Stakeholders must monitor catalyst technology licensing costs and regional carbon border adjustment mechanisms as these will determine which production configurations retain cost advantage through the forecast horizon.
Market Dynamics
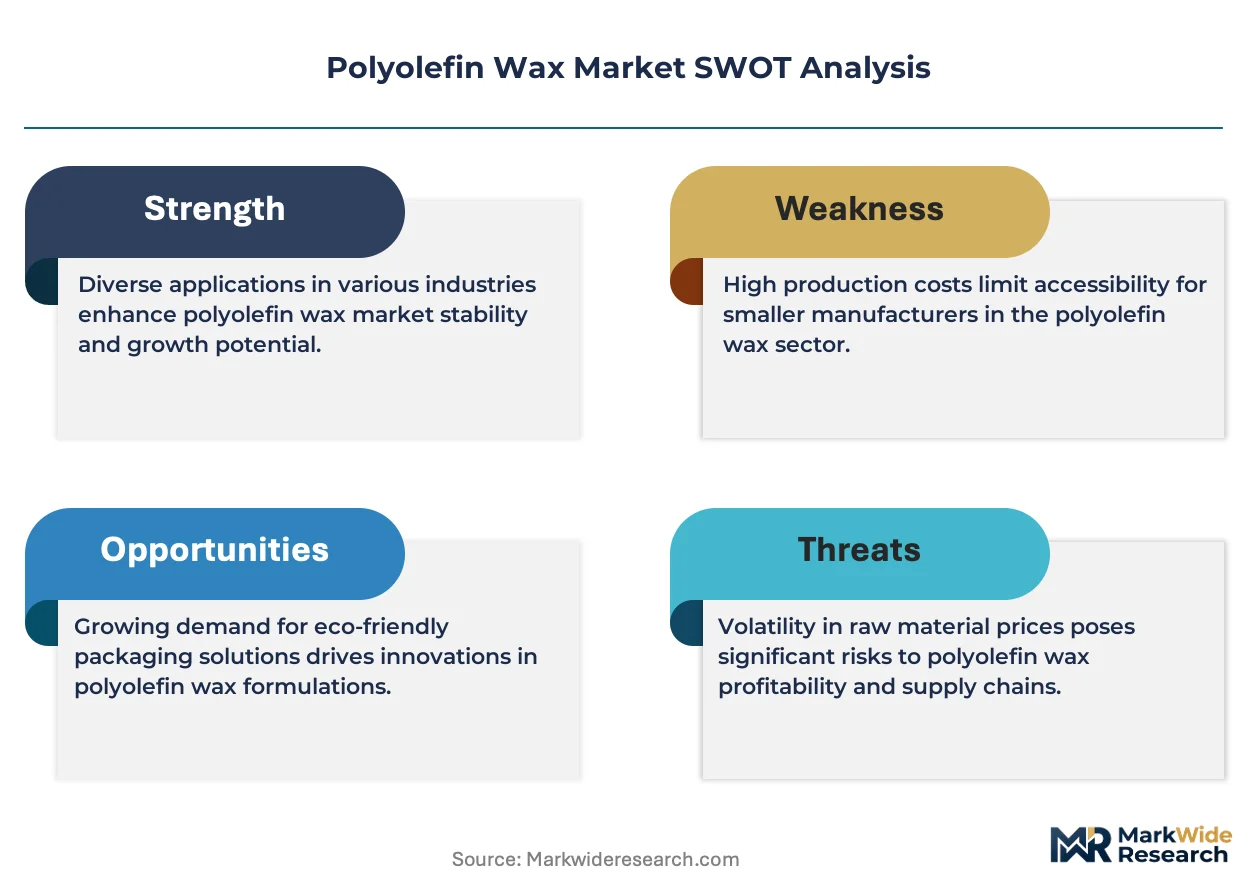
Metallocene catalyst technology is compressing polydispersity ranges and enabling food-contact compliant grades that command premium positioning over conventional Ziegler-Natta output.
Growth Catalysts
- EPA VOC restrictions:Architectural coatings manufacturers in the United States substitute solvent-heavy formulations with low-emission polyolefin wax additives to meet emission ceilings.
- Automotive interior compounds:Polypropylene wax demand accelerates as OEMs specify higher heat deflection temperatures for dashboard and trim applications.
- East China petrochemical clustering:Downstream plastics compounding operations concentrate procurement within 200 kilometers of Shanghai and Ningbo crackers.
Market Restraints
- Ethylene feedstock volatility:Naphtha-to-ethylene spreads compress margins for non-integrated wax producers lacking captive cracker supply.
- Fischer-Tropsch wax substitution:Sasol's integrated synthetic output competes on price in coatings applications where odor and color specifications permit.
- REACH registration burden:ECHA substance evaluation timelines extend 18-24 months, blocking traders without toxicological dossier capabilities from EU market entry.
Strategic Opportunities
- Personal care micronization:Clariant's powder form expertise indicates white space for cosmetic-grade waxes with particle sizes below 50 microns.
- Dual carbon compliance in China:MEE enforcement rewards producers adopting lower-energy thermal cracking routes with preferential permitting.
- Food packaging certification:Narrow polydispersity metallocene grades capture margin pools as GB standards tighten extractable limits for direct contact.
Industry Challenges
- Metallocene licensing complexity:Patent thickets around single-site catalyst systems force producers into royalty-bearing agreements or in-house R&D commitments exceeding $50 million.
- Carbon border adjustment readiness:EU CBAM implementation requires embedded emissions documentation that thermal crackers in Shandong and Jiangsu provinces currently cannot provide.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyolefin Wax Market |
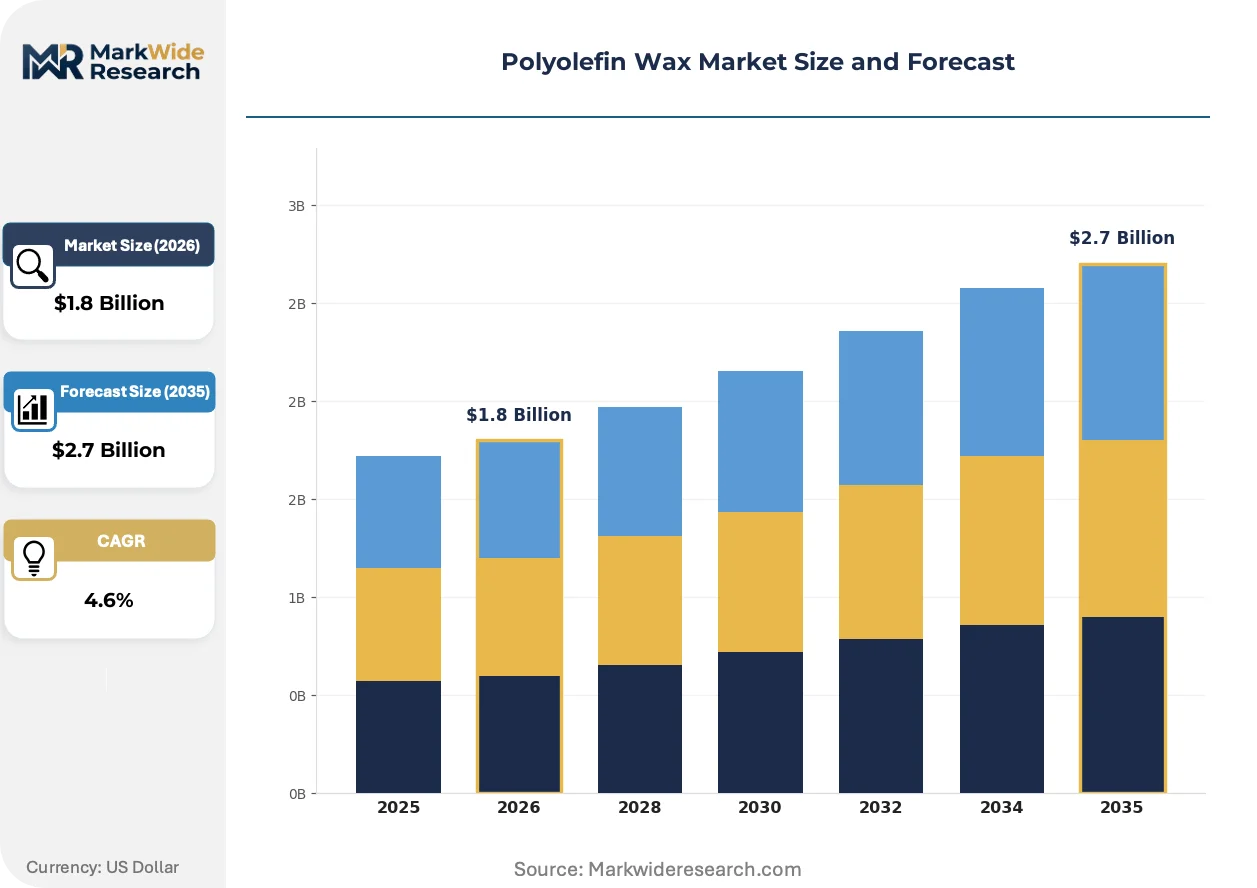
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Density Polyethylene Wax, High Density Polyethylene Wax, Polypropylene Wax, Metallocene Wax Application: Coatings, Adhesives, Plastics, Cosmetics Form: Powder, Granule, Liquid, Pellets End User: Automotive, Construction, Food Packaging, Personal Care |
| Companies Covered | Mitsui Chemicals, Inc., DEUREX, BASF SE, Innospec Inc., Trecora Resources, Clariant, Westlake Chemical Corporation, Sasol Limited, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyolefin Wax Market Evolving Landscape
Catalyst architecture, regulatory compliance automation, and procurement centralization are reconfiguring how value flows through polyolefin wax supply chains.
Process analytical technology is digitizing quality control workflows in metallocene wax production. Coatings manufacturers deploy inline rheometry and molecular weight monitoring to certify batch-to-batch consistency without offline laboratory delays. This compression of quality assurance cycles is digitizing supplier-customer data exchange and reducing specification dispute resolution from weeks to hours.
REACH registration requirements now mandate updated toxicological dossiers for substances above 100 tons annually, forcing established European suppliers to maintain dedicated regulatory affairs teams. The burden falls heaviest on import-dependent traders lacking compliance infrastructure. German coatings formulators increasingly specify pre-registered wax grades to avoid supply interruption during ECHA evaluation windows.
Centralized procurement desks at multinational adhesives manufacturers now consolidate annual wax volumes across regional subsidiaries. This buyer concentration compresses supplier lists to three-to-five approved vendors per geography. The shift is most visible in the United States, where Sherwin-Williams and RPM International negotiate master supply agreements covering North American and select Asian operations.
Polyolefin Wax Market Segmentation
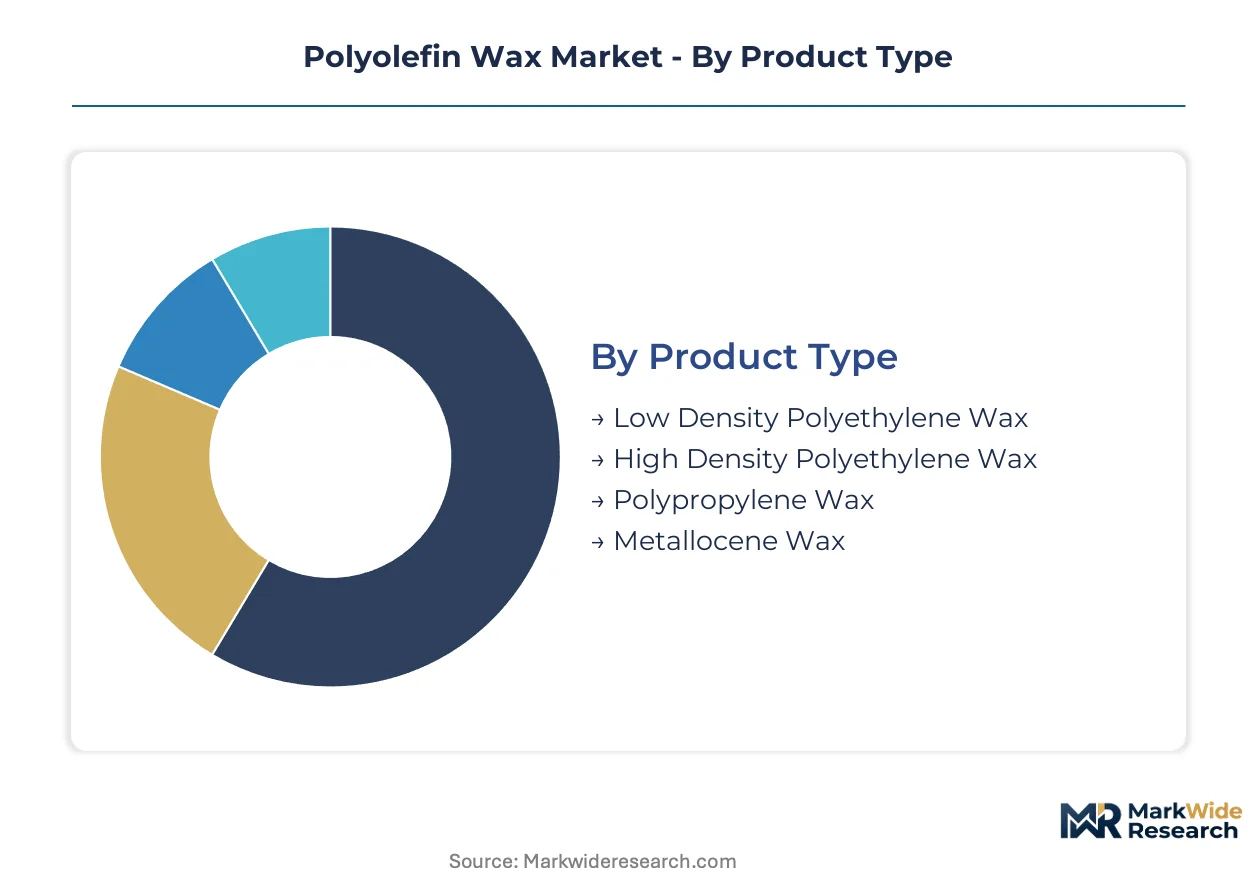
Polyolefin wax segmentation reflects divergent technical requirements across coatings, adhesives, and food-contact applications. Each dimension—product chemistry, physical form, and end-use certification—creates distinct margin tiers and supplier qualification barriers.
Product Type:
Mature commodity grades dominate volume, while metallocene-catalyzed variants command premium positioning through regulatory compliance.
- Low Density Polyethylene Wax:Branched polymer structure yields lower crystallinity and softer hand feel. Demand concentrates in flexible packaging adhesives where compatibility with EVA hot-melts drives formulation selection.
- High Density Polyethylene Wax:Linear chains with high crystallinity deliver hardness and abrasion resistance. Coatings manufacturers in Germany and the United States specify these grades for wood furniture finishes requiring scratch protection.
- Polypropylene Wax:Higher melting points suit automotive interior compounds needing heat deflection above 110°C. Compatibility with polypropylene substrates reduces phase separation in dashboard formulations.
- Metallocene Wax:Narrow polydispersity from single-site catalysis enables FDA and GB standard compliance for direct food contact. Licensing costs from catalyst patent holders compress margins for non-integrated producers.
High density polyethylene wax handles the majority of throughput; metallocene wax is gaining share fastest on regulatory compliance premiums.
Application:
Application segmentation tracks divergent performance specifications across industrial and consumer end uses.
- Coatings:Architectural and industrial formulations employ polyolefin wax for matting, slip, and scratch resistance. EPA VOC restrictions in the United States accelerate substitution of solvent-borne systems with waterborne wax dispersions.
- Adhesives:Hot-melt and pressure-sensitive applications leverage wax for viscosity control and open-time modulation. East China petrochemical clusters supply downstream tape and label manufacturers within 200 kilometers of Ningbo crackers.
- Plastics:Processing aids in extrusion and injection molding reduce torque and improve surface finish. Polypropylene wax demand climbs with automotive lightweighting initiatives requiring higher heat performance.
- Cosmetics:Micronized powder forms below 50 microns serve as rheology modifiers and emulsion stabilizers. Clariant's specialized production infrastructure indicates concentrated supplier control in this niche.
Coatings absorbs the largest volume allocation; cosmetics exhibits the steepest expansion trajectory on personal care formulation premiums.
Form:
Physical form selection determines handling economics and dispersion efficiency in customer processes.
- Powder:Fine particle sizes suit dry-blend compounding and cosmetic formulations. Dust exposure controls add capital burden for producers serving personal care and food packaging segments.
- Granule:Intermediate particle size balances flowability with melt dispersion speed. Standard form for bulk plastics compounding operations in China and the United States.
- Liquid:Aqueous or solvent dispersions enable direct incorporation into waterborne coatings and inks. Higher logistics costs limit geographic radius from production points.
- Pellets:Dust-free handling preferred for automated feeding systems in high-volume extrusion. Automotive tier suppliers specify pellet form to minimize contamination in cleanroom compounding environments.
Pellets and granule forms together dominate shipment volumes; powder commands the highest unit margins on micronization processing.
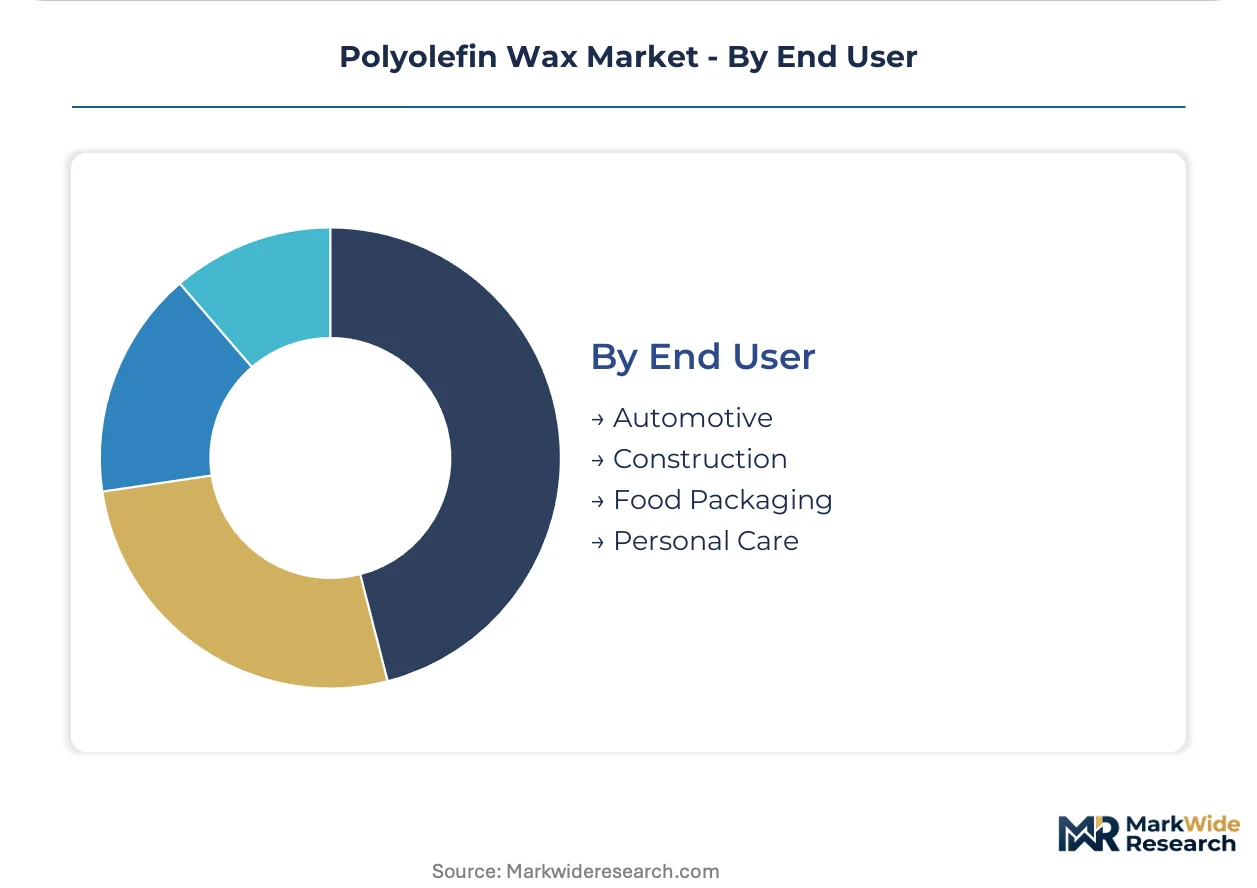
End User:
End-user segmentation separates regulated food-contact and personal care applications from industrial commodity demand.
- Automotive:Interior trim and underhood applications specify polypropylene wax for heat resistance and low VOC emissions. OEM qualification timelines extend 18-24 months, locking in approved supplier lists.
- Construction:Sealants, caulks, and flooring adhesives consume high-density polyethylene wax for durability. Cyclical residential construction activity in the United States creates demand volatility.
- Food Packaging:Direct contact applications require extractable limits compliance under FDA and evolving GB standards. Metallocene grades with narrow polydispersity capture margin pools as certification barriers rise.
- Personal Care:Emulsions, creams, and color cosmetics employ micronized wax for texture and stability. REACH registration dossiers and toxicological data requirements favor established European suppliers over import-dependent traders.
Construction and automotive together represent the largest demand block; food packaging climbs fastest on regulatory tightening and safety certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated crackers in East China, the US Gulf Coast, and Germany's Rhine-Ruhr corridor supply the majority of merchant wax volumes. Regulatory divergence across these zones fragments compliance requirements and shapes procurement patterns.
China
Petrochemical clusters along the Yangtze River Delta and Ningbo-Zhoushan port complex feed downstream plastics compounding operations. MEE enforcement of dual carbon goals pressures thermal cracking producers toward lower-energy process configurations. Shanghai-based formulators consolidate procurement within 200 kilometers of ethylene crackers to minimize logistics exposure.
United States
EPA VOC restrictions in architectural coatings elevate demand for low-emission polyolefin wax additives that reduce solvent dependence. Gulf Coast ethylene production from shale gas feedstock sustains cost-competitive HDPE wax output. Texas and Louisiana host the bulk of domestic compounding capacity serving construction sealant manufacturers.
Germany
REACH registration requirements and ECHA substance evaluation enforce comprehensive toxicological dossiers for wax imports. Coatings manufacturers in North Rhine-Westphalia increasingly specify pre-registered grades to avoid supply interruption during evaluation windows. BASF SE anchors European supply through specialized metallocene catalyst systems.
South Africa
Fischer-Tropsch integration at Sasol's Secunda complex yields synthetic wax output competing on price in coatings applications. The country's central petrochemical regulator maintains odor and color specifications that permit substitution into less demanding formulation tiers. Durban-Johannesburg logistics corridors distribute output into sub-Saharan adhesives markets.
Japan
METI industrial standards govern polyolefin wax purity specifications for automotive interior compounds. Osaka-based automotive tier suppliers specify polypropylene wax grades requiring heat deflection above 110°C. Chubu region chemical producers maintain qualification relationships with domestic OEMs through 18-24 month approval cycles.
Polyolefin Wax Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in catalyst technology and micronized powder forms. The vendor base separates into three strategic archetypes: integrated petrochemical majors with captive ethylene supply, specialized wax producers licensing metallocene technology, and micronization specialists serving personal care niches. Competitive moves concentrate on catalyst technology licensing agreements and backward integration into cracker assets to secure feedstock margin.
Among integrated petrochemical majors, Mitsui Chemicals and Sasol Limited exemplify divergent feedstock strategies—ethylene-alpha olefin integration versus Fischer-Tropsch synthesis. BASF SE occupies a position within the European premium tier, leveraging specialized catalyst systems. Clariant represents the micronization specialist archetype, with powder form expertise indicating concentrated supplier control in cosmetic-grade segments below 50 microns.
| Leading Market Players |
|---|
| Mitsui Chemicals, Inc. |
| DEUREX |
| BASF SE |
| Innospec Inc. |
| Trecora Resources |
| Clariant |
| Westlake Chemical Corporation |
| Sasol Limited |
| Honeywell International Inc. |
| Others |
Value Network & Pricing Analysis
East China petrochemical clusters around Shanghai and Ningbo concentrate ethylene-alpha olefin capacity that feeds downstream wax production, creating regional pricing power for integrated producers while exposing non-integrated traders to feedstock volatility. This geographic concentration compresses margins for importers lacking captive cracker supply and rewards backward integration into ethylene production.
Pricing Analysis
REACH registration requirements and ECHA substance evaluation timelines dictate the pricing tier structure across European markets, forcing three-tier pricing separation between pre-registered premium grades, standard commodity tiers, and unregistered economy imports facing evaluation delays. Price differentiation centers on certification grade and toxicological dossier completeness, with FDA and GB standard compliance commanding substantial premiums in food-contact applications. Cost compression in thermal cracking routes is intensifying as MEE enforcement of dual carbon goals raises energy input costs for Shandong and Jiangsu producers. Volume-scaled automotive tier suppliers exhibit lowest price sensitivity due to 18-24 month qualification lock-ins, while import-dependent coatings formulators face highest exposure to spot price swings.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become critical working capital tools for distributors serving adhesives manufacturers in East China and construction sealant producers along the US Gulf Coast. Raw material flows draw from ethylene crackers in China, shale gas derivatives in the United States, and Fischer-Tropsch synthesis in South Africa. Supply chain risk concentrates in single-source vulnerability for metallocene catalyst systems, where patent thickets around single-site technology create licensing bottlenecks. Distribution runs through multinational procurement desks consolidating annual volumes across regional subsidiaries, compressing approved supplier lists to three-to-five vendors per geography.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and regulatory compliance support layers are expanding faster than base wax volumes, creating service-attach opportunities that deepen customer stickiness beyond commodity supply relationships.
For Market Incumbents: Entrench market position through captive ethylene integration and dedicated regulatory affairs infrastructure that blocks import-dependent traders from ECHA evaluation windows. Prioritize catalyst technology licensing agreements that lock in metallocene production capabilities before patent thickets further consolidate. Capacity additions in Zhejiang province would exploit East China clustering advantages while MEE permitting favors lower-energy thermal cracking configurations. For New Entrants and Emerging Players: Sub-Saharan African adhesives markets present underpenetrated demand corridors where Sasol's Durban-Johannesburg distribution infrastructure has not established dominant share. Target micronized powder forms below 50 microns for personal care applications, where Clariant's specialized production indicates concentrated supplier control and margin expansion potential. A go-to-market angle through toll manufacturing partnerships with established European regulatory dossier holders bypasses 18-24 month REACH registration barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because REACH registration requirements and evolving GB standards for food-contact extractables are raising barriers faster than new entrants can clear them. Acquisition targets should display established toxicological dossier capabilities and pre-registered grade portfolios serving German coatings formulators. The signal to watch is carbon border adjustment mechanism implementation, which would strand thermal cracking assets lacking embedded emissions documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Cracking | Captive feedstock supply from Yangtze River Delta crackers insulates margin from naphtha volatility. |
| Metallocene Catalyst Licensing Agreement | Single-site technology access enables FDA-compliant grades commanding personal care formulation premiums. |
| Long-term Supply Agreement with Automotive Tier | 18-24 month OEM qualification cycles lock in volume commitments through heat-deflection specification lock-in. |
| Green Manufacturing Transition to Lower-Energy Thermal Cracking | MEE dual carbon compliance secures preferential permitting for Shanghai and Ningbo production assets. |
| Joint Venture for Sub-Saharan Distribution Infrastructure | Durban-Johannesburg logistics corridors extend reach into adhesives markets beyond Sasol's current coverage. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with coatings formulators, adhesives procurement leads, automotive tier supplier technical directors, and petrochemical plant managers across East China, the US Gulf Coast, and Germany's Rhine-Ruhr corridor. Secondary validation drew from customs and trade flow data, SEC 10-K disclosures from listed chemical producers, ECHA registration databases, and MEE enforcement bulletins on dual carbon compliance. Bottom-up volume estimates from end-use application consumption were triangulated against top-down ethylene cracker capacity allocations and wax yield assumptions.
Calibration against historical price differentials between metallocene and Ziegler-Natta grades informed margin projections across the analysis window. Segmentation modeling incorporated product chemistry tiers, physical form handling economics, end-use certification requirements, and regional regulatory cluster variations. CAGRs were derived from weighted average of demand growth in coatings, adhesives, plastics compounding, and personal care applications, with specific adjustments for EPA VOC restriction implementation timelines and automotive interior compound specification shifts.
Practitioners should monitor feedstock spread compression, REACH evaluation timeline extensions, and carbon border adjustment mechanism rollout for early signals of forecast deviation. Projections reflect assumptions regarding sustained shale gas cost advantage in the United States, continued East China petrochemical clustering, and stable catalyst licensing cost structures. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polycide Market
Polymers & Resins
Germany Engineering Plastics Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
Construction Polymer Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Global Resin Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Global Alpha Olefins Market
Polymers & Resins
Medical Grade Liquid Crystal Polymer Market