
 Styrenics Market | 2026-2036
Styrenics Market Size, Share, and Industry Trends Forecast 2026-2036
Styrenics Market Outlook
Multi-sourced benzene and ethylene procurement is recalibrating as integrated crackers in Asia tighten feedstock availability. INEOS Styrolution leverages its European pipeline network to sustain cost-competitive styrene monomer supply. BASF SE anchors its position through backward integration into cracker operations at Ludwigshafen. Trinseo competes on specialized ABS grades for medical and automotive specifications.
Styrenics comprise a family of thermoplastic polymers derived from styrene monomer, including polystyrene, acrylonitrile-butadiene-styrene, and styrene-acrylonitrile copolymers, typically processed through bulk or suspension polymerization at temperatures between 120°C and 180°C. These materials serve primarily as rigid, moldable substrates for packaging, consumer durables, and vehicle interior components. ABS formulations command premium positioning in automotive interiors and electronics housings where impact resistance and surface finish quality determine specification. General-purpose polystyrene occupies mature, volume-driven segments in disposable packaging and food service applications. High-impact polystyrene extends into refrigerator liners and appliance housings where dimensional stability under thermal cycling matters.
REACH registration requirements in Europe, FDA food-contact regulations in the United States, and China's GB standards for plastic food packaging collectively elevate compliance costs for cross-border styrenics trade. Residual styrene monomer limits and migration testing protocols increasingly influence grade certification and customer qualification timelines. Stakeholders must monitor feedstock cost pass-through mechanics and regional regulatory divergence when committing to capacity expansion or long-term supply agreements.
Market Dynamics
Integrated petrochemical complexes in Asia are consolidating acrylonitrile-butadiene-styrene supply chains, forcing European and North American producers to defend specialty-grade positioning through regulatory compliance and formulation differentiation.
Growth Catalysts
- Automotive Lightweighting Mandates:OEM cabin redesigns favor high-impact polystyrene and ABS for dashboard substrates, reducing vehicle mass while maintaining crash performance under NHTSA and EU safety protocols.
- REACH Registration Tightening:ECHA's escalating purity requirements for residual styrene monomer are accelerating qualification timelines for medical-grade ABS, locking in supplier relationships with certified European compounders.
- Electronics Manufacturing Concentration:China's integrated crackers are scaling captive ABS output for domestic smartphone and appliance housing production, pulling regional feedstock allocation toward specialty copolymer grades.
Market Restraints
- Benzene Feedstock Volatility:Crude-linked aromatic pricing swings compress styrene monomer margins, particularly for non-integrated producers lacking captive naphtha cracking capacity.
- Polypropylene Substitution:Appliance and food packaging sectors are migrating to clarified PP for comparable stiffness at lower density, eroding general-purpose polystyrene volume in refrigerator liners and disposable cutlery.
- Single-Source Cracker Dependence:European styrenics supply chains rely heavily on Ludwigshafen and Antwerp corridor production, creating concentration risk during unplanned aromatic unit outages.
Strategic Opportunities
- Medical Device Grade Certification:US FDA and EU MDR biocompatibility pathways for implantable ABS housings remain underdeveloped, offering first-mover advantage to compounders mastering residual monomer control below 50 ppm.
- Chemical Recycling Integration:Pyrolysis-based styrene monomer recovery from post-consumer polystyrene waste is converging with mechanical recycling infrastructure, enabling circular feedstock claims for brand-owner sustainability targets.
- India Appliance Manufacturing:BIS certification requirements for refrigerator liner materials are creating localized formulation demand as Haier, Whirlpool, and Godrej expand Gujarat and Pune production bases.
Industry Challenges
- Migration Testing Expertise Gap:Qualified analytical chemists capable of executing EU 10/2011 food-contact migration protocols for styrene and oligomer species remain scarce, extending customer qualification cycles by 4-8 months.
- Legacy Extrusion Line Retrofit Costs:Converting HIPS sheet production to accommodate higher melt-strength recycled content requires screw and die modifications that strain mid-tier processor capex budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Styrenics Market |
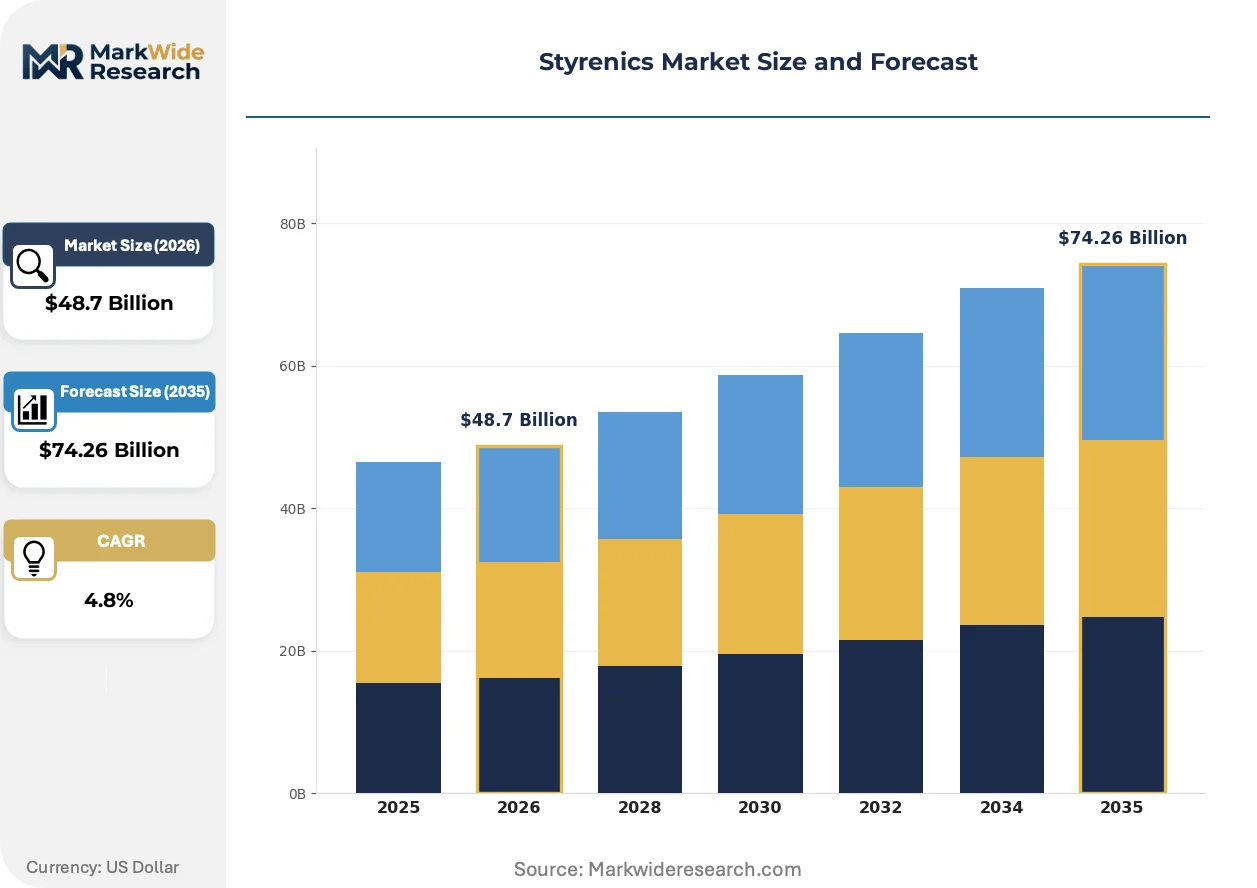
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $74.26 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PS, ABS, SAN, HIPS Application: Automotive Interiors, Consumer Goods, Electronics, Packaging End User: Manufacturers, Retailers, Distributors, OES Grade: General Purpose, High Impact, Food Grade, Electrical |
| Companies Covered | INEOS Styrolution, BASF SE, Trinseo, SABIC, LG Chem, Chi Mei Corporation, Chevron Phillips Chemical Company, LyondellBasell Industries, Nova Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Styrenics Market Strategic Shifts
Styrenics formulation science is pivoting toward monomer efficiency and circular feedstock integration, with regulatory pressure on residual content and end-of-life accountability driving R&D allocation away from commodity volume plays.
Advanced metallocene catalyst systems for styrene-butadiene block copolymer synthesis are electrifying the precision of rubber phase distribution control. Automotive TPO suppliers are adopting these grades for bumper fascia and interior soft-touch surfaces at accelerated qualification pace. The technology is electrifying the displacement of conventional emulsion polymerization routes, compressing capital intensity for specialty elastomer production.
ECHA's 2023 update to REACH Annex XVII restrictions on styrene monomer workplace exposure limits is tightening occupational health compliance across European compounding facilities. Industrial consequence includes mandatory closed-loop reactor venting systems and enhanced personal protective equipment protocols. Medical-grade ABS producers in Germany and Belgium are responding by segregating high-purity production lines from general-purpose operations to maintain dual-use certification.
Brand-owner sustainability scorecards are reshaping procurement specifications for consumer electronics housings. Dell, HP, and Lenovo are mandating mass-balance certified recycled content in ABS chassis materials, displacing virgin-only supply agreements. This specification shift is most visible in China and Vietnam contract manufacturing clusters where Original Design Manufacturers face compressed compliance timelines to retain tier-one vendor status.
Styrenics Market Segmentation
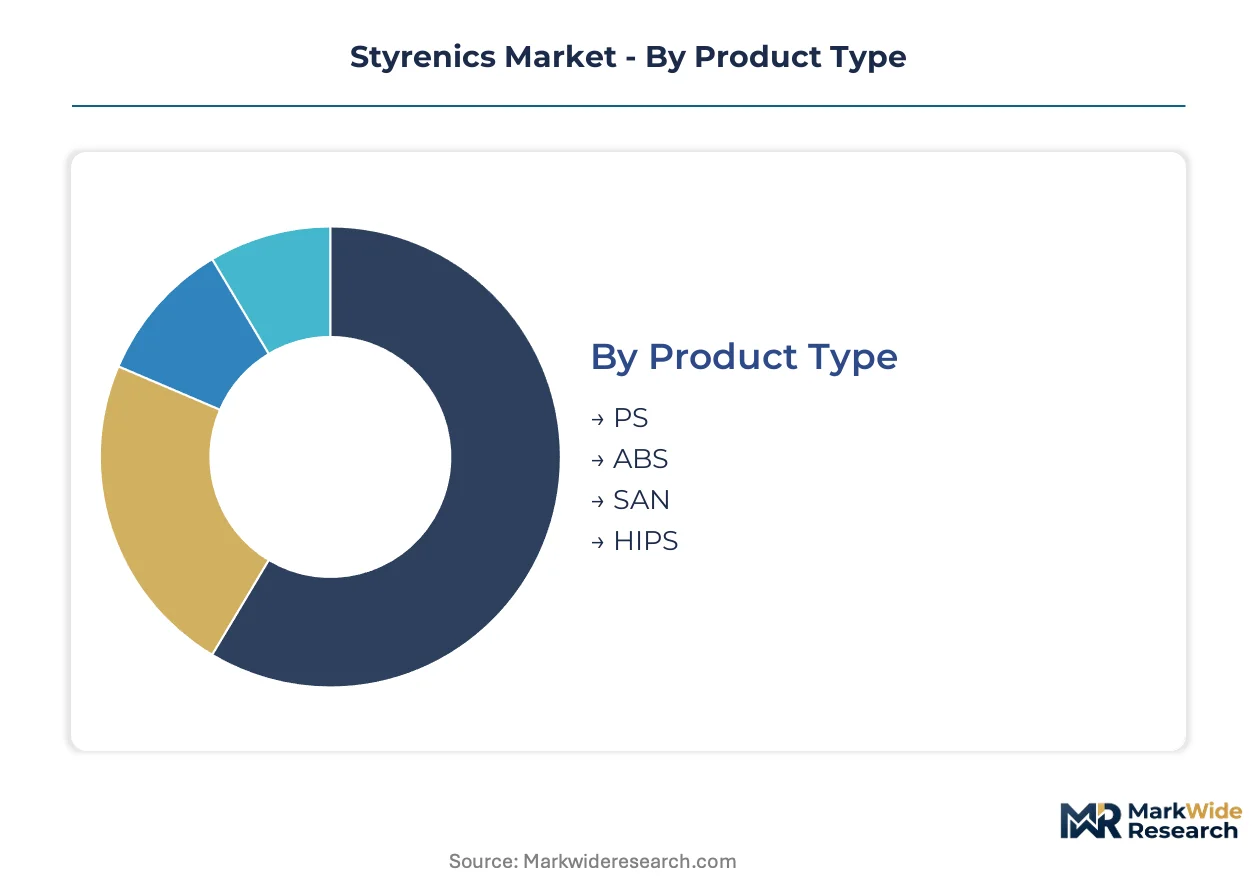
Styrenics procurement decisions pivot on polymer architecture, regulatory certification, and end-use performance thresholds. Each segmentation dimension carries distinct margin structures and qualification barriers that shape supplier selection and capacity allocation across integrated and non-integrated producers.
Product Type:
Product type concentration tracks feedstock integration depth and polymerization technology differentiation across regional production bases.
- PS:General-purpose polystyrene serves disposable food service and protective packaging through bulk polymerization at commodity scale. Chinese integrated crackers are pulling benzene-styrene conversion toward captive ABS output, constraining standalone PS expansion in Asia.
- ABS:Acrylonitrile-butadiene-styrene copolymer commands specification premiums in automotive dashboards and electronics housings where impact resistance and surface aesthetics determine OEM qualification. German compounders at Ludwigshafen and Antwerp corridor sites are segregating high-purity lines to maintain REACH-certified medical-grade supply.
- SAN:Styrene-acrylonitrile copolymer delivers transparency and chemical resistance for appliance glazing and cosmetic packaging.
- HIPS:High-impact polystyrene extends polystyrene toughness through rubber phase incorporation for refrigerator liners and thermoformed sheet.
PS absorbs the bulk of installed capacity; ABS is expanding most quickly.
Application:
Application segmentation reflects diverging regulatory intensity and substitution vulnerability across end-use sectors.
- Automotive Interiors:Dashboard substrates, door panels, and center console housings specify ABS and HIPS grades under NHTSA and EU safety protocols for head impact and flammability compliance. OEM lightweighting mandates are displacing heavier PP compounds in North American and European cabin redesigns.
- Consumer Goods:Appliance housings, furniture components, and recreational equipment utilize HIPS and general-purpose PS where cost-positioning dominates procurement.
- Electronics:Smartphone and laptop chassis require flame-retardant ABS with tight dimensional tolerance for injection molding complex geometries.
- Packaging:Food-contact thermoformed trays and disposable cutlery face clarified PP substitution pressure in United States and European retail channels.
Packaging commands the greatest volume throughput; automotive interiors are climbing the fastest on specification-grade premiums.
End User:
End-user channel structure determines technical service intensity and inventory holding patterns across the value chain.
- Manufacturers:OEM and contract manufacturers specify certified grades with direct supplier qualification and batch traceability for automotive and medical applications.
- Retailers:Private-label food packaging and housewares sourcing emphasizes landed cost and supply security over technical differentiation.
- Distributors:Regional polymer distributors warehouse commodity grades for mid-tier processors lacking direct mill relationships.
- OES:Original equipment suppliers in automotive aftermarket channels require color-matched and UV-stabilized specialty compounds.
Manufacturers concentrate the highest value-per-ton relationships; distributors are gaining share fastest through inventory financing programs.
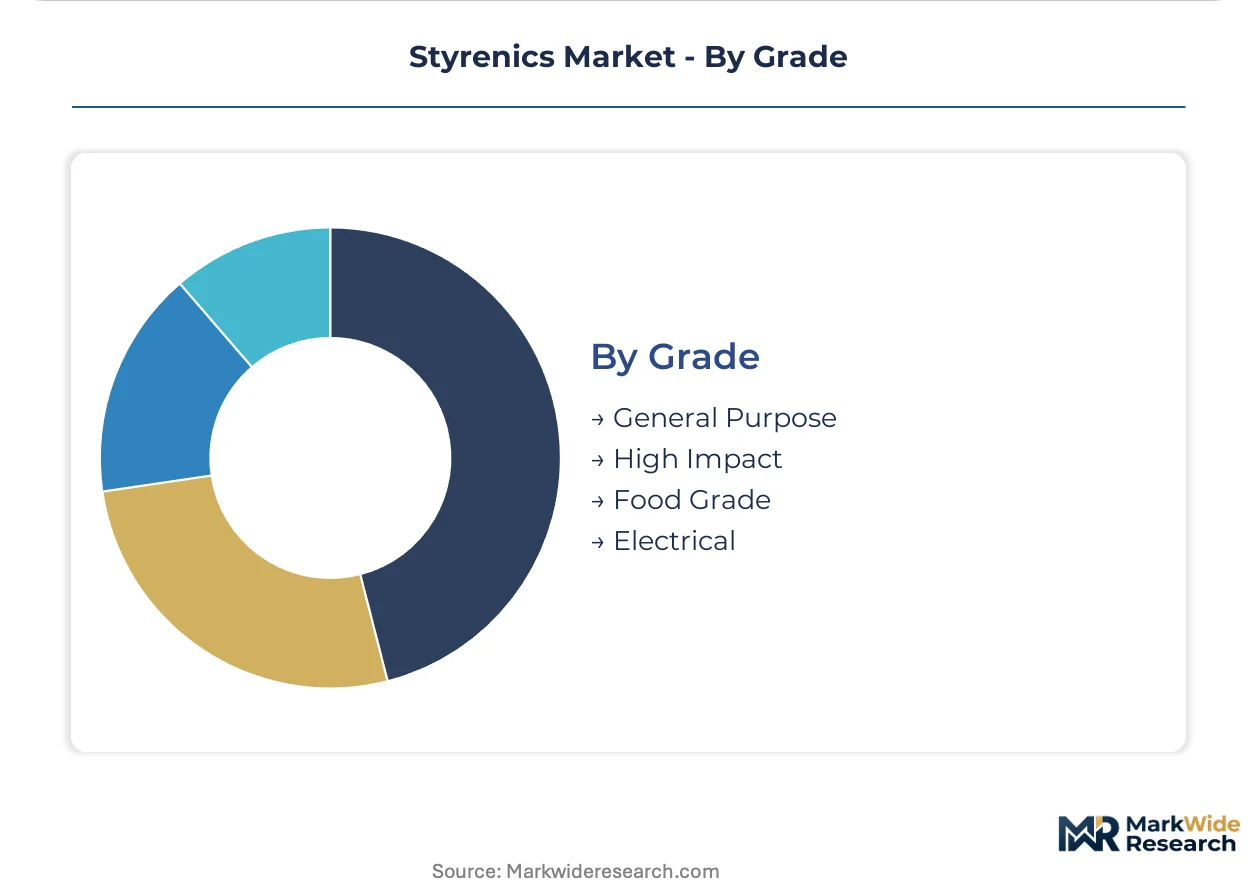
Grade:
Grade tiering separates specification-intensive certified production from volume commodity streams.
- General Purpose:Unmodified polystyrene for disposable applications faces margin compression from polypropylene substitution and mechanical recycling contamination limits.
- High Impact:Rubber-modified grades for appliance liners and construction panels require melt-strength optimization for sheet extrusion and thermoforming.
- Food Grade:Residual styrene monomer limits and EU 10/2011 migration testing protocols extend qualification cycles for European and United States food-contact applications.
- Electrical:Flame-retardant ABS and SAN grades with UL 94 V-0 certification serve switch housings and connector applications in electronics manufacturing.
General purpose holds the deepest installed base; food grade is gaining share fastest on regulatory compliance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Benzene and ethylene feedstock availability concentrates styrenics production near integrated crackers in China, Germany, the United States, and South Korea. Regional supply chains diverge sharply on regulatory intensity and end-use specialization.
China
Captive ABS output for smartphone and appliance manufacturing pulls styrene monomer toward Zhejiang and Jiangsu province petrochemical complexes. MIIT's GB standards for plastic food packaging impose migration testing protocols that extend qualification timelines for export-bound grades. Ningbo and Shanghai house the densest concentrations of compounding capacity serving domestic electronics OEMs.
Germany
Automotive interior specifications from BMW, Mercedes-Benz, and Volkswagen sustain demand for high-impact polystyrene and ABS dashboard substrates. ECHA's REACH Annex XVII workplace exposure limits mandate closed-loop reactor venting at Ludwigshafen and Antwerp corridor facilities. The Rhine-Neckar industrial cluster anchors European medical-grade ABS certification through segregated high-purity production lines.
United States
NHTSA safety protocols for head impact and flammability compliance drive OEM cabin redesigns favoring lighter weight styrenics over polypropylene compounds. FDA food-contact regulations and residual styrene monomer limits shape qualification requirements for disposable packaging processors. Gulf Coast crackers near Houston supply feedstock to specialty compounders serving appliance manufacturers in the Midwest and Southeast.
South Korea
Electronics chassis manufacturing for Samsung and LG pulls flame-retardant ABS demand toward Gyeonggi-do and Incheon production zones. MFDS medical device regulations create parallel certification pathways for implantable housing materials. The Ulsan petrochemical complex integrates backward into naphtha cracking to secure cost-competitive monomer supply.
India
Refrigerator liner demand from Haier, Whirlpool, and Godrej expansion in Gujarat and Maharashtra sustains HIPS formulation requirements. BIS certification mandates for appliance materials are localizing supply chain decisions away from import-dependent distributors. Pune and Ahmedabad industrial corridors concentrate thermoforming capacity for domestic appliance OEMs.
Styrenics Market Competitive Environment
Global majors compete with regional champions across feedstock integration depth and regulatory certification breadth. The vendor base separates into three tiers: integrated petrochemical conglomerates with captive cracking capacity, specialty compounders defending medical and automotive grade premiums, and regional distributors financing inventory for mid-tier processors. Strategic moves concentrate on backward integration into cracker operations and segregation of high-purity production lines for dual-use certification.
Among European integrated producers, INEOS Styrolution and BASF SE exemplify the feedstock-anchored archetype, with pipeline networks and cracker proximity sustaining cost position. Trinseo occupies the specialty-grade tier, competing on formulation differentiation for medical and automotive specifications. South Korean and Middle Eastern petrochemical groups represent the scale-driven challenger archetype, leveraging integrated crackers to capture electronics manufacturing demand in Asia-Pacific contract manufacturing clusters.
| Leading Market Players |
|---|
| INEOS Styrolution |
| BASF SE |
| Trinseo |
| SABIC |
| LG Chem |
| Chi Mei Corporation |
| Chevron Phillips Chemical Company |
| LyondellBasell Industries |
| Nova Chemicals |
| Others |
Value Chain & Pricing Dynamics
Benzene FOB Korea spot pricing cascades through styrenics supply chains into contract tiers that separate REACH-certified medical grades from commodity polystyrene streams. Feedstock volatility at integrated crackers compresses margins for non-integrated compounders while specialty ABS producers defend premiums through certification bundling.
Pricing Analysis
Technical service and regulatory certification bundling separates pricing tiers across the styrenics market. Contract structures stratify across premium, standard, and economy levels based on residual monomer limits and migration testing documentation. Price differentiation hinges on REACH Annex XVII compliance depth and FDA food-contact certification status. Cost compression in general-purpose polystyrene intensifies as clarified PP substitutes erode volume in packaging applications. Retail food packaging buyers exhibit highest price sensitivity; automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Antwerp, Ningbo, and Houston anchor hub-and-spoke patterns for styrenics feedstock and finished polymer flows. Manufacturing concentrates in China, Germany, and the United States near integrated naphtha crackers. Styrene monomer supply draws from benzene-ethylene conversion capacity concentrated in Zhejiang province and the Ludwigshafen corridor. Single-source cracker dependence in Europe creates vulnerability during unplanned aromatic unit outages. Distribution runs through direct mill relationships for automotive and medical OEMs, with regional distributors financing inventory for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Styrenics formulation science is transitioning from commodity volume plays toward monomer efficiency and circular feedstock integration, with pyrolysis-based chemical recycling displacing legacy mechanical recycling infrastructure.
For Market Incumbents: Hedge feedstock exposure through backward integration into cracker operations or long-term benzene offtake agreements with Gulf Coast and Asian producers. Defend medical-grade ABS premiums by segregating high-purity production lines at Ludwigshafen and Antwerp corridor facilities. Polypropylene substitution in appliance liners and food packaging represents the most acute volume threat to general-purpose polystyrene positions. For New Entrants and Emerging Players: Chemical recycling technology for post-consumer polystyrene waste recovery offers entry into brand-owner sustainability procurement specifications. Target electronics contract manufacturing clusters in Vietnam and India where mass-balance certified recycled content mandates are tightening fastest. Pursue toll-compounding partnerships with established distributors to bypass capital-intensive reactor infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty compounders with dual-use medical-automotive certification in Germany and Belgium. Five-to-ten year viability hinges on regulatory compliance breadth rather than scale economics alone. Monitor ECHA migration testing protocol updates as inflection indicators for qualification timeline compression and customer lock-in intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cracker Operations | BASF SE's Ludwigshafen complex secures captive benzene-styrene conversion for cost-competitive monomer supply. |
| Segregated High-Purity Production Lines | German compounders maintain REACH-certified medical-grade ABS certification through dedicated reactor infrastructure. |
| Chemical Recycling Infrastructure Partnership | Pyrolysis-based styrene monomer recovery enables circular feedstock claims for Dell and Lenovo sustainability scorecards. |
| Regional Distribution Center Expansion | Antwerp and Ningbo hubs reduce logistics costs for European and Asian automotive OEM qualification programs. |
| Medical Device Grade Certification Investment | Residual monomer control below 50 ppm opens implantable ABS housing applications under EU MDR pathways. |
Study Parameters
Document review covered customs and trade databases, SEC 10-K filings, ECHA REACH registration dossiers, and ACC industry reports, complemented by interviews with plant managers at integrated petrochemical complexes, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors at specialty compounders. Bottom-up capacity and consumption estimates were triangulated against top-down macroeconomic indicators across the analysis window.
Segment-level projections were generated across polymer architecture, regulatory certification tier, end-use industry, and regional production hub dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted demand modeling incorporating automotive lightweighting mandates, electronics manufacturing concentration, and REACH registration tightening as primary demand drivers. Feedstock cost pass-through mechanics and substitution elasticity parameters informed price trajectory assumptions.
Several conditions sit outside the modeled scope, including unanticipated benzene feedstock disruptions, accelerated polypropylene substitution rates, and ECHA workplace exposure limit revisions beyond current Annex XVII frameworks. Forecasts reflect documented assumptions around regulatory implementation timelines and cracker capacity expansion schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Cyclic Olefin Copolymer Market
Polymers & Resins
Hydrophobic Interaction Chromatography Resins Market
Polymers & Resins
Asia-Pacific Thermoplastics Market
Polymers & Resins
Global Flexible Polyurethane Foam Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
Rigid Spray Polyurethane Foam Market
Polymers & Resins
Bio-Based Polymer Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Polyolefin (PO) Market