
 Southeast Asia Modified Polypropylene Market | 2026-2036
Southeast Asia Modified Polypropylene Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Modified Polypropylene Market Insights
Capital-intensity divergence between integrated petrochemical operators and compounders is bifurcating competitive returns across Southeast Asia. Dow Thailand Group leverages its Map Ta Phut feedstock integration to sustain margin compression resistance in impact-modified grades. HMC Polymers anchors Thai automotive supply chains through dedicated compounding lines serving Toyota and Honda tier networks. SABIC competes via its Singapore trading hub, controlling import flows of specialized copolymers into Indonesia and Malaysia.
Modified polypropylene denotes base polypropylene resin altered through elastomer blending, copolymerization, or additive incorporation to achieve enhanced impact resistance, thermal stability, or processability beyond standard homopolymer specifications; typical modifications incorporate ethylene-propylene rubber phases of 10-40% by weight to elevate notched Izod impact strength above 15 kJ/m² for automotive bumper and interior applications. The product-type landscape positions impact-modified grades as the volume leader given their dominance in automotive and appliance housings, while random copolymers represent the fastest-expanding structural pocket due to clarity and sealing-performance requirements in Vietnam's emerging food-packaging sector. Application-level demand clusters heavily in injection molding, where margin pools concentrate among compounders serving just-in-time automotive sequences in Thailand's Eastern Economic Corridor.
Thailand's Industrial Works Department enforces hazardous substance controls under the Hazardous Substance Act B.E. 2535, compelling compounders to reformulate flame-retardant additive packages for electronics-grade modified polypropylene. Indonesia's Ministry of Environment and Forestry implements extended producer responsibility frameworks that elevate demand for mechanically recyclable modified grades in rigid packaging. Malaysia's Department of Standards administers MS standards aligned with ISO polypropylene testing protocols, shaping quality benchmarks for export-oriented molders. Stakeholders must monitor evolving country-of-origin certification requirements as regional trade agreements tighten rules-of-origin enforcement for petrochemical derivatives.
Market Dynamics
Automotive lightweighting mandates across Thailand and Indonesia are compressing resin substitution timelines, forcing compounders to accelerate impact-modified grade qualification cycles from 18 months to under 12 months for tier-one supplier integration.
Growth Catalysts
- Thailand's Bio-Circular-Green economy model:This regulatory framework mandates recyclable content thresholds in automotive components, compelling OEMs to specify mechanically recyclable modified polypropylene for interior panels and bumper systems.
- Electronics assembly clustering:Vietnam's northern industrial zones are concentrating demand for flame-retardant modified grades serving Samsung and LG display housing contracts, creating dedicated compounder investment corridors.
- Impact copolymer technology maturation:Advances in reactor-grade ethylene-propylene rubber incorporation now deliver 25 kJ/m² Izod ratings without secondary compounding, reducing conversion costs for Indonesian packaging molders.
Market Restraints
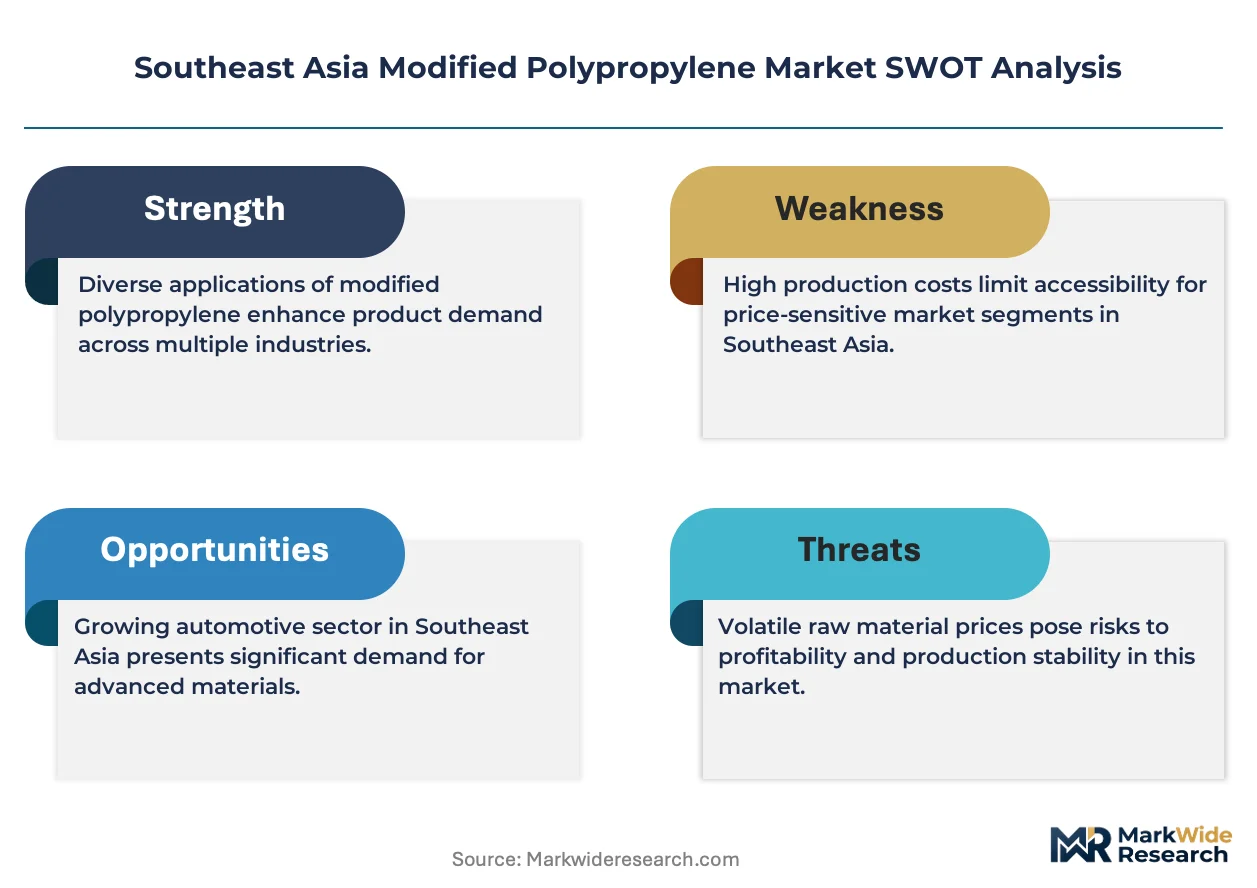
- Naphtha feedstock volatility:Southeast Asian crackers dependent on Middle Eastern naphtha imports face margin compression when oil-price spreads exceed $8 per barrel, squeezing integrated producers in Singapore and Thailand.
- Specialized additive import concentration:Halogen-free flame retardants and nucleating agents flow through a three-supplier chokepoint centered on German and Japanese chemical traders, creating 14-16 week lead time exposure.
- Mechanical recycling contamination limits:Indonesia's extended producer responsibility frameworks cap post-consumer recycled content at 30% in food-contact applications, constraining circular material adoption in rigid packaging.
Strategic Opportunities
- Malaysia's medical device molding corridor:Penang's catheter and diagnostic housing manufacturers currently import European compounded resin, representing captive localization potential for USP Class VI certified grades.
- Indonesia's national plastic waste reduction roadmap:This policy mandates 30% recycled content in non-food rigid packaging by 2030, creating pull-through demand for compatibilized post-industrial scrap compounds.
- Long glass fiber hybridization:Convergence of 20-40% long glass reinforcement with existing impact-modified bases enables metal replacement in Thai pickup truck bed liners, opening structural automotive applications.
Industry Challenges
- Automotive material qualification timelines:Toyota and Honda tier networks demand 18-month durability testing cycles for new compound grades, freezing out smaller compounders lacking capitalized validation infrastructure.
- Multinational resin specification fragmentation:Divergent OEM corporate standards between Japanese, Korean, and European automakers operating in Thailand force compounders to maintain 8-12 parallel certification portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Modified Polypropylene Market |
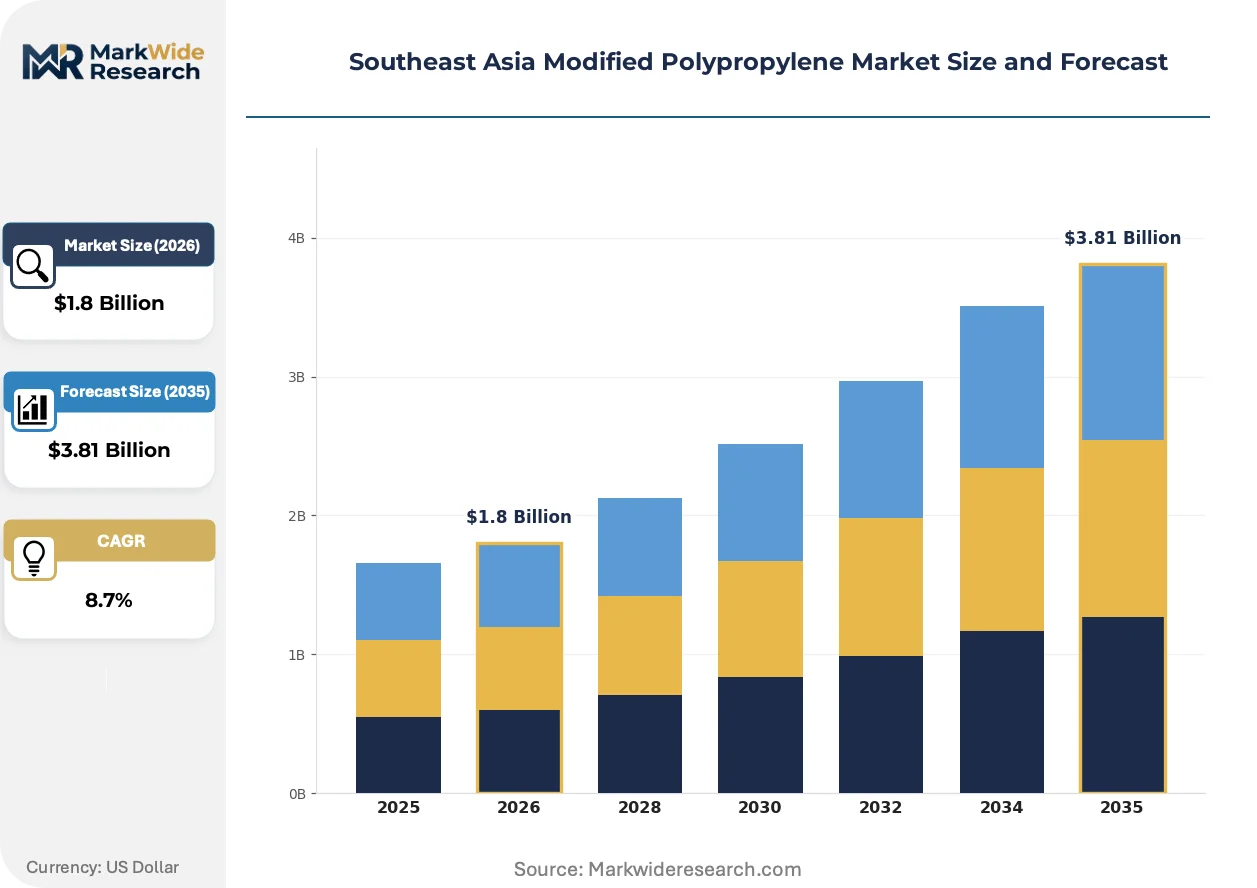
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impact Modified, Copolymer, Random Copolymer, Block Copolymer End User: Automotive, Packaging, Consumer Goods, Electronics Application: Injection Molding, Film Extrusion, Blow Molding, Sheet Production Distribution Channel: Direct Sales, Distributors, Retail, E-commerce |
| Companies Covered | Dow Thailand Group, HMC Polymers, SABIC, China XD Plastics, PolyPacific, LG Chem, PT Mitsui Chemicals, Asahi Kasei, Polyplastics Asia Pacific Sdn Bhd, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Modified Polypropylene Market Trends and Innovations
Reactor-grade copolymer advances and regulatory pressure on recyclability are restructuring how Southeast Asian compounders configure their product portfolios and customer qualification processes.
Reactor-direct impact copolymer technology is bifurcating the traditional compounding value chain by embedding 15-30% ethylene-propylene rubber phases directly during polymerization, eliminating the standalone compounding step for mid-tier automotive applications. Thai and Indonesian automotive suppliers are adopting these grades for non-critical interior components where 12-18 kJ/m² impact strength suffices. This technology is compressing margins for standalone compounders serving commodity automotive tiers while creating premium pockets for specialists handling complex multi-component formulations.
Indonesia's Ministry of Environment and Forestry extended producer responsibility enforcement is mandating recyclability certification for rigid packaging entering the Jakarta and Surabaya metropolitan markets. Compounders must reformulate additive packages to eliminate pigments and fillers that contaminate mechanical recycling streams, increasing R&D overhead by an estimated 15-20%. Malaysian export-oriented molders serving European brand owners are accelerating compliance to preempt EU packaging regulation alignment.
Buyer concentration among Thai automotive tier-one suppliers is consolidating procurement authority into three dominant purchasing cooperatives covering Toyota, Honda, and Isuzu supply chains. These entities are displacing direct mill relationships with centralized compounder nomination systems, compressing supplier counts from 12-15 to 4-6 approved sources per resin grade. Vietnam's electronics contract manufacturers are replicating this model, concentrating modified polypropylene demand through Foxconn and Luxshare procurement hubs in Bac Ninh province.
Southeast Asia Modified Polypropylene Market Segmentation
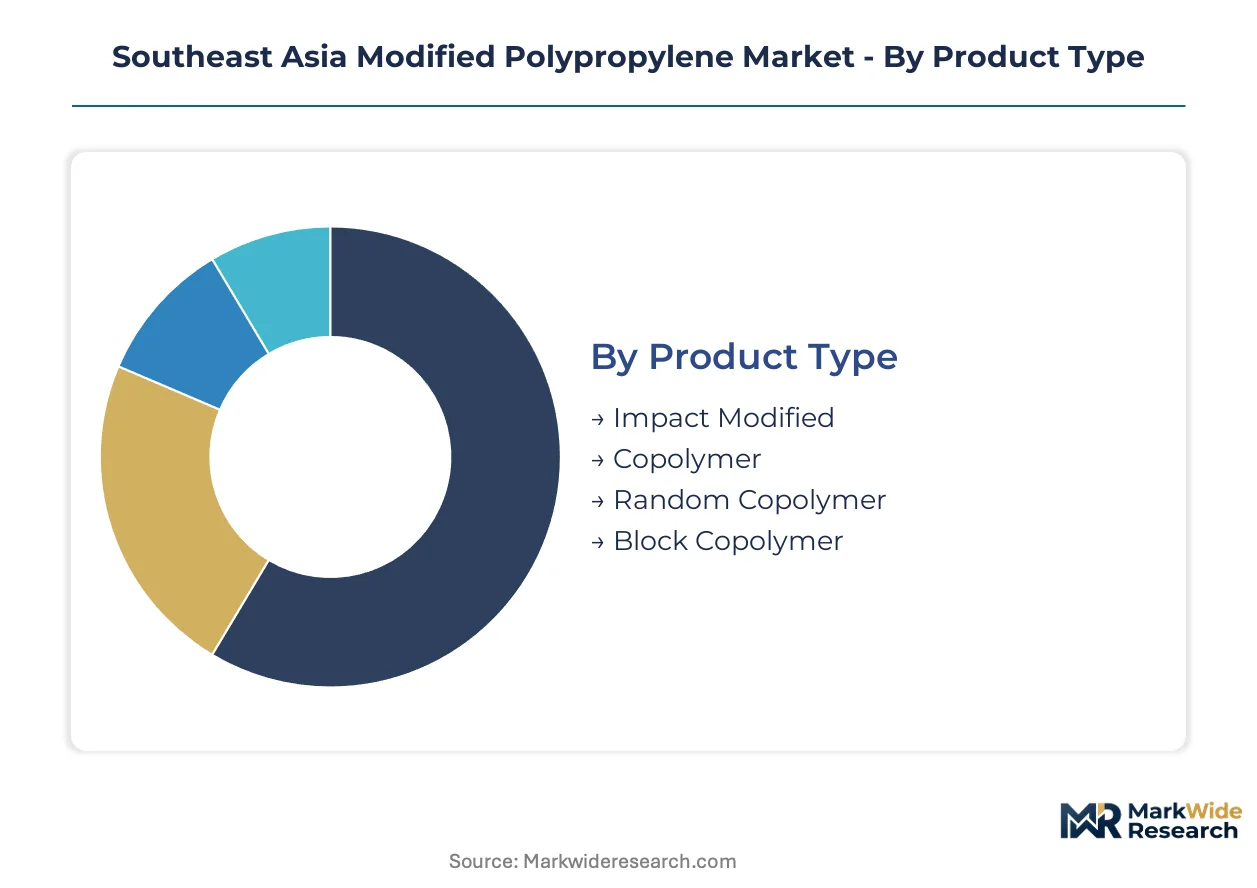
Modified polypropylene segmentation in Southeast Asia reflects divergent margin structures across reactor-direct copolymers versus compounded specialties. Understanding these tiered profit pools guides capital allocation between commodity automotive supply and premium electronics-grade formulations.
Product Type:
Margin pools concentrate in impact-modified grades serving automotive qualification cycles, while reactor-grade copolymers capture volume through streamlined conversion economics.
- Impact Modified:Base polypropylene incorporates 10-40% ethylene-propylene rubber phases through secondary compounding to achieve 15-25 kJ/m² Izod ratings. Thailand's Eastern Economic Corridor automotive tiers command premium pricing for bumper and interior panel grades subject to 18-month Toyota and Honda validation protocols.
- Copolymer:Reactor-direct ethylene incorporation during polymerization eliminates standalone compounding for mid-tier applications. Indonesian packaging molders adopt these grades for 12-18 kJ/m² applications where conversion cost reduction outweighs performance premiums.
- Random Copolymer:Vietnam's food-packaging sector drives clarity and sealing-performance specifications.
- Block Copolymer:Stiffness-ductility balance serves appliance housings and industrial containers.
The dominant share belongs to Impact Modified, while Copolymer is closing the gap fastest through reactor technology maturation.
End User:
Customer concentration patterns split between consolidated automotive procurement cooperatives and fragmented packaging converters.
- Automotive:Thailand and Indonesia lightweighting mandates compress resin substitution timelines from 18 months to under 12 months for tier-one supplier integration. Three purchasing cooperatives covering Toyota, Honda, and Isuzu supply chains have displaced direct mill relationships, consolidating supplier counts from 12-15 to 4-6 approved sources per grade.
- Packaging:Indonesia's extended producer responsibility frameworks mandate 30% recycled content in non-food rigid packaging by 2030, creating demand for compatibilized post-industrial scrap compounds. Malaysian export-oriented molders serving European brand owners accelerate compliance to preempt EU packaging regulation alignment.
- Consumer Goods:Appliance housings and furniture components specify mid-tier impact grades.
- Electronics:Vietnam's northern industrial zones concentrate flame-retardant modified grade demand for Samsung and LG display housing contracts.
Automotive commands the deepest margin pools, though Packaging is expanding most quickly through regulatory-driven specification changes.
Application:
Process technology requirements determine additive package complexity and qualification overhead.
- Injection Molding:Just-in-time automotive sequences in Thailand's Eastern Economic Corridor concentrate margin pools among compounders with dedicated compounding lines and capitalized validation infrastructure. Toyota and Honda tier networks demand parallel certification portfolios across 8-12 corporate standards.
- Film Extrusion:Vietnam's emerging food-packaging sector specifies random copolymer clarity grades for sealing-performance requirements.
- Blow Molding:Indonesian rigid packaging converters face mechanical recycling contamination limits capping post-consumer recycled content at 30% in food-contact applications.
- Sheet Production:Thermoforming applications for appliance liners and industrial trays.
Injection Molding retains the dominant position, with Film Extrusion gaining share fastest on Vietnam's packaging modernization.
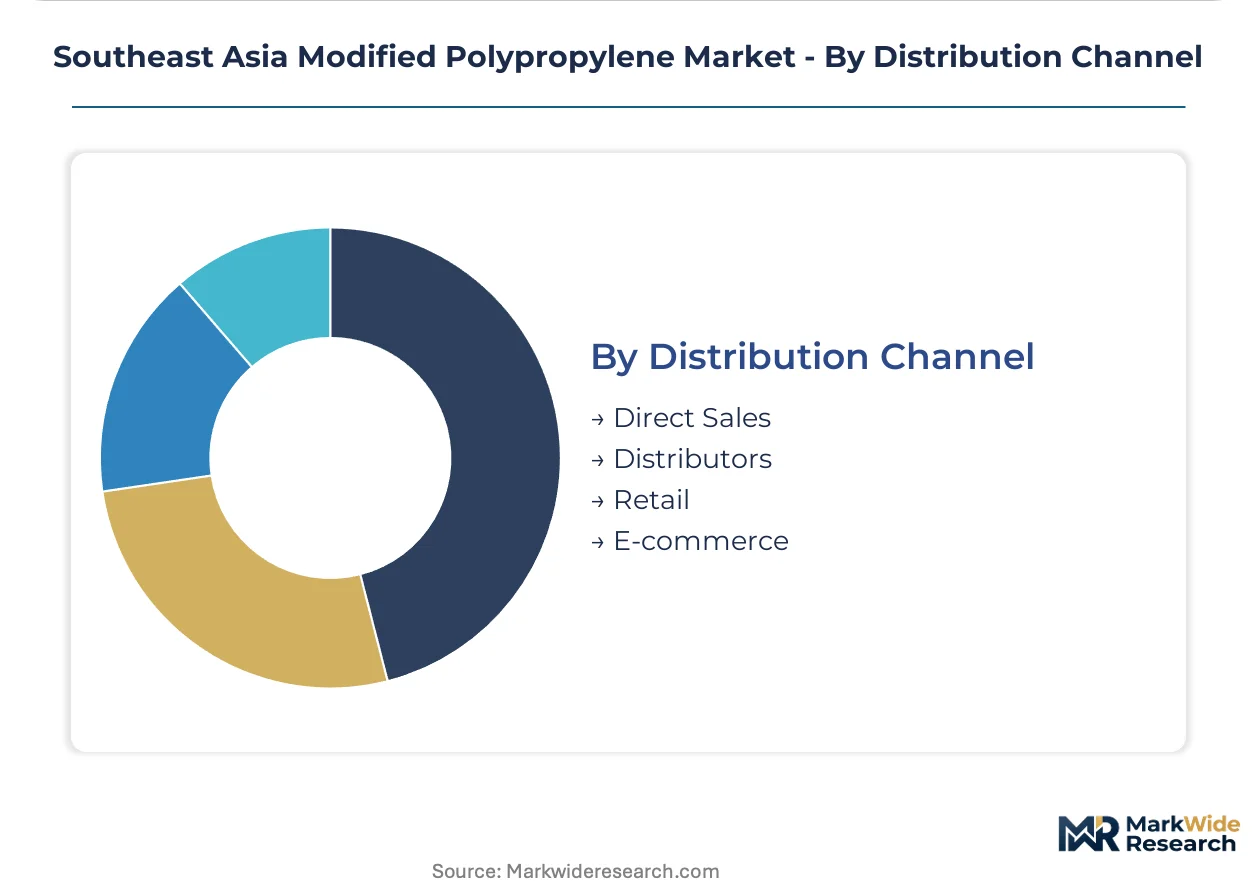
Distribution Channel:
Channel economics reflect order scale, technical service intensity, and geographic coverage requirements.
- Direct Sales:Integrated petrochemical operators and large compounders serve high-volume automotive tiers through mill-direct relationships. Dow Thailand Group leverages Map Ta Phut feedstock integration to sustain margin compression resistance.
- Distributors:Regional chemical traders control import flows of specialized copolymers and halogen-free flame retardants, though three-supplier concentration creates 14-16 week lead time exposure.
- Retail:Small-batch sales to job shops and prototype molders.
- E-commerce:Emerging channel for standard grades with documented technical data sheets.
Direct Sales holds the dominant channel position, while Distributors maintain critical import chokepoint control despite consolidation risks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Thailand's Map Ta Phut corridor while Indonesian compounders absorb feedstock volatility through naphtha import exposure. This asymmetry shapes margin distribution across Southeast Asian production clusters.
Thailand
Automotive lightweighting mandates from Toyota and Honda tier networks drive impact-modified grade qualification. The Industrial Works Department enforces hazardous substance controls under the Hazardous Substance Act B.E. 2535. The Eastern Economic Corridor hosts dedicated compounding lines serving just-in-time injection molding sequences for bumper and interior panel production.
Indonesia
Packaging modernization and rigid container demand pull reactor-grade copolymers for mid-tier applications. The Ministry of Environment and Forestry implements extended producer responsibility frameworks mandating recycled content thresholds. Surabaya and Jakarta metropolitan markets concentrate demand for mechanically recyclable modified grades in non-food rigid packaging.
Vietnam
Electronics assembly expansion in northern industrial zones concentrates flame-retardant modified grade demand. Samsung and LG display housing contracts create dedicated compounder investment corridors in Bac Ninh province. Foxconn and Luxshare procurement hubs consolidate buyer power for specialized resin specifications.
Malaysia
Export-oriented molders serving European brand owners accelerate compliance with recyclability certification requirements. The Department of Standards administers MS standards aligned with ISO polypropylene testing protocols. Penang's medical device molding corridor represents captive localization potential for USP Class VI certified grades currently imported from European compounders.
Singapore
Trading hub functions control import flows of specialized copolymers into regional markets. SABIC leverages Singapore's logistics infrastructure to coordinate supply chain positioning across Indonesia and Malaysia. The city-state's petrochemical refining capacity supports regional distribution of reactor-direct grades.
Southeast Asia Modified Polypropylene Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Southeast Asia. Integrated petrochemical operators leverage feedstock integration to sustain margin compression resistance, while standalone compounders capture premium pricing through qualification-intensive automotive relationships. The market structure splits between Map Ta Phut-anchored producers with captive naphtha supply and import-dependent compounders serving specialized electronics and medical grades. Dominant competitive moves include reactor-grade copolymer technology licensing that eliminates standalone compounding steps, and procurement cooperative consolidation that compresses approved supplier counts from 12-15 to 4-6 per resin grade.
Among Thailand-based integrated operators, Dow Thailand Group and HMC Polymers occupy positions shaped by Map Ta Phut feedstock access and dedicated automotive supply chain integration. SABIC represents the trading-hub archetype, coordinating regional import flows through Singapore logistics infrastructure without captive production in Southeast Asia. These three entities exemplify divergent strategic positions: feedstock-integrated domestic production versus trading-optimized regional coordination.
| Leading Market Players |
|---|
| Dow Thailand Group |
| HMC Polymers |
| SABIC |
| China XD Plastics |
| PolyPacific |
| LG Chem |
| PT Mitsui Chemicals |
| Asahi Kasei |
| Polyplastics Asia Pacific Sdn Bhd |
| Others |
Pricing and Supply Chain Analysis
Map Ta Phut's integrated petrochemical complex generates 40% regional capacity utilization advantages that compress conversion costs for Thai producers while elevating price floors for Indonesian import-dependent compounders. This scale asymmetry bifurcates margin structures across Southeast Asia's modified polypropylene value chain.
Pricing Analysis
Configured-to-order pricing for automotive-grade impact-modified compounds commands 25-35% premiums over standard reactor-grade copolymer spot pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification intensity: Toyota and Honda tier validation protocols anchor premium tiers, Indonesian packaging molders populate economy tiers. Price differentiation rests on qualification overhead and feedstock integration depth. Pricing pressure stems from reactor-direct technology eliminating standalone compounding steps for mid-tier applications. Packaging converters in Indonesia exhibit highest price sensitivity; Thai automotive tiers accept premium positioning for validated supply security.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose naphtha feedstock flows to 14-16 day voyage extensions during monsoon disruptions. Supply concentrates in Thailand, Singapore, and South Korea for base resin production; China and Japan anchor specialized additive manufacturing. Raw material dependencies center on Middle Eastern naphtha, German and Japanese halogen-free flame retardants, and nucleating agents. Single-source vulnerability concentrates in additive import channels controlled through three-supplier chokepoints. Distribution runs through direct mill relationships for high-volume automotive tiers and regional chemical traders for specialty electronics grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified compounder slots for Thai automotive supply chains represent scarce assets that concentrate value capture among incumbents with capitalized validation infrastructure. New entrants face 18-month qualification barriers that freeze out undercapitalized players.
For Market Incumbents: Secure dedicated compounding line expansion in Thailand's Eastern Economic Corridor to capture procurement cooperative consolidation from 12-15 to 4-6 approved suppliers. Deepen backward integration into captive naphtha supply through Map Ta Phut feedstock access. Defend against reactor-direct copolymer substitution by accelerating multi-component formulation capabilities for complex automotive specifications. For New Entrants and Emerging Players: USP Class VI certification fast-track for Penang's medical device molding corridor offers white-space entry with European import displacement potential. Target Vietnam's electronics assembly investment corridors through flame-retardant grade specialization for Samsung and LG display housing contracts. Pursue joint development agreements with Foxconn and Luxshare procurement hubs to bypass direct mill relationship requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with reactor-grade licensing access and established automotive validation portfolios over pure trading plays. Long-term viability hinges on circular economy compliance capabilities for Indonesia's extended producer responsibility enforcement. Acquisition target archetype: mid-tier compounders with 2-3 active automotive certifications and regional distribution infrastructure. Signal to watch: procurement cooperative supplier count compression accelerating beyond current 4-6 approved sources per grade.| Strategic Initiative | Industry Significance |
|---|---|
| Reactor-Direct Copolymer Licensing | Eliminates standalone compounding steps for Indonesian packaging molders seeking conversion cost reduction. |
| Automotive Validation Infrastructure Investment | Captures procurement cooperative consolidation across Toyota and Honda tier networks in Thailand. |
| Halogen-Free Flame Retardant Localization | Reduces 14-16 week additive import lead times for Vietnam electronics assembly corridors. |
| Post-Industrial Scrap Compatibilization | Enables Indonesia's 30% recycled content mandates in non-food rigid packaging applications. |
| Medical Grade USP Class VI Certification | Displaces European compounded resin imports in Penang catheter and diagnostic housing manufacturing. |
Research Methodology
A spread of perspectives from Thai automotive tier procurement managers, Indonesian packaging converter operations heads, Vietnamese electronics contract manufacturer material engineers, and Singapore-based petrochemical trading desks converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs trade databases, SEC petrochemical segment disclosures, and ISO polypropylene testing protocol documentation. Bottom-up resin consumption modeling triangulated against top-down regional polymer production capacity assessments.
Segmentation dimensions modeled span product type tier, end-use industry concentration, application process technology, and distribution channel structure across the analysis window. CAGRs derived from regression-weighted historical consumption patterns and forward-projected automotive lightweighting mandate compliance timelines. Industry-specific forecast inputs incorporated Thailand's Bio-Circular-Green economy model implementation pace and Indonesia's extended producer responsibility enforcement trajectory.
Underlying assumptions cover naphtha feedstock price stability, automotive qualification timeline compression, and regulatory harmonization across ASEAN trade frameworks, with deviation risk concentrated in Middle Eastern supply disruptions and OECD packaging regulation alignment acceleration. Revision becomes warranted when procurement cooperative supplier consolidation crosses below three approved sources per resin grade or reactor-direct copolymer technology adoption exceeds threshold penetration in mid-tier automotive applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Styrenic Polymers Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market
Polymers & Resins
Medical Polyoxymethylene (POM) Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
Methacrylate Monomers Market
Polymers & Resins
Global Colored PU Foams Market
Polymers & Resins
Europe Thermoplastics Market
Polymers & Resins
Amorphous Polyethylene Terephthalate (APET) Market
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
Acrylic Monomers Market
Polymers & Resins
Methyl Silicone Resins Market