
 Fluorinated Polyimide Market | 2026-2036
Fluorinated Polyimide Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorinated Polyimide Market Foresight
ISO 10993 biocompatibility certification is collapsing the supplier pool for medical-grade fluorinated polyimide films, leaving only multinationals with dedicated toxicology dossiers. Sumitomo Chemical leverages captive monomer supply to sustain film-grade output across Japanese electronics corridors. DuPont anchors North American aerospace qualification pipelines with heritage polyimide formulations. SKC competes aggressively on solvent-free resin platforms for Korean display manufacturers.
Fluorinated polyimide denotes aromatic heterocyclic polymers incorporating perfluoroalkyl substituents, typically synthesized through two-step polycondensation of dianhydrides with fluorinated diamines followed by thermal or chemical imidization at 300°C to 400°C, yielding materials with dielectric constants below 2.8 and thermal stability exceeding 400°C for high-frequency substrate and barrier layer applications. Film-grade product dominates current value capture due to roll-to-roll processing scale and flexible electronics penetration, while UV-curable coating formulations represent the fastest-expanding technology segment as semiconductor fabricators seek low-temperature cure cycles for temperature-sensitive wafer architectures. Solvent-based thermal imidization retains entrenched positions in aerospace composite prepregs where outgassing specifications remain stringent.
EPA oversight of per- and polyfluoroalkyl substances under TSCA Section 5 premanufacture notification is tightening monomer access for U.S.-based resin producers, while REACH restrictions on long-chain perfluorinated chemicals in the European Union are forcing reformulation toward C6 fluorotelomer-based dianhydrides. Japan's METI chemical substance reporting framework adds parallel compliance layers for export-oriented Korean and Chinese compounders. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border electronics supply chains.
Market Dynamics
Fluorinated polyimide procurement is consolidating around East Asian semiconductor packaging corridors as advanced node fabrication drives specification tightening for low-dielectric substrate materials.
Growth Catalysts
- Advanced Packaging Substrates:Semiconductor fabricators in South Korea and Taiwan are expanding fluorinated polyimide film specifications for 2.5D and 3D chiplet architectures requiring sub-2.8 dielectric constants.
- REACH C6 Reformulation Mandate:ECHA restrictions on long-chain perfluorinated chemicals are accelerating qualified C6 fluorotelomer-based dianhydride adoption across European electronics supply chains.
- Flexible Display Barrier Layers:Roll-to-roll processing scale in Japanese and Korean OLED manufacturing is pulling film-grade resin volumes for moisture-oxygen barrier applications.
Market Restraints
- Monomer Supply Concentration:Six dianhydride producers control 80% of fluorinated diamine precursor output, creating single-source vulnerability for compounders outside Japan.
- Thermal Imidization Energy Costs:Solvent-based batch processing at 300°C to 400°C imposes natural gas exposure that European resin producers cannot hedge effectively.
- Perfluoroalkyl Substitution Threat:Hydrogenated polyimide formulations with silicon oxide nanocomposite fillers are capturing aerospace qualification pipelines below 350°C service temperatures.
Strategic Opportunities
- UV-Curable Low-Temperature Cure:Semiconductor fabricators processing temperature-sensitive gallium nitride wafers are qualifying photoinitiated imidization below 200°C for temporary bonding layers.
- Indian Electronics Manufacturing:PLI scheme incentives for semiconductor packaging and display fabrication are creating first-mover qualification windows for resin suppliers establishing local compounding.
- ISO 10993 Biocompatibility Gap:Only three multinationals hold complete toxicology dossiers for implantable device films, leaving white space for dedicated medical-grade production lines.
Industry Challenges
- Cross-Border Regulatory Divergence:EPA TSCA Section 5 premanufacture notification timelines conflict with Japan METI chemical substance reporting, stranding inventory for Korean exporters.
- Specialized Polymer Synthesis Talent:Fluorinated diamine handling and anhydride moisture exclusion require chemists with organofluorine training that university pipelines have not replenished since 2015.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorinated Polyimide Market |
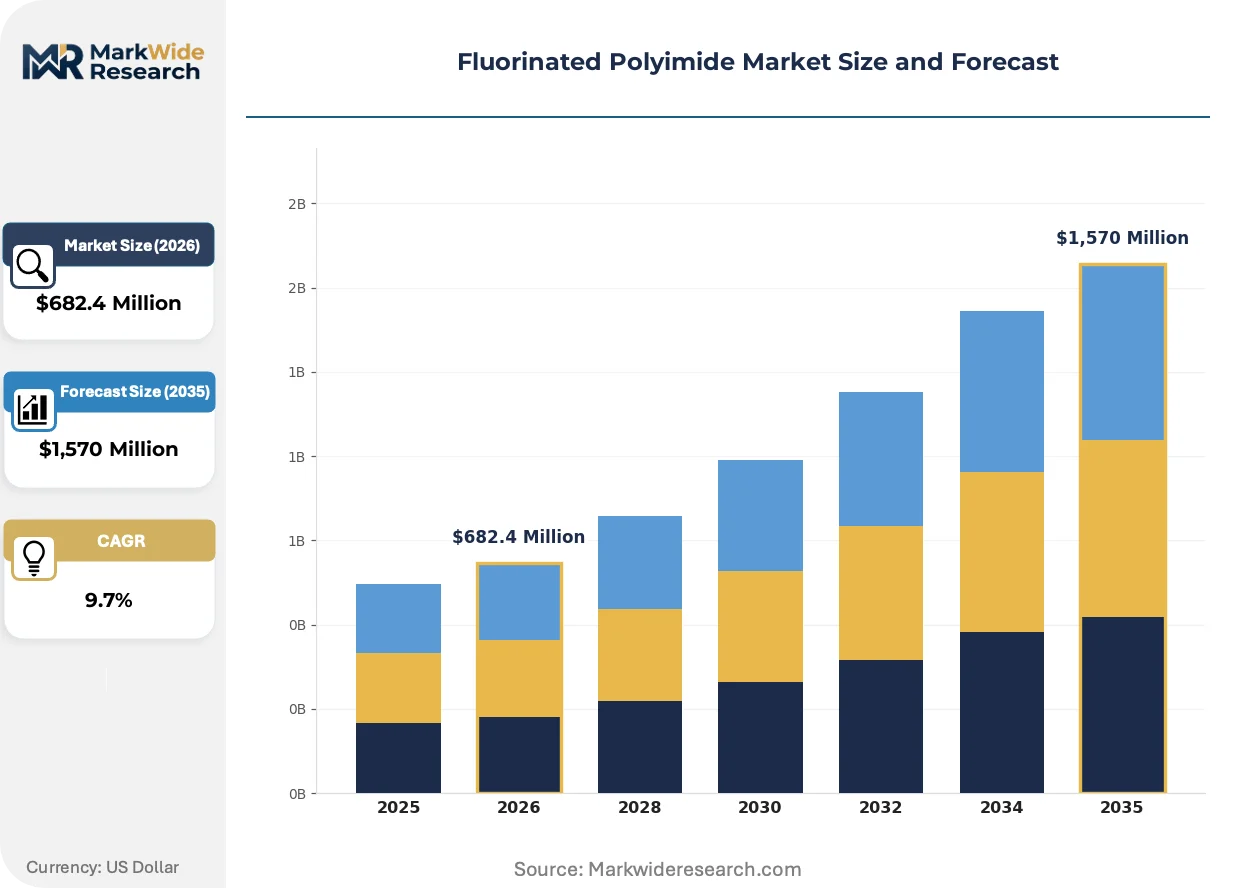
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,570 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film, Resin, Coating, Adhesive, Composite Technology: Solvent-Based, Solvent-Free, Thermal Imidization, Chemical Imidization, UV Curable Application: Flexible Electronics, Aerospace Components, Photovoltaic Cells, Semiconductor Devices, Protective Coatings End User Industry: Electronics Manufacturers, Aerospace Engineers, Solar Panel Producers, Chip Fabricators, Protective Equipment Suppliers |
| Companies Covered | Sumitomo Chemical Co. Ltd., SKC, Daikin Industries Ltd., I.S.T Corporation, Mitsubishi Gas Chemical Company Inc., DuPont, Kaneka Corporation, Capchem, Kolon Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorinated Polyimide Market Shifts & Advancements
Formulation chemistry is bifurcating between high-performance aerospace specifications and semiconductor-compatible low-temperature processing platforms.
UV-curable fluorinated polyimide coatings are decomposing the traditional thermal imidization equipment base. These formulations enable sub-200°C cure cycles essential for gallium nitride and silicon carbide wafer processing. Korean memory chip fabricators are qualifying solvent-free resin platforms that eliminate nitrogen purge requirements and reduce capital intensity for back-end-of-line operations.
REACH restrictions on perfluorooctanoic acid precursors are forcing dianhydride restructuring across European supply chains. Compounders are reformulating toward C6 fluorotelomer architectures that maintain dielectric performance while satisfying ECHA substance restrictions. German automotive electronics suppliers are accelerating qualification timelines to avoid stranded inventory when the 2025 enforcement window closes.
Buyer consolidation around South Korean display and memory clusters is compressing supplier negotiation cycles. Procurement teams at Samsung Display and SK Hynix are unbundling technical service from resin supply contracts, forcing Japanese and American multinationals to compete on specification compliance alone. This shift is most visible in Seoul-Incheon corridor negotiations where three buyers control 70% of regional fluorinated polyimide volume.
Fluorinated Polyimide Market Segmentation
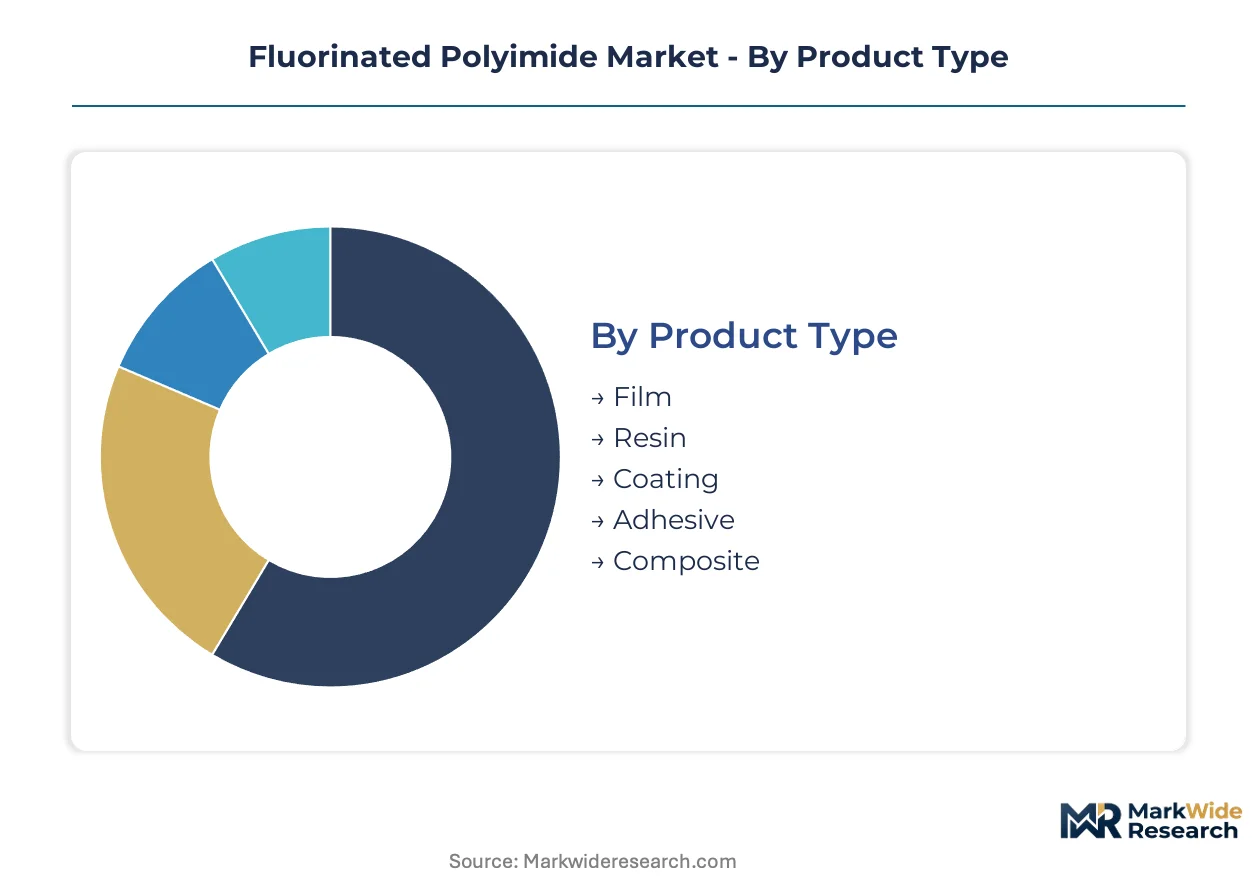
Fluorinated polyimide market segmentation reveals divergent margin structures across product forms and processing technologies. Film-grade and resin platforms command premium positioning in semiconductor packaging, while coating formulations accelerate on low-temperature cure demand.
Product Type:
Margin pools concentrate in film and resin segments where roll-to-roll processing scale and specification tightening create pricing power.
- Film:Roll-to-roll processed aromatic heterocyclic sheets deliver sub-2.8 dielectric constants for flexible substrate applications. Procurement from South Korean display corridors and Japanese OLED manufacturers sustains volume leadership despite thermal imidization energy costs.
- Resin:Solvent-free and solution-cast precursor formulations feed captive film production and third-party compounding. SKC's aggressive positioning on solvent-free platforms for Korean display manufacturers illustrates segment competition.
- Coating:Thin-film barrier and protective layers for moisture-oxygen exclusion.
- Adhesive:High-temperature bonding films for aerospace laminate stacks.
- Composite:Prepreg matrices for structural aerospace components requiring outgassing compliance.
Film holds installed capacity. Resin is rotating up the share rankings.
Technology:
Technology choice determines capital intensity and regulatory exposure across manufacturing footprints.
- Solvent-Based:Traditional thermal imidization at 300°C to 400°C retains entrenched aerospace positions where outgassing specifications remain non-negotiable. European resin producers face natural gas hedging challenges that Korean and Japanese competitors avoid through integrated utility structures.
- UV Curable:Photoinitiated imidization below 200°C enables gallium nitride wafer processing without thermal damage. Semiconductor fabricators in Taiwan and South Korea are qualifying these formulations for temporary bonding layers in advanced packaging.
- Solvent-Free:Eliminates nitrogen purge requirements and reduces volatile organic compound exposure.
- Thermal Imidization:Batch and continuous furnace processing for highest thermal stability specifications.
- Chemical Imidization:Room-temperature cyclization using dehydration agents for intermediate performance tiers.
Solvent-Based retains specification authority. UV Curable is climbing the fastest on semiconductor qualification timelines.
Application:
Application segmentation tracks end-use thermal and electrical requirements that dictate formulation chemistry.
- Semiconductor Devices:Advanced packaging substrates for 2.5D and 3D chiplet architectures drive sub-2.8 dielectric constant specifications. South Korean and Taiwanese fabricators are expanding procurement volumes as node shrinkage intensifies signal integrity demands.
- Flexible Electronics:Roll-to-roll compatible barrier layers for OLED displays and foldable device substrates. Japanese and Korean manufacturing corridors pull film-grade resin volumes for moisture-oxygen protection.
- Aerospace Components:Composite prepregs and insulation films requiring 400°C+ thermal stability.
- Photovoltaic Cells:Backsheet and encapsulant films for concentrated solar applications.
- Protective Coatings:Chemical-resistant barrier layers for industrial equipment.
Semiconductor Devices commands specification investment. Flexible Electronics is gaining share fastest on display manufacturing expansion.
End User Industry:
End user segmentation reflects concentrated buyer power in electronics manufacturing corridors.
- Electronics Manufacturers:Display panel and flexible circuit producers in Japan and South Korea dominate film-grade offtake. Samsung Display procurement teams unbundle technical service from resin supply contracts, compressing supplier negotiation cycles.
- Chip Fabricators:Memory and logic semiconductor packaging operations in Seoul-Incheon corridor control regional volume concentration. Three buyers command 70% of fluorinated polyimide procurement in this geography.
- Aerospace Engineers:Airframe and propulsion system suppliers requiring heritage qualification pipelines.
- Solar Panel Producers:Concentrated photovoltaic system integrators seeking thermal stability.
- Protective Equipment Suppliers:Industrial safety and chemical handling gear manufacturers.
Electronics Manufacturers hold installed demand. Chip Fabricators is rotating up the share rankings on advanced packaging substrate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives in India and semiconductor packaging subsidies in South Korea are redirecting fluorinated polyimide procurement toward new manufacturing corridors. Regulatory divergence between EPA TSCA Section 5 and Japan METI reporting frameworks complicates cross-border inventory management for compounders serving multiple jurisdictions.
United States
Aerospace qualification pipelines and semiconductor packaging operations in Texas and Arizona drive specification demand. EPA oversight under TSCA Section 5 premanufacture notification tightens monomer access for domestic resin producers. DuPont anchors heritage formulation supply from Delaware-based operations serving defense and commercial airframe contractors.
South Korea
Memory chip fabricators and OLED display manufacturers in the Seoul-Incheon corridor concentrate 70% of regional procurement volume. Government semiconductor packaging subsidies accelerate advanced node substrate qualification timelines. SKC competes aggressively on solvent-free resin platforms for Samsung Display and SK Hynix operations.
Japan
Flexible electronics barrier layers and captive film-grade production sustain domestic demand. METI chemical substance reporting frameworks add compliance layers for export-oriented compounders targeting Korean and Chinese buyers. Sumitomo Chemical leverages captive monomer supply across Japanese electronics manufacturing clusters.
Germany
Automotive electronics suppliers accelerate C6 fluorotelomer-based dianhydride qualification to avoid stranded inventory. REACH restrictions on long-chain perfluorinated chemicals enforce the 2025 ECHA enforcement window. Bavarian industrial corridors host reformulation R&D for European aerospace and automotive tier-one suppliers.
China
Display panel manufacturing expansion and domestic semiconductor packaging investments pull resin volumes. NMPA and MIIT chemical substance frameworks parallel international compliance requirements. Yangtze River Delta manufacturing clusters concentrate fluorinated polyimide compounding capacity for flexible electronics and photovoltaic applications.
Fluorinated Polyimide Market Competitive Landscape
Listed leaders compete with private specialists across monomer supply and film-grade processing capabilities. The supplier pool collapses around multinationals with dedicated toxicology dossiers for medical-grade certification, while regional compounders compete on reformulation agility. Three archetypes dominate: integrated chemical conglomerates with captive diamine supply, specialized film processors serving display corridors, and UV-curable formulation specialists targeting low-temperature semiconductor applications. Capacity expansion and strategic technology licensing represent the dominant competitive moves as fabricators unbundle technical service from resin supply contracts.
Within the integrated chemical tier, Sumitomo Chemical Co. Ltd. and Mitsubishi Gas Chemical Company Inc. exemplify Japanese conglomerates with backward control over fluorinated diamine precursors. SKC occupies a position among Korean specialists competing on solvent-free platforms for display manufacturing. DuPont anchors North American aerospace qualification pipelines with heritage polyimide formulations, representing the multinational archetype with cross-regional certification authority.
| Leading Market Players |
|---|
| Sumitomo Chemical Co. Ltd. |
| SKC |
| Daikin Industries Ltd. |
| I.S.T Corporation |
| Mitsubishi Gas Chemical Company Inc. |
| DuPont |
| Kaneka Corporation |
| Capchem |
| Kolon Industries |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Seoul-Incheon corridor fabricators and Japanese resin suppliers lock in both monomer access and eighteen-month price visibility against volatile fluorinated diamine spot markets. These arrangements concentrate procurement leverage with Samsung Display and SK Hynix while insulating compounders from natural gas cost swings that plague European thermal imidization operations.
Pricing Analysis
Certification level creates the primary spread across the value chain, with ISO 10993 biocompatibility-grade films commanding substantial premiums over standard electronics-tier formulations. Three-tier pricing structure across premium, standard, and economy levels reflects dielectric constant performance bands and thermal stability thresholds rather than volume discounts alone. Pricing pressure stems from Korean procurement teams unbundling technical service from resin supply contracts, compressing margins for Japanese and American multinationals. Chip fabricators exhibit the highest price sensitivity due to specification tightening at advanced nodes, while aerospace qualification pipelines remain least sensitive given heritage formulation lock-ins and non-negotiable outgassing requirements.
Supply Chain Analysis
Fluorinated diamine precursor synthesis concentrates in Japan, South Korea, and China, where six integrated producers control upstream monomer output. Raw material flows draw from hexafluoroisopropylidene-based dianhydrides, aromatic diamine feedstocks, and high-purity solvents for solution-cast processing. Single-source vulnerability runs through Japanese captive supply chains that Korean compounders cannot replicate without METI compliance investment. Distribution feeds from integrated chemical conglomerates through regional compounding facilities to captive film production lines at display and semiconductor packaging operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and reformulation support layers are expanding faster than base resin volumes as procurement teams unbundle specification compliance from supply agreements. Recurring revenue from qualification pipeline maintenance and regulatory dossier updates offers higher margin stability than transactional resin sales alone.
For Market Incumbents: Fortify backward integration into fluorinated diamine precursors to defend against Korean solvent-free platform competitors and EPA TSCA Section 5 monomer access restrictions. Prioritize ISO 10993 certification investment for medical-grade film production lines where only three multinationals currently hold complete toxicology dossiers. Expand capacity in the Seoul-Incheon corridor to match Samsung Display and SK Hynix procurement consolidation. For New Entrants and Emerging Players: Differentiate on UV-curable low-temperature cure formulations for gallium nitride wafer processing, where semiconductor fabricators seek sub-200°C alternatives to thermal imidization. Target the Indian electronics manufacturing corridor under PLI scheme incentives, where first-mover qualification windows remain open for local compounding investment. Lead with solvent-free resin platforms that eliminate nitrogen purge requirements and reduce capital intensity for back-end-of-line operations. For Investors and Strategic Acquirers: Regional compounders with C6 fluorotelomer reformulation capabilities and ECHA REACH compliance dossiers represent the most defensible acquisition archetype as the 2025 enforcement window closes. Long-term viability across the analysis window hinges on regulatory agility rather than scale alone. Monitor EPA premanufacture notification timeline extensions as the inflection signal for stranded inventory risk in cross-border electronics supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive fluorinated diamine production insulates Japanese conglomerates from EPA TSCA Section 5 access restrictions. |
| UV-Curable Formulation Launch | Photoinitiated imidization below 200°C enables gallium nitride wafer qualification at Taiwanese fabricators. |
| ISO 10993 Certification Investment | Medical-grade toxicology dossiers collapse the supplier pool to three multinationals with implantable device authority. |
| Long-term Supply Agreement | Seoul-Incheon corridor offtake contracts lock in volume concentration with Samsung Display and SK Hynix procurement teams. |
| Joint Venture for Indian Compounding | PLI scheme incentives create first-mover qualification windows for semiconductor packaging substrate supply. |
Research Methodology
Operator-level perspectives from semiconductor packaging engineers, display panel procurement leads, fluorinated diamine plant managers, and aerospace composite qualification specialists anchored the qualitative base. Primary interview data combined with secondary validation from customs and trade flow databases, SEC 10-K filings of listed chemical conglomerates, and ECHA substance restriction notifications. Bottom-up resin volume estimates triangulated against top-down electronics manufacturing capex disclosures across Japanese, Korean, and Chinese production clusters.
Sensitivity analysis across the projection horizon tested demand elasticity to advanced node semiconductor packaging adoption rates and regulatory enforcement timeline shifts. The analytical framework modeled fluorinated polyimide consumption by product form, processing technology, dielectric constant performance tier, end-use thermal requirement, and regional manufacturing corridor concentration. CAGRs derived from segment-level volume build-ups calibrated to semiconductor fab equipment spend patterns and OLED display capacity expansion schedules.
Material uncertainties — EPA TSCA Section 5 premanufacture notification delays, ECHA REACH C6 fluorotelomer qualification failures, and gallium nitride wafer processing temperature threshold revisions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization and procurement consolidation trajectories that may shift with jurisdiction-specific enforcement intensity. Practitioners should keep alternative scenarios live as cross-border chemical substance reporting frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Super Absorbent Polymers (SAP) Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Southeast Asia Modified Polypropylene Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Global Acrylic Solid Surface Market
Polymers & Resins
PEG 3500 Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market
Polymers & Resins
North America Polyurethane Market
Polymers & Resins
Semi-Crystalline Polymers Market
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
Global Furan Resins Market
Polymers & Resins
Medical Polyoxymethylene (POM) Market
Polymers & Resins
Middle East and Africa Polyethylene Wax Market
Polymers & Resins
Global Vinyl Ester Market