
 North America Durable Medical Equipment Market | 2026-2036
North America Durable Medical Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Durable Medical Equipment Market Intelligence
Mexico's manufacturing corridor is fragmenting as contract producers expand capacity for export-oriented assembly of wheelchairs and respiratory devices. Invacare Corporation leverages its Ohio-based distribution network to sustain North American market presence. Sunrise Medical anchors premium mobility aid design through its California engineering centers. Medline Industries competes across the hospital bed segment with private-label sourcing scale.
Durable medical equipment encompasses reusable devices prescribed for medical necessity over extended periods, typically constructed from aluminum alloys, medical-grade polymers, and sealed electronic housings to withstand repeated sanitization cycles; these products serve therapeutic, monitoring, or mobility assistance functions in clinical and residential settings. Wheelchairs and mobility aids command the largest revenue pool due to chronic condition prevalence, while digital health solutions and remote monitoring represent the fastest-expanding technology layer as payers expand reimbursement for connected devices. Respiratory equipment maintains mature margins concentrated among contracted hospital purchasers.
FDA 510(k) clearance requirements and Health Canada Medical Device Licensing shape product entry timelines, while CMS National Coverage Determinations directly control reimbursement-driven demand volumes. The U.S. Department of Veterans Affairs procurement standards further segment access for specialized mobility and respiratory platforms. Stakeholders must monitor Medicare Advantage plan expansion into home-based benefit structures.
Market Dynamics
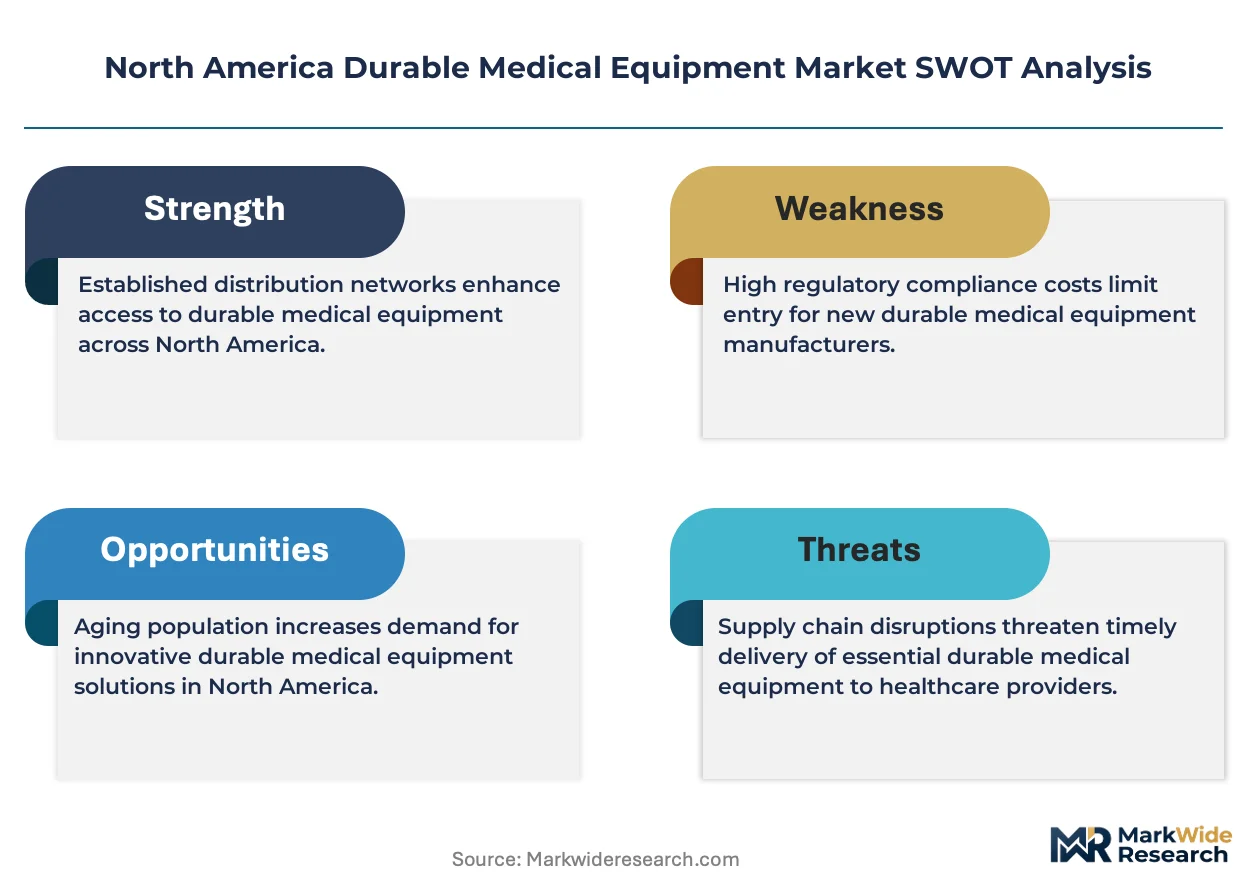
Medicare Advantage plan expansion into home-based benefit structures is redistributing procurement authority from hospital purchasing consortia toward managed care organizations, compressing traditional durable medical equipment distribution hierarchies.
Growth Catalysts
- CMS National Coverage Determinations:Expanded reimbursement for connected respiratory monitors and remote patient monitoring devices pulls capital into digital-enabled equipment categories.
- Sun Belt demographic concentration:Rapid senior population growth across Florida, Arizona, and Texas concentrates demand for powered mobility devices and home oxygen therapy systems.
- Aluminum alloy fabrication advances:Lightweighting breakthroughs in wheelchair frame construction reduce shipping costs and extend battery range for powered models.
Market Restraints
- Medical-grade polymer supply concentration:Specialized polymer feedstocks for sealed electronic housings concentrate among Gulf Coast petrochemical producers, exposing assemblers to hurricane-related disruption.
- FDA 510(k) clearance timelines:Substantial equivalence review periods for novel sensor-integrated mobility devices extend market entry schedules by 12-18 months versus traditional mechanical products.
- Refurbished equipment substitution:Certified pre-owned wheelchair and hospital bed channels capture price-sensitive Medicare fee-for-service beneficiaries.
Strategic Opportunities
- Canada provincial home care expansion:Ontario and British Columbia provincial health plans are broadening community-based equipment lending programs beyond acute discharge scenarios.
- Remote therapeutic monitoring (RTM) reimbursement:CMS physician fee schedule additions for musculoskeletal and respiratory RTM create payment pathways for sensor-embedded braces and nebulizers.
- Veterans Affairs procurement standardization:Consolidated specifications for specialized mobility platforms open volume contracts for modular, upgradeable device architectures.
Industry Challenges
- Biomedical technician certification gaps:Complex repair protocols for sealed electronic housings and lithium battery systems outpace community college training program curricula.
- Legacy hospital bed integration:New digital monitoring attachments must interface with 15-20 year installed bases of analog bed frames through proprietary adapter hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Durable Medical Equipment Market |
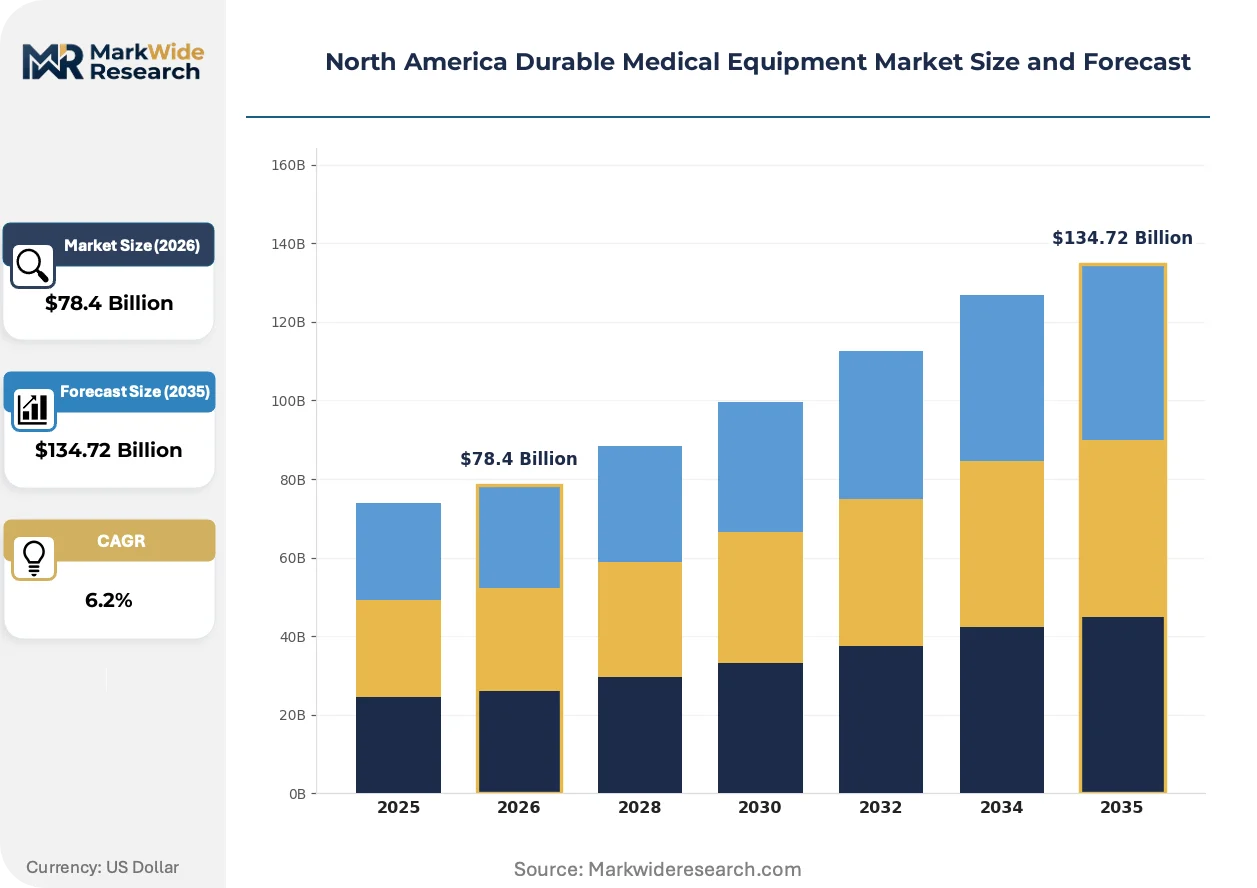
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $134.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
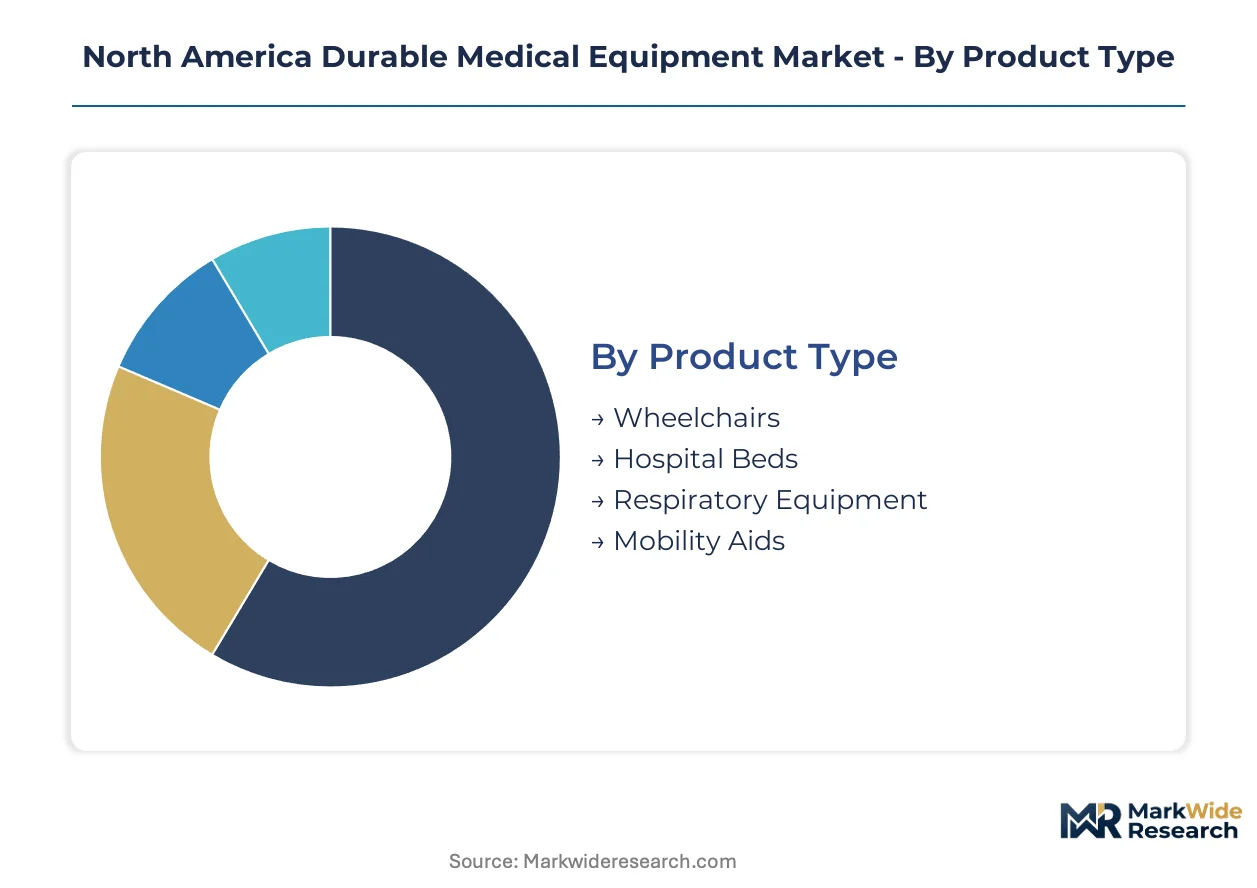
| Segmentation | Product Type: Wheelchairs, Hospital Beds, Respiratory Equipment, Mobility Aids End User: Hospitals, Home Care Settings, Rehabilitation Centers, Long-term Care Facilities Technology: Digital Health Solutions, Wearable Devices, Remote Monitoring, Telehealth Tools Service Type: Equipment Rental, Maintenance, Installation, After-sales Support |
| Companies Covered | Invacare Corporation, Sunrise Medical, Arjo, Medline Industries, Inc., GF Health Products, Inc., Cardinal Health, Drive DeVilbiss Healthcare, Stryker Corporation, Hill-Rom Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Durable Medical Equipment Market Strategic Shifts & Innovations
Connected device architectures and modular platform designs are dissolving traditional boundaries between durable equipment and disposable supply categories, forcing manufacturers to reconceptualize revenue models around data services rather than unit sales.
Sensor-embedded wheelchairs with real-time pressure mapping and predictive maintenance algorithms are collapsing the distinction between mobility aids and remote monitoring platforms. Medicare Advantage plans in California and Florida are piloting per-member-per-month payment structures for these integrated systems. The technology is collapsing standalone remote patient monitoring device markets into consolidated mobility-plus-monitoring offerings.
FDA breakthrough device designation pathways for AI-enabled fall detection attachments are compressing clearance timelines for wheelchair-mounted computer vision systems. Manufacturers are pre-submission consulting with CDRH to align algorithm validation protocols with predicate device comparisons. Powered mobility segments with high catastrophic injury liability exposure are adopting these designations most aggressively.
Hospital purchasing consortia are unbundling preventive maintenance contracts from capital equipment leases, forcing manufacturers to compete for multi-year service agreements separate from initial device procurement. Texas and Florida health systems are leading this separation. Durable medical equipment vendors must now price service labor and spare parts independently of hardware margins.
North America Durable Medical Equipment Market Segmentation
Segmentation in durable medical equipment reveals how reimbursement pathways, patient acuity, and technology integration reshape procurement priorities across North American healthcare delivery systems. Understanding these divisions exposes where capital flows concentrate and where emerging modalities disrupt established supplier relationships.
Product Type:
Mature mechanical categories dominate current revenue pools while sensor-integrated platforms redraw competitive boundaries.
- Wheelchairs:Aluminum alloy and titanium frame constructions now incorporate pressure-mapping sensors and predictive maintenance algorithms. Demand clusters in Florida, Arizona, and Texas as Medicare Advantage plans pilot per-member-per-month payment structures for connected mobility systems.
- Hospital Beds:Electric adjustable frames with integrated scale systems and fall-risk monitoring anchor acute care capital budgets. Texas and Florida health systems are unbundling preventive maintenance contracts from equipment leases, forcing manufacturers to compete for multi-year service agreements separately.
- Respiratory Equipment:Home oxygen concentrators and CPAP devices serve chronic obstructive pulmonary disease populations concentrated in Sun Belt states with elevated smoking histories and altitude-adjusted oxygen requirements.
- Mobility Aids:Walkers, canes, and transfer devices represent high-volume, lower-acuity prescriptions where refurbished equipment channels capture price-sensitive Medicare fee-for-service beneficiaries.
Wheelchairs retain volume leadership; digital health solutions hold the steepest expansion curve.
End User:
Procurement authority is migrating from institutional purchasing consortia toward managed care organizations and direct-to-patient channels.
- Hospitals:Integrated delivery networks in California and Texas negotiate enterprise-wide contracts spanning beds, respiratory fleets, and mobility devices. FDA 510(k) clearance timelines for novel sensor-integrated equipment extend procurement cycles by 12-18 months versus traditional mechanical products.
- Home Care Settings:Aging patients in Florida and Arizona prefer outpatient recovery, expanding demand for powered mobility devices and portable oxygen systems that operate without clinical supervision. CMS National Coverage Determinations for remote patient monitoring directly shape equipment specifications in this channel.
- Rehabilitation Centers:Post-acute facilities in Ontario and British Columbia coordinate with provincial health plans on community-based equipment lending programs beyond acute discharge scenarios.
- Long-term Care Facilities:Skilled nursing operators face compressed margins from Medicaid reimbursement rates, driving preference for durable frames with 10-15 year service lifespans and standardized replacement parts.
Home care settings are gaining share fastest; hospitals maintain the largest absolute procurement volumes.
Technology:
Connected architectures are dissolving traditional boundaries between durable equipment and disposable supply categories.
- Digital Health Solutions:Cloud-connected device platforms enable predictive maintenance and usage analytics. FDA breakthrough device designation pathways for AI-enabled fall detection attachments are compressing clearance timelines for wheelchair-mounted computer vision systems.
- Wearable Devices:Sensor-embedded braces and orthotics capture biomechanical data for musculoskeletal remote therapeutic monitoring, newly reimbursable under CMS physician fee schedule additions.
- Remote Monitoring:Cellular-enabled respiratory devices transmit adherence and efficacy data to pulmonology practices, collapsing standalone remote patient monitoring markets into consolidated equipment-plus-monitoring offerings.
- Telehealth Tools:Integrated video consultation hardware for home care settings must interface with existing WiFi infrastructure and HIPAA-compliant data architectures.
Remote monitoring commands the highest technology premiums; digital health solutions are expanding most quickly.
Service Type:
Revenue models are pivoting from unit sales toward recurring service relationships and outcome-based contracts.
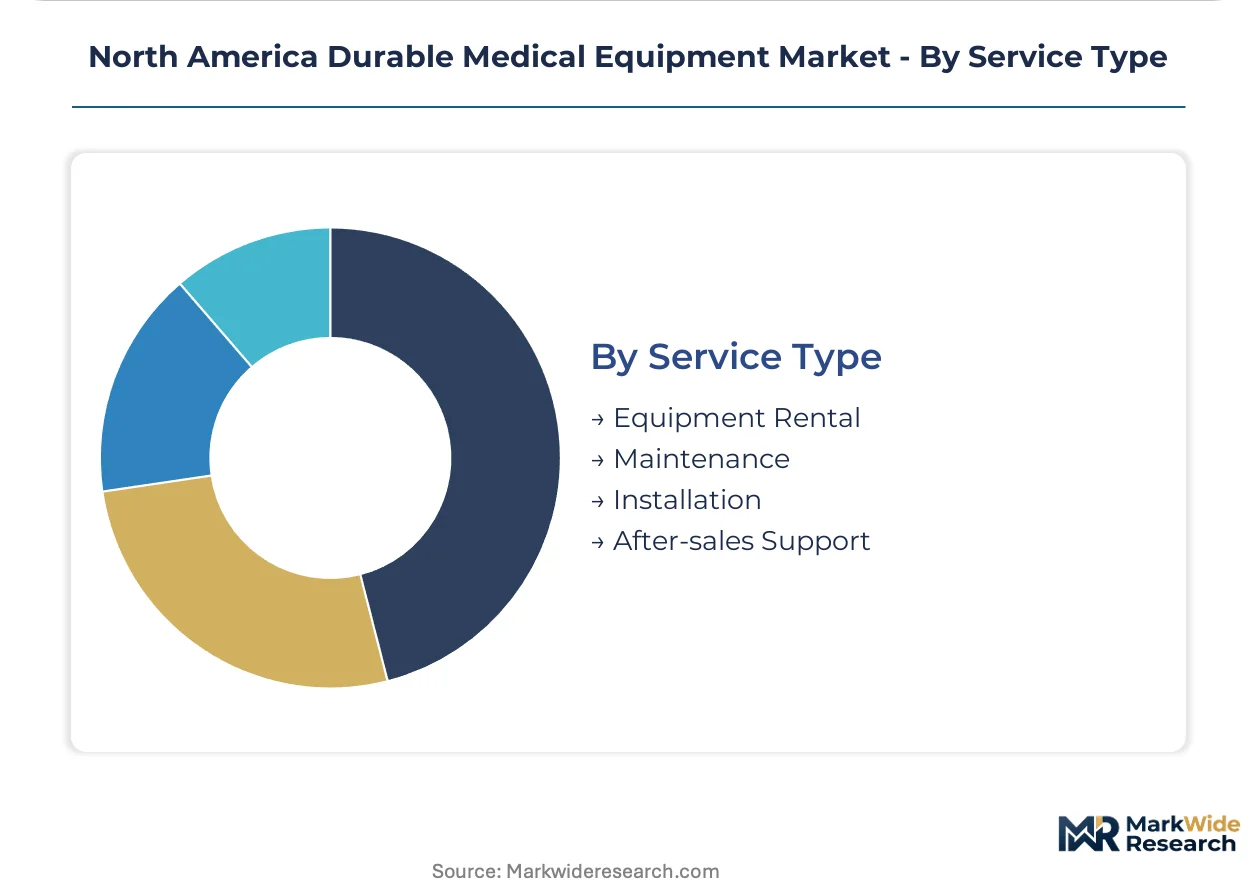
- Equipment Rental:Medicare fee-for-service and Medicaid programs favor monthly rental structures for high-cost items like powered wheelchairs and hospital-grade beds, transferring obsolescence risk to suppliers.
- Maintenance:Biomedical technician certification gaps for sealed electronic housings and lithium battery systems outpace community college training program curricula, creating service capacity constraints.
- Installation:Home modification requirements for wheelchair ramps and oxygen concentrator ventilation create coordination complexity between equipment suppliers and construction contractors.
- After-sales Support:Veterans Affairs procurement standardization for specialized mobility platforms opens volume contracts for modular, upgradeable device architectures with dedicated technical support lines.
Equipment rental generates the most predictable cash flows; maintenance services are climbing the fastest as device complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly of wheelchairs and respiratory devices concentrates along Mexico's northern manufacturing corridor, where contract producers scale export-oriented capacity for US and Canadian markets. This supply-side clustering shapes procurement timelines and logistics costs across the continent.
United States
Medicare Advantage expansion into home-based benefits redistributes procurement authority toward managed care organizations in Florida, Arizona, and Texas. FDA 510(k) clearance pathways govern competitive entry timelines for sensor-integrated mobility devices. Ohio-based distribution networks anchor supply chain reach into Midwest and Northeast markets.
Canada
Ontario and British Columbia provincial health plans broaden community-based equipment lending programs beyond acute discharge scenarios. Health Canada Medical Device Licensing shapes product entry requirements alongside provincial procurement standards. Engineering centers in Ontario concentrate digital health platform development for remote monitoring integration.
Mexico
Export-oriented assembly of aluminum wheelchair frames and respiratory device components scales through Baja California and Chihuahua manufacturing parks. Mexican federal export promotion programs support maquiladora operations serving US hospital purchasing consortia. Tijuana and Ciudad Juárez clusters specialize in lightweight frame fabrication and sealed electronic housing assembly.
North America Durable Medical Equipment Market Key Industry Players
Full-line manufacturers and specialized mobility designers split the market into distinct capability tiers. Hospital bed and respiratory equipment segments show consolidated procurement relationships with integrated delivery networks, while wheelchair and home care categories retain fragmented supplier bases. Three archetypes dominate: diversified health systems suppliers, dedicated mobility specialists, and private-label sourcing platforms. Competitive moves center on multi-year service agreement unbundling from hardware leases and modular platform architectures for Veterans Affairs standardization.
Among diversified health systems suppliers, Cardinal Health and Stryker Corporation occupy positions spanning acute care capital equipment through post-acute distribution. Dedicated mobility specialists exemplified by Invacare Corporation and Sunrise Medical anchor premium and standard-tier wheelchair design. Private-label sourcing platforms represented by Medline Industries compete on scale economies across hospital bed and basic mobility categories.
| Leading Market Players |
|---|
| Invacare Corporation |
| Sunrise Medical |
| Arjo |
| Medline Industries, Inc. |
| GF Health Products, Inc. |
| Cardinal Health |
| Drive DeVilbiss Healthcare |
| Stryker Corporation |
| Hill-Rom Holdings, Inc. |
| Others |
Cost & Logistics Intelligence
Mexico's northern manufacturing corridor concentrates aluminum alloy fabrication and sealed electronic housing assembly, anchoring margin pools with US hospital purchasing consortia and Medicare Advantage plans that dictate downstream pricing power through volume commitment structures.
Pricing Analysis
CMS National Coverage Determinations dictate the pricing tier structure across durable medical equipment categories, separating FDA 510(k)-cleared connected devices from traditional mechanical products. Three-tier pricing structure across premium sensor-integrated, standard electric-adjustable, and economy manual equipment levels reflects certification grade and after-sales service bundling. Cost compression in economy-tier mobility aids intensifies because refurbished equipment channels capture price-sensitive Medicare fee-for-service beneficiaries. Hospital purchasing consortia exhibit lowest price sensitivity due to enterprise-wide contract structures, while individual home care patients show highest sensitivity to out-of-pocket rental differentials.
Supply Chain Analysis
Export control restrictions on lithium battery cells and advanced sensor components limit flows from select Asian manufacturing hubs, forcing North American assemblers to diversify sourcing for powered mobility devices. Supply concentration spans Mexico for aluminum frame fabrication, China for medical-grade polymer feedstocks, and domestic US facilities for final assembly and FDA-regulated quality systems. Raw material dependencies rest on Gulf Coast petrochemical outputs for sealed housings, rare earth elements for motor magnets, and lithium-ion cells for power systems. Single-source vulnerability runs through hurricane-exposed polymer production along the Texas-Louisiana corridor. Distribution runs through Ohio-based logistics networks serving Midwest and Northeast markets, with California and Florida hubs managing Sun Belt demand concentration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern anchored to Medicare Advantage enrollment waves and CMS reimbursement cycle adjustments, with capital deployment timing contingent on federal health policy election cycles.
For Market Incumbents: Entrench service contract unbundling capabilities ahead of hospital purchasing consortia demands in Texas and Florida health systems. Deepen backward integration into aluminum alloy fabrication through Mexican maquiladora partnerships to defend against contract manufacturer margin capture. Invest in biomedical technician certification programs to resolve sealed electronic housing repair capacity constraints that threaten multi-year service agreement profitability.
For New Entrants and Emerging Players: Establish a beachhead in remote therapeutic monitoring reimbursement pathways for sensor-embedded respiratory and musculoskeletal devices newly covered under CMS physician fee schedule additions. Target Ontario and British Columbia provincial home care expansion programs as the most penetrable geographic entry point with streamlined Health Canada licensing requirements. Pursue Veterans Affairs procurement standardization contracts through modular platform architectures with dedicated technical support infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across digital health-enabled equipment categories requiring FDA breakthrough device designation pathways and AI validation protocols. Long-term viability favors manufacturers with recurring revenue models unbundled from hardware sales, particularly those capturing Medicare Advantage per-member-per-month payment structures. Monitor FDA 510(k) clearance timeline compression for novel sensor-integrated mobility devices as the key inflection signal for competitive entry dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS National Coverage Determination alignment unlocks Medicare Advantage plan contracting. |
| Hospital System Partnership | Texas and Florida integrated delivery networks consolidate enterprise-wide equipment procurement. |
| Software Companion Development | Predictive maintenance algorithms differentiate sensor-embedded wheelchairs from commodity mobility aids. |
| CE Marking Pathway | Health Canada Medical Device Licensing enables Ontario and British Columbia provincial program access. |
| Backward Integration | Mexican maquiladora aluminum fabrication captive supply reduces shipping costs for powered mobility frames. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, CMS Medicare reimbursement filings, and hospital GPO contract disclosures. Primary interviews engaged biomedical engineers, hospital purchasing committee directors, durable medical equipment distribution executives, and Medicare Advantage plan product managers. Secondary validation drew from Health Canada Medical Device Licensing records, Veterans Affairs procurement standardization documents, and provincial health plan equipment lending program specifications. Bottom-up equipment shipment analysis triangulates against top-down reimbursement expenditure tracking.
Forecast inputs span product type segmentation across wheelchairs, hospital beds, respiratory equipment, and mobility aids; end user channels spanning hospitals, home care settings, rehabilitation centers, and long-term care facilities; and technology tiers separating connected digital platforms from traditional mechanical devices. CAGRs derive from reimbursement pathway expansion modeling and demographic concentration analysis across Sun Belt states. Industry-specific inputs incorporate Medicare Advantage plan penetration rates and FDA breakthrough device designation pathway utilization.
Sensitivities concentrate around CMS National Coverage Determination reversals, hurricane disruption to Gulf Coast polymer supply, and Medicare Advantage plan benefit structure modifications. Forecasts reflect documented assumptions regarding reimbursement stability and manufacturing corridor operational continuity. Material shifts in federal health policy administration or export control restrictions on lithium battery technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
North America Medical Device Reprocessing Market
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Histology Embedding System Market
Medical Equipment
Cath Lab Market
Medical Equipment
Medical Air Sterilizer Market
Medical Equipment
Photorejuvenation Equipment Market
Medical Equipment
Global Medical Lighting Technologies Market
Medical Equipment
Contact Type Liquid Handling Workstation Market
Medical Equipment
Europe Medical Equipment Maintenance Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
Cryogenic Freezers Market
Medical Equipment
Surgical Generators Market
Medical Equipment
Life Support Systems Market
Medical Equipment
Global Latex Medical Gloves Market
Medical Equipment
Dial Thermometers Market
Medical Equipment
Global Renal Dialysis Equipment Market