
 Global Medical Lighting Technologies Market | 2026-2036
Global Medical Lighting Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Lighting Technologies Market Foresight
Software-defined intensity calibration and remote diagnostics subscription layers is repositioning how hospitals procure surgical illumination, shifting capital expenditure into operational budgets. Koninklijke Philips N.V. leverages its luminaire-to-workflow integration to dominate European operating room retrofits. General Electric Company sustains installed-base loyalty through predictive maintenance contracts tied to its surgical lighting platforms. Herbert Waldmann GmbH & Co. KG specializes in task-optimized dental and examination lighting, anchoring its position in German-speaking clinical markets.
Medical lighting technologies encompass engineered illumination systems producing color-rendering indices exceeding 90 and correlated color temperatures between 3,500K and 5,000K for tissue differentiation during procedures. These systems employ LED chip-on-board arrays, precision optics, and thermal management substrates to deliver shadow-free, adjustable beams for surgical, diagnostic, and therapeutic applications. LED lights command the dominant revenue position due to energy efficiency mandates and lumen maintenance guarantees, while surgical procedures represent the deepest margin pool given the premium pricing of hybrid operating room configurations. Fiber optic lights retain niche demand in minimally invasive suites requiring cold light delivery, though xenon lamps face displacement as mercury-containing sources fall under REACH and RoHS restrictions.
FDA 510(k) clearance pathways and the EU MDR's renewed clinical evidence requirements are elevating barrier costs for new surgical lighting entrants, while IEC 60601-1 third edition compliance shapes electrical safety baselines across all major markets. Japan's PMDA enforces additional electromagnetic compatibility testing that filters non-domestic suppliers from premium hospital tenders. Stakeholders must monitor how AI-integrated surgical navigation systems will redefine lighting control architectures and whether photobiological safety standards tighten further under the EU AI Act's risk classification framework.
Market Dynamics
LED chip-on-board arrays are compressing replacement cycles for surgical luminaires while EU MDR photobiological safety mandates force hardware redesigns across installed bases. Hospital infrastructure renewal in Germany, the United States, and Japan concentrates demand-pull into discrete procurement windows.
Growth Catalysts
- EU MDR photobiological safety mandates:IEC 62471 testing requirements for blue-light hazard assessment are compelling surgical suite retrofits in European tertiary hospitals.
- Hybrid operating room configurations:Integrated imaging-illumination systems command premium positioning in German and Japanese hospital construction pipelines.
- Ambulatory surgical center expansion:United States outpatient facility construction is absorbing mid-tier LED surgical systems at volume scale.
Market Restraints
- REACH and RoHS mercury restrictions:Xenon lamp phase-outs strand legacy endoscope light source inventories before full amortization.
- LED thermal substrate supply concentration:Aluminum nitride ceramic substrate fabrication clusters in Japanese and German supplier networks create input bottlenecks.
- FDA 510(k) clinical evidence elevation:Predicate device equivalence pathways now demand photobiological safety dossiers that extend clearance timelines.
Strategic Opportunities
- Software-defined intensity calibration:Remote diagnostics subscriptions reposition capital expenditure into recurring operational budgets for hospital procurement officers.
- AI-integrated surgical navigation convergence:Lighting control architectures that interface with navigation systems capture workflow integration value in premium Japanese tenders.
- Indian hospital infrastructure buildout:Central government health facility expansion programs absorb standardized examination lighting at mid-market price points.
Industry Challenges
- IEC 60601-1 third edition electrical safety certification:Isolation transformer and leakage current testing protocols extend product validation cycles for multi-market launches.
- Legacy halogen infrastructure incompatibility:Retrofit mounting hardware and control interface mismatches complicate operating room upgrade sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Lighting Technologies Market |
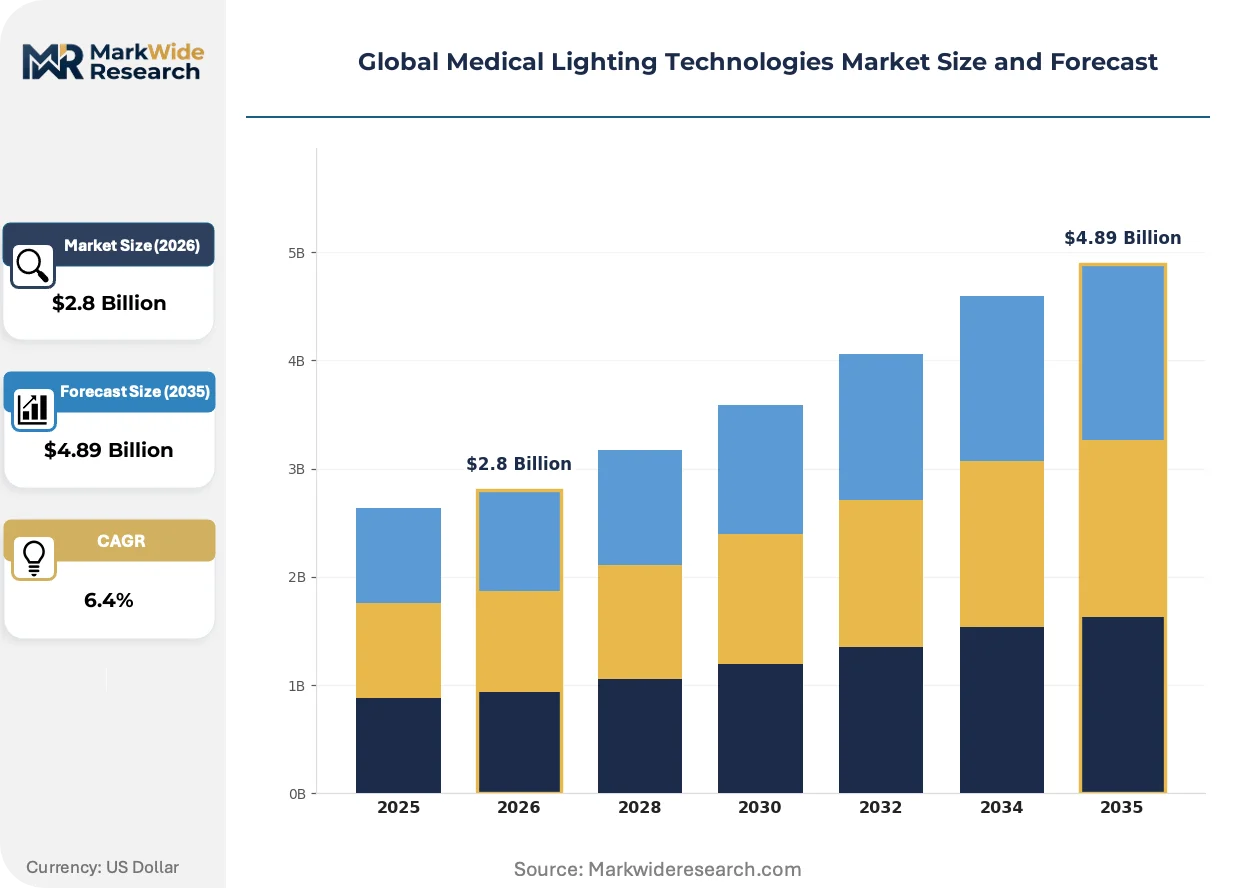
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Lights, Xenon Lamps, Halogen Lamps, Fiber Optic Lights, Fluorescent Lamps Application: Surgical Procedures, Diagnostic Imaging, Patient Examination, Dental Treatments, Veterinary Services End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Centers, Dental Clinics, Veterinary Clinics Deployment: Ceiling-Mounted, Portable Units, Wall-Mounted, Tabletop Fixtures, Mobile Lighting Systems |
| Companies Covered | Koninklijke Philips N.V., General Electric Company, Getinge AB, Eaton Corporation plc, Herbert Waldmann GmbH & Co. KG, Brandon Medical Co. Ltd., KLS Martin Group, Hubbell Incorporated, Zumtobel Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Lighting Technologies Market Shifts & Advancements
Computational lighting control is displacing manual intensity adjustment in surgical workflows. Three developments are compressing product lifecycles and reshaping vendor competitive positions.
Spectral-tunable LED engines is rewriting tissue differentiation capabilities in oncologic resections. Academic medical centers in the United States and Germany are piloting narrow-band illumination for enhanced tumor margin visualization. The technology is compressing the performance gap between standard surgical luminaires and integrated fluorescence imaging systems.
Japan's PMDA electromagnetic compatibility testing protocols are filtering non-domestic suppliers from premium hospital tenders. The expanded EMC requirements for surgical equipment now mandate immunity testing above IEC 60601-1-2 baselines. European and North American manufacturers are establishing Tokyo-based compliance laboratories to maintain access to high-margin procurement channels.
Subscription-based remote diagnostics are unbundling after-sales service from hardware purchase contracts. Ambulatory surgical centers in the United States are adopting predictive maintenance agreements that transfer obsolescence risk to vendors. The model concentrates vendor accountability in high-utilization settings where downtime costs exceed capital amortization schedules.
Global Medical Lighting Technologies Market Segmentation
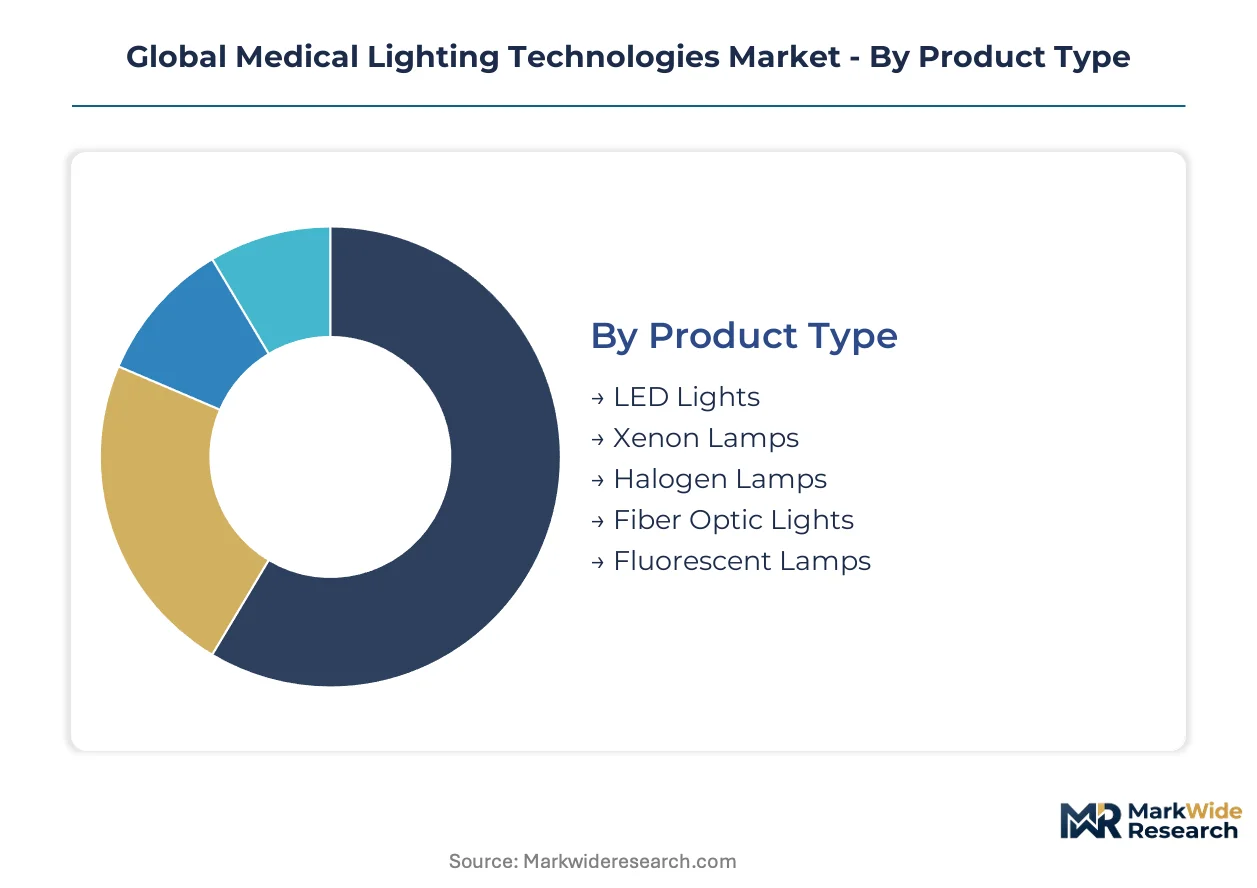
Medical lighting procurement splits across technology generations, clinical settings, and mounting configurations. Each segmentation axis reveals distinct margin structures and replacement dynamics that shape vendor positioning strategies.
Product Type:
LED Lights anchor standalone retrofit demand while Fiber Optic Lights embed into integrated surgical platforms requiring cold light delivery.
- LED Lights:Chip-on-board arrays deliver color-rendering indices exceeding 90 with correlated color temperatures between 3,500K and 5,000K. German hospital infrastructure renewal concentrates demand-pull for surgical suites, though REACH and RoHS restrictions on mercury-containing alternatives accelerate displacement timelines.
- Fiber Optic Lights:Cold light transmission through flexible bundles enables minimally invasive procedures without thermal tissue damage. Japanese hybrid operating room configurations absorb premium fiber-coupled systems where navigation-illumination integration commands workflow value.
- Xenon Lamps:High-intensity arc discharge sources face phase-out pressure under EU mercury restrictions before full amortization of installed endoscope light sources.
- Halogen Lamps:Legacy tungsten-halogen technology retains niche demand in cost-constrained examination settings where color stability requirements remain modest.
- Fluorescent Lamps:Linear and compact fluorescent formats persist in administrative and corridor illumination despite limited surgical adoption due to flicker and color rendering limitations.
Volume placements concentrate in LED Lights; the faster expansion belongs to Fiber Optic Lights in integrated surgical platforms.
Application:
Surgical Procedures extract premium pricing through hybrid operating room configurations while Diagnostic Imaging demands spectral precision for tissue differentiation.
- Surgical Procedures:Precision illumination for open and minimally invasive interventions requires shadow-free beam geometry and adjustable intensity. United States ambulatory surgical center construction absorbs mid-tier LED systems at volume scale, though FDA 510(k) photobiological safety dossiers extend clearance timelines for new entrants.
- Diagnostic Imaging:Spectral-tunable engines enhance tumor margin visualization in oncologic resections through narrow-band illumination. Academic medical centers in Germany pilot fluorescence-compatible luminaires that compress performance gaps with integrated imaging systems.
- Patient Examination:General-purpose illumination for clinical assessment prioritizes cost efficiency and mounting flexibility over surgical-grade specifications.
- Dental Treatments:Task-optimized lighting with focused beam control addresses oral cavity procedures in German-speaking clinical markets where Herbert Waldmann GmbH & Co. KG anchors position.
- Veterinary Services:Cross-adapted surgical and examination luminaires serve companion and livestock veterinary practices with reduced regulatory certification burdens.
Revenue concentration sits with Surgical Procedures; Diagnostic Imaging climbs fastest on spectral-tunable technology adoption.
End User:
Hospitals dominate capital expenditure budgets while Ambulatory Surgical Centers shift procurement toward operational expenditure models.
- Hospitals:Tertiary medical centers in Germany, the United States, and Japan drive infrastructure renewal with integrated imaging-illumination systems. EU MDR photobiological safety mandates under IEC 62471 compel surgical suite retrofits across European installed bases.
- Ambulatory Surgical Centers:United States outpatient facility expansion absorbs standardized LED surgical systems at mid-market price points. Predictive maintenance subscriptions transfer obsolescence risk to vendors where downtime costs exceed capital amortization schedules.
- Diagnostic Centers:Imaging-focused facilities prioritize spectral precision and electromagnetic compatibility compliance for sensitive equipment environments.
- Dental Clinics:Examination and procedure lighting demands task-optimized beam geometry with reduced thermal output for patient comfort.
- Veterinary Clinics:Mixed surgical and general practice settings adopt versatile mounting configurations with simplified control interfaces.
Installed value concentrates in Hospitals; Ambulatory Surgical Centers gain share fastest on subscription-based procurement conversion.
Deployment:
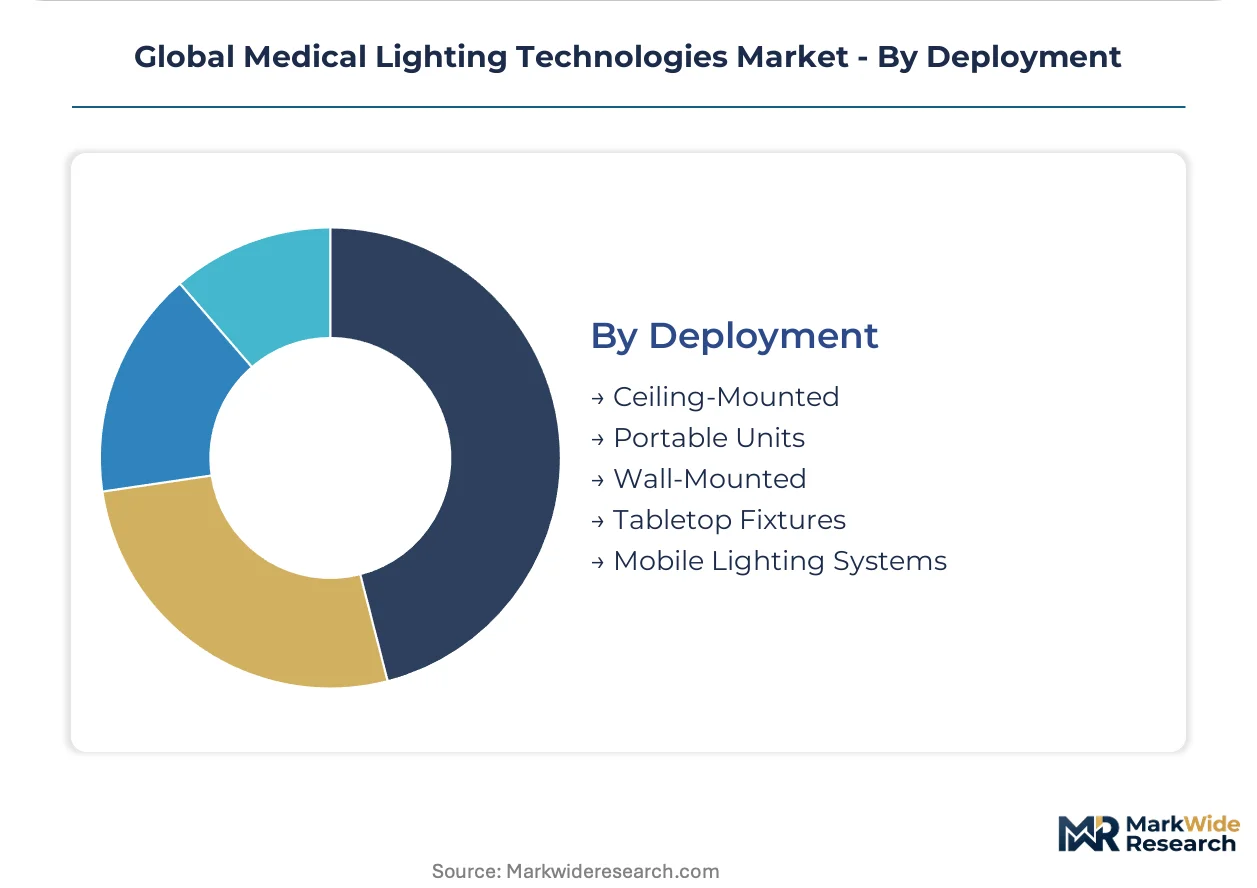
Ceiling-Mounted systems define surgical workflow architecture while Portable Units enable flexible procedure room utilization.
- Ceiling-Mounted:Suspended dual-dome and single-dome configurations dominate operating room construction with centralized power and control integration. Hybrid operating room pipelines in Germany and Japan specify ceiling-integrated imaging-illumination coordination.
- Portable Units:Mobile floor-standing luminaires enable rapid redeployment across procedure rooms and emergency settings. Indian central government health facility expansion programs absorb standardized portable examination lighting at mid-market price points.
- Wall-Mounted:Space-constrained examination and minor procedure rooms utilize articulated arm mounting with reduced floor footprint.
- Tabletop Fixtures:Compact task lighting serves dental, dermatological, and minor surgical applications with localized intensity control.
- Mobile Lighting Systems:Battery-powered and cart-based units address field deployment and disaster response scenarios with reduced infrastructure dependency.
Capital deployment concentrates in Ceiling-Mounted systems; Portable Units expand most quickly on flexible facility design trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of LED chip-on-board arrays and aluminum nitride ceramic substrates concentrates in Japanese and German supplier networks, while hospital infrastructure renewal in the United States, Germany, and Japan absorbs the dominant share of surgical luminaire procurement.
United States
Ambulatory surgical center construction drives mid-tier LED surgical system volumes at scale. FDA 510(k) photobiological safety dossier requirements extend clearance timelines for new market entrants. The Southeast and Southwest corridor absorbs standardized examination lighting through federal health facility expansion programs.
Germany
Tertiary hospital infrastructure renewal concentrates demand-pull for hybrid operating room configurations with integrated imaging-illumination coordination. EU MDR IEC 62471 blue-light hazard assessment mandates compel surgical suite retrofits across installed bases. Baden-Württemberg anchors precision optics fabrication clusters serving luminaire manufacturers.
Japan
PMDA electromagnetic compatibility testing protocols filter non-domestic suppliers from premium hospital tenders. METI-supported domestic semiconductor substrate production secures LED thermal management component supply. The Kanto region around Tokyo hosts compliance laboratories established by European and North American manufacturers.
India
Central government health facility expansion programs absorb standardized portable examination lighting at mid-market price points. BIS certification requirements for medical electrical equipment shape product validation for domestic market entry. Maharashtra and Gujarat concentrate manufacturing operations for cost-optimized LED luminaire assembly.
United Kingdom
NHS infrastructure modernization programs prioritize energy efficiency mandates in surgical suite retrofits. MHRA alignment with EU MDR photobiological safety standards elevates barrier costs for non-compliant hardware. The Southeast and Midlands corridor concentrates private hospital construction absorbing premium ceiling-mounted systems.
Global Medical Lighting Technologies Market Competitive Landscape
Top-tier vendors anchor premium-tier positioning through workflow integration and predictive maintenance contracts, while mid-market specialists compete on standardized product portfolios. The vendor base stratifies across three archetypes: diversified healthcare conglomerates with luminaire-to-platform integration, specialized surgical lighting manufacturers with regional compliance expertise, and component-scale producers serving cost-optimized segments. Dominant competitive moves include predictive maintenance subscription unbundling and Tokyo-based compliance laboratory establishment for PMDA market access.
Within the diversified healthcare technology tier, Koninklijke Philips N.V. and General Electric Company exemplify platform-integrated positioning through luminaire-to-workflow coordination. Herbert Waldmann GmbH & Co. KG represents the specialized manufacturer archetype with task-optimized positioning in German-speaking clinical markets. These three entities occupy distinct competitive vectors: Philips anchors European operating room retrofits, GE sustains installed-base loyalty through service contract structures, and Waldmann concentrates dental and examination lighting specialization.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| General Electric Company |
| Getinge AB |
| Eaton Corporation plc |
| Herbert Waldmann GmbH & Co. KG |
| Brandon Medical Co. Ltd. |
| KLS Martin Group |
| Hubbell Incorporated |
| Zumtobel Group AG |
| Others |
Supply & Pricing Matrix
Tertiary hospital procurement committees in Germany, Japan, and the United States concentrate purchasing power for surgical luminaires, enabling subscription-based pricing models that bundle hardware with predictive maintenance services. This buyer concentration compresses transactional margins while elevating recurring revenue streams for vendors with installed-base loyalty.
Pricing Analysis
Margin tightening in mid-tier LED surgical systems reflects REACH-driven xenon lamp phase-outs and stranded legacy inventory. Pricing stratifies across premium hybrid operating room configurations, standard ceiling-mounted surgical suites, and economy portable examination units. Certification tier under EU MDR IEC 62471 blue-light hazard assessment creates price spreads exceeding fifteen percent between compliant and non-compliant hardware. Ambulatory surgical centers in the United States exhibit highest price sensitivity, while Japanese tertiary hospitals prioritize electromagnetic compatibility certification over unit cost.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Osaka, and Minneapolis serve hub-and-spoke patterns for luminaire assembly and spare parts fulfillment. LED chip-on-board arrays and aluminum nitride ceramic substrates concentrate fabrication in Japanese and German supplier networks. German Baden-Württemberg optics clusters and Tokyo-area semiconductor substrate producers anchor upstream capacity. Single-source vulnerability in thermal management components creates bottleneck exposure. Distribution runs through manufacturer-direct hospital contracts and specialized medical equipment distributors serving ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aluminum nitride ceramic substrate fabrication constraints in Japanese and German supplier networks prop pricing power for vendors with captive thermal management supply. Capacity scarcity in precision optics clusters limits rapid competitor scale-up.
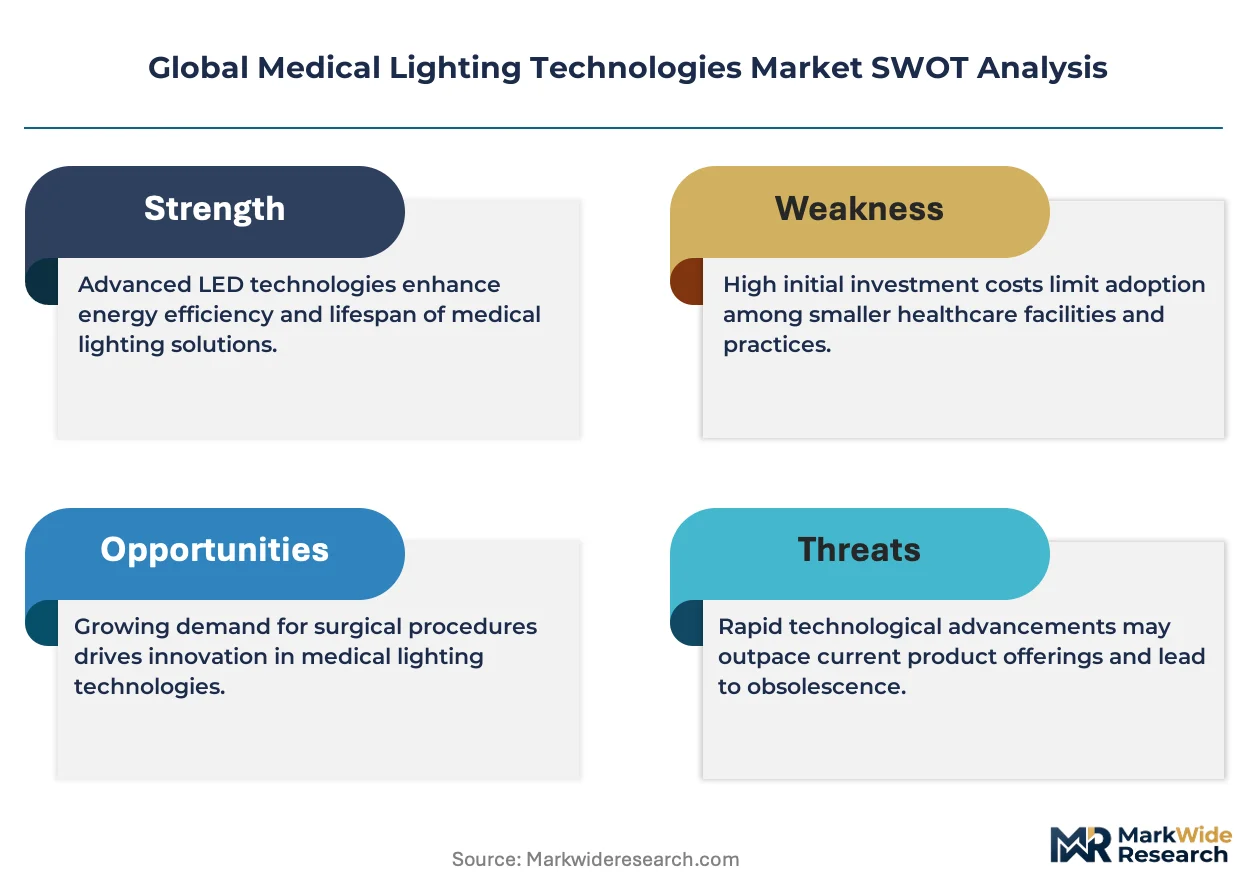
For Market Incumbents: Deepen backward integration into LED thermal substrate supply through partnerships with Osaka-area ceramic fabricators or in-house aluminum nitride capacity additions. Lock in multi-year GPO contracts with United States ambulatory surgical center chains before FDA 510(k) clearance timelines extend further. Software-defined intensity calibration subscriptions defend against mid-tier LED competitors unbundling hardware from service revenue. For New Entrants and Emerging Players: Spectral-tunable LED engines for oncologic margin visualization offer technology-first wedge into academic medical center pilot programs in Germany and the United States. Target Indian central government health facility expansion programs with standardized portable examination lighting at mid-market price points. Pursue BIS certification early to access Maharashtra and Gujarat assembly cost advantages. For Investors and Strategic Acquirers: The window for entry favors specialized surgical lighting manufacturers with regional compliance expertise and established PMDA laboratory access in Tokyo. Long-term viability hinges on workflow integration capabilities with AI-integrated surgical navigation systems. Watch for EU AI Act risk classification framework tightening photobiological safety standards as inflection signal for regulatory-driven replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Tokyo Compliance Laboratory Establishment | PMDA electromagnetic compatibility testing access secures premium Japanese hospital tender participation. |
| Software Companion Development | Remote diagnostics subscriptions reposition capital expenditure into recurring operational budgets. |
| Hospital System Partnership | GPO contracts with United States ambulatory surgical center chains lock in volume placement. |
| CE Marking Pathway Investment | EU MDR IEC 62471 blue-light hazard dossiers elevate barrier costs for non-compliant competitors. |
| Backward Integration into Thermal Substrates | Captive aluminum nitride supply mitigates Japanese-German fabrication concentration risk. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and luminaire manufacturing executives combined with secondary validation from FDA 510(k) clearances, EU MDR technical documentation, and PMDA approval databases. Bottom-up surgical luminaire shipment data and top-down healthcare capital expenditure estimates underwent triangulation across the analysis window.
Data-stream reconciliation merged procurement database tracking with regulatory pathway monitoring and supplier production disclosures. Segmentation modeling spanned technology generation, clinical application, mounting configuration, and end-user facility type across the projection horizon. CAGRs derived from installed-base replacement cycle compression and infrastructure renewal pipeline analysis. Forecast inputs incorporated EU MDR compliance deadline phasing and ambulatory surgical center construction permit data.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PMDA electromagnetic compatibility testing protocol expansion or aluminum nitride substrate supply disruption. Outputs reflect documented assumptions regarding regulatory timeline adherence and hospital capital budget allocation patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Capnography Equipment Market
Medical Equipment
Operating Table Parts Market
Medical Equipment
Electron Beam Linear Accelerators Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
Tanning Units Market
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
Patient Mechanical Lift Handling Equipment Market
Medical Equipment
Asia-Pacific Medical Carts Market
Medical Equipment
Medical Vending Machines Market
Medical Equipment
Global Ultra Low Temperature Freezers Market
Medical Equipment
Global Medical Equipment Calibration Market
Medical Equipment
X-Ray Machine Manufacturing Market
Medical Equipment
Podiatry Equipment Market
Medical Equipment
Global Medical Vacuum System Market