
 Histology Embedding System Market | 2026-2036
Histology Embedding System Market Size, Share, and Industry Trends Forecast 2026-2036
Histology Embedding System Market Analytics
The customer base for histology embedding systems is broadening beyond traditional academic medical centers toward independent diagnostic labs and regional hospital networks. Thermo Fisher Scientific leverages its diagnostic reagent ecosystem to bundle embedding hardware with consumables contracts. Sakura Finetek anchors its position through dense installed bases in Japan and North American reference labs. Leica Biosystems differentiates via vertically integrated digital pathology workflows that connect embedding stations to whole-slide imaging platforms.
A histology embedding system is laboratory equipment that stabilizes processed tissue specimens in molten paraffin or specialized media to create uniform blocks suitable for microtomy sectioning, typically operating at temperatures between 56°C and 62°C with vacuum-assisted infiltration to eliminate air bubbles. Automated systems command the largest revenue share due to labor-cost sensitivity in high-throughput pathology labs, while cryo-embedding units represent the fastest-expanding category as intraoperative consultation volumes rise in oncology centers. Heat block systems remain the mature workhorse technology, though cartridge systems are gaining margin traction through disposable-component recurring revenue models.
FDA device classification and CLIA laboratory certification in the United States shape product validation requirements, while the EU MDR and CE marking framework govern market access across European member states. ISO 13485 quality management standards and IEC 61010-1 electrical safety specifications further constrain supplier qualification for international tenders. Stakeholders must monitor evolving digital pathology interoperability standards and embedding-to-imaging traceability requirements as laboratory information systems deepen integration demands.
Market Dynamics
Workflow integration demands from digital pathology platforms are compressing standalone equipment procurement cycles, forcing embedding system suppliers to prioritize LIS interoperability and specimen traceability over incremental hardware improvements.
Growth Catalysts
- FDA 510(k) clearance streamlining:Expedited pathways for automated tissue-processing equipment accelerate hospital laboratory capital deployment timelines in the United States.
- Intraoperative consultation volumes:Oncology centers in Japan and the United States are expanding cryo-embedding capacity to support frozen-section pathology services.
- Paraffin block standardization:ISO 13485-certified cartridge systems enable reference labs to reduce microtomy preparation variability and improve section quality consistency.
Market Restraints
- Paraffin wax price volatility:Petroleum-derived embedding media costs fluctuate with crude oil benchmarks, compressing consumables margins for high-throughput laboratories.
- EU MDR transition costs:Re-certification requirements for existing CE-marked devices divert R&D resources from next-generation platform development.
- Manual embedding skill retention:Aging histotechnologist workforce in Germany and Japan constrains training pipeline capacity for specialized cryo-embedding techniques.
Strategic Opportunities
- India diagnostic lab consolidation:Corporate chains in Mumbai and Bangalore seek automated embedding platforms to standardize multi-site pathology operations.
- Digital pathology interoperability mandates:DICOM WG-26 standards for specimen metadata create upgrade incentives for labs with legacy embedding stations.
- AI-assisted quality control integration:Machine vision for paraffin block inspection converges with embedding workflows to reduce microtomy failure rates.
Industry Challenges
- CLIA proficiency testing alignment:Embedding system validation must synchronize with CAP laboratory accreditation cycles, extending deployment timelines.
- Legacy LIS integration complexity:Proprietary data formats from 1990s-era laboratory information systems obstruct real-time specimen tracking implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Histology Embedding System Market |
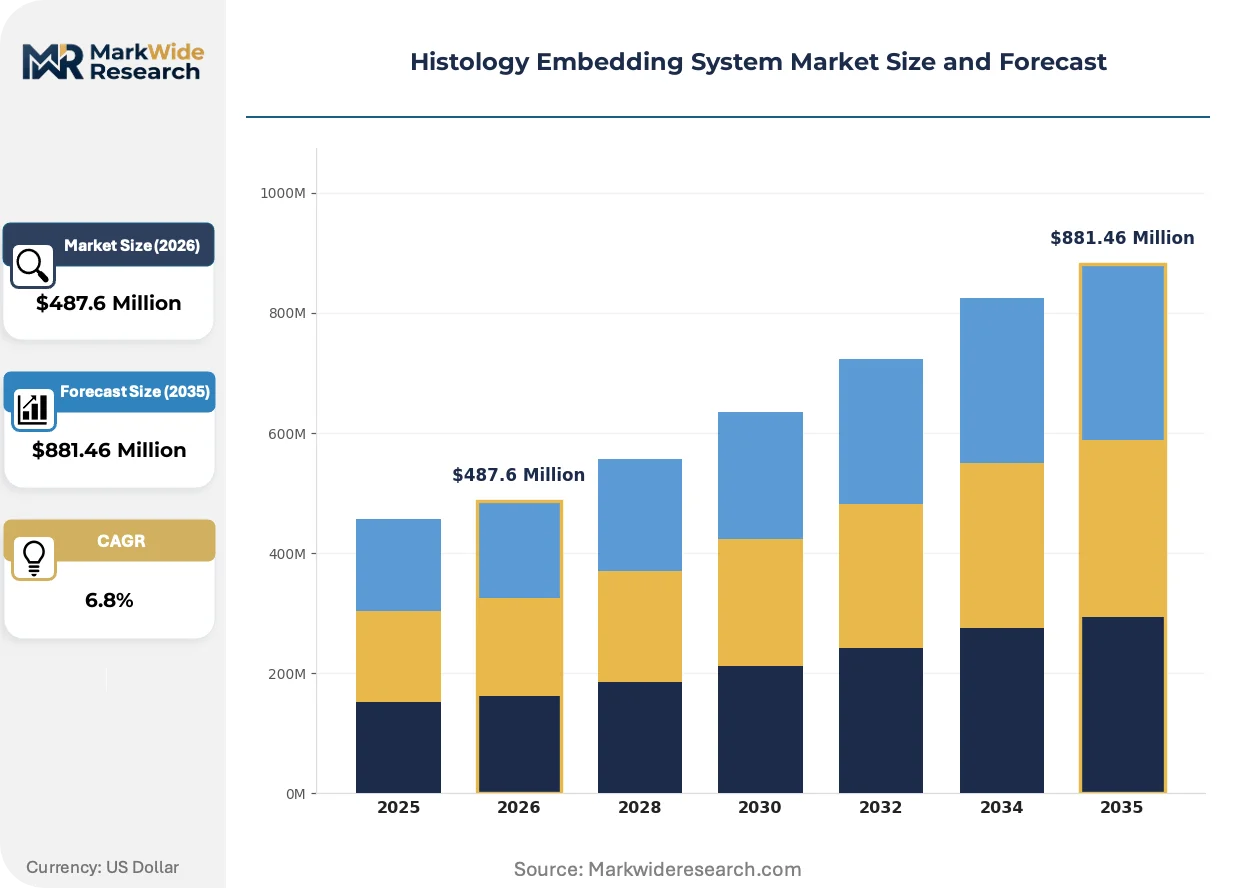
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Embedding Stations, Cryo-Embedding Units, Accessories Technology: Vacuum Embedding, Heat Block Systems, Low-Temperature Systems, Cartridge Systems Application: Research Laboratories, Pathology Labs, Hospital Laboratories, Educational Institutions End User: Diagnostic Labs, Biopharmaceutical Companies, Academic Institutions, Others |
| Companies Covered | Leica Biosystems, Thermo Fisher Scientific, Sakura Finetek, Bio-Optica Milano, Danaher, General Data Healthcare, Medite GmbH, Histo-Line Laboratories, SLEE Medical GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Histology Embedding System Market Evolving Landscape
Specimen throughput pressures and pathologist workforce constraints are accelerating capital rotation toward connected, automated embedding platforms that reduce manual intervention and enable remote quality monitoring.
Vacuum-assisted paraffin infiltration technology is automating air bubble elimination during tissue block preparation, reducing sectioning artifacts that compromise diagnostic accuracy. Academic medical centers in the United States and university hospitals in Germany are prioritizing these systems for high-complexity biopsy workflows. The technology is automating technician time allocation away from manual embedding stations toward specimen triage and quality verification functions.
EU MDR Article 10 technical documentation requirements are mandating enhanced clinical evidence for embedding system safety claims, extending conformity assessment timelines by twelve to eighteen months for manufacturers without prior notified body relationships. German and French pathology equipment distributors report delayed product registrations affecting automated platform introductions. Medium-volume hospital laboratories are extending service contracts on existing CE-marked devices rather than accepting MDR transition uncertainty.
Reagent rental and consumables-bundled procurement models are displacing capital purchase structures for embedding platforms in United States reference pathology networks. Independent diagnostic laboratories in Texas and Florida favor per-block pricing arrangements that align equipment costs with actual specimen volumes. This shift concentrates vendor selection authority within supply chain and finance functions rather than histology department heads.
Histology Embedding System Market Segmentation
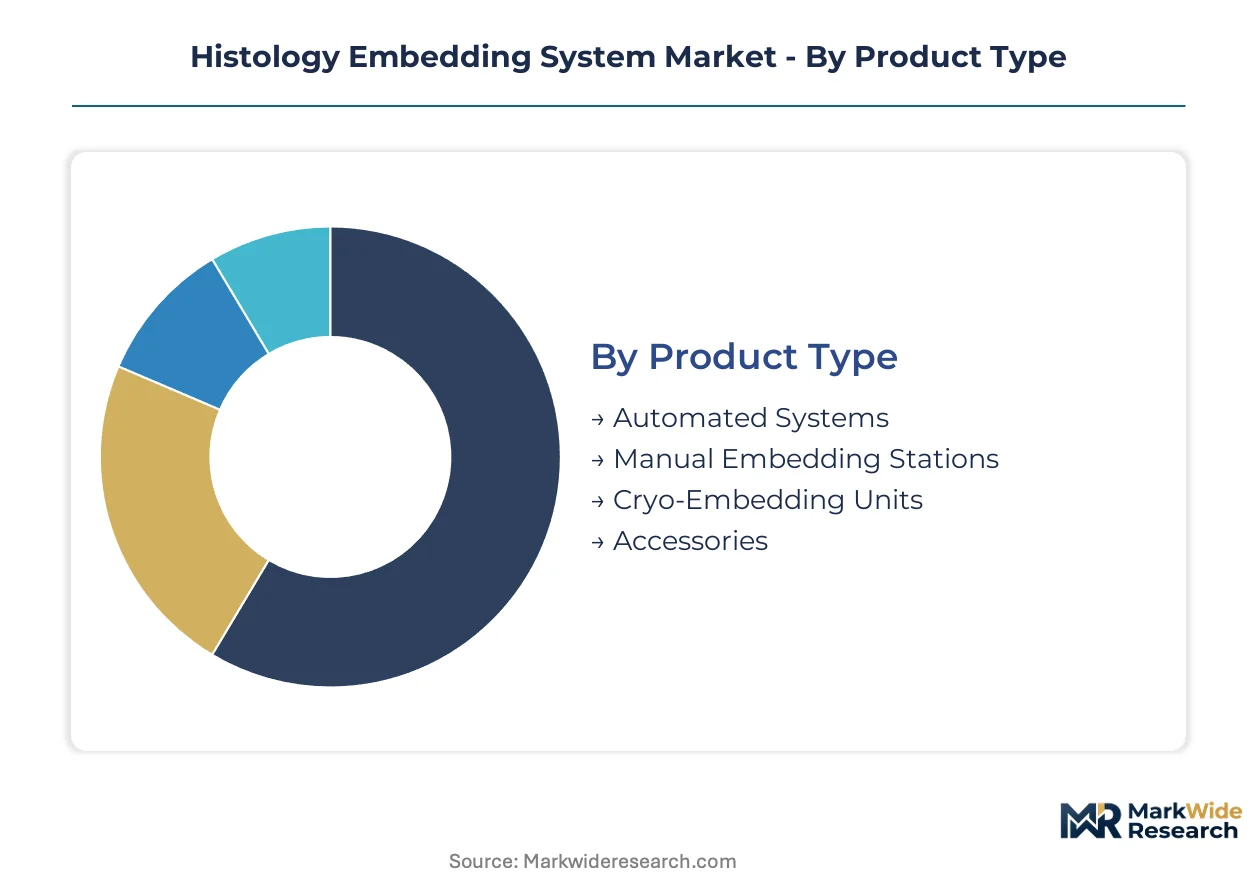
Embedding system procurement patterns diverge sharply between standalone equipment purchases and integrated workflow platforms. Vendors structure pricing and service models around these integration depths, with bundled consumables contracts dominating high-throughput settings while independent labs favor capital-acquisition flexibility.
Product Type:
Standalone automated systems anchor the installed base in high-volume pathology networks, while cryo-embedding units increasingly embed into frozen-section workflow chains.
- Automated Systems:Robotic paraffin dispensing and block cooling modules operate at 56°C to 62°C with programmable infiltration cycles. Hospital laboratories in the United States prioritize these for CLIA-certified high-throughput biopsy processing, though capital budgets tighten during accreditation renewal cycles.
- Cryo-Embedding Units:Rapid freezing platforms using liquid nitrogen or Peltier cooling achieve −20°C to −30°C for intraoperative consultation specimens. Oncology centers in Japan and the United States expand capacity to support frozen-section pathology services as surgical volumes rise.
- Manual Embedding Stations:Heat-controlled work surfaces with forceps-based tissue orientation remain standard in resource-constrained settings and training environments.
- Accessories:Base molds, embedding rings, and forceps constitute recurring consumables purchases tied to block throughput volumes.
Volume placements concentrate in Automated Systems; the faster expansion belongs to Cryo-Embedding Units.
Technology:
Cost tiering separates premium vacuum-assisted platforms from standard heat-block workhorses, with cartridge systems capturing margin through disposable recurring revenue.
- Vacuum Embedding:Pressure-reduced chambers eliminate paraffin air bubbles during tissue infiltration, reducing microtomy sectioning artifacts. Academic medical centers in Germany and the United States specify these for complex biopsy workflows where diagnostic accuracy demands uniform block quality.
- Cartridge Systems:Disposable plastic cassettes with standardized base molds enable block traceability and reduce technician orientation variability. Reference pathology networks favor per-block pricing models that align equipment costs with actual specimen throughput.
- Heat Block Systems:Mature paraffin reservoir technology with gravity-fed dispensing dominates mid-volume hospital laboratories seeking proven reliability.
- Low-Temperature Systems:Specialized cooling platforms for temperature-sensitive specimens and alternative embedding media support research applications outside routine diagnostic workflows.
Revenue concentration sits with Vacuum Embedding installations; Cartridge Systems are gaining share fastest through consumables-bundled procurement structures.
Application:
Customer type determines integration requirements, with pathology labs demanding LIS connectivity while research settings prioritize protocol flexibility over standardization.
- Pathology Labs:Diagnostic facilities processing surgical biopsies and cytology specimens require CAP-aligned quality controls and specimen tracking interoperability.
- Hospital Laboratories:Integrated health system labs coordinate embedding workflows with surgical schedules and frozen-section services.
- Research Laboratories:Academic and commercial R&D facilities utilize specialized embedding media and non-standard protocols for experimental tissue processing.
- Educational Institutions:Histotechnology training programs maintain manual embedding stations to develop core technician competencies.
Capital deployment concentrates in Hospital Laboratories; the steepest expansion trajectory belongs to Pathology Labs consolidating into regional networks.
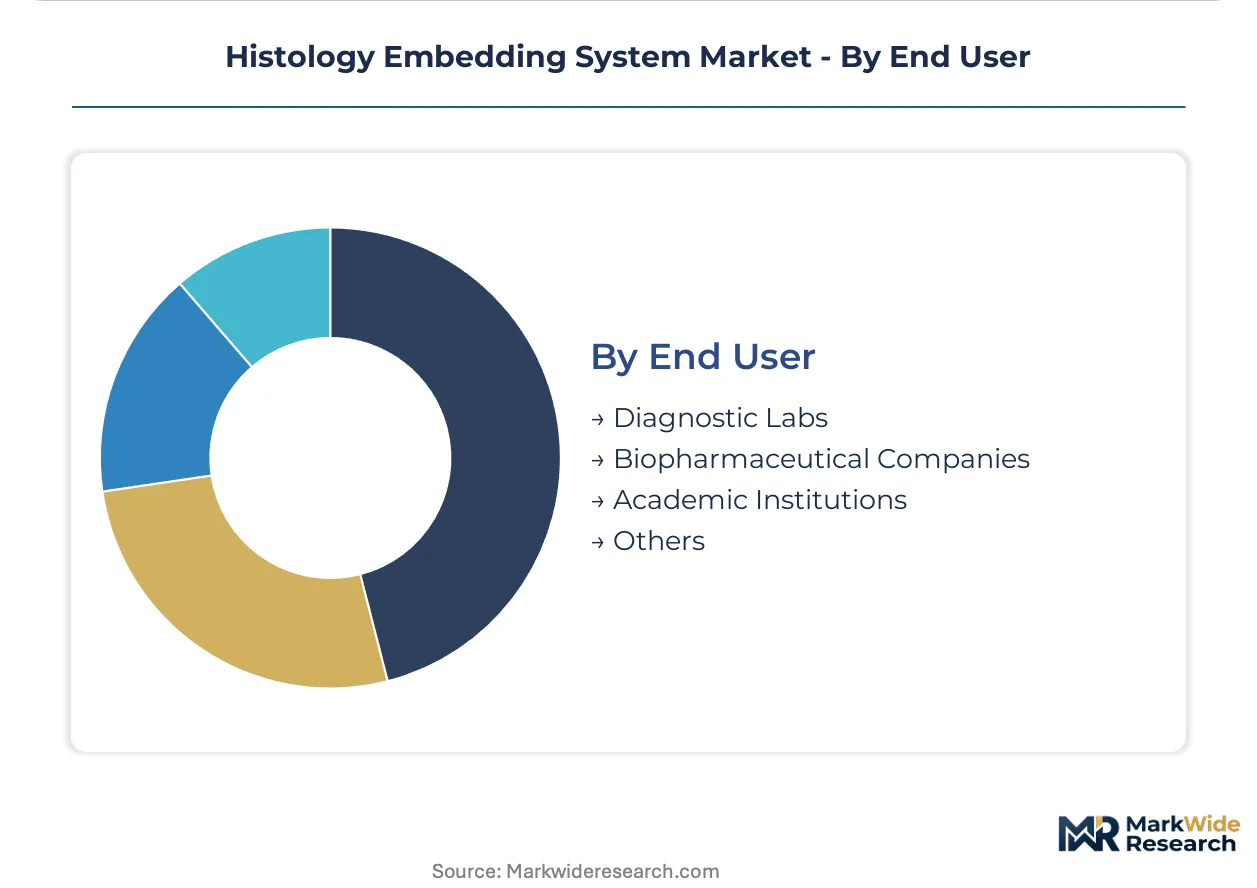
End User:
Procurement authority varies across customer types, with diagnostic chains centralizing equipment decisions while academic settings disperse purchasing to individual departments.
- Diagnostic Labs:Independent and hospital-affiliated reference laboratories drive automated platform adoption through reagent rental and consumables-bundled contracts. Corporate chains in India seek standardization across multi-site operations.
- Biopharmaceutical Companies:Contract research organizations and in-house pathology groups support toxicology studies and clinical trial tissue processing with specialized throughput requirements.
- Academic Institutions:University medical centers balance research protocol diversity with clinical diagnostic service obligations.
- Others:Veterinary pathology services and forensic laboratories constitute niche demand segments with specialized specimen handling requirements.
Equipment placements concentrate in Diagnostic Labs; Biopharmaceutical Companies are expanding capacity fastest to support oncology pipeline tissue analysis demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum-derived paraffin wax feedstocks concentrate in Gulf Coast refining corridors, shaping cost structures for embedding media procurement across diagnostic laboratory networks.
United States
Reference pathology network consolidation drives capital deployment in Texas and Florida, where independent diagnostic laboratories favor consumables-bundled procurement models. FDA 510(k) clearance pathways and CLIA laboratory certification standards tighten performance benchmarks for automated tissue-processing equipment. The Houston-Galveston medical corridor anchors high-throughput biopsy processing infrastructure serving regional cancer centers.
Germany
Aging histotechnologist workforce constraints and EU MDR transition costs compress training pipeline capacity for specialized cryo-embedding techniques. ISO 13485 quality management standards and IEC 61010-1 electrical safety specifications constrain supplier qualification for international tenders. The Baden-Württemberg precision manufacturing cluster hosts pathology equipment distributors reporting delayed product registrations affecting automated platform introductions.
Japan
Oncology centers expand cryo-embedding capacity to support frozen-section pathology services as surgical volumes rise. METI industrial standards and PMDA device regulations govern market access for automated embedding platforms. The Kansai region's university hospitals maintain dense installed bases of embedding systems serving intraoperative consultation workflows.
India
Corporate diagnostic chains in Mumbai and Bangalore seek automated embedding platforms to standardize multi-site pathology operations. CDSCO medical device regulations and BIS certification requirements shape product validation timelines for imported equipment. The Maharashtra pharmaceutical corridor attracts capital investment from reference laboratory networks consolidating regional diagnostic infrastructure.
United Kingdom
NHS pathology service consolidation drives procurement centralization toward automated workflow-integrated platforms. MHRA device regulations and UKCA marking requirements post-Brexit create parallel conformity assessment obligations for embedding system suppliers. The Cambridge-Oxford-London life sciences triangle anchors academic medical center demand for vacuum-assisted infiltration technology.
Histology Embedding System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue consumables-bundled service models and digital pathology interoperability niches. The supplier base concentrates around three to five integrated diagnostic equipment conglomerates with dense installed bases in reference laboratories. Strategic archetypes include vertically integrated reagent-hardware bundlers, standalone automation specialists, and regional service-focused distributors. Competitive moves center on reagent rental contract expansion and MDR transition timing advantages.
Among Germany-based precision equipment fabricators, Leica Biosystems and SLEE Medical GmbH occupy positions within the workflow-integrated systems tier, exemplifying geographic clustering around Baden-Württemberg industrial infrastructure. Thermo Fisher Scientific, a US-based conglomerate, anchors the reagent ecosystem bundling archetype through consumables-contract hardware placement. Sakura Finetek represents the Asia-Pacific reference laboratory specialist position with installed base concentration in Japan and North American markets.
| Leading Market Players |
|---|
| Leica Biosystems |
| Thermo Fisher Scientific |
| Sakura Finetek |
| Bio-Optica Milano |
| Danaher |
| General Data Healthcare |
| Medite GmbH |
| Histo-Line Laboratories |
| SLEE Medical GmbH |
| Others |
Value Network & Pricing Analysis
Aging histotechnologist workforce concentration in Germany and Japan widens pricing-tier spreads between automated vacuum-assisted platforms and manual heat-block systems, as labor-cost differentials force mid-volume hospital laboratories toward reagent-rental contracts that bundle consumables with equipment access.
Pricing Analysis
Volume placements concentrate in automated systems while margin capture belongs to cartridge-based consumables contracts. Pricing stratifies across premium vacuum-assisted platforms, standard heat-block workhorses, and economy-grade manual stations, with ISO 13485 certification tier and after-sales service bundling as primary differentiation drivers. Price erosion runs through petroleum-derived paraffin embedding media as crude oil benchmarks fluctuate. Independent diagnostic laboratories in Texas and Florida exhibit highest price sensitivity through per-block pricing demands, while academic medical centers in Germany and the United States show lowest sensitivity given diagnostic accuracy requirements.
Supply Chain Analysis
Workforce availability constraints in Baden-Württemberg precision manufacturing clusters and Gulf Coast petrochemical corridors shape component lead times for vacuum chamber assemblies and paraffin resin formulations. Supply concentrates in Germany for precision electromechanical subsystems, the United States for control electronics, and Japan for cryo-cooling modules. Raw material dependencies center on petroleum-derived paraffin wax, medical-grade stainless steel, and semiconductor components for temperature control systems. Single-source vulnerability in liquid nitrogen delivery infrastructure for cryo-embedding units poses structural risk. Distribution runs through pathology equipment distributors with dense service networks in reference laboratory corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over consumables supply determines pricing power and customer lock-in, with reagent rental contracts displacing capital purchases across United States reference pathology networks.
For Market Incumbents: Anchor market position by deepening consumables-bundled contract penetration in consolidating diagnostic chains, while accelerating EU MDR technical documentation completion to capture transition-timing advantages over smaller competitors facing twelve-to-eighteen-month conformity assessment delays. Threat from emerging digital pathology interoperability mandates requires embedding-to-LIS integration investment as a defensive priority. For New Entrants and Emerging Players: Enter via cryo-embedding unit specialization targeting oncology centers in Japan and the United States where frozen-section pathology volumes outpace installed base capacity. White-space exists in AI-assisted quality control modules for paraffin block inspection. Go-to-market angle should emphasize DICOM WG-26 standard compliance to exploit legacy system upgrade cycles in mid-volume hospital laboratories. For Investors and Strategic Acquirers: Re-rating potential sits with cartridge system specialists given consumables recurring revenue visibility and per-block pricing model adoption across independent diagnostic laboratories. Long-term viability over a five-to-ten-year window favors targets with dense installed bases in cancer center consolidations. Signal to watch is CAP laboratory accreditation cycle timing as procurement freeze periods create distressed asset opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Consumables-Bundled Contract Expansion | Reagent rental models align Thermo Fisher Scientific equipment costs with actual block throughput volumes. |
| EU MDR Conformity Acceleration | Early notified body relationships enable Leica Biosystems to capture market share from delayed competitors. |
| Cryo-Embedding Capacity Buildout | Sakura Finetek expansion in Kansai region university hospitals serves rising intraoperative consultation demand. |
| Digital Pathology Interoperability Investment | DICOM WG-26 standard compliance creates upgrade incentives for legacy embedding station replacements. |
| India Diagnostic Chain Standardization | Corporate laboratory consolidation in Mumbai and Bangalore drives multi-site automated platform procurement. |
Research Methodology
SEC 10-K filings, FDA 510(k) clearance databases, and EU MDR technical documentation repositories formed the secondary backbone, supplemented by trade data from pathology equipment distributors and hospital procurement records. Primary interviews with histotechnology laboratory directors, biomedical equipment procurement managers, GPO contracts specialists, and pathology informatics officers validated installed base estimates and replacement cycle assumptions. Bottom-up triangulation across product-type shipment data and top-down reconciliation against health system capital expenditure disclosures anchored market size estimates.
Historical trendline analysis across automated system placements, cryo-embedding unit expansions, and consumables throughput established baseline growth patterns. The forecast framework modeled technology-type substitution dynamics, application-segment integration depth, and end-user procurement authority shifts. CAGRs derived from segment-level volume projections weighted by pricing-tier mix. Industry-specific inputs included CLIA laboratory certification renewal cycles, CAP accreditation timelines, and paraffin wax commodity price correlation coefficients.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR transition delays or petroleum price volatility scenarios. Forecasts reflect documented assumptions regarding pathology workforce retirement rates and digital pathology platform adoption curves. Material deviation in FDA clearance timelines or diagnostic laboratory consolidation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Gas Analyzer Market
Medical Equipment
Defibrillator Analyzers Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market
Medical Equipment
Global Medical Lasers Market
Medical Equipment
Middle East and Africa Thermal Cyclers Market
Medical Equipment
Medical Pediatric Bed Market
Medical Equipment
Global Bone Densitometer Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
Global Emergency Medical Equipment Market
Medical Equipment
Medical Gas Equipment Market
Medical Equipment
Marijuana Drying and Curing Equipment Market
Medical Equipment
Tissue Processing Systems Market
Medical Equipment
Cryochambers Market
Medical Equipment
Global Laminar Airflow Cabinets Market
Medical Equipment
Operating Table Market
Medical Equipment
Urodynamics Equipment and Disposables Market