
 Pulmonology Lasers Market | 2026-2036
Pulmonology Lasers Market Size, Share, and Industry Trends Forecast 2026-2036
Pulmonology Lasers Market Analytics
Equipment leasing and pay-per-procedure models are tilting competitive dynamics toward asset-light entrants that lack balance-sheet capacity for capital purchases. Olympus Corporation leverages its endoscopy installed base to bundle laser consoles with bronchoscope contracts. IPG Photonics Corporation anchors its position through in-house fiber production and diode pump source manufacturing. Lumenis Ltd differentiates via specialized airway handpieces and training certification programs.
Pulmonology lasers are medical-grade coherent light systems operating at wavelengths from visible argon lines through mid-infrared CO2 emission, designed for precise tissue vaporization, coagulation, or resection within the tracheobronchial tree via flexible or rigid bronchoscopic delivery. Nd:YAG lasers at 1064 nm penetrate several millimeters for tumor debulking, while CO2 lasers at 10600 nm provide superficial cutting with minimal thermal spread for stenosis management. Diode lasers now lead volume shipments due to compact footprint and lower cooling requirements, though CO2 systems command premium pricing in airway stenosis cases where precision margins justify higher per-procedure costs. Fiber optic delivery technology dominates clinical preference for flexible bronchoscopy compatibility, while solid-state platforms sustain growth through improved pulse control algorithms.
The FDA 510(k) premarket notification process and EU MDR conformity assessment shape product development timelines and clinical evidence requirements for airway laser manufacturers. ISO 13485 quality management certification and IEC 60601-1-3 electromagnetic compatibility standards gate market access across developed jurisdictions. Stakeholders must monitor reimbursement coding decisions for interventional bronchoscopy procedures, as these determine hospital capital allocation cycles and equipment replacement timelines.
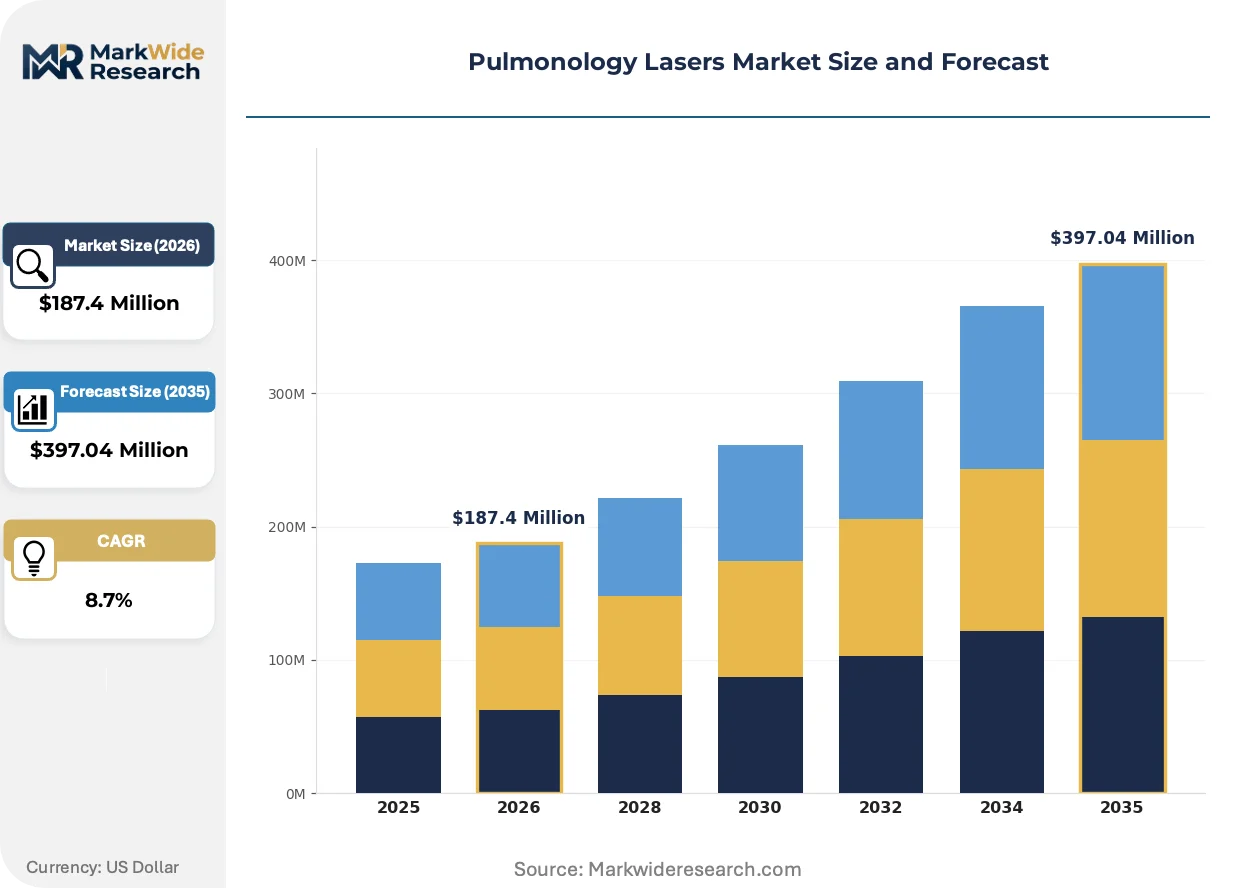
Market Dynamics
Equipment leasing and pay-per-procedure models are compressing capital allocation cycles for interventional pulmonology departments, tilting procurement authority toward clinical service lines and away from centralized hospital supply chains.
Growth Catalysts
- FDA 510(k) Clearance Pathway:The streamlined premarket notification process accelerates commercialization timelines for diode laser platforms, enabling faster clinical validation cycles than PMA-track devices.
- COPD Screening Volumes:Rising early-detection programs in tertiary hospitals across the United States and Germany generate procedural demand for airway stenosis management.
- Fiber Optic Delivery:Advances in flexible bronchoscope compatibility expand addressable procedure volumes beyond rigid bronchoscopy suites.
Market Restraints
- Capital Intensity:CO2 laser systems require substantial upfront investment in precision cooling infrastructure and dedicated procedure rooms.
- Supply Concentration:High-purity germanium-doped silica fiber for Nd:YAG delivery depends on a limited supplier base concentrated in East Asia.
- EU MDR Conformity Assessment:The tightened clinical evidence requirements for Class IIb medical devices extend product development timelines by 18-24 months.
Strategic Opportunities
- Japan's Aging Demographics:Underpenetrated interventional pulmonology infrastructure in regional Japanese hospitals creates whitespace for compact diode platforms.
- Teleproctoring Integration:Real-time remote guidance during laser bronchoscopy procedures enables training scalability and geographic expansion of specialist expertise.
- IRA Hospital Infrastructure Funding:United States federal investment in rural healthcare facilities creates procurement windows for mid-tier laser systems.
Industry Challenges
- Interventional Pulmonology Fellowship Pipeline:The limited annual graduation rate of laser-trained specialists constrains procedure volume growth in community hospital settings.
- ISO 13485 Certification Burden:Small manufacturers face disproportionate quality management system maintenance costs relative to revenue scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulmonology Lasers Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Lasers, CO2 Lasers, Nd:YAG Lasers, Argon Lasers End User: Hospitals, Clinics, Diagnostic Centers, Ambulatory Surgical Centers Application: Bronchoscopic Procedures, Tumor Ablation, Airway Management, Tissue Resecation Technology: Fiber Optic, Gas Laser, Solid State, Pulse Laser |
| Companies Covered | Coherent Corp., IPG Photonics Corporation, Lumenis Ltd, Cynosure Inc., Candela Corporation, Olympus Corporation, Quanta System, Fotona LLC, Han's Laser Technology Industry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulmonology Lasers Market Evolving Landscape
Clinical workflow integration and wavelength tunability are compressing the gap between diagnostic bronchoscopy and therapeutic intervention, eliminating staging delays that previously required separate procedure scheduling.
Diode laser platforms operating at 980 nm and 1470 nm are collapsing the performance gap with legacy Nd:YAG systems for tumor debulking applications. Tertiary hospitals in Germany and the United States are adopting these compact units for dual-purpose airway and gastrointestinal procedures. The footprint reduction is collapsing dedicated laser suite requirements, enabling installation in standard bronchoscopy procedure rooms.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up data collection for airway ablation devices. Manufacturers must now maintain vigilance systems tracking device performance across the product lifecycle. Class IIb laser systems face the steepest compliance burden, with notified bodies demanding expanded clinical evaluation reports.
Service contract unbundling is separating hardware ownership from maintenance and training obligations. Hospital procurement departments in Japan and the United States are negotiating à carte support packages rather than comprehensive multi-year agreements. This shift is most pronounced in academic medical centers with in-house biomedical engineering capabilities.
Pulmonology Lasers Market Segmentation
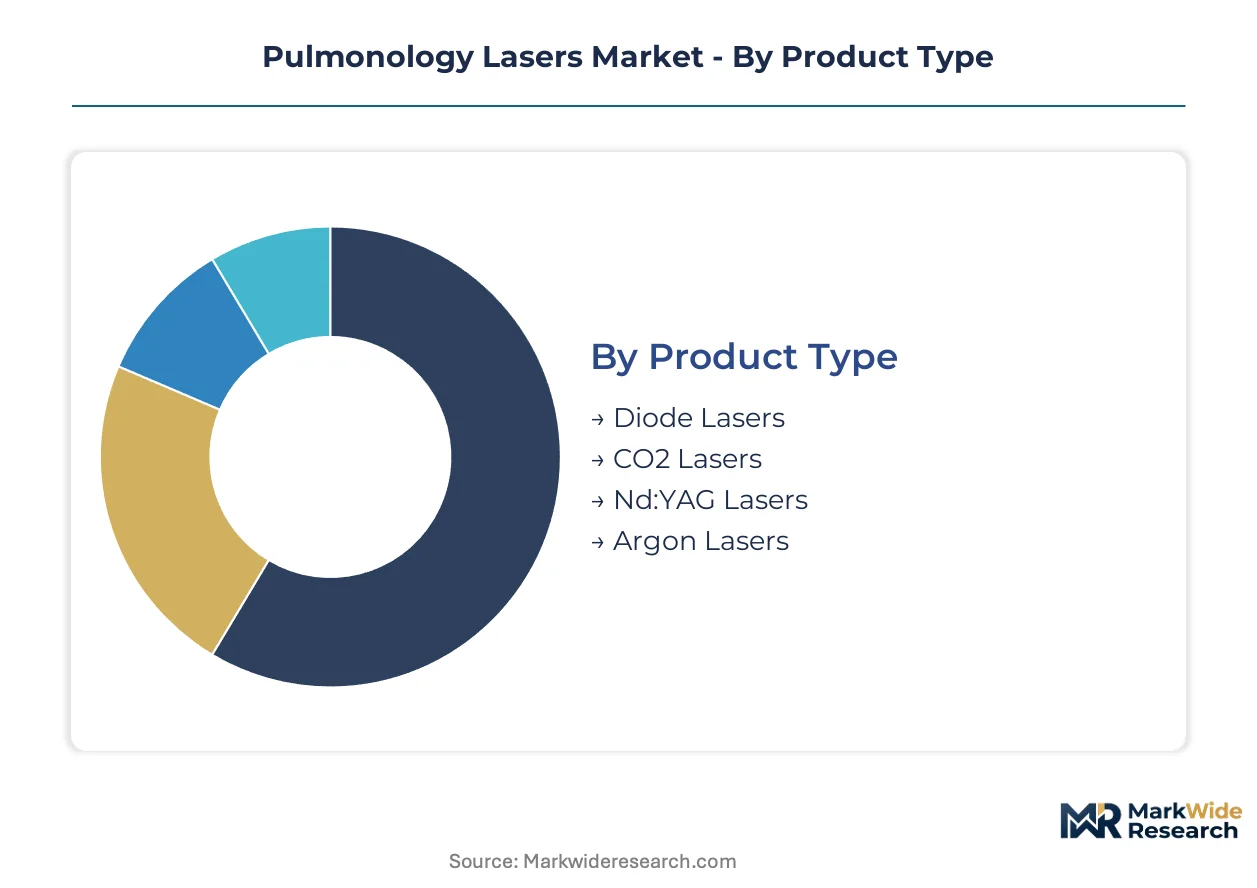
Segmentation in the pulmonology lasers market reveals distinct service intensity profiles across product tiers. After-sales support requirements vary dramatically between compact diode platforms and precision CO2 systems, reshaping vendor-customer relationships and contract structures.
Product Type:
After-sales-service intensity diverges sharply across laser architectures, with cooling-dependent platforms demanding dedicated field engineering contracts while solid-state alternatives shift toward remote diagnostics.
- Diode Lasers:Compact semiconductor platforms operating at 980 nm and 1470 nm wavelengths deliver tumor debulking and coagulation through flexible bronchoscope-compatible fiber delivery. Demand clusters in tertiary hospitals across Germany and the United States seeking dual-purpose airway and gastrointestinal capabilities without dedicated laser suite infrastructure. By volume, Diode Lasers leads. By growth pace, CO2 Lasers is ahead.
- CO2 Lasers:Gas laser systems emitting at 10600 nm provide superficial cutting with minimal thermal spread for tracheal stenosis management. Premium pricing persists in United States academic medical centers where precision margins justify per-procedure cost premiums and dedicated procedure room investments.
- Nd:YAG Lasers:Solid-state platforms at 1064 nm penetrate several millimeters for tumor debulking in rigid bronchoscopy suites.
- Argon Lasers:Visible wavelength systems occupy niche photodynamic therapy activation roles in specialized oncology centers.
Service contract structures favor diode platforms in capital-constrained settings while CO2 systems retain premium positioning where clinical precision demands justify infrastructure investment.
End User:
Procurement authority is decentralizing from hospital supply chains toward clinical service lines, with interventional pulmonology departments gaining direct budget control over laser acquisitions.
- Hospitals:Tertiary institutions with dedicated interventional pulmonology departments anchor equipment demand, particularly in Japan where aging demographics expand airway stenosis caseloads. Academic medical centers in the United States negotiate unbundled service contracts leveraging in-house biomedical engineering capabilities.
- Clinics:Outpatient pulmonology practices in Germany adopt leased diode platforms for pay-per-procedure models that eliminate capital balance-sheet burden.
- Diagnostic Centers:Imaging-integrated facilities in the United States deploy compact lasers for same-session diagnostic-therapeutic workflows.
- Ambulatory Surgical Centers:Freestanding procedural facilities represent emerging demand nodes as reimbursement coding stabilizes for outpatient bronchoscopic interventions.
Hospital procurement maintains volume leadership while ambulatory settings expand most quickly through regulatory alignment with outpatient procedure reimbursement.
Application:
Clinical workflow integration is collapsing staging delays between diagnostic bronchoscopy and therapeutic intervention, eliminating separate procedure scheduling for select indications.
- Bronchoscopic Procedures:Flexible and rigid airway interventions encompass stenosis dilation, foreign body removal, and benign stricture management across United States tertiary centers with fellowship-trained specialist coverage.
- Tumor Ablation:Malignant airway obstruction debulking concentrates in Germany and Japan where screening programs generate early-stage intervention candidates.
- Airway Management:Tracheal and bronchial patency restoration addresses post-intubation stenosis and granulation tissue in long-term ventilated patients.
- Tissue Resection:Precision excision of benign lesions and pre-malignant changes leverages CO2 laser superficial cutting characteristics.
Bronchoscopic procedures dominate current procedural volume while tumor ablation gains share fastest through early-detection program expansion.
Technology:
Delivery mechanism selection determines compatibility with existing endoscope fleets and influences training requirements for interventional pulmonology staff.
- Fiber Optic:Flexible silica-based delivery dominates clinical preference for compatibility with standard bronchoscope working channels, enabling bedside and outpatient procedures without rigid suite requirements.
- Gas Laser:CO2 and argon platforms require articulated arm or rigid waveguide delivery, constraining deployment to dedicated laser suites with specialized ventilation.
- Solid State:Nd:YAG and emerging diode-pumped alternatives sustain growth through improved pulse control algorithms and reduced cooling infrastructure demands.
- Pulse Laser:Q-switched and mode-locked platforms enable precise tissue interaction control for select ablative applications in research-oriented centers.
Fiber optic technology leads by installed base while solid-state platforms climb fastest through footprint reduction and thermal management improvements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of pulmonology laser systems concentrate from German and United States manufacturing clusters toward tertiary hospitals in Japan and emerging procurement nodes in Saudi Arabia. Import dependency for high-purity silica fiber delivery systems creates supply vulnerability for Nd:YAG platform operators across European and North American installed bases.
United States
Academic medical centers in Boston and Houston anchor equipment demand through interventional pulmonology fellowship programs. FDA 510(k) clearance pathways accelerate commercialization timelines for diode laser platforms relative to PMA-track alternatives. The Southeast cluster spanning Atlanta and Nashville expands bronchoscopic laser capacity through IRA-funded rural hospital infrastructure investments.
Germany
COPD screening program expansion in Bavaria and North Rhine-Westphalia generates procedural volume for airway stenosis management. EU MDR conformity assessment requirements extend product development timelines by 18-24 months for Class IIb laser systems. The Baden-Württemberg precision manufacturing belt supplies cooling infrastructure components for CO2 laser installations across European tertiary centers.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas expand caseloads for tracheal stenosis intervention. PMDA regulatory review processes align with international standards while maintaining distinct clinical evidence requirements for airway ablation devices. Regional hospitals in Kyushu and Hokkaido represent underpenetrated whitespace for compact diode platform deployment.
China
NMPA medical device registration reforms streamline market entry pathways for imported laser bronchoscopy systems. Yangtze River Delta hospital clusters in Shanghai and Hangzhou prioritize fiber optic delivery platforms compatible with existing flexible bronchoscope fleets. Domestic diode laser manufacturing capacity expands in Shenzhen and Suzhou industrial zones.
Saudi Arabia
SFDA regulatory harmonization with international standards accelerates procurement cycles for tertiary hospital equipment. Vision 2030 healthcare privatization initiatives expand interventional pulmonology infrastructure in Riyadh and Jeddah medical cities. Eastern Province oil industry health networks invest in occupational lung disease screening and therapeutic intervention capabilities.
Pulmonology Lasers Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in fiber production and diode pump source manufacturing. The vendor base organizes around three archetypes: diversified medical technology conglomerates bundling laser consoles with endoscope contracts, pure-play laser manufacturers competing on wavelength portfolio breadth, and component suppliers capturing value through captive fiber supply. Consolidation pressure concentrates among mid-tier diode platform manufacturers lacking installed base scale to support unbundled service contract economics. Strategic moves center on backward integration into fiber production and geographic expansion through distributor partnerships in underpenetrated Asian markets.
Among diversified platform integrators, Olympus Corporation exemplifies the bundled-system archetype through endoscopy installed base leverage. IPG Photonics Corporation anchors the component-specialist tier through in-house fiber and pump source manufacturing. Lumenis Ltd occupies a differentiated position within the pure-play laser manufacturer category. These three entities represent distinct competitive vectors without implying specific market share or strategic priority claims.
| Leading Market Players |
|---|
| Coherent Corp. |
| IPG Photonics Corporation |
| Lumenis Ltd |
| Cynosure Inc. |
| Candela Corporation |
| Olympus Corporation |
| Quanta System |
| Fotona LLC |
| Han's Laser Technology Industry Group |
| Others |
Value Network & Pricing Analysis
East Asian germanium-doped silica fiber production anchors margin capture for Nd:YAG delivery systems, concentrating value upstream while diode platform assemblers compete on assembly cost and service bundling downstream.
Pricing Analysis
Hospital procurement committees anchor three-tier pricing structure across premium, standard, and economy levels for pulmonology laser systems. CO2 platforms command premium positioning through precision cooling infrastructure and dedicated suite requirements, while compact diode units compete on capital efficiency and pay-per-procedure flexibility. Pricing pressure stems from equipment leasing proliferation that collapses upfront revenue recognition and extends payback periods. Community hospitals exhibit highest price sensitivity due to constrained capital allocation cycles, whereas academic medical centers prioritize clinical performance metrics over acquisition cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for fiber optic delivery components and solid-state laser pump sources. Manufacturing concentration in Germany, Japan, and China feeds system assembly operations across North American and European markets. High-purity silica fiber, precision optical coatings, and semiconductor diode arrays constitute critical input dependencies. Single-source vulnerability persists for specialized germanium-doped fiber drawing capacity. Distribution runs through authorized medical device distributors with field service engineering capabilities rather than direct hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiofrequency ablation and cryotherapy platforms threaten procedural share for laser bronchoscopy, forcing incumbents to defend wavelength-specific clinical advantages through outcome documentation and training ecosystem investment.
For Market Incumbents: Entrench installed base leverage through backward integration into fiber production and captive diode pump source manufacturing. Lock hospital procurement committees into unbundled service contracts that separate hardware ownership from maintenance obligations. Defend against RF ablation substitution by expanding fellowship training program sponsorship and real-world outcome registry participation. For New Entrants and Emerging Players: Pursue regional Japanese hospitals in Kyushu and Hokkaido where interventional pulmonology infrastructure remains underpenetrated and compact diode platforms address space constraints. Target ambulatory surgical centers in United States markets where reimbursement coding stabilization enables outpatient bronchoscopic volume growth. Differentiate through teleproctoring-enabled training scalability that collapses specialist geographic concentration barriers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across compact diode laser sub-segments as semiconductor manufacturing scale effects compress component costs. Long-term viability favors platform integrators with endoscopy installed base leverage over pure-play laser manufacturers lacking channel control. Monitor FDA 510(k) clearance velocity and EU MDR notified body backlogs as inflection signals for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Streamlined premarket pathways compress commercialization timelines for diode platforms against PMA-track alternatives. |
| EU MDR Conformity Investment | Expanded clinical evaluation reports for Class IIb devices extend development cycles but raise competitive barriers. |
| Hospital System Partnership | Bundled bronchoscope-laser contracts with Olympus Corporation leverage endoscopy installed base dominance. |
| Teleproctoring Platform Development | Real-time remote guidance collapses training scalability constraints and expands specialist geographic reach. |
| Reimbursement Strategy Alignment | CPT coding stability for interventional bronchoscopy determines hospital capital allocation and equipment replacement cycles. |
Research Methodology
A spread of perspectives from interventional pulmonologists, hospital purchasing committee chairs, biomedical engineering directors, and GPO contracts managers converged on the working assumptions shaping demand forecasts. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement coding decisions. Bottom-up procedure volume modeling and top-down equipment shipment triangulation anchored value estimates across the analysis window.
Demand-supply balance dynamics shaped the analytical framework, with segmentation across laser architecture, delivery technology, end-user facility type, and clinical application. CAGRs derived from installed base growth rates, replacement cycle compression, and procedure volume elasticity to screening program expansion. Forecast inputs incorporated COPD early-detection program rollout schedules, fellowship training pipeline graduation rates, and regulatory clearance velocity differentials between diode and solid-state platforms.
The forecast holds incumbent behavior within observed patterns; aggressive moves by RF ablation system manufacturers or cryotherapy platform entrants would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Transseptal Access Systems Market
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
Ablation Devices Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Medical Device Validation and Verification Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Global Handheld Bladder Scanner Market
Medical Devices
Global Vertebral Compression Fracture Devices Market
Medical Devices
Arthroscopy Visualization Systems Market
Medical Devices
Buccal Drug Delivery System Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
High Viscosity Bone Cement Market
Medical Devices
Asia-Pacific Integrated Operating Room System Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
Digital Flexible Ureteroscopes Market