
 Global Robotic Wheelchairs Market | 2026-2036
Global Robotic Wheelchairs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Robotic Wheelchairs Market Foresight
Lithium-ion battery packs are rebalancing cost structures against legacy lead-acid systems across the Global Robotic Wheelchairs Market. Permobil AB leverages Scandinavian manufacturing scale to dominate premium power-assisted configurations. WHILL Inc. differentiates through compact AI-enabled chassis designs optimized for dense urban corridors. Ottobock SE & Co. KGaA anchors European distribution through rehabilitation clinic partnerships and physical therapy clinic networks.
Robotic wheelchairs integrate motorized drive systems with sensor arrays, microprocessor-controlled navigation algorithms, and adjustable seating platforms to deliver autonomous or semi-autonomous mobility assistance for users with impaired locomotor function. These devices typically incorporate obstacle-detection lidar, gyroscopic stabilizers, and programmable speed thresholds measured in meters per second to ensure safe operation across indoor and outdoor environments. Power-assisted and AI-enabled segments command the dominant margin pools as elderly care facilities prioritize equipment that reduces caregiver dependency. Neurodegenerative disorder applications represent the fastest-expanding demand category, driven by amyotrophic lateral sclerosis and Parkinson's disease patient cohorts requiring predictive pathing capabilities.
The FDA governs Class II medical device clearance for robotic wheelchairs in the United States, while the EU Medical Device Regulation mandates CE marking and clinical evaluation reports for market access across European member states. Japan's PMDA enforces QMS Ministerial Ordinance standards that shape product development timelines for manufacturers targeting East Asian distribution. Stakeholders must monitor evolving reimbursement codes from Medicare and national health insurers, as coverage determinations for autonomous navigation features will dictate adoption velocity in institutional purchasing channels.
Market Dynamics
Lithium-ion battery chemistry is compressing total cost of ownership against lead-acid legacy systems, while METI's streamlined medical device certification in Japan accelerates sensor-based unit approvals for rehabilitation centers.
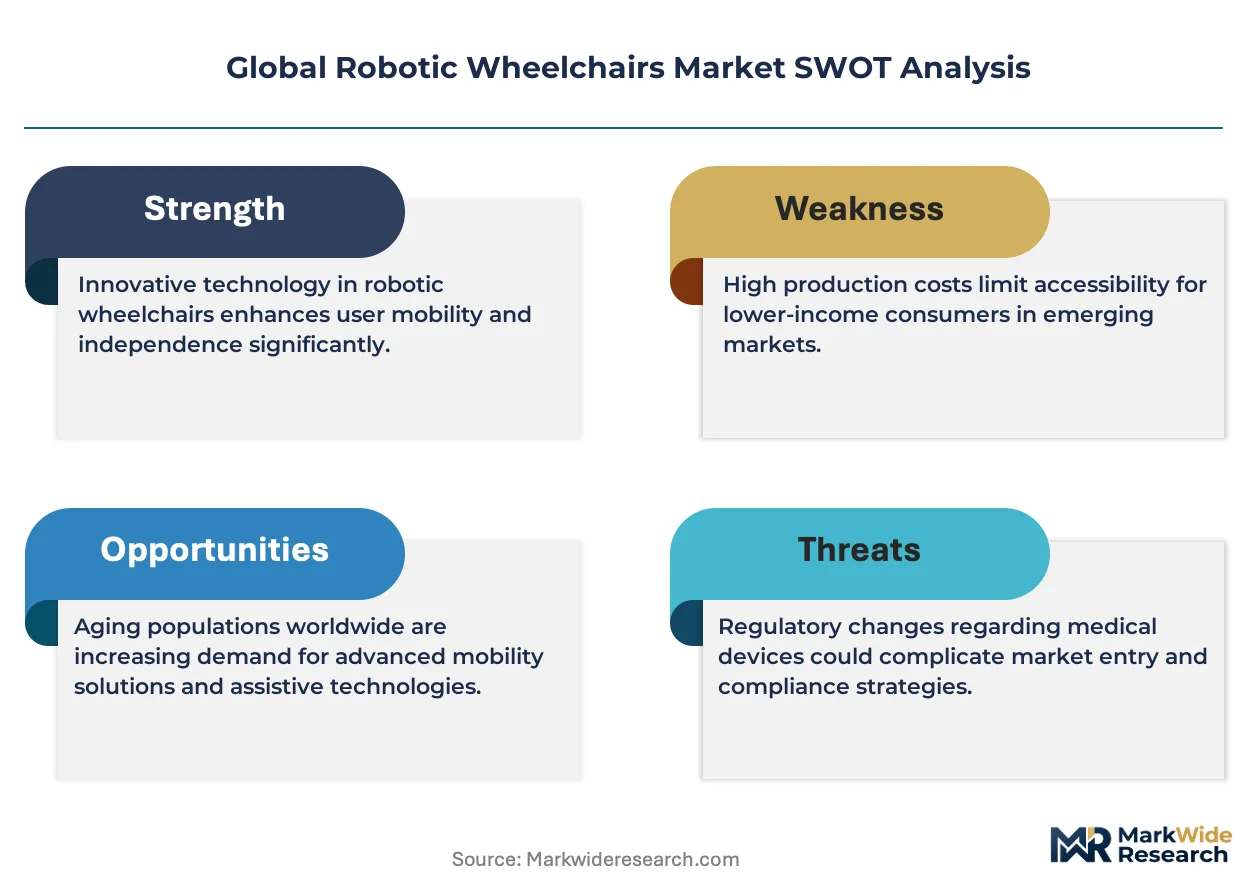
Growth Catalysts
- Sensor Array Proliferation:Lidar and gyroscopic stabilizer integration enables predictive pathing for neurodegenerative patient cohorts, expanding addressable need in amyotrophic lateral sclerosis care protocols.
- EU Medical Device Regulation:MDR-mandated clinical evaluation reports create standardized quality benchmarks that reduce buyer due diligence friction across European institutional procurement channels.
- German Manufacturing Clusters:Dense supplier networks around rehabilitation equipment specialists compress component lead times and enable rapid prototyping of power-assisted configurations.
Market Restraints
- Lithium Supply Concentration:Cathode material processing dependence on East Asian refining capacity exposes battery pack costs to geopolitical supply shocks and freight volatility.
- FDA Class II Clearance Timelines:Premarket notification requirements for autonomous navigation features extend product launch windows by 12-18 months versus conventional power wheelchairs.
- Caregiver Substitution Economics:Semi-autonomous units priced at premium tiers face resistance from Medicaid-reimbursed facilities where labor arbitrage remains cost-competitive.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for medical electronics manufacturing offer tariff-advantaged export platforms targeting Middle East and Southeast Asian distribution.
- AI-Enabled Chassis Convergence:Integration of compact neural navigation with adjustable seating platforms opens dense urban corridor applications previously excluded by footprint constraints.
- Medicare Reimbursement Expansion:Proposed coverage determinations for autonomous navigation features in skilled nursing facilities would unlock institutional purchasing velocity.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for real-time obstacle processing competes with automotive and drone sectors for specialized skill pools in Scandinavia and Germany.
- Legacy Infrastructure Integration:Retrofitting AI-enabled units into existing elevator systems and doorway specifications in aged care facilities demands costly site-specific customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Robotic Wheelchairs Market |
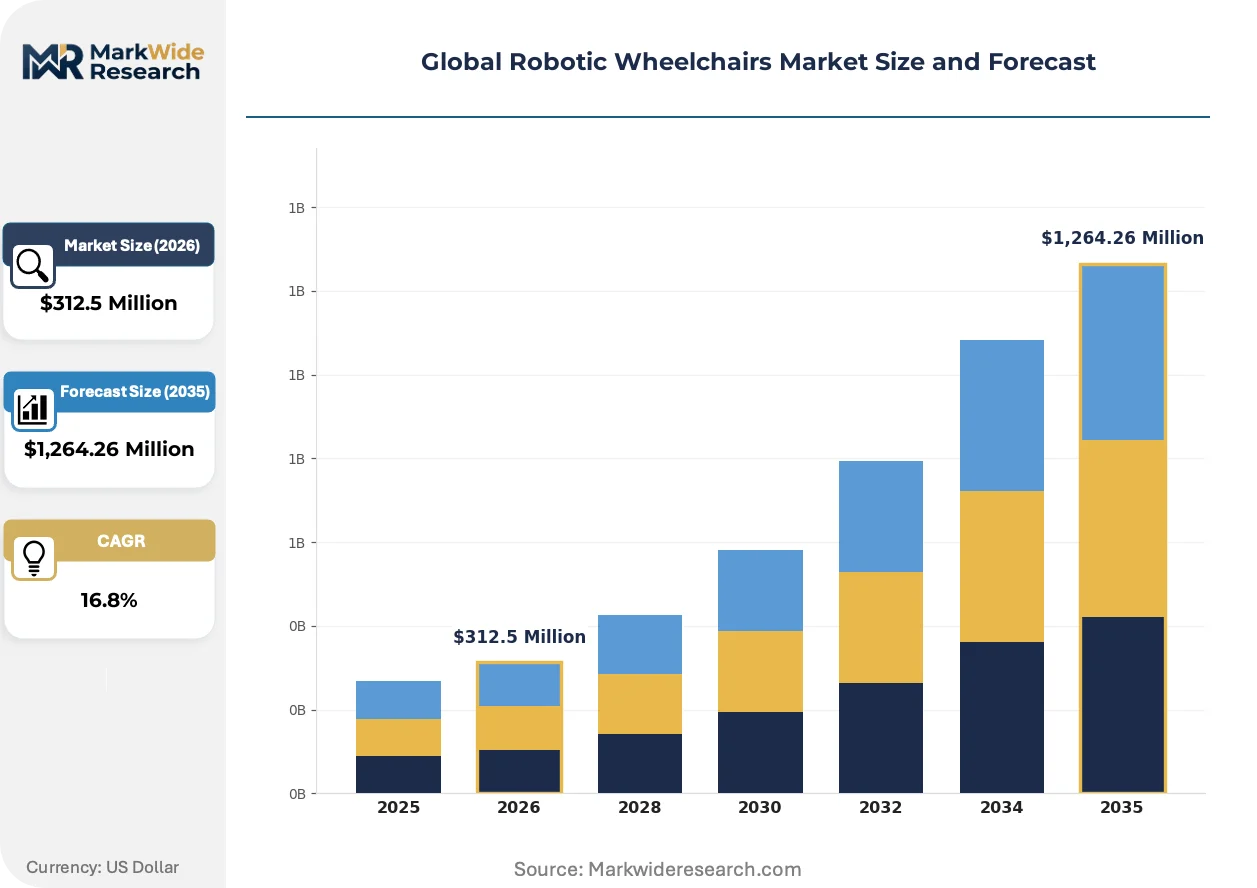
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,264.26 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power-assisted, All-terrain, Manual, Standing, Pediatric Technology: Sensor-based, Voice-activated, AI-enabled, Obstacle detection, Gesture control Application: Mobility impaired, Neurodegenerative disorders, Elderly care, Rehabilitation centers, Home care End User: Long-term care facilities, Physical therapy clinics, Assisted living, Veterans associations, Mobility aid providers |
| Companies Covered | Permobil AB, Invacare Corporation, Sunrise Medical LLC, Ottobock SE & Co. KGaA, WHILL Inc., Meyra GmbH, Karman Healthcare Inc., DEKA Research & Development Corp., Pride Mobility Products Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Robotic Wheelchairs Market Shifts & Advancements
Autonomous navigation algorithms are compressing caregiver dependency ratios in elderly care facilities, while regulatory harmonization across FDA, MDR, and PMDA frameworks reshapes certification strategies for multi-territory launches.
Lidar-based simultaneous localization and mapping is automating real-time path planning in indoor environments. Skilled nursing facilities in Japan are deploying these configurations at pilot scale ahead of METI's 2025 reimbursement schedule revision. This capability is automating corridor navigation previously requiring human attendant intervention, reducing labor allocation per resident by measurable increments.
Japan's PMDA QMS Ministerial Ordinance revisions are compressing quality management documentation requirements for software-as-medical-device components. Manufacturers targeting East Asian distribution are restructuring regulatory affairs teams to exploit accelerated review pathways. Neurodegenerative application segments are responding with earlier-stage product registrations to secure first-mover positioning.
Institutional procurement committees are unbundling after-sales service contracts from equipment capital expenditure, favoring third-party maintenance providers with ISO 13485 certification. Hospital systems in Germany are piloting this model through regional purchasing cooperatives. Dense urban rehabilitation centers exhibit the strongest preference shift, driven by pressure on operational expenditure budgets.
Global Robotic Wheelchairs Market Segmentation
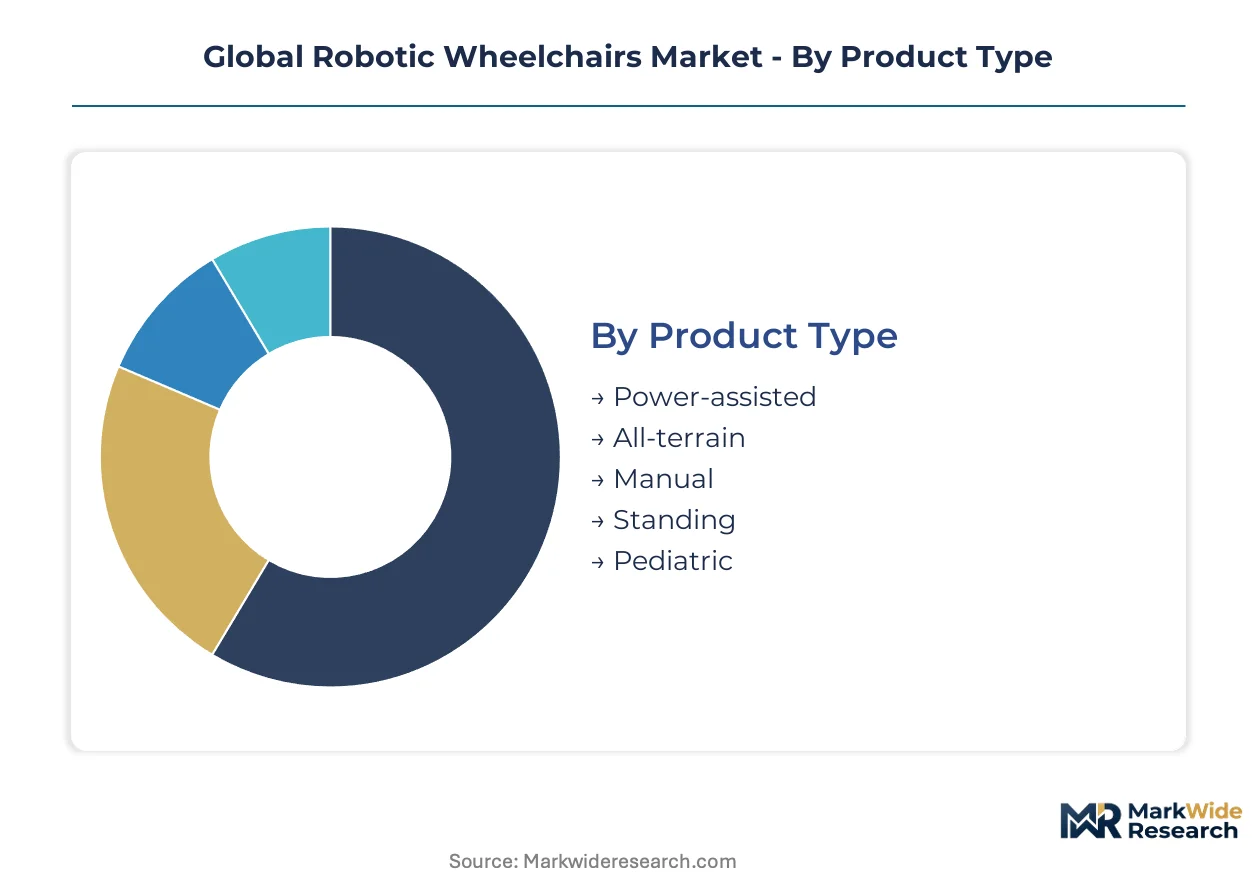
Segmentation in robotic wheelchairs determines procurement pathways and reimbursement eligibility. Product type influences capital expenditure thresholds, while technology selection dictates regulatory clearance complexity across FDA, MDR, and PMDA jurisdictions.
Product Type:
Capital intensity varies sharply across configurations, with autonomous drive systems demanding substantially higher upfront engineering investment than mechanical alternatives.
- Power-assisted:Motorized drive units with manual override capability dominate institutional procurement volumes in Germany and Japan. Rehabilitation centers prioritize these configurations for reducing caregiver strain during patient transport protocols.
- AI-enabled:Neural navigation chassis with predictive pathing algorithms command premium pricing tiers. Demand concentrates in Japanese elderly care facilities where METI reimbursement revisions favor autonomous feature sets.
- All-terrain:Reinforced suspension systems with gyroscopic stabilizers for outdoor gradient navigation.
- Manual:Conventional frame designs with minimal electronic integration, prevalent in cost-constrained Medicaid channels.
- Standing:Motorized seat elevation mechanisms for pressure relief and social interaction positioning.
- Pediatric:Scaled chassis with growth-adjustable seating platforms for developmental disability applications.
Most installed capacity flows through power-assisted configurations. Expansion is steepest in AI-enabled segments.
Technology:
Sensor density and processing architecture differentiate pricing tiers, with lidar-integrated units requiring specialized firmware talent pools concentrated in Scandinavia and Germany.
- Sensor-based:Lidar and ultrasonic arrays enabling real-time obstacle mapping. Japanese rehabilitation centers are expanding procurement as PMDA streamlines software-as-medical-device quality documentation.
- Obstacle detection:Infrared and camera-based proximity systems for corridor navigation in aged care facilities. German physical therapy clinic networks favor these units for retrofit compatibility with existing building infrastructure.
- Voice-activated:Natural language command interfaces for users with limited manual dexterity.
- Gesture control:Motion-sensing input modules for neurodegenerative patient cohorts with speech impairment.
- AI-enabled:Machine learning path optimization with environmental mapping capabilities.
Sensor-based technology carries the heaviest R&D capitalization. Obstacle detection systems are climbing the fastest in skilled nursing facility adoption.
Application:
Clinical indication determines feature prioritization, with neurodegenerative protocols demanding predictive navigation absent from standard mobility impairment cases.
- Neurodegenerative disorders:Amyotrophic lateral sclerosis and Parkinson's disease applications require anticipatory pathing for tremor-compensated operation. Japanese long-term care facilities are piloting these configurations ahead of reimbursement schedule revisions.
- Elderly care:Semi-autonomous units reducing caregiver dependency ratios in institutional settings. German purchasing cooperatives are unbundling service contracts from capital expenditure for this segment.
- Mobility impaired:Standard locomotor assistance for spinal cord injury and amputation cases.
- Rehabilitation centers:Adjustable seating platforms for post-surgical recovery protocols.
- Home care:Compact footprint designs for residential doorway and elevator compatibility.
Neurodegenerative applications attract the steepest technology premium. Elderly care generates the largest absolute unit volume.
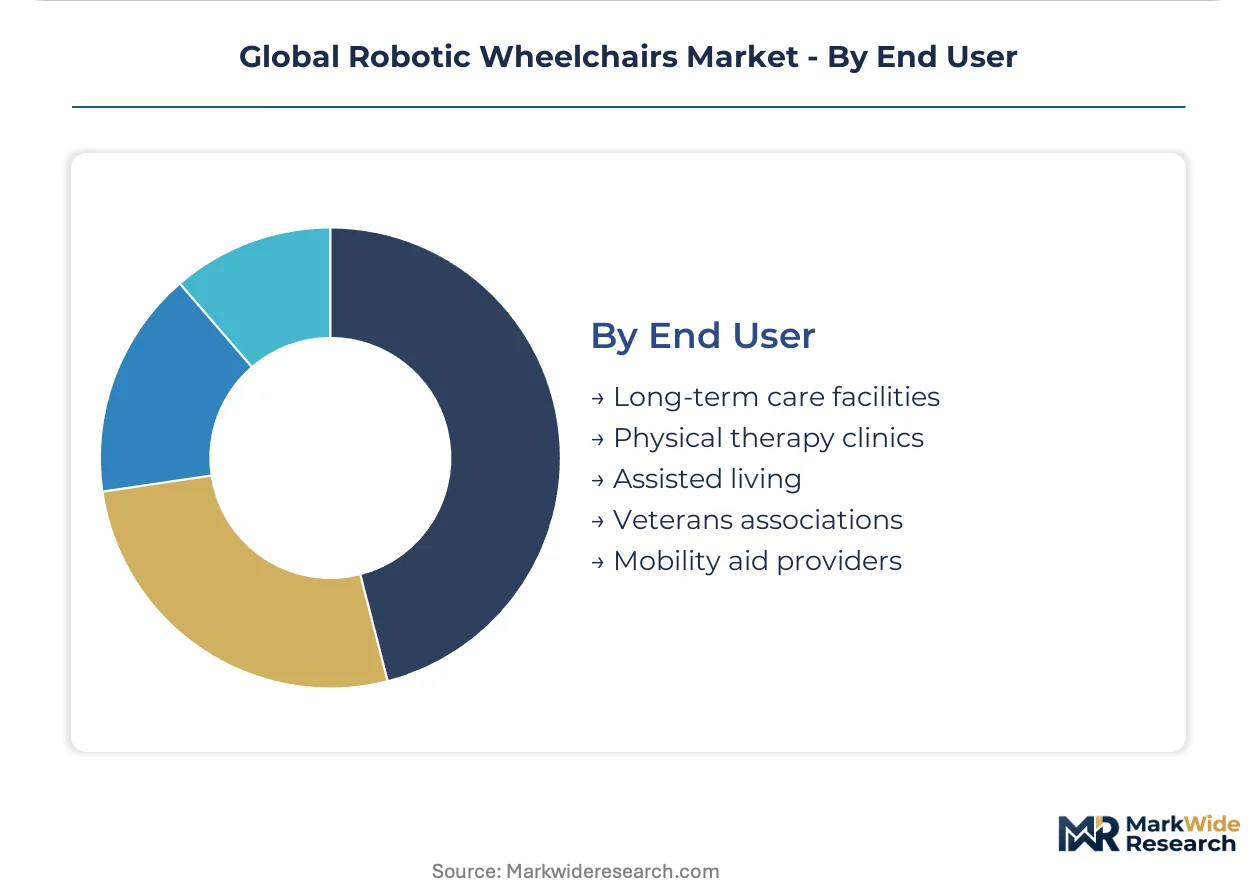
End User:
Procurement authority and reimbursement access vary across institutional buyers, with veterans associations offering distinct funding pathways separate from Medicare and Medicaid channels.
- Long-term care facilities:Skilled nursing institutions with capital expenditure constraints favoring third-party maintenance contracts. German regional purchasing cooperatives are consolidating procurement for sensor-based units.
- Physical therapy clinics:Rehabilitation specialists requiring adjustable platforms for patient progression protocols. Ottobock SE & Co. KGaA anchors European distribution through these networks.
- Assisted living:Residential care operators prioritizing compact chassis for corridor width compliance.
- Veterans associations:Government-funded procurement with distinct technical specifications and service requirements.
- Mobility aid providers:Retail and rental channels serving individual purchasers and home care segments.
Long-term care facilities represent the dominant installed base. Physical therapy clinics are expanding procurement velocity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturing clusters around rehabilitation equipment specialists anchor procurement velocity for power-assisted configurations across European institutional channels.
United States
Skilled nursing facilities drive sensor-based unit procurement as Medicare reimbursement pathways evolve for autonomous navigation features. FDA Class II premarket notification requirements extend product launch timelines by 12-18 months versus conventional power wheelchairs. Cleveland Clinic networks and Veterans Health Administration procurement channels concentrate demand in the Midwest and Southeast corridors.
Germany
Physical therapy clinic networks and regional purchasing cooperatives consolidate procurement for obstacle-detection systems with retrofit compatibility. EU Medical Device Regulation mandates CE marking and clinical evaluation reports that standardize quality benchmarks across member state access. Ottobock SE & Co. KGaA and Meyra GmbH anchor manufacturing clusters in North Rhine-Westphalia and Baden-Württemberg.
Japan
Long-term care facilities pilot AI-enabled chassis configurations ahead of METI's reimbursement schedule revisions for elderly care protocols. PMDA QMS Ministerial Ordinance revisions compress quality management documentation for software-as-medical-device components. Rehabilitation centers in Kanto and Kansai regions expand procurement of lidar-integrated units with predictive pathing capabilities.
India
Production-linked incentives for medical electronics manufacturing attract contract fabrication investment targeting Middle East and Southeast Asian export distribution. CDSCO medical device registration requirements shape product localization strategies for manufacturers entering South Asian markets. Maharashtra and Karnataka industrial corridors host emerging assembly operations for compact chassis designs.
Global Robotic Wheelchairs Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to compress firmware development cycles and secure sensor supply commitments. The vendor base organizes around three tiers: Scandinavian scale players with integrated manufacturing, German rehabilitation specialists with clinic network anchoring, and Japanese compact chassis innovators. Archetypes include premium power-assisted configurators, AI navigation developers, and regional maintenance service bundlers. Geographic expansion and technology licensing represent the dominant competitive moves as firms navigate multi-territory regulatory clearance requirements.
Among rehabilitation equipment specialists, Ottobock SE & Co. KGaA anchors European distribution archetypes through clinic partnership models, while Meyra GmbH exemplifies German manufacturing cluster positioning. WHILL Inc. represents the compact AI-enabled chassis segment targeting dense urban corridor applications. Permobil AB occupies the Scandinavian scale-driven tier with integrated manufacturing footprints.
| Leading Market Players |
|---|
| Permobil AB |
| Invacare Corporation |
| Sunrise Medical LLC |
| Ottobock SE & Co. KGaA |
| WHILL Inc. |
| Meyra GmbH |
| Karman Healthcare Inc. |
| DEKA Research & Development Corp. |
| Pride Mobility Products Corp. |
| Others |
Supply & Pricing Matrix
Lithium carbonate contract pricing cascades through cathode material processing in East Asian refineries before reaching battery pack assembly tiers, compressing margins for European power-assisted configurators while Japanese AI-enabled chassis producers exploit METI's domestic content incentives to offset cell cost volatility.
Pricing Analysis
Input-cost pass-through from lithium-ion cathode materials intensifies margin pressure across power-assisted tiers as East Asian refining capacity concentrates pricing power in cell supply contracts. Three-tier pricing structure across premium AI-enabled, standard power-assisted, and economy manual configurations differentiates by sensor density and FDA clearance tier. Pricing pressure stems from Medicaid-reimbursed facilities where labor arbitrage remains cost-competitive against semi-autonomous premiums. Long-term care facilities exhibit highest price sensitivity; neurodegenerative specialty clinics show lowest.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing strategies for manufacturers targeting Middle East export corridors, compressing tariff exposure against China-origin component flows. Lithium refining concentrates in China, South Korea, and Japan; sensor module fabrication draws from Taiwan and Germany. Cathode precursor supply rests on nickel-cobalt-manganese concentrate flows from Indonesia and DRC. Single-source vulnerability in lidar emitter arrays threatens production continuity. Distribution runs through rehabilitation clinic networks in Germany and regional purchasing cooperatives in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in India's emerging assembly corridors, where PLI tariff advantages against East Asian component costs create margin expansion potential for exporters targeting Gulf and Southeast Asian markets.
For Market Incumbents: Lock in sensor supply commitments through multi-year contracts with Taiwanese lidar specialists before capacity constraints tighten. Secure PMDA QMS pre-certification for software-as-medical-device components to exploit Japan's accelerated review pathways against FDA timeline disadvantages. Defend against WHILL-style compact chassis entrants by anchoring physical therapy clinic service contracts in Germany's regional purchasing cooperatives. For New Entrants and Emerging Players: Enter via India's Maharashtra industrial corridor to capture PLI benefits for Middle East distribution without EU MDR compliance overhead. Target neurodegenerative application segments in Japanese long-term care facilities where METI reimbursement revisions favor autonomous feature sets. Pursue hospital system pilot programs with unbundled third-party maintenance contracts to bypass incumbent service bundling. For Investors and Strategic Acquirers: Consolidation pressure builds where firmware engineering talent scarcity in Scandinavia and Germany outstrips automotive and drone sector competition for embedded systems specialists. Five-to-ten year viability favors acquirers of AI navigation developers with PMDA pre-certification and compact chassis IP. Watch Medicare coverage determination signals for autonomous navigation features as inflection indicator for institutional purchasing velocity unlock.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Medicare coverage pathway for autonomous navigation determines US institutional adoption velocity. |
| CE Marking Pathway | MDR clinical evaluation reports standardize quality benchmarks across German purchasing cooperatives. |
| Hospital System Partnership | Cleveland Clinic networks concentrate US demand for sensor-based rehabilitation configurations. |
| Software Companion Development | PMDA QMS Ministerial Ordinance revisions compress documentation for AI-enabled pathing algorithms. |
| Geographic Manufacturing Footprint | India PLI scheme offers tariff-advantaged export platforms for Middle East distribution. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's regulatory and procurement stakeholders. Interviews with rehabilitation equipment procurement managers, biomedical engineers at long-term care facilities, GPO contracts managers, and PMDA regulatory affairs specialists combined with secondary validation from FDA 510(k) filings, EU MDR clinical evaluation report databases, METI reimbursement schedule revisions, and CDSCO medical device registration records. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Rate-of-change decomposition across the analysis window segments volume and value by product type, technology architecture, clinical application, and end-user procurement channel. CAGRs derived from regression analysis against reimbursement policy timelines, battery cost curves, and regulatory approval velocity differentials. Forecast inputs include METI reimbursement schedule revision probability, lithium contract pricing volatility bands, and firmware engineering labor market tightness indices.
Inputs from PMDA QMS documentation releases and Medicare coverage determination dockets were available through the study window; gaps in real-time Medicaid state-level reimbursement variance introduce uncertainty bands around US institutional adoption assumptions. Forecasts reflect documented assumptions on regulatory harmonization progress and battery chemistry cost compression. Reimbursement policy reversals or lithium supply disruptions could materially revise trajectory. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
Rechargeable Medical Battery Market
Medical Devices
Sleeve Gastrectomy Devices Market
Medical Devices
Heat Therapy Units Market
Medical Devices
High Flow Ventilators Market
Medical Devices
Asia-Pacific Smart Medical Devices Market
Medical Devices
India Anesthesia Devices Market
Medical Devices
Organoids Kits Market
Medical Devices
Smart Pills Technology Market
Medical Devices
Airway Management Devices Market
Medical Devices
Magnetic Ablation Catheter Market
Medical Devices
North America Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Sinus Dilation Devices Market
Medical Devices
Medical Oxygen Concentrators Market
Medical Devices
Fixed and Mobile C-Arms Market