
 Europe Medical Equipment Maintenance Market | 2026-2036
Europe Medical Equipment Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Equipment Maintenance Market Analytics
Subscription-based preventive maintenance is consolidating into multi-year service agreements that bundle labor, parts, and uptime guarantees. Siemens Healthineers leverages its direct field-service footprint across German and Benelux hospital networks. GE Healthcare sustains competitive position through captive parts logistics and remote diagnostics infrastructure. Koninklijke Philips N.V. differentiates via software-defined service tiers that integrate predictive analytics into base contracts.
Europe medical equipment maintenance encompasses the scheduled inspection, calibration, repair, and performance verification of diagnostic, therapeutic, and monitoring devices to ensure clinical accuracy and operator safety. Technicians follow manufacturer-specified intervals measured in operating hours, cycle counts, or calendar periods, with documentation traceable to serial-number level. Imaging equipment maintenance commands the largest revenue pool given the capital intensity of MRI, CT, and angiography systems and the penalty cost of unplanned downtime. Digital devices and automated systems represent the fastest-expanding technology segment as connectivity-enabled remote monitoring shifts failure detection from reactive to predictive modes. Preventive maintenance contracts yield steadier margins than break-fix repair services due to recurring billing and lower technician dispatch variability.
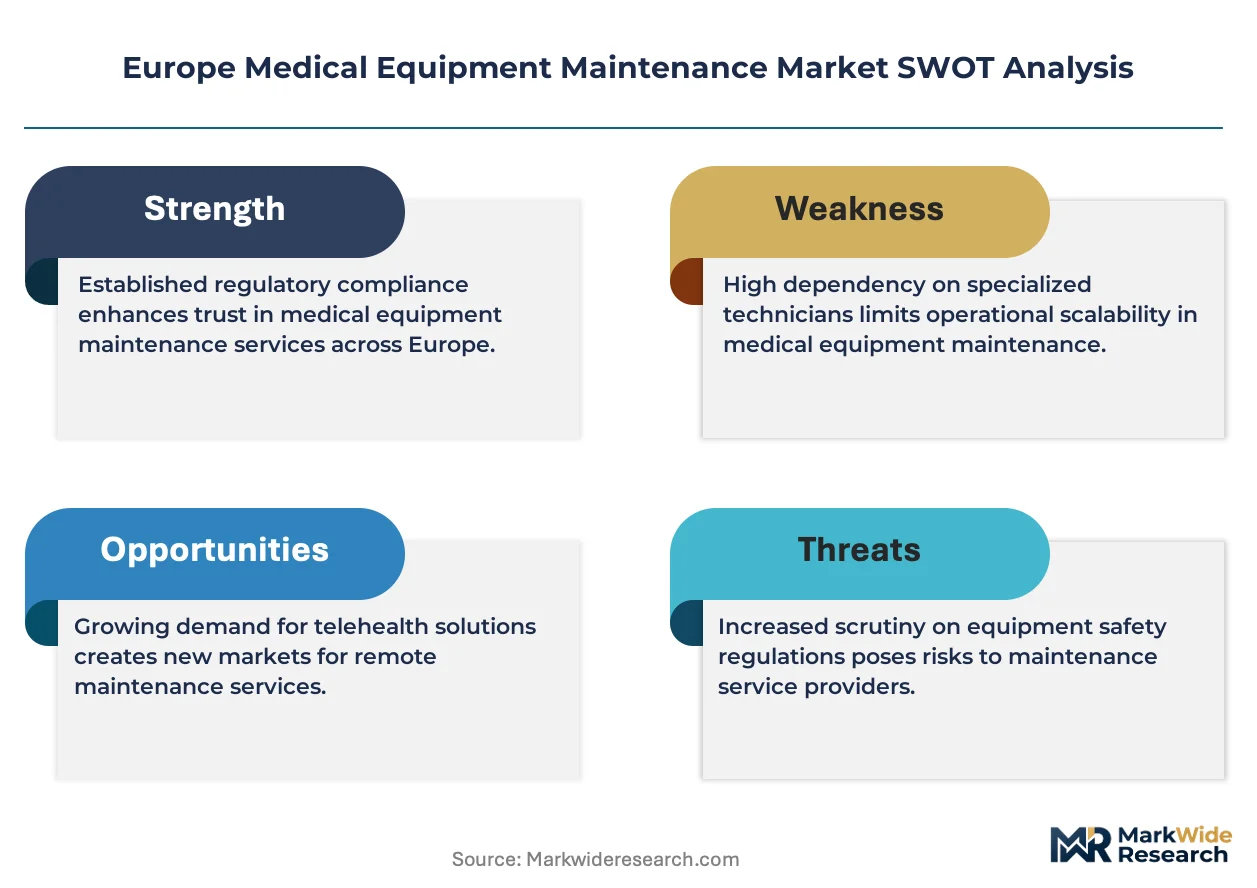
The EU Medical Device Regulation (MDR) and In Vitro Diagnostic Regulation (IVDR) mandate documented maintenance traceability for Class IIa and higher devices, directly expanding compliance-driven service demand. ECHA REACH restrictions on spare-part substances and the F-Gas Regulation on imaging equipment coolants add material-compliance layers that certified service providers must absorb. Stakeholders should monitor how national competent authorities in Germany, France, and Italy interpret MDR post-market surveillance requirements for maintenance records, as divergent enforcement timelines will fragment contract pricing and documentation standards across the region.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing maintenance documentation standards across hospital networks while predictive analytics platforms restructure contract economics from reactive dispatch to uptime-guarantee models.
Growth Catalysts
- MDR post-market surveillance mandates:Class IIa and higher devices now require serial-number-level maintenance traceability, expanding compliance-driven service contracts across German and French hospital procurement.
- Imaging equipment aging:MRI and CT systems exceeding ten-year operational lifespans in Germany's dense installed base generate recurring preventive maintenance demand and parts-replacement cycles.
- Remote diagnostics infrastructure:Connectivity-enabled failure detection shifts technician dispatch from emergency repair to scheduled intervention, improving margin stability for service providers.
Market Restraints
- ECHA REACH substance restrictions:Spare-part materials face compliance-layer costs that certified service providers must absorb without full pass-through to hospital contract pricing.
- F-Gas Regulation coolant protocols:Imaging equipment servicing requires specialized handling infrastructure that fragments provider capability across national competent authorities.
- Technician certification scarcity:Cross-border mobility of qualified imaging engineers remains constrained by divergent national interpretation of MDR competence requirements.
Strategic Opportunities
- Benelux hospital network consolidation:Belgian and Dutch health system mergers create multi-site service agreement opportunities with standardized uptime guarantee terms.
- AI-driven predictive maintenance:Machine learning models trained on equipment telemetry enable condition-based servicing that extends intervals beyond manufacturer-specified calendar periods.
- Software-defined service tiers:Modular contract structures separate base compliance maintenance from advanced analytics subscriptions, capturing budget flexibility in Italian and Spanish facilities.
Industry Challenges
- Legacy device integration:Pre-connectivity imaging systems lack telemetry interfaces, forcing hybrid service models that maintain parallel reactive and predictive dispatch capabilities.
- Competent authority divergence:Germany's BfArM, France's ANSM, and Italy's AIFA enforce MDR documentation timelines inconsistently, complicating multi-national contract standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Equipment Maintenance Market |
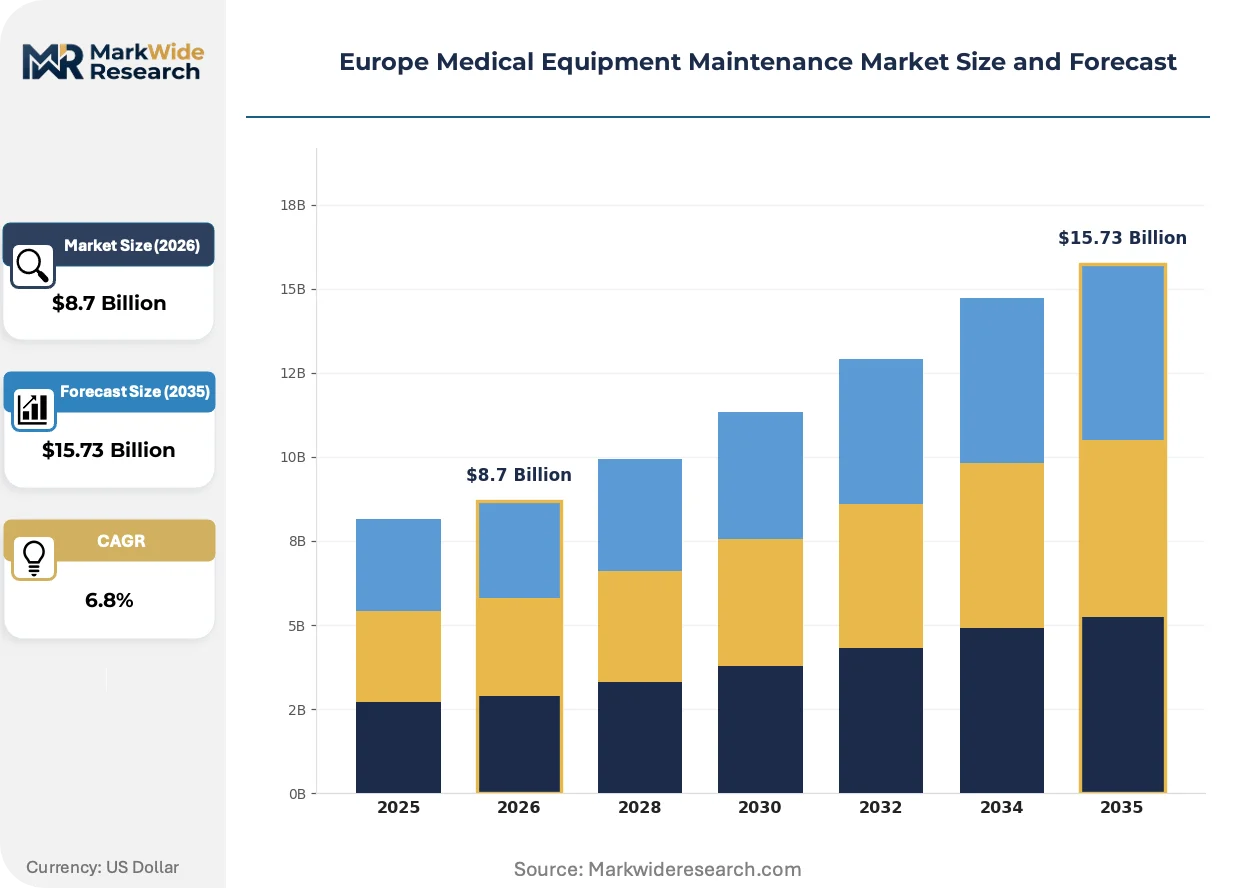
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preventive Maintenance, Repair Services, Calibration Services, Technical Support Product Type: Imaging Equipment, Surgical Instruments, Patient Monitoring Devices, Laboratory Equipment End User: Hospitals, Diagnostic Centers, Clinics, Research Institutions Technology: Traditional Equipment, Digital Devices, Automated Systems, Telehealth Solutions |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Medtronic, FUJIFILM Holdings Corporation, Canon Medical Systems Corporation, Drägerwerk AG & Co. KGaA, B. Braun SE, Agfa-Gevaert Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Equipment Maintenance Market Evolving Landscape
Predictive maintenance platforms are restructuring competitive economics while regulatory documentation requirements and procurement centralization reshape contract structures across European hospital networks.
Edge-computing diagnostics is integrating real-time vibration and thermal sensors into MRI and CT system architectures. German university hospitals are piloting these modules at scale during scheduled magnet replacements. The technology is integrating failure-pattern recognition directly into base service contracts, compressing the distinction between preventive and corrective maintenance revenue pools.
The EU F-Gas Regulation is tightening recovery and recycling mandates for imaging equipment refrigerants. Service providers must now maintain specialized handling infrastructure that smaller independent technicians cannot replicate. Nordic hospital networks are responding by consolidating contracts with manufacturers possessing captive coolant logistics capabilities.
Hospital procurement centralization is consolidating maintenance decisions from individual clinical departments to group purchasing organizations. French public hospital networks are unbundling imaging service contracts from equipment acquisition financing. This shift is most visible in the Ile-de-France region, where AP-HP's centralized tendering now separates uptime guarantees from parts-inclusion terms.
Europe Medical Equipment Maintenance Market Segmentation
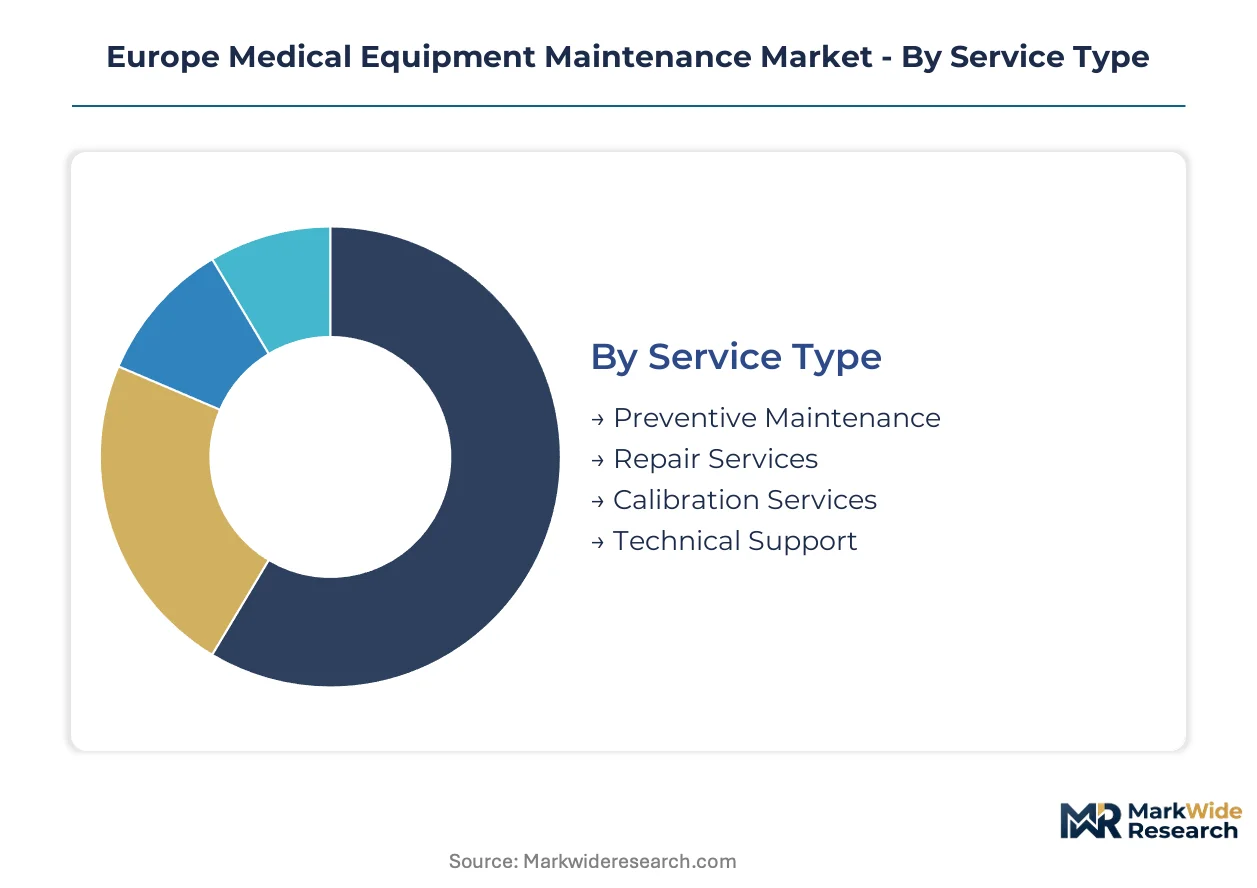
Service contract structures in European medical equipment maintenance diverge sharply by equipment criticality and regulatory exposure. Procurement teams weight uptime guarantees against compliance documentation burdens when allocating budgets across service tiers and technology platforms.
Service Type:
Hospital procurement departments prioritize contract predictability over per-incident cost minimization when selecting maintenance engagement models.
- Preventive Maintenance:Scheduled inspections, parts replacement, and performance verification executed at manufacturer-specified intervals. German hospital networks favor multi-year agreements bundling labor, parts, and uptime guarantees for MRI and CT fleets. MDR documentation mandates expand contract scope to include serial-number-level traceability logs.
- Repair Services:Reactive intervention following equipment failure or performance drift. Demand concentrates in France where aging angiography systems in public hospitals exceed ten-year operational lifespans. Break-fix economics strain departmental budgets but persist for non-critical devices lacking connectivity infrastructure.
- Calibration Services:Accuracy verification against reference standards for diagnostic and monitoring equipment.
- Technical Support:Remote troubleshooting, software updates, and operator training delivered via phone or digital channels.
Preventive Maintenance leads on scale; Repair Services leads on momentum as predictive platforms convert reactive demand into scheduled intervention.
Product Type:
Capital intensity and penalty cost of downtime determine service contract pricing tiers across equipment categories.
- Imaging Equipment:MRI, CT, angiography, and ultrasound systems requiring specialized technician certification and captive parts logistics. Maintenance commands premium pricing given magnet replacement costs and clinical throughput dependency. Benelux hospital consolidations drive volume concentration for multi-site service agreements.
- Surgical Instruments:Electromechanical and robotic surgical platforms with precision calibration requirements. French university hospitals are expanding service coverage for da Vinci systems as procedure volumes rise.
- Patient Monitoring Devices:Bedside and portable units with connectivity-enabled remote diagnostics capabilities.
- Laboratory Equipment:Analyzers and centrifuges subject to IVDR traceability mandates for diagnostic accuracy verification.
Imaging Equipment dominates contract value; Patient Monitoring Devices expands most quickly as telemetry integration enables predictive service models.
End User:
Procurement centralization is compressing vendor fragmentation by shifting maintenance decisions from clinical departments to group purchasing organizations.
- Hospitals:Acute care facilities with dense installed bases of multi-modal diagnostic equipment. AP-HP in Ile-de-France unbundles imaging service contracts from acquisition financing, separating uptime guarantees from parts-inclusion terms. German hospital networks leverage scale for standardized multi-year agreements across Siemens, GE, and Philips equipment.
- Diagnostic Centers:Dedicated imaging and laboratory facilities with high equipment utilization rates. Italian private diagnostic chains are consolidating maintenance procurement to offset margin pressure from tariff compression.
- Clinics:Outpatient facilities with limited in-house biomedical engineering capacity.
- Research Institutions:University hospitals and academic medical centers piloting edge-computing diagnostics modules.
Hospitals anchor contract volume; Diagnostic Centers gain share fastest as outpatient imaging shifts from hospital campuses to dedicated facilities.
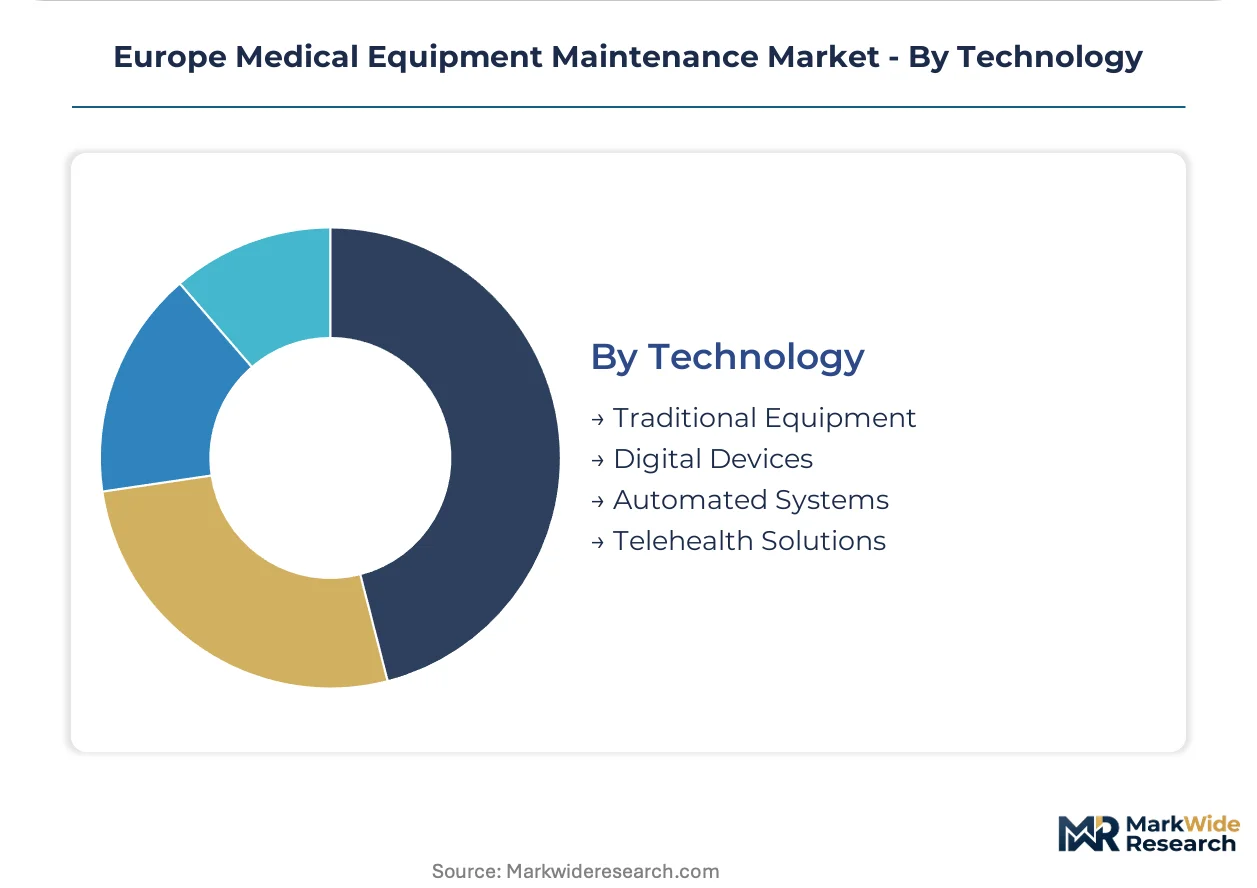
Technology:
Connectivity architecture determines whether maintenance economics favor manufacturer-direct service or third-party competition.
- Digital Devices:Network-connected equipment with embedded sensors enabling real-time performance telemetry. German university hospitals pilot vibration and thermal monitoring modules during scheduled magnet replacements. Remote diagnostics infrastructure shifts failure detection from reactive dispatch to condition-based intervention.
- Automated Systems:Robotic surgical platforms and laboratory automation with self-diagnostic capabilities. Nordic hospital networks consolidate contracts with manufacturers possessing captive software update pipelines.
- Traditional Equipment:Pre-connectivity imaging and monitoring systems lacking telemetry interfaces.
- Telehealth Solutions:Remote patient monitoring devices with cloud-integrated maintenance alerts.
Digital Devices command premium service pricing; Automated Systems climb the fastest as AI-driven predictive maintenance extends intervals beyond calendar-based schedules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the densest installed base of diagnostic imaging equipment in Europe, while France's public hospital networks drive contract unbundling trends that differ sharply from German procurement centralization.
Germany
Hospital networks across Bavaria and North Rhine-Westphalia are expanding multi-year service agreements for aging MRI and CT fleets. BfArM enforces MDR post-market surveillance documentation timelines that compress contract standardization across federal states. Siemens Healthineers leverages its direct field-service footprint across university hospitals in Berlin and Munich to capture preventive maintenance volume.
France
Public hospital procurement centralization in Ile-de-France unbundles imaging service contracts from equipment acquisition financing. ANSM interprets MDR competence requirements for technician certification with stricter mobility constraints than neighboring jurisdictions. AP-HP's centralized tendering in Paris separates uptime guarantees from parts-inclusion terms, reshaping vendor pricing structures.
United Kingdom
NHS trust consolidation drives standardized maintenance procurement for diagnostic imaging across England's regional hospital networks. MHRA alignment with EU MDR documentation standards maintains traceability requirements for Class IIa devices post-Brexit. London's academic medical centers pilot edge-computing diagnostics modules during scheduled system replacements.
Italy
Private diagnostic chains in Lombardy and Emilia-Romagna consolidate maintenance procurement to offset tariff compression pressure. AIFA enforces MDR documentation timelines with variable intensity across northern and southern regions. Milan's dense concentration of outpatient imaging facilities generates demand for software-defined service tiers with modular contract structures.
Netherlands
Belgian and Dutch health system mergers create multi-site service agreement opportunities with standardized uptime guarantee terms across the Benelux region. ECHA REACH substance restrictions on spare-part materials add compliance-layer costs that certified providers absorb. Eindhoven's medical technology cluster drives adoption of predictive analytics platforms in hospital network contracts.
Europe Medical Equipment Maintenance Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with imaging equipment maintenance consolidating around manufacturer-direct service while third-party competition persists in non-critical device categories. The vendor base organizes into three strategic archetypes: OEM-captive service divisions with captive parts logistics, independent service organizations with regional technician networks, and emerging predictive analytics platforms with software-defined contract tiers. M&A activity concentrates on acquiring specialized technician certifications and coolant handling capabilities, while strategic partnerships focus on integrating remote diagnostics infrastructure into base maintenance agreements.
Among OEM-captive service providers, Siemens Healthineers, GE Healthcare, and Koninklijke Philips N.V. exemplify the dominant archetype of vertically integrated field-service operations with direct hospital network relationships. These companies occupy positions that combine captive parts logistics with remote diagnostics infrastructure, representing the competitive standard against which independent service organizations benchmark contract terms. Their geographic concentration across German and Benelux hospital networks anchors regional market structure.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Medtronic |
| FUJIFILM Holdings Corporation |
| Canon Medical Systems Corporation |
| Drägerwerk AG & Co. KGaA |
| B. Braun SE |
| Agfa-Gevaert Group |
| Others |
Value Network & Pricing Analysis
Certified technician labor costs in Germany cascade through three distinct pricing tiers as hospital networks bundle preventive maintenance with uptime guarantees and MDR compliance documentation. ECHA REACH substance restrictions on spare-part materials add compliance-layer costs that certified service providers absorb, compressing margins on economy-tier contracts while premium tiers capture predictive analytics premiums.
Pricing Analysis
Capacity additions in Benelux hospital networks are reshaping price floors for multi-site service agreements as Belgian and Dutch health system mergers create standardized uptime guarantee terms. Three-tier pricing structure across premium, standard, and economy levels separates predictive analytics subscriptions from base compliance maintenance and break-fix repair services. Cost compression in economy tiers intensifies because independent service organizations lack captive parts logistics to match OEM field-service footprints. Public hospital procurement teams in France exhibit highest price sensitivity as AP-HP's centralized tendering unbundles service contracts from equipment acquisition financing.
Supply Chain Analysis
Direct-to-hospital channels handle preventive maintenance demand from German and French hospital networks while third-party distributors serve independent diagnostic centers and outpatient clinics. Component supply concentrates in Germany, the Netherlands, and Switzerland for imaging equipment magnet assemblies, coolant handling systems, and edge-computing diagnostic modules. Raw material dependencies span rare-earth magnet materials, specialized refrigerants subject to F-Gas Regulation protocols, and REACH-compliant spare-part alloys. Single-source vulnerability sits with OEM-captive technician certification programs that constrain cross-border service capacity. Distribution runs through manufacturer-direct field-service operations for premium-tier contracts and regional independent service organizations for non-critical device categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities emerge between Germany's dense installed base of aging imaging equipment and France's procurement centralization that unbundles service contracts from acquisition financing, exploiting cost differentials in compliance documentation and technician mobility constraints.
For Market Incumbents: Acquire specialized coolant handling capabilities and ECHA REACH-certified spare-part logistics infrastructure to defend against independent service organizations gaining share in non-critical device maintenance. Siemens Healthineers and GE Healthcare should deepen backward integration into predictive analytics software development, as AI-driven condition-based servicing displaces calendar-based preventive maintenance contracts. Consolidate technician certification programs across German and Benelux networks to reduce mobility constraints from divergent national MDR competence interpretations. For New Entrants and Emerging Players: Begin with software-defined service tiers targeting Italian and Spanish diagnostic centers where tariff compression pressures create demand for modular contract structures separating base compliance from advanced analytics. The most penetrable segment lies in patient monitoring devices with connectivity-enabled remote diagnostics, where telemetry integration enables predictive service models without requiring captive parts logistics. Pursue partnerships with Nordic hospital networks seeking consolidated contracts for F-Gas Regulation-compliant coolant handling capabilities that smaller independents cannot replicate. For Investors and Strategic Acquirers: Consolidation pressure builds where technician certification scarcity intersects with MDR documentation mandates expanding contract scope across Class IIa and higher devices. Long-term viability favors vertically integrated service providers possessing captive parts logistics, remote diagnostics infrastructure, and direct hospital network relationships over asset-light independents exposed to margin compression. Acquisition target archetypes include regional independent service organizations with specialized imaging equipment certifications and predictive analytics platforms with machine learning models trained on equipment telemetry. The signal to watch is divergence in national competent authority enforcement timelines for MDR post-market surveillance requirements, which will fragment contract pricing and create rollup opportunities for standardized multi-national service agreements.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Documentation Investment | Serial-number-level traceability logs expand contract scope for Class IIa devices across German hospital networks. |
| Predictive Analytics Platform Development | Machine learning models trained on MRI and CT telemetry enable condition-based servicing beyond manufacturer intervals. |
| Multi-Site Service Agreement Consolidation | Benelux health system mergers create standardized uptime guarantee opportunities across Belgian and Dutch facilities. |
| F-Gas Regulation Handling Infrastructure | Specialized coolant recovery and recycling capabilities differentiate providers as Nordic hospitals consolidate contracts. |
| Software-Defined Service Tier Launch | Modular contract structures capture budget flexibility in Italian and Spanish diagnostic centers facing tariff compression. |
Research Methodology
Coverage spans Germany, France, the United Kingdom, Italy, and the Netherlands, with primary inputs from each market's hospital procurement landscape. The research combines structured interviews with biomedical engineering directors, hospital purchasing committee members, GPO contracts managers, and field-service operations heads with secondary validation from EMA MDR guidance documents, BfArM and ANSM enforcement notices, hospital procurement databases, and equipment manufacturer service contract disclosures. Bottom-up triangulation across service contract volumes and top-down cross-checks against installed base estimates anchor the analytical framework.
Segmentation dimensions modeled across the projection horizon include service type, product category, end-user facility type, and technology platform with connectivity architecture. The analytical framework derives CAGRs from equipment aging curves, regulatory compliance cost buildups, and predictive analytics adoption trajectories. Industry-specific forecast inputs incorporate MRI and CT system replacement cycles, F-Gas Regulation implementation timelines, and MDR post-market surveillance documentation expansion rates.
Several conditions sit outside the modeled scope, including potential harmonization of EU member state MDR enforcement timelines, breakthroughs in non-rare-earth magnet technologies, and structural shifts in hospital financing mechanisms. Forecasts reflect assumptions about technician certification mobility constraints and spare-part material compliance costs that periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Medical Vacuum System Market
Medical Equipment
MRI Transport Market
Medical Equipment
Asia-Pacific Nuclear Medicine Equipment Market
Medical Equipment
Irradiation Apparatus Market
Medical Equipment
Urodynamic Equipment Market
Medical Equipment
Hemodialysis Equipment Market
Medical Equipment
Orthopedic Operating Tables Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
India Massage Equipment Market
Medical Equipment
Medical Carts and Workstations Market
Medical Equipment
Medical Oxygen Cylinders Market
Medical Equipment
Medical Cart Battery Market
Medical Equipment
Tissue Culture Incubator Market
Medical Equipment
Mortuary Refrigerator Market
Medical Equipment
Global Medical Lighting Technologies Market
Medical Equipment
Stereotactic Biopsy Tables Market