
 Global Home and Garden Pesticides Market | 2026-2036
Global Home and Garden Pesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home and Garden Pesticides Market Foresight
Agronomic expertise within the home-use formulation sector is collapsing as university extension programs cut pesticide safety curricula and veteran chemists retire without replacement. Bayer AG sustains its position through captive supply of neonicotinoid precursors and backward integration into active ingredient synthesis. The Scotts Company LLC dominates North American retail shelf space through exclusive merchandising agreements with big-box home improvement chains. Spectrum Brands Inc. competes on price in the battery-powered applicator segment, leveraging its electronics manufacturing footprint to undercut traditional sprayer economics.
Home and garden pesticides comprise synthetic and biological formulations engineered to control arthropod, botanical, and fungal pests in non-agricultural environments, typically delivered through aqueous suspensions, granular carriers, or pressurized aerosol systems with active ingredient concentrations ranging from 0.1% to 5% by weight. Their commercial purpose centers on protecting ornamental plantings, turfgrass, and residential structures from yield loss or aesthetic damage. Herbicides command the largest revenue pool among product types as pre-emergent crabgrass control and broadleaf weed management anchor recurring spring purchase cycles. Liquid formulations lead volume shipments due to compatibility with hose-end sprayers and backpack applicators favored by landscaping companies, while aerosol formats capture premium pricing in household pest control where convenience commands margin.
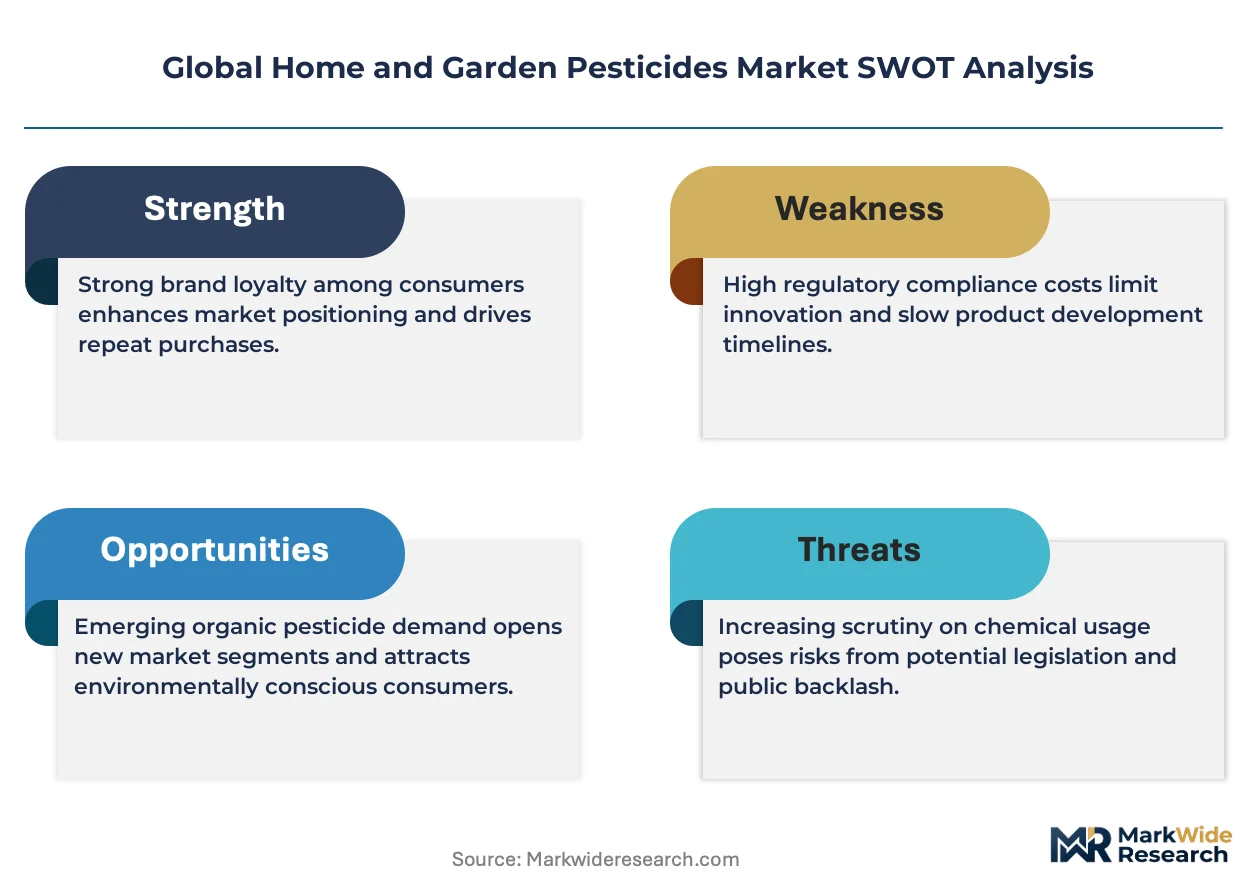
The EPA governs registration and label claims under FIFRA in the United States, while the EU Green Deal and REACH restrict candidate active substances based on endocrine disruption and groundwater persistence criteria. These frameworks are forcing reformulation toward biopesticide alternatives and low-dose synthetic chemistry that satisfies both efficacy thresholds and residue limits. BASF SE and Syngenta navigate this complexity by maintaining parallel registration portfolios across regulatory jurisdictions. Stakeholders must monitor the trajectory of EPA biopesticide policy harmonization with OECD guidelines, as divergence between American and European approval pathways would fragment R&D investment and delay product launches in key markets.
Market Dynamics
EPA re-registration reviews under FIFRA are forcing simultaneous reformulation across multiple active ingredient classes, compressing product development timelines while elevating biopesticide R&D priority.
Growth Catalysts
- Urban gardening participation:Residential consumers in Brazil and the United States are expanding ornamental plantings and edible gardens, creating recurring demand for arthropod and fungal control products.
- EU Green Deal biocide restrictions:The framework's endocrine disruption criteria are redirecting investment toward low-dose synthetic chemistry and microbial alternatives that satisfy residue limits.
- Neonicotinoid precursor supply:Captive backward integration into active ingredient synthesis secures formulation continuity amid regulatory uncertainty.
Market Restraints
- Petrochemical feedstock volatility:Aqueous suspension carriers and pressurized propellants face input cost swings that squeeze margin on economy-tier formulations.
- Groundwater persistence standards:REACH criteria in Europe block candidate substances that fail biodegradability thresholds, eliminating entire chemical families from registration portfolios.
- University extension program cuts:The collapse of pesticide safety curricula erodes consumer education infrastructure that historically drove proper application and repeat purchase.
Strategic Opportunities
- Brazilian middle-class homeownership:Latin American lawn care culture expansion creates white space for pre-emergent crabgrass control and turfgrass protection products.
- Battery-powered applicator convergence:Electronics manufacturing expertise merging with precision dosing technology enables subscription-based device-plus-consumable models.
- OECD biopesticide harmonization:Alignment between EPA guidelines and European approval pathways would streamline multi-jurisdictional launches and concentrate R&D investment.
Industry Challenges
- Veteran chemist retirement:Agronomic expertise attrition without replacement threatens formulation quality and regulatory submission success rates.
- Parallel registration maintenance:BASF SE and Syngenta navigate divergent American and European frameworks that fragment compliance resources and delay market entry.
- Exclusive retail merchandising:Big-box home improvement chain agreements lock shelf access, forcing smaller competitors into direct-to-consumer channels with higher customer acquisition costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home and Garden Pesticides Market |
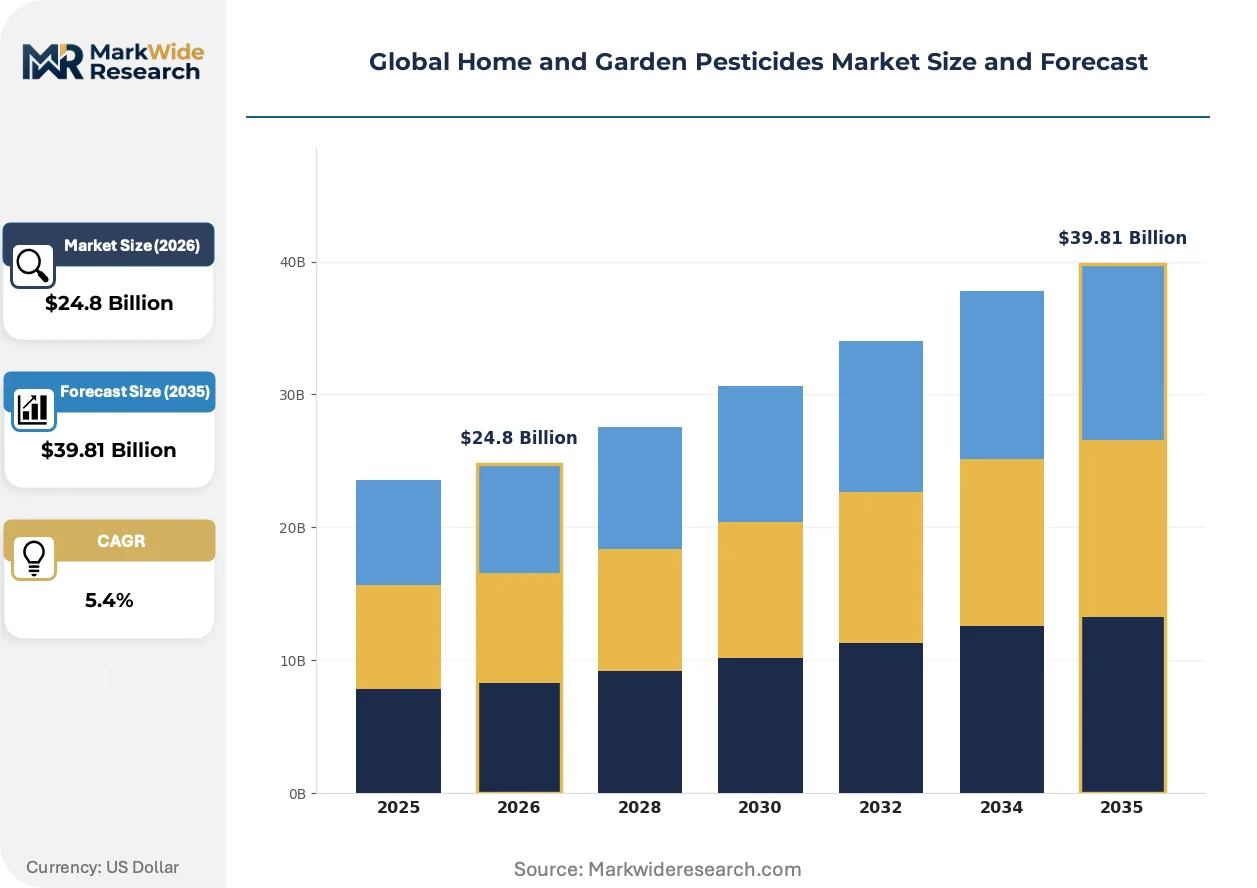
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $39.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insecticides, Herbicides, Rodenticides, Fungicides, Molluscicides Form: Liquid, Granules, Powder, Aerosol, Emulsifiable Concentrate Application: Lawn Care, Garden Protection, Household Pest Control, Seed Treatment, Tree & Shrub Protection End User: Residential Consumers, Garden Centers, Landscaping Companies, Pest Control Operators, DIY Retailers |
| Companies Covered | Central Garden & Pet Company, Bayer AG, The Scotts Company LLC, S.C. Johnson & Sons Inc., Syngenta, BASF SE, DuPont de Nemours, Inc., Reckitt Benckiser Group PLC, Spectrum Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home and Garden Pesticides Market Shifts & Advancements
Formulation chemistry and application hardware are diverging along regulatory fault lines, with biopesticide platforms gaining investment share while conventional synthesis faces compressed approval windows.
Microbial biopesticide platforms incorporating Bacillus thuringiensis and entomopathogenic fungi are fragmenting the arthropod control segment. Residential gardeners in Germany and the Netherlands are adopting these alternatives at twice the rate of synthetic rotations. The technology is fragmenting manufacturer R&D budgets between biological fermentation infrastructure and legacy chemical synthesis assets.
REACH authorization requirements for endocrine-disrupting candidates are eliminating pyrethroid and organophosphate alternatives from European portfolios. Formulators are redirecting active ingredient sourcing toward microbial extracts and plant-derived compounds that bypass the candidate substance restriction process. Turfgrass protection products face the steepest reformulation burden, with label claim adjustments consuming 18-24 month regulatory cycles.
Subscription-based replenishment models are displacing seasonal retail purchasing patterns among landscaping contractors. Hose-end sprayer compatibility and backpack applicator calibration services now bundle with consumable shipments, locking annual volume commitments. This shift concentrates most visibly in the United States, where commercial lawn maintenance companies prioritize inventory predictability over spot-market price flexibility.
Global Home and Garden Pesticides Market Segmentation
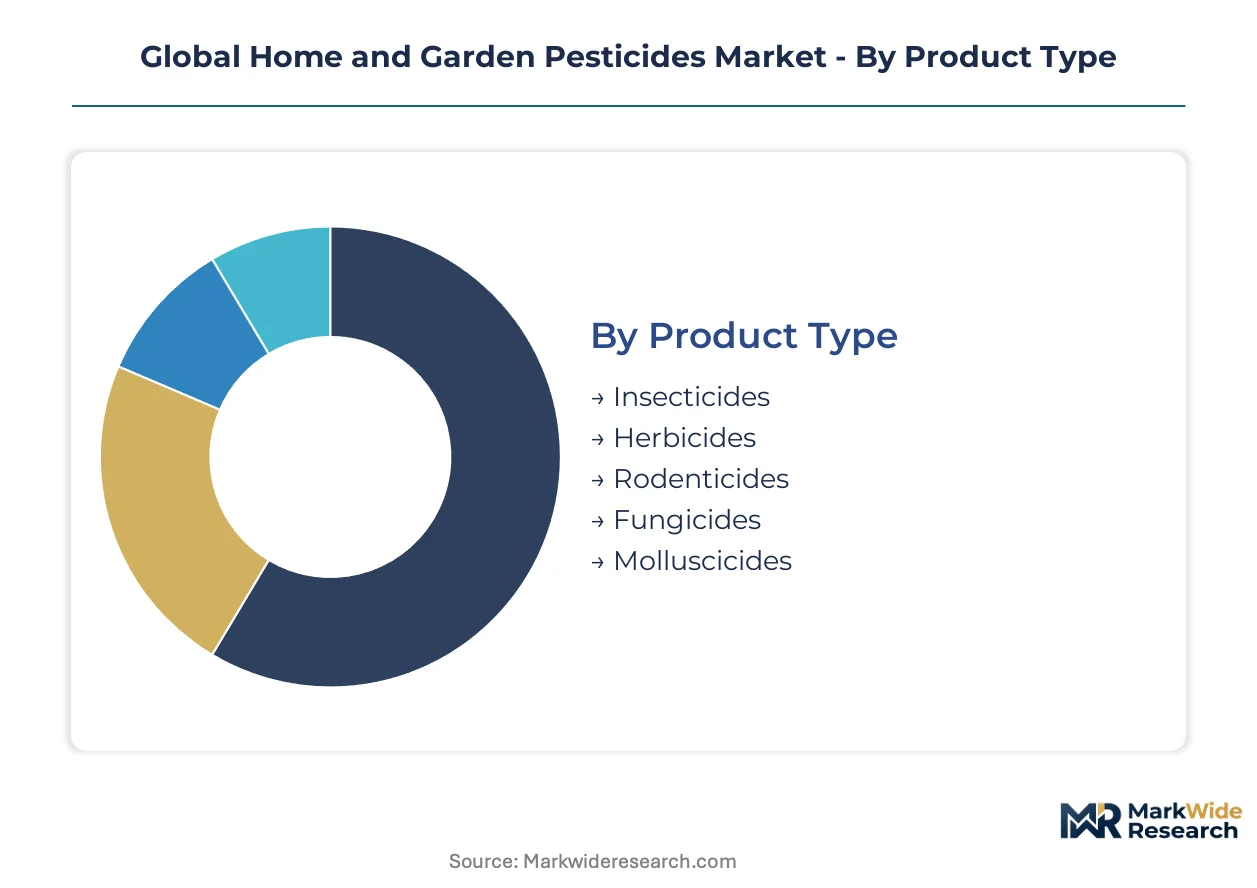
Segmentation in home and garden pesticides reveals how regulatory pressure and application convenience reshape competitive investment. Each dimension exposes different vulnerability to biopesticide substitution and hardware-enabled service models.
Product Type:
Herbicides face the most acute substitution pressure as EU Green Deal criteria eliminate legacy chemistries faster than reformulation cycles can replace them.
- Herbicides:Pre-emergent crabgrass control and broadleaf weed management formulations anchor recurring spring purchase cycles in North American retail. Demand concentrates among residential consumers in the United States and Brazil where lawn care culture drives repeat application schedules.
- Insecticides:Arthropod control formulations span synthetic pyrethroids, neonicotinoids, and emerging microbial alternatives incorporating Bacillus thuringiensis. German and Dutch residential gardeners adopt biopesticide rotations at twice the rate of synthetic options, fragmenting manufacturer R&D budgets.
- Fungicides:Turfgrass and ornamental disease control products carry the steepest reformulation burden under REACH authorization timelines.
- Rodenticides:Anticoagulant and acute toxicant baits for residential and commercial structural pest management face tightening EPA risk mitigation measures.
- Molluscicides:Slug and snail control formulations for edible gardening and greenhouse operations occupy niche volume positions with limited active ingredient diversity.
Herbicides retain volume leadership; insecticides hold the steepest expansion curve as microbial platforms gain regulatory preference.
Form:
Liquid formats dominate cost-tier positioning through compatibility with professional-grade application equipment and subscription replenishment models.
- Liquid:Aqueous suspensions and solutions engineered for hose-end sprayers and backpack applicators lead volume shipments among landscaping companies. United States commercial lawn maintenance operators prioritize inventory predictability through bundled calibration services and consumable subscriptions.
- Aerosol:Pressurized systems with active ingredient concentrations optimized for household convenience capture premium pricing in residential pest control where immediate knockdown commands margin. Brazilian middle-class consumers driving urban gardening participation favor single-use formats for ornamental protection.
- Granules:Slow-release carriers for pre-emergent herbicide application in turfgrass management support seasonal broadcast spreading equipment.
- Powder:Dry flowable formulations for dust application in structural voids and garden bed perimeter treatments serve specialized pest control operator requirements.
- Emulsifiable Concentrate:Oil-based carriers requiring dilution before application persist in professional channels despite handling complexity and personal protective equipment requirements.
Liquid formulations capture the broadest customer base; aerosol formats generate the highest per-unit margins.
Application:
Lawn care applications concentrate volume through recurring seasonal cycles, while household pest control commands price premiums via emergency purchase behavior.
- Lawn Care:Turfgrass protection spanning pre-emergent weed control, grub management, and fungal disease prevention generates the most predictable replenishment demand. United States big-box retail chains anchor shelf space through exclusive merchandising agreements with dominant suppliers.
- Household Pest Control:Perimeter barrier treatments and interior crack-and-crevice applications for ants, cockroaches, and spiders drive aerosol and ready-to-use liquid purchases. Brazilian urban residential expansion creates white space for structural protection products as middle-class homeownership deepens.
- Garden Protection:Edible and ornamental plantings in residential settings require arthropod, fungal, and mollusk control with residue limit sensitivity.
- Tree & Shrub Protection:Systemic insecticide drenches and trunk injection applications for woody ornamentals serve higher-value landscaping contracts.
- Seed Treatment:Prophylactic fungal and insect protection applied before planting occupies limited home-use volume due to equipment requirements.
Lawn care commands the largest revenue pool; household pest control delivers the most stable margin profile.
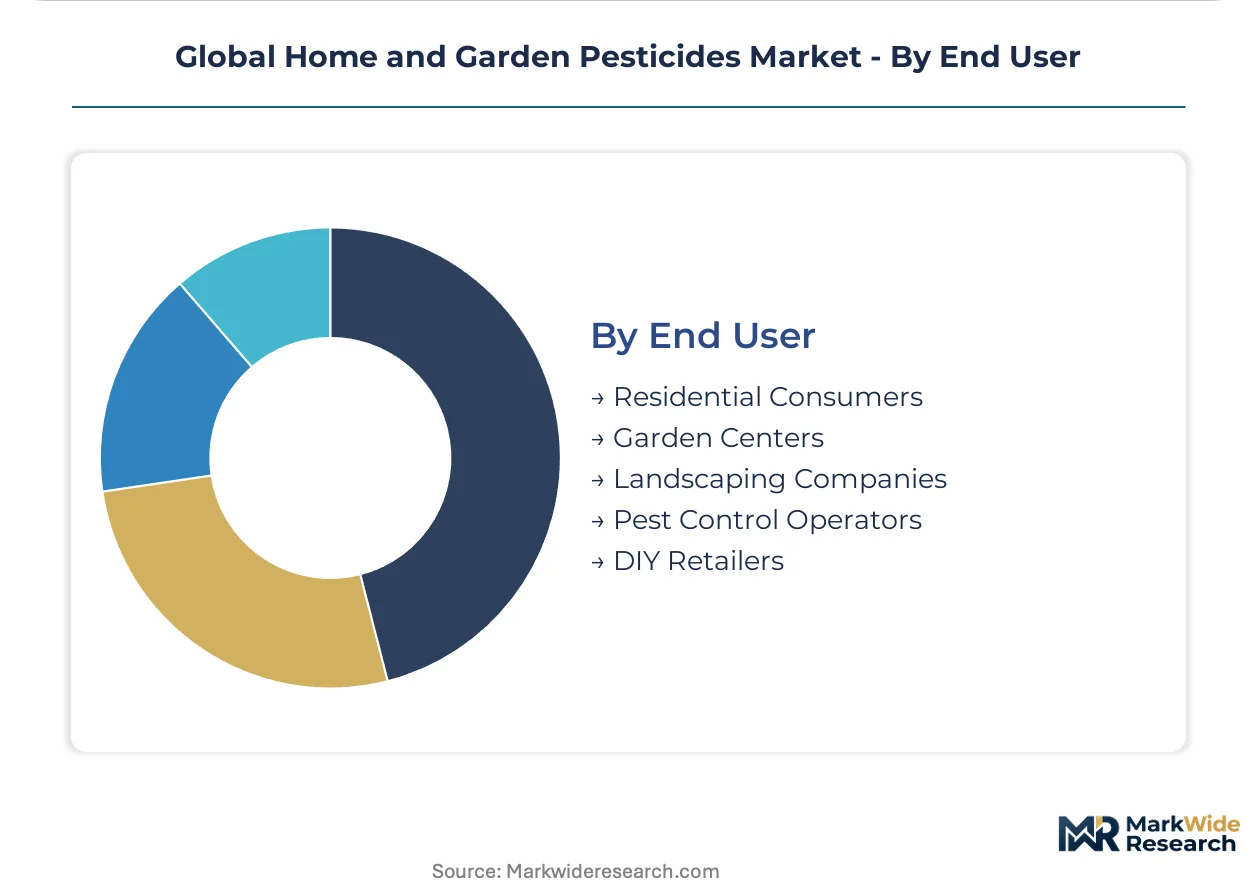
End User:
Residential consumers drive the fastest segment expansion as urban gardening participation rises, while landscaping companies concentrate volume through professional procurement discipline.
- Residential Consumers:Individual homeowners managing ornamental plantings, edible gardens, and structural pest barriers represent the fastest-expanding buyer segment. United States and Brazilian participation in urban gardening creates recurring demand for arthropod and fungal control products with convenience-oriented packaging.
- Landscaping Companies:Commercial lawn maintenance and garden service providers purchase liquid formulations in volume through subscription-based replenishment models. Equipment calibration services now bundle with consumable shipments, locking annual volume commitments in the United States market.
- Garden Centers:Specialty retail channels serving enthusiast gardeners with technical product knowledge requirements and premium formulation preferences.
- Pest Control Operators:Licensed professionals requiring restricted-use pesticide access and specialized application equipment for structural and ornamental management.
- DIY Retailers:Mass-market home improvement chains capturing seasonal purchase spikes through promotional scheduling and exclusive brand placement.
Landscaping companies retain volume leadership; residential consumers are expanding most quickly as gardening participation broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: Brazilian households favor single-use aerosol formats for ornamental protection, while German gardeners adopt microbial biopesticide rotations at twice the synthetic rate, and American landscaping companies drive volume through subscription-based liquid replenishment models.
United States
Commercial lawn maintenance operators anchor global volume through bundled calibration services and consumable subscriptions that lock annual commitments. The EPA's FIFRA re-registration reviews compress product development timelines while elevating biopesticide R&D priority. Big-box retail chains in the Southeast and Midwest concentrate shelf access through exclusive merchandising agreements with dominant suppliers.
Brazil
Middle-class homeownership expansion in São Paulo and Rio de Janeiro creates white space for pre-emergent crabgrass control and structural protection products. ANVISA alignment with OECD biopesticide guidelines would streamline approval pathways for microbial alternatives. Urban gardening participation concentrates in the Southeast region where convenience-oriented packaging commands premium positioning.
Germany
Residential gardeners in Bavaria and North Rhine-Westphalia adopt Bacillus thuringiensis and entomopathogenic fungi formulations at accelerated rates. REACH authorization requirements for endocrine-disrupting candidates eliminate pyrethroid alternatives from registration portfolios. The Eindhoven-Randstad corridor anchors reformulation R&D as manufacturers redirect active ingredient sourcing toward microbial extracts.
Netherlands
Greenhouse operations and edible gardening specialists drive demand for residue-sensitive fungal and mollusk control products. EU Green Deal biocide restrictions redirect investment toward low-dose synthetic chemistry that satisfies groundwater persistence thresholds. Wageningen University research clusters support biological fermentation infrastructure development for microbial biopesticide platforms.
China
Dual carbon goals and MEE enforcement tighten manufacturing emissions standards for aqueous suspension carriers and pressurized propellants. Yangtze River Delta chemical parks consolidate active ingredient synthesis capacity as smaller formulators exit. Urban gardening participation in Shanghai and Hangzhou creates emerging demand for convenience-oriented household pest control formats.
Global Home and Garden Pesticides Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding captive supply of neonicotinoid precursors and backward integration into active ingredient synthesis. The middle tier competes through exclusive retail merchandising agreements that lock shelf access in big-box home improvement chains. Three archetypes dominate: integrated multinationals with parallel registration portfolios, retail-captive formulators with merchandising leverage, and electronics manufacturers converging on battery-powered applicator segments. Competitive moves concentrate on regulatory submission capacity expansion and subscription-based device-plus-consumable model deployment.
Within the integrated multinational tier, Bayer AG and BASF SE occupy positions defined by captive precursor supply and jurisdiction-spanning registration maintenance. Syngenta represents the specialist-agrochemical archetype navigating divergent American and European approval frameworks. Among retail-captive formulators, The Scotts Company LLC exemplifies merchandising-driven market presence through big-box exclusive arrangements. Spectrum Brands Inc. sits within the hardware-convergence segment, leveraging electronics manufacturing footprints to undercut traditional sprayer economics. These three groupings—integrated synthesis leaders, retail-captive formulators, and hardware specialists—anchor competitive dynamics as regulatory pressure fragments R&D investment and elevates biopesticide platform priority.
| Leading Market Players |
|---|
| Central Garden & Pet Company |
| Bayer AG |
| The Scotts Company LLC |
| S.C. Johnson & Sons Inc. |
| Syngenta |
| BASF SE |
| DuPont de Nemours, Inc. |
| Reckitt Benckiser Group PLC |
| Spectrum Brands Inc. |
| Others |
Supply & Pricing Matrix
Scale economies in neonicotinoid precursor synthesis anchor pricing power among integrated multinationals, compressing margin floors for non-integrated formulators while elevating entry barriers. Contract structures bifurcate between subscription-based replenishment models for landscaping companies and spot-market transactional purchasing for residential consumers, with the former locking volume commitments that insulate suppliers from petrochemical feedstock volatility.
Pricing Analysis
Long-term offtake agreements dominate commercial procurement between landscaping operators and liquid formulation suppliers, while aerosol formats trade through project-based seasonal purchasing cycles. Three-tier pricing structure across premium biopesticide, standard synthetic, and economy generic levels differentiates by certification grade and after-sales calibration bundling. Pricing pressure stems from REACH-driven reformulation costs that compress margins on legacy chemistries. Residential consumers in Brazil exhibit highest price sensitivity, whereas United States commercial lawn maintenance operators prioritize inventory predictability over unit cost.
Supply Chain Analysis
Strait of Hormuz transit risk concentrates petrochemical feedstock vulnerability for aqueous suspension carriers sourced from Gulf producers. Active ingredient synthesis concentrates in China, Germany, and the United States, with Yangtze River Delta chemical parks consolidating capacity as smaller formulators exit. Neonicotinoid precursors, microbial fermentation substrates, and pressurized propellants constitute critical input dependencies. Single-source vulnerability in backward-integrated neonicotinoid supply chains elevates concentration risk. Distribution runs through big-box home improvement chains with exclusive merchandising agreements, supplemented by direct-to-consumer channels for battery-powered applicator hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The home and garden pesticides market functions as a regulatory entrenchment moat, where parallel registration portfolios across EPA FIFRA and EU REACH frameworks create switching costs that deter challenger entry.
For Market Incumbents: Compound defensive positioning by expanding captive backward integration into biopesticide fermentation infrastructure and locking extended exclusive merchandising terms with big-box retail chains. Microbial platform substitution threatens synthetic formulation margins; vertical integration into active ingredient synthesis secures supply continuity amid regulatory uncertainty. For New Entrants and Emerging Players: Lead with battery-powered applicator hardware convergence in the Brazilian middle-class homeownership expansion, where subscription-based device-plus-consumable models face limited incumbent penetration. Direct-to-consumer channels bypass locked retail shelf access, though customer acquisition costs run higher than wholesale distribution. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated multinationals with parallel registration portfolios and captive precursor supply over retail-captive formulators dependent on merchandising leverage. Long-term viability rests on biopesticide platform readiness and OECD harmonization trajectory. The signal to monitor is EPA biopesticide policy alignment with European approval pathways, as divergence would fragment R&D returns and delay multi-jurisdictional product launches.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biopesticide Fermentation | Captive microbial production capacity secures formulation continuity under REACH authorization timelines. |
| Exclusive Retail Merchandising Extension | Locked shelf access at Home Depot and Lowe's anchors North American volume against challenger entry. |
| Battery-Powered Applicator Platform Launch | Electronics manufacturing convergence enables subscription-based recurring revenue models among landscaping contractors. |
| Parallel Registration Portfolio Expansion | Simultaneous EPA FIFRA and EU REACH submissions compress time-to-market across regulatory jurisdictions. |
| Urban Gardening Direct-to-Consumer Channel | Brazilian middle-class homeownership creates white space for convenience-oriented packaging and digital acquisition. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with formulation chemists, regulatory affairs directors at agrochemical multinationals, procurement managers at commercial landscaping companies, and category buyers at big-box home improvement chains; and secondary validation through EPA registration databases, ECHA authorization records, customs trade data for neonicotinoid precursor flows, and SEC 10-K filings of publicly traded suppliers. Bottom-up volume modeling triangulated against top-down market sizing across product type, formulation, application, and end-user segments.
Across the analysis window, the forecasting framework modeled herbicide, insecticide, fungicide, rodenticide, and molluscicide demand by liquid, aerosol, granular, powder, and emulsifiable concentrate formats, with end-user splits between residential consumers, landscaping companies, garden centers, pest control operators, and DIY retailers. CAGRs derived from regression analysis of historical volume trends, regulatory approval pipeline visibility, and urban gardening participation elasticity. Industry-specific inputs included EPA re-registration review timelines and EU Green Deal biocide restriction implementation schedules.
Underlying assumptions cover continued OECD biopesticide guideline harmonization and Brazilian middle-class homeownership expansion, with deviation risk concentrated in petrochemical feedstock volatility and veteran chemist retirement rates. Practitioners should keep alternative scenarios live as EPA-EU regulatory divergence and university extension program funding levels evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
Middle East and Africa Turf and Ornamental Grass Protection Market
Crop Protection
China Fungicide Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Asia Pacific Insecticide Market
Crop Protection
South America Molluscicides Market
Crop Protection
Global Organophosphate Pesticide Market
Crop Protection
Europe Soil Treatment Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Acetochlor Herbicide Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
China Insecticide Market
Crop Protection
North America Insecticide Market
Crop Protection
Tebuconazole Market