
 Canada Crop Protection Chemicals Market | 2026-2036
Canada Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Crop Protection Chemicals Market Outlook
Consolidation among Prairie grain elevators and farm-service cooperatives is repositioning procurement leverage toward fewer, larger buyers. BASF SE leverages its glufosinate-tolerant trait systems to sustain loyalty among canola growers facing blackleg pressure. Bayer AG anchors its position through digital-ag platforms bundled with seed-chemistry packages. Corteva Agriscience differentiates via its Enlist weed-control system, competing directly in the glyphosate-resistance-management segment.
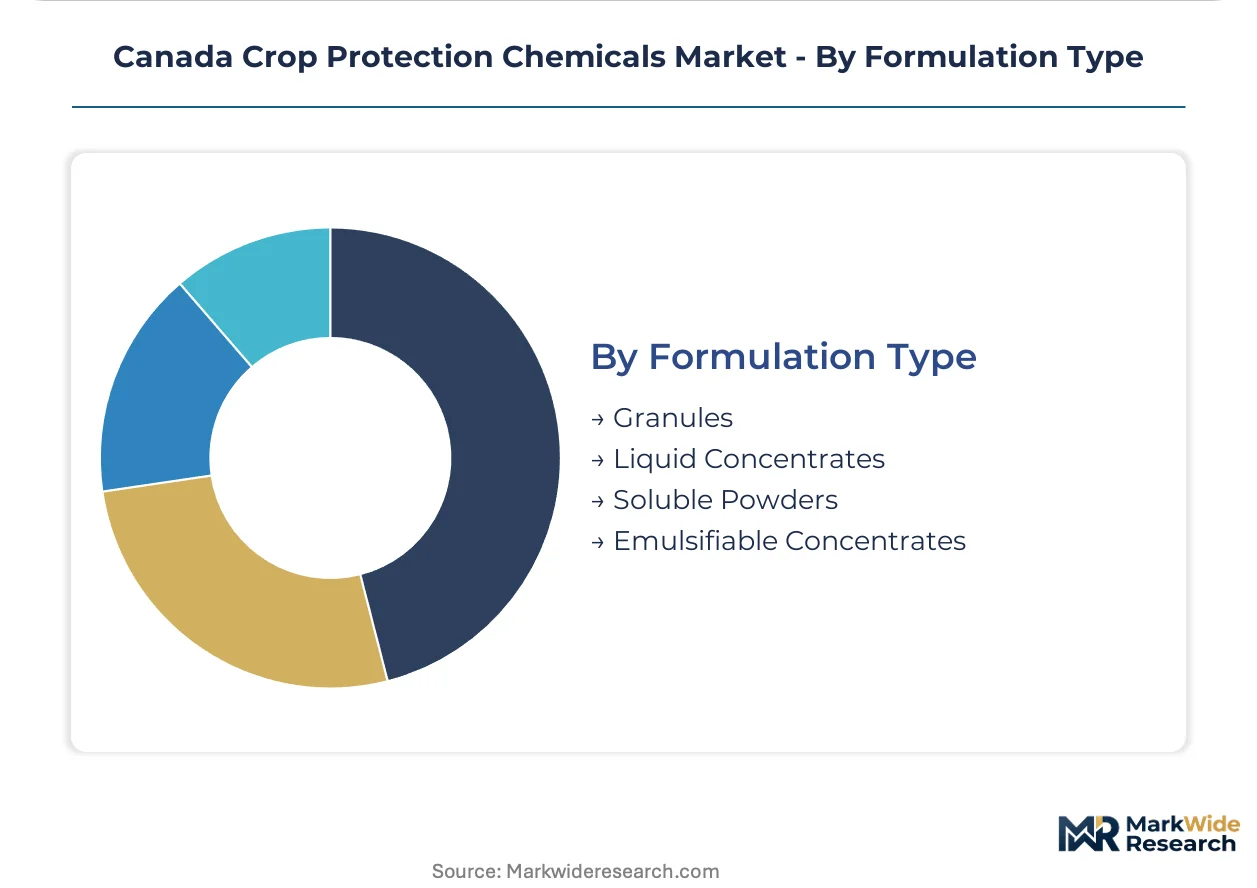
Canada crop protection chemicals comprise synthetic and biological formulations designed to manage weeds, insects, and fungal pathogens across commercial agriculture, with active ingredients typically applied at rates measured in grams per hectare to achieve field-level efficacy. These products serve the primary purpose of preserving yield potential and crop quality under variable climatic stress across the country's diverse agroecological zones. Herbicides command the largest share of product-type spending as glyphosate-resistant weed biotypes proliferate across the Prairies, while fungicide demand accelerates fastest in pulse and specialty-crop zones where moisture-driven disease pressure intensifies. Liquid concentrates dominate formulation-type volumes due to their compatibility with precision-spray equipment, though soluble powders retain margin strength in aerial-application markets serving remote northern acreage.
Health Canada's PMRA governs active-ingredient registration and maximum residue limits under the Pest Control Products Act, directly determining which chemistries gain market access and renewal timelines. The Pest Management Regulatory Agency's re-evaluation framework for neonicotinoids and chlorpyrifos analogues is forcing reformulation investments and accelerating biological-pesticide submissions from registrants. Provincial environmental farm plans in Alberta, Saskatchewan, and Manitoba layer additional buffer-zone and application-timing requirements that shape seasonal demand patterns. Stakeholders must monitor PMRA's cumulative risk-assessment pipeline and provincial buffer-rule harmonization to anticipate which product portfolios retain commercial viability.
Market Dynamics
Health Canada's PMRA is compressing re-registration timelines for legacy chemistries while Prairie grain elevators consolidate procurement leverage, forcing reformulation investments and biological-pesticide submissions from registrants seeking to retain market access.
Growth Catalysts
- Glyphosate-resistant weed proliferation:Kochia and wild oat biotypes spread across Saskatchewan and Manitoba canola belts, forcing growers toward multi-chemistry rotation protocols and expanding addressable demand for alternative herbicide modes of action.
- Pulse crop expansion:Saskatchewan lentil and pea acreage intensifies fungicide application rates as moisture-driven ascochyta and sclerotinia pressure climbs, creating seasonal demand spikes in specialty-crop zones.
- PMRA biological-pesticide fast-track:The agency's streamlined submission pathway for microbials and pheromones accelerates registrant pipeline conversion, lowering time-to-market for novel active ingredients.
Market Restraints
- Active ingredient supply concentration:China dominates technical-grade glyphosate and 2,4-D manufacturing, exposing Canadian formulators to tariff volatility and ocean freight disruptions.
- Neonicotinoid re-evaluation friction:PMRA's cumulative risk assessment for seed-treatment chemistries forces canola growers toward alternative flea beetle management without proven yield-equivalent substitutes.
- Application labor scarcity:Certified pesticide applicator shortages in rural Alberta and Manitoba compress spraying windows and delay resistance-management timing.
Strategic Opportunities
- Remote northern aerial markets:Soluble powder formulations compatible with float-plane application serve Peace River Valley and northwestern Ontario acreage underserved by ground rig infrastructure.
- Digital-ag platform bundling:Variable-rate prescription tools paired with chemistry recommendations capture data-integrated loyalty among Prairie cooperatives consolidating buying decisions.
- Provincial environmental farm plan incentives:Alberta's buffer-zone compliance credits reward biological-pesticide adoption, creating policy-tailored demand for Bacillus thuringiensis and mating-disruption products.
Industry Challenges
- Resistance-monitoring infrastructure gaps:Provincial extension services lack coordinated weed-survey funding, delaying early detection of novel herbicide-tolerant biotypes and compressing response timelines.
- Legacy equipment incompatibility:Enlist and LibertyLink trait systems require nozzle and tank-cleanout modifications that aging sprayer fleets in eastern Saskatchewan cannot accommodate without capital replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Crop Protection Chemicals Market |
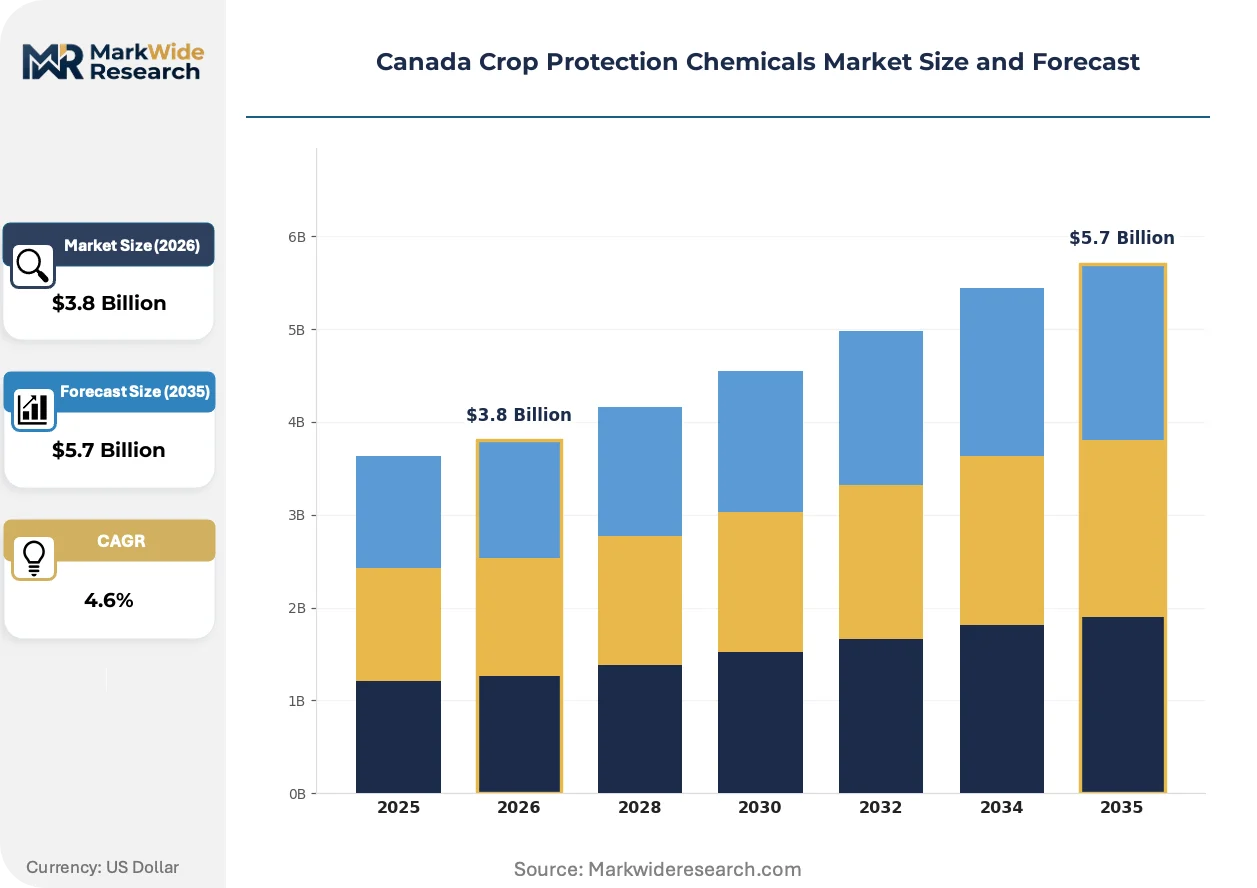
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Acaricides Application: Cereals, Oilseeds, Fruits, Vegetables End User: Farmers, Agricultural Cooperatives, Distributors, Exporters Formulation Type: Granules, Liquid Concentrates, Soluble Powders, Emulsifiable Concentrates |
| Companies Covered | BASF SE, Bayer AG, Corteva Agriscience, FMC Corporation, Syngenta Group, Nufarm Ltd, Nutrien Ltd, ADAMA Agricultural Solutions Ltd, UPL Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Crop Protection Chemicals Market Strategic Shifts
Biological-synthetic hybrid formulations and precision-application hardware are collapsing traditional boundaries between chemistry and data services, reshaping how Prairie growers purchase, apply, and verify crop protection outcomes.
RNA interference sprayable formulations targeting specific lepidopteran pests are unifying biological specificity with synthetic-scale manufacturing economics. Large-scale Saskatchewan canola operations piloted these products during the 2023-2024 growing seasons. The technology is unifying resistance-management protocols with reduced-residue export compliance, compressing the trade-off between yield protection and market access.
PMRA's cumulative risk-assessment framework for pollinator-exposed chemistries is forcing registrants toward sublethal-exposure study investments and pollinator mitigation label language. Seed-treatment manufacturers face reformulation deadlines without equivalent-efficacy alternatives for flea beetle control in canola. Saskatchewan's canola belt is responding with earlier planting windows and increased row-spacing to compensate for chemistry constraints.
Cooperative buying desks at Prairie grain elevators now aggregate spray-program decisions across ten-thousand-hectare footprints, displacing individual farm-level procurement. These consolidated buyers demand outcome-based performance guarantees from suppliers, shifting risk from grower to registrant. Manitoba's Red River Valley exhibits the most advanced contracting, with fungicide rebates tied to disease-pressure-index verification.
Canada Crop Protection Chemicals Market Segmentation
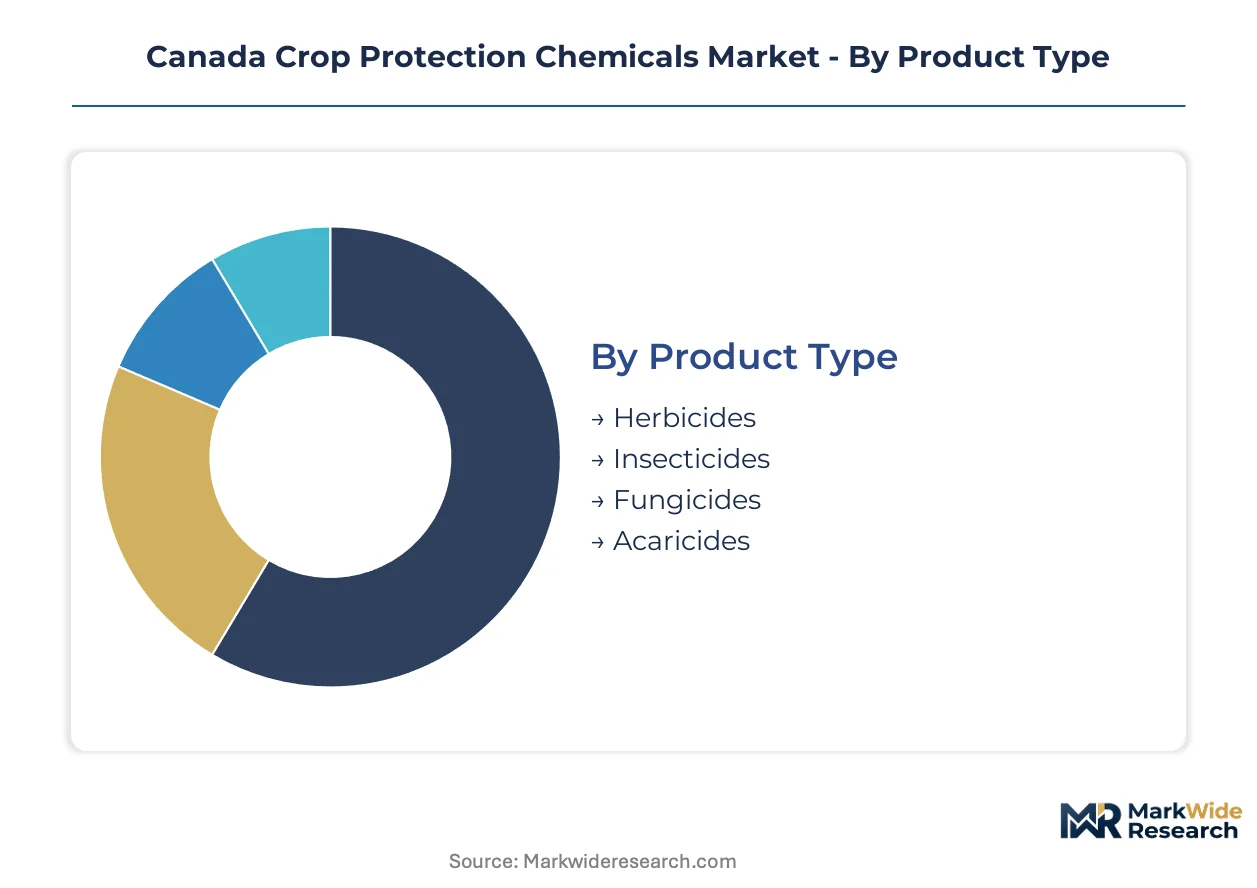
Segmentation reveals how Prairie procurement consolidation and PMRA regulatory pressure reshape demand patterns across chemistries, crops, and buyer channels. Each dimension exposes distinct margin pressures and growth vectors for registrants navigating Canada's tightening re-registration environment.
Product Type:
Herbicides dominate absolute volume while fungicides command premium pricing per hectare; the volume-premium split reflects resistance-management complexity versus commodity chemistry scale.
- Herbicides:Synthetic formulations targeting broadleaf and grassy weeds, with glyphosate, glufosinate, and Group 2 ALS inhibitors forming the backbone of Prairie programs. Saskatchewan's canola belt drives rotation-protocol demand as kochia resistance spreads, forcing multi-chemistry stacking that expands addressable spend per acre.
- Fungicides:Triazole and SDHI chemistries managing ascochyta, sclerotinia, and fusarium pressure in moisture-stressed zones. Saskatchewan lentil and pea expansion concentrates seasonal demand spikes where disease-index thresholds trigger aerial application at flowering windows.
- Insecticides:Pyrethroid and neonicotinoid alternatives for flea beetle, bertha armyworm, and grasshopper control. PMRA's seed-treatment re-evaluation pushes Alberta growers toward foliar rescue applications with compressed timing margins.
- Acaricides:Miticide chemistries for spider mite outbreaks in drought-stressed soybean and corn margins. Manitoba's Red River Valley specialty crop zones generate sporadic high-value demand during hot, dry growing seasons.
Today's leader: Herbicides. Tomorrow's challenger: Fungicides.
Application:
Crop-specific disease and weed pressure patterns determine formulation choice and application timing across Canada's agroecological gradient.
- Cereals:Wheat and barley acres in Alberta and Manitoba drive demand for Group 1 grass herbicides and Fusarium head blight fungicides. Fusarium graminearum pressure in Manitoba's Interlake region sustains triazole prophylaxis rates despite commodity price volatility.
- Oilseeds:Canola dominates chemistry spend per hectare through blackleg, sclerotinia, and herbicide-tolerant trait systems. Saskatchewan's canola belt anchors glufosinate and glyphosate demand while resistance protocols mandate rotation across four herbicide groups minimum.
- Fruits:Okanagan Valley orchards and Niagara Peninsula vineyards require specialized fungicide programs for powdery mildew and botrytis. British Columbia's tree fruit sector sustains niche demand for reduced-residue chemistries serving export certification.
- Vegetables:Ontario's Holland Marsh and Quebec's Montérégie muck soils drive insecticide and fungicide intensity for carrot, onion, and lettuce production. Processor contract specifications enforce maximum residue limit compliance that shapes product selection.
Oilseeds capture the steepest expansion trajectory through trait-chemistry bundling; cereals face volume compression from crop rotation economics.
End User:
Buyer consolidation is displacing farm-level procurement toward aggregated decision-making with performance-guarantee demands.
- Farmers:Individual Prairie grain operations above two thousand hectares retain direct supplier relationships for resistance-management advice. These growers negotiate early-order discounts and application-window priority during compressed spring seasons.
- Agricultural Cooperatives:Saskatchewan Wheat Pool and Federated Co-operatives aggregate spray programs across ten-thousand-hectare footprints. Cooperative buying desks now demand outcome-based rebates tied to disease-pressure-index verification from registrants.
- Distributors:Richardson Pioneer and Cargill AgHorizons manage inventory risk and logistics for remote northern delivery. These intermediaries buffer formulators from ocean freight volatility and provincial buffer-zone compliance complexity.
- Exporters:Grain handlers sourcing for EU and Asian markets impose maximum residue limit protocols that filter permissible chemistries. Canola exporters to Europe enforce neonicotinoid-free certification that constrains seed-treatment options.
Agricultural cooperatives are consolidating procurement leverage fastest; exporters exert growing chemistry-selection authority through certification gatekeeping.
Formulation Type:
Equipment compatibility and application method determine formulation economics across ground rig versus aerial delivery channels.
- Liquid Concentrates:Suspension and solution formulations compatible with precision-spray electronics and pulse-width modulation nozzles. Prairie ground rig fleets favor these products for variable-rate prescription compatibility and tank-mix flexibility.
- Soluble Powders:Dry formulations reconstituting for aerial application via fixed-wing and rotary equipment. Peace River Valley and northwestern Ontario operations depend on float-plane delivery where ground infrastructure is absent.
- Emulsifiable Concentrates:Oil-based carriers for lipophilic active ingredients requiring penetration aids. These formulations retain share in perennial weed control programs where cuticle penetration determines efficacy.
- Granules:Soil-applied formulations for pre-emergence herbicide and insecticide delivery. Row-crop vegetable operations in Ontario and Quebec favor banded granule application for reduced drift liability near urban boundaries.
Liquid concentrates anchor current volume; soluble powders gain share through northern aerial market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saskatchewan generates higher crop protection chemical spend per hectare than Ontario, reflecting canola's intensive trait-chemistry bundling versus corn-soybean rotations. Provincial regulatory layering and cooperative procurement consolidation create distinct sub-national markets within Canada's federal structure.
Prairie Provinces
Saskatchewan's canola belt drives glufosinate and glyphosate demand through blackleg and sclerotinia pressure, while Manitoba's Red River Valley concentrates fungicide application on pulse crops. Health Canada's PMRA buffer-zone requirements intersect with provincial environmental farm plans to shape seasonal application windows. Federated Co-operatives and Saskatchewan Wheat Pool buying desks now aggregate spray programs across ten-thousand-hectare footprints around Saskatoon and Regina.
Ontario
Holland Marsh vegetable operations and Niagara Peninsula tender fruit production sustain specialized fungicide and insecticide demand for processor contract compliance. Ontario's Ministry of Agriculture enforces maximum residue limit protocols that filter permissible chemistries for EU and Asian export markets. The province's grain elevator consolidation lags Prairie levels, preserving more farm-level procurement autonomy around Guelph and London.
Quebec
Montérégie muck soil vegetable production drives high-intensity pest management programs for carrot, onion, and lettuce supply chains. Quebec's provincial environmental regulations layer additional application-timing restrictions beyond federal PMRA baselines. Cooperative buying structures around Saint-Hyacinthe aggregate demand from smaller-scale operations than Prairie counterparts.
British Columbia
Okanagan Valley orchards and vineyards require reduced-residue chemistries serving export certification to Asian and European markets. The province's tree fruit sector sustains niche demand distinct from Prairie commodity grain patterns. Vancouver-based distributors manage import logistics for specialty formulations serving this coastal concentration.
Atlantic Canada
Potato production in Prince Edward Island and New Brunswick generates concentrated fungicide demand for late blight management in moisture-prone growing seasons. Regional procurement runs through fewer distributor nodes than central Canada, creating price transmission lags. Provincial extension services coordinate resistance monitoring with less funding than Prairie counterparts.
Canada Crop Protection Chemicals Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Canada's tightening regulatory environment. The market structure concentrates around six major registrants with integrated seed-chemistry platforms, while mid-tier formulators serve geographic niches and specialty crops. Three archetypes dominate: global integrated life-science conglomerates with trait systems, regional formulators with distribution depth, and biological-pesticide specialists exploiting PMRA fast-track pathways. Competitive moves center on digital-ag platform bundling and biological pipeline acquisitions.
Among global integrated players, BASF SE, Bayer AG, and Corteva Agriscience occupy positions defined by trait-chemistry integration. BASF SE exemplifies the glufosinate-tolerant system archetype sustaining loyalty among canola growers. Bayer AG anchors the digital-ag platform bundling approach, pairing prescription tools with chemistry recommendations. Corteva Agriscience represents the Enlist weed-control system specialization, competing directly in glyphosate-resistance management segments. These three conglomerates collectively shape Prairie cooperative procurement negotiations.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Corteva Agriscience |
| FMC Corporation |
| Syngenta Group |
| Nufarm Ltd |
| Nutrien Ltd |
| ADAMA Agricultural Solutions Ltd |
| UPL Limited |
| Others |
Value Chain & Pricing Dynamics
Technical-grade glyphosate spot prices in China cascade through Canadian formulator margins into Prairie cooperative procurement tiers, compressing price floors for generic herbicides while premium trait-chemistry bundles retain pricing power through resistance-management protocols.
Pricing Analysis
Capacity additions in Chinese technical manufacturing are reshaping price floors for commodity herbicides across Prairie grain elevators. Three-tier pricing structure across premium, standard, and economy levels separates glufosinate-tolerant trait systems from generic glyphosate and economy 2,4-D formulations. Price differentiation hinges on certification grade for export-compliant residue limits and volume scale through cooperative aggregation. Pricing pressure stems from ocean freight volatility and tariff exposure on Chinese technical imports. Small-scale eastern Saskatchewan growers exhibit highest price sensitivity; large-scale Saskatchewan Wheat Pool members command volume rebates and application-window priority.
Supply Chain Analysis
Single-source vulnerability sits with Chinese technical-grade glyphosate and 2,4-D manufacturing concentration. Canadian formulators draw from China, India, and the United States for active ingredient supply, with formulation and packaging anchored in Alberta and Manitoba. Raw material dependencies center on technical-grade active ingredients, specialized surfactants, and polymer seed-coating carriers. Supply chain risk concentrates in tariff exposure and ocean freight disruption through Vancouver port congestion. Distribution runs through Richardson Pioneer and Cargill AgHorizons nodes buffering remote northern delivery logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada crop protection chemicals market represents a late-cycle quality story where Prairie cooperative consolidation and PMRA regulatory tightening shift procurement toward premium biological-synthetic hybrid formulations with verified resistance-management outcomes.
For Market Incumbents: Anchor market position through backward integration into biological active ingredient production and PMRA fast-track pipeline investments. Defensive consolidation should prioritize digital-ag platform bundling to capture data-integrated loyalty among Federated Co-operatives buying desks. The threat of RNA interference sprayable formulations from emerging biotech entrants demands accelerated Enlist and LibertyLink trait-chemistry integration. For New Entrants and Emerging Players: Launch via soluble powder formulations compatible with float-plane aerial application serving Peace River Valley and northwestern Ontario acreage underserved by ground rig infrastructure. White-space targets include remote northern markets lacking distributor coverage and Alberta buffer-zone compliance credit programs rewarding Bacillus thuringiensis adoption. Biological-pesticide specialists should exploit PMRA's streamlined microbial submission pathway for faster time-to-market. For Investors and Strategic Acquirers: Asymmetric upside sits with biological-pesticide specialists possessing PMRA fast-track approvals and Prairie cooperative distribution relationships. Long-term viability over a five-to-ten year window favors registrants with integrated seed-chemistry platforms and digital prescription tool capabilities. Acquisition targets should demonstrate resistance-management protocol adoption across Saskatchewan's canola belt. The signal to watch is PMRA cumulative risk-assessment pipeline announcements for neonicotinoid and chlorpyrifos analogues.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biological Active Ingredients | Captures margin from Chinese technical supply concentration while meeting PMRA fast-track demand. |
| Digital-Ag Platform Bundling | Bayer AG's prescription tool integration with chemistry recommendations sets loyalty standard for Prairie cooperatives. |
| PMRA Fast-Track Pipeline Investment | Microbial and pheromone submissions accelerate registrant time-to-market versus synthetic re-registration timelines. |
| Remote Northern Aerial Formulation Development | Soluble powder compatibility with float-plane delivery opens Peace River Valley acreage absent ground infrastructure. |
| Cooperative Buying Desk Performance Contracts | Outcome-based rebates tied to disease-pressure-index verification shift risk from grower to registrant. |
Study Parameters
Coverage spans Prairie Provinces, Ontario, Quebec, and British Columbia, with primary inputs from each region combined with secondary validation. Primary interviews engaged crop protection registrant R&D directors, Prairie cooperative procurement managers, PMRA regulatory affairs specialists, and grain elevator agronomists. Secondary sources included Health Canada PMRA registration databases, provincial environmental farm plan documentation, Agriculture and Agri-Food Canada trade statistics, and SEC 10-K filings of listed agrochemical conglomerates. Bottom-up volume modeling triangulated against top-down value estimates across product type, application, and end-user segments.
Granularity-level modeling deployed province-by-province acreage projections, crop-specific disease pressure indices, and cooperative procurement consolidation trajectories. Segmentation dimensions included product type chemistry class, application crop family, end-user buyer archetype, and formulation equipment compatibility. CAGRs derived from weighted average of historical volume trends and forward-looking regulatory constraint scenarios. Industry-specific forecast inputs incorporated PMRA re-evaluation pipeline status and Prairie precipitation-driven disease pressure variability.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme weather volatility or accelerated PMRA withdrawal timelines for legacy chemistries. Forecasts reflect assumptions around cooperative buying desk consolidation pace and biological-pesticide adoption rates. Specific risk factors that could revise projections include China-Canada trade friction disrupting technical supply, provincial buffer-zone rule harmonization failures, and novel herbicide-resistant weed biotype detection compressing chemistry rotation options. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
Tembotrione Market
Crop Protection
Japan Crop Protection Chemicals Market
Crop Protection
Trapping and Mating Disruption Systems Market
Crop Protection
Seed Treatment Materials Market
Crop Protection
Global Termite Control Market
Crop Protection
Generic Crop Protection Chemicals Market
Crop Protection
Organic Pesticides Market
Crop Protection
France Crop Protection Chemicals Market
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Propiconazole Market
Crop Protection
Europe Insecticides Market
Crop Protection
Europe Molluscicides Market
Crop Protection
Global Acephate Market