
 Isoxaflutole Market | 2026-2036
Isoxaflutole Market Size, Share, and Industry Trends Forecast 2026-2036
Isoxaflutole Market Foresight
Aftermarket resistance-management advisory services is reshaping margin distribution across the Isoxaflutole value chain. Corteva Agriscience leverages its seed-trait integration platforms to bundle herbicide recommendations with proprietary genetics. Bayer CropScience anchors its position through deep R&D investment in HPPD-inhibitor formulation science. Syngenta competes on geographic breadth, sustaining channel density across North American corn belts.
Isoxaflutole is a selective pre-emergence HPPD-inhibiting herbicide with a molecular weight of 359.32 g/mol, formulated primarily as emulsifiable concentrates or suspension concentrates for broadleaf and grass weed control in corn and sugarcane. The herbicide functions by disrupting carotenoid biosynthesis, causing bleaching symptoms in susceptible weeds before crop canopy closure. Agricultural Crops dominates volume absorption, with corn and soybean applications commanding the largest share of active ingredient demand. Liquid formulations lead the product mix due to ease of tank-mixing and precision application compatibility, while granule formats retain niche positions in soil-incorporation regimes. Direct sales channels capture premium-margin relationships with large-scale farming cooperatives, though distributor networks still handle the majority of volume throughput to mid-tier growers.
EPA registration requirements under FIFRA mandate extensive environmental fate studies for isoxaflutole metabolites, particularly concerning groundwater mobility assessments in vulnerable soil zones. The EU REACH framework and EFSA residue evaluations constrain import tolerance alignment for grain destined for European food and feed channels. China's NMPA and Ministry of Agriculture standards govern domestic manufacturing quality and export certification for Chinese producers like Shandong Binnong Technology. Stakeholders must monitor evolving metabolite regulation thresholds and trait-stacking approval timelines that condition product utility across major corn-producing jurisdictions.
Market Dynamics
Herbicide resistance management protocols are restructuring demand patterns across the Isoxaflutole market as growers rotate chemistries to preserve HPPD-inhibitor efficacy against evolving weed biotypes.
Growth Catalysts
- EPA FIFRA re-registration requirements:Stringent metabolite study mandates under FIFRA are accelerating formulation upgrades that extend product lifecycle viability in US corn belts.
- No-till farming expansion:Soil conservation practices across the US Midwest are amplifying pre-emergence herbicide dependency where mechanical weed control is minimized.
- Palmer amaranth pressure:Glyphosate-resistant weed populations in southern soybean regions are forcing growers toward HPPD-inhibitor stacks including isoxaflutole.
Market Restraints
- Active ingredient supply concentration:Manufacturing of HPPD-inhibitor intermediates concentrates among specialized Chinese chemical producers, exposing formulators to input volatility.
- Groundwater mobility constraints:EPA environmental fate assessments for isoxaflutole metabolites restrict application windows in vulnerable aquifer zones.
- Herbicide resistance cycling requirements:Mandatory rotation protocols under resistance management plans compress single-chemistry revenue windows.
Strategic Opportunities
- Brazilian sugarcane expansion:Cerrado region cane cultivation offers untapped volume potential for pre-emergence HPPD-inhibitor applications.
- Seed-trait integration platforms:Stacking isoxaflutole tolerance genes with insect resistance traits creates bundled input offerings.
- Precision application technology:Variable-rate sprayers combined with drone-based field mapping enable site-specific herbicide deposition.
Industry Challenges
- Metabolite analytical capacity:Commercial labs capable of quantifying isoxaflutole degradates at regulatory detection limits remain scarce in rural agricultural regions.
- Application timing coordination:Pre-emergence windows require precise weather forecasting integration that many distributor advisory services lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isoxaflutole Market |
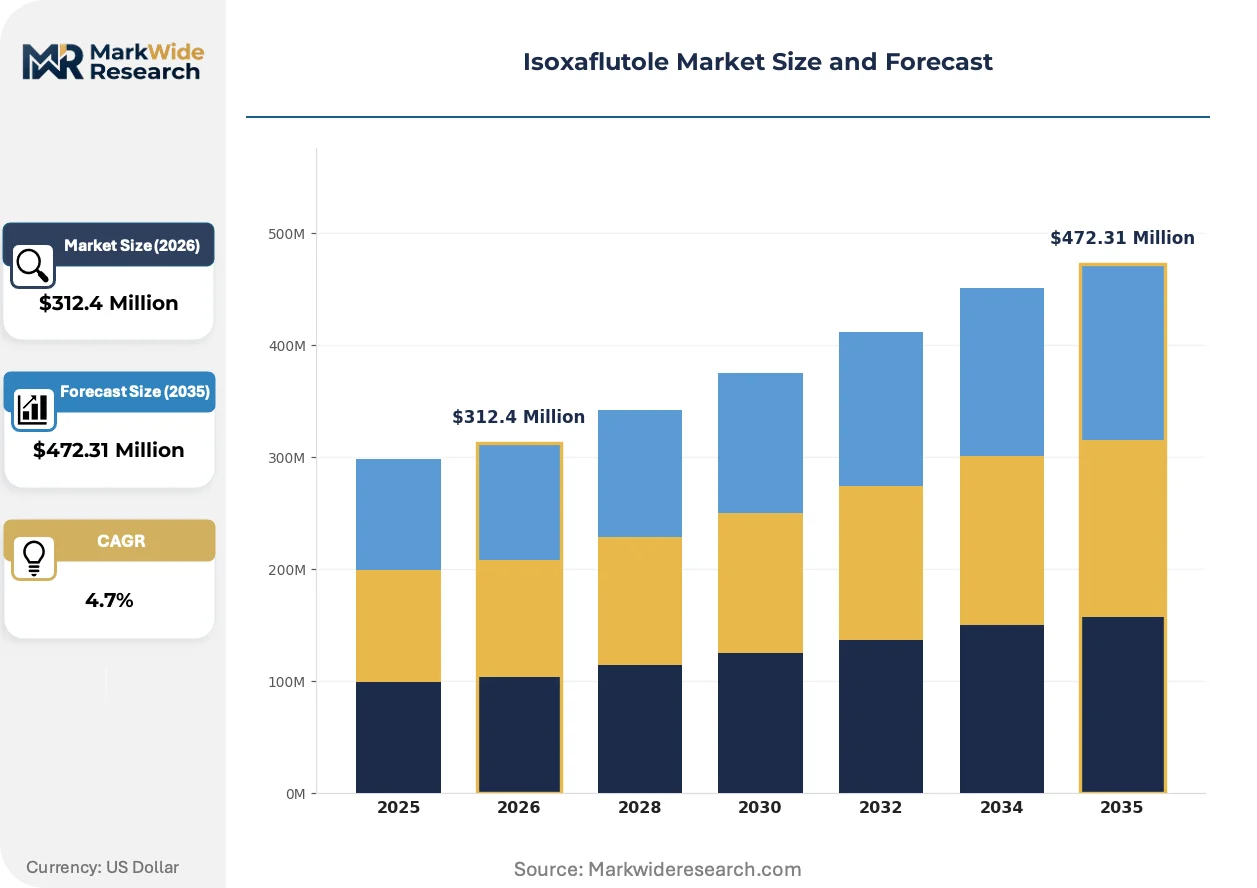
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicide, Insecticide, Fungicide, Pesticide Application: Agricultural Crops, Horticulture, Turf Management, Soil Treatment Formulation: Granule, Liquid, Powder, Suspension Distribution Channel: Online Retail, Direct Sales, Distributors, Agrochemicals Suppliers |
| Companies Covered | Corteva Agriscience, ADAMA, Bayer CropScience, FMC Corporation, Nufarm, Syngenta, UPL, Shandong Binnong Technology, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isoxaflutole Market Shifts & Advancements
Formulation chemistry advances and digital agriculture tools are compressing application error rates while regulatory metabolite scrutiny intensifies product stewardship requirements.
Micro-encapsulated suspension concentrate technology is collapsing the efficacy gap between liquid and granular delivery systems. Large-scale corn cooperatives in Iowa and Illinois are adopting these formulations for improved rainfastness. The technology is collapsing residual activity variability that previously drove growers toward soil-incorporation methods.
EFSA residue evaluation protocols for HPPD-inhibitor metabolites are tightening maximum residue limits for grain entering European food and feed channels. Export-oriented US elevators now require pre-harvest interval documentation that conditions supplier relationships with formulators. Corn destined for EU markets faces stricter analytical certification than domestic consumption channels.
Outcome-based agronomic advisory contracts are displacing product-centric sales relationships across the US agricultural belt. Farming cooperatives in Nebraska and Kansas now compensate distributors on weed control performance metrics rather than volume throughput. This restructuring concentrates purchasing authority among technical service providers with soil science capabilities.
Isoxaflutole Market Segmentation
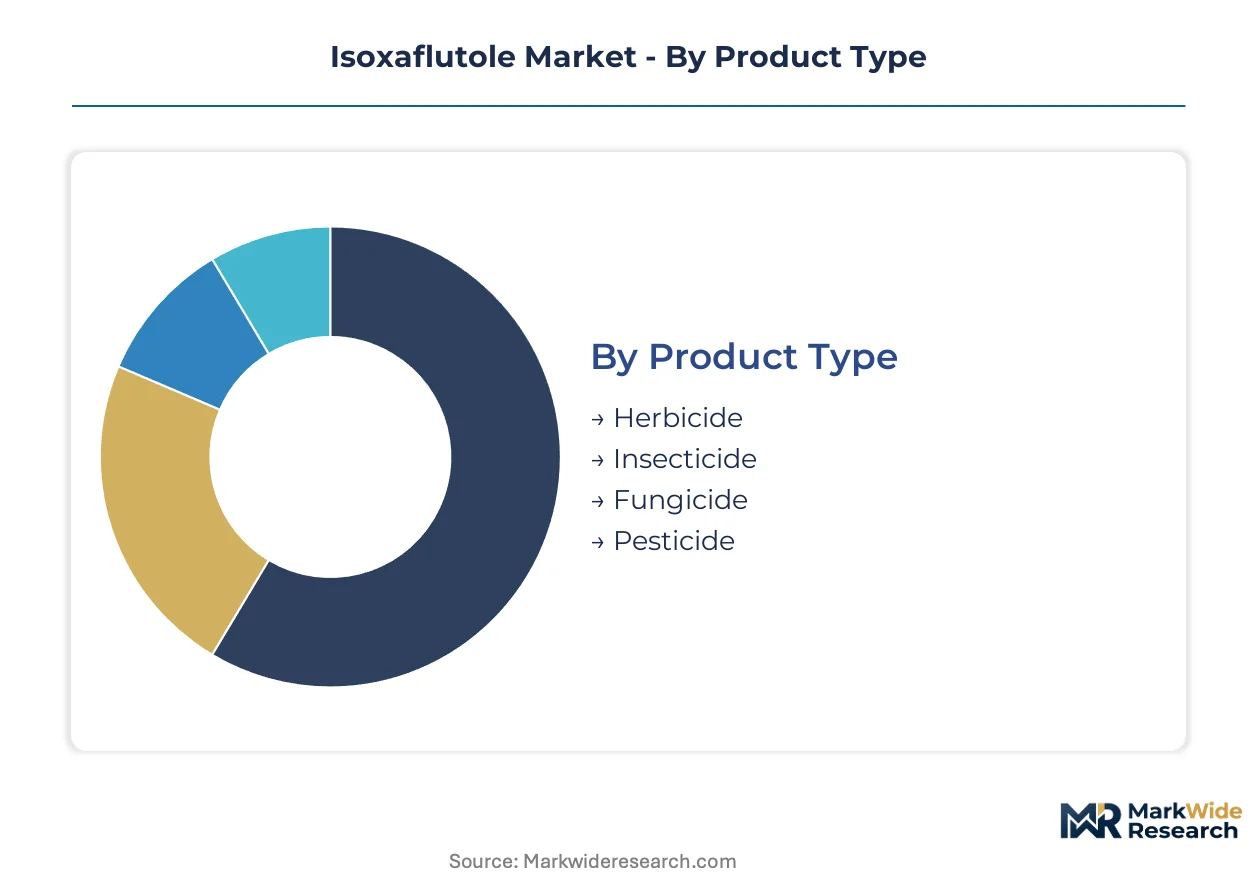
Isoxaflutole's commercial structure fragments across four critical dimensions that determine pricing power, channel access, and regulatory exposure. Each segmentation layer reveals distinct margin profiles and competitive dynamics that shape go-to-market strategy for HPPD-inhibitor formulators.
Product Type:
Use-case spectrum spans from broad-spectrum weed control to specialized crop protection, with herbicide chemistry commanding the primary commercial focus.
- Herbicide:HPPD-inhibiting chemistry disrupts carotenoid biosynthesis in susceptible weeds, causing pre-emergence bleaching symptoms before crop canopy closure. Corn and soybean growers across the US Midwest drive concentrated uptake as glyphosate resistance management becomes operationally critical. EPA FIFRA re-registration requirements for metabolite environmental fate studies condition formulation investments and product lifecycle extensions.
- Insecticide:Pyrethroid and neonicotinoid chemistries target corn rootworm and aphid populations in integrated pest management protocols. Seed-trait integration platforms from major agrichemical firms bundle insect resistance with herbicide tolerance genetics, compressing standalone insecticide margins in row-crop applications.
- Fungicide:Azole and strobilurin formulations address foliar diseases in high-value horticulture and specialty crop segments.
- Pesticide:Broad-spectrum synthetic and biological agents serve niche soil fumigation and stored-grain protection applications.
The dominant share belongs to Herbicide, while Insecticide is closing the gap fastest through trait-stacking bundling.
Application:
Cost tier stratification separates commodity row-crop volume from premium horticulture margins, with input intensity per acre varying tenfold across the spectrum.
- Agricultural Crops:Corn and soybean cultivation absorbs the majority of isoxaflutole volume, with pre-emergence applications timed to soil temperature thresholds and planting windows. No-till farming expansion across Iowa, Illinois, and Nebraska amplifies dependency on chemical weed control where mechanical cultivation is eliminated. Palmer amaranth pressure in southern soybean regions forces rotation toward HPPD-inhibitor stacks.
- Horticulture:Vegetable and fruit production commands premium pricing for specialized formulations with shorter pre-harvest intervals. California's Central Valley and Florida's winter vegetable belt concentrate demand for residue-sensitive chemistries that meet EFSA import tolerance standards for EU-bound produce.
- Turf Management:Golf course and sports field maintenance drives seasonal demand for aesthetic weed control with rapid visual results.
- Soil Treatment:Pre-plant fumigation and nematode suppression applications serve potato and vegetable rotations in the Pacific Northwest.
Agricultural Crops captures volume leadership, though Horticulture delivers the steepest expansion trajectory on per-acre value metrics.
Formulation:
Application technology compatibility and rainfastness requirements determine formulation selection, with liquid systems dominating precision agriculture adoption.
- Liquid:Emulsifiable concentrates and suspension concentrates enable seamless tank-mixing with adjuvants and micronutrients in variable-rate sprayer systems. Iowa and Illinois cooperatives favor liquid formats for drone-based field mapping integration and site-specific deposition control. Micro-encapsulated suspension technology is collapsing residual activity variability that previously drove growers toward soil-incorporation methods.
- Suspension:Concentrated aqueous dispersions offer improved stability in hard water conditions common across the Great Plains.
- Granule:Clay-based carriers suit soil-incorporation regimes in sugarcane and vegetable transplant operations.
- Powder:Wettable powder formats retain niche positions in manual backpack sprayer applications for smallholder plots.
Liquid formulations hold the dominant position, while Suspension formats are gaining share fastest through improved compatibility with precision equipment.
Distribution Channel:
Customer type segmentation separates enterprise-scale cooperatives seeking technical advisory bundles from price-sensitive mid-tier growers served through distributor networks.
- Distributors:Independent agricultural retailers handle the majority of volume throughput to mid-tier growers across the Corn Belt, combining credit extension with seasonal inventory positioning. Nebraska and Kansas distributors now face outcome-based compensation contracts tied to weed control performance metrics rather than volume throughput.
- Direct Sales:Large-scale farming cooperatives in Iowa and Illinois negotiate premium-margin relationships with formulators, bypassing distributor markups for thousand-acre-plus operations with in-house agronomy staff.
- Agrochemicals Suppliers:Regional blending facilities and formulator-owned depots serve custom applicator fleets and cooperative buying groups.
- Online Retail:E-commerce platforms capture price-sensitive spot purchases for replacement inventory and emergency resupply scenarios.
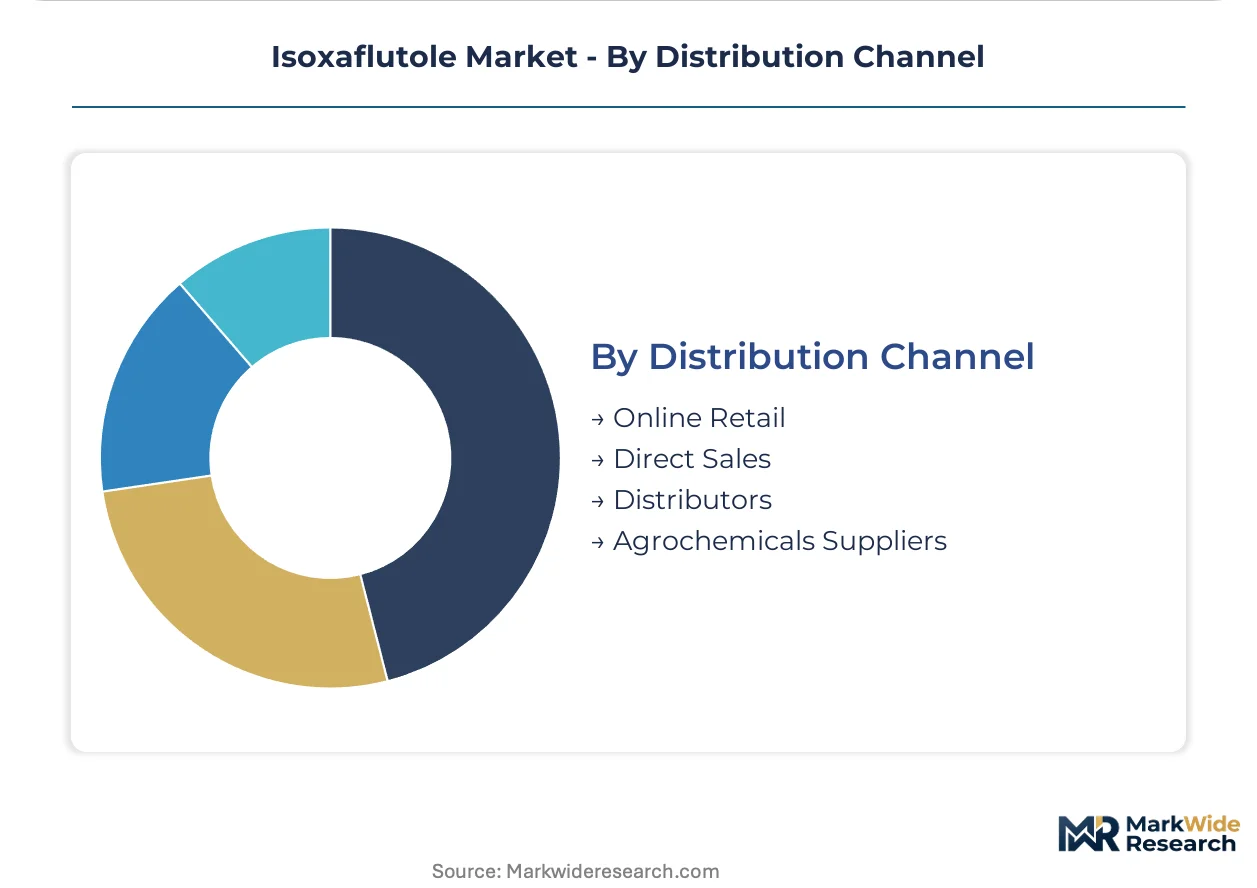
Distributors maintain volume dominance, though Direct Sales channels are expanding most quickly as cooperative consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern US growers exhibit the lowest price elasticity for isoxaflutole formulations due to resistance-management imperatives, while Brazilian sugarcane operators remain highly sensitive to input costs amid currency volatility. European grain exporters face the tightest regulatory constraints on metabolite residues.
United States
Iowa and Illinois corn cooperatives drive concentrated uptake of HPPD-inhibitor stacks as Palmer amaranth populations expand northward. EPA FIFRA re-registration mandates for metabolite environmental fate studies condition formulation investments and product lifecycle extensions. The Corn Belt's no-till farming belt amplifies pre-emergence herbicide dependency where mechanical weed control is eliminated.
Brazil
São Paulo state sugarcane mills represent untapped volume potential for pre-emergence HPPD-inhibitor applications in Cerrado expansion zones. ANVISA residue evaluation protocols govern import tolerance alignment for grain destined for domestic food and feed channels. Mato Grosso soybean operations increasingly rotate toward HPPD-inhibitor chemistry as glyphosate resistance spreads.
China
Shandong province chemical manufacturers concentrate active ingredient production for HPPD-inhibitor intermediates, exposing formulators to input volatility. NMPA and Ministry of Agriculture standards govern domestic manufacturing quality and export certification for producers like Shandong Binnong Technology. Yangtze River Delta formulation facilities serve both captive demand and international contract manufacturing.
Argentina
Buenos Aires province soybean growers face intensifying weed resistance pressure that forces rotation toward HPPD-inhibitor stacks including isoxaflutole. The country's national agricultural regulator mandates residue monitoring for export-bound grain shipments. Pampas region no-till adoption rates exceed regional averages, amplifying chemical weed control dependency.
Germany
Bavaria and Baden-Württemberg specialty crop producers command premium pricing for residue-sensitive formulations meeting EFSA import tolerance standards. ECHA REACH framework and EFSA residue evaluations constrain tolerance alignment for grain entering European food and feed channels. BASF's Ludwigshafen headquarters anchors HPPD-inhibitor formulation R&D investment for EU market compliance.
Isoxaflutole Market Competitive Landscape
Capability concentration sits with integrated seed-chemistry platforms; scale advantage sits with broad-spectrum agrochemical portfolios. The vendor base organizes around three strategic archetypes: trait-integrated input bundlers, standalone herbicide formulators, and regional generic manufacturers. Consolidation pressure intensifies as resistance-management protocols favor technical advisory relationships over transactional volume. Dominant competitive moves include seed-trait licensing partnerships and precision application technology alliances.
Among integrated agrichemical platforms, Corteva Agriscience and Bayer CropScience exemplify the trait-bundling archetype that collapses herbicide and genetics decisions into unified purchasing frameworks. Syngenta occupies a position spanning both proprietary chemistry and geographic channel density across North American corn belts. Shandong Binnong Technology represents the regional manufacturing tier concentrated in Chinese intermediate supply.
| Leading Market Players |
|---|
| Corteva Agriscience |
| ADAMA |
| Bayer CropScience |
| FMC Corporation |
| Nufarm |
| Syngenta |
| UPL |
| Shandong Binnong Technology |
| BASF |
| Others |
Supply & Pricing Matrix
Overcapacity in Shandong province HPPD-inhibitor intermediate production is compressing input costs while simultaneously eroding supplier pricing discipline, forcing formulators to choose between margin retention and volume defense through extended payment terms to downstream distributors.
Pricing Analysis
Contract-based long-term offtake agreements dominate volume relationships between formulators and large-scale corn cooperatives in Iowa and Illinois, while spot purchases handle emergency resupply scenarios. Price differentiation rests on formulation technology tier—micro-encapsulated suspension concentrates command premium positioning against standard emulsifiable concentrates—and bundled seed-trait integration depth. Cost compression in generic intermediate supply is intensifying because Chinese manufacturers compete on utilization rates rather than technical specifications. Mid-tier growers served through independent distributors exhibit the highest price sensitivity, whereas enterprise cooperatives with in-house agronomy staff prioritize performance guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from Shandong province intermediate suppliers now stretch 90-120 days as utilization pressure mounts, exposing formulators to working capital strain during seasonal inventory build. Active ingredient production concentrates in China, with formulation finishing distributed across the US Midwest, Brazil, and Germany. Supply chain risk centers on single-source vulnerability for HPPD-inhibitor chemistry precursors subject to environmental compliance shutdowns. Distribution runs through independent agricultural retailers handling credit extension and seasonal positioning to mid-tier growers, though direct sales channels capture premium-margin relationships with consolidated cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outcome-based agronomic advisory contracts represent the fastest-expanding revenue layer, displacing product-centric sales relationships as farming cooperatives compensate distributors on weed control performance metrics rather than volume throughput.
For Market Incumbents: Entrench position through captive supply of HPPD-inhibitor intermediates via backward integration into Chinese manufacturing partnerships or long-term offtake agreements with Shandong producers. Deepen seed-trait integration platforms to bundle herbicide recommendations with proprietary genetics, raising switching costs against generic formulators. Corteva Agriscience and Bayer CropScience demonstrate this archetype through stacked tolerance gene offerings.
For New Entrants and Emerging Players: Brazilian sugarcane expansion zones in the Cerrado region represent the most penetrable entry point for pre-emergence HPPD-inhibitor volume build, as established players underinvest in application timing advisory services for this crop system. Precision application technology partnerships with drone-based field mapping providers offer a differentiated go-to-market angle that collapses application error rates and justifies premium positioning.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because resistance-management protocols favor technical advisory relationships over transactional volume, concentrating purchasing authority among service-capable distributors. Target acquisition archetypes include regional formulators with soil science capabilities and established cooperative relationships. Monitor EPA metabolite regulation threshold revisions as the critical inflection signal—tightening standards would accelerate formulation R&D investment requirements and disadvantage undercapitalized competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Seed-Trait Integration Partnership | Bundles herbicide tolerance genetics with insect resistance, collapsing input purchasing decisions into unified frameworks. |
| Precision Application Technology Alliance | Combines variable-rate sprayers with drone-based field mapping for site-specific deposition control in Iowa and Illinois cooperatives. |
| Backward Integration into Intermediate Supply | Captures HPPD-inhibitor precursor production through Shandong manufacturing partnerships or long-term offtake structures. |
| Outcome-Based Advisory Contract Expansion | Shifts distributor compensation from volume throughput to weed control performance metrics across Nebraska and Kansas. |
| Metabolite Analytical Capacity Investment | Addresses commercial lab scarcity for quantifying isoxaflutole degradates at EPA regulatory detection limits in rural regions. |
Research Methodology
A standing panel of herbicide formulator R&D directors, agricultural cooperative procurement managers, and EPA regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with distribution channel partners and Shandong province intermediate suppliers combined with secondary validation from EPA FIFRA registration databases, EFSA residue evaluation protocols, and customs trade data. Bottom-up volume modeling triangulated against top-down agrichemical market assessments.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions including formulation technology tier, crop application intensity, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for resistance-management protocol adoption curves and no-till farming expansion rates. Specific inputs incorporated Palmer amaranth pressure indices and EPA metabolite study timelines.
Practitioners should monitor ANVISA residue protocol revisions and EU REACH framework amendments for early signals of tolerance alignment shifts. Forecasts reflect documented assumptions regarding cooperative consolidation velocity and precision agriculture adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Pest Control Market
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Tebufenozide Market
Crop Protection
Indonesia Fungicide Market
Crop Protection
Chile Crop Protection Chemicals Market
Crop Protection
Specialty Pesticides Market
Crop Protection
Europe Nematicide Market
Crop Protection
US Herbicide Market
Crop Protection
North America Nematicides Market
Crop Protection
US Insecticide Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
North America Acaricides Market
Crop Protection
Urban Rooftop Farm-Safe Pest Management Chemistry Market
Crop Protection
Soil Fumigant Market
Crop Protection
Global Organophosphate Pesticide Market
Crop Protection
South Korea Crop Protection Chemicals Market