
 Global Insecticides Market | 2026-2036
Global Insecticides Market Size, Share, and Industry Trends Forecast 2026-2036
Global Insecticides Market Foresight
Specialty fruit and vegetable cultivation is decoupling from broad-acre cereal applications as the primary demand vector for insecticide manufacturers. Bayer AG leverages its biologicals pipeline to anchor positions in integrated pest management systems across high-value horticulture. Syngenta Group sustains R&D intensity in neonicotinoid alternatives following regulatory restrictions in European jurisdictions. FMC Corporation specializes in diamide chemistry for lepidopteran control, occupying a defensible niche in vegetable seed treatment.
Insecticides comprise synthetic and naturally derived chemical formulations designed to disrupt arthropod nervous systems, metabolism, or growth regulation, typically applied at rates between 0.1 and 2.0 kilograms active ingredient per hectare depending on pest pressure and crop stage. Their primary commercial purpose centers on protecting yield quantity and quality in agricultural systems while managing vector-borne disease transmission in public health programs. Neonicotinoid demand is contracting across European markets as REACH and EU Green Deal frameworks tighten ecological risk assessments, while pyrethroid formulations retain dominance in sub-Saharan malaria control programs. Botanical extracts represent the fastest-expanding product category as greenhouse operators in the Netherlands and Israel adopt residue-free protocols for export-oriented tomato and pepper production.
The EPA governs insecticide registration through FIFRA-mandated ecological toxicity reviews, while India's Central Insecticides Board enforces label compliance under the Insecticides Act of 1968. Brazil's ANVISA and IBAMA jointly evaluate human health and environmental endpoints, creating dual-track approval complexity for multinational registrants. China's MEE has tightened effluent standards for organophosphate manufacturing clusters in Jiangsu Province. Stakeholders must monitor regulatory divergence between jurisdictions that accept hazard-based cutoffs versus those maintaining risk-assessment frameworks, as this schism determines portfolio viability and manufacturing location decisions.
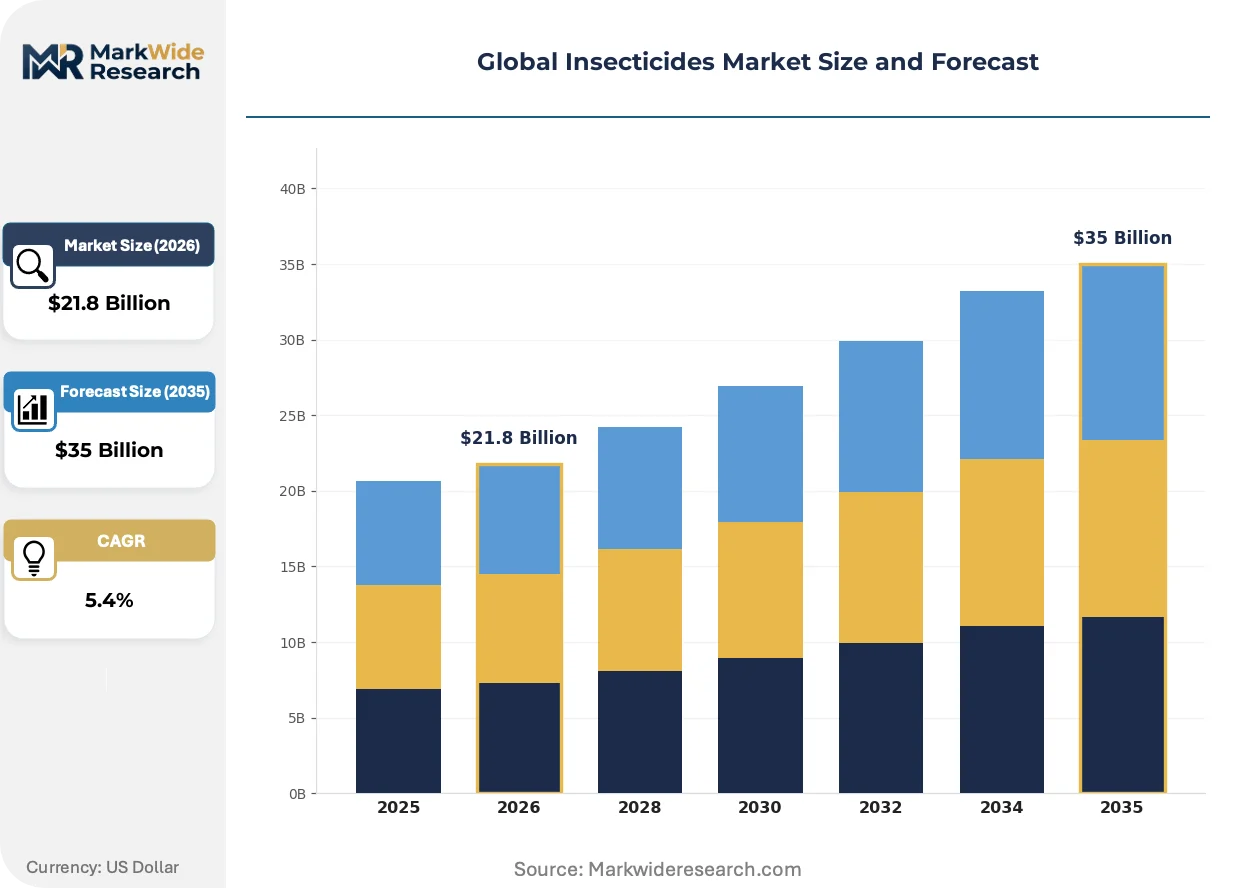
Market Dynamics
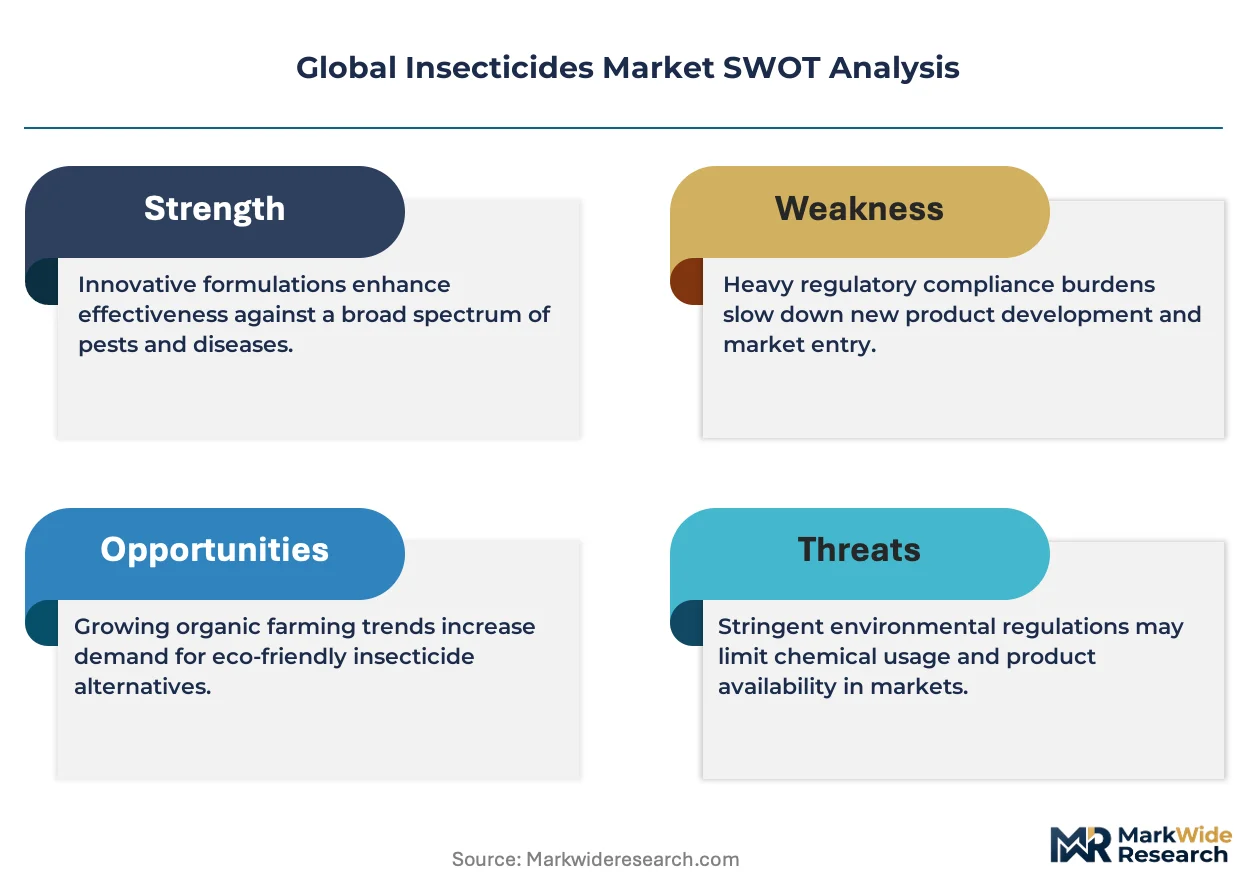
Biological insecticide registration acceleration under the EU Green Deal's Farm to Fork strategy is compressing approval timelines and forcing synthetic chemistry portfolios into accelerated obsolescence planning across multinational registrants.
Growth Catalysts
- EU Green Deal acceleration:The Farm to Fork strategy compresses biological insecticide registration timelines from 36 months to under 18 months in European jurisdictions, redirecting R&D budgets toward microbial and botanical platforms.
- Brazil's Cerrado expansion:Soybean hectarage growth in Mato Grosso and Goiás states sustains demand for lepidopteran-specific chemistries as second-crop cultivation intensifies.
- Integrated pest management adoption:Greenhouse operators in the Netherlands and Israel deploy pheromone disruption systems alongside reduced-risk chemistry, creating bundled service demand for input suppliers.
Market Restraints
- Neonicotinoid phase-out friction:REACH and EFSA ecological risk assessments force withdrawal of clothianidin and thiamethoxam formulations from 18 EU member states, eliminating cornerstone chemistry for seed treatment providers.
- Active ingredient concentration:Four Chinese manufacturers control over 70% of technical-grade pyrethroid and organophosphate production in Jiangsu and Shandong provinces, creating supply vulnerability during environmental compliance crackdowns.
- Resistance management complexity:Fall armyworm populations across sub-Saharan Africa exhibit metabolic resistance to Cry1F Bt proteins, degrading the efficacy of trait-stack seed investments.
Strategic Opportunities
- Maharashtra cotton corridor:India's Central Insecticides Board fast-tracks diamide registrations for pink bollworm management, opening formulation partnerships for registrants with existing China technical supply agreements.
- RNA interference convergence:dsRNA sprayable formulations combined with precision application drones enable species-specific suppression without non-target toxicity, attracting specialty vegetable operators in California's Salinas Valley.
- Public health vector programs:WHO prequalification pathways for malaria control insecticides create dual-use manufacturing scale for agricultural pyrethroid producers serving sub-Saharan procurement agencies.
Industry Challenges
- Ecotoxicology talent scarcity:GLP-compliant study directors with pollinator risk assessment experience command 40% salary premiums, constraining registration timeline execution for mid-tier consultancies.
- Manufacturing reconfiguration capex:China's MEE effluent standard tightening in Jiangsu Province requires wastewater treatment investments exceeding $15 million per technical-grade facility, forcing portfolio rationalization decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Insecticides Market |
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $35 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organophosphates, Pyrethroids, Carbamates, Neonicotinoids, Botanical Extracts Application: Cereal Crops, Fruits & Vegetables, Plantation Crops, Public Health, Non-Crop Land End User: Farmers, Pest Control Services, Government Agencies, Greenhouse Operators Formulation Type: Emulsifiable Concentrate, Wettable Powder, Granules, Aerosols, Microencapsulated |
| Companies Covered | Syngenta Group, Bayer AG, BASF SE, Corteva Agriscience, FMC Corporation, ADAMA Agricultural Solutions Ltd., UPL Limited, Sumitomo Chemical Co., Ltd., Nufarm Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Insecticides Market Shifts & Advancements
Precision delivery systems and residue-free cultivation protocols are compressing application rates while elevating biological formulation complexity. These shifts favor registrants with integrated hardware-chemistry service models over standalone active ingredient suppliers.
RNA interference sprayable technology targets specific lepidopteran mRNA sequences, disrupting protein synthesis without broad-spectrum toxicity. Large-scale greenhouse operators in Almeria and California are piloting dsRNA-chitosan complexes at 500-hectare vegetable facilities. This precision mechanism is electrifying the competitive boundary between biological and synthetic chemistry portfolios, forcing incumbents to acquire or partner with nucleic acid formulation specialists.
REACH authorization requirements now mandate substitution plans for all candidate list substances with endocrine-disrupting potential, affecting pyrethroid metabolite classifications. Formulators must submit socio-economic analyses demonstrating lack of alternatives to maintain Annex XIV authorization. Seed treatment applications face the steepest compliance burden, driving Bayer and Syngenta biologicals pipeline prioritization toward European field trial networks.
Buyer consolidation among Brazilian grain trading houses has compressed procurement decision cycles from annual to semi-annual tendering. Input distributors now bundle application services with credit facilities to maintain supplier relationships. This purchasing compression is most visible in Mato Grosso's Sorriso municipality, where three cooperatives control 60% of soybean hectarage and demand real-time pest monitoring data as a contract condition.
Global Insecticides Market Segmentation
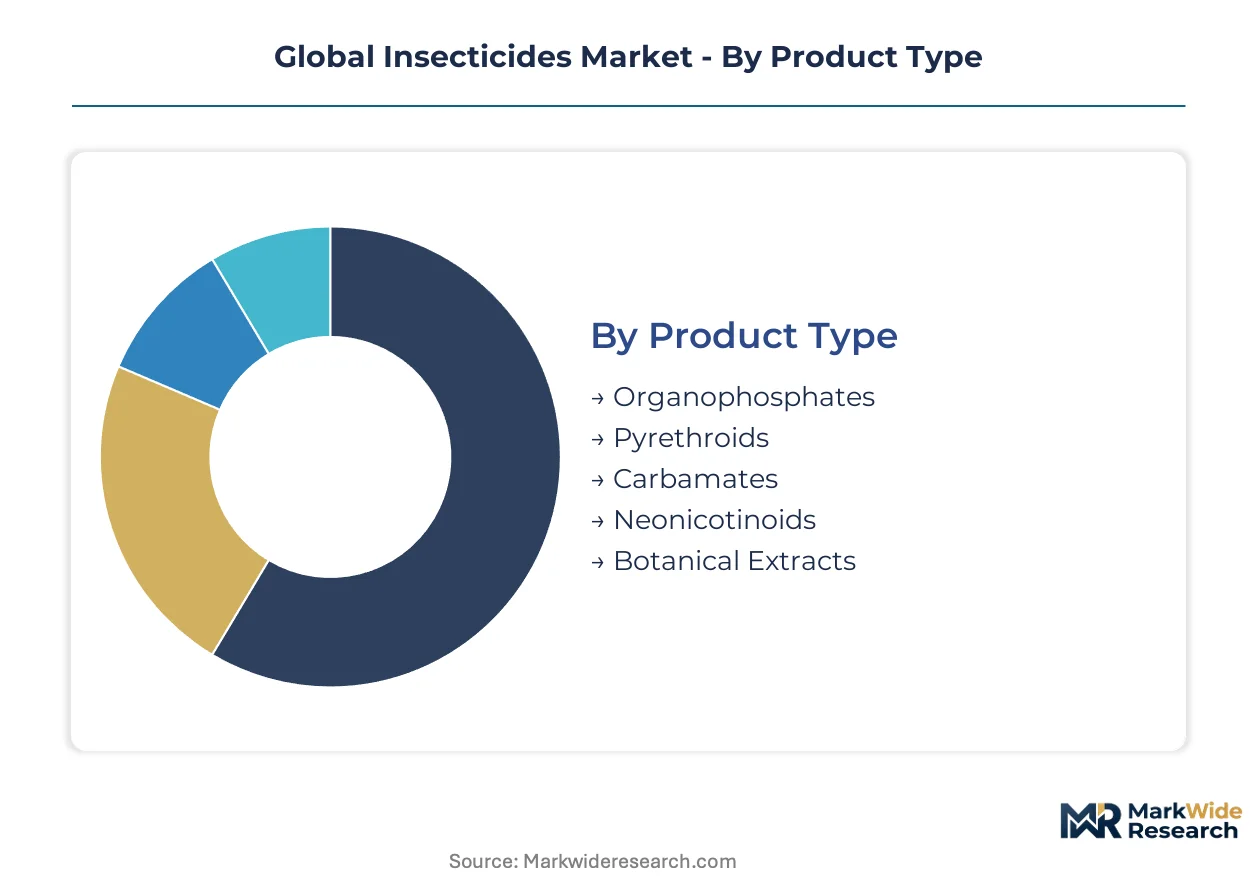
Insecticide segmentation reveals divergent regulatory pathways across chemistries and end-uses, with biological formulations accelerating through compressed approval timelines while synthetic categories face extended ecological risk reviews. Understanding these certification burdens enables registrants to prioritize portfolio investments and anticipate formulation obsolescence.
Product Type:
REACH authorization and EPA FIFRA registration timelines vary dramatically across chemical classes, with hazard-based cutoffs in European jurisdictions forcing substitution planning for legacy molecules.
- Organophosphates:These cholinesterase inhibitors require extensive mammalian toxicity dossiers under EPA ecological risk assessments. Demand persists in Indian cotton corridors and sub-Saharan malaria vector programs where cost constraints override substitution pressure.
- Pyrethroids:Synthetic esters derived from chrysanthemum acid structures dominate residual spraying for Anopheles control. WHO prequalification pathways sustain manufacturing scale for agricultural producers serving dual-use public health procurement in Kenya and Nigeria.
- Carbamates:Reversible acetylcholinesterase inhibitors face EFSA groundwater metabolite scrutiny in vulnerable aquifer regions.
- Neonicotinoids:Systemic nicotinic agonists confront pollinator risk assessment expansions across 18 EU member states, eliminating seed treatment cornerstone applications.
- Botanical Extracts:Azadirachtin and pyrethrin formulations navigate accelerated EU Green Deal biological registration tracks, with greenhouse operators in the Netherlands adopting residue-free protocols for export tomato production.
Pyrethroids sit at the top of the volume ranking, with botanical extracts climbing the fastest.
Application:
Application segmentation tracks cost tier stratification, with high-value horticulture commanding premium formulation pricing and broad-acre cereals operating on thin margin structures.
- Cereal Crops:Wheat and maize applications emphasize seed treatment and foliar spray economies of scale. Brazilian Cerrado soybean belt procurement concentrates through grain trading cooperatives demanding bundled application services.
- Fruits & Vegetables:Specialty cultivation in California's Salinas Valley and Spain's Almeria greenhouse complexes drives precision application technology adoption. Residue tolerance thresholds below 0.01 ppm for export markets favor microencapsulated and biological formulations.
- Plantation Crops:Oil palm and rubber estates in Southeast Asia deploy aerial spraying for defoliator control across contiguous hectarage.
- Public Health:Malaria and dengue vector programs operate through WHO and national ministry procurement channels with specification-driven tendering.
- Non-Crop Land:Industrial vegetation management and turf applications face municipal runoff restrictions in watershed protection zones.
Cereal crops anchor procurement volume, while fruits and vegetables deliver the steepest margin expansion.
End User:
Customer type segmentation maps to application sophistication tiers, with greenhouse operators deploying integrated hardware-chemistry bundles and government agencies enforcing specification compliance.
- Farmers:Individual growers and cooperative members in India's Maharashtra cotton corridor purchase through distributor credit facilities with technical advisory attachments.
- Pest Control Services:Commercial applicators in urban markets carry liability coverage for structural and residential treatments, favoring reduced-risk chemistry for re-entry interval compliance.
- Government Agencies:Vector control divisions in Brazil and Nigeria operate through centralized procurement with WHO prequalification requirements.
- Greenhouse Operators:Dutch and Israeli controlled-environment agriculture facilities deploy pheromone disruption alongside biological insecticides for residue-free export certification.
Farmers represent the largest addressable base, with greenhouse operators gaining share fastest through biological adoption.
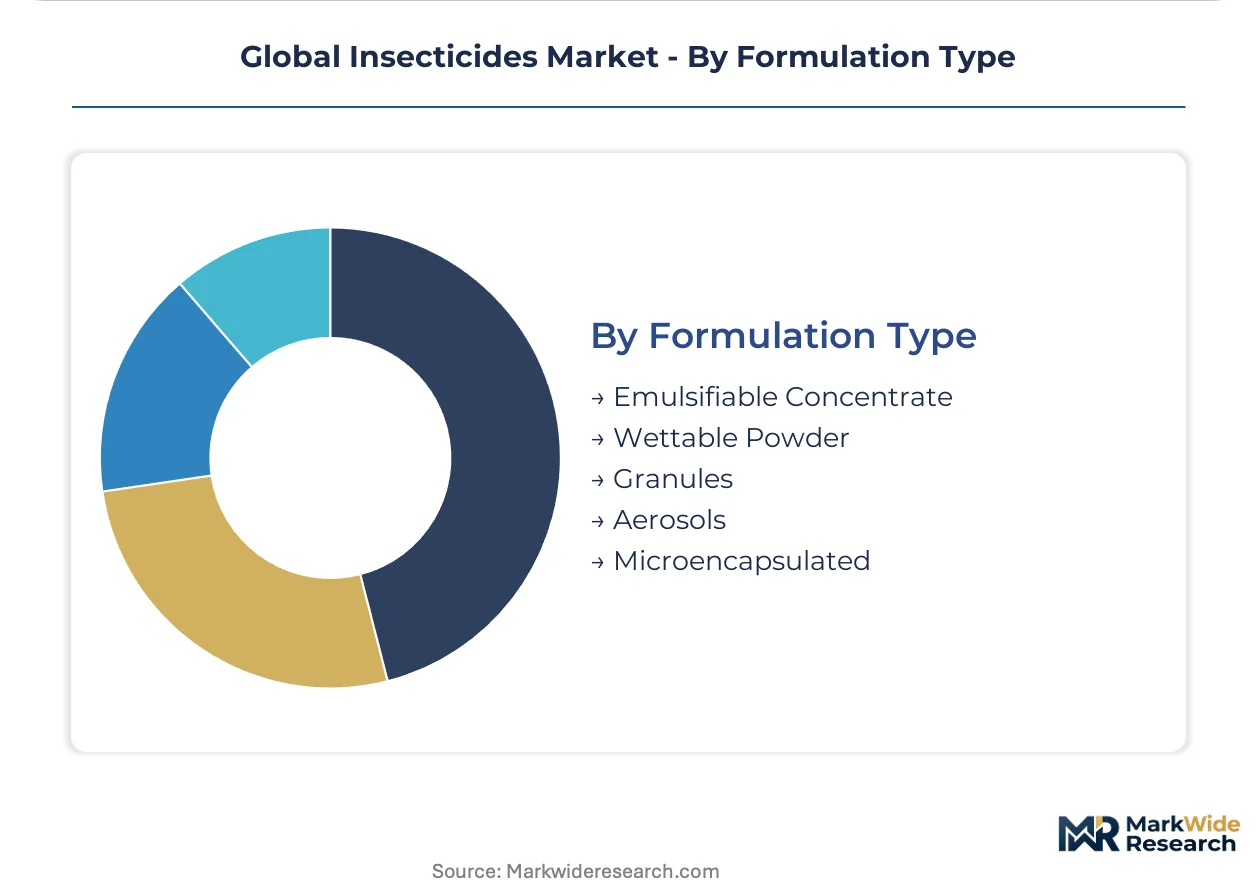
Formulation Type:
Formulation selection reflects supply concentration in Chinese technical manufacturing clusters and downstream packaging flexibility for regional label requirements.
- Emulsifiable Concentrate:Oil-based solutions containing surfactant systems dominate broad-acre spraying in Brazilian soybean operations. Solvent volatility regulations in California air districts constrain formulation flexibility.
- Wettable Powder:Dry flowable granules with dispersing agents suit smallholder backpack sprayer applications across Indian cotton belts. Dust exposure concerns during mixing drive gradual displacement by suspension concentrates.
- Granules:Clay-based carriers for soil incorporation target root-feeding pests in plantation crop systems.
- Aerosols:Pressurized formulations serve consumer and professional pest control markets with immediate knockdown requirements.
- Microencapsulated:Polymer-shell delivery systems extend residual activity while reducing non-target exposure, penetrating high-value vegetable seed treatment and greenhouse markets.
Emulsifiable concentrate formulations retain volume leadership, with microencapsulated systems expanding most quickly through specialty crop penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting technical-grade manufacturing toward jurisdictions with risk-assessment frameworks rather than hazard-based cutoffs, compressing formulation margins in European markets while expanding capacity in Asia-Pacific and Latin American production clusters.
Brazil
Second-crop soybean intensification in Mato Grosso and Goiás sustains demand for lepidopteran-specific chemistries. ANVISA and IBAMA enforce dual-track approval requirements that extend registration timelines for multinational entrants. The Sorriso municipality anchors procurement consolidation, where three cooperatives control 60% of hectarage and mandate real-time pest monitoring data.
United States
California's Salinas Valley vegetable operators drive precision application adoption for residue thresholds below 0.01 ppm. EPA FIFRA mandates ecological toxicity reviews that compress approval windows for biological formulations relative to synthetic chemistry. The Midwest corn-soy belt concentrates seed treatment demand through distributor credit facilities with bundled advisory services.
India
Maharashtra's cotton corridor generates fast-track diamide registrations for pink bollworm management. The Central Insecticides Board enforces label compliance under the 1968 Insecticides Act, creating formulation partnership openings for registrants with China technical supply agreements. Gujarat and Telangana extend demand for smallholder backpack sprayer applications.
China
Jiangsu Province organophosphate manufacturing clusters face MEE effluent standard tightening that forces $15 million wastewater treatment investments per facility. Technical-grade pyrethroid and organophosphate production concentrates in Jiangsu and Shandong, where four manufacturers control over 70% of output. Shandong facilities supply downstream formulators across Southeast Asian plantation crop markets.
Netherlands
Greenhouse operators in Westland and North Brabant deploy pheromone disruption systems alongside biological insecticides for residue-free tomato and pepper export certification. The EU Green Deal's Farm to Fork strategy compresses biological registration timelines from 36 months to under 18 months. Dutch facilities pilot RNA interference sprayable formulations at 500-hectare vegetable operations.
Global Insecticides Market Competitive Landscape
Portfolio diversification dominates the current landscape as registrants accelerate biologicals pipelines to offset synthetic chemistry obsolescence. The vendor base stratifies across three tiers: integrated agrochemical conglomerates with seed-trait synergies, mid-scale specialists in narrow chemistries, and regional formulators with technical supply advantages. Strategic archetypes include R&D-intensive innovators pursuing RNA interference platforms, manufacturing-lean asset-light formulators, and integrated service providers bundling hardware-chemistry offerings. M&A activity and capacity reconfiguration represent the dominant competitive moves, with acquisition targets clustering in microbial formulation capabilities and precision application hardware.
Within the integrated conglomerate tier, Bayer AG and Syngenta Group exemplify R&D-intensive positioning through biologicals pipeline prioritization and neonicotinoid alternative development. FMC Corporation occupies a defensible niche as a chemistry specialist. Among Asia-Pacific-based manufacturers, Sumitomo Chemical Co., Ltd. and ADAMA Agricultural Solutions Ltd. represent regional formulators with technical supply integration. UPL Limited anchors Indian market access through distributor network density. These five entities collectively illustrate the competitive spectrum from global R&D leadership to regional manufacturing scale.
| Leading Market Players |
|---|
| Syngenta Group |
| Bayer AG |
| BASF SE |
| Corteva Agriscience |
| FMC Corporation |
| ADAMA Agricultural Solutions Ltd. |
| UPL Limited |
| Sumitomo Chemical Co., Ltd. |
| Nufarm Limited |
| Others |
Supply & Pricing Matrix
Technical-grade pyrethroid feedstock indices in Jiangsu Province cascade through formulation tiers, compressing margins for emulsifiable concentrate suppliers while elevating microencapsulated premium positioning in Dutch greenhouse markets.
Pricing Analysis
Distributor margins in Brazilian soybean procurement absorb credit facility costs and bundled application advisory services. Three-tier pricing structure across premium, standard, and economy levels separates residue-free biological formulations from commodity pyrethroid generics. Cost compression in standard-tier seed treatments is intensifying because ANVISA dual-track approval timelines extend working capital cycles. Smallholder cotton farmers in Maharashtra exhibit highest price sensitivity; California Salinas Valley greenhouse operators show least.
Supply Chain Analysis
Technical-grade organophosphate production rests on Jiangsu and Shandong manufacturing clusters, where four producers anchor over seventy percent of global pyrethroid and organophosphate output. Key inputs include chlorinated intermediates, phosphorus pentasulfide, and chrysanthemum acid derivatives. Single-source vulnerability concentrates in Chinese environmental compliance crackdowns under MEE effluent standards. Distribution runs through regional formulators with China technical supply agreements and downstream packaging for local label requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Insecticides Market reads as a late-cycle quality story. Residue-free cultivation protocols in Netherlands and Israel greenhouse operations are elevating biological formulation premiums over synthetic commodity tiers.
For Market Incumbents: Anticipate neonicotinoid substitution mandates across EU member states by accelerating microbial formulation partnerships and RNA interference platform investments. Prioritize backward integration into Chinese technical supply agreements to secure diamide chemistry access for Maharashtra cotton corridor registrations. Channel control through bundled hardware-chemistry service models defends margin position against generic pressure. For New Entrants and Emerging Players: Sprayable dsRNA-chitosan complexes offer technology-first wedge into California Salinas Valley precision vegetable operations with species-specific lepidopteran suppression. Target underpenetrated RNA interference formulation partnerships with Dutch greenhouse cooperatives seeking EU Green Deal compliance. Go-to-market through precision drone application service bundling bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with microbial formulation specialists possessing GLP-compliant ecotoxicology study director networks and EU biological registration track records. Five-to-ten year viability favors nucleic acid delivery platform acquisitions over commodity pyrethroid manufacturing. Watch EPA FIFRA biological approval timeline compression as inflection signal for synthetic portfolio obsolescence acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Registration Acceleration | EU Green Deal Farm to Fork timelines compress from thirty-six to eighteen months, redirecting R&D budgets toward microbial platforms. |
| RNA Interference Platform Development | dsRNA sprayable formulations enable species-specific suppression without non-target toxicity, attracting California specialty vegetable operators. |
| Technical Supply Integration | Backward integration into Jiangsu Province organophosphate manufacturing secures diamide chemistry access for Indian cotton corridor partnerships. |
| Precision Application Hardware Bundling | Drone-mounted delivery systems bundled with biological formulations create service-based revenue streams in Brazilian cooperative procurement. |
| Ecotoxicology Talent Acquisition | GLP-compliant study directors with pollinator risk assessment expertise command salary premiums, constraining mid-tier consultancy execution timelines. |
Research Methodology
Bottom-up crop-specific demand modeling reconciled against top-down technical-grade manufacturing capacity tracking forms the analytical core of this study. Primary interviews with agrochemical R&D directors, Brazilian grain cooperative procurement managers, Indian distributor network heads, and EPA registration consultants combined with secondary validation from customs trade data, SEC 10-K filings, and ANVISA registration databases. Triangulation across supply-side production surveys and demand-side acreage projections ensures cross-verification.
Historical trendline analysis of active ingredient pricing and registration timeline patterns established baseline trajectory assumptions across the analysis window. Segmentation modeling incorporated product type, application crop, formulation technology, and regional regulatory cluster dimensions. CAGRs derived from acreage expansion rates in Brazil's Cerrado and India's Maharashtra corridor, weighted against EU synthetic chemistry phase-out schedules. Forecast inputs included pollinator risk assessment expansion timelines and Chinese environmental compliance enforcement intensity.
The model holds under stable regulatory enforcement intensity and continued biological registration timeline compression; deviation in EU hazard-based cutoff expansion or Chinese manufacturing cluster shutdowns would shift trajectory assumptions. Forecasts reflect documented assumptions about resistance management complexity and supply concentration stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Dicamba Market
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
Fosthiazate Market
Crop Protection
Brazil Crop Protection Chemical Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Africa Crop Protection Chemicals Market
Crop Protection
Europe Nematicide Market
Crop Protection
Global Aquatic Herbicides Market
Crop Protection
Organic Pesticides Market
Crop Protection
Crop Protection Chemicals Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
Microbial Pesticides Market
Crop Protection
Poland Crop Protection Chemicals Market
Crop Protection
Generic Crop Protection Chemicals Market