
 Grain Protectant Market | 2026-2036
Grain Protectant Market Size, Share, and Industry Trends Forecast 2026-2036
Grain Protectant Market Foresight
Direct-to-elevator supply contracts is reshaping how protectant manufacturers reach end users in North American grain corridors. BASF SE leverages its formulation science leadership to sustain premium positioning in liquid protectant categories. Syngenta AG competes through integrated seed-to-storage advisory services that anchor long-term elevator relationships. Bayer AG differentiates via biological protectant pipelines targeting phosphine-resistant insect populations.
Grain protectants are chemical or biological formulations applied to harvested cereals, oilseeds, and pulses to prevent insect infestation, fungal colonization, and moisture-driven spoilage during storage and transit; active ingredients range from pyrethroid and organophosphate insecticides to microbial antagonists and diatomaceous earth, with application rates typically calibrated to grain moisture content and ambient temperature thresholds. Organic protectants represent the fastest-expanding product category as food processors and export houses respond to EU Green Deal residue restrictions and buyer sustainability audits. Stored grain applications command the deepest margin pools due to extended holding periods and regulatory mandates for export certification, while transportation segments remain fragmented across regional logistics providers with limited standardization.
The EPA governs active ingredient re-registration and tolerance limits under FIFRA, while the EU REACH framework and MRL harmonization through EFSA constrain conventional pesticide access to European export markets. India's CEA and FSSAI jointly enforce fumigation standards at major port facilities, creating compliance complexity for multinational suppliers. Stakeholders must monitor evolving biological registration pathways and residue testing protocols to preserve market access across divergent national regimes.
Market Dynamics
Phosphine resistance in stored-product insects is forcing grain handlers to abandon fumigation-first protocols and adopt residual protectant layering strategies. This biological pressure is restructuring procurement priorities across commercial elevators and export houses.
Growth Catalysts
- EPA FIFRA re-registration deadlines:The 2026-2028 review cycle for organophosphates is accelerating biological protectant R&D pipelines and opening shelf space for microbial antagonists at major US grain cooperatives.
- EU Green Deal residue restrictions:MRL harmonization through EFSA is compelling export-oriented elevators in France and Germany to certify organic protectant use for premium wheat shipments.
- India's port infrastructure expansion:CEA-mandated fumigation standards at Visakhapatnam and Mundra are creating dedicated protectant application facilities with captive chemical handling capabilities.
Market Restraints
- Pyrethroid active ingredient concentration:Three suppliers control over 70% of technical-grade deltamethrin and permethrin supply, exposing formulators to input cost volatility and allocation risk.
- Biological protectant stability limitations:Microbial formulations require cold-chain distribution and 4-8°C storage, constraining deployment in subtropical grain belts with inadequate logistics infrastructure.
- REACH registration cost burden:The €200,000-400,000 per-substance dossier requirement is blocking small-scale botanical extract suppliers from EU market entry.
Strategic Opportunities
- Brazil's corn export corridor:ANVISA's accelerated biological pesticide registration pathway offers first-mover positioning for microbial protectant suppliers targeting Santos and Paranaguá grain terminals.
- Blockchain-enabled residue certification:Integration of IoT sensors with distributed ledger verification is creating premium pricing tiers for traceable protectant application records in specialty grain contracts.
- Japan's METI carbon-neutral agriculture roadmap:Subsidies for reduced-chemical storage protocols are opening demand for diatomaceous earth and heat-treatment hybrid systems in Hokkaido rice elevators.
Industry Challenges
- Entomological expertise scarcity:Grain handlers lack trained personnel to diagnose resistance allele frequencies and calibrate protectant rotation schedules, creating dependency on third-party advisory services.
- Legacy phosphine infrastructure lock-in:Existing fumigation chambers and recapture systems represent sunk capital that slows protectant diversification decisions at family-owned elevators.
- Biological registration data requirements:EFSA's 2023 guidance on microbial metabolite characterization demands multi-year field efficacy studies that extend time-to-market for novel antagonist strains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grain Protectant Market |
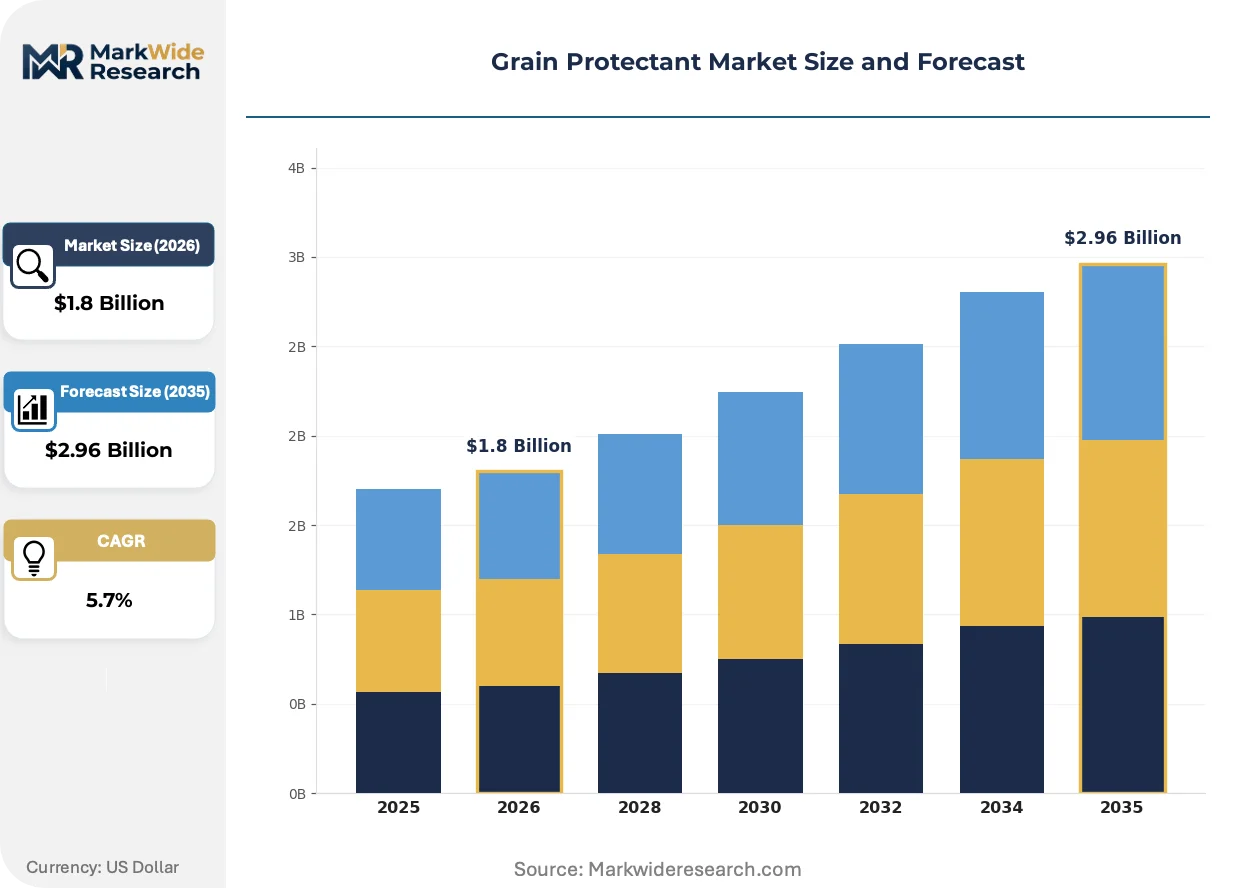
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pesticides, Insecticides, Fungicides, Organic Protectants Application: Stored Grain, Field Grain, Processing Facilities, Transportation End User: Agriculture Producers, Grain Elevators, Food Processors, Wholesale Distributors Formulation: Liquid, Granular, Powder, Emulsifiable Concentrate |
| Companies Covered | BASF SE, Syngenta AG, Bayer AG, FMC Corporation, Corteva Agriscience, UPL Limited, Nufarm Limited, Sumitomo Chemical, ADAMA Agricultural Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grain Protectant Market Shifts & Advancements
Biological formulation science and digital application monitoring are converging to displace calendar-based spraying with precision-driven protectant deployment. This shift is compressing the value capture window for commodity chemical suppliers.
RNA interference protectants targeting species-specific gene expression in Sitophilus and Tribolium genera are entering pilot trials at Australian bulk handlers. GrainCorp and CBH Group are evaluating spray-on dsRNA formulations for 2025 commercial deployment. This technology is rendering obsolete broad-spectrum neurotoxic insecticides that disrupt beneficial predator populations in stored grain ecosystems.
REACH Annex XVII restrictions on persistent organic pollutants are tightening maximum residue thresholds for legacy organochlorine contaminants in EU-bound shipments. German and Dutch grain traders now require pre-loading third-party residue certification from Black Sea and Argentine suppliers. Organic protectant documentation is becoming a mandatory tender requirement for EU feed compounders sourcing maize and soybeans.
Elevator procurement teams are consolidating supplier relationships around full-season storage management contracts rather than transactional chemical purchases. Major US grain cooperatives in Iowa and Illinois are bundling protectant supply with moisture monitoring and aeration control services. This service integration is most advanced in the Corn Belt, where thin operating margins incentivize outsourced post-harvest risk management.
Grain Protectant Market Segmentation
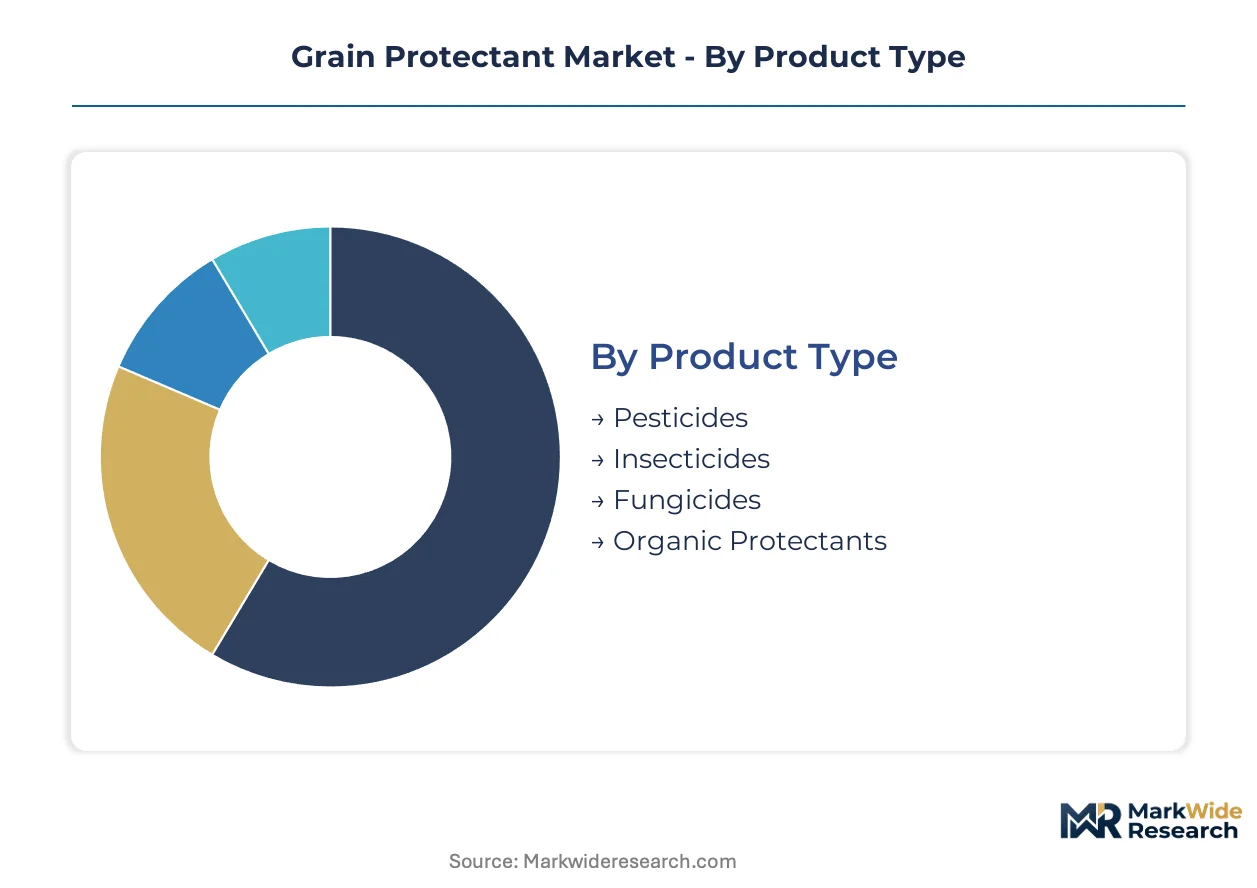
Grain protectant procurement patterns diverge sharply across storage duration, regulatory exposure, and handling infrastructure. Segment boundaries are blurring as elevator operators bundle chemical supply with integrated pest management services.
Product Type:
Cost tier stratification separates commodity chemical inputs from premium biological formulations with certification premiums.
- Pesticides:Broad-spectrum synthetic formulations combining insecticidal and fungicidal actives. Demand concentrates in US Corn Belt export elevators where phosphine resistance management protocols mandate residual chemical layering.
- Insecticides:Pyrethroid and organophosphate-based products targeting Sitophilus and Tribolium genera. Brazilian grain terminals at Santos and Paranaguá are expanding procurement as ANVISA accelerates biological registration pathways.
- Fungicides:Triazole and strobilurin formulations preventing aflatoxin and vomitoxin accumulation in high-moisture storage. Elevators in India's Visakhapatnam port cluster deploy these under CEA-mandated handling standards.
- Organic Protectants:Microbial antagonists, diatomaceous earth, and botanical extracts. EU Green Deal MRL harmonization through EFSA is compelling German and French export houses to certify organic protectant use for premium wheat shipments.
Pesticides hold installed capacity. Organic Protectants is rotating up the share rankings.
Application:
Volume throughput and holding duration determine protectant selection intensity across the post-harvest chain.
- Stored Grain:Extended-holding applications in commercial elevators with aeration and moisture monitoring systems. Iowa and Illinois grain cooperatives are bundling protectant supply with full-season storage management contracts.
- Field Grain:Pre-storage treatment at harvest points with limited infrastructure. Australian bulk handlers GrainCorp and CBH Group are piloting RNA interference formulations for field-edge application.
- Processing Facilities:Milling and feed compounder inbound grain treatment with strict residue thresholds. Dutch and German traders now require pre-loading third-party residue certification for EU-bound shipments.
- Transportation:Railcar, barge, and container protectant application with fragmented logistics provider coverage. Regional providers in subtropical grain belts face cold-chain constraints for microbial formulations.
Stored Grain holds installed capacity. Processing Facilities is rotating up the share rankings.
End User:
Customer type determines contract structure, from transactional chemical purchases to multi-year advisory relationships.
- Agriculture Producers:On-farm storage operators with limited technical expertise. Japan's METI carbon-neutral agriculture roadmap is subsidizing reduced-chemical storage protocols in Hokkaido rice elevators.
- Grain Elevators:Commercial storage facilities with fumigation chambers and recirculation systems. Family-owned elevators face sunk capital lock-in that slows protectant diversification decisions.
- Food Processors:Milling and baking operations with zero-tolerance residue specifications. Blockchain-enabled residue certification with IoT sensor integration is creating premium pricing tiers for traceable application records.
- Wholesale Distributors:Regional chemical suppliers serving fragmented farm and elevator bases. REACH Annex XVII persistent organic pollutant restrictions are tightening maximum residue thresholds for legacy organochlorine contaminants.
Grain Elevators hold installed capacity. Food Processors is rotating up the share rankings.
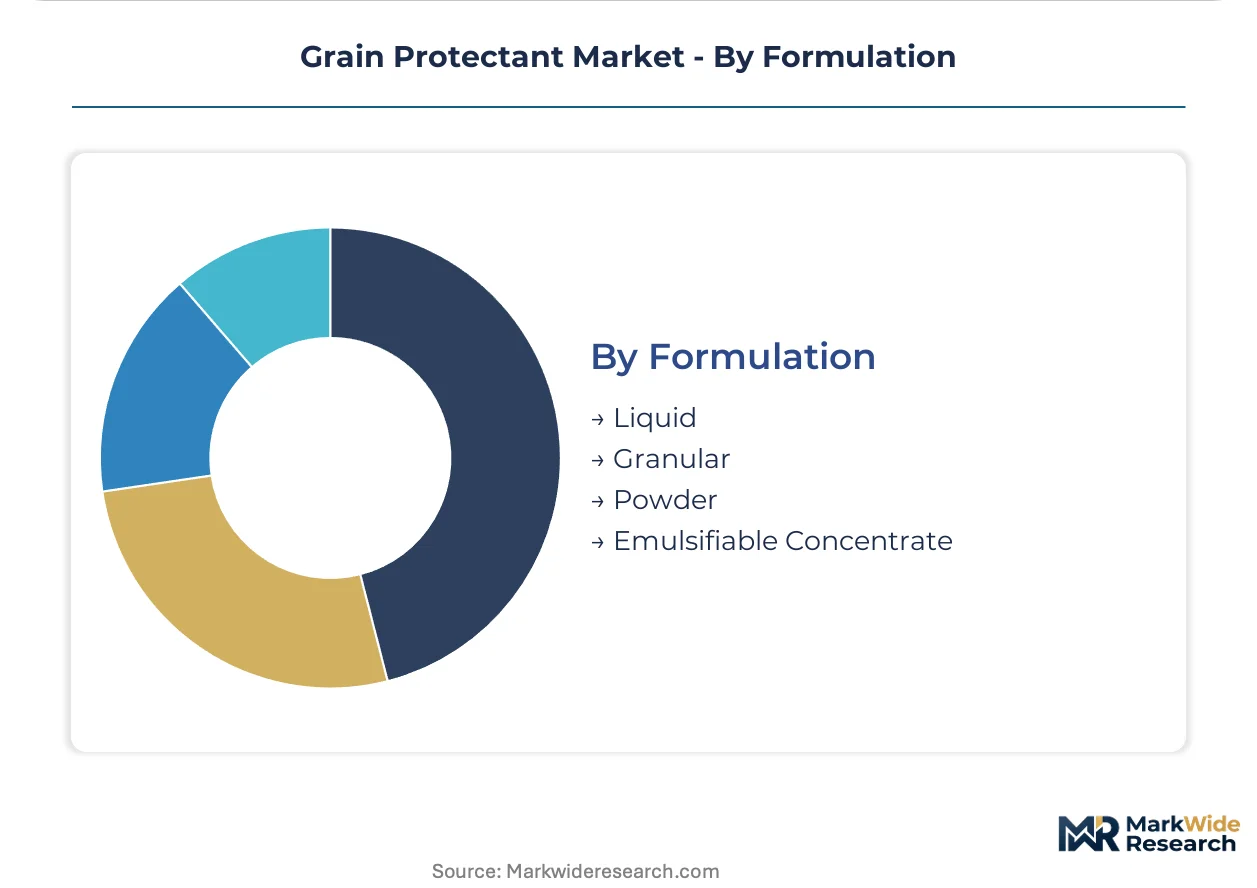
Formulation:
Supply concentration in technical-grade active ingredients shapes formulator margin structure and allocation risk.
- Liquid:Emulsifiable and suspension concentrates with uniform coverage characteristics. BASF SE leverages formulation science leadership to sustain premium positioning in this category.
- Granular:Slow-release matrix formulations for extended protection windows. Syngenta AG competes through integrated seed-to-storage advisory services anchoring long-term elevator relationships.
- Powder:Dust formulations including diatomaceous earth for desiccant action. Subtropical grain belts with inadequate logistics infrastructure face deployment constraints for moisture-sensitive products.
- Emulsifiable Concentrate:High-loading solvent-based formulations requiring specialized handling equipment. Three suppliers control over 70% of technical-grade pyrethroid supply, exposing formulators to input cost volatility.
Liquid holds installed capacity. Granular is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where export certification mandates sustain premium protectant procurement, while Indian port handlers absorb cost pressures from CEA-mandated fumigation infrastructure requirements.
United States
Commercial grain elevators in Iowa and Illinois are bundling protectant supply with full-season storage management contracts. The EPA's FIFRA re-registration deadlines for organophosphates are accelerating biological protectant R&D pipelines. Corn Belt export handlers are deploying residual protectant layering strategies to manage phosphine-resistant insect populations.
Brazil
ANVISA's accelerated biological pesticide registration pathway is attracting microbial protectant suppliers targeting Santos and Paranaguá grain terminals. Corn export corridor expansion is creating dedicated protectant application facilities with captive chemical handling capabilities. São Paulo-based grain traders are certifying organic protectant use for premium soybean shipments.
Germany
EU Green Deal MRL harmonization through EFSA is compelling Hamburg and Bremen export houses to mandate organic protectant documentation for EU-bound grain. REACH Annex XVII restrictions on persistent organic pollutants are tightening residue thresholds for legacy contaminants. Rhine-Ruhr logistics clusters are integrating blockchain-enabled residue certification with IoT sensor verification.
India
CEA and FSSAI joint enforcement of fumigation standards at Visakhapatnam and Mundra is creating compliance complexity for multinational suppliers. Port infrastructure expansion is driving dedicated protectant application facilities with captive handling systems. Maharashtra and Gujarat grain terminals are adopting triazole fungicides under mandated handling protocols.
Australia
GrainCorp and CBH Group are piloting RNA interference protectants targeting Sitophilus and Tribolium genera for field-edge application. The country's national agricultural regulator is evaluating spray-on dsRNA formulations for commercial deployment. Western Australia bulk handlers are displacing broad-spectrum neurotoxic insecticides that disrupt beneficial predator populations.
Grain Protectant Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in active ingredient supply. The market structure consolidates around diversified agrochemical conglomerates with formulation science capabilities, while regional distributors fragment across logistics-constrained subtropical belts. Three archetypes dominate: multinational platform providers with seed-to-storage advisory integration, mid-scale formulators with regional elevator relationships, and biological R&D specialists with microbial pipeline assets. Competitive moves concentrate on M&A for biological registration portfolios and backward integration into technical-grade pyrethroid supply.
Within the multinational platform tier, BASF SE, Syngenta AG, and Bayer AG exemplify divergent strategic positioning. BASF SE leverages its Ludwigshafen-based formulation science leadership to sustain premium positioning in liquid protectant categories. Syngenta AG competes through integrated seed-to-storage advisory services that anchor long-term elevator relationships across North American grain corridors. Bayer AG occupies a position within biological protectant pipelines targeting phosphine-resistant insect populations, representing the R&D-specialist archetype among the three.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta AG |
| Bayer AG |
| FMC Corporation |
| Corteva Agriscience |
| UPL Limited |
| Nufarm Limited |
| Sumitomo Chemical |
| ADAMA Agricultural Solutions |
| Others |
Supply & Pricing Matrix
Single-source dependency on Chinese technical-grade pyrethroid supply determines both the premium commanded by formulation-ready protectants and the geographic shape of active ingredient sourcing networks. Three suppliers control over seventy percent of deltamethrin and permethrin feedstock, compressing margins for downstream formulators while amplifying price volatility across liquid and emulsifiable concentrate tiers.
Pricing Analysis
The customization-premium spread separates standard liquid formulations from certified organic and biological alternatives with EU Green Deal documentation. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and cold-chain logistics requirements. Cost compression in the economy tier intensifies because pyrethroid feedstock allocation risk concentrates pricing power upstream. Small-scale agriculture producers exhibit highest price sensitivity, while export-oriented grain elevators absorb premiums for residue certification.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for pyrethroid-dependent formulators. Active ingredient production concentrates in China, India, and Germany, with microbial antagonist strain development anchored in the United States and Brazil. Technical-grade pyrethroid, diatomaceous earth, and microbial fermentation feedstock constitute critical input dependencies. Distribution runs through direct-to-elevator contracts in North American grain corridors and regional chemical distributors in subtropical belts with cold-chain constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Full-season storage management contracts represent a service-attach opportunity expanding faster than standalone chemical supply, as Iowa and Illinois grain cooperatives outsource post-harvest risk management to bundled advisory providers.
For Market Incumbents: Pre-empt biological protectant registration portfolio gaps by acquiring microbial R&D specialists with EFSA-compliant metabolite characterization data. Anchor long-term elevator relationships through integrated seed-to-storage advisory services that embed moisture monitoring and aeration control. Backward integration into technical-grade pyrethroid supply mitigates allocation risk from Chinese feedstock concentration. For New Entrants and Emerging Players: Establish a beachhead in Brazil's corn export corridor by exploiting ANVISA's accelerated biological pesticide registration pathway for microbial protectant deployment at Santos and Paranaguá terminals. Target organic protectant certification for premium wheat shipments to German and French export houses facing EU Green Deal MRL harmonization. Lead with blockchain-enabled residue verification as a differentiated service layer. For Investors and Strategic Acquirers: Biological R&D specialists with phosphine-resistant insect targeting pipelines offer the strongest acquisition target archetype for long-term viability within a five-to-ten year window. Monitor EFSA microbial metabolite guidance compliance timelines as the critical inflection signal for time-to-market competitiveness. Elevator procurement consolidation toward full-season contracts indicates service-attach revenue durability.| Strategic Initiative | Industry Significance |
|---|---|
| Biological Registration Portfolio Acquisition | EFSA's metabolite characterization demands multi-year field studies that incumbents can shortcut through targeted M&A. |
| Direct-to-Elevator Contract Expansion | Corn Belt grain cooperatives in Iowa and Illinois are consolidating supplier relationships around bundled storage management services. |
| Cold-Chain Distribution Infrastructure | Microbial formulation stability requirements at four-to-eight degrees Celsius constrain deployment in subtropical grain belts with inadequate logistics. |
| Blockchain Residue Certification Integration | IoT sensor verification with distributed ledger documentation creates premium pricing tiers for specialty grain contracts in EU-bound shipments. |
| Backward Integration into Pyrethroid Supply | Three-supplier concentration in technical-grade deltamethrin and permethrin exposes formulators to input cost volatility and allocation risk. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with grain elevator procurement directors, biological R&D scientists at microbial formulation labs, regulatory affairs specialists navigating EPA FIFRA and EFSA registration pathways, and fumigation equipment operators at Indian port facilities. Secondary validation drew from EPA re-registration dockets, EFSA scientific opinions on maximum residue limits, ANVISA biological pesticide registration disclosures, and customs trade data on pyrethroid active ingredient flows. Bottom-up protectant volume estimates triangulated against top-down grain storage capacity assessments across major producing regions.
Calibration against historical price realization data and documented procurement contract structures anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, application stage, end-user archetype, and formulation chemistry class. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules. Phosphine resistance allele frequency trajectories and biological registration pathway timelines served as industry-specific forecast inputs.
Stress conditions across pyrethroid feedstock allocation disruption, EFSA microbial metabolite guidance stringency, and phosphine resistance spread rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on regulatory deadline adherence and cold-chain infrastructure deployment pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
China Fungicide Market
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Europe Soil Treatment Market
Crop Protection
Global Algaecides Market
Crop Protection
Europe Crop Protection Chemicals Market
Crop Protection
Phytogenic Poultry Feed Additives Market
Crop Protection
Acetochlor Herbicide Market
Crop Protection
Russia Crop Protection Chemicals Market
Crop Protection
Global Seed Treatment Chemicals Market
Crop Protection
Fumigation Service Market
Crop Protection
Global Dicamba Herbicide Market
Crop Protection
Latin America Crop Protection Chemicals Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
Africa Crop Protection Chemicals Market
Crop Protection
Asia-Pacific Acaricides Market
Crop Protection
Global Home and Garden Pesticides Market