
 Latin America Crop Protection Chemicals Market | 2026-2036
Latin America Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Crop Protection Chemicals Market Intelligence
ANVISA's updated pesticide residue thresholds is consolidating the cost-of-entry calculus for foreign manufacturers seeking Brazilian market access. Corteva Agriscience leverages its proprietary seed-trait pipeline to anchor herbicide demand across Brazil's soybean belt. Bayer AG sustains broad-spectrum fungicide development for countering Asian soybean rust pressure in Argentina. FMC Corporation specializes in novel insecticide modes of action targeting fall armyworm resistance management.
Crop protection chemicals encompass synthetic and biological formulations engineered to control weeds, insects, fungi, and plant diseases through precise active ingredient concentrations, typically applied via foliar spray or seed treatment at rates calibrated to crop growth stages. Their primary commercial purpose centers on yield preservation and quality maintenance across mechanized commodity agriculture. Herbicides command the largest value pool across Latin America, anchored by glyphosate-tolerant soybean systems, while fungicide demand accelerates fastest as climate volatility intensifies rust and blight cycles across the Pampas and Cerrado. Field crop applications dominate volume, though horticultural segments generate superior per-hectare spending through intensive spray programs.
Brazil's ANVISA, Argentina's SENASA, and Mexico's COFEPRIS collectively determine registration timelines, residue limits, and import authorization pathways that directly shape product availability and reformulation investment priorities across the region. REACH-aligned hazard classifications from Europe increasingly influence Latin American regulatory convergence, particularly on endocrine disruptor screening and aquatic toxicity thresholds. Stakeholders must monitor pending biocide reauthorization waves and emerging biologicals registration pathways to calibrate portfolio transitions between synthetic chemistry and microbial alternatives.
Market Dynamics
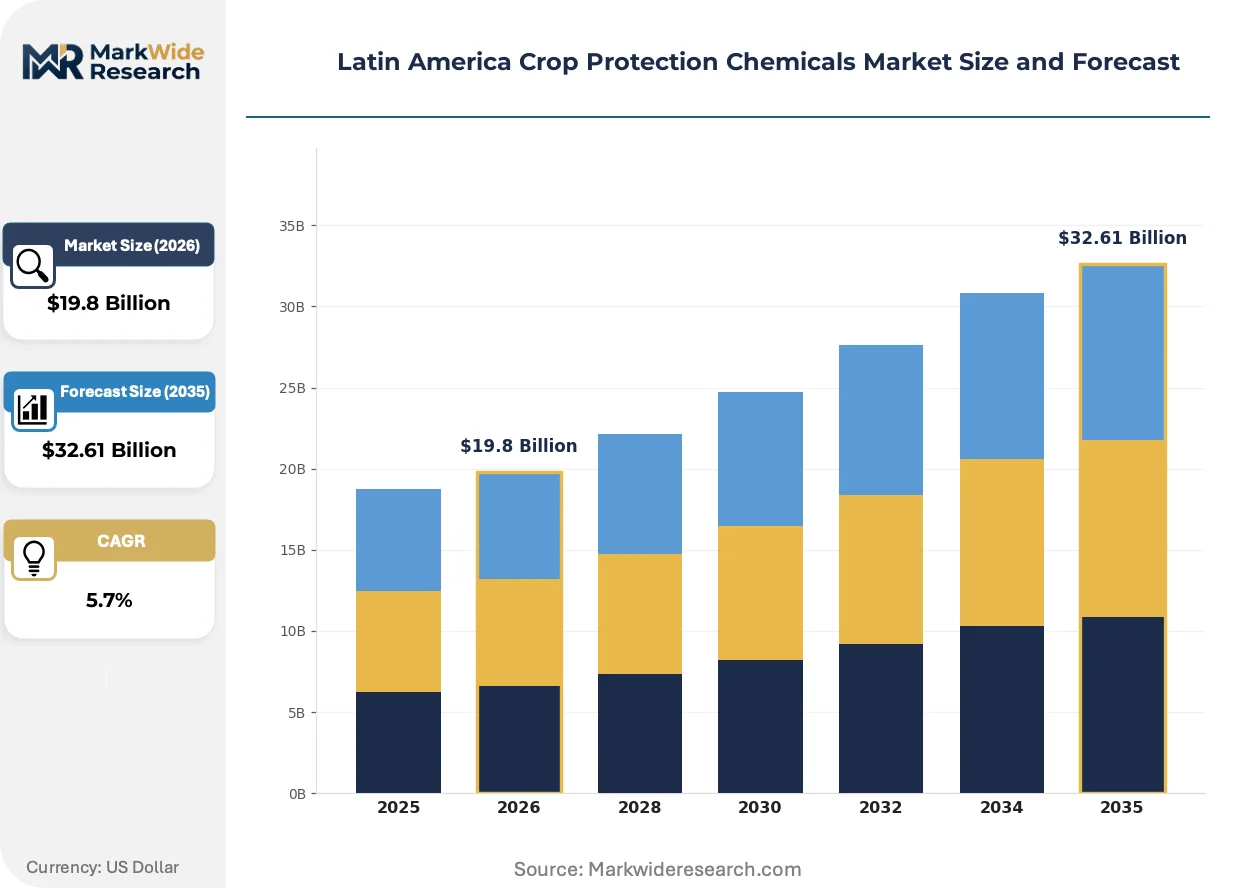
ANVISA's residue threshold recalibration is compressing formulation approval timelines and forcing active ingredient substitutions across Brazil's registration pipeline, fundamentally restructuring manufacturer cost structures for Brazilian market access.
Growth Catalysts
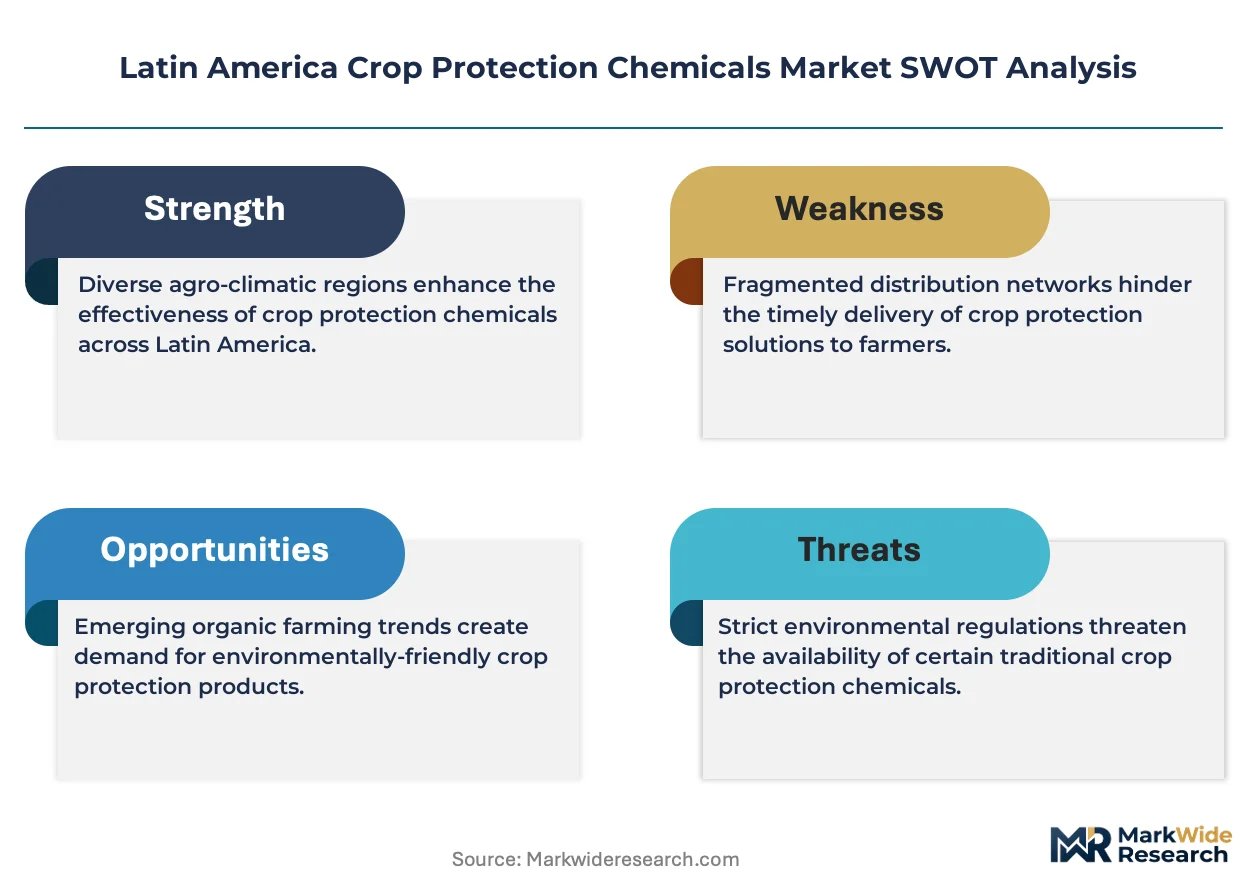
- Herbicide-tolerant seed systems:Brazil's Cerrado soybean expansion drives bundled chemical-seed demand, locking in recurring herbicide volume through trait licensing structures.
- Asian soybean rust pressure:Argentina's Pampas grain belt requires intensified fungicide applications, accelerating product rotation cycles and premium formulation uptake.
- Fall armyworm resistance cycles:Novel insecticide mode-of-action demand intensifies across Paraguay and Bolivia as established chemistries lose field efficacy.
Market Restraints
- Active ingredient import concentration:Chinese intermediate supply dominates synthesis pathways, exposing formulators to shipping cost volatility and customs clearance delays.
- ANVISA registration timelines:Brazil's residue limit revisions extend product reformulation cycles by 18-24 months, freezing portfolio turnover.
- Biological substitution threat:Microbial inoculants and biofungicides capture share in Brazilian organic soybean and Argentine horticulture segments.
Strategic Opportunities
- Colombian coffee belt expansion:Fungicide demand in Antioquia and Caldas intensifies as leaf rust pressure climbs at higher altitudes, opening specialty formulation channels.
- Seed treatment convergence:Biological-synthetic co-formulations penetrate Brazilian maize and cotton planting programs, commanding per-hectare premiums.
- COFEPRIS fast-track pathways:Mexico's emerging biocide registration acceleration for low-toxicity candidates rewards early microbial portfolio entrants.
Industry Challenges
- Resistance management expertise:Agronomic advisory capacity lags behind novel chemistry deployment rates, degrading product lifecycle returns.
- Multinational formulation capex:Localized production investments for Brazil's import substitution mandates strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Crop Protection Chemicals Market |
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $32.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Growth Regulators Application: Field Crops, Horticultural Crops, Turf & Ornamental, Others End Use Industry: Agriculture, Aquaculture, Forestry, Others Distribution Channel: Direct Sales, Distributor, Retail, E-commerce |
| Companies Covered | Corteva Agriscience, UPL Limited, BASF SE, ADAMA Ltd, Sumitomo Chemical Co. Ltd, Bayer AG, FMC Corporation, Nufarm Ltd, Syngenta AG, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Crop Protection Chemicals Market Strategic Shifts & Innovations
Biological-synthetic hybrid formulations are displacing pure chemistry portfolios across Latin America's major row-crop segments, while regulatory data requirements harden and distribution channels consolidate around integrated agronomy service bundles.
RNA interference crop protection is converging with precision application systems to enable species-specific pest suppression without broad-spectrum ecological damage. Brazilian soybean cooperatives in Mato Grosso are piloting foliar RNAi sprays against lepidopteran pests at scale. This convergence is compressing conventional insecticide development pipelines as trait-specific chemistries bypass resistance management complexity.
ANVISA's updated toxicological reassessment protocols now mandate chronic exposure studies for all endocrine-active candidates seeking Brazilian registration renewal. The industrial consequence forces reformulation of legacy organophosphate and triazole portfolios before patent cliff deadlines. Argentina's SENASA is harmonizing residue testing methodologies with these standards, accelerating regional regulatory convergence.
Cooperative procurement consortia across Brazil's Mato Grosso and Goiás grain belts are consolidating chemical purchasing into annual volume tenders with embedded technical advisory services. Traditional distributor networks face margin compression as these buying groups negotiate direct manufacturer relationships. This pattern is most visible in soybean-dominant municipalities where scale concentration enables price transparency platforms.
Latin America Crop Protection Chemicals Market Segmentation
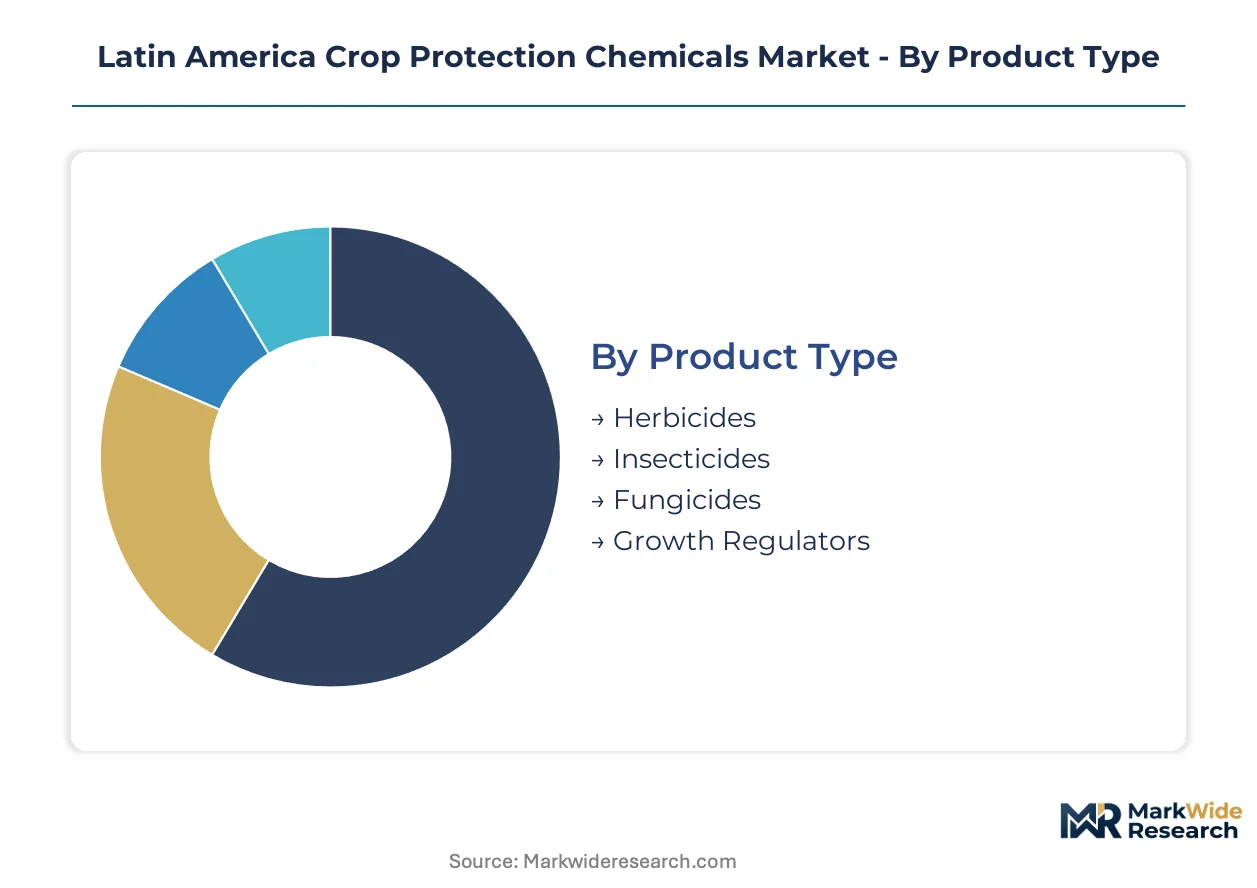
Segmentation reveals how capital deployment and regulatory exposure vary across Latin America's crop protection landscape. Product type and application channel determine where manufacturers concentrate R&D investment and where distributors build technical service capabilities.
Product Type:
Herbicide formulation demands the heaviest upfront capital outlay due to trait-licensing infrastructure and resistance management R&D. Fungicide synthesis requires specialized fermentation and downstream processing assets.
- Herbicides:Glyphosate-tolerant seed systems anchor volume across Brazil's Cerrado, with formulation plants requiring dedicated adjuvant blending lines and trait-stacking compatibility testing. Brazilian cooperatives in Mato Grosso and Goiás lock in recurring volume through bundled chemical-seed procurement.
- Fungicides:Azole and strobilurin chemistry dominates rust control in Argentina's Pampas, where Asian soybean rust pressure forces product rotation cycles. Climate volatility intensifies blight outbreaks, accelerating premium formulation uptake.
- Insecticides:Novel mode-of-action molecules target fall armyworm resistance in Paraguay and Bolivia.
- Growth Regulators:Cytokinin and gibberellin formulations penetrate Brazilian sugarcane and Argentine wine grape segments.
Most installed capacity flows through Herbicides. Expansion is steepest in Fungicides.
Application:
Field crop programs generate volume concentration, while horticultural applications command per-hectare premium pricing through intensive spray calendars.
- Field Crops:Soybean, maize, and wheat dominate chemical consumption across the region's mechanized grain belts. Brazil's Cerrado and Argentina's Pampas concentrate tractor-mounted boom sprayer deployment at scale.
- Horticultural Crops:Argentine pome fruit and Brazilian citrus require precision application equipment and residue compliance protocols. Per-hectare spending multiples exceed row-crop benchmarks due to export market MRL requirements.
- Turf & Ornamental:Golf course and landscape maintenance drives specialized formulation demand in Mexico's urban centers.
- Others:Pasture renovation and rangeland brush control absorb volume in Uruguay and southern Brazil.
Field Crops absorb the largest volume share. Horticultural Crops deliver the steepest margin expansion trajectory.
End Use Industry:
Agriculture concentrates procurement decision-making through cooperative structures, while aquaculture and forestry present specialized regulatory pathways.
- Agriculture:Row-crop and specialty crop production consumes the vast majority of formulated products. ANVISA registration timelines and SENASA residue protocols directly shape portfolio availability.
- Aquaculture:Shrimp and finfish operations in Ecuador and Honduras require aquatic-toxicity-screened chemistries with restricted environmental persistence.
- Forestry:Eucalyptus and pine plantation management in Brazil and Chile drives pre-emergent herbicide demand for establishment-phase weed control.
- Others:Industrial vegetation management and rights-of-way maintenance absorb residual volume.
Agriculture commands nearly all formulation throughput. Aquaculture is climbing the fastest on export certification requirements.
Distribution Channel:
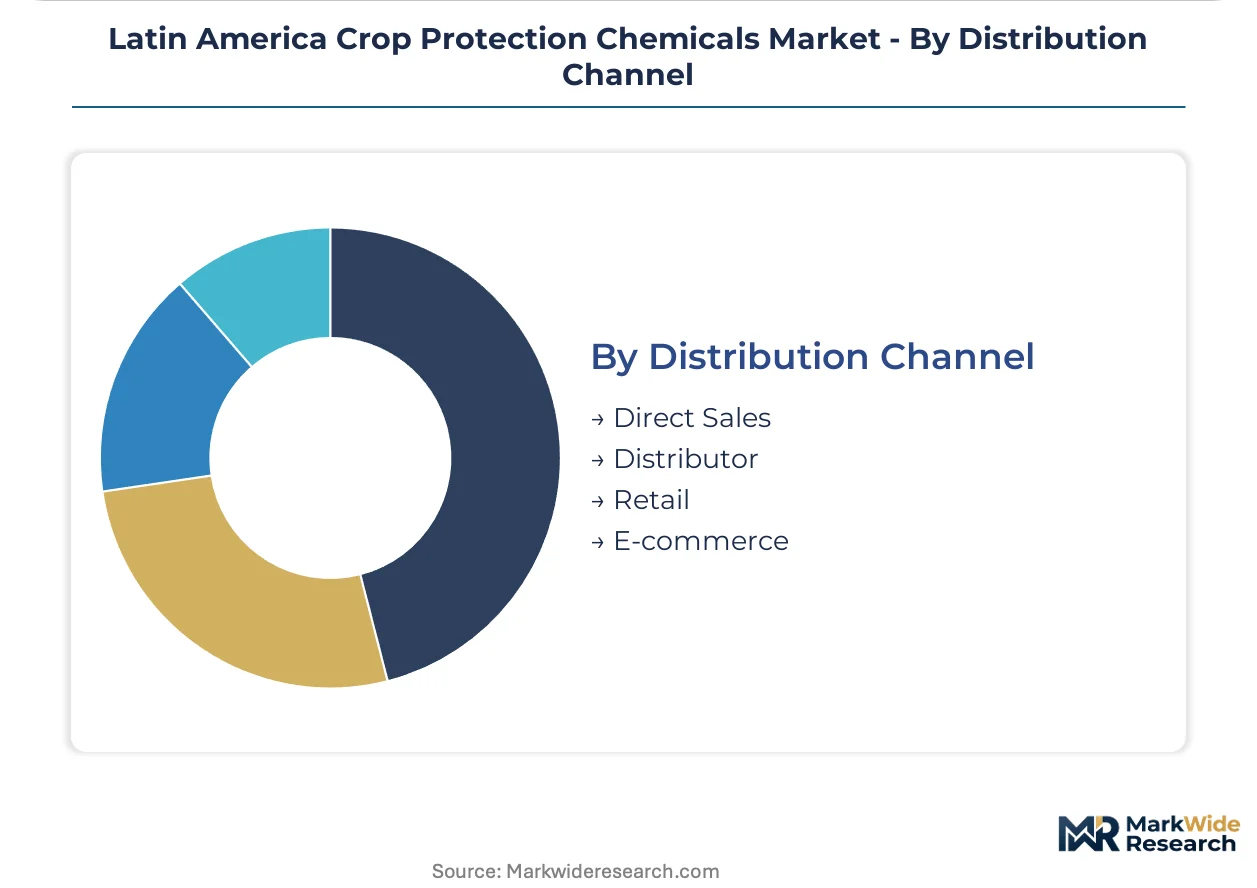
Channel selection determines working capital intensity and technical service obligations, with direct sales requiring the deepest agronomic advisory infrastructure.
- Direct Sales:Manufacturer-to-cooperative relationships bypass traditional distributor margins in Brazil's consolidated grain belts. Annual volume tenders embed technical advisory services and resistance monitoring protocols.
- Distributor:Regional chemical distributors maintain formulation inventory and application equipment fleets across fragmented farm structures in Paraguay and Bolivia.
- Retail:Agrochemical retail outlets serve smallholder segments with break-bulk packaging and seasonal credit terms.
- E-commerce:Digital procurement platforms penetrate Brazilian soybean municipalities where price transparency tools enable direct price discovery.
Direct Sales channels capture the largest value pool. E-commerce is gaining share fastest on cooperative procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agronomic expertise concentrates in Brazil's Cerrado research corridors and Argentina's Pampas extension networks, anchoring formulation demand and field trial infrastructure across the continent.
Brazil
Soybean seed-trait licensing and herbicide bundling drive recurring chemical volume through Mato Grosso and Goiás cooperatives. ANVISA's residue threshold recalibration extends reformulation cycles by 18-24 months, freezing portfolio turnover for foreign registrants. São Paulo state hosts multinational formulation plants serving the domestic market and Mercosur re-export channels.
Argentina
Asian soybean rust pressure across the Pampas grain belt accelerates fungicide rotation cycles and premium azole uptake. SENASA harmonizes residue testing protocols with Brazilian standards, tightening import authorization pathways for European and Asian suppliers. Rosario and Buenos Aires provinces concentrate blending facilities and grain export logistics that synchronize chemical procurement calendars.
Mexico
Horticultural export certification to US markets drives residue-compliant formulation demand in Sinaloa and Jalisco berry and vegetable clusters. COFEPRIS fast-track registration pathways for low-toxicity biocide candidates reward early microbial portfolio entrants. Mexico City metropolitan area anchors distributor networks serving the Bajío region's intensive glasshouse operations.
Colombia
Coffee leaf rust intensification at higher altitudes in Antioquia and Caldas departments opens specialty fungicide formulation channels for arabica protection. The country's national agricultural regulator mandates stricter aquatic toxicity screening for watershed-adjacent applications. Medellín-based cooperatives consolidate procurement for the central coffee belt's 800,000+ hectare footprint.
Chile
Table grape and stone fruit export MRL compliance commands per-hectare premium spending in the Central Valley's intensive horticulture zones. The national agricultural and livestock service enforces residue protocols aligned with EU and US destination markets. Santiago and O'Higgins regions concentrate precision application equipment fleets serving vertically integrated fruit exporters.
Latin America Crop Protection Chemicals Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across Latin America's crop protection chemicals sector, creating a tiered structure where scale-driven multinationals anchor volume segments and regional formulators capture niche resistance-management niches. The market exhibits moderate consolidation with the top five players commanding significant share in soybean-dominant territories. Strategic archetypes include trait-anchored seed-chemical bundlers, fermentation-based fungicide specialists, and distribution-integrated regional formulators. Competitive dynamics center on direct-to-cooperative procurement bypasses and localized production investments for import substitution compliance.
Within the diversified agrochemical tier, Bayer AG and BASF SE exemplify scale-driven conglomerates with integrated seed-trait pipelines, while Corteva Agriscience occupies a position anchored in proprietary herbicide-tolerant systems. FMC Corporation represents the specialized insecticide archetype targeting novel mode-of-action deployment against resistance cycles. These entities sit within a competitive matrix where registration capacity and agronomic advisory infrastructure determine cooperative procurement access across Brazil's consolidated grain belts and Argentina's Pampas farming syndicates.
| Leading Market Players |
|---|
| Corteva Agriscience |
| UPL Limited |
| BASF SE |
| ADAMA Ltd |
| Sumitomo Chemical Co. Ltd |
| Bayer AG |
| FMC Corporation |
| Nufarm Ltd |
| Syngenta AG |
| Others |
Cost & Logistics Intelligence
Captive production of glyphosate intermediates in São Paulo and Paraná states anchors pricing power for Brazilian formulators serving Mato Grosso cooperatives, while Chinese import dependency among Argentine blenders exposes them to freight volatility and customs clearance arbitrage.
Pricing Analysis
Bundled chemical-seed procurement through trait-licensing structures commands premium positioning against unbundled spot purchases in Paraguay and Bolivia. Pricing stratifies across premium, standard, and economy tiers based on formulation complexity and embedded technical advisory services. Cost compression in generic herbicide segments is intensifying because Mato Grosso cooperative tenders force transparency on active ingredient sourcing. Smallholder retail channels exhibit highest price sensitivity; direct-to-cooperative volumes show lowest.
Supply Chain Analysis
Regional distribution centers in São Paulo and Rosario operate hub-and-spoke patterns feeding satellite blending facilities across the Cerrado and Pampas. Active ingredient synthesis concentrates in China, India, and domestic Brazilian fermentation plants. Formulation draws from glyphosate technical, azole intermediates, and novel insecticide molecules. Single-source vulnerability in Chinese intermediate supply creates exposure to shipping cost spikes. Distribution runs through cooperative procurement consortia bypassing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American crop protection functions as a geographic-arbitrage play where ANVISA registration timelines stretch 18-24 months versus COFEPRIS fast-track pathways for biocide candidates, rewarding portfolio allocation toward Mexico's accelerated approval jurisdiction.
For Market Incumbents: Acquire microbial formulation capabilities to counter biological substitution threats in Brazilian organic soybean segments. Backward integration into captive azole fermentation insulates against Chinese intermediate volatility. Lock in multi-year resistance monitoring contracts with Mato Grosso cooperatives to defend service-embedded pricing.
For New Entrants and Emerging Players: Distributor partnerships in Paraguay and Bolivia offer lowest barrier-to-entry given fragmented farm structures and limited incumbent technical advisory penetration. Target fall armyworm resistance management niches where novel insecticide modes-of-action face minimal generic competition. Lead with digital procurement platforms enabling cooperative price discovery.
For Investors and Strategic Acquirers: Consolidation pressure builds where ANVISA registration capacity constraints strand foreign portfolios awaiting reformulation approval. Mid-term viability hinges on biological-synthetic hybrid R&D pipelines and seed-treatment convergence capabilities. Watch SENASA-ANVISA regulatory harmonization progress as inflection signal for Argentine market access premium compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredient Synthesis | Captive glyphosate technical production in São Paulo state insulates Brazilian formulators from Chinese shipping volatility. |
| Biological-Synthetic Co-formulation Development | Microbial inoculant bundling with conventional chemistry captures premium positioning in seed treatment channels. |
| Direct Cooperative Procurement Relationships | Annual volume tenders with Mato Grosso and Goiás buying groups bypass distributor margin extraction. |
| COFEPRIS Fast-track Registration Investment | Early microbial portfolio positioning in Mexico exploits accelerated low-toxicity biocide approval pathways. |
| Resistance Monitoring Service Contracts | Embedded technical advisory with Pampas farming syndicates locks in fungicide rotation cycle recurring revenue. |
Research Approach
Coverage spans Brazil, Argentina, Mexico, Colombia, and Chile, with primary inputs from each country's major agricultural production corridors. The analysis combines structured interviews with formulation plant managers, cooperative procurement directors, SENASA regulatory affairs leads, and distribution channel partners with secondary validation through customs trade data, ANVISA registration filings, and SEC 10-K agricultural chemical segment disclosures. Bottom-up volume builds triangulate against top-down macroeconomic agricultural output projections.
Granularity-level modeling operates at product-type, application-channel, and country-regulation cluster dimensions. Value outputs across the analysis window derive from price-point sampling at cooperative tender, distributor wholesale, and retail channel levels. CAGRs emerge from segment-level growth rate reconciliation with macro agricultural commodity price assumptions and climate volatility indices affecting pest pressure cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANVISA residue threshold recalibration timing and Chinese intermediate export policy shifts. Outputs reflect documented assumptions around regulatory harmonization pace and biological substitution adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Global Acaricides Market
Crop Protection
Soil Fumigant Market
Crop Protection
Tembotrione Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
China Crop Protection Chemicals Market
Crop Protection
Europe Molluscicides Market
Crop Protection
South Korea Crop Protection Chemicals Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
North America Molluscicides Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Tebuconazole Epoxide Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
Europe Seed Treatment Market
Crop Protection
Thailand Crop Protection Chemicals Market
Crop Protection
Europe Herbicide Market