
 Italy Crop Protection Chemicals (Pesticides) Market | 2026-2036
Italy Crop Protection Chemicals (Pesticides) Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Crop Protection Chemicals (Pesticides) Market Foresight
EC-formulation premium tiers is redrawing competitive dynamics across the Italian pesticide sector. Syngenta Group leverages its integrated seed-chemistry platform to dominate high-value specialty crop segments in the Po Valley. BASF SE anchors its position through advanced fungicide R&D targeting vineyard downy mildew pressures in Veneto and Trentino. Bayer CropScience AG differentiates via digital farming tools bundled with crop protection packages for northern Italy's precision agriculture adopters.
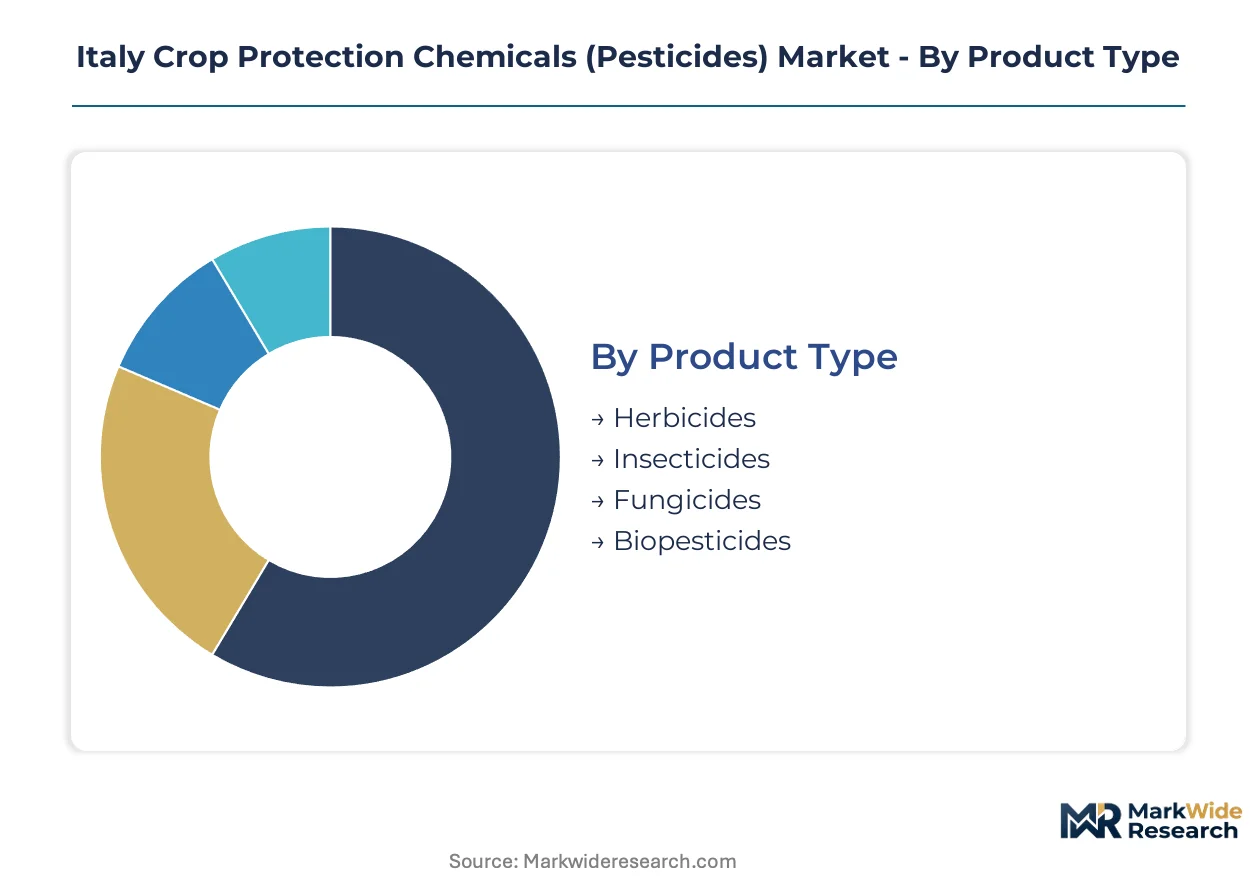
Crop protection chemicals are synthetic or biological active ingredients formulated to control weeds, insects, fungi, and other agricultural pests, typically delivered as emulsifiable concentrates or wettable powders with specified active ingredient loadings between 100–500 g/L for field-scale application. These agents protect yield and quality in commercial crop production by disrupting pest physiology or behavior at threshold infestation levels. Herbicides command the largest share of Italy's product type split, reflecting extensive cereal and vineyard acreage, while biopesticides represent the fastest-expanding category as EU Farm-to-Fork targets constrain synthetic molecule approvals. On-field deployment generates the dominant volume flow, though greenhouse applications in southeastern Sicily yield higher per-hectare formulation values due to intensive horticultural rotations.
Italy's pesticide market operates under the EU Plant Protection Products Regulation (EC 1107/2009), with EFSA conducting peer reviews of active substance renewals that directly determine product portfolio viability for manufacturers serving Italian growers. The EU Green Deal's 50% pesticide reduction target is forcing reformulation investments toward biological and reduced-risk chemistries before national Farm-to-Fork implementation deadlines. REACH compliance for co-formulant substances adds secondary regulatory screening that shapes import sourcing and local blending economics. Stakeholders must monitor ECHA candidate list expansions for endocrine-disruptor classifications that could trigger abrupt product withdrawals across Italy's stone fruit and vegetable sectors.
Market Dynamics
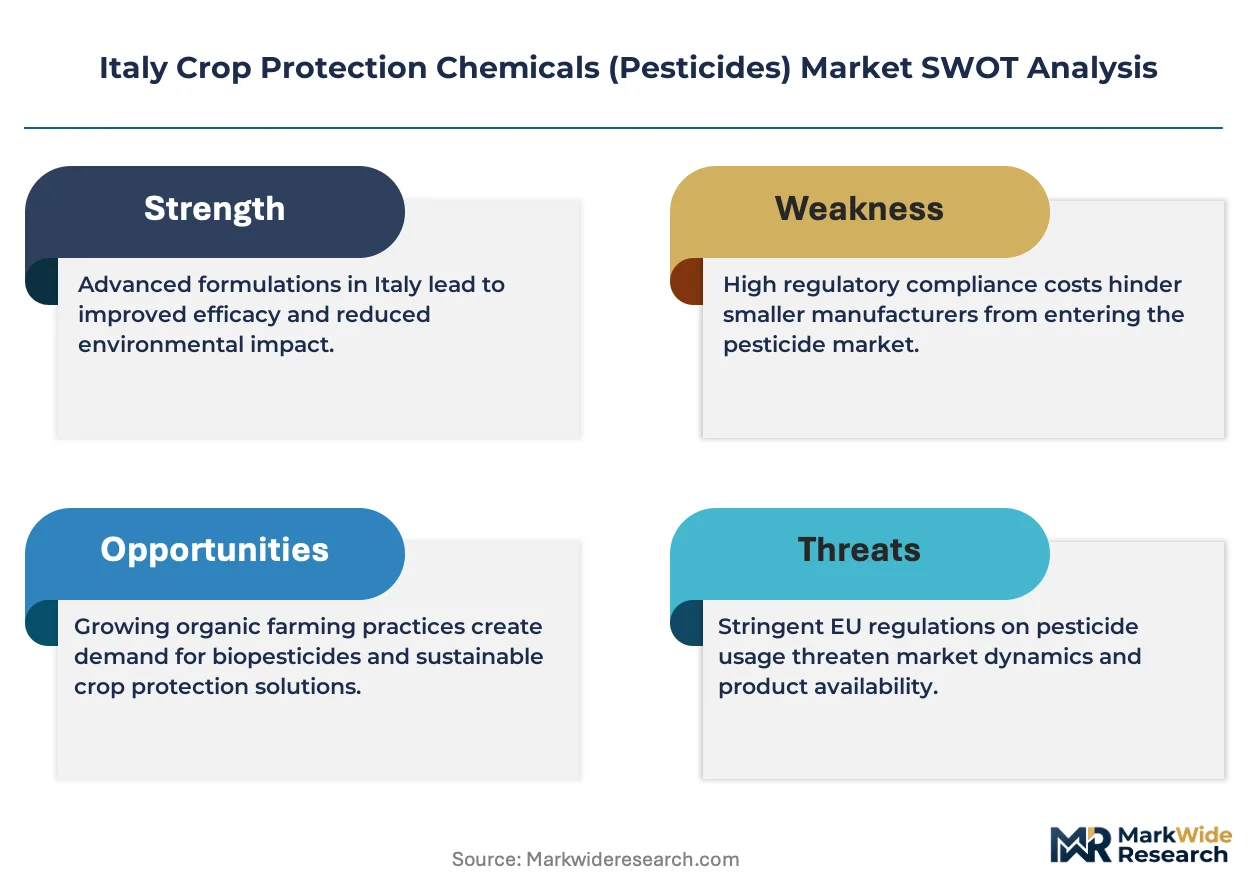
The EU Green Deal's 50% pesticide reduction mandate is compressing formulation economics across Italy, forcing manufacturers to rebuild portfolios around biological actives and reduced-risk chemistries before Farm-to-Fork deadlines lock in.
Growth Catalysts
- EU Sustainable Use Regulation:Italy's National Action Plan accelerates low-dose formulation demand, creating pull-through for precision application equipment in northern cereal zones.
- Sicily-Apulia specialty crop expansion:Olive and vineyard acreage growth drives herbicide volume in southern regions with limited mechanical weed control alternatives.
- Biological fermentation advances:Improved strain viability in wettable powder formats reduces cold-chain dependency, unlocking distribution to smaller Po Valley cooperatives.
Market Restraints
- Active substance renewal volatility:EFSA peer review unpredictability for existing molecules forces manufacturers to maintain parallel R&D tracks, inflating fixed costs.
- Co-formulant REACH screening:ECHA candidate list expansions for endocrine disruptors threaten abrupt withdrawals across stone fruit and vegetable protection portfolios.
- Import sourcing concentration:Technical grade active ingredient reliance on non-EU suppliers exposes blenders to currency and customs friction at Italian port terminals.
Strategic Opportunities
- Greenhouse horticulture intensification:Southeastern Sicily's protected vegetable rotations generate per-hectare formulation values 3-4x above open-field cereals, rewarding high-frequency application schedules.
- Digital bundling models:Sensor-based pest monitoring integrated with variable-rate spraying creates subscription revenue streams among precision agriculture adopters in Emilia-Romagna.
- Biopesticide registration fast-tracks:EU Farm-to-Fork implementation timelines offer temporary regulatory preference for microbial and biochemical submissions, compressing time-to-market versus synthetic equivalents.
Industry Challenges
- Formulation chemist scarcity:Expertise in EC-to-SC (suspension concentrate) conversion for low-dose actives concentrates among retiring specialists in Lombardy blending facilities.
- Legacy equipment incompatibility:Existing spray tank and nozzle configurations in Piedmont cooperatives require capital retrofit to handle biological product viscosity and particle size distributions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Crop Protection Chemicals (Pesticides) Market |
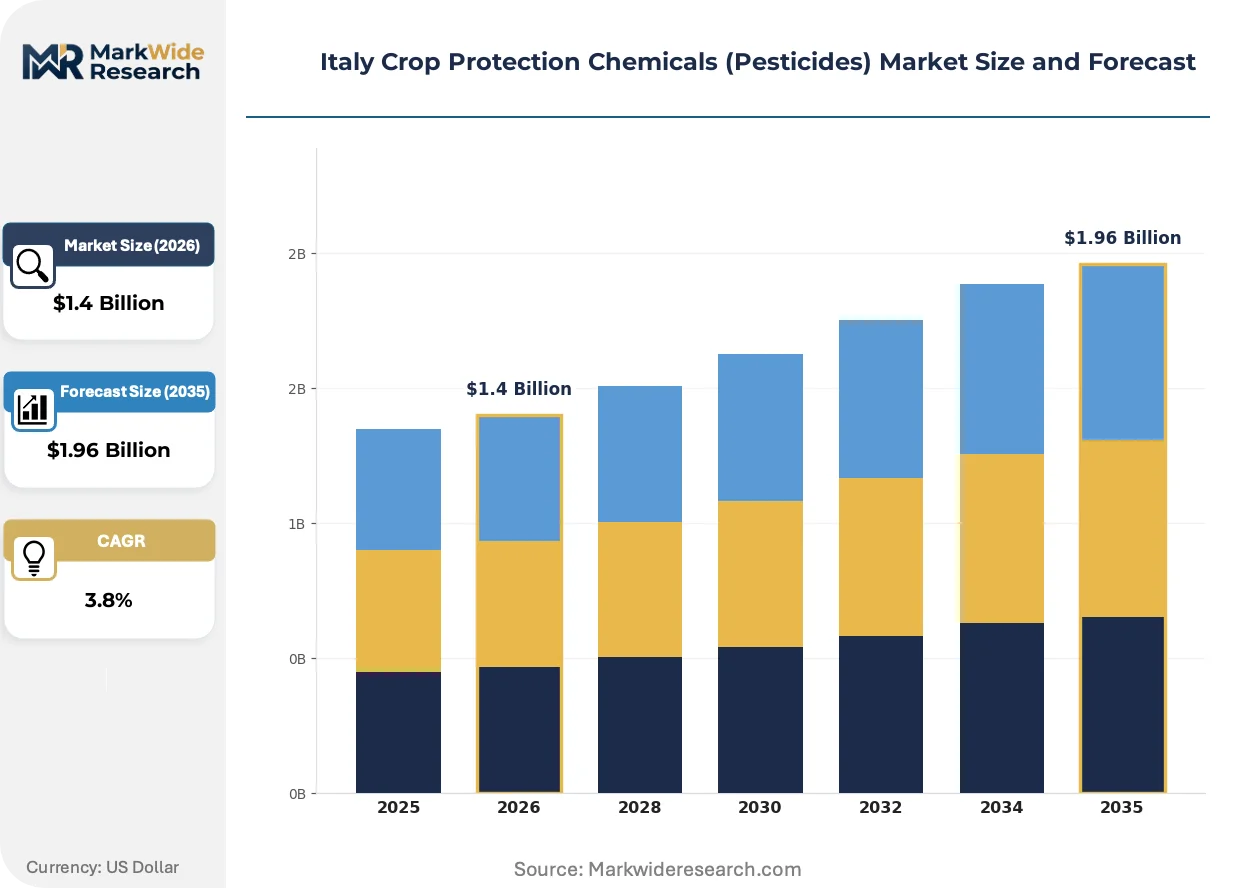
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $1.96 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Biopesticides Deployment: On-field, Greenhouse, Seed Treatment, Soil Treatment End Use Industry: Agricultural, Horticultural, Turf Management, Ornamental Formulation: Granular, Liquid, Emulsifiable Concentrate, Wettable Powder |
| Companies Covered | Syngenta Group, BASF SE, Bayer CropScience AG, Corteva Agriscience, UPL Ltd, Adama Agricultural Solutions Ltd, Sumitomo Chemical Co Ltd, Sipcam Oxon S.p.A., FMC Agro Italia S.r.l., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Crop Protection Chemicals (Pesticides) Market Shifts & Advancements
Formulation chemistry and application precision are converging to redefine product value capture, with hardware-software bundling and biological actives eroding the standalone chemical model.
Microencapsulated delivery systems are supplanting conventional emulsifiable concentrates in vineyard and orchard applications. Veneto and Trentino wine cooperatives are adopting these formats at accelerating rates to align spray timing with fungal pressure alerts. The technology is supplanting calendar-based application schedules, compressing fungicide volume per hectare while raising per-liter formulation premiums.
EU Farm-to-Fork pesticide reduction targets are forcing reformulation investments toward reduced-risk chemistries before 2030 implementation deadlines. Manufacturers serving Italian growers must rebuild active substance portfolios around biological and low-dose synthetic molecules to maintain registration viability. The Po Valley cereal belt faces the steepest adjustment, as wheat and maize protection historically relied on broad-spectrum actives now facing renewal scrutiny.
Cooperative procurement consolidation is compressing distributor margins across northern Italy. Large arable farming associations in Emilia-Romagna and Lombardy are centralizing chemical purchasing through tender platforms, displacing independent agrochemical retailers. This concentration is most visible in fungicide categories for winter wheat, where volume commitments extract price concessions exceeding 15% from traditional channel structures.
Italy Crop Protection Chemicals (Pesticides) Market Segmentation
Italy's pesticide market fragments across formulation chemistry, application setting, and crop system economics. Each dimension carries distinct margin profiles and regulatory exposure that shape manufacturer portfolio priorities.
Product Type:
Margin pools concentrate in synthetic actives with established residue tolerance frameworks, though biological alternatives are capturing premium positioning in specialty crop channels.
- Herbicides:Synthetic auxins and ALS inhibitors dominate volume, formulated as emulsifiable concentrates for cereal and vineyard weed control. Po Valley arable cooperatives drive tonnage for pre-emergent grass management in wheat rotations, though glyphosate renewal uncertainty at EFSA is forcing parallel R&D investment.
- Fungicides:Triazole and SDHI chemistry protects high-value vineyard and orchard assets across Veneto and Trentino. Downy mildew pressure in humid northern climates sustains application frequency, with microencapsulated formulations commanding 20-30% price premiums over standard wettable powders.
- Insecticides:Pyrethroid and neonicotinoid alternatives face restricted use zones under EU Sustainable Use Regulation implementation.
- Biopesticides:Microbial fermentation products from Bacillus subtilis and Trichoderma strains are climbing the fastest, accelerated by Farm-to-Fork registration fast-tracks and Sicily greenhouse grower adoption.
Herbicides hold installed capacity. Biopesticides are rotating up the share rankings.
Deployment:
Application setting determines formulation value density, with protected cultivation yielding per-hectare economics that dwarf open-field commodity cropping.
- On-field:Broadcast spraying dominates volume, delivered via tractor-mounted boom sprayers across Lombardy and Emilia-Romagna cereal belts. Standard emulsifiable concentrates and suspension concentrates flow through cooperative procurement channels at thin margins.
- Greenhouse:Protected vegetable rotations in southeastern Sicily generate formulation values multiple times above open-field equivalents. High-frequency fungicide and insecticide schedules for tomato and pepper crops reward precision application equipment and low-volume concentrate formats.
- Seed Treatment:Neonicotinoid replacement chemistry for maize and cereal sowing faces regulatory transition pressure.
- Soil Treatment:Fumigant alternatives and biological inoculants target nematode and soil-borne pathogen suppression in intensively rotated vegetable ground.
On-field deployment anchors volume throughput. Greenhouse applications are expanding most quickly in value contribution.
End Use Industry:
Customer type stratification separates price-tolerant specialty producers from margin-pressed commodity operators.
- Agricultural:Arable and permanent crop farming across northern and central Italy consumes the dominant share of synthetic active volume. Wheat, maize, and rice protection in the Po Valley operates on thin margins with centralized cooperative purchasing.
- Horticultural:Protected and open-field vegetable production in Sicily, Apulia, and Campania demands intensive pest management with lower tolerance for cosmetic damage. This segment absorbs premium formulation chemistry and biological alternatives at price points unavailable to cereal growers.
- Turf Management:Golf course and sports ground maintenance in affluent northern regions sustains selective herbicide demand.
- Ornamental:Nursery and floriculture operations concentrate in Liguria and Tuscany, requiring disease suppression for export-grade plant material.
Agricultural end use holds installed capacity. Horticultural applications are rotating up the share rankings.
Formulation:
Physical delivery format determines manufacturing complexity, distribution economics, and compatibility with precision application hardware.
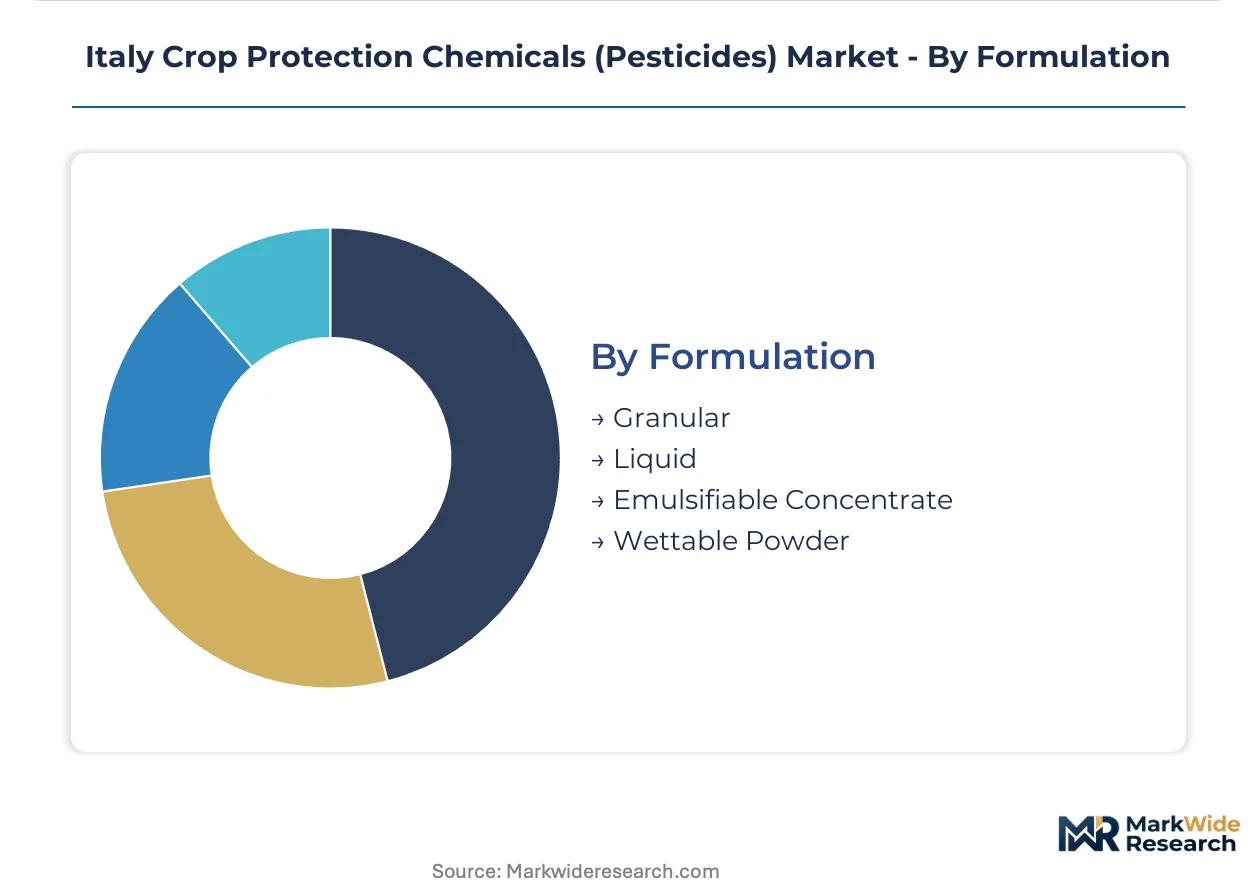
- Liquid:Suspension concentrates and solution formulations dominate new product development, offering low-dose compatibility and tank-mix flexibility. Northern Italian precision agriculture adopters favor these formats for variable-rate spraying systems.
- Emulsifiable Concentrate:Traditional solvent-based chemistry retains share in vineyard and orchard segments where lipophilic active penetration enhances efficacy. Veneto wine cooperatives maintain EC preference for certain fungicide actives despite regulatory pressure on aromatic solvent content.
- Granular:Controlled-release matrices and soil-applied insecticide granules target specific crop-pest combinations.
- Wettable Powder:Dry flowable biological products reduce cold-chain dependency for microbial actives distributed to smaller Po Valley cooperatives.
Emulsifiable concentrate holds installed capacity. Liquid formulations are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active ingredient blending concentrates in northern Italy's industrial corridor, with formulation plants clustering around Milan and Bologna to serve Po Valley cereal cooperatives. Southern regions depend on imported technical grade inputs transshipped through Taranto and Gioia Tauro ports.
Lombardy
Precision agriculture adopters in the Po Valley cereal belt drive suspension concentrate demand for wheat and maize protection. EFSA peer review timelines for active substance renewals directly determine product portfolio viability for blenders operating around Milan. The Lombardy agrochemical cluster anchors formulation supply for northern Italian arable cooperatives.
Veneto
Downy mildew pressure in humid vineyard zones sustains fungicide application frequency across prosecco and still wine production areas. EU Sustainable Use Regulation implementation forces spray record digitization in Verona and Treviso provinces. Veneto wine cooperatives command microencapsulated formulation premiums exceeding standard wettable powders.
Emilia-Romagna
Large arable farming associations centralize chemical purchasing through tender platforms, extracting price concessions from traditional distribution channels. REACH compliance screening for co-formulant substances shapes import sourcing economics at Ravenna port terminals. The region's precision agriculture adopters favor variable-rate spraying systems bundled with sensor-based pest monitoring.
Sicily
Protected vegetable rotations in southeastern provinces generate per-hectare formulation values multiple times above open-field cereal equivalents. Farm-to-Fork registration fast-tracks accelerate microbial biopesticide adoption among greenhouse tomato and pepper growers. Catania and Syracuse horticultural clusters reward high-frequency application schedules with low-volume concentrate formats.
Apulia
Olive and vineyard acreage expansion drives herbicide volume where mechanical weed control alternatives remain limited. ECHA candidate list expansions for endocrine disruptor classifications threaten abrupt product withdrawals across stone fruit protection portfolios. Bari and Brindisi distribution hubs face cold-chain infrastructure constraints for biological product viability.
Italy Crop Protection Chemicals (Pesticides) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Italian pesticide sector. Integrated seed-chemistry platforms dominate high-value specialty crop segments, while generic technical grade suppliers compete on price in commodity cereal protection. Three archetypes structure competitive dynamics: R&D-intensive multinationals with proprietary active pipelines, regional blenders with formulation flexibility, and biological specialists leveraging regulatory fast-tracks. Consolidation pressure intensifies through cooperative procurement centralization and parallel R&D track requirements for EFSA renewal volatility.
Within the integrated multinational tier, Syngenta Group, BASF SE, and Bayer CropScience AG exemplify divergent strategic positioning. Syngenta anchors high-value specialty crop segments through seed-chemistry integration. BASF occupies advanced fungicide R&D positioning targeting vineyard disease pressures. Bayer represents digital farming bundling approaches for precision agriculture adopters. Each occupies a distinct competitive vector rather than direct segment overlap.
| Leading Market Players |
|---|
| Syngenta Group |
| BASF SE |
| Bayer CropScience AG |
| Corteva Agriscience |
| UPL Ltd |
| Adama Agricultural Solutions Ltd |
| Sumitomo Chemical Co Ltd |
| Sipcam Oxon S.p.A. |
| FMC Agro Italia S.r.l. |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between Po Valley cereal cooperatives and Milan-based formulators lock in both technical grade active ingredient supply and price visibility across multi-season procurement cycles. These arrangements insulate Italian blenders from spot market volatility in glyphosate and azole fungicide precursors while compressing margin flexibility for distributors caught between fixed input costs and cooperative tender pressures.
Pricing Analysis
EU Farm-to-Fork implementation timelines dictate the pricing tier structure across Italian crop protection portfolios. Three-tier pricing structure across premium microencapsulated fungicides, standard suspension concentrates, and economy emulsifiable concentrates separates vineyard specialists in Veneto from commodity cereal operators in Lombardy. Price differentiation hinges on formulation complexity and cold-chain biological viability. Cost compression in economy-tier herbicides is intensifying because cooperative procurement centralization extracts volume concessions exceeding traditional channel margins. Commodity wheat protection shows highest price sensitivity; greenhouse horticulture in Sicily demonstrates lowest sensitivity due to cosmetic damage thresholds.
Supply Chain Analysis
Taranto port customs clearance capacity serves as the primary chokepoint for technical grade active ingredients entering southern Italian blending facilities. Geographic supply concentration centers on China for glyphosate and pyrethroid precursors, India for generic fungicide intermediates, and Germany for proprietary SDHI chemistry. Raw material dependencies include aromatic solvents for EC formulations, microbial fermentation substrates for biopesticides, and polymer encapsulation agents for controlled-release products. Single-source vulnerability runs through non-EU technical grade suppliers exposed to currency friction and REACH co-formulant screening. Distribution runs through cooperative procurement platforms in northern Italy and independent agrochemical retailers in fragmented southern markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian crop protection is transitioning toward service-attach revenue models where sensor-based pest monitoring subscriptions expand faster than standalone chemical volumes. Digital bundling with variable-rate application hardware creates recurring revenue layers that offset commodity formulation margin erosion.
For Market Incumbents: Compound defensive positioning through backward integration into microbial fermentation capacity and exclusive distribution agreements with Emilia-Romagna precision agriculture cooperatives. EFSA active substance renewal volatility threatens portfolio viability for synthetic molecules; priority investment in biological R&D and low-dose formulation chemist recruitment locks in Farm-to-Fork compliance. For New Entrants and Emerging Players: EU biopesticide registration fast-tracks offer temporary regulatory preference compressing time-to-market versus synthetic equivalents. White-space targets include southeastern Sicily greenhouse horticulture with high-frequency application schedules and Apulia olive grove herbicide segments with limited mechanical alternatives. Go-to-market angle: wettable powder biological products eliminating cold-chain dependency for smaller Po Valley cooperatives. For Investors and Strategic Acquirers: Capital is best deployed toward regional blenders with formulation flexibility and established cooperative relationships rather than R&D-intensive multinationals facing parallel pipeline risks. Long-term viability favors biological specialists leveraging regulatory fast-tracks and digital farming integrators capturing subscription revenue. Signal to watch: ECHA candidate list expansions for endocrine disruptor classifications triggering abrupt product withdrawals across stone fruit and vegetable portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Microbial Fermentation | Captures Farm-to-Fork biological demand while reducing reliance on Chinese technical grade suppliers. |
| Digital Bundling with Sensor-Based Monitoring | Creates subscription revenue streams among Emilia-Romagna precision agriculture adopters beyond chemical sales. |
| Low-Dose Formulation Conversion (EC-to-SC) | Aligns with EU Sustainable Use Regulation mandates and extends product registration viability. |
| Cooperative Procurement Platform Partnerships | Secures volume commitments from Lombardy and Emilia-Romagna arable associations displacing independent retailers. |
| Greenhouse Horticulture Application Specialist Positioning | Captures 3-4x per-hectare formulation values in southeastern Sicily protected vegetable rotations. |
Research Methodology
Cross-validation between primary interviews with Italian formulator plant managers, cooperative procurement leads, vineyard technical directors, and EFSA regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from EU Pesticides Database active substance renewal records, REACH co-formulant screening notifications, Italian customs trade data for technical grade imports, and Cefic sector reports. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers across the Italian agricultural economy.
Sensitivity analysis around EFSA peer review timelines and EU Farm-to-Fork implementation pacing shapes the analytical framework. Segmentation dimensions span product type, deployment setting, end-use industry, and formulation chemistry across the projection horizon. CAGRs derive from installed base erosion rates for synthetic actives and adoption curves for biological alternatives. Industry-specific forecast inputs include cooperative procurement consolidation velocity and greenhouse horticulture intensification rates in Sicily.
Decision-makers should treat outputs as directional under sustained EU Green Deal policy commitment and stable EFSA renewal procedures; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA endocrine disruptor classifications and non-EU supplier trade policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
US Herbicide Market
Crop Protection
Vietnam Crop Protection Chemicals Market
Crop Protection
Tebuconazole Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
Global Aquatic Herbicides Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
India Herbicide Market
Crop Protection
Fumigation Market
Crop Protection
Metamitron Herbicides Market
Crop Protection
Middle East and Africa Algaecides Market
Crop Protection
Global Organophosphate Pesticide Market
Crop Protection
US Pest Control Market
Crop Protection
Glufosinate Ammonium Market
Crop Protection
Germany Crop Protection Chemicals Market
Crop Protection
Europe Agricultural Pheromones Market
Crop Protection
North America Crop Protection Chemicals Market