
 Tebuconazole Market | 2026-2036
Tebuconazole Market Size, Share, and Industry Trends Forecast 2026-2036
Tebuconazole Market Analysis
China's agrochemical manufacturing corridor is rewriting supply dynamics for triazole fungicide output. Bayer CropScience leverages integrated active ingredient production to sustain cost leadership across European cereal markets. Sumitomo Chemical Corporation anchors its position through proprietary formulation technology that extends field persistence. Jiangsu Sword Agrochemicals competes on volume scale, supplying technical-grade material to blenders across Southeast Asia.
Tebuconazole functions as a systemic triazole fungicide inhibiting ergosterol biosynthesis in fungal cell membranes, with typical application rates of 125–250 grams active ingredient per hectare in cereal and soybean protection. The molecule delivers curative and protective activity against rusts, powdery mildews, and leaf spot complexes in broadacre and specialty crops. Among formulation types, emulsifiable concentrate and liquid suspension dominate volume due to superior tank-mix compatibility and ease of aerial application. The agriculture application segment absorbs the majority of fungicide-class tebuconazole, while horticulture and turf represent higher-margin niches where residue sensitivity commands premium pricing.
EPA tolerance settings and EU MRL harmonization under EFSA guidance shape product registration timelines and residue management protocols for export-oriented growers. Brazil's ANVISA and China's MEE enforce divergent environmental fate standards that fragment formulation requirements across destination markets. REACH compliance in Europe and evolving F-Gas Regulation analogs for pesticide co-formulants add compliance layers for importers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation investments and label expansion opportunities.
Market Dynamics
The EU's Farm to Fork Strategy is compressing maximum residue limits for triazole fungicides while accelerating biological alternative registrations, forcing reformulation investments across export-oriented supply chains.
Growth Catalysts
- Asian soybean rust pressure:Brazil's Mato Grosso and Paraná states sustain heavy tebuconazole application rates in preventive spray programs. Growers prioritize curative efficacy over input cost.
- REACH compliance integration:ECHA substance evaluation timelines are streamlining data dossier preparation for active ingredient renewals. Early movers secure label continuity.
- Micro-encapsulation advances:Proprietary formulation technology extends field persistence and reduces application frequency. Aerial applicators favor liquid suspension compatibility.
Market Restraints
- Feedstock volatility:Propylene and chlorine derivative costs fluctuate with petrochemical pricing, squeezing technical-grade production margins in China's manufacturing corridor.
- Residue limit divergence:Brazil's ANVISA and China's MEE enforce incompatible environmental fate standards, fragmenting formulation specifications across destination markets.
- Biological substitution:Bacillus-based and extract-derived fungicides are capturing specialty crop segments where residue sensitivity commands premium positioning.
Strategic Opportunities
- Seed treatment pivot:Systemic tebuconazole coatings on cereal and oilseed germplasm address early-season soil-borne pressure. Equipment manufacturers are retrofitting treater lines.
- EU Green Deal alignment:Precision application technologies qualify for CAP eco-scheme payments. Variable-rate nozzles reduce off-target drift and input waste.
- Turf and amenity expansion:Golf course superintendents in the US and Australia specify tebuconazole for dollar spot complexes. This segment tolerates higher price points than broadacre agriculture.
Industry Challenges
- Regulatory data generation:EFSA residue metabolism studies and ecotoxicology endpoints require 18-24 month lead times. Smaller blenders lack in-house toxicology capacity.
- Tank-mix compatibility testing:Co-formulant interactions with biologicals and micronutrients demand field validation. Extension services are backlogged with combination requests.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tebuconazole Market |
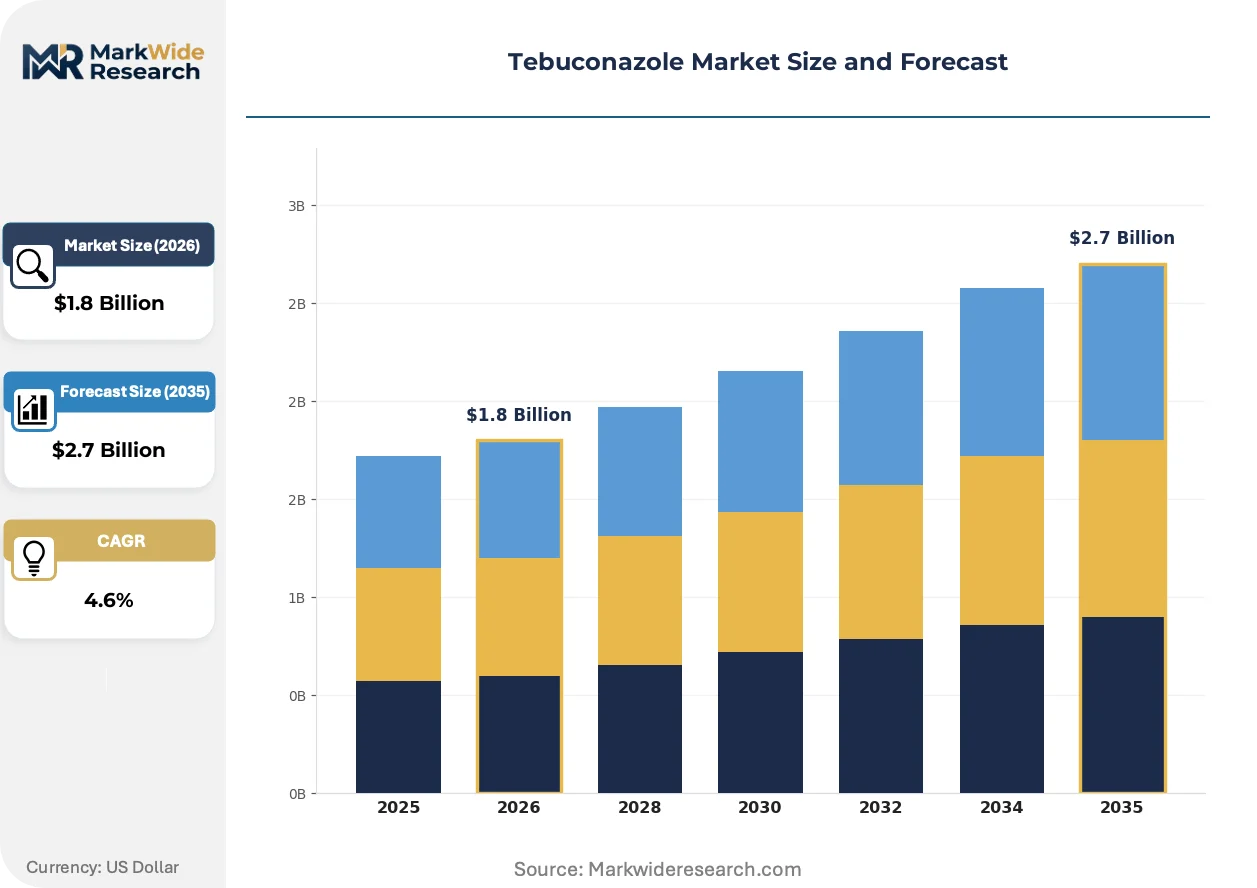
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fungicide, Herbicide, Insecticide, Biopesticide Application: Agriculture, Horticulture, Turf, Ornamentals Formulation: Granules, Liquid, Powder, Emulsifiable Concentrate Distribution Channel: Online Retail, Direct Sales, Distributors, Agricultural Cooperatives |
| Companies Covered | Bayer CropScience, DuPont Crop Protection, Shandong Weifang Rainbow Chemical Co. Ltd., Shanghai Shengnong Pesticide Co. Ltd., Sumitomo Chemical Corporation, Huntsman Corporation, P & G Chemicals, Henkel AG & Co. KGaA, Jiangsu Sword Agrochemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tebuconazole Market Emerging Trajectories
Digital agriculture platforms are reshaping how fungicide prescriptions are generated, validated, and executed across heterogeneous field conditions. Three forces are reconfiguring competitive positioning.
Variable-rate application technology is digitizing spray decision workflows. Agronomists in Brazil and the US Corn Belt integrate satellite-derived disease pressure maps with soil moisture data to trigger site-specific tebuconazole applications. This compression of blanket spraying into targeted interventions reduces volume throughput per hectare while preserving efficacy outcomes.
EFSA guidance on endocrine disruption criteria is extending active substance review timelines for triazoles. The industrial consequence is deferred re-registration certainty for legacy formulations. Cereal protection programs in Germany and France are diversifying tank-mix portfolios to reduce single-AI dependency ahead of potential restrictions.
Direct procurement between large growers and technical-grade suppliers is disintermediating traditional distribution channels. Mato Grosso soybean producers negotiate active ingredient volumes through cooperatives with import licenses. This channel shift compresses distributor margins while rewarding logistics efficiency and credit flexibility in Brazilian interior states.
Tebuconazole Market Segmentation
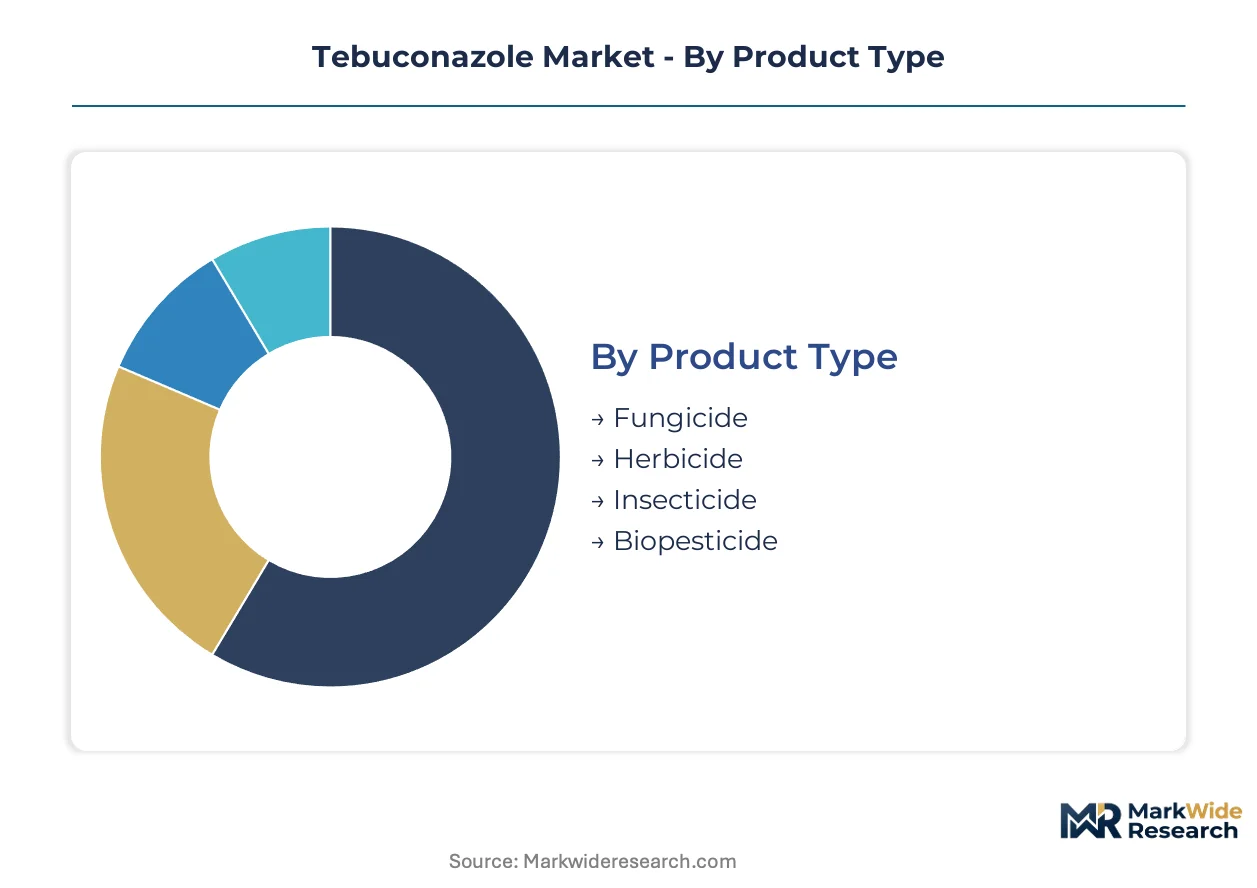
Tebuconazole's systemic action against ergosterol biosynthesis creates distinct demand profiles across crop protection categories. Formulation chemistry and channel economics fragment purchasing behavior in ways that reward targeted portfolio construction.
Product Type:
Fungicide-class tebuconazole anchors curative and preventive spray programs, while co-formulated products extend its utility into adjacent protection categories.
- Fungicide:Pure tebuconazole formulations deliver systemic control of rusts, powdery mildews, and leaf spot complexes in cereals and soybeans. Brazil's Mato Grosso growers prioritize this segment for Asian soybean rust management despite input cost pressures.
- Herbicide:Tank-mix compatibility with glyphosate and glufosinate formulations expands tebuconazole's presence in burndown and early post-emergence programs. Demand concentrates in North American no-till systems where weed-fungicide combination sprays reduce field passes.
- Insecticide:Co-formulation with pyrethroids and neonicotinoids addresses multi-pest pressure in seed treatment and foliar applications. The segment serves cotton and corn belt operators seeking simplified protection protocols.
- Biopesticide:Hybrid formulations combining tebuconazole with Bacillus subtilis or Trichoderma extracts target specialty crop segments where residue limits are tightening fastest.
The dominant share belongs to Fungicide, while Biopesticide is closing the gap fastest.
Application:
Volume scale diverges sharply from margin structure across end-use environments, with broadacre agriculture absorbing tonnage while specialty segments capture price premiums.
- Agriculture:Cereal and oilseed protection programs in Germany, France, and Brazil account for the majority of tebuconazole volume. EPA tolerance settings and EU MRL harmonization under EFSA guidance shape residue management protocols for export-oriented growers.
- Horticulture:High-value fruit and vegetable operations in Spain's Almería and California's Central Valley specify tebuconazole for powdery mildew complexes. Residue sensitivity commands premium pricing above broadacre benchmarks.
- Turf:Golf course superintendents in the US and Australia deploy tebuconazole against dollar spot and brown patch. This segment tolerates three-tier pricing stratification across premium, standard, and economy fungicide tiers.
- Ornamentals:Nursery and greenhouse operations in the Netherlands and Florida utilize tebuconazole for foliar disease prevention in container production. Regulatory data requirements for minor uses limit formulation diversity.
Agriculture retains volume leadership, though Turf delivers superior unit economics per hectare treated.
Formulation:
Physical form determines application method compatibility, storage stability, and co-formulant flexibility across destination markets.
- Liquid:Suspension concentrates and soluble liquids dominate aerial application in Brazil and the US Corn Belt. Tank-mix compatibility with micronutrients and biologicals drives agronomist preference.
- Emulsifiable Concentrate:Oil-based formulations extend field persistence through rainfastness and cuticular penetration. ECHA substance evaluation timelines for co-formulants are extending registration lead times for legacy EC products.
- Granules:Controlled-release granules serve soil-incorporation and seed-treatment applications where early-season protection against soil-borne pathogens is critical. Equipment manufacturers retrofit treater lines for precision dosing.
- Powder:Wettable powders retain niche demand in manual spray programs across Southeast Asian smallholder systems. Dust exposure concerns are accelerating conversion to liquid alternatives.
Liquid formulations command the installed base, while Granules are expanding most quickly through seed treatment adoption.
Distribution Channel:
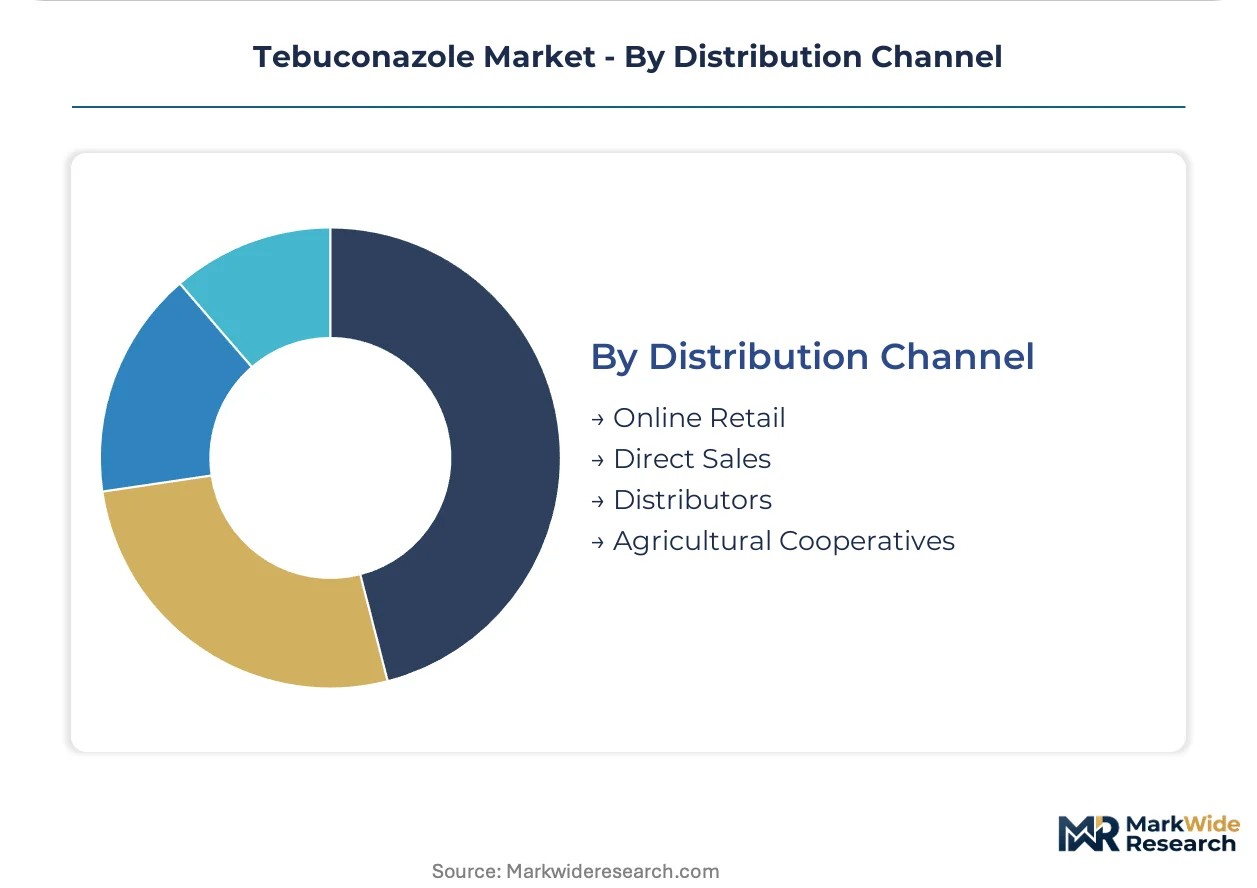
Channel structure reflects credit requirements, technical support intensity, and import licensing complexity across grower segments.
- Distributors:Regional agrochemical distributors maintain inventory depth and extension service networks across Brazil's interior states and the US Midwest. Logistics efficiency and credit flexibility determine competitive position.
- Agricultural Cooperatives:Mato Grosso soybean producers negotiate active ingredient volumes through cooperatives holding direct import licenses. This procurement pattern compresses traditional distributor margins while rewarding scale aggregation.
- Direct Sales:Large integrated growers in Australia's wheat belt and Argentina's Pampas source technical-grade material directly from Chinese manufacturers. REACH compliance integration and data dossier preparation separate qualified buyers.
- Online Retail:E-commerce platforms capture hobbyist and smallholder demand in India and Southeast Asia. Regulatory fragmentation across state-level pesticide sales permits constrains cross-border fulfillment.
Distributors retain structural share leadership, though Agricultural Cooperatives are gaining share fastest through import license aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's residue protocols anchor Brazil's dominant position in tebuconazole consumption. EPA tolerance settings and EFSA MRL harmonization shape registration timelines across export-oriented supply chains. China's MEE environmental fate standards fragment formulation requirements for technical-grade manufacturers.
Brazil
Asian soybean rust pressure in Mato Grosso and Paraná sustains heavy application rates in preventive spray programs. ANVISA enforces divergent environmental fate standards that complicate export compliance for co-formulated products. The Mato Grosso soybean belt concentrates procurement through cooperatives holding direct import licenses.
United States
Cereal protection programs in the Corn Belt and wheat belt absorb substantial tebuconazole volumes for rust and powdery mildew management. EPA tolerance settings determine residue management protocols for export-oriented growers. Variable-rate application technology adoption concentrates in Iowa and Illinois, digitizing spray decision workflows.
Germany
Cereal farmers in Bavaria and North Rhine-Westphalia deploy tebuconazole within diversified tank-mix portfolios. EFSA guidance on endocrine disruption criteria extends active substance review timelines for triazoles. The Rhine-Ruhr industrial corridor hosts formulation facilities serving domestic and export markets.
China
Agrochemical manufacturing corridors in Jiangsu and Shandong provinces dominate technical-grade tebuconazole output. MEE environmental fate standards enforce divergent formulation specifications from Brazil and EU requirements. The Yangtze River Delta concentrates active ingredient production for Southeast Asian blenders.
Australia
Wheat belt operators in New South Wales and Victoria source technical-grade material directly from Chinese manufacturers. TGA and APVMA residue protocols align with export market requirements for grain shipments. Golf course superintendents in metropolitan Sydney and Melbourne specify tebuconazole for turf disease complexes.
Tebuconazole Market Vendor Landscape
Integrated multinationals and specialized agrochemical manufacturers split the market along capability and scale vectors. Patent-protected formulation technology separates premium-positioned suppliers from commodity-grade blenders. Two archetypes dominate: diversified crop science conglomerates with captive active ingredient production, and regional technical-grade specialists serving formulation houses. Capacity consolidation in China's manufacturing corridor and proprietary micro-encapsulation advances represent the dominant competitive moves.
Among integrated crop science conglomerates, Bayer CropScience and Sumitomo Chemical Corporation exemplify archetypes combining proprietary formulation technology with label continuity investments. Jiangsu Sword Agrochemicals occupies a position within China's technical-grade manufacturing tier, supplying active ingredient to blenders across Southeast Asia. Shandong Weifang Rainbow Chemical Co. Ltd. represents the Shandong-based specialist segment focused on volume-scale output.
| Leading Market Players |
|---|
| Bayer CropScience |
| DuPont Crop Protection |
| Shandong Weifang Rainbow Chemical Co. Ltd. |
| Shanghai Shengnong Pesticide Co. Ltd. |
| Sumitomo Chemical Corporation |
| Huntsman Corporation |
| P & G Chemicals |
| Henkel AG & Co. KGaA |
| Jiangsu Sword Agrochemicals |
| Others |
Supply Flow & Price Mechanics
Propylene feedstock volatility in China's Jiangsu manufacturing corridor determines both pricing tier spreads and supply chain shape for tebuconazole technical-grade output. Buyers face divergent landed costs depending on formulation complexity and REACH compliance integration.
Pricing Analysis
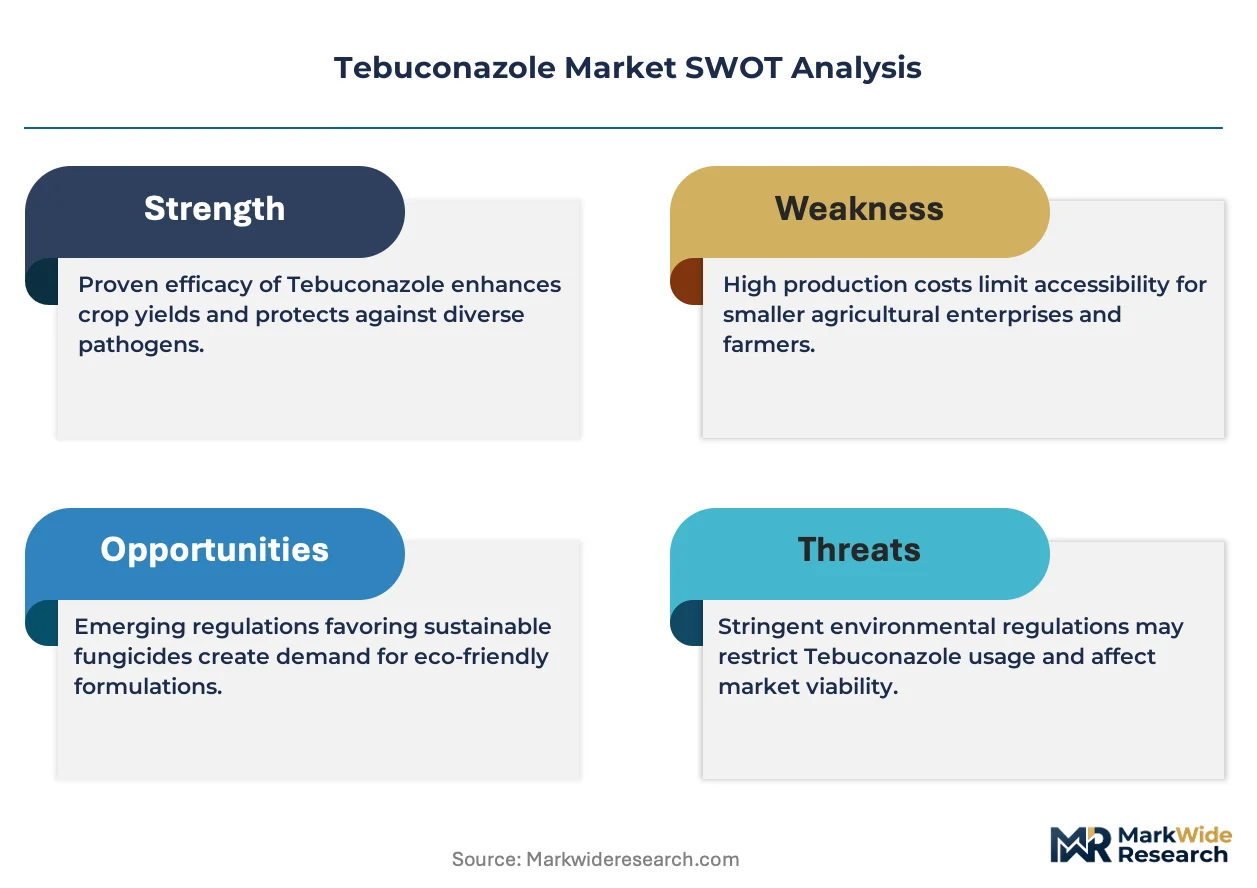
Brazil's Mato Grosso soybean belt commands premium pricing against Southeast Asian smallholder markets. Three-tier pricing structure across premium, standard, and economy levels reflects formulation sophistication, with micro-encapsulated suspensions capturing top-tier margins. Pricing pressure stems from biological substitution in EU specialty crops, compressing fungicide-class premiums. Agricultural cooperatives exhibit highest price sensitivity through direct import license aggregation, while golf course superintendents tolerate elevated unit economics for turf-specific formulations.
Supply Chain Analysis
Jiangsu Sword Agrochemicals and Shandong Weifang Rainbow Chemical anchor contract-manufacturing concentration for technical-grade tebuconazole. Supply concentrates in China, with secondary formulation blending in Germany and Brazil. Raw material dependencies center on propylene derivatives, chlorine intermediates, and triazole ring precursors. Single-source vulnerability runs through Jiangsu province's agrochemical corridor, where environmental compliance inspections disrupt batch continuity. Distribution runs through agricultural cooperatives in Brazil, regional distributors in the US Corn Belt, and direct procurement by Australian wheat belt operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tebuconazole market fragmentation creates entry niches as regulatory divergence between ANVISA, EPA, and EFSA multiplies formulation specifications. Biological substitution pressure and residue limit compression reward specialized compliance capabilities.
For Market Incumbents: Harden formulation portfolios against EFSA endocrine disruption reviews by diversifying tank-mix combinations and accelerating proprietary micro-encapsulation patents. Secure backward integration into propylene derivative supply to defend margin position against feedstock volatility. Prioritize seed treatment line retrofits to capture early-season application volume before foliar spray compression intensifies. For New Entrants and Emerging Players: Establish a beachhead in turf and amenity segments where dollar spot management commands three-tier pricing tolerance and regulatory scrutiny remains lighter than broadacre agriculture. Target Australian golf course superintendents through direct technical-grade procurement partnerships bypassing distributor markup. Lead with liquid suspension formulations optimized for aerial applicator compatibility and micronutrient tank-mix flexibility. For Investors and Strategic Acquirers: Regional formulation specialists with captive ANVISA registration expertise represent priority acquisition targets as Brazil's soybean belt procurement consolidates through cooperative import licenses. Long-term viability hinges on navigating biological substitution trajectories in EU cereal protection while maintaining Asian soybean rust efficacy positioning. Monitor ECHA substance evaluation timelines for triazole renewals as inflection indicator for portfolio reallocation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Derivatives | Captive supply of chlorine intermediates insulates margin compression from petrochemical volatility in Jiangsu corridor. |
| Micro-Encapsulation Patent Expansion | Extended field persistence technology differentiates premium formulations against generic suspension concentrates in Brazil. |
| Seed Treatment Equipment Partnership | Treater line retrofits by equipment manufacturers secure early-season volume ahead of foliar spray seasonality. |
| ANVISA Registration Dossier Acquisition | Label continuity in Mato Grosso soybean belt accelerates market access versus de novo regulatory submission timelines. |
| Precision Application Technology Integration | Variable-rate nozzle compatibility qualifies Brazilian growers for CAP eco-scheme payments under EU Green Deal alignment. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cereal protection agronomists, seed treatment equipment manufacturers, agrochemical procurement leads at Brazilian agricultural cooperatives, and formulation R&D directors at technical-grade suppliers. Secondary validation drew from ANVISA registration databases, EFSA residue metabolism study disclosures, customs trade flows for triazole fungicide categories, and SEC filings of integrated crop science conglomerates. Bottom-up volume estimates from application rate assumptions triangulated against top-down value projections from pricing tier analysis.
Calibration anchored volume and value outputs across the analysis window to observed procurement patterns in Mato Grosso and the US Corn Belt. Segmentation dimensions modeled include formulation chemistry, crop application, distribution channel structure, and regional regulatory cluster. CAGRs were derived from cohort-level growth rate aggregation across these segments. Forecast inputs incorporated Asian soybean rust pressure indices, propylene derivative cost trajectories, and ECHA renewal timeline probabilities.
Stress conditions across feedstock volatility bands, regulatory restriction scenarios, and biological substitution penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding label continuity and residue limit trajectories. Quarterly review of EFSA substance evaluation progress, ANVISA environmental fate standard revisions, and Brazilian cooperative import license expansions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Agricultural Pheromones Market
Crop Protection
Asia Pacific Insecticide Market
Crop Protection
Global Turf Protection Market
Crop Protection
North America Acaricides Market
Crop Protection
Fumigation Market
Crop Protection
United States Crop Protection Chemicals Market
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
Synthetic Pesticide Market
Crop Protection
Europe Herbicide Market
Crop Protection
United Kingdom Crop Protection Chemicals Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
Tebufenozide Market
Crop Protection
Global Integrated Pest Management (IPM) Pheromones Market
Crop Protection
Seed Treatment Materials Market
Crop Protection
North America Insecticide Market
Crop Protection
Trapping and Mating Disruption Systems Market