
 Tebuconazole Epoxide Market | 2026-2036
Tebuconazole Epoxide Market Size, Share, and Industry Trends Forecast 2026-2036
Tebuconazole Epoxide Market Insights
Technical grade specifications is bifurcating the competitive landscape into premium purity suppliers and cost-optimized blenders. BASF leverages its integrated azole synthesis network to sustain feedstock cost advantages across European and Asian manufacturing nodes. Bayer anchors its position through proprietary formulation chemistry that extends residual efficacy in high-rainfall tropical zones. Syngenta differentiates by controlling distribution depth in Latin American soybean belts.
Tebuconazole epoxide functions as a triazole fungicide metabolite and synthetic precursor characterized by epoxidation of the tertiary butyl side chain, serving primarily as an active ingredient and quality marker in systemic crop protection formulations against ascomycete and basidiomycete pathogens. Formulated concentrate output leads value generation due to downstream blending flexibility and longer shelf stability under tropical storage conditions. Emulsifiable concentrate demand is accelerating in plantation crop segments where oil palm and banana growers prioritize spray penetration and cuticle adhesion. Wettable powder retains share in cereal crop applications across price-sensitive procurement channels where water dispersibility governs farmer adoption.
EPA registration requirements under FIFRA govern import tolerances and residue limits for tebuconazole derivatives entering United States food channels, while REACH Annex XVII restrictions in Europe constrain impurity profiles in azole active substances shipped to EU formulation plants. India's Central Insecticides Board mandates dual registration for technical and formulated products, creating compliance layering that favors established manufacturers with dedicated regulatory affairs capacity. Stakeholders must monitor evolving maximum residue limits in Codex Alimentarius negotiations, as harmonized standards will reshape competitive access into Middle Eastern and Southeast Asian import markets.
Market Dynamics
REACH Annex XVII impurity restrictions and EPA FIFRA residue limits are compressing the supplier base for tebuconazole epoxide technical grades, forcing smaller blenders toward toll manufacturing arrangements or exit.
Growth Catalysts
- Asia-Pacific cereal protection:State agricultural extension programs in India are expanding fungicide procurement volumes for wheat and rice cultivation belts.
- REACH compliance tiering:Premium purity specifications under ECHA guidelines are creating supplier differentiation that rewards integrated azole manufacturers with captive synthesis capabilities.
- Emulsifiable concentrate formulation:Plantation crop growers in tropical zones are prioritizing spray penetration chemistry that extends residual efficacy in high-rainfall conditions.
Market Restraints
- Feedstock cost volatility:Tertiary butyl side chain precursors face pricing pressure from petroleum-derived intermediate markets.
- Regulatory friction:India's Central Insecticides Board dual registration mandates create compliance layering that disadvantages manufacturers without dedicated regulatory affairs capacity.
- Substitution threat:Strobilurin fungicide classes compete for soybean and oil palm protection contracts in Latin American procurement channels.
Strategic Opportunities
- Underpenetrated geography:Southeast Asian banana cultivation belts present volume expansion potential for wettable powder formulations optimized for smallholder water dispersibility requirements.
- Regulatory tailwind:Codex Alimentarius harmonization negotiations on maximum residue limits will reshape competitive access into Middle Eastern import markets for compliant suppliers.
- Channel innovation:Direct-to-cooperative distribution models in Indian state procurement systems are bypassing traditional agrochemical distributor markups.
Industry Challenges
- Analytical chemistry skill gap:Epoxide purity verification and metabolite quantification require specialized chromatography expertise that contract laboratories struggle to staff.
- Capex intensity:Dedicated azole synthesis facilities with integrated epoxidation capacity demand significant capital commitment for REACH-compliant impurity control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tebuconazole Epoxide Market |
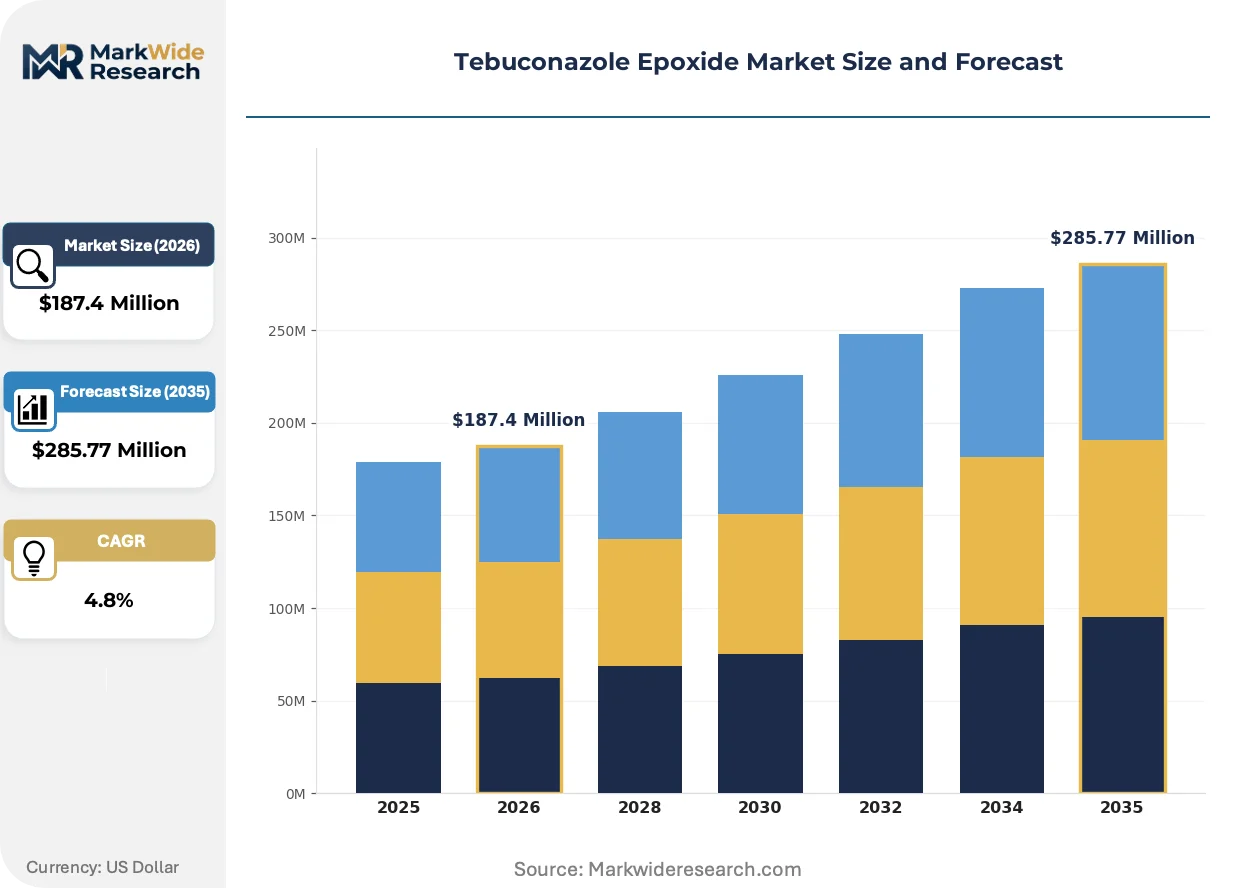
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Formulated Concentrate, Wettable Powder, Emulsifiable Concentrate, Granules Application: Cereal Crops, Oilseed Crops, Horticulture, Turf Management, Plantation Crops End User: Agrochemical Manufacturers, Crop Protection Services, Agricultural Cooperatives, Independent Farmers Packaging Type: Plastic Bottles, Metal Drums, Fiber Drums, Bulk Containers, Sachets |
| Companies Covered | BASF, Bayer, Syngenta, United Phosphorus, Gharda Chemicals, Rallis India, Jiangsu Sevencontinent Green Chemical, Shanghai Shengnong Pesticide, Jiangsu Sword Agrochemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tebuconazole Epoxide Market Trends and Innovations
Formulation chemistry and regulatory compliance systems are the primary vectors of change, with manufacturers investing in stability-under-storage capabilities and residue analytics to maintain access to tightening import channels.
Microencapsulation technology for tebuconazole epoxide is displacing conventional emulsifiable concentrate formats in high-humidity storage environments. Plantation crop operators in Malaysian oil palm belts are adopting these formats to reduce active ingredient degradation during monsoon season inventory cycles. This shift is compressing shelf-life risk premiums previously captured by regional formulators with superior cold-chain logistics.
REACH Annex XVII restrictions on azole impurity profiles are tightening specification windows for technical grade shipments entering EU formulation plants. ECHA guidance documents on persistent, bioaccumulative, and toxic substance thresholds are forcing suppliers to invest in crystallization purification upgrades. Wettable powder manufacturers serving cereal crop channels face the steepest compliance cost escalation.
State-level tender consolidation in Indian agricultural procurement is compressing supplier fragmentation that historically characterized fungicide purchasing. Wheat and rice cultivation extension programs are aggregating volume through centralized state agricultural departments, replacing district-level procurement autonomy. This concentration is visible most acutely in Maharashtra and Punjab input distribution systems.
Tebuconazole Epoxide Market Segmentation
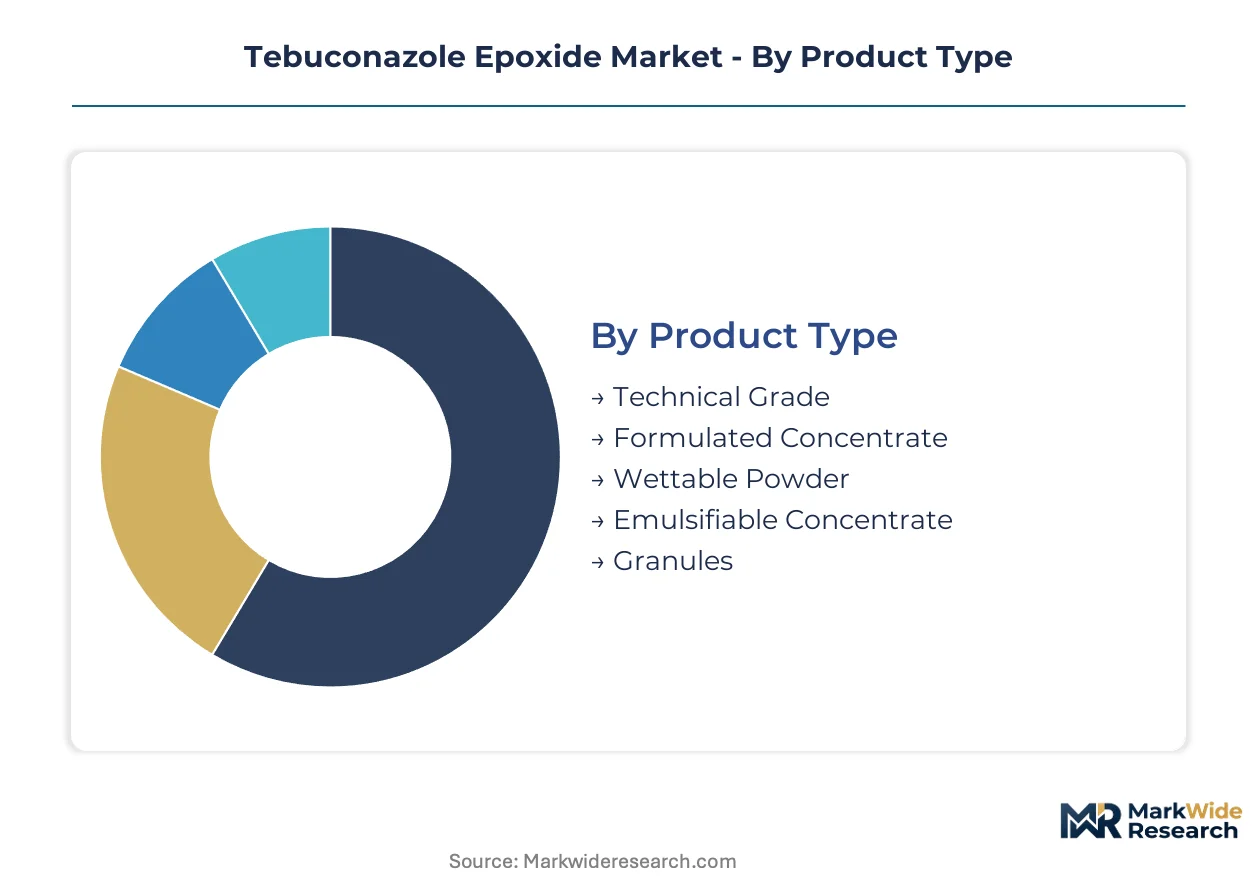
Segmentation in tebuconazole epoxide markets reveals where value capture concentrates across purity tiers and formulation chemistry. Margin pools shift dramatically based on regulatory compliance burdens and downstream blending economics.
Product Type:
Margin concentration tracks regulatory burden intensity, with purity verification costs creating tiered profitability across manufacturing modes.
- Technical Grade:Active ingredient concentrates at 95% purity or higher serve as feedstock for downstream formulation. Integrated azole manufacturers with captive epoxidation capacity capture margin premiums in European REACH-compliant channels where impurity thresholds tighten specification windows.
- Formulated Concentrate:Pre-blended active ingredient matrices offer downstream flexibility and extended tropical shelf stability. Demand clusters in Indian state procurement systems where agricultural extension programs aggregate volume for wheat and rice protection.
- Wettable Powder:Solid dispersible formulations optimize water compatibility for smallholder spraying equipment. Price-sensitive cereal crop channels in Asia-Pacific farming belts favor this format for procurement efficiency.
- Emulsifiable Concentrate:Oil-based liquid formulations enhance cuticle adhesion in high-rainfall plantation zones. Malaysian oil palm and Indonesian banana growers prioritize spray penetration chemistry.
- Granules:Slow-release solid matrices reduce application frequency in labor-constrained agricultural systems. Turf management and large-scale cereal operations adopt this format for mechanized spreading compatibility.
The dominant share belongs to Formulated Concentrate, while Emulsifiable Concentrate is closing the gap fastest.
Application:
Volume distribution follows crop value density and disease pressure intensity across climatic zones.
- Cereal Crops:Wheat and rice protection drives systemic fungicide deployment against Fusarium and rust pathogens. Indian state-level tender consolidation in Maharashtra and Punjab procurement systems is compressing supplier fragmentation.
- Oilseed Crops:Soybean and rapeseed applications combat Sclerotinia and Phakopsora infections. Latin American procurement channels face substitution pressure from strobilurin fungicide classes competing for grower contracts.
- Horticulture:Fruit and vegetable cultivation requires precise residue management for export compliance. Codex Alimentarius maximum residue limit negotiations reshape competitive access into Middle Eastern import markets.
- Turf Management:Golf course and sports field maintenance demands aesthetic performance without phytotoxicity. North American and European amenity grass sectors specify low-odor formulation variants.
- Plantation Crops:Oil palm and banana monocultures in Southeast Asian belts prioritize residual efficacy through monsoon seasons. Microencapsulation formats are displacing conventional concentrates in Malaysian inventory cycles.
Cereal Crops commands the largest volume position, with Plantation Crops expanding most quickly on tropical acreage intensification.
End User:
Procurement authority concentration determines pricing power and formulation specification influence.
- Agrochemical Manufacturers:Integrated formulation companies source technical grade for proprietary blend development. REACH Annex XVII compliance capabilities differentiate supplier relationships.
- Crop Protection Services:Commercial application contractors demand ready-to-use formats with logistics efficiency. Equipment compatibility governs formulation selection in contracted spraying operations.
- Agricultural Cooperatives:Aggregated smallholder purchasing in Indian state systems bypasses traditional distributor markups. Direct-to-cooperative distribution models are restructuring channel economics.
- Independent Farmers:Fragmented retail procurement favors small-pack wettable powder and sachet formats. Water dispersibility and price-per-hectare metrics dominate adoption decisions.
Agrochemical Manufacturers retain the deepest value chain penetration, though Agricultural Cooperatives are gaining procurement leverage fastest.
Packaging Type:
Logistics cost structures and storage condition requirements shape format selection across distribution tiers.
- Plastic Bottles:Standard retail containers for emulsifiable concentrate and liquid formulations. Corrosion resistance and handling ergonomics suit independent farmer channels.
- Metal Drums:Industrial-scale containment for technical grade and formulated concentrate shipments. UN-certified specifications govern cross-border transport compliance.
- Fiber Drums:Lightweight solid formulation packaging for wettable powder and granule products. Moisture barrier properties protect hygroscopic active ingredients.
- Bulk Containers:Intermediate bulk formats reduce per-unit logistics costs for cooperative and manufacturer direct procurement. Returnable container systems penetrate closed-loop supply chains.
- Sachets:Single-use water-soluble packets eliminate measuring error for smallholder applicators. Southeast Asian banana cultivation belts show expanding uptake for precision dosing.
Metal Drums holds the dominant procurement share, while Sachets is climbing the fastest on smallholder format innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in tebuconazole epoxide track regulatory compliance costs, with surplus technical grade capacity in Asian manufacturing nodes supplying formulation demand in regulated Western markets.
India
State agricultural extension programs in Maharashtra and Punjab are aggregating fungicide procurement volumes for wheat and rice protection. The Central Insecticides Board mandates dual registration for technical and formulated products, creating compliance layering that favors established manufacturers. Gharda Chemicals and Rallis India anchor domestic production clusters in Mumbai and Hyderabad.
United States
EPA FIFRA registration requirements govern import tolerances and residue limits for tebuconazole derivatives entering food channels. Plantation crop protection in Florida and Gulf Coast states drives emulsifiable concentrate uptake for high-rainfall disease management. BASF leverages integrated azole synthesis networks to sustain feedstock cost advantages across American formulation plants.
Germany
REACH Annex XVII restrictions under ECHA guidelines constrain impurity profiles in azole active substances shipped to EU formulation plants. Bavarian and North Rhine-Westphalia chemical clusters host precision purification facilities serving premium technical grade specifications. Bayer anchors proprietary formulation chemistry development from Leverkusen headquarters.
China
Jiangsu and Zhejiang provinces concentrate epoxidation capacity for azole fungicide intermediates serving Asian and Latin American export markets. Jiangsu Sevencontinent Green Chemical and Jiangsu Sword Agrochemicals occupy positions in the technical grade supplier tier. Shanghai Shengnong Pesticide exemplifies coastal formulation specialists targeting plantation crop channels.
Brazil
Soybean and oil palm protection contracts in Mato Grosso and Pará states face substitution pressure from strobilurin fungicide classes competing for grower procurement. Syngenta controls distribution depth in Latin American soybean belts through regional formulation partnerships. Anvisa registration pathways govern import compliance for technical grade active ingredients.
Tebuconazole Epoxide Market Competitive Landscape
Concentration sits with integrated azole manufacturers possessing captive epoxidation capacity and dedicated regulatory affairs infrastructure. The supplier base compresses into three archetypes: premium purity specialists serving REACH-compliant EU channels, cost-optimized blenders supplying price-sensitive Asian procurement systems, and plantation-focused formulators optimizing for tropical storage stability. Dominant competitive moves include crystallization purification upgrades for impurity control and direct-to-cooperative distribution models bypassing traditional agrochemical distributor markups.
Among German and Swiss-based integrated chemical conglomerates, BASF and Bayer exemplify the premium-tier archetype through upstream control over azole synthesis networks. Syngenta anchors the plantation-specialist position in Latin American soybean belts. Chinese technical grade suppliers including Jiangsu Sevencontinent Green Chemical and Jiangsu Sword Agrochemicals occupy the cost-optimized manufacturing tier, while Indian formulators Gharda Chemicals and Rallis India represent emerging regulatory-compliance capacity in state procurement systems.
| Leading Market Players |
|---|
| BASF |
| Bayer |
| Syngenta |
| United Phosphorus |
| Gharda Chemicals |
| Rallis India |
| Jiangsu Sevencontinent Green Chemical |
| Shanghai Shengnong Pesticide |
| Jiangsu Sword Agrochemicals |
| Others |
Pricing and Supply Chain Analysis
REACH Annex XVII impurity restrictions gate both supplier qualification and price differentiation simultaneously, compressing the technical grade supply base into premium purity specialists and cost-optimized blenders while amplifying margin dispersion across European and Asian procurement channels.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in tebuconazole epoxide markets. Price differentiation rests on purity verification costs and REACH certification tiers, with integrated azole manufacturers commanding premiums in EU-compliant channels. Cost compression in the wettable powder segment is intensifying because Indian state procurement systems aggregate volume through centralized tenders. Smallholder retail channels exhibit the highest price sensitivity, while agrochemical manufacturers sourcing technical grade for proprietary formulations demonstrate the lowest.
Supply Chain Analysis
Inventory cycles in Malaysian oil palm belts extend lead times for microencapsulated formats during monsoon seasons, forcing buyers to pre-position stock ahead of disease pressure windows. Supply concentrates in China, India, and Germany, with Jiangsu and Zhejiang provinces hosting epoxidation capacity, Maharashtra and Punjab anchoring formulation demand, and Bavarian chemical clusters serving purification upgrades. Feedstock dependencies center on tertiary butyl side chain precursors and petroleum-derived intermediates. Single-source vulnerability from concentrated azole synthesis capacity in Asian manufacturing nodes poses structural risk. Distribution runs through direct-to-cooperative models in Indian state systems alongside traditional agrochemical distributor networks in Latin American soybean belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority is shifting toward agricultural cooperatives and state-level tender consolidation in India, compressing supplier fragmentation that historically characterized fungicide purchasing and amplifying buyer leverage in price negotiations.
For Market Incumbents: Consolidate regulatory affairs capacity to defend against REACH Annex XVII compliance cost escalation and Central Insecticides Board dual registration mandates that disadvantage smaller blenders. Backward integration into captive epoxidation capacity secures feedstock cost advantages as petroleum-derived intermediate markets face volatility. Channel control through direct-to-cooperative distribution models bypasses traditional agrochemical distributor markups in Maharashtra and Punjab procurement systems.
For New Entrants and Emerging Players: Anchor in Southeast Asian banana cultivation belts where wettable powder formulations optimized for smallholder water dispersibility requirements remain underpenetrated. Target plantation crop segments in Malaysian oil palm and Indonesian banana monocultures where microencapsulation technology displaces conventional concentrates. Pursue toll manufacturing arrangements with established technical grade suppliers to circumvent Capex intensity of dedicated azole synthesis facilities.
For Investors and Strategic Acquirers: Codex Alimentarius harmonization negotiations on maximum residue limits reshape the acquisition landscape by privileging compliant suppliers with analytical chemistry expertise for epoxide purity verification. Long-term viability centers on integrated manufacturers with crystallization purification upgrades and dedicated regulatory affairs infrastructure. Watch for consolidation signals in Indian state procurement systems as tender aggregation accelerates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Azole Synthesis | Captive epoxidation capacity insulates BASF and Bayer from petroleum-derived intermediate price volatility. |
| Crystallization Purification Upgrade | REACH Annex XVII compliance investments enable premium technical grade access to EU formulation plants. |
| Direct-to-Cooperative Distribution | Maharashtra and Punjab state procurement systems bypass traditional agrochemical distributor markups. |
| Microencapsulation Format Development | Malaysian oil palm operators reduce active ingredient degradation during monsoon inventory cycles. |
| Regulatory Affairs Capacity Expansion | Central Insecticides Board dual registration mandates favor established manufacturers with dedicated compliance teams. |
Research Methodology
A spread of perspectives from agrochemical procurement managers, plant managers at azole synthesis facilities, regulatory affairs leads, and distribution channel partners converged on the working assumptions underlying this analysis. Primary interview insights combined with secondary validation from customs and trade data, SEC filings of listed chemical conglomerates, and ECHA guidance documents on persistent, bioaccumulative, and toxic substance thresholds. Bottom-up volume modeling across formulation chemistry tiers triangulated against top-down market sizing from production capacity disclosures.
Segmentation dimensions modeled include product type tier, application crop category, end-user procurement authority, and packaging format logistics economics across the analysis window. CAGRs were derived from trend extrapolation of historical volume uptake patterns and forward projection of regulatory compliance cost trajectories. Forecast inputs incorporated state-level tender consolidation rates in Indian agricultural extension programs and substitution pressure indices from strobilurin fungicide classes in Latin American soybean belts.
Decision-makers should treat outputs as directional under assumptions of stable REACH Annex XVII enforcement intensity and continued Indian state procurement aggregation; material deviation in regulatory timelines or subsidy program funding would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
South America Insecticide Market
Crop Protection
Global Acaricides Market
Crop Protection
Global Phosphine Fumigation Market
Crop Protection
Canada Crop Protection Chemicals Market
Crop Protection
Fogger Market
Crop Protection
IPM Pheromones Market
Crop Protection
Herbicides Market
Crop Protection
Propiconazole Market
Crop Protection
Acetochlor Herbicide Market
Crop Protection
Tebufenozide Market
Crop Protection
Italy Crop Protection Chemicals (Pesticides) Market
Crop Protection
France Crop Protection Chemicals Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Global Acephate Market
Crop Protection
Asia-Pacific Molluscicides Market
Crop Protection
Miticides Market