
 Miticides Market | 2026-2036
Miticides Market Size, Share, and Industry Trends Forecast 2026-2036
Miticides Market Outlook
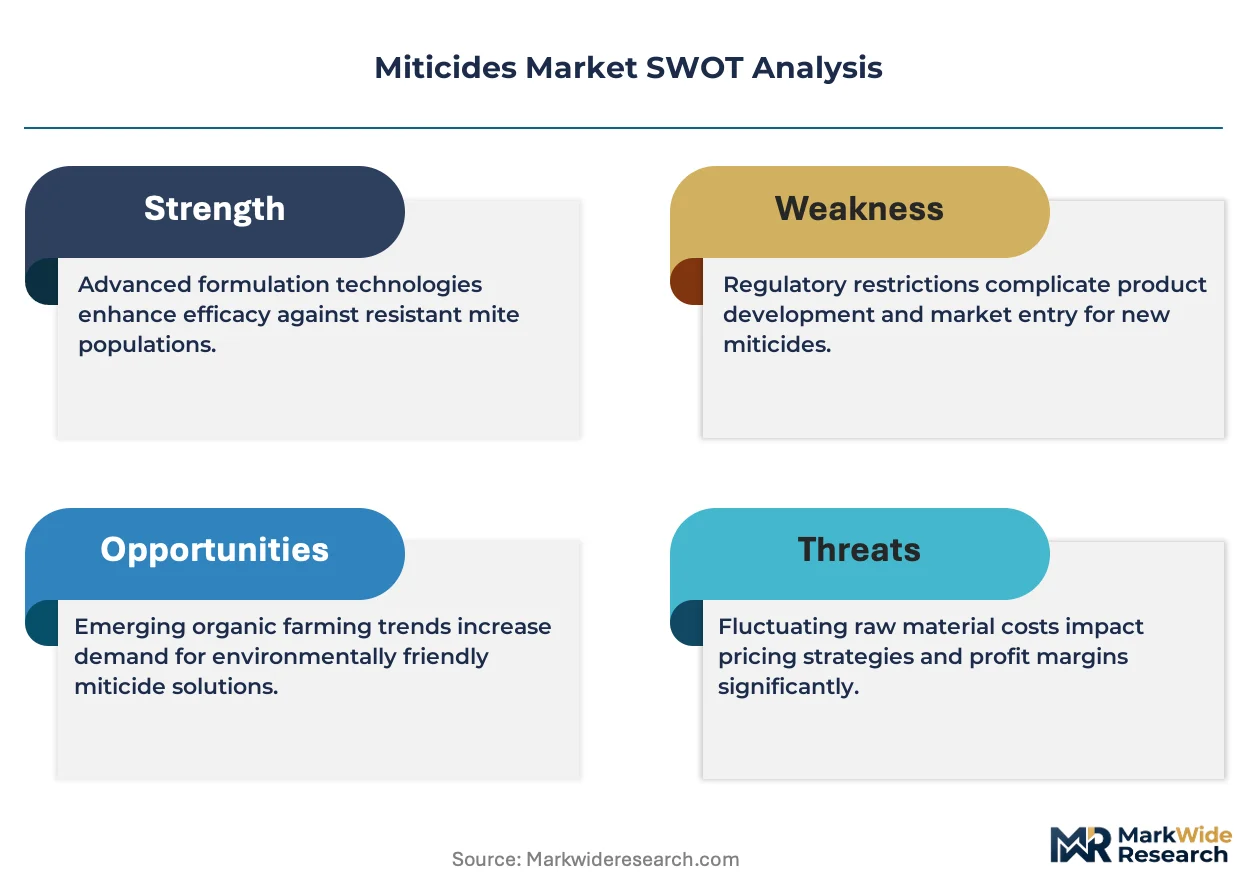
ISO 17025 accreditation for residue testing laboratories is reorganizing supplier qualification across the miticides value chain. BASF SE leverages its backward integration into active ingredient synthesis to sustain cost advantages in emulsifiable concentrate formulations. Syngenta Group anchors its position through proprietary acaricide molecule development, while FMC Corporation differentiates via biological fermentation capabilities.
Miticides are chemical or biological agents formulated specifically to kill mites, typically containing active ingredients such as abamectin, bifenazate, or spinosad at concentrations between 1.5% and 15% w/w, and are manufactured through multi-step synthesis or fermentation processes followed by formulation into sprayable or soil-applied products. These agents serve essential crop protection functions in high-value fruit, vegetable, and ornamental production where spider mites and eriophyid mites cause yield losses exceeding economic thresholds. Synthetic miticides currently occupy the largest value share due to proven efficacy and established distribution infrastructure, though biological types are gaining fastest growth as organic acreage expands and residue limits tighten. Liquid formulations dominate commercial applications for their ease of tank-mixing and uniform coverage, while granular types serve niche horticultural settings requiring root-zone protection.
The EPA regulates miticide registration under FIFRA with mandatory ecological risk assessments, while the EU's REACH framework and MDR requirements govern active substance approval and maximum residue levels in food imports. These regulatory structures elevate R&D barriers, extend product development timelines, and create competitive moats for incumbents with established regulatory dossiers. Stakeholders must monitor evolving resistance management mandates and biocontrol substitution thresholds to align portfolio allocation with shifting compliance requirements.
Market Dynamics
Resistance management protocols in Brazil's soybean belt and California's Central Valley are forcing rotation requirements that expand biological miticide portfolios while compressing synthetic product lifecycles.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory pesticide reduction targets accelerate biological alternative registration timelines across European specialty crop sectors.
- California Central Valley IPM Expansion:Integrated pest management program adoption among stone fruit and nut growers drives tank-mix compatibility testing for novel acaricide combinations.
- Abamectin Resistance Mapping:Molecular diagnostic tools enable precision resistance monitoring that sustains premium pricing for next-generation mode-of-action products.
Market Restraints
- Active Ingredient Supply Concentration:Chinese manufacturers control upstream fermentation capacity for avermectin derivatives, creating input volatility during environmental compliance shutdowns.
- REACH Registration Burden:European active substance renewal processes extend timelines to 48-60 months, freezing portfolio turnover for mid-scale formulators.
- Biological Efficacy Ceiling:Beauveria bassiana and Metarhizium anisopliae formulations fail to match synthetic knockdown speed in high-pressure mite infestations.
Strategic Opportunities
- India Horticulture Belt:Grape and pomegranate export zones near Nashik and Sangli lack ISO 17025-accredited residue testing, creating first-mover advantage for compliant suppliers.
- Drone Application Convergence:Ultralow-volume spraying systems paired with electrostatic nozzles enable foliar coverage in dense canopy structures previously inaccessible to ground rigs.
- USDA Organic Cost-Share:Certification expense reimbursement programs lower switching costs for conventional growers transitioning premium acreage.
Industry Challenges
- Resistance Modeling Expertise Gap:Computational biology talent scarcity delays implementation of predictive rotation algorithms for regional extension services.
- ISO 17025 Accreditation Timelines:Multi-year laboratory qualification processes bottleneck supplier qualification for residue-critical export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Miticides Market |
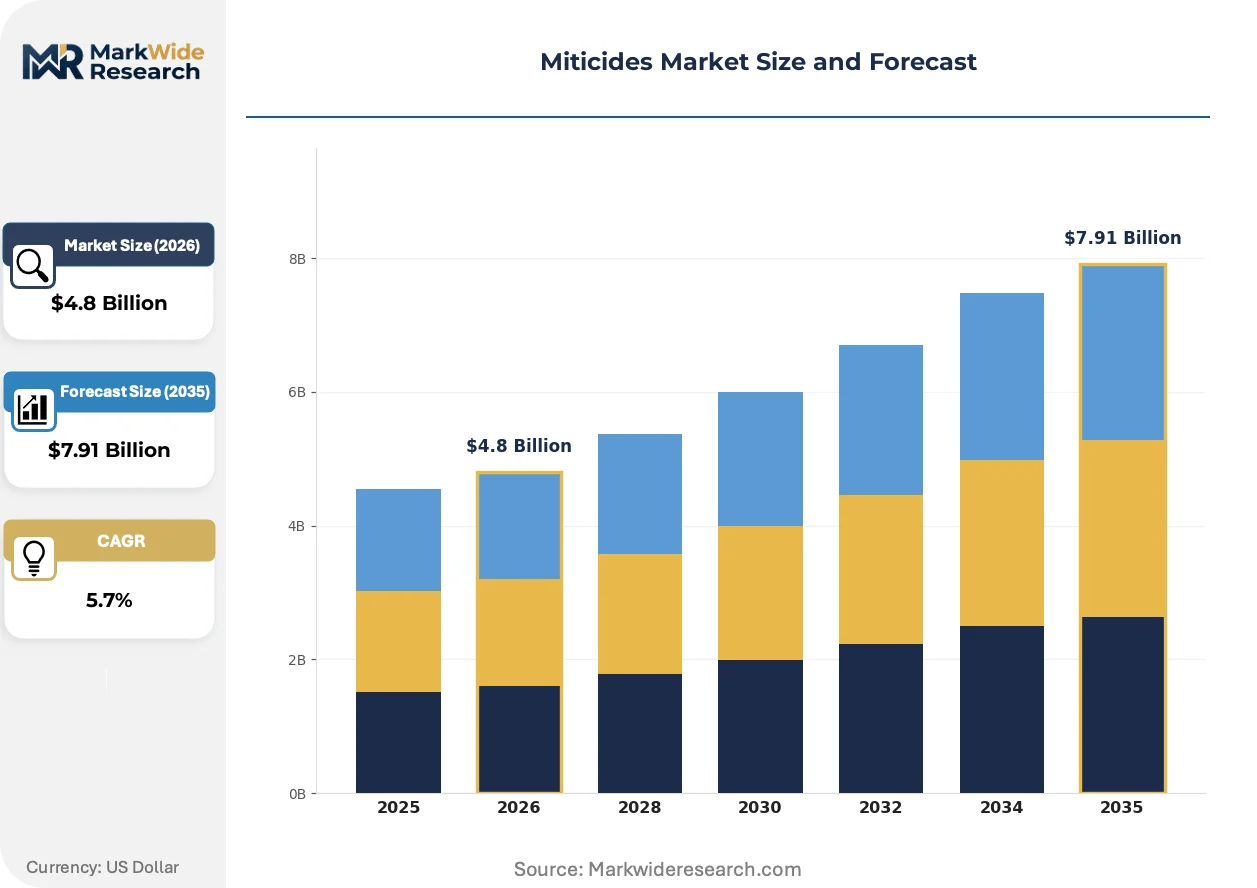
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Organic, Inorganic, Biological, Synthetic Application: Agricultural, Horticultural, Residential, Commercial Formulation: Liquid, Granular, Powder, Emulsifiable Concentrate Active Ingredient: Acaricides, Insect Growth Regulators, Neem Oil, Others |
| Companies Covered | BASF SE, Bayer AG, Syngenta Group, FMC Corporation, UPL Limited, Corteva Agriscience, Nufarm Limited, ADAMA Agricultural Solutions, Sumitomo Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Miticides Market Strategic Shifts
Formulation chemistry and application technology are diverging toward precision delivery systems that reduce active ingredient load per hectare while maintaining efficacy thresholds against resistant populations.
RNA interference-based acaricide development is bifurcating the discovery pipeline. Startups with CRISPR screening platforms identify novel target sites faster than legacy high-throughput chemistry programs. Specialty vegetable producers in the Netherlands and Spain pilot these solutions under controlled-release greenhouse conditions, compressing development feedback loops.
EPA's revised ecological risk assessment protocols under FIFRA now mandate pollinator field studies for all new acaricide registrations. This elevates data package costs and extends review timelines by 18-24 months. Row crop segments in the US Corn Belt delay adoption of novel chemistries pending honey bee exposure modeling completion.
Certification-driven procurement now dominates export-oriented supply chains. Supermarket chains in Germany and the United Kingdom require residue monitoring data at the lot level, displacing traditional spot-checking by national regulators. Chilean cherry and blueberry exporters invest in blockchain-tracked spray records to maintain shelf access.
Miticides Market Segmentation
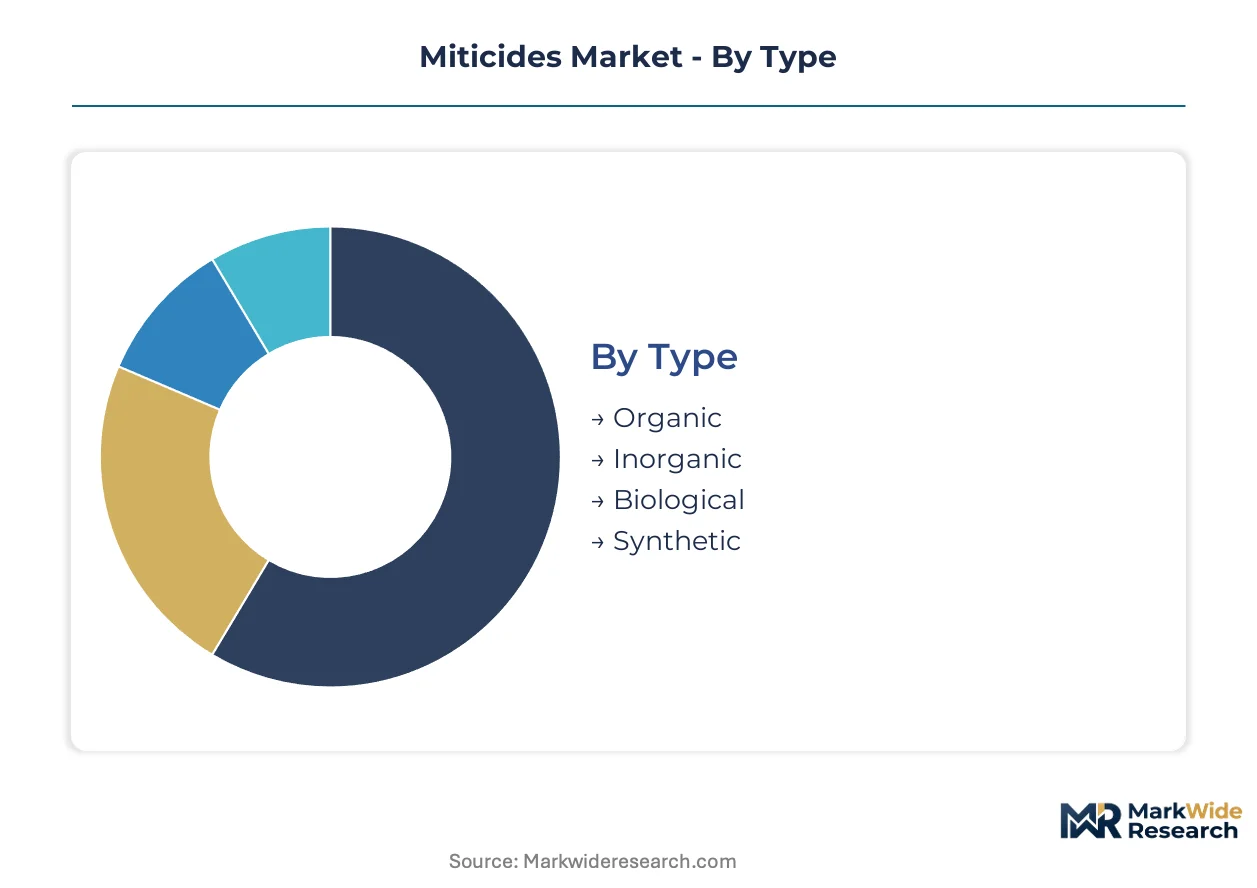
Miticide procurement patterns diverge sharply across end-use contexts, with agricultural buyers prioritizing cost-per-hectare efficiency while horticultural operators emphasize residue compliance for export certification. Formulation selection directly determines application infrastructure requirements and tank-mix compatibility, locking in supplier relationships across multi-season contracts.
Type:
Domestic consumption concentrates synthetic and inorganic formulations in Brazil's soybean belt and India's grape corridors, while biological and organic types command premium export positioning into EU and North American specialty crop markets.
- Synthetic:Multi-step synthesis yields abamectin, bifenazate, and spiromesifen at concentrations between 1.5% and 15% w/w. Brazil's Mato Grosso growers rotate these against resistance pressure, though supply volatility from Chinese fermentation capacity creates input cost spikes during environmental compliance shutdowns.
- Biological:Fermentation-derived Beauveria bassiana and Metarhizium anisopliae formulations carry organic certification for EU Green Deal compliance. Dutch greenhouse vegetable producers pilot these under controlled-release conditions, accepting slower knockdown speed for residue-free export access.
- Organic:Botanical extracts and mineral oils serve certified organic acreage in California's Central Valley and Germany's supermarket-contracted vegetable supply chains.
- Inorganic:Sulfur-based legacy formulations persist in price-sensitive Indian horticulture and African export rose production.
Synthetic formulations hold the largest share; momentum sits with biological types as organic acreage expands and residue limits tighten.
Application:
Cost tier stratification separates high-frequency agricultural spraying from precision horticultural programs, with residential and commercial segments operating on equipment-access and labor-availability constraints rather than per-hectare economics.
- Agricultural:Row crop and broad-acre specialty producers in Brazil, Argentina, and the US Corn Belt deploy ground rigs and aerial application for spider mite control in soybeans, cotton, and corn. Resistance management protocols mandate rotation scheduling that expands supplier qualification lists.
- Horticultural:Greenhouse and open-field vegetable, fruit, and ornamental producers in Spain's Almería, the Netherlands' Westland, and Chile's Central Valley prioritize residue monitoring for supermarket chain compliance. Blockchain-tracked spray records now standard for German and UK retail access.
- Residential:Lawn and garden consumers in US suburban markets and Australian metropolitan areas purchase ready-to-spray formulations through retail channels, with efficacy claims driving brand selection.
- Commercial:Golf course superintendents and municipal park managers in Japan and South Korea balance aesthetic thresholds with pollinator protection mandates under revised EPA and national ecological risk protocols.
Agricultural application dominates volume; horticultural commands value premium through certification requirements.
Formulation:
Volume concentration favors liquid and emulsifiable concentrate formats compatible with existing spray infrastructure, while granular and powder types occupy niche positions requiring specialized application equipment or root-zone delivery systems.
- Liquid:Ready-to-use and tank-mix compatible solutions enable uniform foliar coverage in dense canopy structures. California stone fruit and nut growers rely on these for IPM program integration, with electrostatic nozzle compatibility now standard for drone convergence.
- Emulsifiable Concentrate:Oil-in-water systems concentrate active ingredients for transport efficiency and extended shelf stability. BASF SE's backward integration into active ingredient synthesis sustains cost advantages in this format for Latin American export markets.
- Granular:Slow-release matrix formulations protect root zones in container nursery stock and greenhouse bedding plants, requiring mechanical spreader or soil-incorporation equipment.
- Powder:Wettable powder and dust formulations serve organic certification programs and aerial application in terrain-inaccessible regions, with drift management constraints limiting expansion.
Liquid formulations hold the largest share; granular types gain traction in protected cultivation segments.
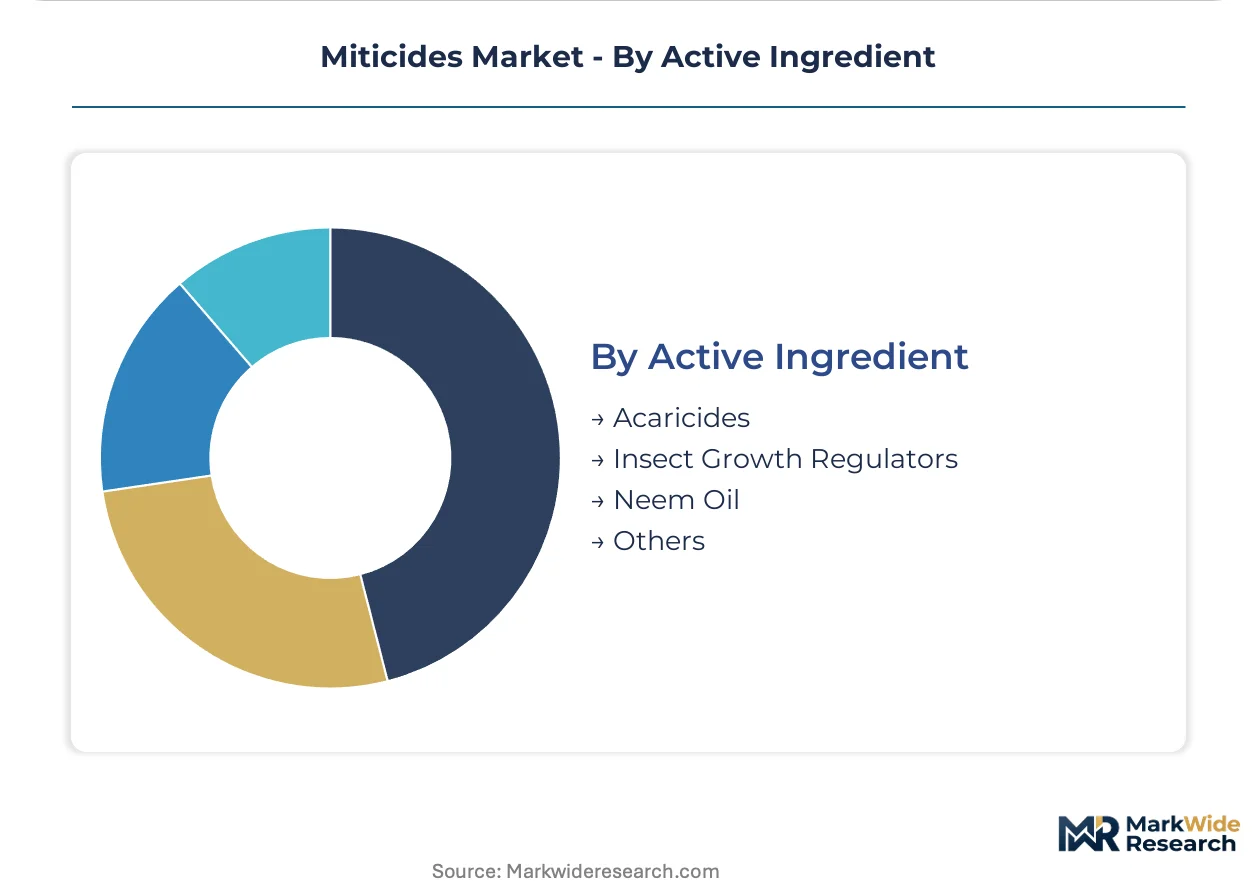
Active Ingredient:
Supply concentration in avermectin fermentation capacity shapes competitive dynamics, with botanical alternatives and insect growth regulators carving differentiated positions through regulatory preference and resistance management rotation requirements.
- Acaricides:Synthetic molecules targeting mite-specific physiological pathways include abamectin, bifenazate, and etoxazole. Syngenta Group's proprietary acaricide development anchors market position, though resistance mapping in Brazil and California compresses product lifecycles.
- Neem Oil:Azadirachtin-based botanical extracts serve organic certification requirements in India's Nashik grape belt and East African export horticulture, with variable efficacy against high-pressure infestations limiting adoption.
- Insect Growth Regulators:Juvenile hormone mimics and chitin synthesis inhibitors disrupt mite development without acute toxicity, fitting IPM rotation protocols in EU specialty crop sectors under Farm to Fork pesticide reduction mandates.
- Others:Mineral oils, soaps, and experimental RNA interference formulations occupy emerging positions, with CRISPR-screened target sites advancing through Dutch and Spanish greenhouse pilots.
Acaricides hold the largest share; neem oil and insect growth regulators are expanding most quickly through organic and IPM channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agricultural buyers concentrate in Brazil's soybean belt and California's Central Valley, while horticultural procurement clusters in EU greenhouse corridors and India's export-oriented fruit zones.
Brazil
Soybean and cotton growers in Mato Grosso and Rio Grande do Sul deploy resistance management protocols mandating acaricide rotation. ANVISA regulates active ingredient registration with ecological risk assessments. The Mato Grosso cluster drives biological miticide adoption as rotation requirements compress synthetic product lifecycles.
United States
Stone fruit and nut producers in California's Central Valley expand integrated pest management programs requiring tank-mix compatibility testing. EPA mandates pollinator field studies under revised FIFRA protocols, extending registration timelines. Fresno and Kern counties anchor demand for liquid formulations compatible with electrostatic drone spraying.
Germany
Supermarket chains in Berlin and Munich enforce lot-level residue monitoring for imported horticultural products. The EU Green Deal's Farm to Fork strategy accelerates biological alternative registration timelines. The Lower Saxony greenhouse corridor pilots RNA interference-based acaricides under controlled-release conditions.
India
Grape and pomegranate exporters near Nashik and Sangli seek ISO 17025-accredited residue testing to access EU retail channels. The country's national agricultural regulator enforces maximum residue limits for export certification. The Maharashtra horticulture belt lacks compliant laboratory infrastructure, creating supplier qualification bottlenecks.
Netherlands
Greenhouse vegetable producers in Westland and Almería prioritize residue-free export access to German and UK retail chains. ECHA's REACH framework governs active substance renewal processes extending 48-60 months. Dutch growers pilot Beauveria bassiana formulations, accepting slower knockdown for organic certification compliance.
Miticides Market Competitive Environment
Player mix skews toward integrated agrochemical conglomerates with backward integration into active ingredient synthesis. The structure concentrates around three tiers: global innovators with proprietary molecule pipelines, regional formulators with distribution scale, and biological specialists with fermentation capabilities. Dominant competitive moves include capacity expansion in Chinese avermectin fermentation and strategic partnerships for drone application technology licensing.
Within the integrated conglomerate tier, BASF SE leverages its captive supply of synthetic intermediates for emulsifiable concentrate cost advantages, while Syngenta Group anchors its position through proprietary acaricide development. FMC Corporation represents the biological fermentation archetype, differentiating via microbial production capabilities. These three exemplify the strategic divergence between synthetic chemistry scale and biological alternative positioning.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Group |
| FMC Corporation |
| UPL Limited |
| Corteva Agriscience |
| Nufarm Limited |
| ADAMA Agricultural Solutions |
| Sumitomo Chemical |
| Others |
Value Chain & Pricing Dynamics
Biological fermentation inputs replacing synthetic chemistry feedstocks are redrawing procurement geography toward Indian and European microbial production hubs while compressing margin structures for legacy acaricide manufacturers dependent on Chinese avermectin supply.
Pricing Analysis
Cost-plus contracts indexed to Chinese environmental compliance shutdown frequency dominate synthetic miticide procurement, with BASF SE and Syngenta Group leveraging backward integration into active ingredient synthesis to buffer margin volatility. Three-tier pricing structure across premium biological formulations, standard synthetic emulsifiable concentrates, and economy sulfur-based generics separates residue-critical export growers from price-sensitive domestic row crop operators. Cost compression in the synthetic tier is intensifying because Brazilian resistance management protocols are compressing product lifecycles and accelerating rotation requirements. Agricultural buyers in Brazil's Mato Grosso exhibit highest price sensitivity, while horticultural exporters near Nashik and Sangli absorb premium biological pricing for EU supermarket access.
Supply Chain Analysis
China anchors upstream fermentation capacity for avermectin derivatives and abamectin intermediates, while India and the Netherlands concentrate biological formulation and controlled-release packaging. Active ingredient synthesis draws from fermentation-derived macrocyclic lactones, petrochemical-based pyrethroid precursors, and botanical neem oil extracts. Single-source vulnerability in Chinese environmental compliance enforcement creates input volatility during seasonal shutdowns. Distribution runs through regional agrochemical distributors with multi-season contract lock-in, supplemented by direct procurement relationships for horticultural exporters requiring lot-level residue documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The miticides market functions as a service-attach opportunity where resistance monitoring diagnostics and precision application advisory layers expand faster than base chemical formulation revenues.
For Market Incumbents: Shield proprietary acaricide pipelines by accelerating RNA interference target site development through CRISPR screening partnerships, while securing captive fermentation capacity in India to offset Chinese supply concentration. Resistance mapping services represent the critical defensive lever against biological substitution threats in EU greenhouse corridors. For New Entrants and Emerging Players: Lead with ISO 17025-accredited residue testing infrastructure in India's Maharashtra horticulture belt, where compliant laboratory capacity bottlenecks exclude conventional suppliers from premium export channels. Drone application technology licensing partnerships offer the most penetrable go-to-market angle for ultralow-volume electrostatic spraying systems. For Investors and Strategic Acquirers: The market sits at a substitution-transition phase that favors biological fermentation specialists with regulatory dossiers already filed under EU Green Deal acceleration pathways. Acquisition targets should demonstrate validated Beauveria bassiana production scale and existing relationships with Dutch or Spanish greenhouse cooperatives. The signal to watch is ANVISA approval timelines for novel biological acaricides in Brazil, which would confirm rotation-mandate tailwinds for non-synthetic portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | BASF SE's captive avermectin synthesis buffers margin volatility during Chinese environmental compliance shutdowns. |
| RNA Interference Target Site Development | CRISPR screening platforms accelerate novel acaricide discovery faster than legacy high-throughput chemistry programs. |
| ISO 17025 Laboratory Accreditation | Compliant residue testing infrastructure unlocks supplier qualification for EU and North American export-oriented horticulture. |
| Drone Application Technology Licensing | Electrostatic nozzle compatibility enables foliar coverage in dense canopy structures previously inaccessible to ground rigs. |
| Biological Formulation Scale-Up | FMC Corporation's microbial production capabilities position for EU Farm to Fork pesticide reduction mandate compliance. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA registration databases, ECHA active substance renewal records, ANVISA approval filings, and EU MRL compliance directories. Interviews with agrochemical R&D directors, regulatory affairs leads at formulators, procurement managers at Brazilian soybean cooperatives, and residue testing laboratory operators combined with customs trade data and SEC 10-K segment disclosures. Bottom-up volume modeling triangulates against top-down value estimates derived from distributor channel checks.
Segmentation dimensions modeled include synthetic versus biological versus organic type, agricultural versus horticultural versus residential application, liquid versus emulsifiable concentrate versus granular formulation, and acaricide versus neem oil versus insect growth regulator active ingredient chemistry. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory acceleration effects and resistance management protocol adoption curves. Forecast inputs incorporate EU Green Deal implementation pace, Brazilian rotation mandate enforcement intensity, and drone application technology penetration rates.
Forecasts assume regulatory continuity in EPA FIFRA ecological risk protocols, ECHA REACH renewal timelines, and ANVISA registration requirements; material policy shifts would require re-modeling. Specific risks include accelerated biological substitution thresholds, Chinese environmental compliance disruption, and pollinator protection mandate expansion. Recalibration cycles align with material shifts in resistance mapping data availability and novel mode-of-action approval velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Sustainable Crop Protection Chemicals Market
Crop Protection
South America Insecticide Market
Crop Protection
Vietnam Herbicide Market
Crop Protection
Low-Odor, Enclosed-Greenhouse Foliar Protection Market
Crop Protection
IPM Pheromones Market
Crop Protection
Global Insect Pest Control Market
Crop Protection
Soil Sterilizers Market
Crop Protection
Iprodione Market
Crop Protection
Global Acaricides Market
Crop Protection
Indonesia Insecticide Market
Crop Protection
Tebuconazole Market
Crop Protection
China Insecticide Market
Crop Protection
Crop Protection Chemicals Market
Crop Protection
Avicides Market
Crop Protection
Organic Pesticides Market
Crop Protection
Europe Acaricides Market