
 India Insecticide Market | 2026-2036
India Insecticide Market Size, Share, and Industry Trends Forecast 2026-2036
India Insecticide Market Insights
CIBRC registration under the Insecticides Act, 1968 is collapsing the supplier base as renewal costs and bio-efficacy data requirements escalate. Bayer CropScience leverages its global molecule pipeline to sustain premium positioning in cotton and vegetable segments. UPL Ltd anchors its portfolio through backward integration into active ingredient manufacturing at its Gujarat facilities. Rallis India Ltd competes on brand loyalty built over decades in the Deccan plateau markets.
An insecticide is a biologically active chemical formulation designed to disrupt the neural, respiratory, or developmental systems of arthropod pests, typically synthesized through chlorination, phosphorylation, or pyrethroid esterification processes, and deployed to protect standing crops from yield-destroying infestations. Emulsifiable concentrates retain dominance in foliar spraying due to established farmer familiarity and compatibility with knapsack sprayers, while seed treatment formulations gain structural importance as integrated pest management protocols expand. Wettable powders occupy a shrinking but defended niche in rice cultivation where waterlogged conditions demand rapid dispersion.
BIS quality certification and FSSAI residue limits for agricultural commodities shape product development priorities, with CEA monitoring power availability for formulation plants. The Insecticides Act mandates label compliance that restricts import and domestic sale to registered entities, compressing gray-market volumes. Stakeholders must track evolving CIBRC re-registration timelines and state-level pesticide procurement tender structures to anticipate volume allocation shifts.
Market Dynamics
CIBRC re-registration timelines under the Insecticides Act, 1968 are compressing the supplier base as bio-efficacy data costs escalate, forcing smaller formulators to exit while integrated manufacturers consolidate procurement leverage across cotton and rice belts.
Growth Catalysts
- Stem borer pressure in eastern Uttar Pradesh:Repeated infestation cycles in rice-paddy belts necessitate multiple application windows, sustaining volume demand for organophosphates and neonicotinoids through the kharif season.
- CIBRC registration framework:Mandatory label compliance under the Insecticides Act restricts gray-market imports, formalizing channel structures and protecting registered domestic manufacturers from unregistered competition.
- Synthetic pyrethroid chemistry:Cotton cultivation expansion in Maharashtra and Gujarat drives procurement of alpha-cypermethrin and lambda-cyhalothrin formulations for bollworm management.
Market Restraints
- Technical-grade import concentration:Active ingredient supply clusters in China create vulnerability to freight volatility and customs delays at Mumbai and Mundra ports.
- FSSAI residue limit compliance:Tightening maximum residue limits for agricultural commodities force reformulation investments that erode margin on legacy products.
- Biological substitute emergence:Bacillus thuringiensis and neem-based alternatives gain traction in export-oriented vegetable cultivation, displacing synthetic share in premium segments.
Strategic Opportunities
- Seed treatment formulation expansion:Integrated pest management protocol adoption creates white space for imidacloprid and thiamethoxam coatings on hybrid cotton and maize seeds.
- Bihar procurement tender structures:State-level pesticide distribution programs offer volume allocation stability for formulators meeting BIS quality certification standards.
- Drone spraying service convergence:UAV-based application technology intersects with knapsack sprayer replacement cycles, opening channel partnerships between manufacturers and agri-tech operators.
Industry Challenges
- Bio-efficacy trial capacity:CIBRC-mandated field study requirements exceed available testing infrastructure, extending registration timelines and freezing product pipelines.
- Formulation plant power reliability:CEA-monitored grid availability disruptions at Gujarat manufacturing clusters force diesel generator dependence, inflating operating costs.
- Label claim litigation exposure:State agriculture department enforcement actions against off-label usage create liability risk for manufacturers with extensive distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Insecticide Market |
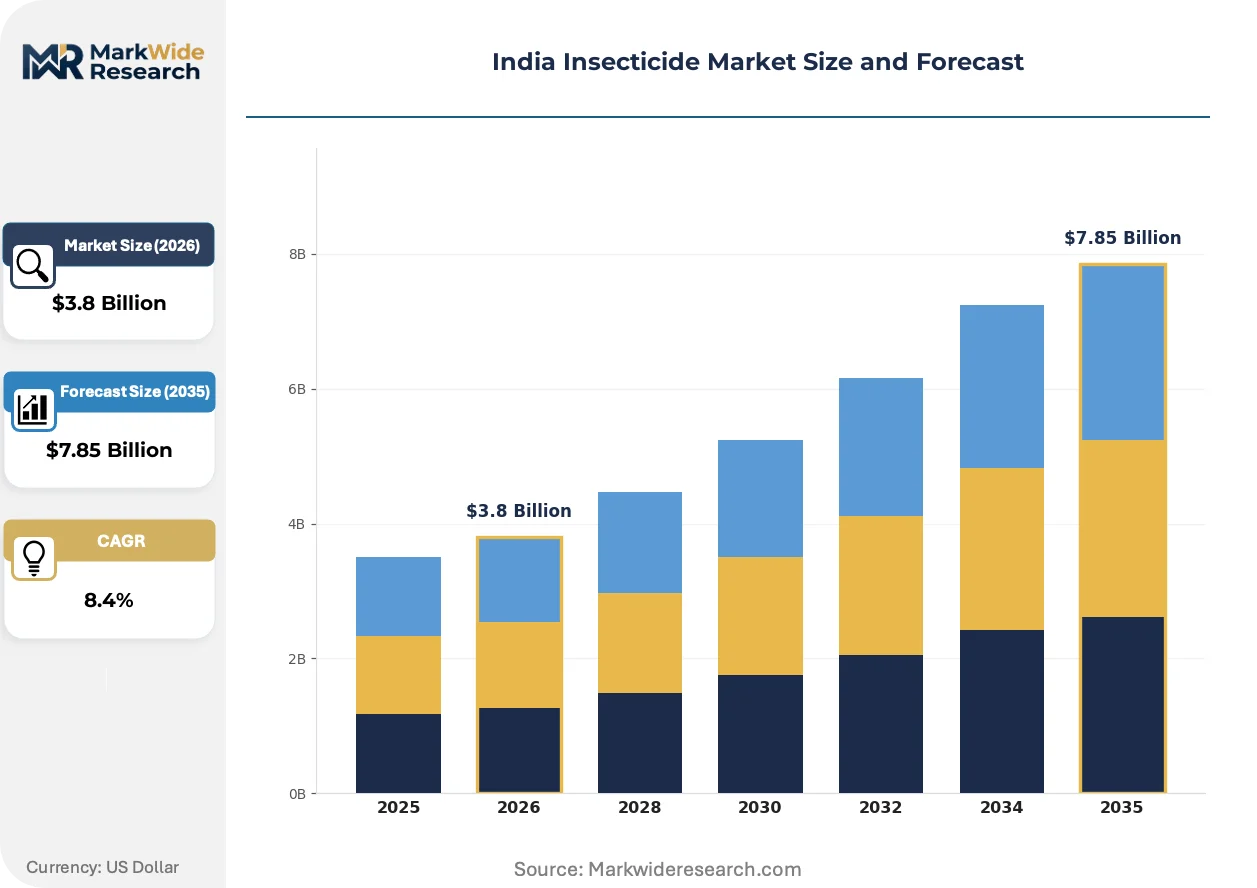
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acaricides, Herbicides, Fungicides, Insect Growth Regulators Formulation: Emulsifiable Concentrates, Granules, Wettable Powders, Suspensions Application Method: Aerial Application, Ground Spraying, Soil Treatment, Seed Treatment End User: Agricultural Producers, Pest Control Services, Homeowners, Commercial Growers |
| Companies Covered | Rallis India Ltd, Dhanuka Agritech Ltd, Syngenta India Ltd, Coromandel International Ltd, Sumitomo Chemical India Ltd, Bayer CropScience Ltd, PI Industries Ltd, Insecticides (India) Ltd, UPL Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Insecticide Market Trends and Innovations
Formulation chemistry and application technology are diverging from established emulsifiable concentrate dominance as regulatory pressure and labor scarcity force adaptation across the value chain.
Nano-emulsion and micro-encapsulation delivery systems are fragmenting the traditional wettable powder and emulsifiable concentrate categories. Cotton growers in Gujarat are adopting these formats for reduced phytotoxicity and extended residual control. The shift is fragmenting procurement patterns as distributors stock multiple formulation grades for identical active ingredients.
CIBRC has tightened data requirements for re-registration under the Insecticides Act, 1968, mandating additional ecotoxicology studies for molecules registered before 2000. This regulatory compression is forcing portfolio rationalization among formulators with extensive legacy product lines. Rice cultivation in West Bengal faces the most acute adjustment pressure as chlorpyrifos and monocrotophos replacements require new label approvals.
Farmer buying patterns are consolidating around state procurement tender participation rather than open-market retail purchases. The cooperative channel in Maharashtra and Gujarat is displacing traditional dealer networks for volume transactions. This behavioral shift is most visible in cotton belts where farmer producer organizations aggregate demand for synthetic pyrethroid procurement.
India Insecticide Market Segmentation
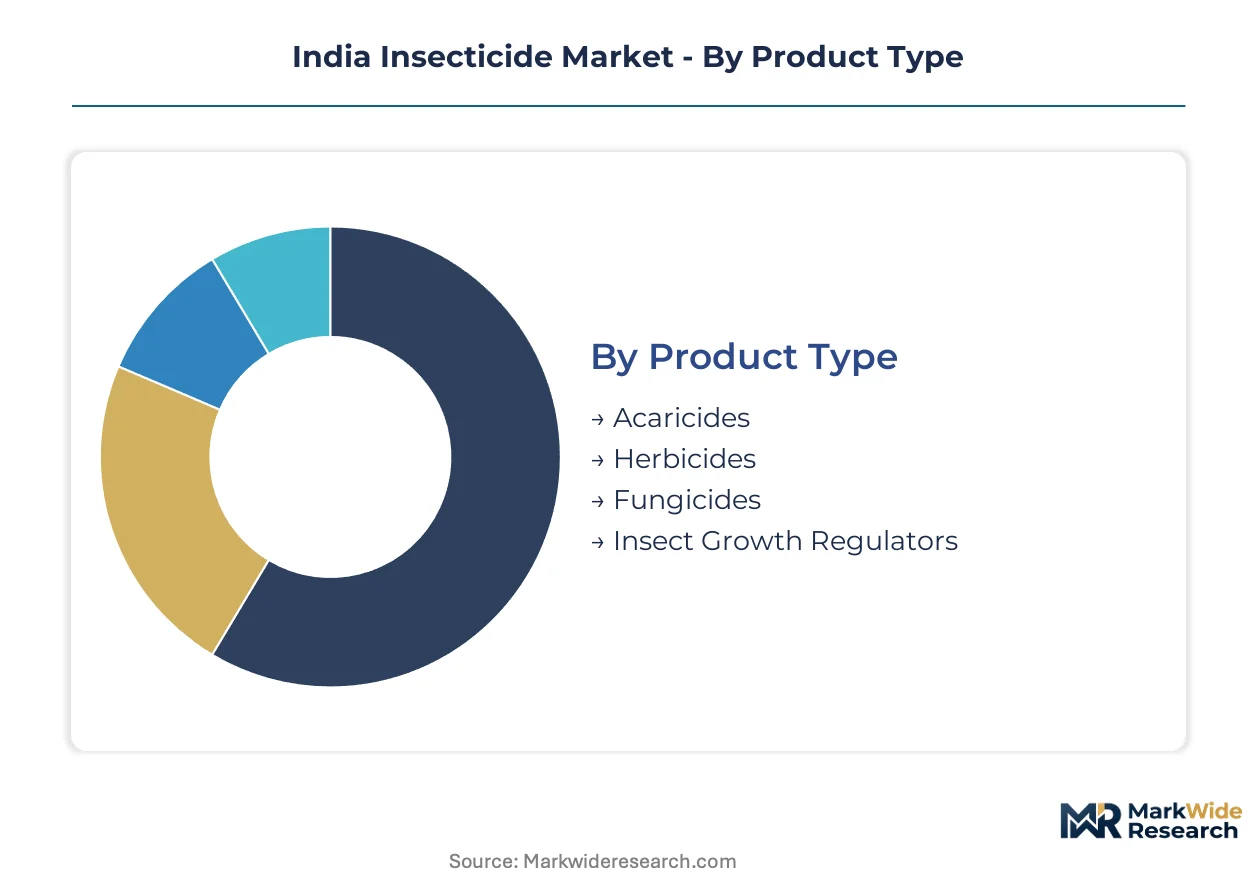
Segmentation in the India insecticide market reflects divergent regulatory pathways and application economics. CIBRC registration requirements under the Insecticides Act create distinct compliance burdens across product categories, while formulation choices determine compatibility with knapsack sprayer infrastructure prevalent in eastern Uttar Pradesh and Bihar rice belts.
Product Type:
BIS certification requirements and FSSAI residue limits apply differential stringency across chemistries, shaping manufacturer portfolio priorities.
- Acaricides:Miticide formulations targeting spider mite infestations in cotton and vegetable cultivation require specialized bio-efficacy data for CIBRC registration. Demand concentrates in Maharashtra's cotton belt where two-spotted mite pressure necessitates repeated acaricide rotation to delay resistance development.
- Herbicides:Weed control chemistry competes for application windows with insecticide spraying in rice-paddy systems. Procurement volumes are climbing fastest in Bihar and West Bengal where labor scarcity drives pre-emergent herbicide adoption, displacing manual weeding.
- Fungicides:Crop protection against fungal pathogens often co-formulated with insecticides for integrated disease-pest management.
- Insect Growth Regulators:Chitin synthesis inhibitors and juvenile hormone mimics disrupt molting cycles with reduced mammalian toxicity.
Established volume favors herbicides; emerging adoption favors insect growth regulators.
Formulation:
Cost tiers separate premium nano-delivery systems from economy-grade conventional formats.
- Emulsifiable Concentrates:Oil-in-water formulations dissolve active ingredients in organic solvents with emulsifying agents. Dominance persists in Gujarat cotton cultivation where farmer familiarity with EC dilution ratios and knapsack sprayer compatibility sustains procurement volumes despite phytotoxicity risks.
- Granules:Controlled-release matrices embed active ingredients in clay or sand carriers for soil application. Adoption accelerates in West Bengal rice systems where standing water conditions prevent foliar spraying during monsoon periods.
- Wettable Powders:Finely ground active ingredients with dispersing agents suspend in water for spraying.
- Suspensions:Aqueous concentrated suspensions of solid active particles reduce solvent exposure.
Farmer preference anchors emulsifiable concentrates; environmental compliance pressures favor suspensions.
Application Method:
Volume scale distinguishes smallholder ground spraying from emerging mechanized alternatives.
- Aerial Application:UAV-based drone spraying services deploy ultra-low volume formulations across contiguous cotton holdings. Maharashtra farmer producer organizations aggregate demand for drone service contracts, bypassing traditional dealer networks for synthetic pyrethroid application.
- Ground Spraying:Knapsack sprayer operations remain the default delivery mode across eastern Uttar Pradesh rice belts. CEA-monitored grid reliability at Gujarat formulation plants affects concentrate supply timing for peak kharif season ground application.
- Soil Treatment:Pre-planting incorporation of granular or liquid formulations targets soil-dwelling pests.
- Seed Treatment:Active ingredient coatings on hybrid cotton and maize seeds integrate with integrated pest management protocols.
Operational scale favors ground spraying; labor cost trajectories favor aerial application.
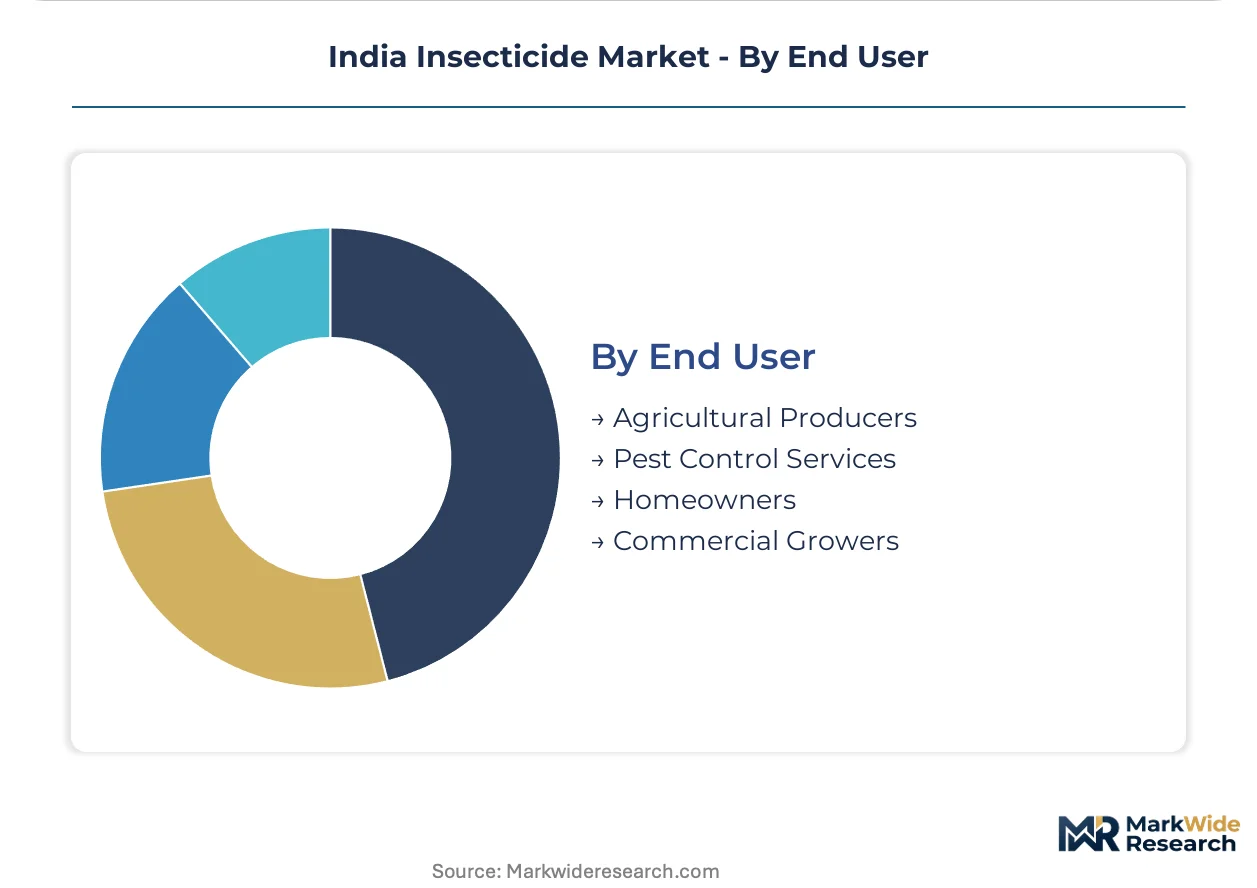
End User:
Customer type determines procurement channel structure and price sensitivity.
- Agricultural Producers:Smallholder and commercial farming operations constitute the dominant demand base. State-level pesticide distribution tenders in Bihar offer volume allocation stability for formulators meeting BIS quality certification standards.
- Pest Control Services:Professional application contractors purchase bulk formulations for horticultural and plantation contracts. Channel partnerships with agri-tech drone operators are opening in Gujarat and Maharashtra cotton belts.
- Homeowners:Retail packaged formats for domestic pest control represent a marginal volume segment.
- Commercial Growers:Export-oriented vegetable cultivation in Gujarat and Maharashtra faces FSSAI residue limit compliance pressures.
Procurement concentration favors agricultural producers; margin expansion favors commercial growers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level pesticide procurement programs under the Insecticides Act, 1968 concentrate demand across India's agricultural belts. Maharashtra and Gujarat anchor synthetic pyrethroid consumption through cotton cultivation expansion. Eastern rice-paddy states drive organophosphate volumes through repeated stem borer applications.
Maharashtra
Cotton cultivation across the Deccan plateau sustains alpha-cypermethrin and lambda-cyhalothrin procurement for bollworm management. State agriculture department enforcement actions against off-label usage tighten distribution compliance. Farmer producer organizations in the Vidarbha region aggregate synthetic pyrethroid demand through cooperative procurement channels.
Gujarat
CEA-monitored grid reliability at formulation plants affects concentrate supply timing for peak kharif season application. BIS quality certification requirements shape product development priorities for export-oriented vegetable cultivation. The Saurashtra cotton belt drives nano-emulsion adoption for reduced phytotoxicity in extended residual control.
Uttar Pradesh
Stem borer and brown planthopper pressure in the eastern rice-paddy belt necessitates repeated organophosphate and neonicotinoid applications. State-level pesticide distribution tenders offer volume allocation stability for formulators meeting registration standards. The Gorakhpur-Faizabad corridor concentrates knapsack sprayer-based ground spraying operations.
Bihar
Labor scarcity drives pre-emergent herbicide adoption alongside insecticide spraying in rice systems. Procurement tender structures under state agriculture department programs formalize channel structures for registered manufacturers. The Kosi-Gandak floodplains anchor granular formulation demand where standing water prevents foliar spraying during monsoon periods.
West Bengal
Chlorpyrifos and monocrotophos replacement requirements under tightened CIBRC re-registration timelines force portfolio adjustment. Rice cultivation faces acute adjustment pressure as legacy molecules require new label approvals. The Hooghly-Bardhaman belt concentrates wettable powder consumption where waterlogged conditions demand rapid dispersion.
India Insecticide Market Competitive Landscape
Player mix skews toward integrated manufacturers with backward integration into active ingredient production. CIBRC registration renewal costs and bio-efficacy data requirements compress the supplier base, forcing smaller formulators to exit. Three archetypes dominate: global molecule pipeline owners, domestic integrated manufacturers with captive technical-grade supply, and regional brand loyalty builders. Consolidation proceeds through M&A absorption of stranded registration portfolios and capacity expansion at Gujarat manufacturing clusters.
Within the integrated manufacturer tier, UPL Ltd anchors portfolio positioning through in-house production of active ingredients at its Gujarat facilities. Bayer CropScience Ltd exemplifies the global pipeline archetype with premium positioning in cotton and vegetable segments. Rallis India Ltd occupies a position built on decades of brand loyalty in Deccan plateau markets. These three represent the structural divergence between technical-grade self-sufficiency, imported molecule dependence, and distribution network depth.
| Leading Market Players |
|---|
| Rallis India Ltd |
| Dhanuka Agritech Ltd |
| Syngenta India Ltd |
| Coromandel International Ltd |
| Sumitomo Chemical India Ltd |
| Bayer CropScience Ltd |
| PI Industries Ltd |
| Insecticides (India) Ltd |
| UPL Ltd |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Gujarat formulation plants shapes both procurement leverage and price floors across the India insecticide market. Scale economies in backward-integrated active ingredient manufacturing compress unit costs for domestic producers while import-dependent formulators face margin compression from technical-grade supply volatility.
Pricing Analysis
Certification level (BIS-grade versus non-certified) creates the primary spread between premium and economy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects FSSAI residue compliance investment and CIBRC registration status. Pricing pressure stems from legacy molecule reformulation costs under tightened re-registration timelines. Smallholder agricultural producers in eastern Uttar Pradesh exhibit highest price sensitivity, while export-oriented commercial growers in Gujarat absorb premium tiers for residue-compliant formulations.
Supply Chain Analysis
Freight volatility through Mumbai and Mundra ports elevates inbound logistics costs for technical-grade imports. Active ingredient supply clusters in China, with secondary sourcing from Germany and Japan, creates single-source vulnerability for organophosphate and pyrethroid chemistries. Raw material dependencies span chlorinated intermediates, phosphorus derivatives, and pyrethroid acid moieties. Distribution runs through state agriculture department tender structures and cooperative procurement channels, displacing traditional dealer networks in Maharashtra and Gujarat cotton belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India insecticide market operates as a defensive-moat story where CIBRC registration entrenchment creates switching costs that lock in farmer loyalty and distributor relationships.
For Market Incumbents: Consolidate stranded registration portfolios through targeted M&A absorption of smaller formulators exiting under bio-efficacy data cost pressure. Deepen backward integration into active ingredient manufacturing at Gujarat facilities to defend margin position against technical-grade import volatility. Prioritize seed treatment formulation R&D to capture integrated pest management protocol expansion in hybrid cotton and maize segments.
For New Entrants and Emerging Players: Differentiate on drone spraying service partnerships as the most penetrable channel wedge in Maharashtra and Gujarat cotton belts. Target Bihar state procurement tender participation where volume allocation stability rewards BIS-certified newcomers. Pursue biological substitute co-development with agricultural universities to displace synthetic share in export-oriented vegetable cultivation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated manufacturers with captive technical-grade supply and established CIBRC registration pipelines. Long-term viability rests on consolidation economics rather than molecule innovation, with acquisition targets clustering around regional brand loyalty builders in Deccan plateau markets. The signal to watch is CIBRC re-registration timeline acceleration as an inflection indicator for supplier base compression velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CIBRC Registration Portfolio Acquisition | Absorbing stranded registrations accelerates market access under compressed approval timelines. |
| Backward Integration into Technical-Grade Manufacturing | Gujarat-based captive production insulates margin from China import volatility. |
| Seed Treatment Formulation Expansion | Imidacloprid and thiamethoxam coatings align with integrated pest management protocol adoption. |
| Drone Spraying Channel Partnerships | UAV service convergence opens direct farmer access bypassing traditional dealer networks. |
| Biological Substitute Co-Development | Neem-based and Bacillus thuringiensis alternatives capture export vegetable segment displacement. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork spanning formulation plant managers, state agriculture department procurement officers, CIBRC registration consultants, distribution channel partners, and farmer producer organization leaders. Secondary validation drew from Central Insecticides Board registration databases, FSSAI residue limit notifications, Directorate of Plant Protection reports, customs import data for technical-grade active ingredients, and SEC filings of listed agrochemical manufacturers. Bottom-up volume triangulation across state-level tender structures converged with top-down value estimation from manufacturer revenue disclosures.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product chemistry class, formulation format, application method, and end-user procurement channel. CAGRs were derived from trend extrapolation of registration pipeline velocity, acreage expansion patterns in cotton and rice belts, and substitution elasticities between synthetic and biological alternatives. Key inputs included CIBRC re-registration timeline assumptions, state procurement budget allocations, and farmer producer organization aggregation rates.
Material uncertainties — regulatory acceleration in residue limit tightening, monsoon variability affecting application windows, and technical-grade supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about CIBRC capacity expansion and bio-efficacy trial infrastructure development. Recalibration cycles align with material shifts in CIBRC policy pronouncements and state agriculture department tender structure reforms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Spain Crop Protection Chemicals Market
Crop Protection
US Turf and Ornamental Protection Market
Crop Protection
Rodent Control Pesticides Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
Organic Pesticides Market
Crop Protection
South America Crop Protection Chemicals Market
Crop Protection
Global Chlorpyrifos Market
Crop Protection
Fosthiazate Market
Crop Protection
Asia-Pacific Nematicides Market
Crop Protection
Fruit and Vegetable Crop Protection Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Dicamba Market
Crop Protection
Grain and Cereal Crop Protection Market
Crop Protection
Pest Resistant Crops Market
Crop Protection
Global Acaricides Market
Crop Protection
North America Molluscicides Market