
 Chile Crop Protection Chemicals Market | 2026-2036
Chile Crop Protection Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Crop Protection Chemicals Market Outlook
Agronomic technician availability in Chile's central valley is collapsing as vineyard and orchard intensification outpaces university training programs. Bayer AG sustains its market presence through extensive field advisory networks that compensate for this labor gap. Adama Chile SA competes by leveraging localized formulation facilities that reduce import dependency. BASF SE anchors its position through digital farming platforms that automate pest monitoring across remote farm plots.
Crop protection chemicals comprise synthetic and biological formulations designed to suppress agricultural pests, diseases, and weeds through active ingredients such as glyphosate, chlorpyrifos, and Bacillus thuringiensis-based compounds, typically applied via ground sprayers or aerial systems to maintain yield quality and phytosanitary compliance. Herbicides dominate product type revenue due to extensive monoculture vineyard and fruit orchard operations where weed pressure threatens mechanical harvesting efficiency. Agricultural Production anchors application demand as export-oriented growers prioritize residue-compliant chemistry to satisfy FDA and EFSA import standards. Farmers represent the core end user segment, though agricultural cooperatives are gaining procurement scale as consolidation accelerates in the O'Higgins and Maule regions.
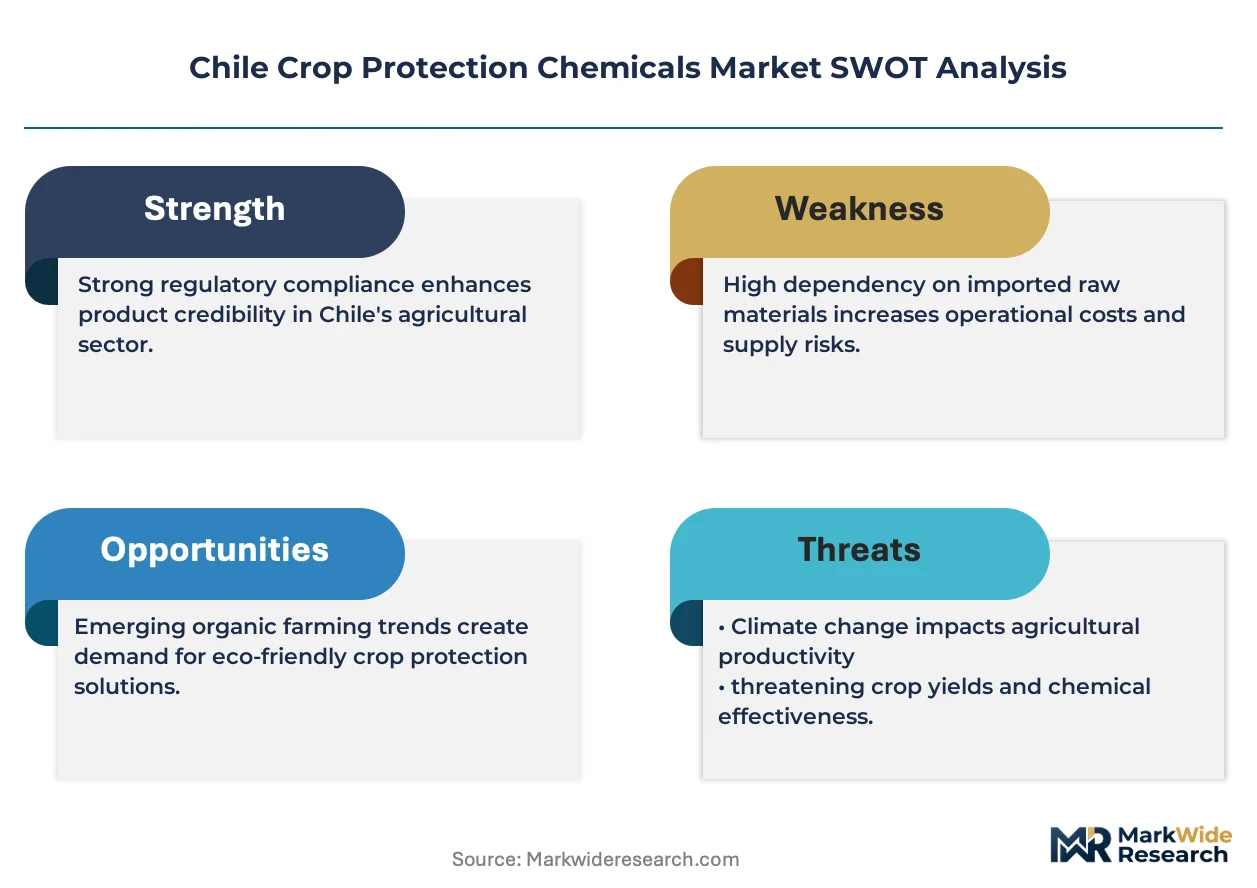
Chile's SAG (Agricultural and Livestock Service) and the Ministry of Agriculture enforce the National Policy on Pesticides, tightening maximum residue limits and reshaping product portfolios toward lower-toxicity alternatives. The EPA and EFSA import standards exert indirect but powerful pressure, as non-compliant shipments face rejection at destination ports. Stakeholders must monitor evolving biopesticide registration pathways and cooperative procurement consolidation to align portfolio and distribution investments with regulatory and buyer-structure shifts.
Market Dynamics
Chile's crop protection sector is compressing around residue compliance mandates from export destination regulators, forcing rapid portfolio turnover toward lower-toxicity chemistries and biological alternatives.
Growth Catalysts
- SAG Accelerated Registration:The Agricultural and Livestock Service has streamlined biopesticide approval timelines, cutting regulatory lag for biological entrants targeting cherry and table grape exports.
- Precision Application Hardware:GPS-guided sprayers and variable-rate nozzles are penetrating O'Higgins and Maule valley operations, reducing chemical waste and residue risk.
- Asian Market Phytosanitary Standards:Chinese and South Korean import protocols now mandate documented spray records and pre-shipment residue testing, creating pull for compliant formulation portfolios.
Market Restraints
- Active Ingredient Import Dependency:Chile lacks domestic synthesis capacity for most synthetic actives, exposing formulators to currency volatility and maritime logistics disruptions.
- EPA Reregistration Uncertainty:Pending US reviews of organophosphate tolerances threaten label retention for chlorpyrifos-based products still used in stone fruit orchards.
- Water Scarcity in Northern Zones:Atacama and Coquimbo regions face severe irrigation constraints that limit spray window flexibility and concentrate runoff compliance costs.
Strategic Opportunities
- Biological-Compatible Adjuvant Formulations:Tank-mix stability challenges with Bacillus thuringiensis and Trichoderma products create white space for specialty surfactant development.
- Cooperative Procurement Consolidation:Agricultural cooperatives in Maule are aggregating volume to negotiate direct manufacturer contracts, bypassing traditional distributor markups.
- Digital Pest Monitoring Integration:Automated pheromone traps and AI-driven population forecasting enable just-in-time spraying, reducing calendar-based prophylactic applications.
Industry Challenges
- Agronomic Technician Shortage:University training programs in agronomy and crop science are failing to match vineyard and orchard intensification rates in the central valley.
- Residue Testing Infrastructure Bottlenecks:SAG-certified laboratories face sample backlogs during peak harvest windows, delaying export clearance and risking shipment degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Crop Protection Chemicals Market |
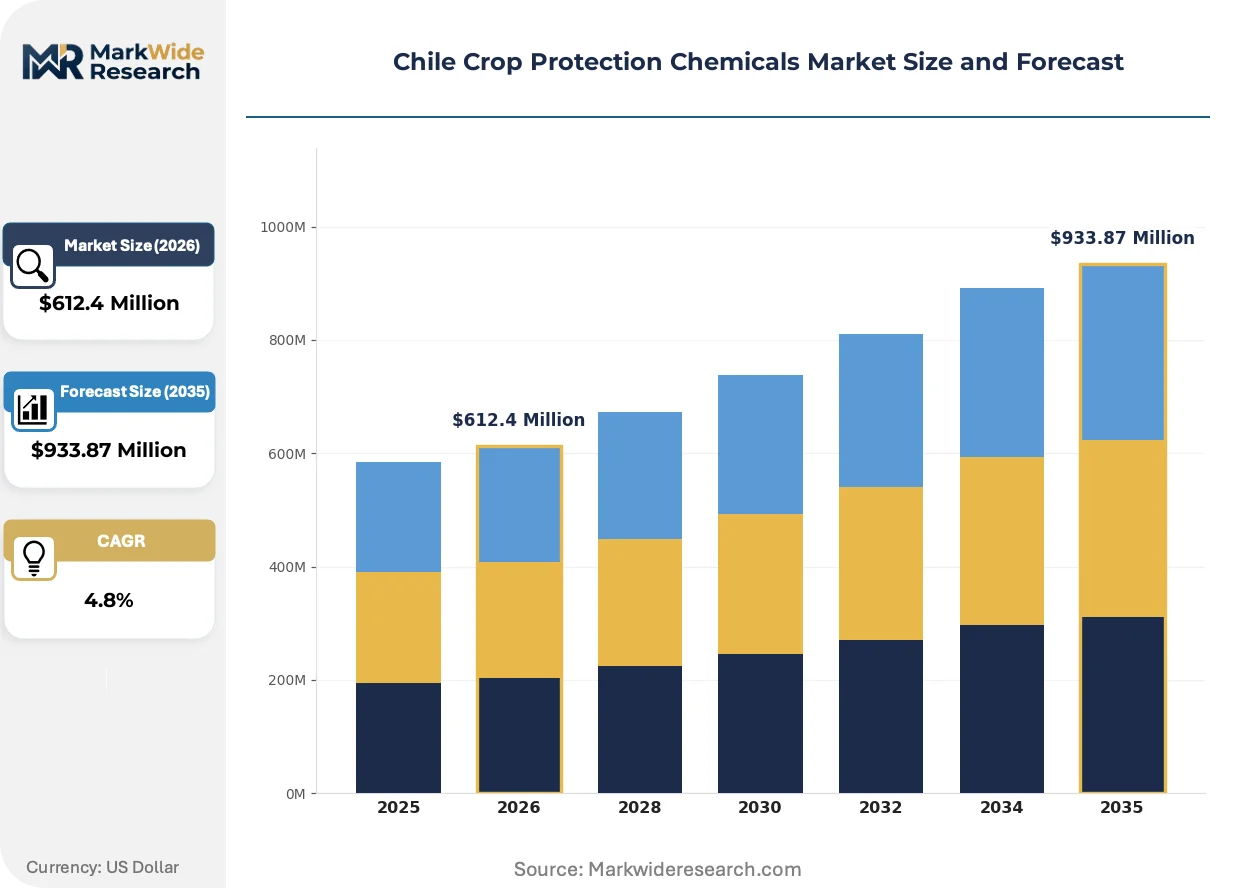
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $933.87 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Insecticides, Fungicides, Pesticides Application: Agricultural Production, Horticulture, Forestry, Turf Management End User: Farmers, Agricultural Cooperatives, Distributors, Research Institutions Distribution Channel: Online Retail, Direct Sales, Agricultural Supply Stores, Wholesalers |
| Companies Covered | Corteva Agriscience, Adama Chile SA, Bayer AG, FMC Corporation, Sumitomo Chemical Co., Ltd., BASF SE, UPL Ltd., Anasac Chile SA, Syngenta Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Crop Protection Chemicals Market Strategic Shifts
Biological crop protection formulations are capturing share from synthetic chemistry as export markets harden residue limits and Chilean growers face technical advisory gaps.
RNA interference pesticides targeting specific lepidopteran pests are displacing broad-spectrum organophosphates in table grape operations. Large integrated exporters in the O'Higgins valley are piloting these precision biocontrol tools despite premium pricing. The technology is displacing calendar-spray programs by enabling population-threshold-triggered applications that reduce total chemical load.
SAG's National Policy on Pesticides is tightening maximum residue limits for cherry and blueberry exports to align with EFSA import standards. Formulators must now submit expanded toxicology dossiers and environmental fate studies for reregistration. The policy is compressing product lifecycles and accelerating withdrawal of older chemistries from the Chilean market.
Cooperative procurement models are aggregating farmer demand into volume contracts with direct manufacturer pricing. Agricultural cooperatives in the Maule region are consolidating spray service operations and chemical purchasing, displacing independent distributor relationships. This concentration is most visible among mid-scale stone fruit growers seeking cost relief amid compressed export margins.
Chile Crop Protection Chemicals Market Segmentation
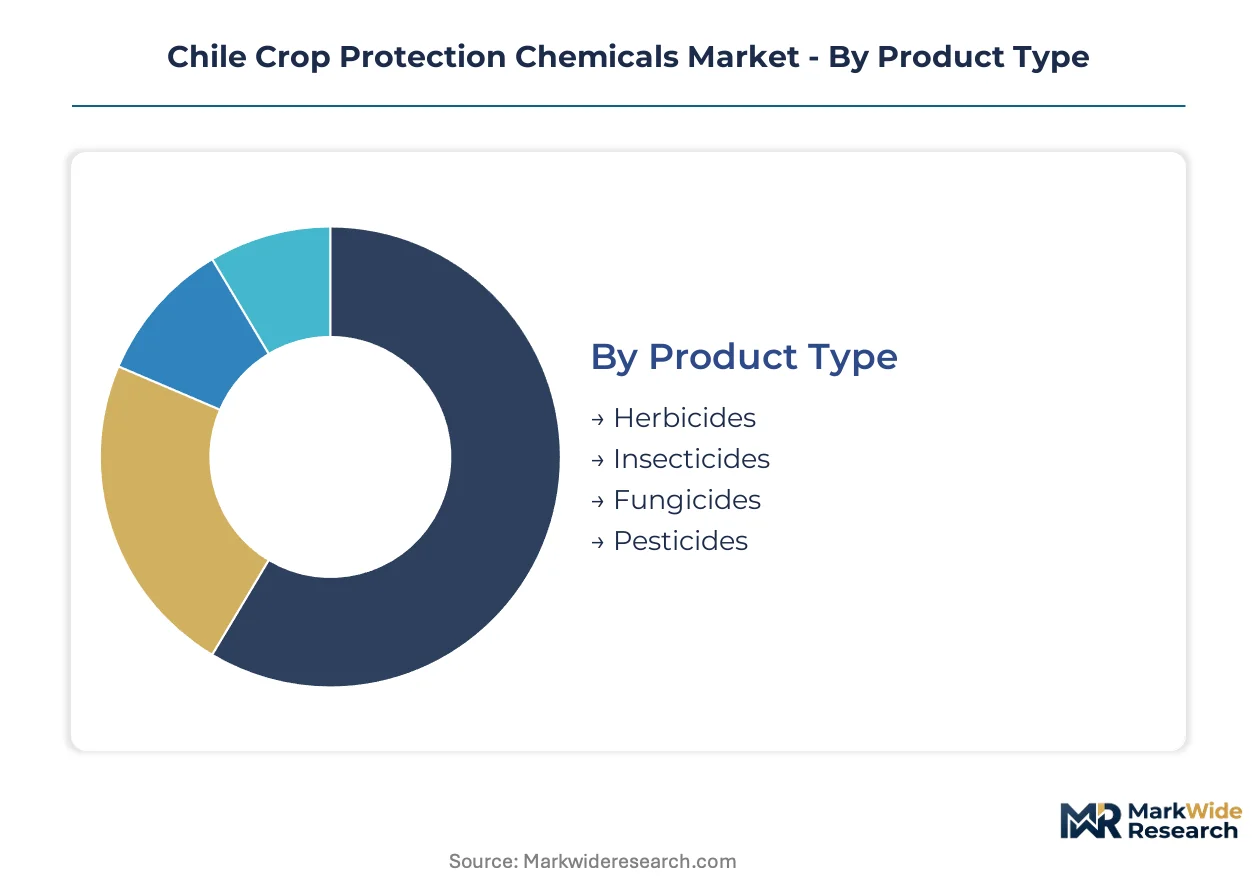
Segmentation in Chile's crop protection chemicals market reveals distinct procurement and application patterns across export-oriented fruit zones. Channel preferences diverge sharply between large integrated exporters in the O'Higgins valley and fragmented smallholders in peripheral regions.
Product Type:
Herbicides and insecticides move predominantly through agricultural supply stores with technical advisory support, while fungicides and biological alternatives increasingly flow via direct manufacturer relationships with cooperatives.
- Herbicides:Glyphosate-based formulations dominate vineyard and orchard floor management, with demand concentrating in the O'Higgins and Maule valleys where mechanical harvesting requires weed-free alleys. SAG residue compliance mandates are compressing pre-harvest intervals and driving formulation turnover toward lower-toxicity alternatives.
- Insecticides:Organophosphate and pyrethroid chemistries face EPA reregistration pressure, with chlorpyrifos-based products under particular scrutiny in stone fruit operations. RNA interference biocontrols are penetrating table grape export operations despite premium positioning.
- Fungicides:Azole and strobilurin combinations anchor powdery mildew programs in cherry and table grape production.
- Pesticides:Broad-spectrum synthetic formulations are yielding share to Bacillus thuringiensis-based biologicals in phytosanitary-sensitive export corridors.
By volume, herbicides lead. By growth pace, biological pesticides are climbing the fastest.
Application:
Cost tier differentiation separates precision-intensive fruit export operations from lower-input forestry and turf segments, with agricultural production commanding premium formulation pricing.
- Agricultural Production:Export-oriented table grape and cherry operations in the Atacama, Coquimbo, O'Higgins, and Maule regions drive demand for residue-compliant chemistry with documented spray records. FDA and EFSA import standards enforce strict maximum residue limits that reshape product portfolios seasonally.
- Horticulture:Protected cultivation in the central valley requires integrated pest management protocols combining biological and synthetic tools.
- Forestry:Pine and eucalyptus plantations in the Biobío and Araucanía regions utilize lower-cost herbicide programs with less stringent residue documentation.
- Turf Management:Golf course and landscape maintenance in Santiago metropolitan area represents a niche, price-sensitive segment.
Agricultural production captures the dominant value share; horticulture applications are expanding most quickly amid protected cultivation investment.
End User:
Customer type fragmentation creates divergent service models, with cooperatives aggregating volume for direct manufacturer negotiation while individual farmers rely on distributor technical support.
- Farmers:Mid-scale stone fruit growers in Maule are consolidating into cooperative procurement structures to bypass traditional distributor markups and access direct pricing from formulators like Adama Chile SA and BASF SE.
- Agricultural Cooperatives:Volume aggregation in the O'Higgins valley enables spray service integration and centralized residue testing, reducing per-hectare compliance costs for export-oriented members.
- Distributors:Traditional channel players face margin compression as cooperative direct procurement and manufacturer field advisory networks disintermediate their technical service role.
- Research Institutions:INIA and university agronomy programs generate trial data that influences SAG registration pathways and grower adoption of novel biocontrol tools.
Farmers remain the largest user base by volume; agricultural cooperatives are gaining share fastest through consolidation.
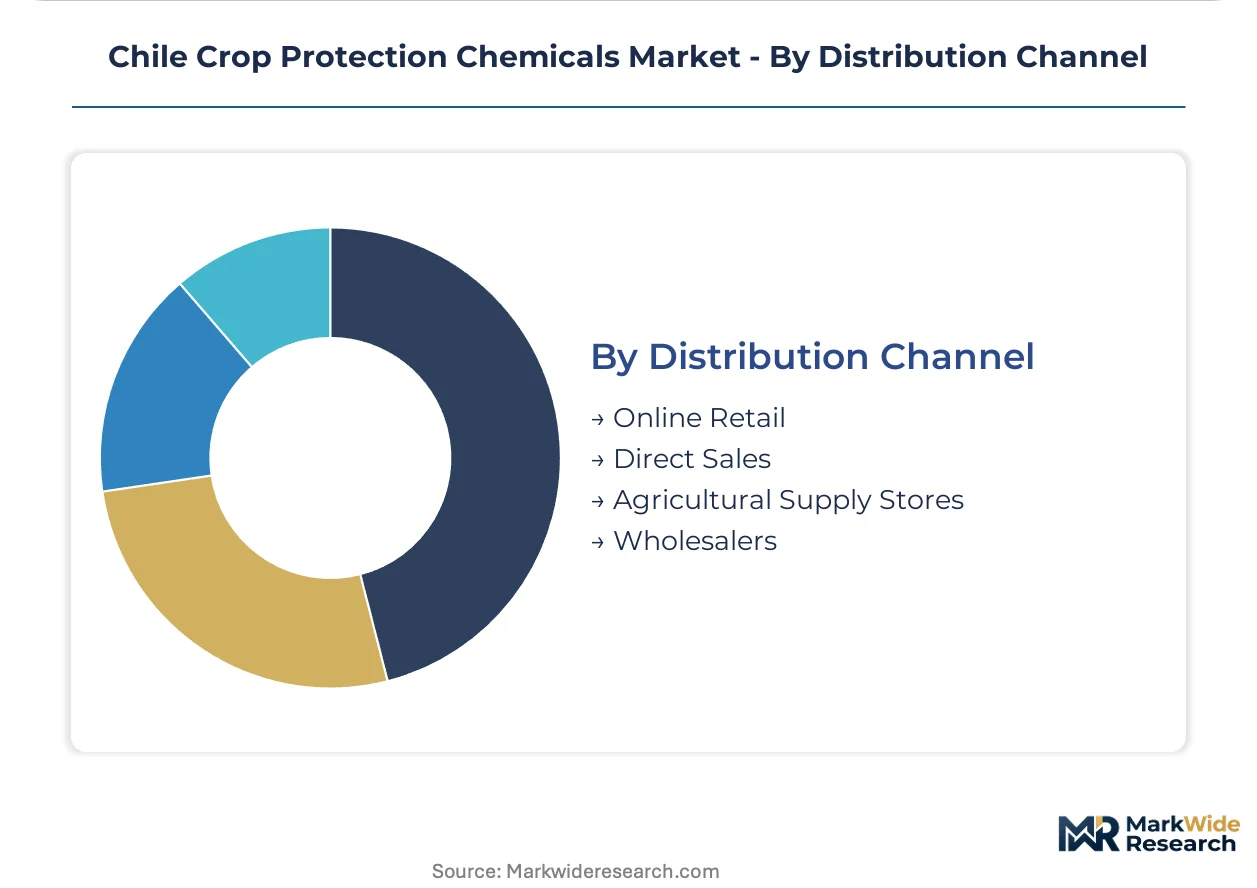
Distribution Channel:
Supply concentration in the central valley shapes channel viability, with direct sales and agricultural supply stores dominating while online retail struggles to replicate technical advisory services.
- Agricultural Supply Stores:Local outlets in O'Higgins and Maule anchor smallholder access to generic herbicides and insecticides, though agronomic technician shortages strain their advisory capacity.
- Direct Sales:Manufacturer field teams from Bayer AG and BASF SE bypass distribution layers to serve large integrated exporters with precision application hardware bundles and digital pest monitoring platforms.
- Wholesalers:Regional distributors face working capital pressure from currency volatility on imported active ingredients and cooperative volume aggregation.
- Online Retail:E-commerce penetration remains limited by the need for technical consultation and SAG documentation requirements that favor physical channel relationships.
Agricultural supply stores lead by transaction volume; direct sales channels are expanding most quickly among export-oriented operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAG enforcement of the National Policy on Pesticides compresses product lifecycles across Chile's central valley export corridors. Regional demand concentrates in fruit-producing valleys where residue compliance mandates reshape procurement patterns.
O'Higgins Valley
Table grape exporters dominate agrochemical procurement in the O'Higgins region. SAG residue testing requirements for Asian market access drive precision spraying hardware adoption. Rancagua anchors spray service consolidation as cooperatives aggregate volume for direct manufacturer contracts.
Maule Valley
Cherry and stone fruit operations in Maule generate concentrated demand for fungicide and insecticide formulations. The National Policy on Pesticides accelerates withdrawal of older chemistries from this production zone. Talca and Curicó host expanding cooperative procurement structures that displace traditional distributor channels.
Atacama Region
Specialty fruit exporters in Atacama face severe irrigation constraints that limit spray window flexibility. Phytosanitary requirements for Chinese and South Korean markets mandate documented spray records and pre-shipment residue testing. Copiapó anchors agrochemical distribution to northern export operations.
Coquimbo Region
Grape and avocado producers in Coquimbo expand biopesticide procurement to meet tightening EFSA-aligned residue limits. Water scarcity concentrates compliance costs around runoff management and buffer zone enforcement. La Serena formulates regional distribution strategy for biological entrants targeting export corridors.
Bío Bío and Araucanía
Forestry plantations in southern zones utilize lower-cost herbicide programs with less stringent residue documentation. Pine and eucalyptus operations generate steady demand for glyphosate-based formulations. Concepción anchors supply chain logistics for chemical distribution to non-export agricultural segments.
Chile Crop Protection Chemicals Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes in Chile's crop protection sector. The market structures around three tiers: multinational formulators with field advisory networks, regional specialists with localized production assets, and generic distributors serving price-sensitive segments. Strategic moves concentrate on cooperative direct procurement bypass and digital pest monitoring platform deployment. Portfolio turnover toward biological alternatives accelerates competitive repositioning.
Within the multinational tier, Bayer AG and BASF SE exemplify technology-forward positioning through precision application hardware bundles and digital farming platforms. Adama Chile SA occupies a cost-leadership position anchored by localized formulation facilities that reduce import dependency. Anasac Chile SA represents the regional specialist archetype with Chile-based operations calibrated to SAG registration pathways and central valley distribution logistics.
| Leading Market Players |
|---|
| Corteva Agriscience |
| Adama Chile SA |
| Bayer AG |
| FMC Corporation |
| Sumitomo Chemical Co., Ltd. |
| BASF SE |
| UPL Ltd. |
| Anasac Chile SA |
| Syngenta Group |
| Others |
Value Chain & Pricing Dynamics
Formulation plant utilization rates in Argentina and Brazil shape regional price floors for Chilean crop protection imports, concentrating supply power among multinational formulators while compressing margins for distributor intermediaries. Scale advantages in active ingredient synthesis outside South America translate directly into tiered pricing leverage across Chile's central valley export corridors.
Pricing Analysis
Geographic price spreads between Santiago metropolitan distributors and Maule valley cooperative buyers reach substantial deltas, with inland freight and technical advisory bundling driving differentiation. Pricing stratifies across premium residue-compliant formulations, standard synthetic chemistries, and economy generic herbicides. Cost compression in the standard tier is intensifying because cooperative volume aggregation bypasses traditional distributor markups. Smallholder farmers in peripheral Atacama zones exhibit highest price sensitivity; large integrated O'Higgins exporters demonstrate lowest sensitivity due to compliance-driven specification lock-in.
Supply Chain Analysis
China, India, and Germany anchor active ingredient production for Chile's formulators, with glyphosate technical and azole fungicide intermediates flowing through maritime corridors to Valparaíso. Domestic formulation capacity draws from imported technicals, with local blending operations in Rancagua and Talca reducing finished product import dependency. Single-source vulnerability concentrates in organophosphate reregistration uncertainty, where EPA tolerance reviews threaten label continuity for cherry and stone fruit programs. Distribution runs through agricultural supply stores in O'Higgins and Maule, supplemented by direct manufacturer field teams serving cooperative aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital pest monitoring platforms are creating platform-economics inflection in Chile's crop protection sector, with interoperability between sensor networks and spray service providers reshaping value capture. This ecosystem shift favors players controlling data infrastructure over pure chemical suppliers.
For Market Incumbents: Fortify advisory network density in O'Higgins and Maule valleys to defend against cooperative disintermediation. Deepen backward integration into biological formulation capacity to offset synthetic active import exposure. Prioritize SAG registration pathway expertise as a moat against generic entrants facing accelerated biopesticide timelines. For New Entrants and Emerging Players: Anchor in biological-compatible adjuvant development, where tank-mix stability gaps with Bacillus thuringiensis products create immediate white space. Target cooperative procurement consolidation in Maule as the most penetrable channel, leveraging direct pricing negotiations to bypass entrenched distributor relationships. Pursue spray-service bundling as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors digital farming platform operators with established pheromone trap networks and AI-driven population forecasting capabilities. Long-term viability rests on controlling data layers that enable just-in-time spraying adoption across Chile's export-oriented fruit zones. Watch cooperative procurement volume thresholds as the inflection signal indicating distributor displacement momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biological Formulation | Captures margin from imported actives while aligning with SAG accelerated registration pathways. |
| Digital Pest Monitoring Platform Deployment | Enables population-threshold-triggered applications that displace calendar-spray programs in table grape operations. |
| Cooperative Direct Procurement Partnership | Bypasses distributor markups in Maule and O'Higgins valleys where volume aggregation accelerates. |
| Residue Testing Infrastructure Investment | Resolves SAG-certified laboratory bottlenecks that delay export clearance during peak harvest windows. |
| Precision Application Hardware Bundling | Locks in large integrated exporters through GPS-guided sprayer and variable-rate nozzle integration. |
Study Parameters
Operator-level perspectives from agronomic technicians, cooperative procurement managers, SAG registration officials, and distributor supply chain leads anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SAG pesticide registration databases, Chilean customs import records, and INIA agronomic trial publications. Bottom-up volume modeling triangulated against top-down value estimates derived from cooperative procurement aggregation patterns and manufacturer field advisory network scale.
Sensitivity analysis tested forecast robustness across regulatory acceleration scenarios and currency volatility bands over the projection horizon. Segmentation dimensions modeled include product type, application intensity tier, end-user scale archetype, and regional production zone regulatory cluster. CAGRs derived from compound growth trajectory fitting to historical import volume patterns and cooperative procurement expansion rates. Industry-specific inputs incorporated SAG biopesticide approval velocity and EPA reregistration uncertainty timelines.
Material uncertainties — EPA organophosphate tolerance revisions, maritime logistics disruptions affecting active ingredient flows, and cooperative procurement consolidation velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding SAG enforcement continuity and Asian market phytosanitary standard stability. Recalibration cycles align with material shifts in residue limit harmonization and precision spraying hardware penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Crop Protection
Miticides Market
Crop Protection
Asia Pacific Herbicide Market
Crop Protection
India Crop Protection Chemicals Market
Crop Protection
Russia Crop Protection Chemicals Market
Crop Protection
Sweet Potato Fly Market
Crop Protection
Asia-Pacific Crop Protection Chemicals Market
Crop Protection
Larvicides Market
Crop Protection
North America Insecticide Market
Crop Protection
Indonesia Fungicide Market
Crop Protection
Indonesia Crop Protection Chemicals Market
Crop Protection
Europe Fungicide Market
Crop Protection
Fumigation Market
Crop Protection
South Korea Crop Protection Chemicals Market
Crop Protection
Vietnam Fungicide Market
Crop Protection
Global Insect Growth Regulators Market
Crop Protection
Grape Fungicides Market