
 North America Corrugated Boxes Market | 2026-2036
North America Corrugated Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Corrugated Boxes Market Intelligence
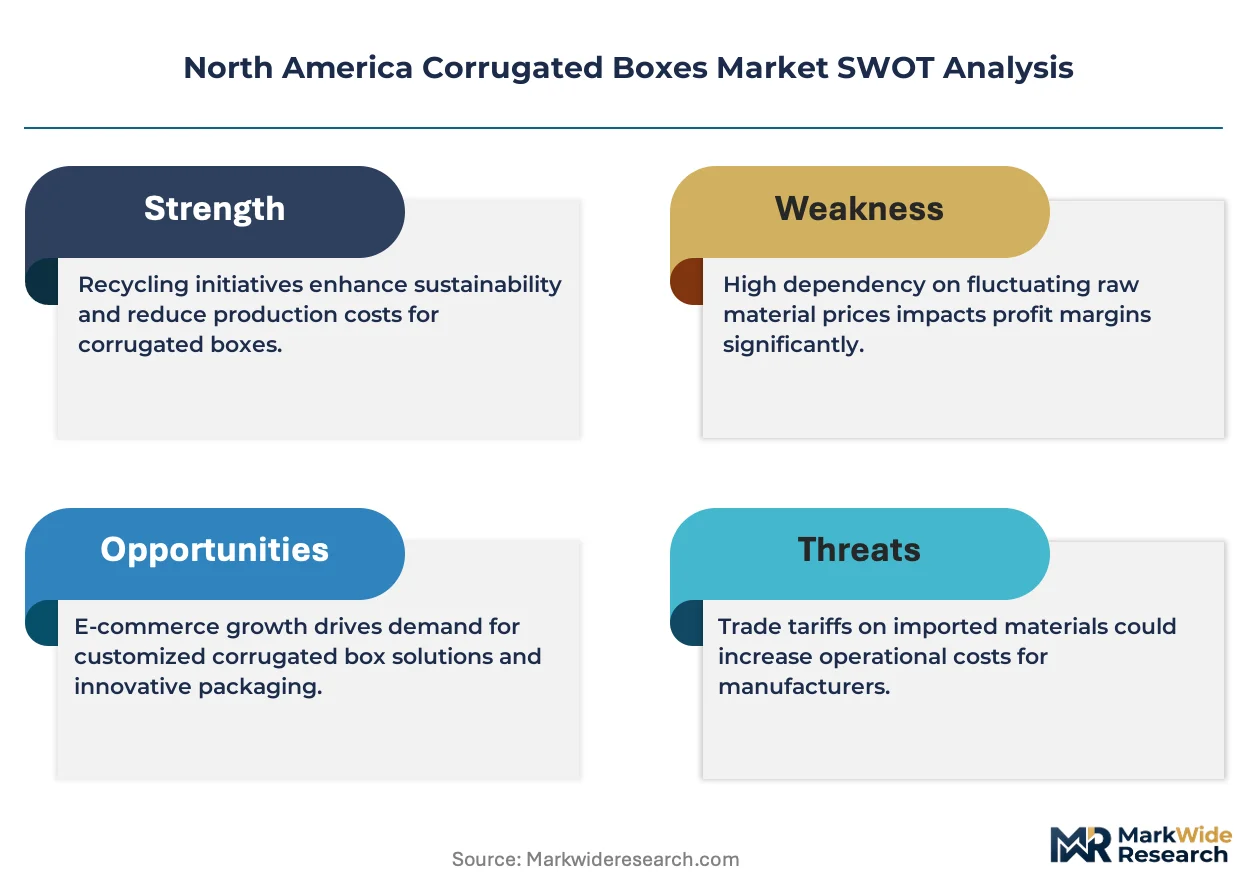
The divergence between premium branded packaging and commodity shipping boxes is realigning procurement strategies across North America. International Paper leverages its integrated pulp-to-box network to control cost positions in bulk segments. WestRock Company differentiates through coated and printed containerboard grades targeting consumer-facing shelf applications. Packaging Corporation of America anchors its footprint with lightweighting R&D focused on e-commerce void reduction.
Corrugated boxes are paper-based containers manufactured from fluted medium sandwiched between linerboard facings, with burst strength, edge crush test ratings, and basis weight defining performance grades for stacking, printing, and protection requirements. Regular Slotted Container formats dominate volume throughput in automated fulfillment centers, while Die-Cut Boxes command margin pools in electronics and personal care where unboxing experience drives brand equity. C Flute constructions sustain broad adoption across food and beverage applications for their balance of cushioning and printability.
The US EPA, California's CalRecycle, and Canada's Competition Bureau collectively shape North American corrugated markets through recycled fiber thresholds, extended producer responsibility programs, and greenwashing enforcement on sustainability claims. FDA compliance for direct food contact applications adds a secondary compliance layer for dairy and produce shippers. Stakeholders must monitor how state-level packaging EPR legislation fragments procurement standards across provincial and state boundaries.
Market Dynamics
E-commerce fulfillment networks are compressing order-to-delivery windows, forcing corrugated converters to co-locate production capacity within 150 miles of major distribution hubs. This geographic tethering is reshaping capital deployment patterns across the US Southeast and Midwest manufacturing belts.
Growth Catalysts
- California's SB 54 Extended Producer Responsibility:Mandates 30% post-consumer recycled content thresholds by 2032, accelerating investment in domestic fiber recovery infrastructure and closed-loop pulping systems.
- Automated fulfillment center expansion:Amazon, Walmart, and Target distribution networks are standardizing on Regular Slotted Container formats optimized for robotic palletizing and dimensioning systems.
- Food-grade barrier coatings:Fluorochemical-free oil and grease resistant treatments are unlocking direct-contact applications for hot-fill and frozen food segments previously reserved for plastic alternatives.
Market Restraints
- Old corrugated container fiber supply concentration:US domestic OCC recovery rates plateaued at 91%, constraining feedstock availability for mills expanding recycled linerboard capacity.
- Natural gas cost volatility:Drying and pulping operations consume 65-75% of mill energy inputs, exposing margin structures to Henry Hub price swings.
- Rigid plastic substitution in beverage:Polyethylene terephthalate bottles and aluminum cans are capturing single-serve liquid packaging share from gable-top and brick cartons.
Strategic Opportunities
- Mexico nearshoring corridor:Appliance and automotive manufacturers relocating from Asia are creating demand for heavy-duty triple-wall export packaging through Laredo-Nuevo Laredo logistics nodes.
- Digital print direct-to-board:Water-based inkjet systems are collapsing minimum order quantities from 5,000 units to 500, enabling seasonal and promotional SKU proliferation for mid-tier CPG brands.
- USDA BioPreferred program procurement mandates:Federal agency purchasing preferences for certified biobased materials are opening institutional foodservice and military supply channels.
Industry Challenges
- Flexographic prepress technician scarcity:Retirement waves among skilled plate-makers and color specialists are extending new product qualification timelines from two weeks to six weeks.
- Legacy enterprise resource planning integration:Mill scheduling systems from the 1990s require custom middleware to connect with customer EDI platforms, delaying real-time order visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Corrugated Boxes Market |
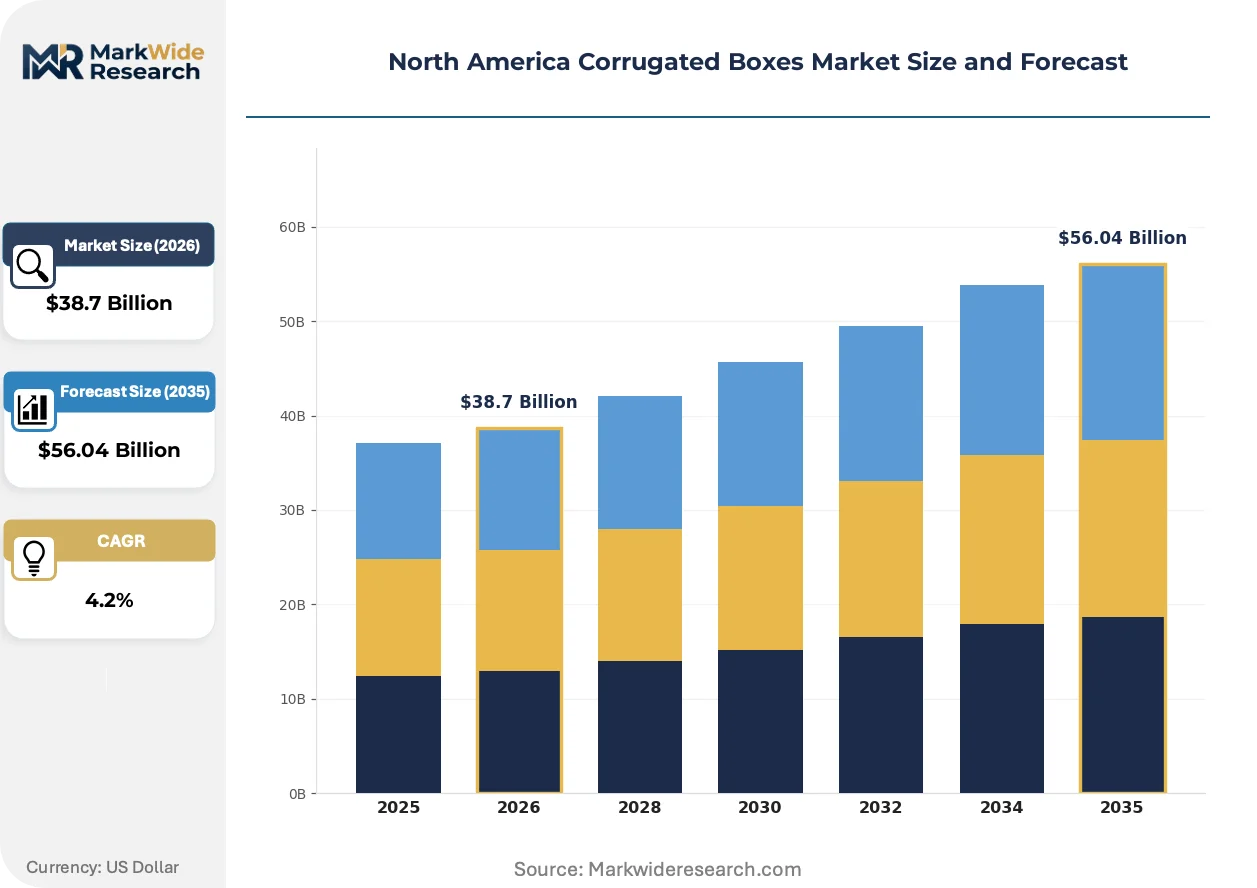
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Slotted Container, Half Slotted Container, Full Overlap Container, Die-Cut Boxes Flute Type: A Flute, B Flute, C Flute, E Flute End User Industry: Food & Beverage, Electronics, Pharmaceuticals, Personal Care Box Style: Single Wall, Double Wall, Custom Boxes, Inserts |
| Companies Covered | International Paper, WestRock Company, Smurfit Kappa, Packaging Corporation of America, Georgia-Pacific, DS Smith, Mondi, Cascades Inc., Pratt Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Corrugated Boxes Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory compliance automation are converging to redefine performance specifications and sourcing protocols across North American corrugated supply chains.
Lightweighting through micro-flute engineering is absorbing structural load requirements previously assigned to heavier C-flute and B-flute constructions. E-commerce shippers of electronics and cosmetics are adopting E-flute and F-flute alternatives to reduce dimensional weight charges and void fill dependency. The technology is absorbing margin pressure from parcel carriers' pricing models while maintaining edge crush test ratings above 32 pounds per inch.
The US EPA's Comprehensive Procurement Guidelines are tightening post-consumer fiber thresholds for federal purchasing contracts. Mills serving government channels must now document chain-of-custody certification through third-party auditors. Food-contact applications face the steepest compliance burden, with dairy and produce shippers reformulating adhesive systems to eliminate wet-strength resin migration risks.
Consolidated buying desks at omnichannel retailers are compressing supplier rosters from twelve corrugated vendors to three or four strategic partners. Target and Costco procurement teams now demand integrated design services, inventory management, and just-in-time delivery guarantees as table stakes. The Southeast US manufacturing corridor exhibits the most pronounced concentration, with Georgia and Carolina-based converters capturing disproportionate share of new contract awards.
North America Corrugated Boxes Market Segmentation
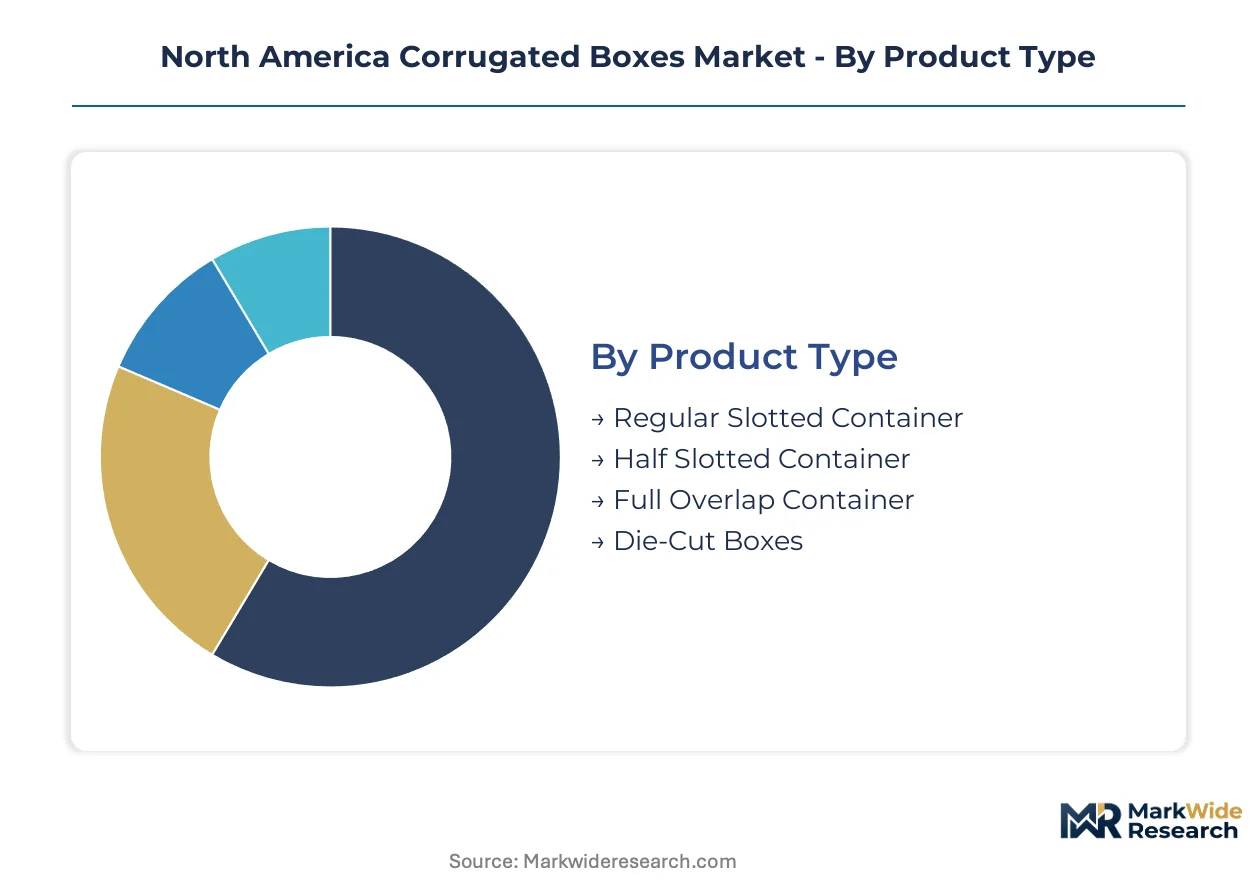
Corrugated box segmentation in North America reflects a bifurcation between high-velocity standardized formats and engineered solutions for protective or branded applications. Procurement teams calibrate specifications across structural performance, printability, and automated handling compatibility to match fulfillment network requirements.
Product Type:
Volume throughput concentrates in formats optimized for mechanized palletizing and case sealing, while premium margins attach to customized structural designs.
- Regular Slotted Container:All flaps meet at the center with equal length, creating the most efficient blank utilization and fastest tape-sealing throughput. Amazon, Walmart, and Target distribution networks have standardized this format for robotic dimensioning systems across their Southeast and Midwest fulfillment hubs.
- Die-Cut Boxes:Precision-cut corrugated blanks eliminate flaps and create self-locking structures for unboxing experience. Demand concentrates in electronics and personal care segments where brand equity justifies per-unit premiums over commodity shipping alternatives.
- Half Slotted Container:Features flaps on one end only, requiring a separate lid or tray for closure. Common in palletized bulk shipments where top access facilitates loading and unloading operations.
- Full Overlap Container:Outer flaps extend fully across the width, providing extra stacking strength for heavy or abrasive contents. Deployed in automotive parts and industrial hardware distribution.
Mature deployment sits with Regular Slotted Container formats across mass retail fulfillment. Newer deployment is concentrated in Die-Cut Boxes as direct-to-consumer brands prioritize packaging as a marketing touchpoint.
Flute Type:
Structural caliper selection balances cushioning requirements against print surface quality and dimensional weight economics in parcel networks.
- C Flute:3.6-4.0mm caliper with 39-43 flutes per linear foot delivers the standard balance of crush resistance and printability. Food and beverage shippers across the US Southeast manufacturing corridor specify this grade for shelf-ready secondary packaging.
- E Flute:1.0-1.8mm micro-flute construction reduces material basis weight while maintaining edge crush ratings above 32 pounds per inch. Cosmetics and electronics e-commerce shippers adopt this format to minimize dimensional weight charges and void fill dependency.
- A Flute:4.7-5.3mm caliper with 33-36 flutes per foot provides maximum cushioning for fragile or heavy items. Appliance and furniture manufacturers specify this grade for damage prevention in long-haul distribution.
- B Flute:2.1-3.0mm caliper offers finer flute count for improved lithographic printing quality. Deployed in retail-ready point-of-sale displays and premium consumer goods packaging.
C Flute maintains the broadest installed base across food and beverage applications. E Flute is expanding most quickly as lightweighting initiatives penetrate e-commerce fulfillment specifications.
End User Industry:
Regulatory compliance thresholds and damage sensitivity create divergent procurement criteria across vertical markets.
- Food & Beverage:FDA-compliant adhesives and fluorochemical-free barrier coatings dominate specifications. Dairy and produce shippers reformulate wet-strength resin systems to eliminate migration risks in direct-contact applications.
- Electronics:Anti-static coatings and precision-fit die-cut structures protect high-value components from shock and electrostatic discharge. California's SB 54 recycled content mandates drive fiber sourcing documentation requirements.
- Pharmaceuticals:Serialization compatibility and tamper-evident closure systems integrate with track-and-trace regulations. Cold chain specifications add insulated liner requirements for temperature-sensitive biologics.
- Personal Care:Shelf appeal through high-graphics printing and structural differentiation supports brand positioning. Unboxing experience drives adoption of premium flute combinations and soft-touch coatings.
Food and Beverage represents the deepest historical penetration with established supply chain protocols. Electronics is gaining share fastest as protective packaging specifications tighten for direct-to-consumer fulfillment.
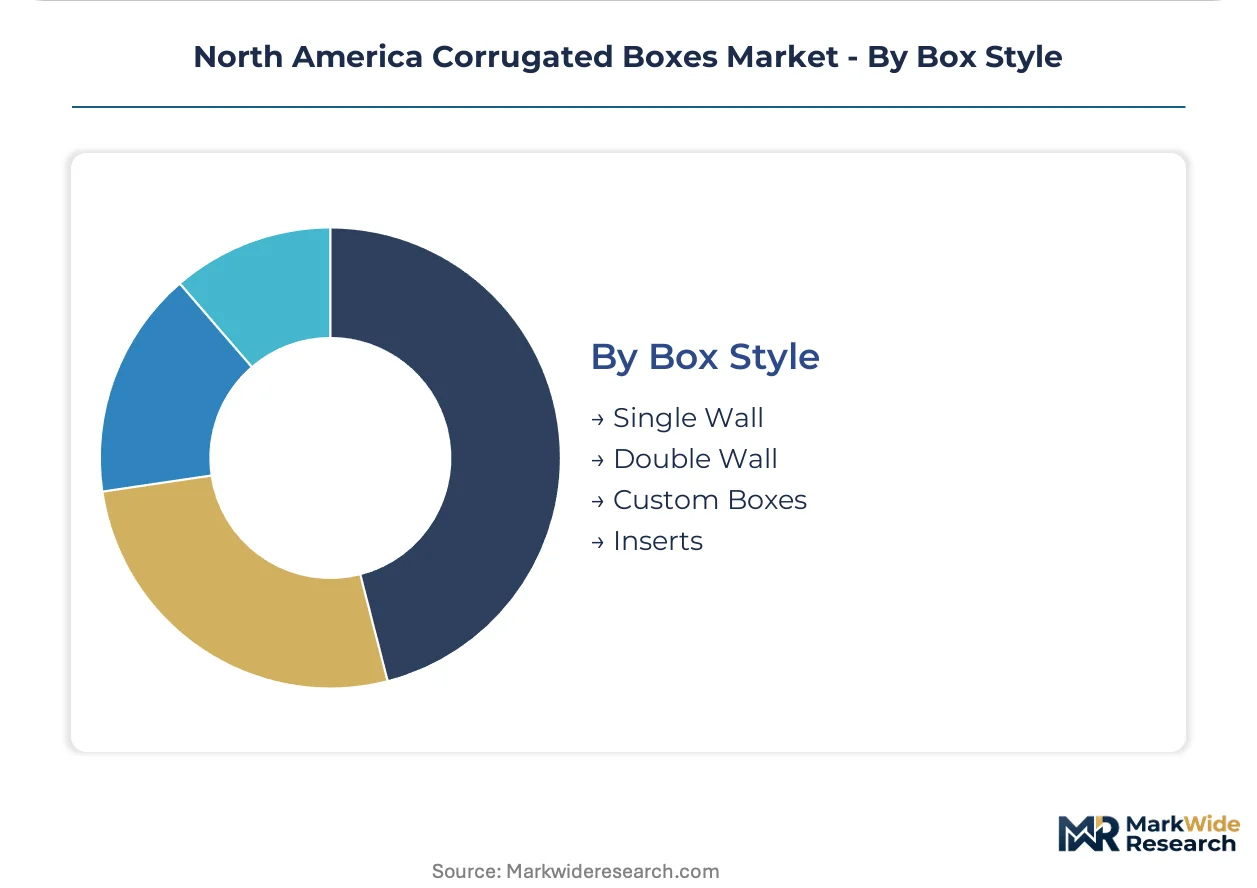
Box Style:
Wall construction and accessory integration address load-bearing requirements and product protection hierarchies.
- Single Wall:One fluted medium between two linerboard facings serves standard-duty applications up to 35 pounds gross weight. Dominates volume throughput in grocery and general merchandise distribution.
- Double Wall:Two fluted layers separated by an intermediate liner provide enhanced stacking strength for warehouse palletization. Heavy-duty consumer electronics and bulk industrial shipments specify this construction.
- Custom Boxes:Engineered structures with proprietary dimensions, cutouts, or reinforcement patterns. Mexico nearshoring corridors for appliance and automotive manufacturers drive demand for heavy-duty triple-wall export configurations.
- Inserts:Internal fitments, dividers, and corner posts immobilize contents within outer containers. Fragile glass and precision instrument shippers specify molded pulp or corrugated insert systems.
Single Wall deployment saturates mainstream retail and grocery logistics. Custom Boxes are climbing the fastest as reshoring initiatives create demand for specialized export packaging through Laredo-Nuevo Laredo logistics nodes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Southeast manufacturing corridor stretching from Georgia through the Carolinas anchors corrugated box production capacity, with converters clustering within 150 miles of Atlanta, Charlotte, and Charleston distribution hubs to serve compressed e-commerce fulfillment windows.
United States
E-commerce fulfillment networks and food-grade barrier coating adoption drive demand across the Southeast and Midwest belts. The EPA's Comprehensive Procurement Guidelines tighten post-consumer fiber thresholds for federal contracts. Georgia and North Carolina-based mills capture disproportionate share of new retail procurement awards through co-located design services.
Canada
Cold chain pharmaceutical logistics and agricultural export packaging sustain demand in Ontario and Quebec corridors. Health Canada and PMRA compliance requirements for food-contact adhesives shape specification standards. Cascades Inc. anchors Quebec's fiber recovery infrastructure with closed-loop pulping systems serving institutional foodservice channels.
Mexico
Appliance and automotive nearshoring from Asia creates demand for heavy-duty triple-wall export configurations through Laredo-Nuevo Laredo logistics nodes. Mexico's environmental ministry implements extended producer responsibility frameworks aligned with US EPA recycled content benchmarks. Nuevo León and Bajío Region converters expand capacity to serve cross-border manufacturing parks.
North America Corrugated Boxes Market Key Industry Players
Premium-margin players sit above commodity-margin players across coating technology and direct-to-board digital print capabilities. The North American corrugated box market structures around three tiers: integrated pulp-to-box operators controlling fiber costs, specialty converters capturing brand-equity premiums, and regional independents serving localized just-in-time delivery requirements. Strategic differentiation concentrates on lightweighting R&D and automated fulfillment format standardization. Consolidated buying desks at omnichannel retailers compress supplier rosters, while Mexico nearshoring corridors attract capacity expansion investments.
Among integrated North American operators, International Paper, WestRock Company, and Packaging Corporation of America occupy positions across the cost-control and premium-format spectrum. International Paper exemplifies the fiber-integrated archetype with captive pulp supply chains. WestRock Company represents coated and printed containerboard specialization for consumer-facing applications. Packaging Corporation of America anchors lightweighting R&D focused on e-commerce void reduction. These three entities collectively illustrate how scale, vertical fiber control, and format engineering define competitive positioning in automated fulfillment procurement.
| Leading Market Players |
|---|
| International Paper |
| WestRock Company |
| Smurfit Kappa |
| Packaging Corporation of America |
| Georgia-Pacific |
| DS Smith |
| Mondi |
| Cascades Inc. |
| Pratt Industries |
| Others |
Cost & Logistics Intelligence
Old corrugated container fiber costs cascade through three distinct pricing tiers, with integrated mills commanding margin buffers unavailable to independent converters facing spot market volatility for linerboard feedstock. Henry Hub natural gas price swings transmit directly to drying and pulping energy expenditures, forcing procurement desks at omnichannel retailers to consolidate vendor rosters and demand volume guarantees in exchange for contract stability.
Pricing Analysis
Throughput-based pricing anchors corrugated box valuation, with per-unit rates scaling to edge crush test performance grades and automated handling compatibility rather than commodity paper tonnage alone. Price differentiation separates FDA-compliant food-grade specifications from standard-duty shipping grades, while California's SB 54 recycled content mandates add certification premiums for documented post-consumer fiber chain-of-custody. Pricing pressure stems from consolidated buying desks at Target and Costco compressing supplier margins through integrated design service demands. Mid-tier CPG brands exhibit highest price sensitivity as digital print minimum order quantity collapse enables smaller-batch sourcing flexibility.
Supply Chain Analysis
FDA food-contact and EPA Comprehensive Procurement Guidelines certification gating restricts viable supplier pools, particularly for dairy and produce shippers reformulating adhesive systems to eliminate wet-strength resin migration risks. Geographic supply concentration centers on the US Southeast manufacturing corridor from Georgia through the Carolinas, with Ontario and Quebec corridors serving Canadian cold chain pharmaceutical and agricultural export packaging. Raw material dependencies include domestic OCC fiber recovery plateaued at 91% availability, natural gas for mill energy inputs, and fluorochemical-free barrier coating chemicals. Single-source vulnerability concentrates in flexographic prepress technician scarcity extending new product qualification timelines. Distribution runs through co-located converter capacity within 150 miles of major distribution hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from omnichannel retailer vendor roster compression is eliminating sub-scale converters unable to deliver integrated design services and just-in-time guarantees.
For Market Incumbents: Anchor market position through captive fiber recovery infrastructure and closed-loop pulping systems serving California SB 54 compliance requirements. Defend against rigid plastic substitution in beverage packaging by accelerating fluorochemical-free barrier coating R&D for direct-contact hot-fill applications. Prioritize lightweighting R&D investment in E-flute and F-flute micro-flute engineering to capture e-commerce dimensional weight reduction demand. For New Entrants and Emerging Players: Mid-tier CPG brands with seasonal SKU proliferation needs represent the most penetrable buyer archetype as digital print direct-to-board technology collapses minimum order quantities from 5,000 units to 500. Target Mexico nearshoring corridors through Laredo-Nuevo Laredo logistics nodes where appliance and automotive manufacturers relocating from Asia create demand for heavy-duty triple-wall export packaging. Lead with water-based inkjet design services as the go-to-market wedge against legacy flexographic prepress bottlenecks. For Investors and Strategic Acquirers: California SB 54 recycled content threshold enforcement accelerating domestic fiber recovery infrastructure investment is the leading indicator that integrated pulp-to-box operators will capture disproportionate share of compliance-driven contract migration. Long-term viability favors entities with vertical fiber control and automated fulfillment format standardization capabilities. Target acquisition profiles center on regional independents with 150-mile proximity to Southeast US distribution hubs and stranded design service assets. Watch for inflection in Amazon, Walmart, and Target distribution network expansion announcements as capacity co-location demand signals.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Fiber Recovery Infrastructure | California SB 54 mandates 30% post-consumer thresholds by 2032, requiring captive OCC pulping systems. |
| Digital Print Direct-to-Board Capability | Water-based inkjet systems collapse MOQs and enable seasonal SKU proliferation for mid-tier CPG brands. |
| Micro-Flute Lightweighting R&D | E-flute and F-flute engineering reduces dimensional weight charges while maintaining edge crush ratings above 32 pounds per inch. |
| Mexico Nearshoring Corridor Capacity | Appliance and automotive manufacturing relocation from Asia drives heavy-duty triple-wall export packaging demand through Laredo-Nuevo Laredo nodes. |
| Fluorochemical-Free Barrier Coating Development | FDA-compliant oil and grease resistant treatments unlock direct-contact applications for hot-fill and frozen food segments. |
Research Approach
Trade association filings, EPA procurement guideline documentation, and SEC 10-K disclosures from integrated paper and packaging operators formed the secondary backbone of this analysis. Primary interviews with corrugated converters, procurement managers at omnichannel retailers, flexographic prepress technicians, and mill operations directors validated demand patterns and capacity utilization assumptions. Bottom-up segmentation modeling across product type, flute construction, end-use industry, and box style dimensions was cross-checked against top-down macroeconomic indicators and trade flow data.
Historical trendline analysis of linerboard pricing, OCC fiber recovery rates, and e-commerce fulfillment center expansion patterns informed the projection framework. Segmentation dimensions modeled include structural format, flute caliper, end-use vertical, wall construction, and geographic manufacturing cluster. CAGRs were derived from regression analysis of volume and value trajectories across the projection horizon, incorporating natural gas cost volatility scenarios and recycled content mandate compliance timelines as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Henry Hub price volatility, state-level packaging EPR legislation fragmentation, and flexographic prepress technician labor market tightness. Forecasts reflect assumptions documented in the analysis framework without guarantee of realization. A model refresh is warranted upon material change in California SB 54 enforcement intensity or Amazon, Walmart, and Target distribution network expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Carton Form Fill Seal Machine Market
Cartons
Tuck Top Box Market
Cartons
Brick Carton Packaging Market
Cartons
Indonesia Folding Carton Packaging Market
Cartons
Cardboard Crates Market
Cartons
Pick and Place Carton Packers Market
Cartons
Global Beverage Carton Packaging Machinery Market
Cartons
Folding Carton in Healthcare Market
Cartons
XXL Packaging Market
Cartons
Carton Sealer Machine Market
Cartons
Brick Liquid Carton Market
Cartons
Carton Sealer Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Luxury Folding Carton Market
Cartons
Shaped Corrugated Packaging Market
Cartons
Mailers Market