
 Luxury Folding Carton Market | 2026-2036
Luxury Folding Carton Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Folding Carton Market Outlook
Digital print-to-pack workflows is tilting production economics toward shorter runs with variable embellishment. Mondi plc leverages its European pulp-to-paperboard chain to sustain margin control across specialty grades. WestRock Company anchors North American supply through integrated containerboard and converting assets. Smurfit Kappa Group competes on recycled-content certification programs that align with retailer sustainability mandates.
A luxury folding carton is a rigid paper-based package typically constructed from coated solid bleached sulfate board ranging from 300 to 600 gsm, formed through die-cutting, creasing, and adhesive or mechanical closure to protect and present high-value consumer goods. Its primary commercial purpose is to merge structural protection with tactile surface finishes—embossing, foil stamping, soft-touch lamination—that signal brand equity at point of sale. Paperboard grades command the dominant share of material value, while magnetic closure formats capture expanding share in cosmetics and electronics as unboxing experience becomes a purchase driver. Digital printing represents the fastest-growing print technology segment, enabling versioning for limited releases without plate costs that gravure and offset impose.
FDA food-contact substance notifications govern board coatings and adhesives for luxury cartons entering US commerce, while REACH and the EU Packaging and Packaging Waste Regulation restrict substances and mandate recyclability targets across European supply chains. EMA and national cosmetics regulators in France and Germany impose secondary packaging labeling requirements that directly influence carton surface design and print area allocation. Stakeholders must monitor evolving extended producer responsibility schemes and substrate certification thresholds as these rules increasingly determine supplier qualification and format approval timelines.
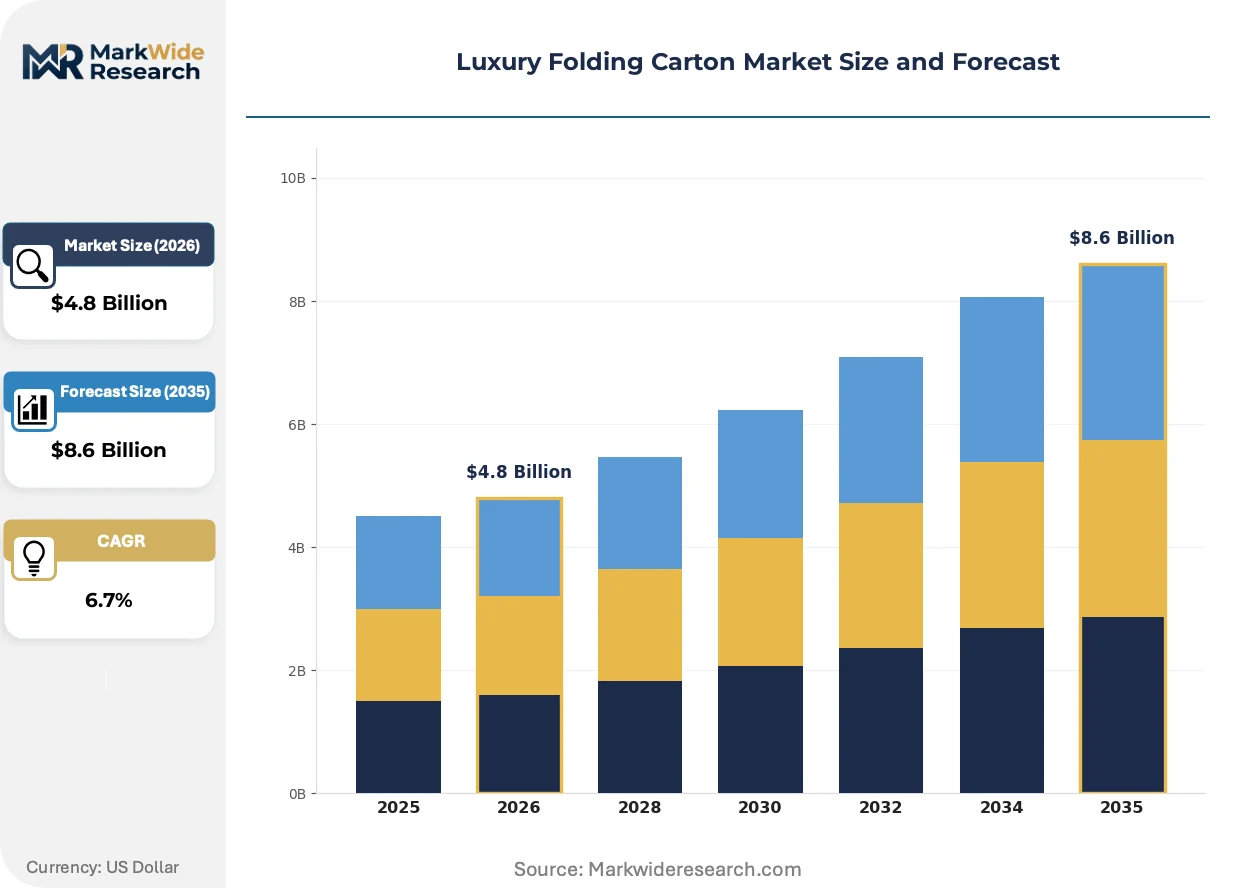
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material substitution across European supply chains, compressing lead times for certified recyclable substrates while fragrance houses in France and Germany accelerate format approvals for high-converting folding carton specifications.
Growth Catalysts
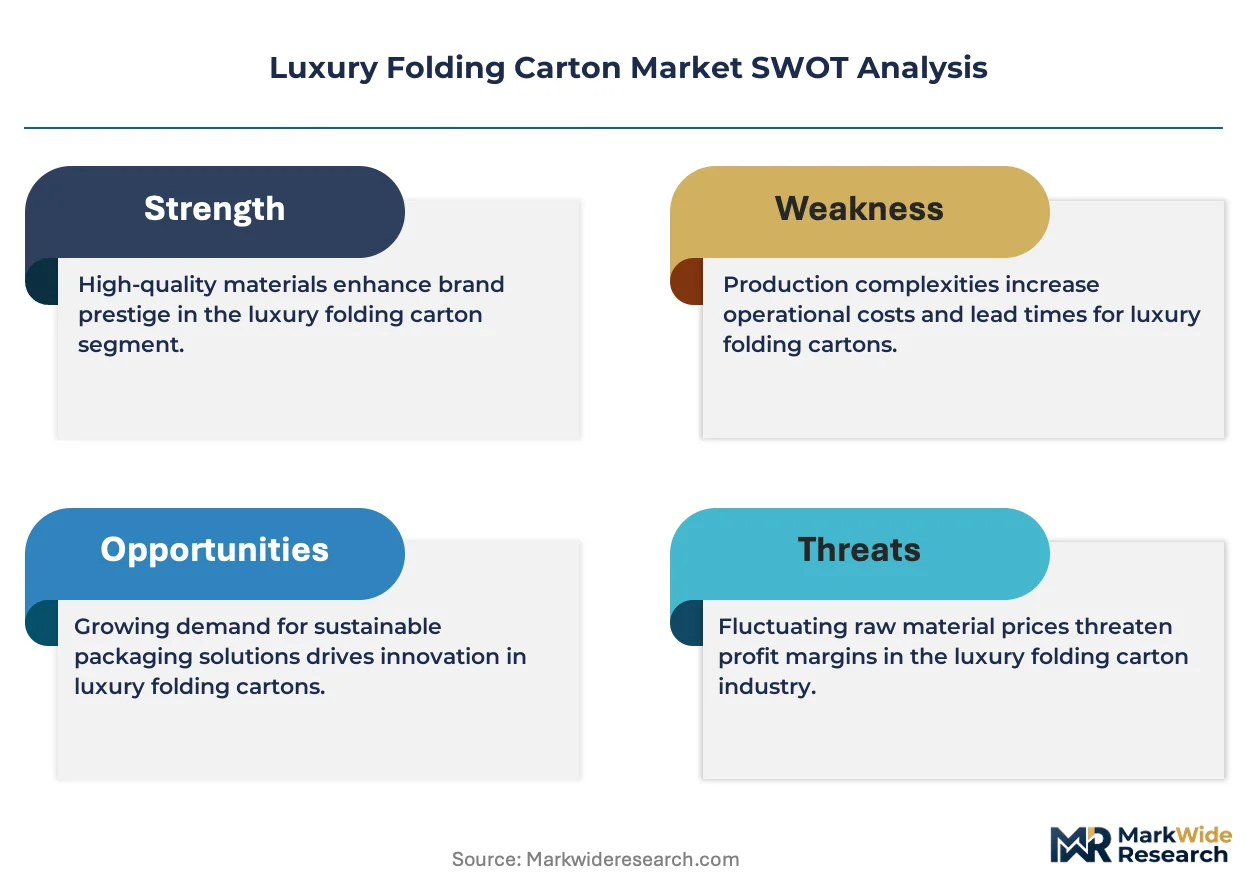
- EMA cosmetics labeling mandates:Secondary packaging requirements in France and Germany expand print area allocation for regulatory information, increasing premium carton surface complexity and value per unit.
- Magnetic closure adoption:Unboxing experience demands from cosmetics and electronics brands are displacing conventional tuck-end formats with rigid mechanical closures that command higher converting margins.
- Solid bleached sulfate board availability:Integrated European pulp-to-paperboard supply chains sustain specialty grade production for 300-600 gsm coated substrates serving luxury applications.
Market Restraints
- Pulp cost volatility:Northern European softwood pulp pricing fluctuations compress margin predictability for coated solid bleached sulfate board producers serving fragrance and skincare segments.
- REACH substance restrictions:Board coatings and adhesives face compliance friction entering European commerce, extending supplier qualification timelines for US and Asian converters.
- Rigid plastic substitution:Premium electronics brands in Asia-Pacific are piloting molded fiber and bio-based rigid formats that compete with paperboard for structural protection applications.
Strategic Opportunities
- CSRD disclosure alignment:European corporate sustainability reporting mandates create certification-driven demand for recycled-content folding cartons with chain-of-custody documentation.
- Digital embellishment convergence:Variable data printing combined with tactile finishing technologies enables limited-release versioning without gravure plate investment.
- German skincare export growth:Frankfurt and Hamburg-based contract manufacturers are sourcing high-converting formats for third-party logistics distribution into Middle Eastern duty-free channels.
Industry Challenges
- Extended producer responsibility scheme complexity:Divergent national implementation timelines across EU member states fragment compliance resource allocation for multi-market suppliers.
- Die-cutting tooling capex intensity:Magnetic closure and complex window formats require specialized steel-rule die investment that strains mid-cap converting operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Folding Carton Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Paperboard, Kraft, Specialty Paper, Recycled Material Application: Cosmetics, Beverages, Food Packaging, Electronics Print Technology: Offset Printing, Flexographic Printing, Digital Printing, Gravure Printing Closure Type: Locking Bottom, Tuck Flap, Seal End, Magnetic Closure |
| Companies Covered | Mayr-Melnhof Karton AG, Mondi plc, WestRock Company, Huhtamaki, DS Smith Plc, Smurfit Kappa Group, Graphic Packaging International, Diamond Packaging, International Paper Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Folding Carton Market Strategic Shifts
Digital production workflows are compressing minimum order quantities while regulatory pressure on substrate certification accelerates material innovation across European and North American supply chains.
HP Indigo and comparable electrophotographic presses are digitizing short-run luxury carton production by eliminating plate costs and enabling same-day proof-to-production cycles. Premium cosmetics brands in France now release monthly limited editions with region-specific embellishment that would be uneconomical under offset or gravure economics. This capability is digitizing the traditional volume-moat advantage of large integrated converters, allowing specialized finishers to capture versioning business from multinational fragrance houses.
REACH substance restrictions and the EU Packaging and Packaging Waste Regulation are mandating recyclability targets that eliminate certain laminated barrier coatings from cosmetic folding cartons. German converters are accelerating water-based coating substitution and mono-material substrate development to maintain market access. Fragrance houses sourcing from Smurfit Kappa and Mondi supply chains are prioritizing FSC-certified solid bleached sulfate grades with established fiber recovery pathways.
Unboxing content creation has elevated packaging from protective function to media asset, with magnetic closure formats and soft-touch lamination becoming non-negotiable for premium skincare launches. German and French brands now specify haptic specifications that require specialized converting equipment and extend supplier qualification periods. This behavior concentrates procurement among converters with captive finishing capabilities, compressing the vendor base for high-complexity formats.
Luxury Folding Carton Market Segmentation
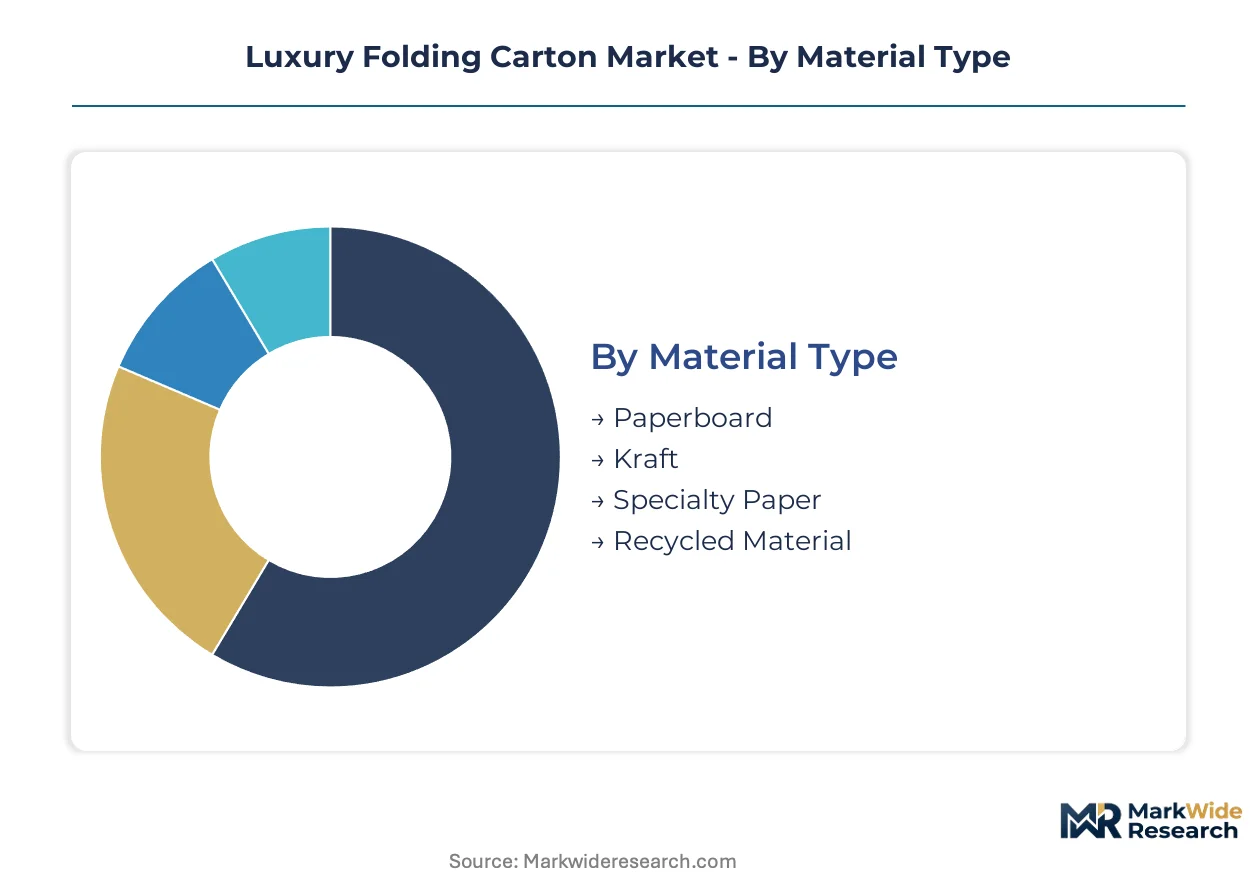
Material specifications and closure mechanics determine supplier qualification timelines for fragrance houses and skincare labels. Print technology selection governs minimum order economics and versioning flexibility across European and North American supply chains.
Material Type:
Coated substrates span protective performance requirements from fragrance oils to moisture-sensitive electronics.
- Paperboard:Solid bleached sulfate grades ranging 300-600 gsm provide the structural rigidity and surface receptivity for embossing and foil stamping. French fragrance houses specify coated SBS for high-definition print reproduction and tactile finishing compatibility.
- Specialty Paper:Textured and metallized substrates incorporate in-fiber visual effects that reduce post-print embellishment steps. German skincare brands source cotton-fiber and laid-finish papers for organic positioning and unboxing differentiation.
- Kraft:Unbleached brown stock serves sustainability-positioned beverage and food applications with visible fiber content signaling recyclability.
- Recycled Material:Post-consumer fiber grades certified to FSC or comparable chain-of-custody standards align with retailer sustainability mandates and CSRD disclosure requirements.
The dominant share belongs to Paperboard, while Recycled Material is closing the gap fastest.
Application:
End-use sectors impose divergent regulatory and haptic specifications that shape converting investment priorities.
- Cosmetics:Secondary packaging for fragrance and skincare commands the highest value per unit through multi-stage finishing and magnetic closure integration. EMA labeling mandates in France and Germany expand required print area, increasing surface complexity.
- Electronics:Rigid structural protection for premium devices emphasizes unboxing choreography and anti-tamper features. Asia-Pacific brands pilot molded fiber alternatives that compete for share in structural applications.
- Beverages:Gift and limited-edition formats for spirits and champagne require moisture-resistant coatings and high-converting window specifications.
- Food Packaging:Premium confectionery and specialty foods drive FDA food-contact compliance for board coatings and adhesives entering US commerce.
Cosmetics captures the highest margin concentration, with Electronics expanding most quickly as unboxing content creation elevates packaging to media asset status.
Print Technology:
Plate economics and run-length thresholds segment converter capabilities across versioning and mass-production requirements.
- Digital Printing:Electrophotographic and inkjet systems eliminate plate costs and enable same-day proof-to-production cycles. French cosmetics brands release monthly limited editions with region-specific embellishment uneconomical under analog processes.
- Offset Printing:Sheet-fed lithography dominates long-run premium work with consistent color matching across large fragrance and beverage campaigns.
- Gravure Printing:Cylinder-based systems sustain the highest-volume cosmetic and tobacco applications with superior ink laydown on coated stocks.
- Flexographic Printing:Water-based and UV-curable flexo serves mid-volume folding carton work with faster makeready than offset for shorter runs.
Offset retains volume leadership, though Digital Printing is gaining share fastest as brand versioning accelerates and run lengths compress.
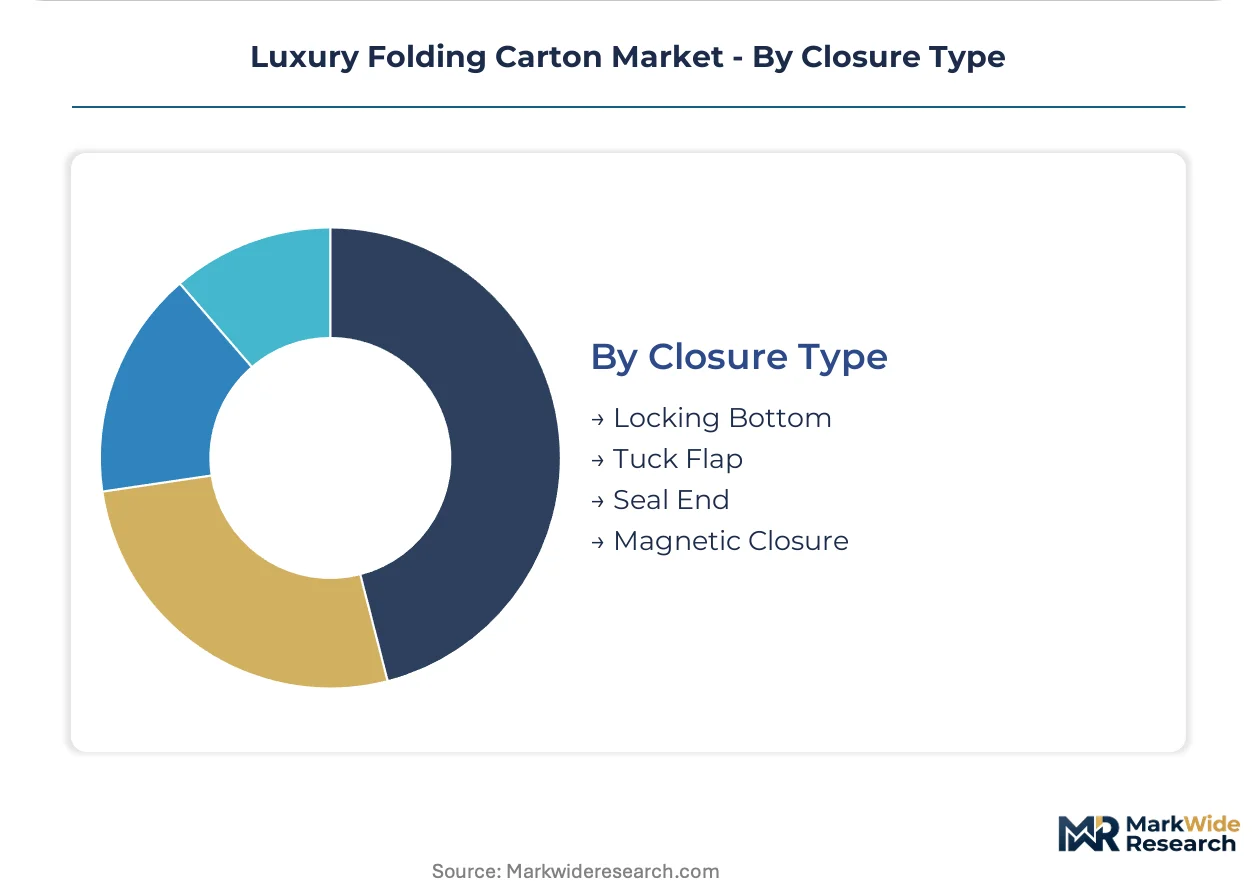
Closure Type:
Mechanical opening experiences differentiate premium positioning and influence die-cutting tooling investment.
- Magnetic Closure:Embedded neodymium or ferrite magnets create rigid box structures with satisfying tactile release. German and French skincare brands specify haptic requirements that extend supplier qualification periods and concentrate procurement among converters with captive finishing capabilities.
- Tuck Flap:Conventional friction-fit closures sustain mass-market cosmetics and food applications with lower converting complexity and faster production throughput.
- Locking Bottom:Auto-bottom or crash-lock bases provide structural integrity for heavier contents without adhesive application, common in beverage and electronics formats.
- Seal End:Adhesive-sealed closures offer tamper evidence and clean aesthetic lines for premium fragrance and gift applications requiring security assurance.
Tuck Flap maintains the broadest installed base, yet Magnetic Closure is climbing the fastest as unboxing experience becomes a non-negotiable purchase driver.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fragrance houses and premium cosmetics brands concentrate procurement among converters with captive finishing capabilities in France and Germany. Electronics manufacturers in Asia-Pacific pilot molded fiber alternatives that compete for structural protection applications. North American beverage and confectionery brands drive FDA food-contact compliance requirements for coated board substrates.
France
Paris-based fragrance houses specify coated solid bleached sulfate grades for high-definition print reproduction and tactile finishing compatibility. EMA cosmetics labeling mandates expand required print area allocation on secondary packaging, increasing surface complexity per unit. Grasse and Île-de-France clusters source magnetic closure formats with soft-touch lamination for unboxing content creation.
Germany
Frankfurt and Hamburg contract manufacturers source high-converting folding carton formats for third-party logistics distribution into Middle Eastern duty-free channels. REACH substance restrictions eliminate certain laminated barrier coatings, accelerating water-based coating substitution among domestic converters. Bavarian and North Rhine-Westphalia finishing operations concentrate procurement for skincare brands specifying haptic requirements.
United States
Premium cosmetics and electronics brands in New York and California drive demand for rigid paperboard packaging with unboxing choreography features. FDA food-contact substance notifications govern board coatings and adhesives entering US commerce, extending supplier qualification timelines. Midwest converting operations anchor North American supply through integrated containerboard assets serving fragrance and skincare segments.
China
Shanghai and Shenzhen electronics brands pilot molded fiber and bio-based rigid formats competing with paperboard for structural protection applications. SAMR and GB standards regulate packaging material safety for consumer goods entering domestic and export channels. Yangtze River Delta and Pearl River Delta manufacturing clusters evaluate mono-material substrate development for premium device packaging.
Japan
Tokyo and Osaka cosmetics brands specify magnetic closure formats with specialized die-cutting requirements for limited-edition skincare launches. METI guidelines influence sustainable packaging material selection among domestic fragrance houses and beauty retailers. Kanto region converting operations serve premium unboxing experience demands from electronics and luxury goods manufacturers.
Luxury Folding Carton Market Competitive Environment
Channel-controlling players compete with product-specialist players across integrated pulp-to-paperboard supply chains and captive finishing capabilities. The vendor base spans multinational paperboard producers with European and North American converting networks alongside regional specialists with mono-material certification expertise. Three archetypes dominate: integrated pulp-to-packaging conglomerates with specialty grade control, mid-cap converters with digital embellishment convergence, and sustainability-certified specialists with chain-of-custody documentation. Competitive moves concentrate on recycled-content certification programs and magnetic closure format tooling investment.
Within the integrated conglomerate tier, Mayr-Melnhof Karton AG and Mondi plc exemplify European pulp-to-paperboard supply chain control. WestRock Company anchors North American market presence through integrated containerboard and converting assets. Among sustainability-certified specialists, Smurfit Kappa Group occupies a position aligned with retailer mandates and CSRD disclosure requirements.
| Leading Market Players |
|---|
| Mayr-Melnhof Karton AG |
| Mondi plc |
| WestRock Company |
| Huhtamaki |
| DS Smith Plc |
| Smurfit Kappa Group |
| Graphic Packaging International |
| Diamond Packaging |
| International Paper Company |
| Others |
Value Chain & Pricing Dynamics
REACH substance restrictions and the EU Packaging and Packaging Waste Regulation function as a regulatory chokepoint that widens pricing tier spreads between FSC-certified and uncertified substrates while compressing supplier qualification timelines for converters serving French and German fragrance houses.
Pricing Analysis
Cost-plus contracts indexed to Northern European softwood pulp benchmarks govern long-term supply agreements for coated solid bleached sulfate board. Pricing stratifies across FSC-certified premium grades, standard recyclable substrates, and economy kraft alternatives. Cost compression in mid-tier recycled material segments is intensifying because German converters accelerate water-based coating substitution to maintain EU market access. Mass-market cosmetics brands exhibit highest price sensitivity, while Paris-based fragrance houses prioritize haptic specifications over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard procurement tools for converters managing die-cutting tooling capex for magnetic closure formats. Production concentrates in Sweden, Finland, and Germany for specialty pulp-to-paperboard supply chains. Raw material flows draw from Northern European softwood pulp, Chinese coating chemicals, and neodymium magnet components. Single-source vulnerability concentrates in integrated pulp suppliers serving 300-600 gsm coated grades. Distribution runs through fragrance house procurement offices in Paris and Frankfurt, contract manufacturers in Hamburg, and duty-free logistics channels into Middle Eastern retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital print-to-pack workflows are reshaping production economics as a technological inflection, enabling versioning capabilities that fragment volume-moat advantages of large integrated converters and create entry pathways for specialized finishers.
For Market Incumbents: Build captive finishing capability moats through magnetic closure format tooling investment and soft-touch lamination equipment. Mondi plc and WestRock Company should expand FSC-certified substrate certification programs to defend against Smurfit Kappa Group's sustainability-aligned positioning. Backward integration into European pulp supply secures specialty grade availability against Northern European softwood pricing volatility.
For New Entrants and Emerging Players: Pursue white-space opportunities in digital embellishment convergence for limited-release cosmetics versioning. The most penetrable segment sits with French monthly limited-edition fragrance launches requiring same-day proof-to-production cycles. A go-to-market angle targeting Grasse and Île-de-France clusters with electrophotographic press capacity bypasses gravure plate cost barriers that constrain incumbent economics.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap converters with digital workflow capabilities and mono-material certification expertise. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than scale alone. The signal to watch is EMA labeling mandate expansion into additional EU member states, which would accelerate procurement concentration among qualified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnetic Closure Format Tooling Investment | Captures unboxing experience premiums from German and French skincare brands specifying haptic requirements. |
| FSC-Certified Substrate Certification Program | Aligns with CSRD disclosure mandates and retailer sustainability procurement thresholds across European supply chains. |
| Digital Embellishment Convergence | Enables limited-release versioning for monthly fragrance launches without gravure plate cost penalties. |
| Water-Based Coating Substitution | Maintains EU market access as REACH restrictions eliminate laminated barrier coatings from cosmetic cartons. |
| Third-Party Logistics Distribution Partnership | Accesses Middle Eastern duty-free channels through Frankfurt and Hamburg contract manufacturer relationships. |
Study Parameters
A spread of perspectives from fragrance house procurement directors, folding carton converting plant managers, pulp supply specialists, and regulatory compliance officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against EU Packaging and Packaging Waste Regulation implementation documents, EMA cosmetics labeling guidance, FSC chain-of-custody certification databases, and Northern European pulp trade association reports. Bottom-up volume estimates from individual converter capacity and top-down demand segmentation from fragrance and skincare brand procurement data were triangulated to establish market sizing.
Demand-supply balance dynamics across material type, print technology, closure mechanism, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include substrate certification tier, end-use application complexity, and regional extended producer responsibility scheme maturity. CAGRs were derived from trend extrapolation of digital print adoption curves and magnetic closure format penetration rates, cross-referenced against pulp cost forecast sensitivity and EU regulatory timeline assumptions.
Sensitivities concentrate around REACH substance restriction expansion, Northern European softwood pulp price volatility, and molded fiber substitution pilots in Asia-Pacific electronics packaging. Forecasts reflect documented assumptions regarding regulatory implementation timelines and brand unboxing experience investment continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Beverage Cartons Market
Cartons
Child-Resistant Carton Box Market
Cartons
Interlocking Boxes Market
Cartons
Printed Folding Cartons Market
Cartons
Pulp Roll Cradles Market
Cartons
MET-PET Cartons Market
Cartons
Mono Carton Market
Cartons
Twist Opening Cartons Market
Cartons
Global Hand Carton Sealers Market
Cartons
End Load Cartoning Machine Market
Cartons
Braille Cartons Packaging Market
Cartons
Tuck Top Box Market
Cartons
Global Cartonboard Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Digital Printed Cartons Market