
 Mexico Pouch Packaging Market | 2026-2036
Mexico Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Pouch Packaging Market Insights
Skilled flexographic and rotogravure press operators is redrawing the competitive map in Mexico's pouch converting sector, with talent scarcity in Querétaro and Puebla pushing wages up for certified technicians. Amcor leverages its Monterrey film extrusion complex to sustain captive supply of multilayer substrates for stand-up pouches. Gualapack anchors the spout pouch segment through specialized Italian-licensed filling equipment deployed across its Toluca plant. Berry Global competes on high-barrier vacuum pouch capacity serving beef and pork processors in Sonora.
Mexico pouch packaging comprises flexible laminated structures—typically PET/PE, PET/AL/PE, or coextruded PA/EVOH/PE combinations between 80–200 microns total gauge—formed into three-side-seal, stand-up, or fitmented configurations using heat-seal layer activation at 120–180°C, designed primarily to extend shelf life and reduce distribution weight versus rigid alternatives. Stand-up pouches dominate value capture in the Food & Beverage channel where gravity-fed retail display and reclosure convenience command premium placement fees. Spout pouches represent the fastest-expanding product type as pediatric nutrition and adult beverage brands adopt single-serve portability formats. Composites lead material selection where oxygen transmission rates below 0.5 cc/m²/day are required for retort applications in Jalisco's processed tomato and chili sauce sector.
COFEPRIS enforces NOM-051 food labeling and NOM-117 packaging material migration limits, while PROFECO monitors net content compliance through periodic market surveillance, collectively raising compliance costs for importers of unregistered Asian substrates. BIS-equivalent material certification pressures are intensifying as Mexican exporters seek USMCA qualification for cross-border CPG shipments. Stakeholders must weigh backward integration into cast PP film extrusion against toll-coating partnerships as resin volatility and labor arbitration reforms reshape unit economics.
Market Dynamics
Material compliance investments are redrawing capital allocation across Mexico's pouch converting base as NOM-117 migration limits force substrate requalification and converter consolidation accelerates in Jalisco's industrial corridor.
Growth Catalysts
- NOM-051 Labeling Mandate:COFEPRIS enforcement of front-of-pack nutritional warnings is driving CPG brands toward high-resolution flexographic print platforms capable of variable data integration at pouch converting lines.
- Retort Pouch Adoption:Processed tomato and chili sauce manufacturers in Jalisco are converting from metal cans to multilayer laminated retort pouches, cutting distribution weight and enabling microwave-ready convenience formats.
- Guadalajara Converter Cluster:Concentrated flexographic and rotogravure capacity within this industrial corridor reduces logistics costs for national CPG brands and accelerates prototype-to-production cycles for regional sauce processors.
Market Restraints
- Resin Price Volatility:Polypropylene and polyethylene input costs fluctuate with Pemex refining capacity constraints, compressing converter margins on fixed-price annual contracts with beverage brands.
- Asian Substrate Import Friction:Unregistered Chinese and Korean film imports face extended COFEPRIS registration timelines, creating supply gaps for small converters lacking backward integration into cast PP extrusion.
- Aluminum Foil Substitution Pressure:Metallized PET films with oxygen transmission rates below 1.0 cc/m²/day are capturing shelf-stable applications where EVOH barrier economics prove prohibitive for mid-volume runs.
Strategic Opportunities
- Spout Pouch White Space:Pediatric nutrition and adult beverage segments in Mexico City and Monterrey remain underpenetrated for single-serve fitmented formats, with Italian-licensed filling equipment deployment creating first-mover advantages.
- USMCA Qualification Pathway:BIS-equivalent material certification for Mexican exporters opens duty-free CPG shipment corridors into Texas and California retail networks, rewarding converters with documented resin traceability systems.
- Mono-Material Recyclability Convergence:Polyethylene-rich pouch structures compatible with existing Mexican mechanical recycling streams are aligning with PROFECO sustainability guidelines and retailer private-label requirements.
Industry Challenges
- Certified Press Operator Scarcity:Skilled flexographic and rotogravure technicians in Querétaro and Puebla command wage premiums that erode unit economics for mid-cap converters serving regional meat processors.
- Multilayer Lamination Complexity:PET/AL/PE and PA/EVOH/PE substrate bonding requires precise heat-seal layer activation at 120–180°C, with defect rates spiking during humidity season without climate-controlled slitting operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Pouch Packaging Market |
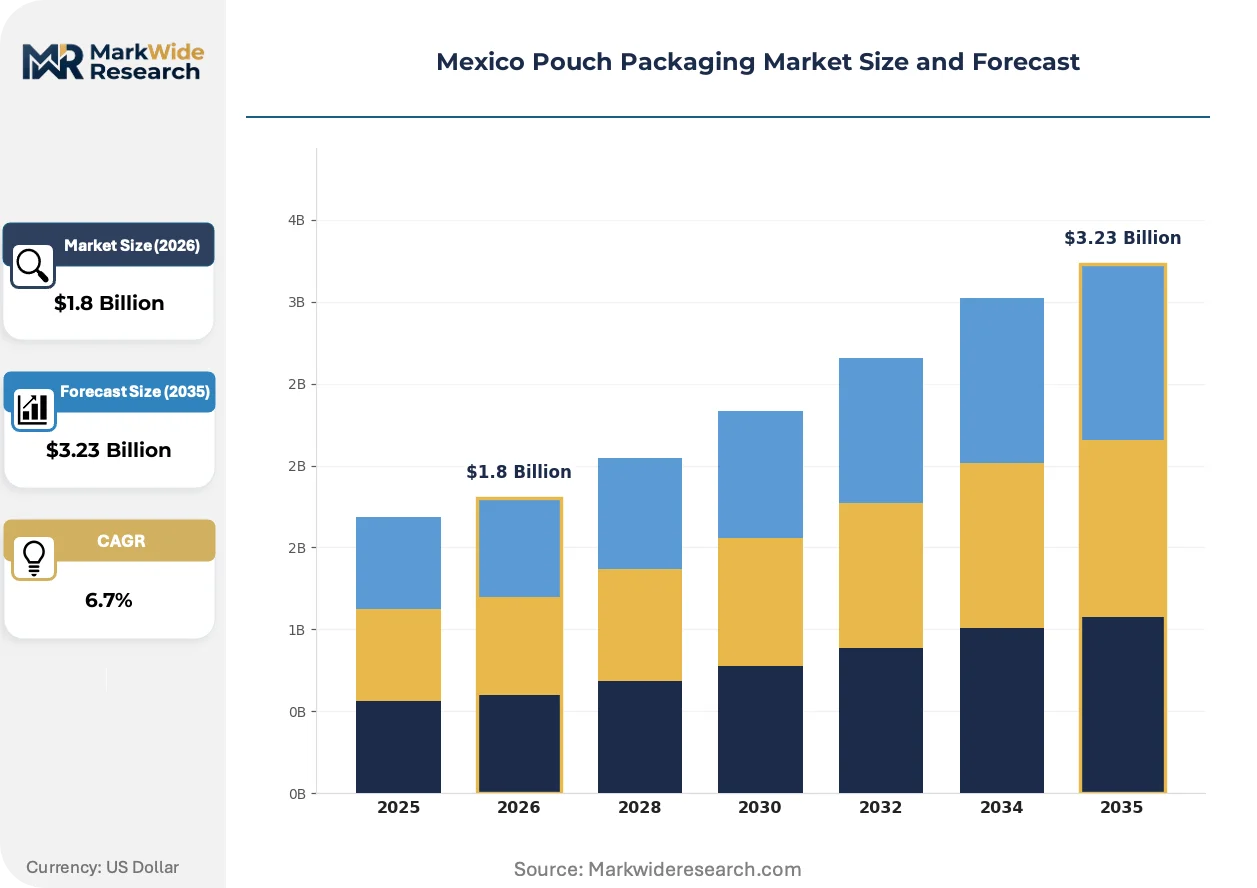
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Spout Pouches, Vacuum Pouches Material: Plastic, Paper, Aluminum Foil, Composites End User: Food & Beverage, Cosmetics, Pharmaceuticals, Household Products Closure Type: Zip Lock, Press Seal, Heat Seal, Snap Fit |
| Companies Covered | Amcor, Sonoco Products Company, Gualapack, Berry Global Inc., Sealed Air Corporation, ABA S.A de C.V., Zubex Industrial S.A de C.V., Mondi, Constantia Flexibles, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Pouch Packaging Market Trends and Innovations
Digital print integration and barrier material substitution are compressing traditional converting economics while regulatory compliance costs reshape competitive positioning across Mexico's pouch packaging base.
Water-based flexographic ink systems with solvent-free adhesive lamination are supplanting conventional solvent-based gravure workflows in Jalisco's converter corridor. Regional sauce processors adopting these platforms achieve VOC emission reductions that satisfy COFEPRIS environmental audits while maintaining 150-line-screen print resolution. The technology is supplanting legacy equipment investments among mid-cap converters who previously relied on toll-coating partnerships for high-barrier applications.
COFEPRIS NOM-117 enforcement tightens migration limits for food-contact plastics, requiring substrate requalification with third-party laboratory documentation. Converters face six-to-nine month certification timelines for new multilayer structures, forcing advance material commitments before commercial trials. The processed meat segment in Sonora bears the highest compliance burden, with beef and pork processors demanding vacuum pouch oxygen transmission rates below 0.5 cc/m²/day under revised testing protocols.
Direct converter relationships are displacing traditional distributor intermediaries for national CPG brands seeking faster prototype iteration. Procurement teams at beverage and sauce manufacturers now mandate on-site technical collaboration for spout pouch development, compressing supplier qualification cycles. This pattern concentrates contract awards among Guadalajara-area converters with in-house CAD/CAM die-making and same-day sample production capabilities.
Mexico Pouch Packaging Market Segmentation
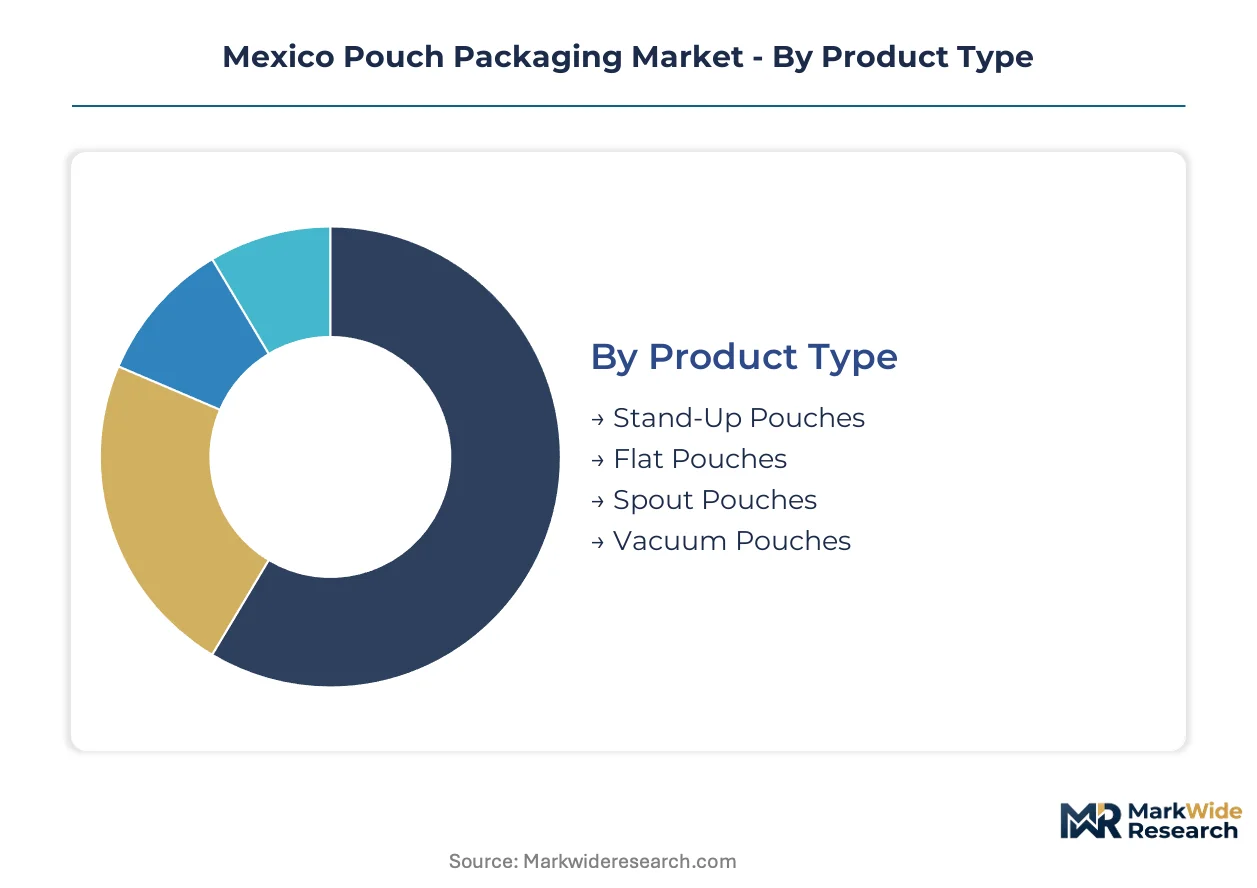
Channel differentiation across Mexico's pouch packaging market determines margin capture and technical requirements. Each segment category reflects distinct supply chain configurations and regulatory exposure.
Product Type:
Channel mix varies sharply by format, with retail gravity-fed displays favoring stand-up configurations while foodservice and industrial buyers prioritize flat and vacuum-sealed alternatives.
- Stand-Up Pouches:These structures incorporate gusseted bottoms enabling vertical shelf presentation. Jalisco's processed tomato and chili sauce manufacturers command premium placement fees in retail channels through this format.
- Spout Pouches:Fitmented configurations with integrated dispensing closures serve single-serve portability demands. Pediatric nutrition brands in Mexico City and adult beverage processors in Monterrey are expanding capacity for this segment most aggressively.
- Flat Pouches:Three-side-seal configurations dominate cost-sensitive industrial applications. Sonora's beef and pork processors specify these for bulk vacuum packaging where display aesthetics matter less.
- Vacuum Pouches:Multilayer barrier structures with oxygen transmission specifications below 0.5 cc/m²/day serve extended shelf-life requirements. High-barrier EVOH and aluminum foil laminations concentrate in protein processing corridors.
Stand-up pouches dominate installed base. Spout pouches are where expansion concentrates.
Material:
Cost tier stratification separates commodity resin buyers from converters investing in compliance-heavy multilayer structures.
- Plastic:Polyethylene-rich mono-material structures align with PROFECO sustainability guidelines and existing Mexican mechanical recycling infrastructure. Cast PP and PE films from Pemex-derived resins form the volume base.
- Composites:PET/AL/PE and PA/EVOH/PE laminations between 80–200 microns achieve retort-grade barrier performance. Jalisco's sauce sector demands these for microwave-ready convenience formats despite NOM-117 requalification burdens.
- Aluminum Foil:Pure foil layers face substitution pressure from metallized PET films with oxygen transmission rates below 1.0 cc/m²/day. Mid-volume runs find EVOH barrier economics prohibitive.
- Paper:Fiber-based structures with polymer barrier coatings serve limited premium cosmetic and dry food applications. COFEPRIS migration testing requirements constrain adoption in direct food contact.
Plastic structures command volume leadership. Composites capture value concentration in retort applications.
End User:
Application-specific performance requirements drive material selection and certification intensity across buyer categories.
- Food & Beverage:Shelf-stable sauces, ready-to-eat meals, and protein packaging generate the majority of demand. NOM-051 front-of-pack labeling mandates push brands toward high-resolution flexographic print platforms.
- Pharmaceuticals:COFEPRIS enforces stringent migration limits for pediatric nutrition and medical device packaging. Extended registration timelines for new substrate qualifications favor established converter relationships.
- Cosmetics:Premium positioning requirements favor tactile finishes and metallic effects. Smaller lot sizes and SKU proliferation challenge converters without digital print integration.
- Household Products:Chemical resistance specifications for detergents and cleaning agents favor coextruded PE structures. Price sensitivity limits barrier layer complexity relative to food applications.
Food & Beverage anchors installed capacity. Pharmaceuticals represent the steepest expansion trajectory for certified barrier structures.
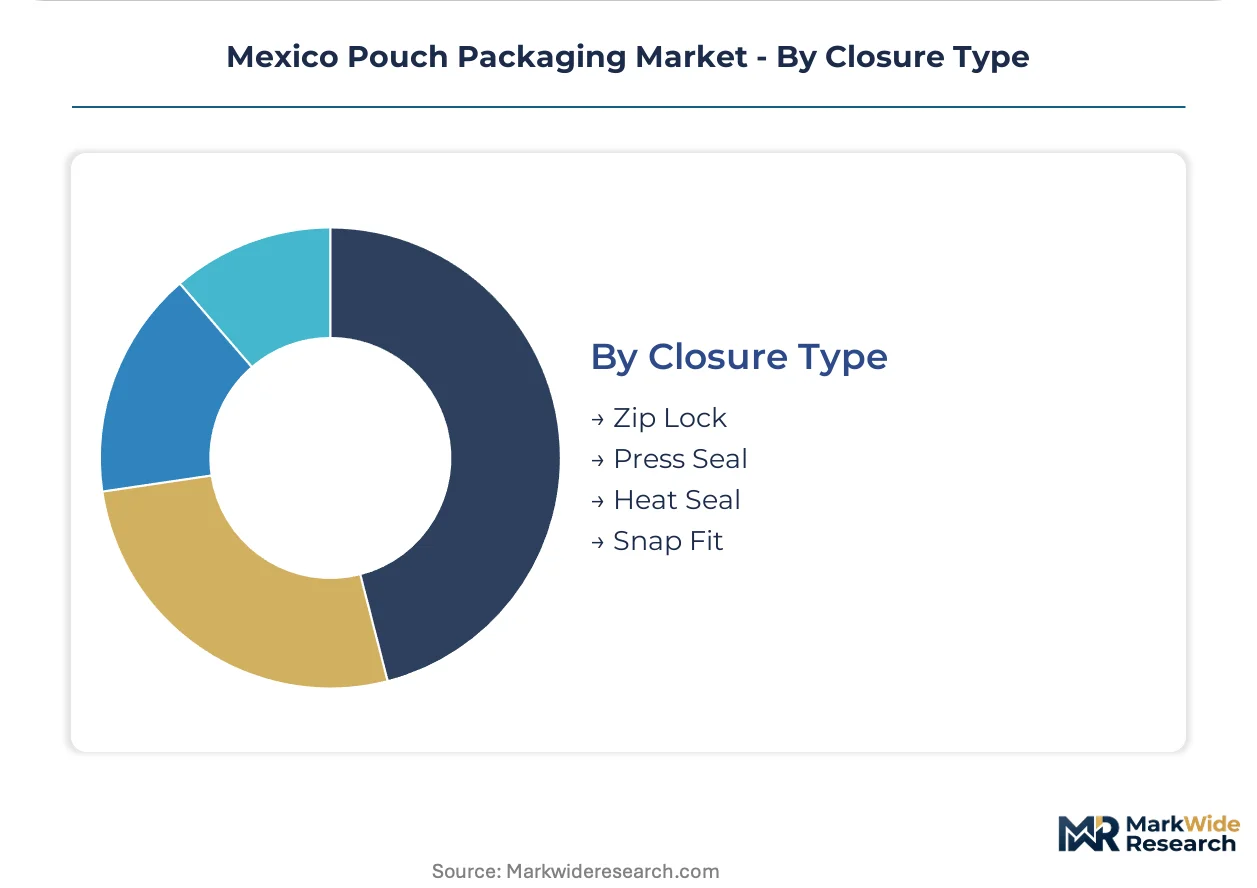
Closure Type:
Customer type and use-case occasion determine reclosure mechanism selection and equipment investment requirements.
- Heat Seal:Permanent fusion bonding at 120–180°C dominates industrial and foodservice channels where single-use opening is standard. Defect rates spike during humidity season without climate-controlled slitting.
- Zip Lock:Interlocking profile reclosure serves multi-occasion consumption in retail channels. Gualapack's Italian-licensed filling equipment deployment in Toluca anchors technical capability for this segment.
- Press Seal:Adhesive-based reclosure offers cost positioning between permanent heat seals and mechanical zip systems. Limited adoption in moisture-exposed applications.
- Snap Fit:Rigid plastic spout-and-cap combinations enable controlled dispensing. Adult beverage and pediatric nutrition brands in Mexico City specify these for on-the-go consumption occasions.
Heat seal closures dominate production volume. Zip lock and snap fit systems are gaining share fastest in premium retail channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Jalisco's Guadalajara corridor exceeds that of Mexico City converters by 12-18% due to captive flexographic capacity and NOM-117 certification density. This asymmetry reflects supply chain concentration rather than demand differentiation.
Jalisco
Processed tomato and chili sauce manufacturers drive multilayer retort pouch demand with oxygen transmission specifications below 0.5 cc/m²/day. COFEPRIS NOM-117 enforcement mandates third-party laboratory documentation for substrate requalification. Guadalajara's industrial corridor hosts concentrated flexographic and rotogravure capacity serving national CPG brands.
Nuevo León
Beef and pork processors in Sonora corridor demand high-barrier vacuum pouches for extended shelf-life protein packaging. PROFECO net content compliance monitoring raises operational costs for regional meat packers. Monterrey anchors captive film extrusion complexes supplying multilayer substrates to stand-up pouch converters.
Mexico City Metro
Pediatric nutrition and adult beverage brands generate fastest-expanding demand for single-serve spout pouch formats. NOM-051 front-of-pack nutritional warning mandates push brands toward high-resolution flexographic print platforms. Toluca plants deploy Italian-licensed filling equipment for fitmented pouch production.
Bajío Region
Mid-cap converters serving regional sauce processors face certified press operator scarcity driving wage premiums. Labor arbitration reforms reshape unit economics for toll-coating partnerships versus backward integration decisions. Querétaro and Puebla clusters compete on prototype-to-production cycle speed.
Northern Border States
USMCA qualification pathways reward converters with documented resin traceability systems for duty-free CPG shipments into Texas and California retail networks. BIS-equivalent material certification pressures intensify for cross-border meat and produce processors. Chihuahua and Tamaulipas facilities balance Pemex resin volatility against Asian substrate import friction.
Mexico Pouch Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Mexico's pouch converting base. The market structures around three tiers: multinational integrated film extruders with captive substrate supply, specialized fitmented pouch converters with licensed foreign equipment, and regional mid-caps competing on toll-coating partnerships. Strategic moves concentrate on backward integration into cast PP film extrusion and direct technical collaboration with CPG procurement teams.
Within the integrated multinational tier, Amcor and Berry Global occupy positions anchored by Monterrey film extrusion complexes and high-barrier vacuum pouch capacity respectively. Gualapack exemplifies the specialized fitmented pouch archetype through Italian-licensed equipment deployment. Among mid-cap regional fabricators, ABA S.A. de C.V. and Zubex Industrial S.A. de C.V. represent toll-coating-dependent competitors navigating NOM-117 requalification timelines.
| Leading Market Players |
|---|
| Amcor |
| Sonoco Products Company |
| Gualapack |
| Berry Global Inc. |
| Sealed Air Corporation |
| ABA S.A de C.V. |
| Zubex Industrial S.A de C.V. |
| Mondi |
| Constantia Flexibles |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety day substrate requalification timelines under COFEPRIS NOM-117 enforcement concentrate pricing power among Jalisco converters with captive laboratory partnerships, while Pemex resin volatility compresses margins for toll-coating-dependent mid-caps locked into fixed-price annual beverage contracts.
Pricing Analysis
The customization-premium spread between configured-to-order multilayer retort structures and standard three-side-seal formats runs wide across Mexico's pouch converting base. Contract-based long-term offtake dominates the channel, with price differentiation hinging on NOM-117 certification grade and volume scale commitments. Cost compression in standard PE-rich mono-material tiers is intensifying because Asian substrate import friction forces small converters toward premium domestic resin sourcing. Regional meat processors in Sonora exhibit highest price sensitivity, while pediatric nutrition brands in Mexico City tolerate premium positioning for spout pouch convenience.
Supply Chain Analysis
Inventory cycles stretching sixty-to-ninety days for NOM-117 substrate requalification tether Mexican converters to domestic film extrusion capacity. Geographic supply concentrates in the United States for EVOH barrier resins, China for metallized PET films, and domestic Pemex facilities for commodity PE and PP. Raw material dependencies rest on ethylene feedstock availability, aluminum foil gauge specifications, and solvent-free adhesive chemistries. Single-source vulnerability around Italian-licensed spout pouch filling equipment creates bottleneck risk for fitmented format expansion. Distribution runs through direct technical collaboration models displacing traditional distributor intermediaries for national CPG procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's pouch packaging sector sits in early-cycle expansion, with retort pouch adoption in Jalisco's processed sauce corridor providing durable penetration tailwinds as manufacturers abandon metal can formats for microwave-ready convenience.
For Market Incumbents: Compound barrier technology leadership through captive film extrusion investments in Monterrey and NOM-117 certification density expansion, defending against metallized PET substitution pressure in mid-volume shelf-stable applications while anchoring high-barrier vacuum pouch relationships with Sonora protein processors. For New Entrants and Emerging Players: Same-day prototype turnaround capabilities in Querétaro and Puebla represent the most penetrable service-layer gap, where certified press operator scarcity delays incumbent response times; target pediatric nutrition and adult beverage spout pouch development through Italian-licensed equipment partnerships with Mexico City brands seeking direct technical collaboration. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational film extruders divesting non-core converting assets; mid-cap Jalisco converters with documented resin traceability systems and NOM-117 laboratory partnerships offer strongest long-term viability through the USMCA qualification pathway. Watch for Pemex refining capacity announcements as inflection signals on domestic resin cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cast PP Film Extrusion | Captive substrate supply insulates margins from Pemex resin volatility and Asian import friction. |
| NOM-117 Certification Laboratory Partnership | Third-party documentation capabilities compress six-to-nine month substrate requalification timelines for retort applications. |
| Italian-Licensed Spout Pouch Filling Equipment Deployment | Fitmented format technical capability creates first-mover positioning in underpenetrated pediatric nutrition and adult beverage segments. |
| Direct Technical Collaboration with CPG Procurement | On-site CAD/CAM die-making and same-day sample production displace distributor intermediaries for national brand relationships. |
| USMCA-Qualifying Resin Traceability System Implementation | Documented supply chain transparency opens duty-free shipment corridors into Texas and California retail networks. |
Research Methodology
A spread of perspectives from flexographic press operators, COFEPRIS regulatory affairs consultants, national CPG procurement directors, and Pemex resin supply planners converged on the working assumptions. Primary interview intelligence combined with secondary validation from COFEPRIS NOM-051 and NOM-117 regulatory filings, Mexican customs substrate import records, and SEC 10-K disclosures of multinational film extruders. Bottom-up converter capacity assessments and top-down CPG packaging spend estimates were triangulated to anchor volume and value outputs.
Segmentation dimensions modeled span product type, material composition, end-use application, closure mechanism, and regional production cluster across the analysis window. CAGRs were derived from elasticity-adjusted demand projections incorporating NOM-051 labeling mandate enforcement intensity and retort pouch substitution rates in Jalisco's processed sauce sector. Forecast inputs included Pemex ethylene feedstock allocation patterns and Italian-licensed spout pouch equipment installation pipelines.
Forecasts assume regulatory continuity in COFEPRIS NOM-117 migration limit enforcement and USMCA origin qualification protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
China Pouch Packaging Market
Pouch
Liquid Pouch Packaging Market
Pouch
Brazil Pouch Packaging Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Slider Zipper Pouch Market
Pouch
Recyclable PE Pouch Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Argentina Pouch Packaging Market
Pouch
Automatic Pre-Made Pouch Packaging Machine Market
Pouch
Germany Pouch Packaging Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Doy Pouch Packaging Market
Pouch
Flexible Plastic Pouches Market
Pouch
Flat Bottom Pouch Market
Pouch
Inverted Pouch Market
Pouch
South Africa Pouch Packaging Market