
 Carton Form Fill Seal Machine Market | 2026-2036
Carton Form Fill Seal Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Carton Form Fill Seal Machine Market Outlook
Recycled paperboard is recalibrating raw-material economics for carton forming equipment as mills narrow furnish specifications. Syntegon leverages its pharmaceutical serialization expertise to command premium positioning in compliance-heavy installations. ProMach sustains broad application coverage across food and personal care through decentralized manufacturing footprints. Krones AG anchors beverage carton integration with its downstream filling line synergies.
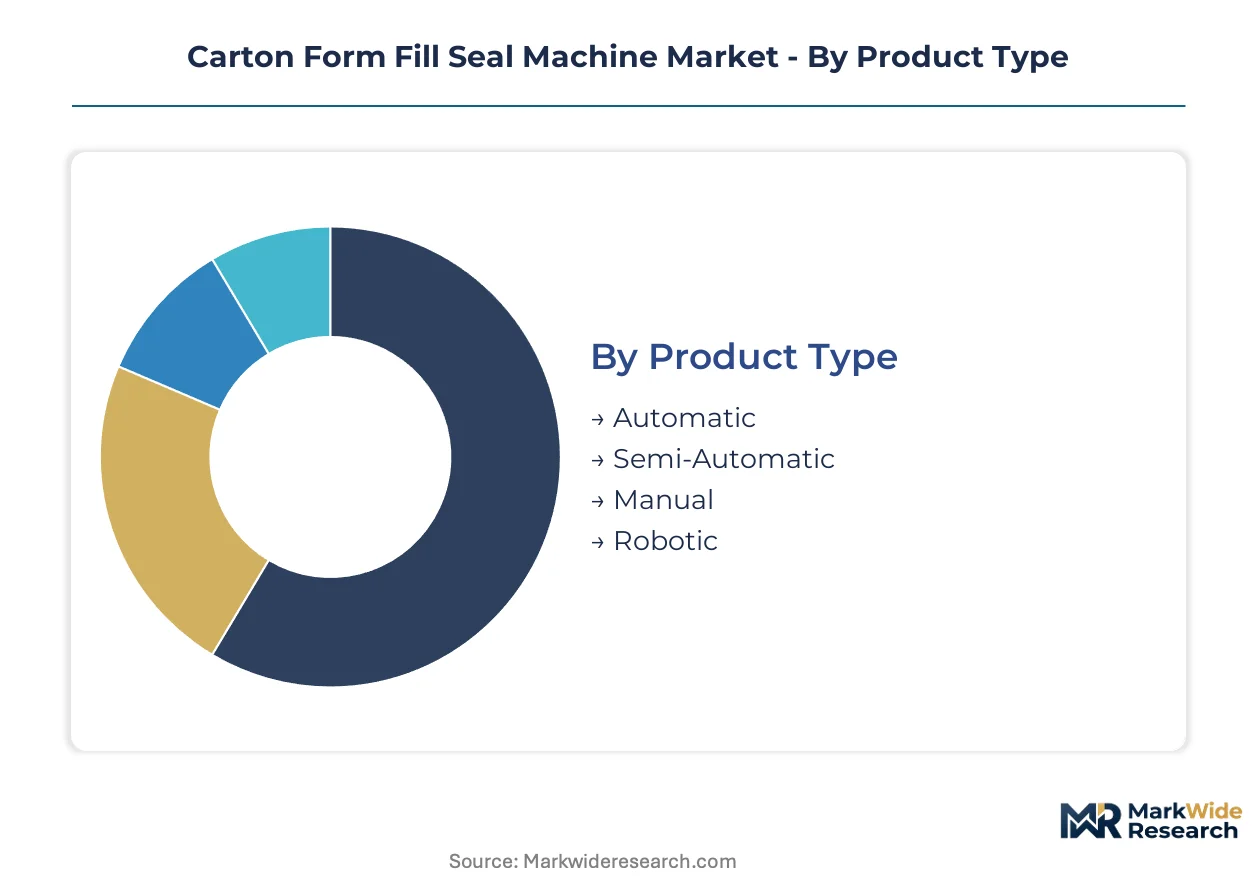
A carton form fill seal machine erects flat carton blanks, forms them into three-dimensional containers, fills them with product, and seals closures through integrated mechanical, thermal, or pressure-based methods; typical line speeds range from 50 to 600 units per minute depending on carton geometry and product viscosity. Automatic systems dominate installed capacity in high-volume food and beverage plants where labor arbitrage has collapsed, while robotic configurations represent the fastest-expanding segment as pharmaceutical batch sizes shrink and changeover frequency multiplies. Heat seal technology occupies the largest margin pool due to energy-cost sensitivity and seal-integrity requirements in liquid dairy.
FDA cGMP guidelines and EU MDR traceability rules are tightening validation documentation for pharmaceutical carton lines, forcing equipment upgrades at contract packer sites. EPA emissions standards and OSHA combustible dust regulations shape material-handling architectures in North American food plants. REACH compliance in Europe restricts adhesive chemistries used in cold-seal applications, redirecting R&D toward ultrasonic alternatives. Stakeholders must weigh capex recovery timelines against the accelerating regulatory half-life of legacy seal technologies.
Market Dynamics
Heat-seal technology is compressing cold-seal margins across liquid dairy installations as energy costs and seal-integrity standards tighten operational requirements for carton forming equipment.
Growth Catalysts
- EU MDR traceability mandates:Pharmaceutical contract packers in Germany and Switzerland are retrofitting lines with serialization-ready robotic configurations to meet device tracking deadlines.
- Recycled paperboard furnish narrowing:Mills supplying carton blanks are tightening specifications, forcing equipment makers to recalibrate forming precision for variable fiber content.
- OSHA combustible dust rules:North American food plants are upgrading material-handling architectures to meet particulate emission standards, triggering replacement cycles in legacy installations.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price swings compress margin predictability for precision-engineered forming components sourced from German and Italian metalworking clusters.
- Ultrasonic seal R&D redirection:REACH restrictions on adhesive chemistries are forcing cold-seal specialists to absorb unplanned development costs without guaranteed commercialization timelines.
- Robotic integration complexity:Pharmaceutical batch-size fragmentation requires motion-control architectures that exceed the technical ceiling of mid-tier system integrators.
Strategic Opportunities
- Indian pharmaceutical packaging:CDSCO serialization rollout and FSSAI dairy safety expansion are creating first-mover openings for heat-seal and robotic system suppliers in Mumbai-Pune corridor plants.
- Ultrasonic-cold seal convergence:Hybrid sealing architectures that merge ultrasonic energy with reduced adhesive dependency are opening patent white space outside established heat-seal incumbents.
- Outcome-based service contracting:Pharmaceutical contract packers in the Netherlands are unbundling capex into throughput-guaranteed agreements, shifting vendor revenue toward uptime performance.
Industry Challenges
- Mechatronics talent scarcity:Motion-control programming and vision-system calibration for robotic changeover sequences outstrip vocational pipeline output in German and Swiss engineering clusters.
- Legacy PLC integration friction:Pharmaceutical sites running 1990s-era Siemens and Rockwell architectures face protocol incompatibility with modern serialization data layers, extending commissioning timelines.
- FDA cGMP validation documentation:Equipment qualification protocols for pharmaceutical carton lines require 18-24 month paper trails that delay revenue recognition and strain vendor project management capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carton Form Fill Seal Machine Market |
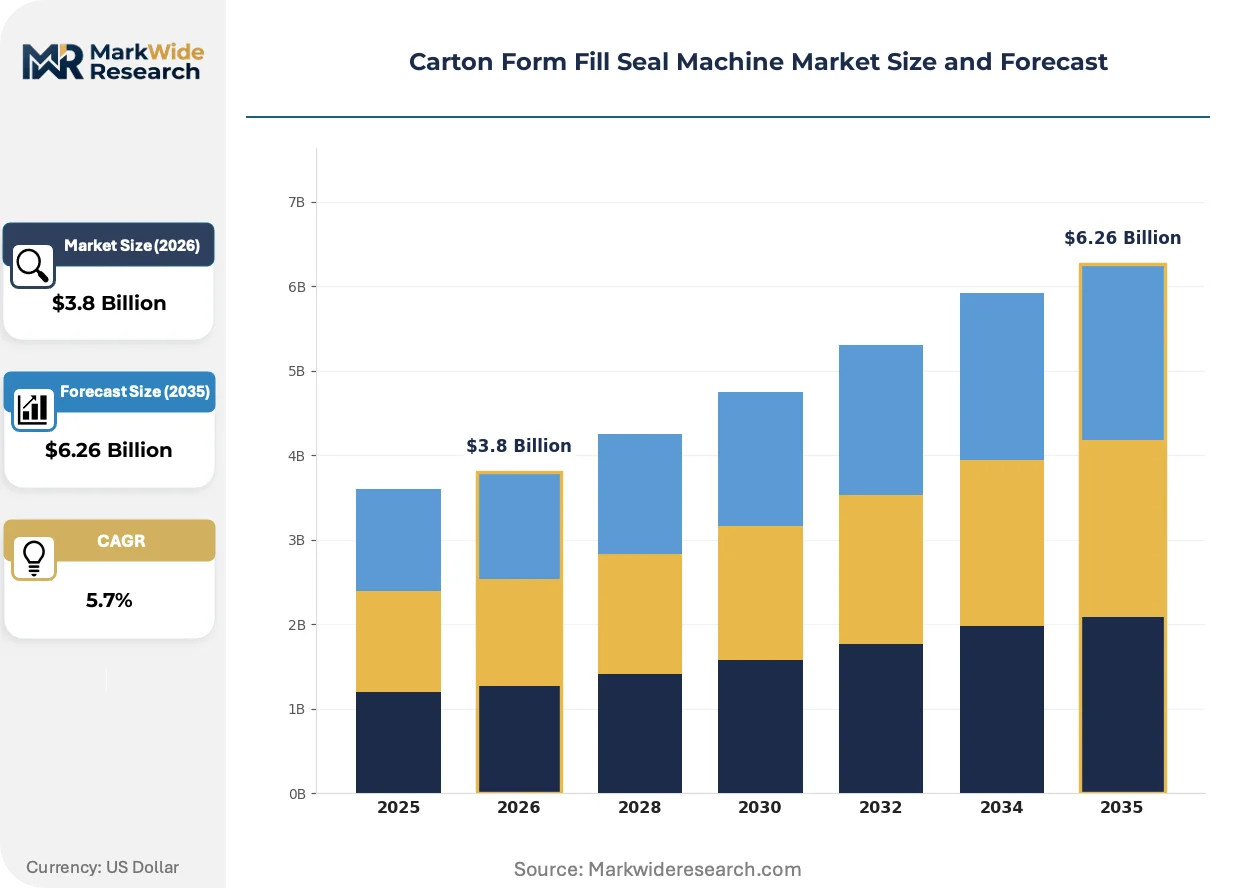
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Robotic Application: Food, Beverage, Pharmaceuticals, Personal Care End User: Manufacturers, Distributors, Retailers, Contract Packers Technology: Ultrasonic, Heat Seal, Cold Seal, Pressure Seal |
| Companies Covered | Syntegon, ProMach, IMA Group, Bosch Packaging Technology, Krones AG, Omori Machinery, Mespack, Uhlmann, Marchesini Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carton Form Fill Seal Machine Market Strategic Shifts
Active thermal management and digital thread architectures are redefining competitive differentiation in carton forming equipment, compressing the window between regulatory mandate and commercial deployment.
Ultrasonic sealing is consolidating position in pharmaceutical and personal care applications where adhesive-free closure integrity meets serialization readability requirements. Contract packers in Switzerland and Germany are piloting systems at 200-400 units per minute, displacing legacy cold-seal lines that risk REACH non-compliance. The technology is consolidating vendor R&D budgets away from incremental heat-seal improvements toward acoustic-engineering competencies.
REACH adhesive restrictions are forcing cold-seal equipment makers to reformulate chemistries or abandon the segment entirely, redirecting capital toward ultrasonic and advanced heat-seal platforms. The industrial consequence is a bifurcation in installed base economics: compliant lines command residual value premiums while legacy assets face accelerated depreciation. Pharmaceutical applications in France and Germany are most affected, with ANSM and BfArM inspections prioritizing closure traceability in secondary packaging.
Buyer concentration among top-ten pharmaceutical contract packers is compressing vendor negotiation leverage and standardizing equipment specifications across multi-site tenders. Tier-one packers in the Netherlands and Denmark are consolidating procurement through framework agreements that specify interchangeable tooling and 15-minute changeover ceilings. This pattern is most visible in the Rhine-Ruhr and Copenhagen logistics corridors, where regional hub strategies favor vendor scale over local service proximity.
Carton Form Fill Seal Machine Market Segmentation
Carton form fill seal equipment fragments across automation intensity, regulatory exposure, and seal-technology physics. Each segmentation axis carries distinct capex recovery timelines and aftermarket service attach rates that reshape vendor portfolio priorities.
Product Type:
Supply concentration for precision motion components tilts toward German and Swiss engineering clusters, compressing margin structures for mid-tier automation tiers.
- Automatic:Continuous-motion architectures dominate high-volume dairy and beverage plants with line speeds exceeding 400 units per minute. German food manufacturers anchor demand as labor arbitrage collapses and shift differentials widen.
- Robotic:Servo-driven delta and SCARA configurations enable 15-minute changeover sequences for shrinking pharmaceutical batch sizes. Swiss contract packers are retrofitting legacy lines with serialization-ready robotic modules ahead of EU MDR deadlines.
- Semi-Automatic:Intermediate tier serving regional dairy cooperatives in France and mid-size personal care brands in Italy.
- Manual:Niche presence in artisan food startups and pilot-scale pharmaceutical validation labs.
Automatic systems absorb the bulk of installed capacity; robotic configurations are expanding most quickly.
Application:
Cost tier differentiation separates validation-heavy pharmaceutical installations from throughput-optimized food and beverage lines.
- Food:Liquid dairy and dry bakery segments drive heat-seal adoption where seal integrity prevents spoilage. French dairy cooperatives are replacing cold-seal legacy assets ahead of REACH adhesive restrictions.
- Pharmaceuticals:Secondary packaging for vials, ampoules, and medical devices demands FDA cGMP-compliant documentation and serialization integration. German contract packers in the Rhine-Ruhr corridor command premium pricing for validated installations.
- Beverage:Aseptic carton filling for extended-shelf-life milk and juice concentrates procurement in Netherlands hub plants.
- Personal Care:Cosmetic and hygiene product lines favor ultrasonic sealing for adhesive-free closure integrity.
Food applications dominate current installed base; pharmaceutical lines carry the steepest expansion trajectory.
End User:
Customer type concentration is bifurcating between capital-rich contract packers and margin-constrained manufacturer-direct procurement.
- Contract Packers:Multi-site pharmaceutical service providers in Denmark and the Netherlands consolidate procurement through framework agreements specifying interchangeable tooling. These buyers unbundle capex into throughput-guaranteed service contracts.
- Manufacturers:Integrated food and beverage producers in Germany and Italy favor captive packaging lines with 20-year depreciation horizons.
- Distributors:Regional equipment resellers serving Eastern European dairy plants with refurbished automatic systems.
- Retailers:Private-label food brands in France operating captive packaging for store-brand dairy and bakery products.
Contract packers absorb the bulk of high-margin pharmaceutical capacity; manufacturer-direct procurement is climbing the fastest in beverage integration projects.
Technology:
Margin pool distribution favors heat-seal platforms where energy-cost sensitivity and seal-integrity requirements sustain premium pricing.
- Heat Seal:Thermal bonding systems using controlled temperature and pressure profiles dominate liquid dairy where hermetic closure prevents microbial ingress. German dairy engineering standards specify 0.5-second dwell times for polyethylene-coated paperboard.
- Ultrasonic:Acoustic energy welding eliminates adhesive dependency for REACH-compliant pharmaceutical and personal care applications. Swiss manufacturers are piloting 300-unit-per-minute systems for cosmetic carton lines.
- Cold Seal:Pressure-activated adhesive bonding faces regulatory pressure from ECHA restrictions on solvent-based chemistries.
- Pressure Seal:Mechanical interlock closures for dry goods and low-moisture bakery products.
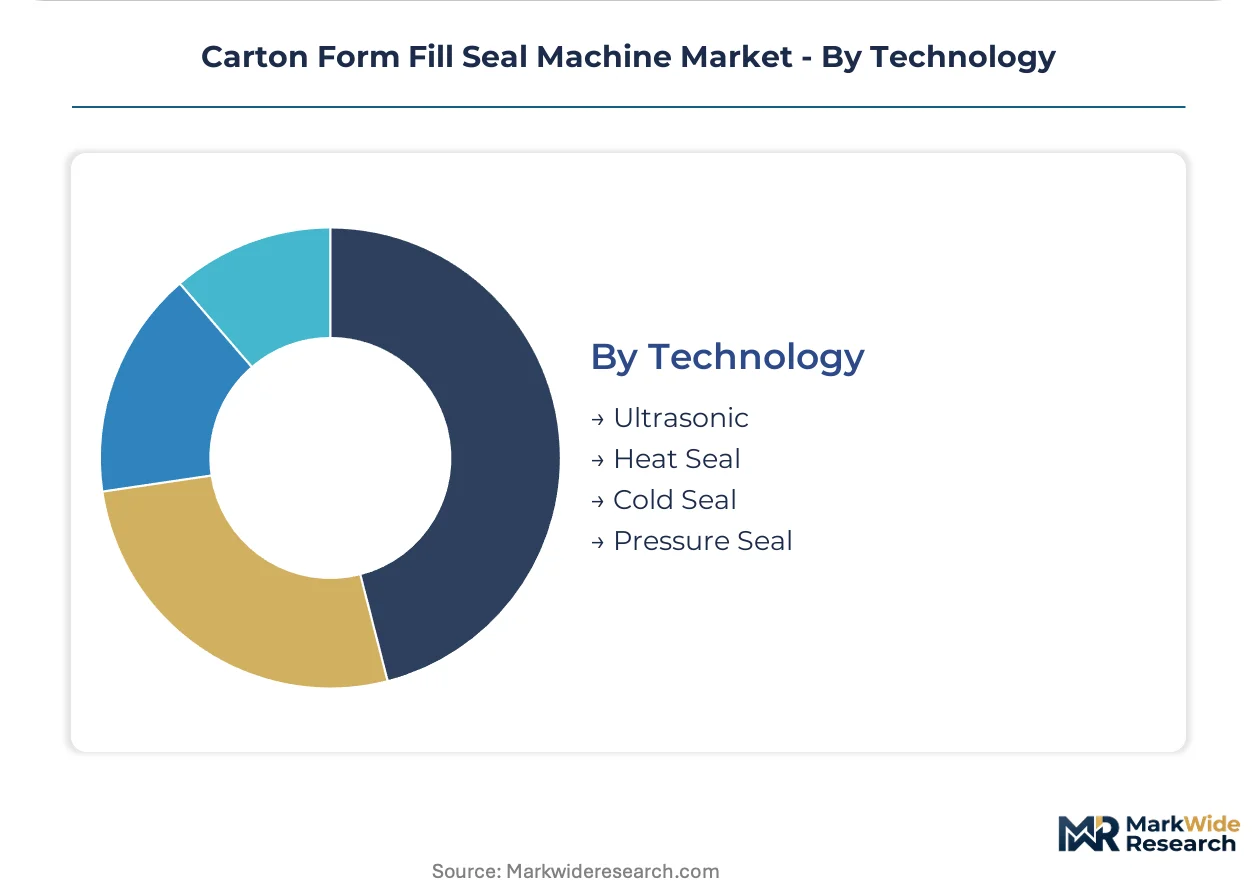
Heat seal technology commands the largest margin pool; ultrasonic systems are gaining share fastest in compliance-heavy installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate Indian pharmaceutical packaging investment as CDSCO serialization mandates approach enforcement deadlines.
Germany
Precision engineering clusters in Baden-Württemberg and North Rhine-Westphalia anchor European carton machinery supply. BfArM inspections prioritize closure traceability in secondary pharmaceutical packaging. Bosch Packaging Technology and Syntegon command premium positioning in Rhine-Ruhr corridor contract packer installations.
United States
FDA cGMP guidelines tighten validation documentation for pharmaceutical carton lines at contract packer sites. OSHA combustible dust regulations reshape material-handling architectures in food plants across Wisconsin and California dairy belts. Midwest engineering hubs sustain precision component fabrication for forming equipment.
Switzerland
Swissmedic oversight drives serialization-ready robotic retrofits ahead of EU MDR traceability deadlines. Geneva and Basel pharmaceutical contract packers pilot ultrasonic sealing at 200-400 units per minute. Zürich engineering consultancies specialize in motion-control programming for delta robot configurations.
India
CDSCO serialization rollout and FSSAI dairy safety expansion create first-mover openings in Mumbai-Pune corridor plants. Gujarat pharmaceutical special economic zones attract heat-seal and robotic system suppliers. Domestic contract packers consolidate procurement for multi-site tenders specifying 15-minute changeover ceilings.
Netherlands
Rotterdam and Amsterdam logistics hubs favor vendor scale over local service proximity in pharmaceutical framework agreements. Outcome-based service contracting unbundles capex into throughput-guaranteed agreements. Dutch food safety authorities enforce stringent seal-integrity standards in aseptic dairy carton applications.
Carton Form Fill Seal Machine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with precision-engineered pharmaceutical configurations commanding margin premiums over standardized food and beverage lines. The vendor base concentrates around German and Swiss engineering clusters for motion-control components, while Italian and Spanish fabricators dominate mid-tier dairy applications. Three archetypes define competitive positioning: vertically integrated precision specialists, decentralized application generalists, and regional cost-optimized fabricators. M&A activity targets serialization software capabilities, while capacity expansion concentrates in Indian and Southeast Asian pharmaceutical corridors.
Among German precision-engineering specialists, Syntegon and Bosch Packaging Technology exemplify the compliance-heavy installation tier where pharmaceutical serialization expertise commands premium positioning. Krones AG anchors beverage carton integration through downstream filling line synergies. These three entities occupy distinct competitive spaces: Syntegon represents pharmaceutical-focused robotic configurations, Bosch Packaging Technology exemplifies precision forming heritage, and Krones AG sits within beverage system integration archetypes.
| Leading Market Players |
|---|
| Syntegon |
| ProMach |
| IMA Group |
| Bosch Packaging Technology |
| Krones AG |
| Omori Machinery |
| Mespack |
| Uhlmann |
| Marchesini Group |
| Others |
Value Chain & Pricing Dynamics
Contract packer consolidation in the Netherlands and Denmark anchors three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical framework agreements compress vendor negotiation leverage while mandating interchangeable tooling specifications.
Pricing Analysis
Lead-time premiums command substantial markups for Swiss and German contract packers facing EU MDR serialization deadlines. Pricing stratifies across premium, standard, and economy tiers based on validation documentation depth and motion-control precision grade. Cost compression in mid-tier dairy installations intensifies as cold-seal equipment faces REACH-driven obsolescence. Regional dairy cooperatives in France exhibit highest price sensitivity; validated pharmaceutical lines in Germany show lowest.
Supply Chain Analysis
Mechatronics talent scarcity in Baden-Württemberg and Zürich engineering clusters constrains production scaling for robotic motion components. Precision forming equipment draws from German stainless steel fabricators, Swiss servo motor specialists, and Italian pneumatic subsystem suppliers. Single-source vulnerability concentrates in pharmaceutical-grade vision-system calibration modules. Distribution runs through Rotterdam and Amsterdam logistics hubs serving Rhine-Ruhr corridor contract packers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat-seal technology is displacing legacy cold-seal platforms across liquid dairy and pharmaceutical applications. This transition phase compresses margins for adhesive-dependent equipment makers while rewarding ultrasonic and thermal bonding specialists.
For Market Incumbents: Hedge against REACH non-compliance exposure by accelerating ultrasonic R&D spend and acquiring serialization software capabilities. Secure backward integration into servo motor supply through partnerships with Swiss engineering clusters. Defensive patent filings around hybrid sealing architectures protect margin pools from emerging acoustic-engineering entrants.
For New Entrants and Emerging Players: Capture first-mover position in Indian pharmaceutical packaging corridors ahead of CDSCO enforcement deadlines. Target Mumbai-Pune contract packers with heat-seal configurations priced below German incumbent offerings. Go-to-market through outcome-based service contracting unbundles capex barriers for capital-constrained regional players.
For Investors and Strategic Acquirers: The window for entry favors mid-tier automation specialists with existing pharmaceutical validation expertise. Long-term viability hinges on consolidation plays in serialization software and motion-control engineering. Watch FDA cGMP documentation backlogs as inflection signal for vendor project management capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Serialization Software Acquisition | EU MDR traceability mandates in Germany and Switzerland drive premium positioning for compliance-ready vendors. |
| Ultrasonic R&D Expansion | REACH adhesive restrictions redirect capital toward acoustic-engineering competencies outside heat-seal incumbents. |
| Indian Manufacturing Footprint | CDSCO rollout in Gujarat special economic zones creates localized supply advantage for first movers. |
| Outcome-Based Service Contracting | Dutch contract packers unbundle capex into throughput-guaranteed agreements shifting revenue toward uptime performance. |
| Precision Component Backward Integration | Swiss and German servo motor supply scarcity motivates upstream control over motion-control subsystems. |
Study Parameters
Independent corroboration across equipment procurement directors, pharmaceutical contract packer operations leads, dairy plant engineers, and aftermarket service heads underwrites the qualitative findings. Secondary validation draws from FDA cGMP guidance documents, ECHA REACH restriction notices, EU MDR implementation timelines, and trade customs data for carton forming machinery. Bottom-up installation base analysis triangulates against top-down market sizing from vendor revenue disclosures.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. Segmentation dimensions span automation intensity, seal technology physics, regulatory exposure tier, and geographic adoption cluster. CAGRs derive from logistic curve fitting to installed base replacement cycles and greenfield capacity announcements. Forecast inputs incorporate stainless steel price volatility indices and pharmaceutical serialization mandate enforcement calendars.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH adhesive restriction expansion and mechatronics talent pipeline constraints. Forecasts reflect documented assumptions on regulatory enforcement timing and raw material cost trajectories. A small set of triggers warrants ongoing watch: FDA cGMP documentation processing speeds, ECHA solvent-based adhesive restriction scope expansion, and Indian CDSCO serialization deadline adherence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Folding Carton in Healthcare Market
Cartons
Brick Carton Packaging Market
Cartons
Global Folding Carton Packaging Market
Cartons
End Load Cartoning Machine Market
Cartons
Fluted Carton Trays Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
Carton Sealer Machine Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Luxury Folding Carton Market
Cartons
Global Cartonboard Market
Cartons
Global Open Top Cartons Market
Cartons
Printed Folding Cartons Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Litho Laminated Cartons Market
Cartons
Interlocking Boxes Market
Cartons
Folding Cartons Market