
 Tuck Top Box Market | 2026-2036
Tuck Top Box Market Size, Share, and Industry Trends Forecast 2026-2036
Tuck Top Box Market Analytics
E-commerce fulfillment channels is tilting toward automated packing lines that favor die-cut tuck top configurations. International Paper Company leverages its North American containerboard network to supply high-volume online retailers. WestRock Company anchors its position through integrated corrugated fiberboard operations spanning mills to box plants.
A tuck top box is a paper-based container with flaps that fold and interlock at the top without adhesive or tape, typically manufactured from corrugated fiberboard or carton board in calipers ranging from 200 to 400 gsm, designed for secure closure in shipping and retail display applications. Corrugated fiberboard dominates material selection for heavy-duty logistics, while carton board captures premium cosmetics and electronics packaging where print fidelity matters. Die-cut box formats represent the fastest-growing product type as brands demand bespoke unboxing geometries.
The EPA regulates recycled content thresholds in paper packaging under municipal solid waste guidelines, while the EU Packaging and Packaging Waste Regulation mandates extended producer responsibility schemes that reshape material sourcing across export-oriented manufacturers. FDA compliance requirements for food-contact paperboard add a compliance layer for dairy and ready-meal applications. Stakeholders must weigh virgin versus recycled fiber strategies against tightening traceability mandates before committing to capacity expansion.
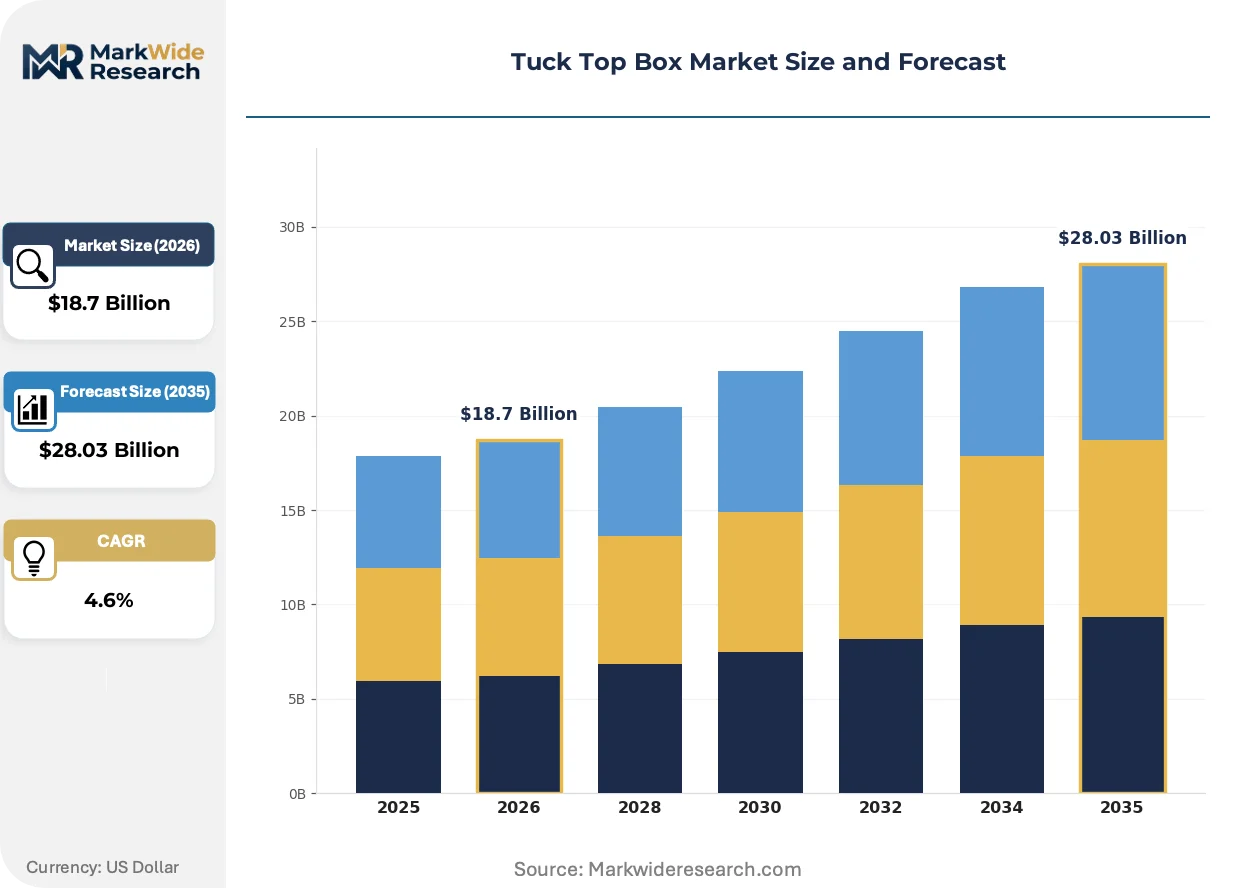
Market Dynamics
Automated e-commerce fulfillment lines are compressing the design-to-delivery cycle for tuck top packaging, forcing converters to align die-cut geometries with robotic packing speeds rather than manual assembly workflows.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility mandates are accelerating fiberboard recycling infrastructure investments across export-oriented manufacturing zones.
- Robotic case erectors:Fulfillment centers in Germany's industrial packaging corridor are specifying tuck top formats that eliminate tape application bottlenecks.
- Cosmetics unboxing economics:Premium beauty brands are commissioning bespoke die-cut geometries that reduce protective void fill requirements.
Market Restraints
- Old corrugated container (OCC) price volatility:Recycled fiber input costs swing with municipal collection program funding cycles, squeezing converter margins.
- Single-source linerboard dependence:Containerboard mill concentration in the US Southeast creates hurricane-season supply vulnerability.
- Dimensional weight pricing:Parcel carriers' volumetric billing algorithms penalize non-optimized box geometries, limiting design freedom.
Strategic Opportunities
- Pharmaceutical cold chain:Insulated tuck top configurations with phase-change material integration address temperature-sensitive biologics distribution gaps.
- India's PLI scheme for paper packaging:Domestic manufacturing incentives are drawing capacity investments away from import-dependent converters.
- Digital print-to-pack workflows:Web-to-box platforms are collapsing minimum order quantities for seasonal promotional packaging.
Industry Challenges
- Die-board tooling lead times:CNC-machined steel rule die procurement stretches 8-12 weeks, constraining rapid prototyping for brand launches.
- FDA food-contact substantiation:Recycled fiber compliance documentation for dairy applications requires extensive migration testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tuck Top Box Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular Slotted Container, Half Slotted Container, Full Flap Container, Die-Cut Box Material: Corrugated Fiberboard, Carton Board, Kraft Paper, Recycled Paper End User: Food & Beverage, Electronics, Cosmetics, Pharmaceuticals Size: Small, Medium, Large, Custom |
| Companies Covered | International Paper Company, WestRock Company, Smurfit Kappa, Packaging Corporation of America, DS Smith, Georgia-Pacific, Mondi Group, Sonoco Products Company, U Pack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tuck Top Box Market Evolving Landscape
Convergence of digital manufacturing workflows with circular material specifications is redefining how converters quote, produce, and recover tuck top packaging across fragmented end-use verticals.
Embedded RFID inlay integration is digitizing supply chain traceability for high-value electronics shipments. Luxury audio equipment manufacturers in Japan are specifying NFC-enabled tuck top boxes that authenticate product provenance at unboxing. This capability is compressing warranty fraud exposure while enabling direct-to-consumer re-engagement channels.
REACH SVHC disclosure requirements are tightening chemical transparency obligations for carton board coatings used in cosmetics packaging. EU-based converters must now map formaldehyde-based wet strength additives through multi-tier supplier networks. Small-batch beauty brands are responding by shifting to uncoated kraft substrates that simplify compliance documentation.
Subscription box procurement is consolidating vendor relationships around vertically integrated converters who control both structural design and lithographic print. Meal kit operators in the United Kingdom are awarding multi-year contracts to partners with in-house CAD/CAM die development capabilities. This pattern concentrates volume with fewer suppliers while raising technical barriers for regional box plants lacking design-engineering staff.
Tuck Top Box Market Segmentation
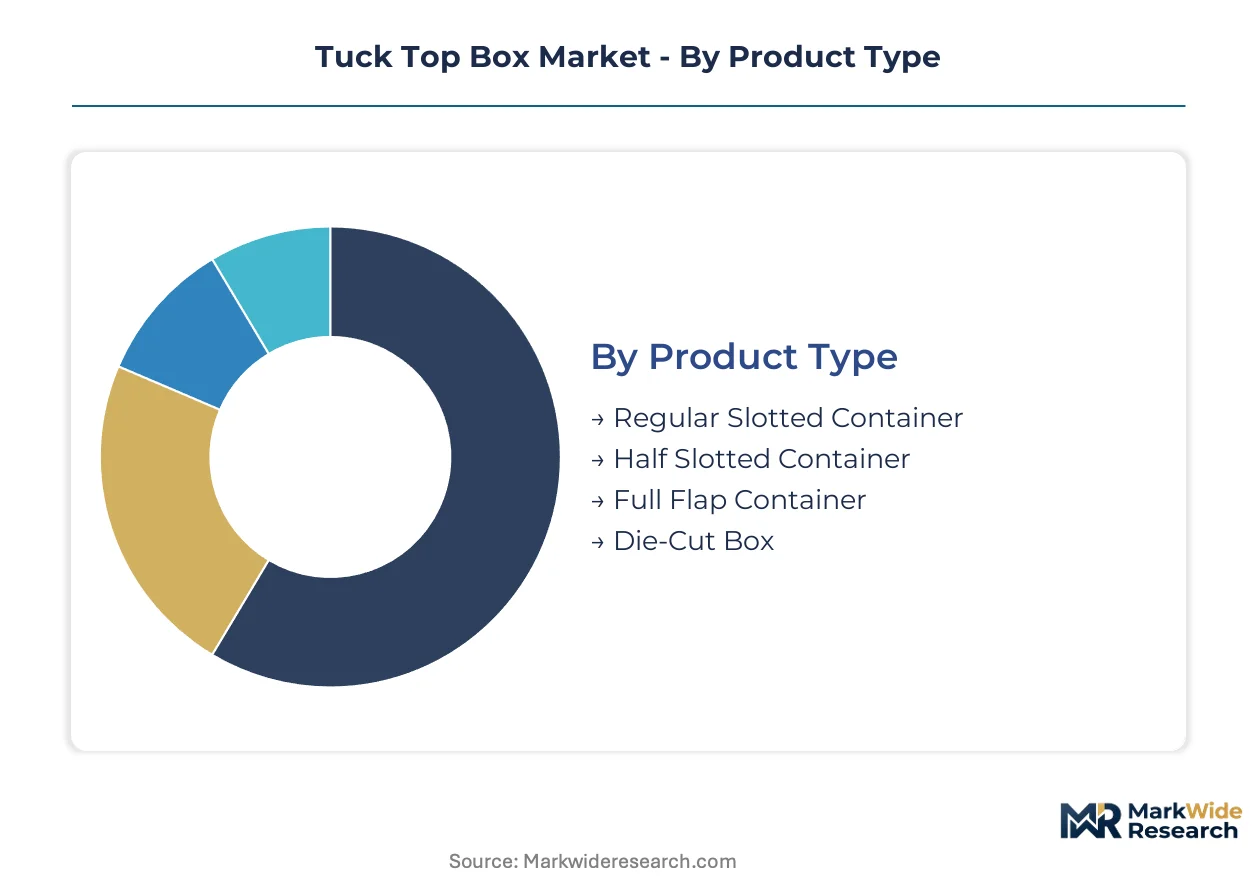
Tuck top box segmentation reveals how material specifications and structural formats align with distinct fulfillment velocities and unboxing requirements. Converters configure production lines around these dimensional boundaries to optimize die-board utilization and print-to-pack workflows.
Product Type:
Cost tier determines automation compatibility and tooling amortization across converter operations.
- Die-Cut Box:Precision-cut geometries with interlocking tabs eliminate tape application in robotic fulfillment lines. E-commerce fulfillment centers in Germany's industrial packaging corridor specify these formats to match case erector throughput speeds. Bespoke unboxing geometries for cosmetics brands reduce void fill requirements while commanding premium unit economics.
- Regular Slotted Container:Standardized flap configurations dominate high-volume logistics with minimal tooling changeover. Food & beverage distributors in the US Midwest rely on these workhorse formats for case-level palletization efficiency. Corrugated fiberboard mills optimize linerboard weights specifically for this geometry's stacking strength requirements.
- Half Slotted Container:Open-top designs accommodate top-loading assembly workflows for bulk produce distribution.
- Full Flap Container:Extended flap coverage provides enhanced protection for flat-pack furniture and glassware shipments.
Regular Slotted Container holds installed capacity. Die-Cut Box is rotating up the share rankings.
Material:
Application requirements for print fidelity, moisture resistance, and structural rigidity drive material selection.
- Corrugated Fiberboard:Fluted medium sandwiched between linerboard facings delivers compression strength for heavy-duty logistics. International Paper Company's North American containerboard network supplies high-volume online retailers with calibrated ECT specifications. Recycled content thresholds under EPA municipal solid waste guidelines shape fiber sourcing strategies.
- Carton Board:Solid bleached sulfate and folding boxboard substrates capture premium cosmetics and electronics packaging where lithographic print quality drives shelf impact. WestRock Company's integrated operations span mills to box plants for consistent caliper control. REACH SVHC disclosure requirements tighten chemical transparency for coated grades used in EU beauty applications.
- Kraft Paper:Unbleached virgin fiber appeals to sustainability-positioned brands seeking simplified compliance documentation.
- Recycled Paper:Post-consumer fiber content responds to extended producer responsibility mandates under EU Packaging and Packaging Waste Regulation.
Corrugated Fiberboard anchors volume throughput. Carton Board is climbing the fastest on value per ton metrics.
End User:
Customer type dictates closure security requirements, barrier properties, and regulatory substantiation burdens.
- E-commerce:Automated packing lines demand die-cut geometries compatible with robotic case erectors and void fill elimination. Parcel carriers' dimensional weight pricing algorithms penalize non-optimized box geometries, forcing structural design discipline. Subscription box procurement consolidates around converters with in-house CAD/CAM capabilities.
- Food & Beverage:FDA food-contact compliance for dairy and ready-meal applications requires extensive migration testing for recycled fiber content. Temperature-controlled distribution drives insulated tuck top configurations with phase-change material integration.
- Cosmetics:Premium unboxing economics commission bespoke structural designs that reduce protective packaging while amplifying brand narrative.
- Pharmaceuticals:Cold chain integrity for biologics distribution demands validated thermal performance in insulated configurations.
E-commerce commands absolute tonnage. Cosmetics is gaining share fastest on margin contribution.
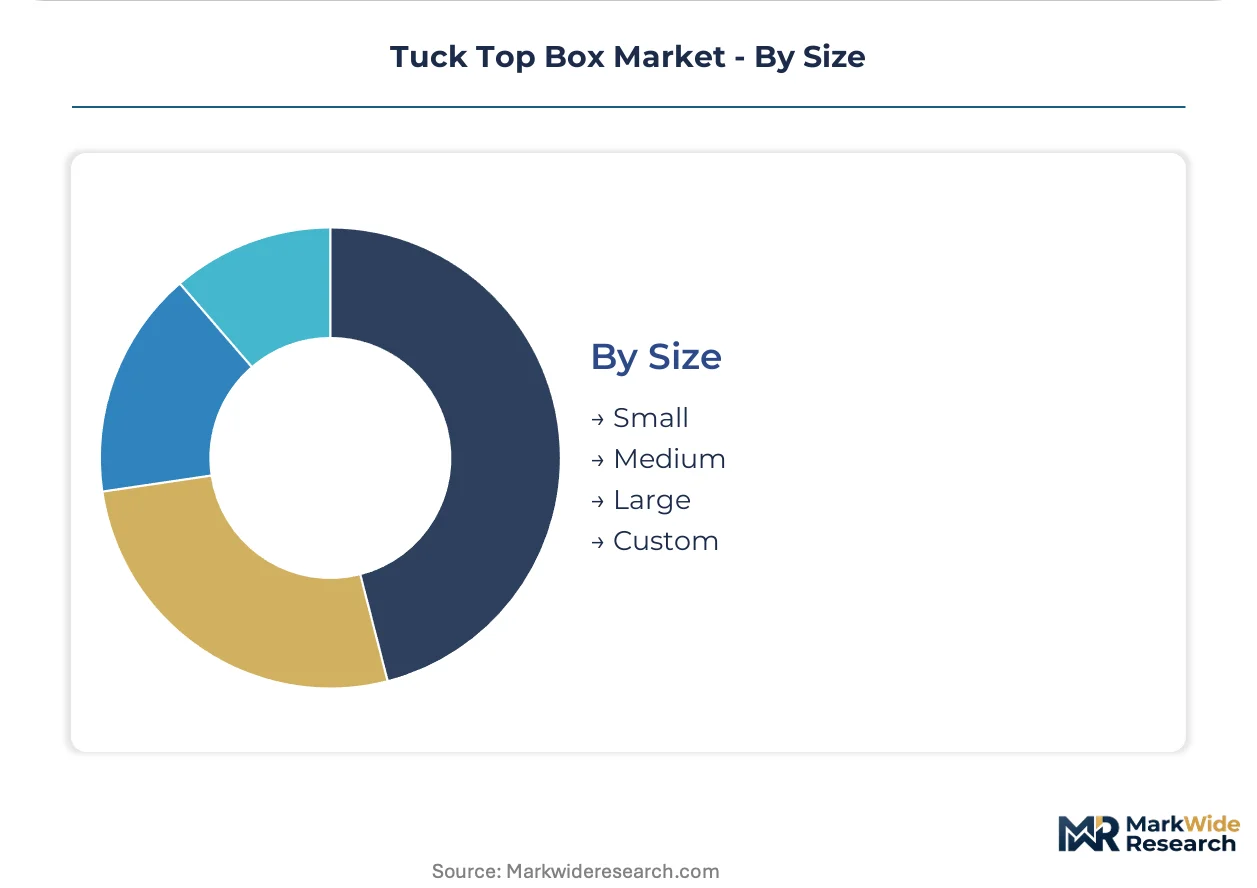
Size:
Volume throughput and tooling utilization rates vary dramatically across dimensional tiers.
- Small:Compact formats for electronics accessories and sample-sized cosmetics optimize parcel carrier dimensional weight algorithms. Digital print-to-pack workflows collapse minimum order quantities for seasonal promotional campaigns.
- Medium:Mid-range dimensions balance pallet cube efficiency with manual handling ergonomics for fulfillment operations.
- Large:Bulk retail and industrial applications require enhanced stacking strength through heavier flute profiles.
- Custom:Non-standard dimensions address dimensional weight pricing optimization and product-specific protection requirements.
Medium holds baseline capacity allocation. Custom is expanding most quickly as brands engineer out void fill.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage tilts toward German converters commanding premium die-cut specifications, while US Gulf Coast suppliers absorb hurricane-season linerboard volatility without commensurate pass-through power.
United States
E-commerce fulfillment networks in Memphis and Louisville drive die-cut tuck top adoption for automated case erector compatibility. EPA municipal solid waste guidelines enforce recycled content thresholds that reshape fiber sourcing strategies for export-oriented manufacturers. Containerboard mill concentration along the Gulf Coast creates supply vulnerability during Atlantic hurricane seasons.
Germany
Industrial packaging corridors in North Rhine-Westphalia anchor European demand for precision die-cut configurations. EU Packaging and Packaging Waste Regulation mandates extended producer responsibility schemes that accelerate fiberboard recycling infrastructure investments. Robotic fulfillment centers in the Ruhr region specify tape-free tuck top formats to eliminate packing line bottlenecks.
China
Cross-border e-commerce platforms in Shenzhen and Hangzhou commission bespoke unboxing geometries for cosmetics and electronics exports. Dual carbon goals under MEE oversight tighten energy intensity standards for containerboard production. Yangtze River Delta converters integrate digital print-to-pack workflows to collapse minimum order quantities for seasonal campaigns.
India
Domestic e-commerce expansion in Mumbai and Bangalore drives demand for automated packing line compatibility. PLI scheme incentives for paper packaging draw capacity investments away from import-dependent converters. Gujarat's industrial corridor attracts integrated mill-to-box plant operations seeking tariff-advantaged export positioning.
United Kingdom
Subscription box operators in London and the Midlands consolidate procurement around converters with in-house CAD/CAM die development capabilities. REACH SVHC disclosure requirements tighten chemical transparency for coated carton board used in premium beauty applications. Meal kit distributors specify multi-year contracts with vertically integrated partners controlling structural design and lithographic print.
Tuck Top Box Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying calibrated linerboard and precision die-board tooling. Market structure concentrates around North American and European containerboard networks with integrated mill-to-box plant operations. Three archetypes dominate: scale-driven containerboard majors, regional converter specialists with captive design engineering, and digital-native platforms collapsing quote-to-delivery cycles. Competitive moves center on backward integration into recycled fiber collection networks and strategic partnerships with robotic case erector OEMs.
Among North American integrated producers, International Paper Company and WestRock Company exemplify scale-driven archetypes with captive containerboard supply. DS Smith represents the European converter specialist model with design-engineering capabilities spanning structural CAD and lithographic print. These three anchors demonstrate how geographic fiber network control and in-house die development capacity separate tier-one suppliers from regional box plants.
| Leading Market Players |
|---|
| International Paper Company |
| WestRock Company |
| Smurfit Kappa |
| Packaging Corporation of America |
| DS Smith |
| Georgia-Pacific |
| Mondi Group |
| Sonoco Products Company |
| U Pack |
| Others |
Value Network & Pricing Analysis
The US Southeast containerboard corridor absorbs hurricane-season supply disruptions that compress converter margins without full cost pass-through to e-commerce fulfillment centers. Old corrugated container price volatility swings with municipal collection funding cycles, forcing tuck top box manufacturers to arbitrage between virgin linerboard spot markets and long-term recycled fiber contracts.
Pricing Analysis
The customization-premium spread separates die-cut bespoke configurations from standard regular slotted containers by a factor driven by CNC-machined steel rule die amortization and CAD/CAM engineering hours. Price differentiation hinges on automation compatibility certification for robotic case erectors and lithographic print fidelity grades for cosmetics applications. Pricing pressure intensifies in the standard container tier as dimensional weight algorithms penalize non-optimized geometries. Subscription box operators show lowest price sensitivity, while bulk produce distributors negotiate aggressively on per-unit economics.
Supply Chain Analysis
Upstream feedstock concentration in the US, Germany, and China determines linerboard availability for tuck top box converters across export-oriented manufacturing zones. The supply chain draws from old corrugated container collection networks, virgin kraft pulp mills, and coated folding boxboard producers. Single-source linerboard dependence on Gulf Coast mills creates hurricane-season vulnerability. Distribution runs through vertically integrated mill-to-box plant networks and regional converter specialists with captive design engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as subscription box operators and meal kit distributors consolidate procurement around fewer converters with in-house CAD/CAM capabilities, compressing vendor counts by half across the United Kingdom and Germany.
For Market Incumbents: Insulate margin position through backward integration into recycled fiber collection networks and strategic partnerships with robotic case erector OEMs. International Paper Company and WestRock Company demonstrate how captive containerboard supply hedges against OCC price volatility. Invest in die-board tooling capacity to collapse 8-12 week lead times that constrain rapid prototyping for brand launches.
For New Entrants and Emerging Players: India's domestic e-commerce corridor offers white-space expansion as PLI scheme incentives draw capacity investments away from import-dependent converters. Target pharmaceutical cold chain applications with insulated tuck top configurations for temperature-sensitive biologics. Pursue digital print-to-pack workflows to collapse minimum order quantities for seasonal promotional campaigns.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with integrated structural design and lithographic print capabilities over pure-play box plants. Long-term viability over a 5-10 year window rests on circular material specifications and extended producer responsibility compliance infrastructure. Watch for EU Packaging and Packaging Waste Regulation enforcement intensity as the inflection signal for fiberboard recycling infrastructure valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Collection | Captures OCC price volatility hedge while satisfying EPA municipal solid waste thresholds. |
| Robotic Case Eector Partnership Program | Locks in die-cut specification demand from Germany's automated fulfillment centers. |
| Digital Print-to-Pack Platform Launch | Collapses minimum order quantities for cosmetics brands running seasonal campaigns. |
| Pharmaceutical Cold Chain Certification | Opens insulated tuck top configurations for biologics distribution gaps. |
| EU Extended Producer Responsibility Compliance Infrastructure | Secures export positioning under tightening Packaging and Packaging Waste Regulation mandates. |
Research Methodology
The analysis maps die-cut box formats, regular slotted containers, carton board grades, and corrugated fiberboard specifications, each validated through converter operations managers, e-commerce fulfillment procurement leads, brand packaging directors, and containerboard mill technical sales staff. Primary interviews triangulate with secondary sources including EPA municipal solid waste guidelines, EU Packaging and Packaging Waste Regulation filings, FDA food-contact substantiation protocols, and customs trade data for linerboard imports. Bottom-up production capacity estimates reconcile with top-down end-use demand segmentation.
The forecast framework holds fixed EU regulatory enforcement timelines and robotic fulfillment adoption curves while varying e-commerce penetration rates and recycled fiber content thresholds across geographies. Segmentation dimensions include product type, material specification, end-use vertical, and dimensional tier. CAGRs derive from production capacity expansion schedules mapped against fulfillment center automation investment pipelines and subscription box shipment growth trajectories.
Practitioners should monitor OCC price index movements, hurricane-season disruption severity, and FDA migration testing protocol revisions for early signals requiring forecast reassessment. Cross-checking against containerboard mill operating rate disclosures and parcel carrier dimensional weight algorithm updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Carton Form Fill Seal Machine Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
Brick Carton Packaging Market
Cartons
Japan Corrugated Boxes Market
Cartons
Foldable/Compressible Beverage Carton Market
Cartons
Carton Bottle Market
Cartons
Pick and Place Carton Packers Market
Cartons
Beverage Cartons Market
Cartons
Microwaveable Carton Market
Cartons
Mono Carton Market
Cartons
Africa Folding Carton Market
Cartons
Twist Opening Cartons Market
Cartons
Shaped Liquid Cartons Market
Cartons
Horizontal Cartoning Machines Market
Cartons
XXL Packaging Market
Cartons
Global Printed Cartons Market