
 Carton Sealer Machine Market | 2026-2036
Carton Sealer Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Carton Sealer Machine Market Outlook
Multi-source procurement for carton sealer components is shifting toward vertically integrated domestic supply chains as lead times and tariff exposure reshape sourcing calculus. Syntegon leverages its European engineering base to sustain premium positioning in pharmaceutical-grade sealing systems. Lantech anchors North American demand through stretch wrapping and carton sealing integration. 3M competes via adhesive and tape technology leadership that extends into OEM partnerships with sealer manufacturers.
A carton sealer machine applies adhesive tape, hot melt glue, or pressure-sensitive material to close and seal corrugated or paperboard containers at throughput rates typically ranging from 15 to 60 cases per minute. The equipment integrates into end-of-line packaging operations to secure products for palletization, storage, and distribution with consistent seal integrity. Automatic sealers command the largest installed base due to labor cost pressures in high-volume food and beverage plants, while semi-automatic units retain strength among small-batch consumer goods producers with frequent changeovers. Hot melt technology captures expanding share where tamper-evident seals and fiber-reinforced tape meet pharmaceutical and e-commerce validation requirements.
The U.S. OSHA governs operator safety interlocks and guarding standards that elevate machine design costs for entrants lacking established compliance infrastructure. The EU Machinery Directive and CE marking framework shape export viability for Chinese and American manufacturers selling into European food processing and logistics markets. Stakeholders must monitor adhesive formulation regulations from ECHA and EPA simultaneously, as dual-jurisdiction compliance becomes a prerequisite for multinational packaging contracts rather than a competitive differentiator.
Market Dynamics
E-commerce fulfillment centers are compressing sealing cycle times while REACH compliance on adhesive emissions forces hot-melt and tape-sealing retrofits across European installed bases.
Growth Catalysts
- EU REACH adhesive mandates:Emission caps on solvent-based formulations push food processors toward hot-melt systems that eliminate volatile organic compound exposure during case sealing operations.
- China domestic machinery scaling:Local packaging equipment manufacturers expand production capacity to capture both indigenous demand and export orders from Southeast Asian logistics hubs.
- Pharmaceutical validation protocols:Tamper-evident fiber-reinforced tape specifications from FDA and EMA drive replacement cycles in sterile packaging lines.
Market Restraints
- Steel and servo motor input volatility:Carbon steel frame costs fluctuate with commodity indexes, compressing margins for mid-tier automatic sealer producers without captive metalworking.
- Control system supplier concentration:PLC and HMI modules concentrate among German and Japanese automation vendors, exposing assemblers to 26-week lead times during semiconductor shortages.
- Hot-melt adhesive substitution ceiling:Pressure-sensitive tape retains cost advantage in ambient-temperature beverage distribution, limiting hot-melt penetration in high-volume water and soft drink plants.
Strategic Opportunities
- India PLI scheme for packaging machinery:Production-linked incentives attract component localization investments to serve domestic FMCG and pharmaceutical contract manufacturers.
- Retrofit automation kits:Semi-automatic sealers upgrade to automatic throughput via modular feeder and discharge attachments, extending equipment life for small-batch cosmetics producers.
- CE marking acceleration services:Third-party conformity assessment providers reduce EU market entry timelines for Chinese sealer exporters facing Machinery Directive complexity.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of servo-driven sealing heads requires cross-trained electricians and mechanics, a skill profile in short supply across Midwest US manufacturing clusters.
- Legacy WMS integration friction:New sealers must communicate with decade-old warehouse management systems through middleware development, delaying commissioning in established distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carton Sealer Machine Market |
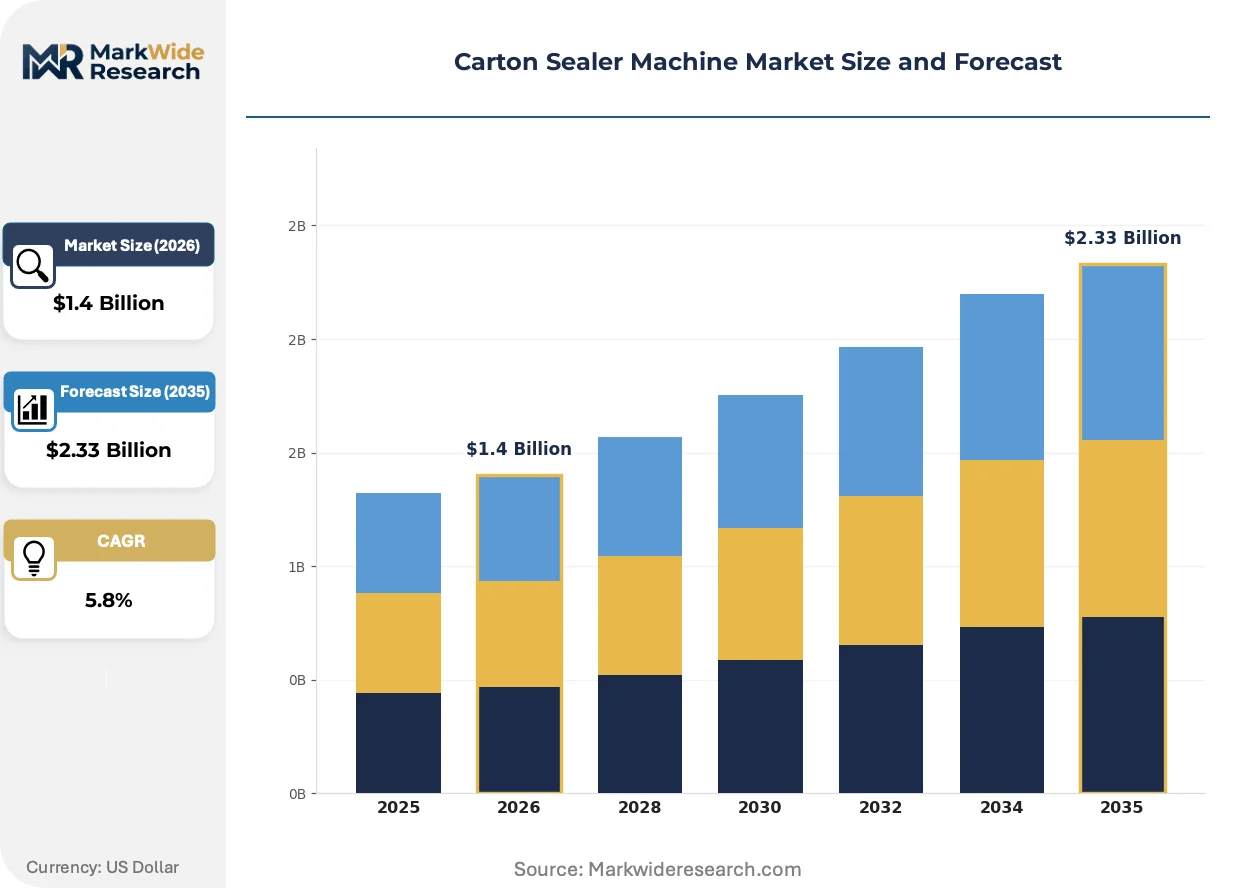
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Stationary Technology: Hot Melt, Pressure Sensitive, Tape Sealing, Adhesive End User: Food & Beverage, Pharmaceuticals, Consumer Goods, E-Commerce Packaging Type: Plastic, Corrugated, Metal, Paper |
| Companies Covered | Intertape Polymer Group, Syntegon, Lantech, BestPack Packaging Systems, 3M, Combi Packaging Systems LLC, Hualian, Packway Inc., Pearson Packaging Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carton Sealer Machine Market Strategic Shifts
Sealing equipment architecture is fragmenting into interoperable subsystems as end-users demand changeover flexibility without full line replacement.
Collaborative robot feeding stations are modularizing case presentation and discharge functions, allowing pharmaceutical packagers to reconfigure line layouts within shift changes rather than weekend shutdowns. Contract manufacturers in New Jersey and North Carolina deploy these units to handle multiple SKUs with divergent case dimensions. The technology is modularizing capital deployment patterns, converting fixed automation investments into reconfigurable operating expenditures.
EPA enforcement of adhesive hazardous air pollutant standards tightens emissions monitoring at tape coating facilities, elevating compliance costs for pressure-sensitive suppliers serving food-contact applications. Tape manufacturers respond with water-based acrylic formulations that sacrifice initial tack for regulatory clearance. Beverage bottlers in California and Texas face reformulation-driven seal integrity validation delays of four to six months.
Maintenance contract unbundling accelerates as third-party service providers capture retrofit and spare parts revenue previously retained by OEMs. Independent technicians in Ohio and Pennsylvania now perform PLC programming and hot-melt tank rebuilds on multi-brand equipment fleets. This pattern concentrates in regions with dense food processing and e-commerce fulfillment footprints where uptime penalties exceed annual service contract values.
Carton Sealer Machine Market Segmentation
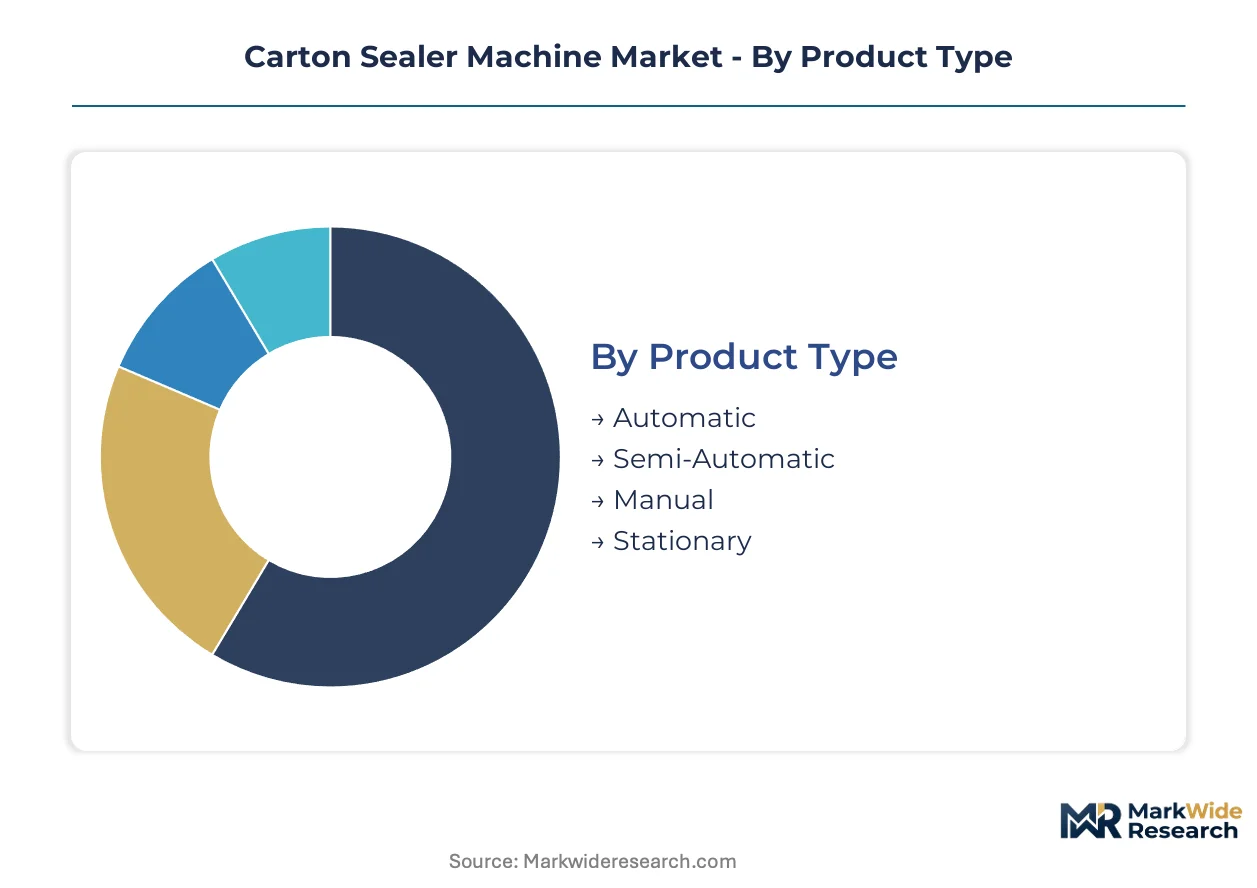
Carton sealer procurement patterns diverge sharply between high-throughput automated installations and flexible semi-automatic configurations. Understanding these splits enables equipment suppliers to align R&D investment with operational constraints across food processing, pharmaceutical validation, and e-commerce fulfillment environments.
Product Type:
Automatic sealers command premium pricing through servo-driven throughput, while semi-automatic units balance labor input with capital efficiency for batch operations.
- Automatic:Servo-controlled sealing heads achieve 15-60 cases per minute with consistent tape tension and hot-melt bead placement. Demand concentrates in Coca-Cola and PepsiCo bottling plants where OSHA-mandated guarding integrates with existing line safety architectures.
- Semi-Automatic:Operators present cases to fixed sealing heads, enabling 8-20 cases per minute with rapid format changeover. New Jersey and North Carolina contract manufacturers deploy these for multi-SKU cosmetics packaging where batch sizes fall below automatic changeover thresholds.
- Manual:Hand-held tape dispensers and bench-top units serve micro-fulfillment operations with sub-50 case daily volumes.
- Stationary:Fixed-base sealers anchor dedicated production lines without mobility requirements, common in steel-framed beverage distribution centers.
Mature deployment sits with Automatic sealers in Fortune 500 food and beverage plants. Newer deployment is concentrated in Semi-Automatic units among regional contract packagers serving direct-to-consumer brands.
Technology:
Sealing chemistry selection tracks regulatory jurisdiction, with hot-melt systems gaining share where REACH and EPA emissions caps constrain solvent-based alternatives.
- Hot Melt:Thermoplastic adhesives create tamper-evident fiber-reinforced bonds with 2-5 second set times. Pharmaceutical packagers in Germany and Switzerland specify these for EMA validation protocols requiring seal integrity documentation.
- Pressure Sensitive:Acrylic and rubber-based tapes adhere at ambient temperatures without thermal activation. Water-based formulations from 3M and tesa respond to EPA hazardous air pollutant enforcement in California and Texas coating facilities.
- Tape Sealing:Polypropylene and PVC tape systems dominate beverage distribution for cost efficiency in high-volume water and soft drink plants.
- Adhesive:Solvent-based formulations retreat to non-food industrial applications as REACH emission caps and FDA food-contact restrictions tighten.
Established penetration sits with Tape Sealing in ambient-temperature beverage logistics. Steepest expansion trajectory belongs to Hot Melt systems in pharmaceutical and e-commerce validation environments.
End User:
End-use demand intensity correlates with regulatory validation burden and throughput consistency requirements.
- Food & Beverage:High-volume plants integrate automatic sealers with palletizing robotics. USDA-inspected facilities specify stainless steel contact surfaces and washdown-rated enclosures.
- Pharmaceuticals:FDA and EMA tamper-evident mandates drive fiber-reinforced tape specifications with serialization compatibility. sterile packaging lines in New Jersey and North Carolina require IQ/OQ/PQ documentation packages.
- Consumer Goods:Cosmetics and personal care packagers prioritize changeover speed over raw throughput, favoring semi-automatic configurations with quick-release tooling.
- E-Commerce:Amazon and Shopify fulfillment centers compress cycle times through automatic random-case sealers with dynamic box-sizing integration.
Deep installed base sits with Food & Beverage. Emerging deployment concentrates in E-Commerce as order velocity outstrips manual sealing capacity.
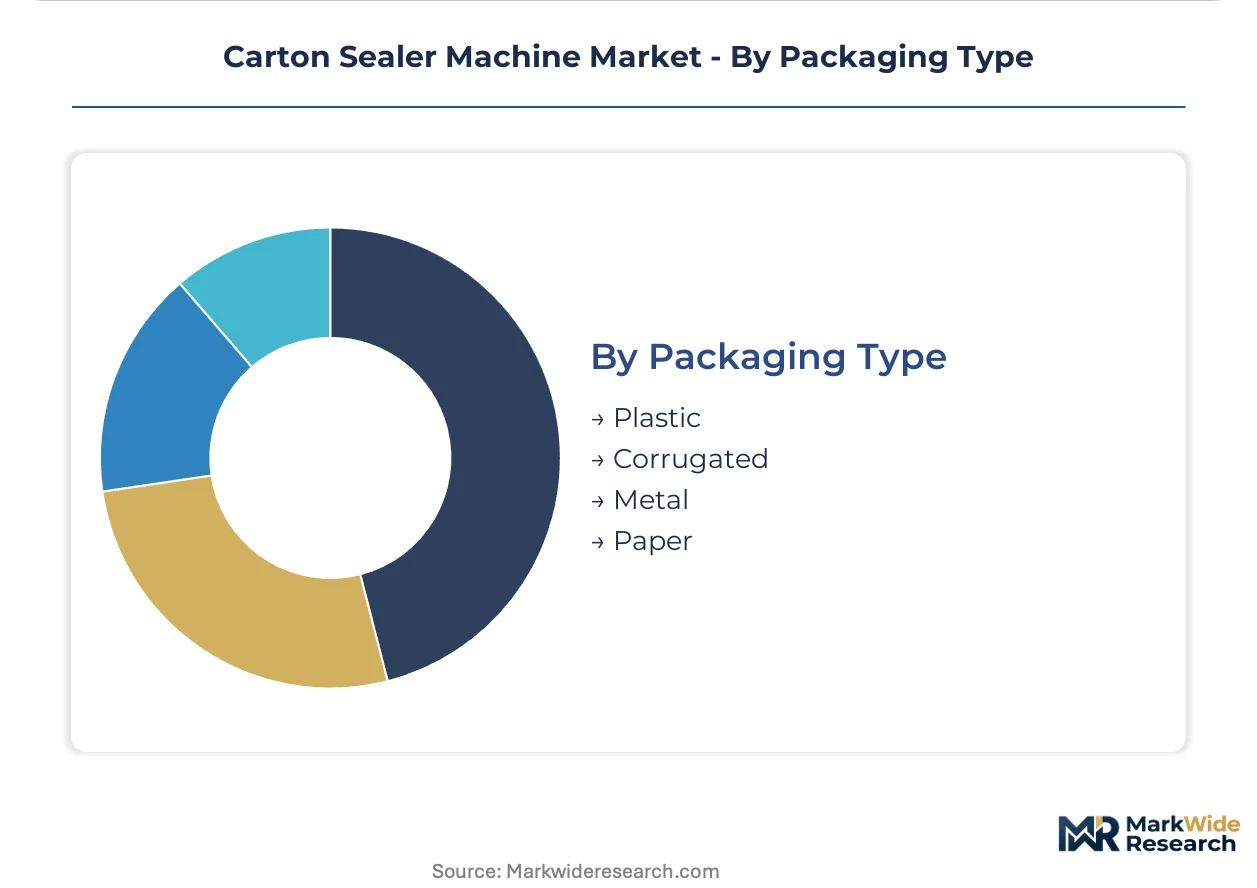
Packaging Type:
Substrate compatibility determines sealing head geometry and adhesive formulation selection.
- Corrugated:Recycled flute structures dominate shipping container specifications. Kraft liner tape adhesion varies with recycled content percentage, requiring hot-melt compensation in high-recycling-content boards.
- Plastic:Polyethylene and polypropylene cases in personal care and chemical distribution demand surface-activated adhesive systems or mechanical closure.
- Paper:Lightweight ecommerce mailers and book wraps use pressure-sensitive tape with fiber reinforcement for tear resistance.
- Metal:Tin and aluminum containers in specialty food and aerosol applications require crimp-sealing rather than adhesive methods, limiting addressable sealer market.
Volume concentration sits with Corrugated across all end-use segments. Technology evolution targets Plastic compatibility as sustainable packaging shifts from fiber to film substrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates carton sealer demand as domestic packaging machinery production scales to serve both local e-commerce fulfillment centers and export orders across Southeast Asian logistics hubs. Equipment procurement intensity correlates with warehouse automation density and regulatory validation requirements in each jurisdiction.
China
Domestic machinery manufacturers expand production capacity to capture indigenous demand from JD.com and Alibaba fulfillment networks. MIIT industrial upgrading guidelines incentivize servo-driven automation adoption in packaging equipment. Yangtze River Delta machinery clusters in Shanghai and Jiangsu province ship automatic sealers to Vietnam and Indonesia distribution centers.
United States
Amazon and Shopify fulfillment centers compress sealing cycle times through random-case automatic systems with dynamic box-sizing integration. OSHA operator safety interlock mandates elevate machine design costs for equipment lacking established compliance infrastructure. New Jersey and North Carolina pharmaceutical contract manufacturers specify tamper-evident fiber-reinforced tape systems for FDA validation protocols.
Germany
Food processors retrofit solvent-based adhesive systems to hot-melt alternatives under REACH emission caps on volatile organic compounds. EU Machinery Directive CE marking requirements shape export viability for Chinese and American manufacturers entering European markets. Bavarian packaging machinery specialists engineer pharmaceutical-grade sealing systems for EMA compliance documentation.
India
Production-linked incentive schemes attract component localization investments to serve domestic FMCG and pharmaceutical contract manufacturers. BIS certification requirements for industrial machinery create compliance entry barriers for unverified foreign suppliers. Maharashtra and Gujarat industrial corridors host emerging packaging equipment assembly operations for regional consumer goods brands.
Japan
Precision manufacturing standards from METI drive quality specifications for servo motor integration in high-throughput sealing heads. Pharmaceutical exporters require serialization-compatible tamper-evident systems for international market access. Kanto region machinery builders supply cosmetic and personal care packagers with rapid-changeover semi-automatic configurations.
Carton Sealer Machine Market Competitive Environment
Strategic partnerships dominate the current landscape as equipment manufacturers seek adhesive technology integration and regional distribution access. The vendor base organizes into three tiers: multinational automation conglomerates with end-of-line integration capabilities, regional machinery specialists serving validation-intensive pharmaceutical segments, and emerging Asian fabricators competing on capital efficiency. Two strategic archetypes predominate: tape and adhesive technology suppliers extending into OEM equipment partnerships, and packaging machinery pure-plays building stretch wrapping and sealing integration. Competitive moves concentrate on M&A for control system capabilities and capacity expansion in Southeast Asian assembly operations.
Among diversified adhesive and materials suppliers, 3M exemplifies technology-led positioning that extends pressure-sensitive tape formulations into equipment manufacturer partnerships. Syntegon occupies a position within the premium pharmaceutical-grade tier, leveraging European engineering bases for validation-intensive sealing systems. Lantech anchors North American demand through stretch wrapping and carton sealing integration capabilities. These three represent distinct competitive vectors: materials science extension, regulatory-specialized engineering, and regional end-of-line integration.
| Leading Market Players |
|---|
| Intertape Polymer Group |
| Syntegon |
| Lantech |
| BestPack Packaging Systems |
| 3M |
| Combi Packaging Systems LLC |
| Hualian |
| Packway Inc. |
| Pearson Packaging Systems |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade CE-marked systems and commodity beverage sealers occupy divergent value bands that reshape both procurement budgets and supplier sourcing footprints across European and Asian manufacturing clusters. Equipment buyers in FDA-validated environments absorb 40-60% premiums for IQ/OQ/PQ documentation packages and stainless steel washdown ratings, while high-volume water bottlers in China and the United States prioritize capital efficiency over certification depth.
Pricing Analysis
High-volume automatic sealers trade volume for margin compression as Chinese domestic manufacturers capture share in 15-60 case-per-minute installations, while pharmaceutical-grade systems sustain premium capture through EMA validation protocols. Price differentiation stratifies across CE certification tier, servo motor specification grade, and aftermarket service bundling intensity. Pricing pressure stems from carbon steel frame cost volatility and 26-week PLC lead times squeezing mid-tier assemblers without captive metalworking. Contract packagers in New Jersey and North Carolina exhibit highest price sensitivity due to SKU fragmentation, whereas German pharmaceutical exporters prioritize seal integrity documentation over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Amazon and Coca-Cola bottling networks, while regional distributors serve small-batch cosmetics producers with semi-automatic configurations. Component sourcing concentrates in Germany and Japan for servo motors and PLC modules, China for carbon steel frames and basic pneumatics, and the United States for pressure-sensitive tape formulations. Raw material dependencies include cold-rolled carbon steel, semiconductor-grade servo controllers, and hot-melt adhesive polymers. Supply chain risk centers on single-source vulnerability in Japanese automation electronics during semiconductor allocation cycles. Distribution runs through OEM direct sales for Fortune 500 accounts and machinery dealer networks for regional contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around equipment suppliers with captive control system capabilities and established CE marking infrastructure, as REACH compliance complexity and servo motor scarcity eliminate margin-tightened pure-play assemblers.
For Market Incumbents: Anchor defensive positioning through backward integration into servo motor assembly partnerships and captive hot-melt tank manufacturing to offset 26-week Japanese PLC lead times. Fortify CE marking acceleration services and IQ/OQ/PQ documentation capabilities to sustain pharmaceutical-grade premium capture against emerging Chinese exporters. Prioritize retrofit automation kit development for installed base retention as third-party service providers erode aftermarket revenue. For New Entrants and Emerging Players: Launch via modular feeder attachment sales to semi-automatic installed bases in North Carolina and Ohio contract manufacturing corridors, bypassing capital-intensive automatic sealer development. Target India's PLI scheme beneficiary facilities in Maharashtra and Gujarat with localized component sourcing partnerships. Pursue water-based acrylic tape formulation partnerships with EPA-compliant coating facilities to exploit California and Texas beverage bottler reformulation windows. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier European specialists possessing CE marking infrastructure and pharmaceutical validation relationships given REACH enforcement acceleration and FDA tamper-evident mandate expansion. Long-term viability favors equipment assemblers with backward integration into control system capabilities and Southeast Asian assembly footprint. Watch semiconductor allocation normalization in Japanese automation electronics as inflection indicator for margin recovery in servo-dependent premium tier.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Assembly | Mitigates 26-week lead time exposure from Japanese PLC vendors during allocation cycles. |
| CE Marking Acceleration Service Launch | Reduces EU market entry timelines for Chinese exporters facing Machinery Directive complexity. |
| Retrofit Automation Kit Development | Captures upgrade revenue from semi-automatic installed bases in cosmetics contract manufacturing. |
| Hot-Melt Formulation Partnership | Aligns with EPA hazardous air pollutant enforcement in California and Texas coating facilities. |
| India PLI Scheme Facility Investment | Localizes component production for domestic FMCG and pharmaceutical contract manufacturers. |
Study Parameters
Independent corroboration across packaging machinery OEM technical directors, plant engineers at Fortune 500 beverage bottlers, pharmaceutical validation specialists, and aftermarket service technicians underwrites the qualitative findings in this study. Primary fieldwork engaged maintenance directors and procurement leads at e-commerce fulfillment centers, supplemented by secondary validation from EU Machinery Directive guidance documents, EPA hazardous air pollutant enforcement records, FDA tamper-evident packaging guidelines, and MIIT industrial upgrading circulars. Bottom-up equipment shipment analysis triangulates against top-down end-use demand modeling across food processing, pharmaceutical, and consumer goods verticals.
Rate-of-change decomposition separates volume effects from mix shifts and pricing dynamics across the projection horizon. Segmentation modeling incorporates product type tier, sealing technology chemistry, end-use regulatory intensity, and geographic production cluster dimensions. CAGRs derive from equipment replacement cycle analysis, e-commerce fulfillment center buildout trajectories, and REACH compliance retrofit penetration curves. Industry-specific inputs include pharmaceutical serialization mandate timelines and carbon steel commodity index volatility patterns.
Semiconductor allocation disruptions, REACH adhesive emission cap enforcement intensity, and China domestic machinery export financing availability are the dominant revision risks to modeled outcomes. Forecasts reflect base-case assumptions regarding regulatory implementation pacing and input cost normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Beverage Cartons Market
Cartons
Braille Cartons Packaging Market
Cartons
Luxury Folding Carton Market
Cartons
Carton Liners Market
Cartons
Shaped Corrugated Packaging Market
Cartons
MET-PET Cartons Market
Cartons
Pizza Cartons Market
Cartons
Metallized PET Cartons Market
Cartons
Global Printed Cartons Market
Cartons
North America Corrugated Boxes Market
Cartons
Carton Serialization Machine Market
Cartons
Africa Folding Carton Market
Cartons
Child-Resistant Carton Box Market
Cartons
Soap Boxes Market
Cartons
Pulp Roll Cradles Market
Cartons
GCC Folding Carton Market