
 North America Packaging Tapes Market | 2026-2036
North America Packaging Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Packaging Tapes Market Insights
Adhesive chemist shortages across the Midwest and Southeast are redrawing where manufacturers locate technical centers and pilot lines. 3M Company leverages its captive polymer research campus in Minnesota to sustain formulation leadership without relying on external talent pools. Intertape Polymer Group anchors its competitive stance through backward integration into film extrusion, controlling resin conversion costs across its North American footprint.
North America packaging tapes comprise pressure-sensitive adhesive systems laminated to flexible backings, typically measuring 48 mm to 72 mm in width and engineered to deliver shear resistance exceeding 500 minutes per PSTC-107 test protocols for secure carton closure through temperature cycling. Carton sealing tapes occupy the dominant volume position, though water-activated variants are gaining share in corrugated recycling streams where repulpability standards are tightening. Polypropylene backings lead material usage for cost-sensitive industrial applications, while PVC retains preference in food and beverage cold-chain logistics where moisture resistance is non-negotiable.
The US EPA regulates volatile organic compound emissions from adhesive coating operations under Clean Air Act Title V permitting, pushing converters toward hot-melt and UV-cured systems. Health Canada and the PMRA oversee chemical migration limits for food-contact tapes, creating dual compliance burdens for cross-border suppliers. California's Department of Toxic Substances Control maintains additional Safer Consumer Products regulations that function as de facto North American design constraints. Stakeholders must monitor how state-level extended producer responsibility bills in New York and Washington reshape downstream collection obligations for tape-containing packaging waste.
Market Dynamics
The EPA's Clean Air Act Title V permitting regime is forcing coating operations across the United States to abandon solvent-based adhesive systems, redirecting capital toward hot-melt and UV-cured alternatives that demand entirely different production footprints and technical competencies.
Growth Catalysts
- E-commerce fulfillment expansion:Third-party logistics providers operating mega-warehouses in Georgia, Texas, and Ohio are consuming carton sealing tapes at volumes that justify dedicated slitting and distribution facilities adjacent to their sortation hubs.
- California Safer Consumer Products regulations:The state's DTSC mandates on chemical disclosure are accelerating reformulation investments that yield repulpable water-activated tapes compatible with corrugated recycling infrastructure.
- Polypropylene backing cost advantages:Resin price stability relative to PVC and paper alternatives is cementing this material's dominance in industrial packaging applications across cost-sensitive Midwest manufacturing corridors.
Market Restraints
- Petrochemical feedstock volatility:Propylene monomer supply disruptions originating from Gulf Coast refining complexes transmit directly to polypropylene film costs, compressing converter margins without pricing power to pass through.
- Adhesive chemist scarcity:Talent pipeline failures at Midwest and Southeast universities are constraining formulation innovation capacity, forcing manufacturers to relocate technical centers to Minnesota and Massachusetts where polymer science programs remain robust.
- PVC cold-chain lock-in:Food and beverage distributors cannot substitute polypropylene tapes for moisture-critical refrigerated applications, trapping volume in higher-cost backing categories resistant to material switching.
Strategic Opportunities
- Mexico nearshoring corridor:Automotive and electronics manufacturers relocating assembly from Asia to Baja California and Querétaro are generating demand for export-compliant packaging tapes with dual US-Mexico regulatory certifications.
- Extended producer responsibility legislation:New York and Washington state bills mandating downstream collection of packaging waste create service-revenue streams for tape suppliers offering take-back logistics alongside product sales.
- Smart tape convergence:Integration of RFID inlays and printable sensors into pressure-sensitive constructions is opening track-and-trace applications in pharmaceutical distribution and high-value electronics fulfillment.
Industry Challenges
- PSTC certification timeline compression:Shear resistance and peel adhesion testing protocols required for major retailer supplier qualification now demand 12-16 week validation cycles that delay new product commercialization.
- Legacy coating line retrofit costs:Converters operating solvent-based equipment face $4-8 million capital outlays per facility to install hot-melt or UV systems compliant with Title V permits, straining mid-tier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Packaging Tapes Market |
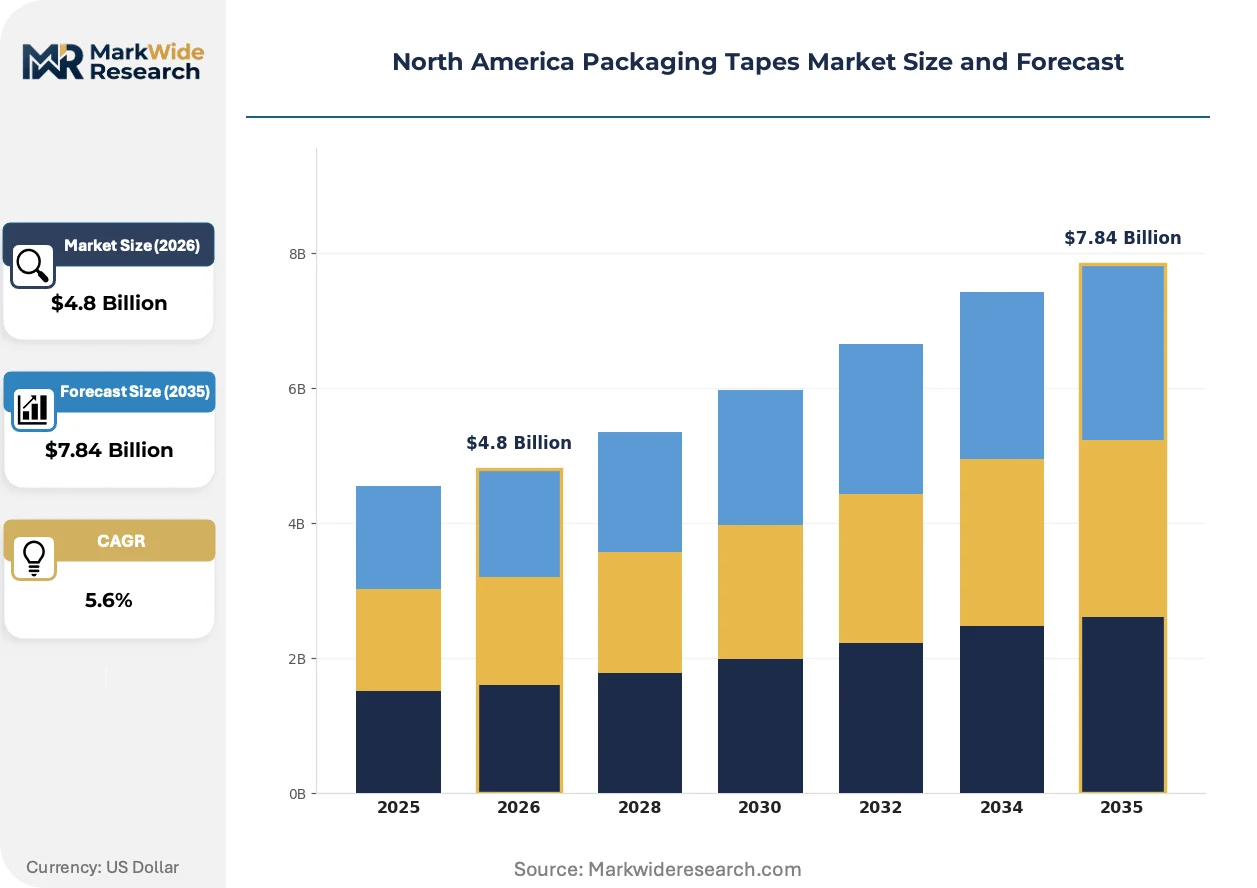
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carton Sealing, Stretch Film, Strapping, Water-Activated Material: Plastic, Paper, PVC, Polypropylene End User: Retail, E-Commerce, Food & Beverage, Industrial Distribution Channel: Online, Retail Stores, Direct Sales, Distributors |
| Companies Covered | 3M Company, Intertape Polymer Group Inc., Avery Dennison Corporation, Berry Global Inc., Shurtape Technologies LLC, Nitto Denko Corporation, Mactac LLC, CCT Tapes, Tesa Tape Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Packaging Tapes Market Trends and Innovations
Adhesive chemistry and backing material evolution is fragmenting the competitive landscape into specialists commanding premium positions versus commodity converters trapped in price-driven segments.
Water-activated tape formulations incorporating synthetic resin adhesives are displacing traditional gummed kraft tapes in corrugated recycling streams. Amazon and Walmart distribution centers in Tennessee and Pennsylvania are adopting these variants at scale to meet internal sustainability targets. This displacement is compressing market share for conventional pressure-sensitive carton sealing tapes in e-commerce channels where repulpability verification is becoming a procurement gate.
Health Canada and the PMRA are tightening chemical migration limits for food-contact adhesive tapes, forcing cross-border suppliers to maintain dual formulation inventories. The industrial consequence is elevated compliance costs for converters serving both US and Canadian markets. Cold-chain logistics segments serving Ontario and Quebec food processing clusters are responding by consolidating supplier relationships with vendors holding Health Canada Drug Establishment Licences.
Buyer concentration among third-party logistics providers is compressing purchasing cycles and demanding vendor-managed inventory arrangements. Regional 3PLs operating Southeast warehousing clusters are replacing spot-buying with multi-year supply agreements that bundle tape, stretch film, and corrugated into single-source contracts. This consolidation is most visible in Georgia and South Carolina, where Prologis and Duke Realty industrial parks have concentrated fulfillment demand within 50-mile radii.
North America Packaging Tapes Market Segmentation
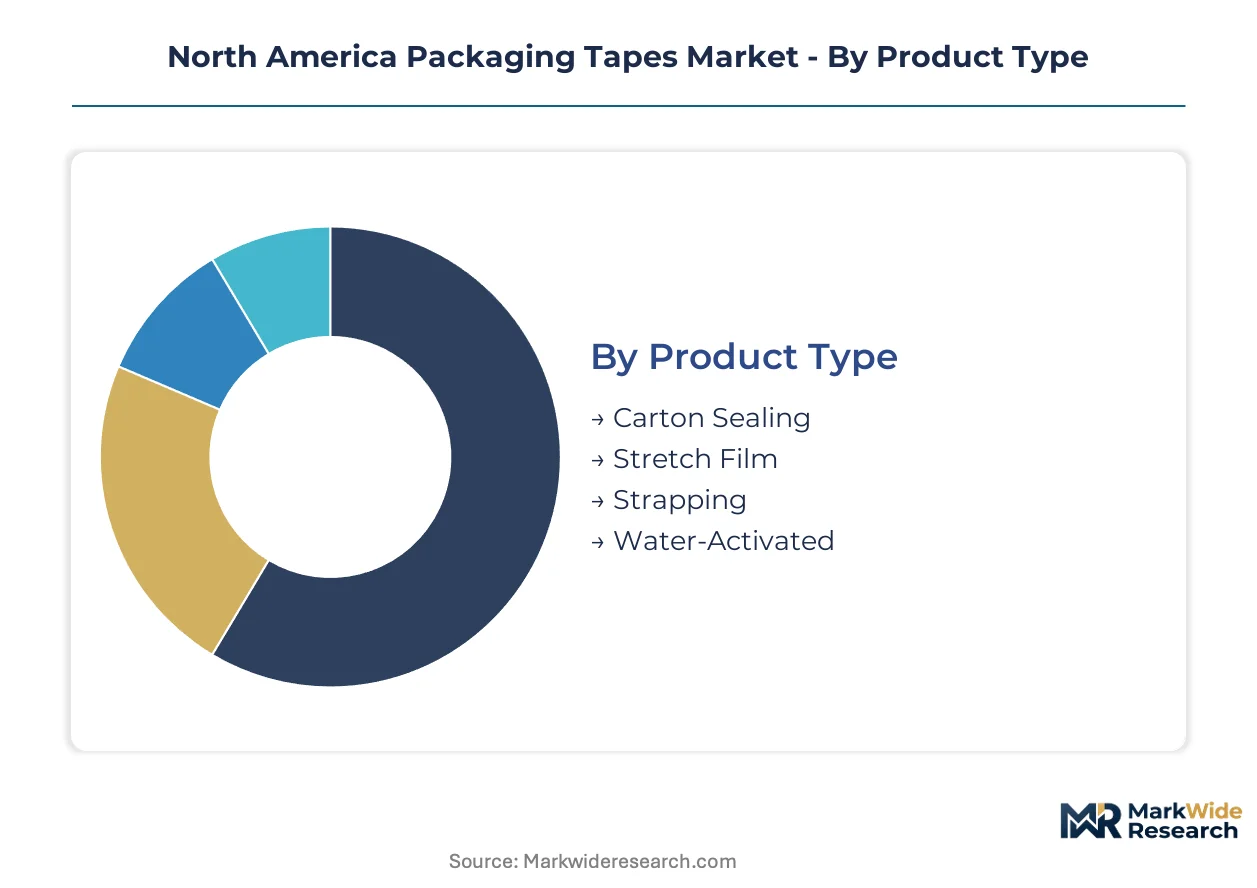
Packaging tape segmentation in North America reflects divergent supply chain logics across e-commerce fulfillment, industrial manufacturing, and food distribution channels. Each dimension—product construction, material substrate, end-use application, and procurement pathway—carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Domestic consumption concentrates in carton sealing variants serving US Southeast warehousing clusters, while water-activated formats find stronger traction in Canadian corrugated recycling streams governed by stricter repulpability standards.
- Carton Sealing:Pressure-sensitive adhesive systems laminated to polypropylene or PVC backings, typically 48-72 mm width, engineered for shear resistance exceeding 500 minutes per PSTC-107 protocols. Third-party logistics providers operating mega-warehouses in Georgia, Texas, and Ohio consume these at volumes justifying dedicated slitting facilities adjacent to sortation hubs.
- Water-Activated:Synthetic resin adhesives on reinforced paper backings that bond molecularly with corrugated fibers. Amazon and Walmart distribution centers in Tennessee and Pennsylvania are adopting these variants at scale to meet internal sustainability targets and corrugated recycling compatibility requirements.
- Stretch Film:Linear low-density polyethylene formulations for pallet unitization, distinct from adhesive tapes but bundled in packaging supply contracts. Demand concentrates in Midwest automotive parts distribution.
- Strapping:Polypropylene and polyester bands for heavy-load securing in industrial applications. Steel variants retain share in construction materials shipping.
Carton sealing holds the largest share; momentum sits with water-activated formats gaining procurement preference in sustainability-focused e-commerce channels.
Material:
Cost tier differentiation separates commodity resin-dependent substrates from specialty backings commanding cold-chain premiums, with polypropylene anchoring volume and PVC defending margin in moisture-critical applications.
- Polypropylene:Biaxially oriented film extruded from propylene monomer, delivering cost stability relative to PVC and paper alternatives. Resin price volatility originating from Gulf Coast refining complexes transmits directly to converter margins, compressing profitability without pricing power to pass through.
- PVC:Calendered vinyl backings with inherent moisture barrier properties essential for refrigerated food and beverage logistics. Food distributors cannot substitute polypropylene for these cold-chain applications, trapping volume in higher-cost categories resistant to material switching.
- Paper:Kraft and reinforced paper backings for water-activated and gummed tape constructions. Repulpability advantages align with California DTSC mandates and extended producer responsibility legislation in New York and Washington.
- Plastic:Catch-all category encompassing polyethylene and specialty film backings for niche industrial applications. Limited differentiation from polypropylene in standard carton sealing.
Polypropylene dominates volume throughput; PVC defends the steepest expansion trajectory in cold-chain segments where moisture resistance is non-negotiable.
End User:
Customer type fragmentation splits between high-velocity e-commerce procurement with vendor-managed inventory demands versus industrial spot-buying patterns in Midwest manufacturing corridors.
- E-Commerce:Third-party logistics providers and direct-to-consumer fulfillment operations driving tape consumption through automated carton sealing lines. Regional 3PLs in Georgia and South Carolina are consolidating purchasing into multi-year supply agreements bundling tape, stretch film, and corrugated.
- Industrial:Midwest manufacturing facilities consuming cost-sensitive polypropylene carton sealing tapes at scale. Procurement patterns favor distributor relationships over direct manufacturer contracts.
- Food & Beverage:Cold-chain distributors and processors requiring PVC-backed moisture-resistant tapes for refrigerated transport. Health Canada and PMRA chemical migration limits create dual compliance burdens for cross-border suppliers.
- Retail:Brick-and-mortar distribution centers with seasonal demand spikes and less stringent sustainability requirements than e-commerce counterparts.
E-commerce holds the largest share; food and beverage is climbing the fastest as cold-chain infrastructure expands across the US Southeast and Ontario-Quebec corridors.
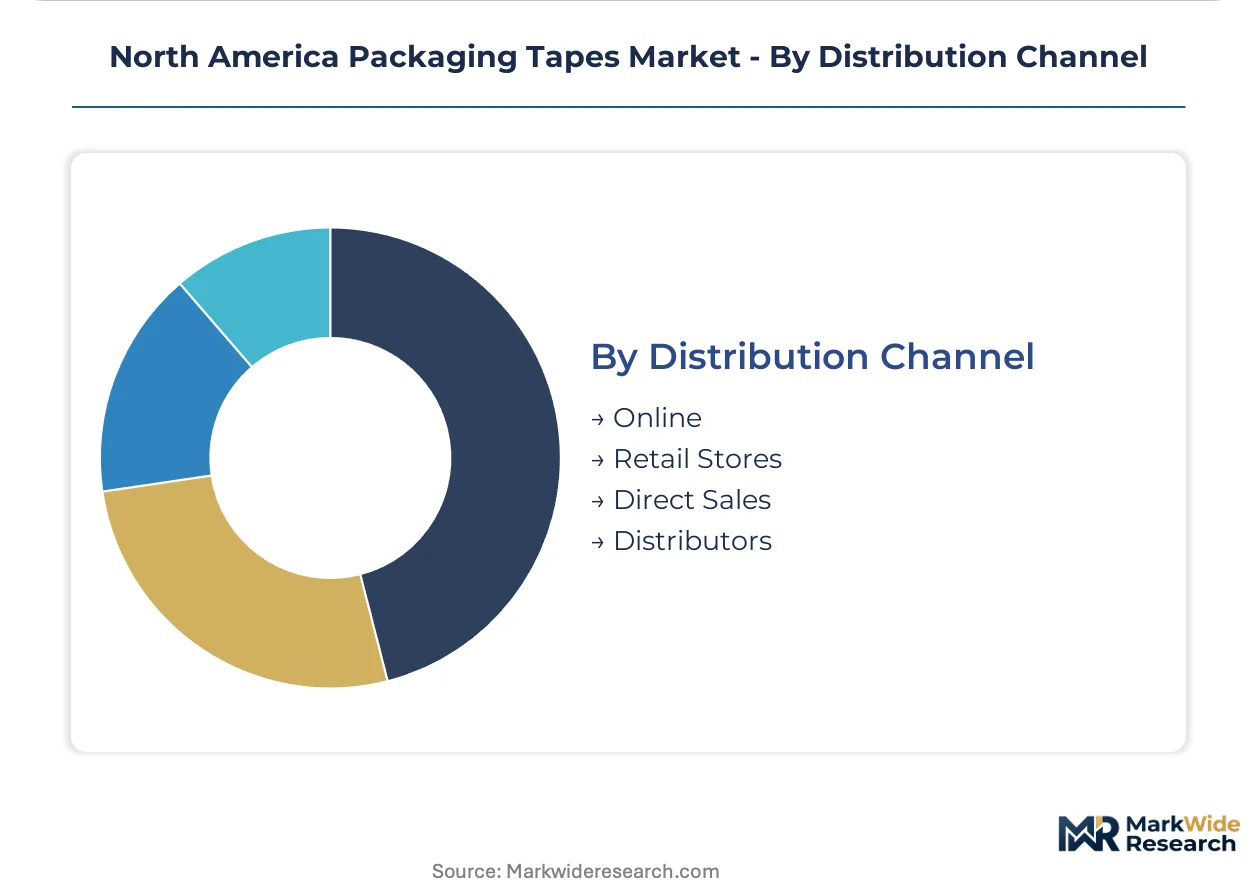
Distribution Channel:
Supply concentration varies by channel, with distributor networks dominating industrial procurement while direct sales capture strategic e-commerce accounts through integrated packaging supply contracts.
- Distributors:Industrial supply houses and packaging specialists serving Midwest manufacturing with stock-and-ship logistics. W.W. Grainger and similar networks maintain regional warehouses for next-day tape availability.
- Direct Sales:Manufacturer account teams embedding with major 3PLs and e-commerce fulfillment operators for vendor-managed inventory arrangements. Prologis and Duke Realty industrial park concentrations enable dedicated service territories.
- Online:E-procurement platforms capturing small-to-mid industrial buyers with standardized SKU offerings. Limited penetration in custom-formulation or certification-intensive segments.
- Retail Stores:Big-box and specialty packaging outlets serving small business and consumer demand. Margins compress relative to B2B channels.
Distributors hold the largest share; direct sales is gaining share fastest as buyer concentration among mega-warehousing operators accelerates single-source contract consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes packaging tapes through e-commerce fulfillment clusters that dwarf Canadian and Mexican demand patterns, while Canada drives water-activated tape adoption through stricter corrugated recycling mandates, and Mexico's nearshoring corridor generates specialized export-compliant requirements.
United States
Third-party logistics providers operating mega-warehouses in Georgia, Texas, and Ohio consume carton sealing tapes at volumes justifying dedicated slitting facilities adjacent to sortation hubs. The EPA's Clean Air Act Title V permitting regime forces coating operations to abandon solvent-based adhesive systems, redirecting capital toward hot-melt and UV-cured alternatives. Southeast warehousing clusters in Atlanta and Savannah have proliferated, concentrating demand within 50-mile radii of Prologis and Duke Realty industrial parks.
Canada
Health Canada and the PMRA oversee chemical migration limits for food-contact tapes, creating dual compliance burdens for cross-border suppliers serving Ontario and Quebec food processing clusters. The country's stricter repulpability standards accelerate water-activated tape displacement of pressure-sensitive variants in corrugated recycling streams. Toronto and Montreal distribution centers adopt these formats at scale to meet internal sustainability targets and regulatory alignment.
Mexico
Automotive and electronics manufacturers relocating assembly from Asia to Baja California and Querétaro generate demand for export-compliant packaging tapes with dual US-Mexico regulatory certifications. The federal environmental regulator SEMARNAT implements emissions standards that parallel EPA frameworks, easing cross-border formulation standardization. Tijuana and Monterrey industrial corridors anchor tape consumption through maquiladora operations serving North American supply chains.
North America Packaging Tapes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper stratum commanding formulation control and captive resin supply while mid-tier converters compete on slitting efficiency and regional logistics. The market structure rewards backward integration into film extrusion and polymer research campuses that insulate against adhesive chemist shortages. Two strategic archetypes dominate: diversified materials conglomerates leveraging cross-divisional R&D spillover, and tape-focused specialists anchoring competitive stance through resin conversion cost control. Capacity expansion in Southeast slitting facilities and strategic partnerships with third-party logistics providers constitute the dominant competitive moves reshaping territorial control.
Among North American-dominant operators, 3M Company and Intertape Polymer Group occupy positions exemplifying the integrated leader archetype, while Tesa Tape Inc. represents the European specialist model transplanted into regional competition. 3M's Minnesota-based polymer research campus sustains formulation leadership without external talent pool dependency. Intertape Polymer Group anchors its stance through in-house film extrusion controlling resin conversion costs. Tesa Tape exemplifies how cross-Atlantic specialists compete through certification depth rather than scale.
| Leading Market Players |
|---|
| 3M Company |
| Intertape Polymer Group Inc. |
| Avery Dennison Corporation |
| Berry Global Inc. |
| Shurtape Technologies LLC |
| Nitto Denko Corporation |
| Mactac LLC |
| CCT Tapes |
| Tesa Tape Inc. |
| Others |
Pricing and Supply Chain Analysis
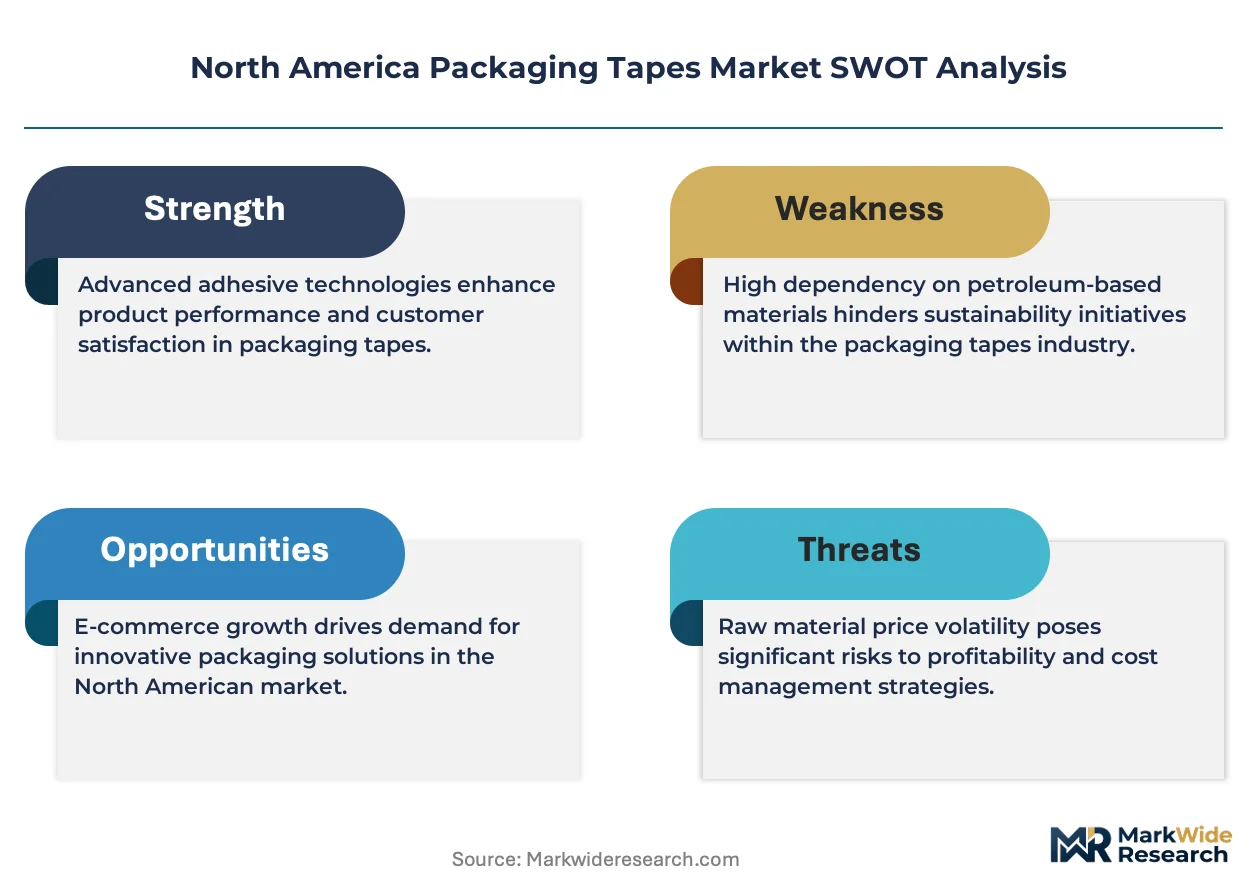
EPA Clean Air Act Title V permitting gates both supplier qualification and price differentiation simultaneously, as converters must invest in compliant coating infrastructure to access major retailer supply chains while certification tiers separate premium hot-melt formulations from commodity solvent-based alternatives.
Pricing Analysis
Long-term offtake agreements dominate procurement between third-party logistics providers and integrated tape manufacturers, with Amazon and Walmart distribution centers locking in multi-year supply contracts that bundle carton sealing tapes with stretch film and corrugated. Price differentiation hinges on PSTC-107 certification tier and shear resistance performance grade, with sub-500-minute variants facing intense cost compression from polypropylene resin volatility while moisture-resistant PVC tapes command cold-chain premiums. Pricing pressure stems from Gulf Coast propylene monomer supply disruptions transmitting directly to converter margins without full pass-through capacity. Industrial manufacturing buyers in Midwest corridors exhibit highest price sensitivity, whereas food and beverage distributors accept premium positioning for Health Canada-compliant food-contact formulations.
Supply Chain Analysis
Gulf Coast petrochemical complex concentration creates a chokepoint where propylene monomer supply disruptions cascade through North American polypropylene film production. Raw material flows draw from Texas and Louisiana refining operations, Canadian specialty resin imports, and Mexican maquiladora extrusion capacity for regional conversion. Single-source vulnerability concentrates in biaxially oriented polypropylene film supply to Southeast slitting facilities serving Georgia and South Carolina warehousing clusters. Distribution runs through dedicated slitting operations adjacent to Prologis and Duke Realty industrial parks, with vendor-managed inventory arrangements replacing traditional distributor channels for strategic e-commerce accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as water-activated tapes displace pressure-sensitive variants in sustainability-focused e-commerce procurement, requiring rapid reformulation investments to maintain volume positions.
For Market Incumbents: Fortify formulation leadership through captive polymer research campuses insulated from Midwest adhesive chemist shortages, while accelerating hot-melt coating line retrofits ahead of EPA Title V enforcement deadlines. Backward integration into film extrusion secures resin conversion cost control against Gulf Coast feedstock volatility. Water-activated tape displacement in Amazon and Walmart distribution centers represents the critical substitution threat demanding immediate technical response. For New Entrants and Emerging Players: PSTC certification fast-track investments unlock procurement access to regional 3PLs consolidating purchasing in Georgia and Texas mega-warehouse corridors. White-space targets concentrate in Mexico nearshoring corridors serving Baja California automotive assembly and Querétaro electronics manufacturing with dual US-Mexico regulatory certifications. Health Canada Drug Establishment Licence pathways offer penetrable positioning for cross-border food-contact tape supply to Ontario-Quebec cold-chain clusters. For Investors and Strategic Acquirers: Extended producer responsibility legislation in New York and Washington reshapes the acquisition landscape toward tape suppliers with integrated take-back logistics capabilities and repulpable water-activated portfolios. Long-term viability over a multi-year horizon favors converters with compliant coating infrastructure already deployed and Southeast slitting capacity adjacent to demand concentration. The signal to watch is California DTSC regulatory expansion into additional chemical disclosure categories that would accelerate incumbent compliance cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Melt Coating Retrofit | EPA Title V compliance unlocks major retailer supplier qualification and sustains market access. |
| Backward Integration into Film Extrusion | Captive resin conversion insulates margins from Gulf Coast propylene monomer volatility. |
| Water-Activated Tape Formulation | Repulpability alignment captures Amazon and Walmart sustainability procurement preferences. |
| Southeast Slitting Capacity Expansion | Proximity to Georgia and South Carolina 3PL clusters enables vendor-managed inventory capture. |
| Dual US-Canada Regulatory Certification | Health Canada PMRA compliance opens Ontario-Quebec food processing tape demand. |
Research Methodology
A spread of perspectives from adhesive chemists, coating operations managers, third-party logistics procurement directors, and corrugated recycling facility operators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with technical R&D leads at integrated manufacturers and distribution channel partners serving Midwest industrial corridors. Secondary validation drew from EPA Clean Air Act permitting databases, Health Canada PMRA chemical migration guidelines, SEC 10-K disclosures from materials conglomerates, and customs trade data tracking polypropylene film imports. Bottom-up demand modeling from end-use consumption patterns and top-down supply capacity assessments were triangulated to establish market boundaries.
Segmentation dimensions modeled include product construction type, backing material substrate, end-use application channel, and procurement pathway structure across the analysis window. Volume and value outputs reflect convergence between demand-side consumption estimates from e-commerce fulfillment cluster expansion and supply-side capacity tracking from coating line retrofit announcements. CAGRs were derived from trend extrapolation of resin cost pass-through elasticity and regulatory compliance investment cycles. Forecast inputs incorporated PSTC certification timeline compression effects and extended producer responsibility legislative progression patterns.
Decision-makers should treat outputs as directional under base assumptions of continued EPA Title V enforcement and sustained e-commerce fulfillment center expansion; material deviation in either would warrant model refresh. Practitioners should keep alternative scenarios live as California DTSC regulatory scope and New York-Washington EPR implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Shipping Tapes Market
Tapes
Masking Tape Market
Tapes
Tape Stretching Line Market
Tapes
Coding Foils and Tapes Market
Tapes
Aluminum Foil Tape Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
Twist Tube Market
Tapes
Adhesive Transfer Tape Market
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Pipe Marking Tape Market
Tapes
UV Cured Acrylic Foam Tapes Market
Tapes
Thermoplastic Tape Market
Tapes
Global Pressure Sensitive Tapes Market
Tapes
Aerospace Tapes Market
Tapes
Dry Wall Tapes Market
Tapes
Unsupported Single Coated Tape Market