
 Carton Sealer Market | 2026-2036
Carton Sealer Market Size, Share, and Industry Trends Forecast 2026-2036
Carton Sealer Market Analysis
CE-marked servo-driven sealing specifications is collapsing the gap between entry-level and industrial-grade equipment, forcing mid-tier suppliers to reposition. Syntegon leverages its pharmaceutical-grade validation protocols to command premium positioning in regulated environments. Intertape Polymer anchors North American tape supply through backward integration into adhesive formulation. 3M differentiates via proprietary pressure-sensitive adhesive chemistry that extends seal integrity across temperature extremes.
A carton sealer is an automated or semi-automated machine that applies adhesive tape, hot melt glue, or pressure-sensitive material to close and seal corrugated cardboard boxes at speeds ranging from 15 to 100+ cases per minute depending on configuration. Its primary commercial purpose is to secure products for distribution while maintaining package integrity through transit, storage, and handling stress. Automatic sealers capture the dominant share of capital expenditure as warehouse labor costs rise and throughput requirements tighten. Random case sealers represent the fastest-growing configuration because they accommodate variable box dimensions without manual changeover, a critical capability for e-commerce operations shipping mixed-SKU orders. Pressure sensitive technology leads installed base but hot melt systems command higher margins in food and beverage applications where tamper-evidence requirements are strictest.
The EU Machinery Directive and CE marking requirements shape equipment design standards across European installations, while OSHA lockout/tagout regulations in the United States mandate specific guarding and emergency stop configurations that add engineering cost. ISO 9001 quality management certification has become a baseline qualifier for supplier qualification programs at multinational consumer packaged goods companies, effectively filtering market access. Stakeholders must monitor how pending extended producer responsibility frameworks in multiple jurisdictions will alter material specifications for sealing consumables and the equipment compatibility requirements that follow.
Market Dynamics
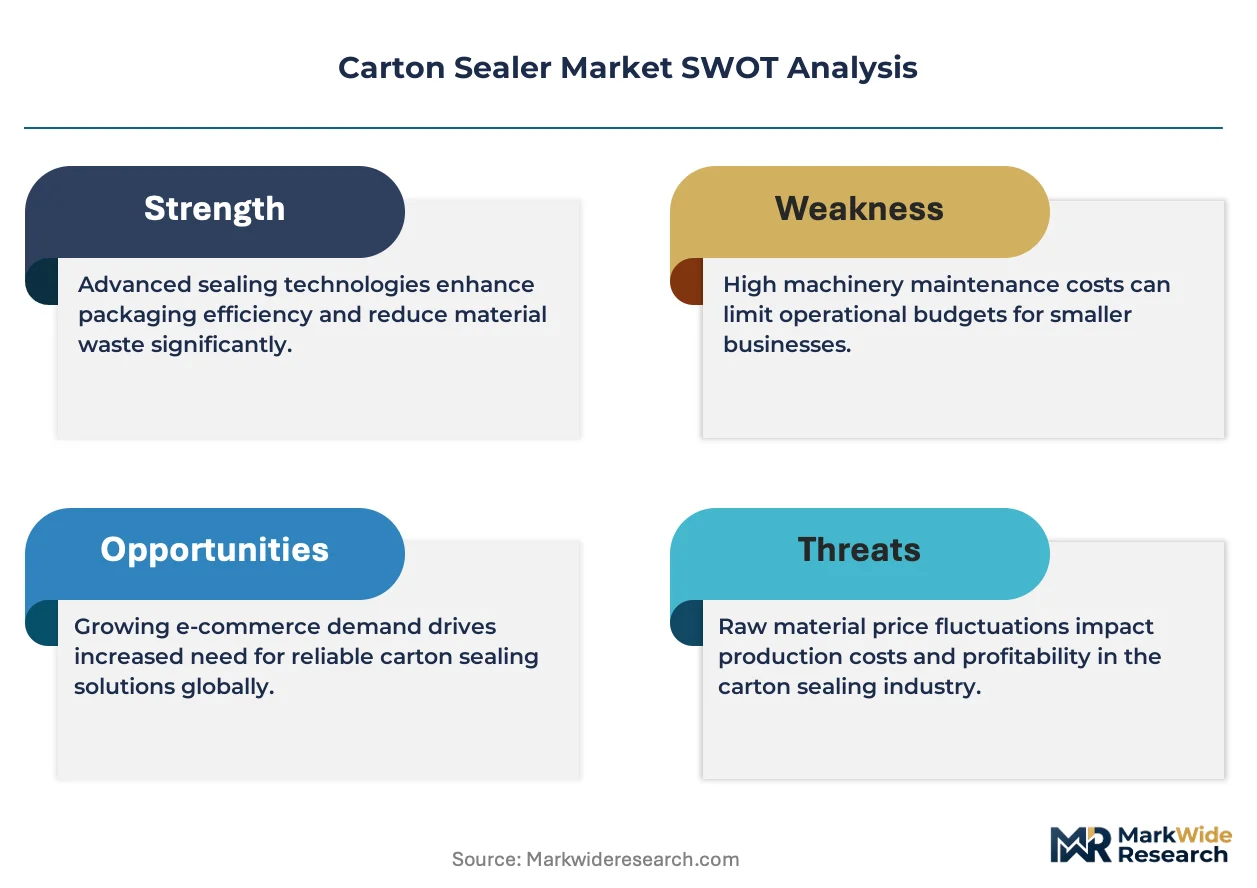
The central structural force reshaping carton sealer demand is the compression of order cycle times in e-commerce fulfillment, which is forcing warehouse operators to eliminate manual changeover delays between mixed-SKU shipments.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory material recovery targets are accelerating equipment replacement cycles as operators seek sealers compatible with recyclable adhesive systems and reduced plastic tape formulations.
- Random case sealer technology:Variable-dimension handling without manual adjustment addresses the operational bottleneck in omnichannel distribution centers processing heterogeneous order profiles.
- Germany's industrial packaging corridor:Concentrated automotive and machinery manufacturing clusters sustain premium equipment demand through continuous line integration requirements and high-throughput specifications.
Market Restraints
- Adhesive raw material volatility:Petroleum-derived hot melt formulations and synthetic rubber pressure-sensitive adhesives expose equipment margins to petrochemical price swings and supply rationing.
- CE marking compliance costs:EU Machinery Directive validation protocols impose extended engineering timelines and third-party certification expenses that filter smaller vendors from regulated tenders.
- Mechanical reliability thresholds:High-speed servo-driven sealing heads require precision tolerances that strain maintenance capabilities in facilities without dedicated automation technicians.
Strategic Opportunities
- Extended producer responsibility frameworks:Pending regulations in multiple jurisdictions will mandate equipment compatibility with biodegradable sealing consumables, creating retrofit and replacement demand.
- Food and beverage tamper-evidence requirements:Hot melt systems with integrated verification sensors address stringent supply chain security protocols in pharmaceutical and perishable goods distribution.
- Retrofit automation kits:Modular servo upgrades for legacy semi-automatic sealers offer a capital-efficient path for mid-sized warehouses to approach automatic throughput without full line replacement.
Industry Challenges
- ISO 9001 certification timelines:Multinational consumer packaged goods supplier qualification programs demand documented quality management systems that extend sales cycles by 12-18 months for uncertified vendors.
- Legacy WMS integration complexity:Random case sealers require dimensional data feeds from warehouse management systems, and fragmented middleware standards impede plug-and-play deployment.
- Skilled maintenance technician scarcity:Servo motor diagnostics and vision system calibration exceed the capabilities of traditional packaging mechanics, forcing operators to contract specialized service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carton Sealer Market |
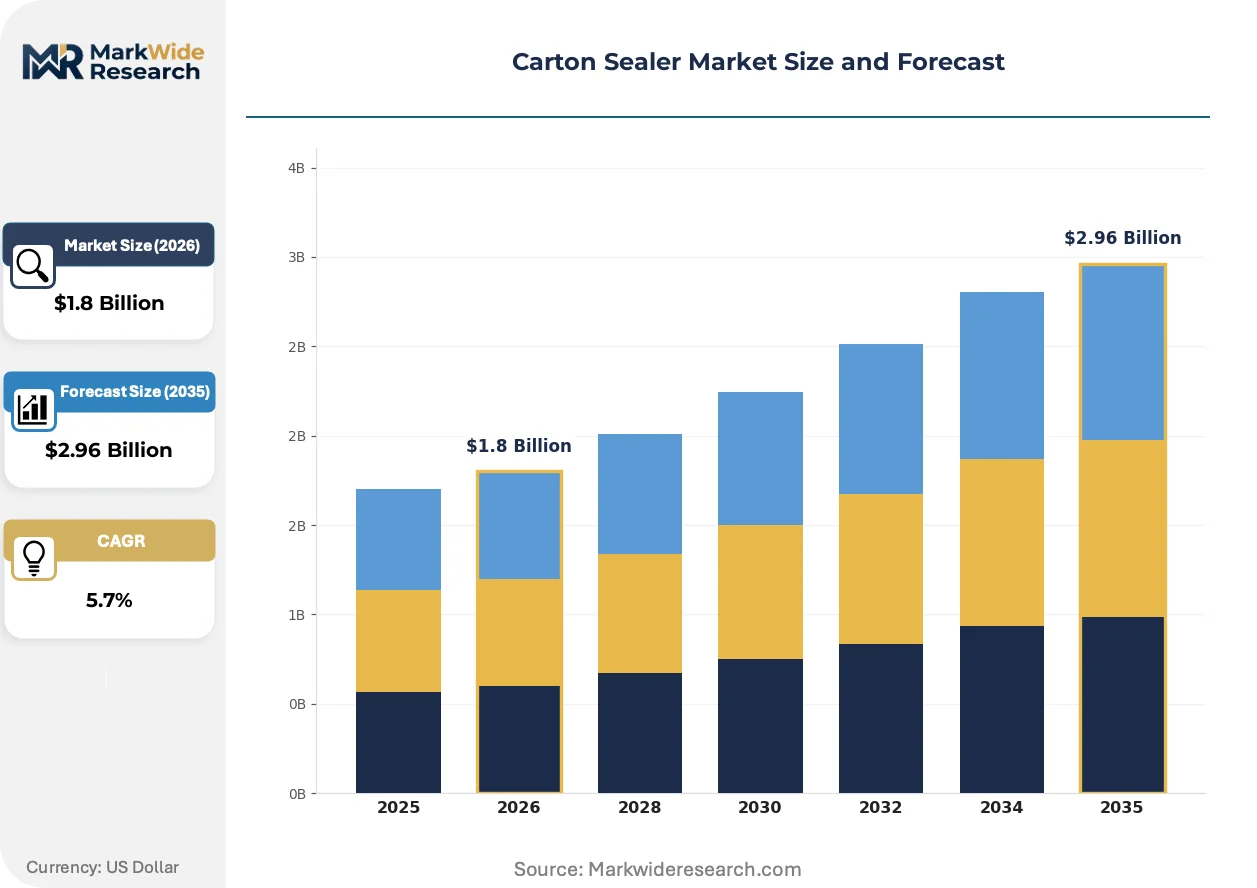
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Sealers, Semi-Automatic Sealers, Manual Sealers, Random Case Sealers Application: Food Packaging, Beverage Packaging, Pharmaceutical Packaging, Electronics Packaging End User: Manufacturers, Retailers, Wholesalers, Distributors Technology: Hot Melt, Cold Glue, Pressure Sensitive, Tape Sealing |
| Companies Covered | Syntegon, Intertape Polymer, 3M, Lantech, Clearpack, Hamrick, Pearson Packaging Systems, Combi, Signode, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carton Sealer Market Emerging Trajectories
Active innovation in carton sealing centers on three vectors: the displacement of mechanical adjustment with sensor-driven automation, regulatory pressure on consumable material specifications, and the unbundling of equipment ownership from operational responsibility.
Vision-guided dimensioning systems integrated with random case sealers are supplanting manual measurement and mechanical adjustment in e-commerce fulfillment operations. Third-party logistics providers operating high-variability SKU environments have adopted these systems at accelerating rates. The technology is compressing equipment specification differentiation toward software-defined performance rather than mechanical durability ratings.
REACH restrictions on adhesive chemical constituents are tightening formulations available for pressure-sensitive tape production. Industrial users in the European Union face reformulation mandates affecting seal integrity across temperature ranges. Food and beverage processors are responding by migrating capital expenditure toward hot melt systems with verified food-contact compliance and integrated temperature monitoring.
Equipment-as-a-service contracting is displacing outright purchase in mid-market warehouse operations seeking to convert fixed automation capital into variable fulfillment costs. Third-party logistics operators in North American urban distribution corridors have pioneered this shift. The model is most visible in facilities serving seasonal demand spikes where utilization rates fluctuate below thresholds that justify full ownership depreciation.
Carton Sealer Market Segmentation
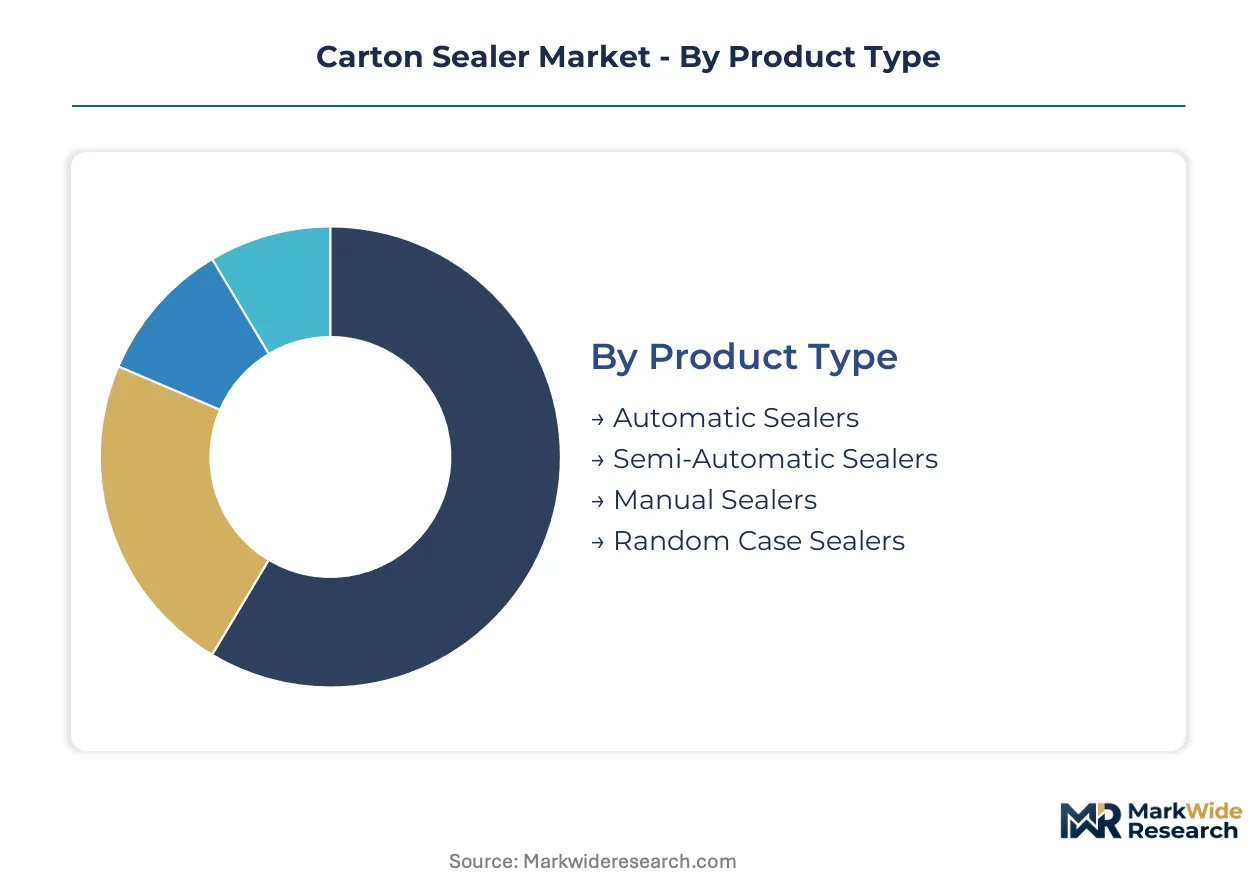
Carton sealer procurement patterns diverge sharply between domestic fulfillment operations and export-oriented manufacturing facilities, with regulatory compliance requirements and throughput specifications driving distinct equipment configurations across each segment category.
Product Type:
Automatic sealers dominate capital deployment in Germany's automotive export corridors, while semi-automatic units sustain domestic wholesale operations across Central European distribution hubs.
- Automatic Sealers:Servo-driven systems achieve 60-100 cases per minute through continuous feed mechanisms integrated with conveyor networks. Demand concentrates in e-commerce fulfillment centers across Poland and the Netherlands, driven by compressed order cycle requirements and 24-hour delivery guarantees.
- Random Case Sealers:Vision-guided dimensioning eliminates manual changeover between heterogeneous box sizes. Third-party logistics providers in Belgium and northern France have adopted these systems fastest, addressing mixed-SKU omnichannel shipments without line stoppages.
- Semi-Automatic Sealers:Operator-fed systems serve mid-volume manufacturers in Spain and Italy with batch production schedules.
- Manual Sealers:Handheld units sustain small-scale retailers and artisan food producers in Portugal and Greece with intermittent sealing needs.
Automatic sealers command the established base. The steepest expansion runs through random case sealers.
Application:
Food and pharmaceutical packaging drive premium equipment specifications, while electronics applications prioritize anti-static sealing environments in export processing zones.
- Food Packaging:Hot melt systems with food-contact compliance and integrated temperature monitoring address EU hygiene package regulations. German dairy processors and Dutch meatpacking facilities sustain replacement demand through continuous line integration requirements.
- Pharmaceutical Packaging:Validated sealing protocols with tamper-evidence verification meet EMA serialization mandates. Facilities in Switzerland and Ireland command the tightest specification tolerances for temperature-stable seal integrity.
- Beverage Packaging:High-moisture environments in Belgian breweries and Czech bottling plants favor corrosion-resistant stainless steel construction.
- Electronics Packaging:Anti-static pressure-sensitive systems protect semiconductor shipments from ESD damage in Hungarian and Slovakian export corridors.
Food packaging anchors volume demand. Pharmaceutical applications generate the highest margin capture per installed unit.
End User:
Manufacturer procurement concentrates in industrial clusters with continuous production schedules, while retailer investments track omnichannel fulfillment expansion.
- Manufacturers:Integrated production lines in Germany's machinery corridor and France's automotive belt specify heavy-duty automatic sealers with predictive maintenance capabilities. These facilities prioritize equipment uptime metrics over initial capital expenditure.
- Distributors:Third-party logistics operators across the Benelux region deploy random case sealers to handle variable client SKUs without dedicated line configurations. Their equipment utilization rates fluctuate with seasonal demand patterns.
- Retailers:Omnichannel grocers in the United Kingdom and Scandinavia retrofit existing warehouses with modular automation kits.
- Wholesalers:Traditional cash-and-carry operations in Eastern Europe maintain semi-automatic installations with lower throughput requirements.
Manufacturers represent the largest installed equipment base. Distributor channel investment is climbing fastest on third-party logistics expansion.
Technology:
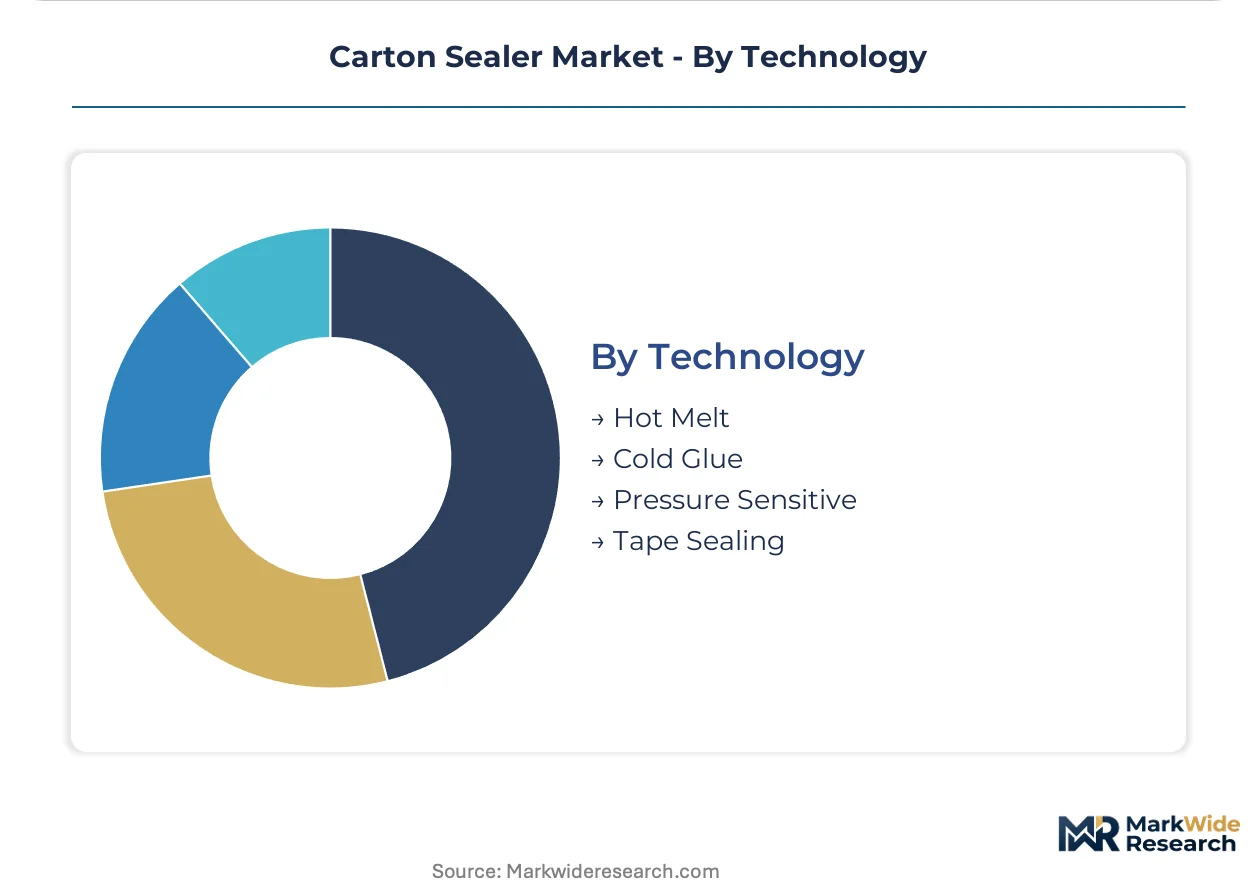
Pressure-sensitive systems retain dominance in general industrial applications, while regulatory pressure on adhesive chemistry drives hot melt adoption in regulated sectors.
- Pressure Sensitive:Synthetic rubber adhesive tapes achieve immediate bond strength without curing time. REACH reformulation mandates on petroleum-derived constituents are forcing European users toward bio-based alternatives with modified temperature performance profiles.
- Hot Melt:Thermoplastic adhesives deliver tamper-evident seals with verified food-contact compliance. French pharmaceutical packagers and Italian pasta exporters specify these systems for supply chain security protocols and perishable goods integrity.
- Tape Sealing:Polypropylene and PVC formulations dominate cost-sensitive applications in Eastern European wholesale operations.
- Cold Glue:Water-based adhesives sustain specialized paperboard applications in Scandinavian sustainable packaging lines.
Pressure-sensitive technology retains the broadest installed footprint. Hot melt systems are gaining share fastest on regulatory compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing clusters in Germany, the United States, China, and Japan supply the dominant share of automated sealing systems. Demand concentrates in export-oriented manufacturing corridors and e-commerce fulfillment hubs where throughput specifications are tightest.
Germany
Automotive and machinery manufacturers in Bavaria and Baden-Württemberg sustain premium equipment demand through continuous line integration requirements. CE marking under the EU Machinery Directive shapes equipment design standards and filters smaller vendors from regulated tenders. The industrial packaging corridor spanning Stuttgart to Munich commands the tightest specification tolerances for servo-driven sealing heads.
United States
Third-party logistics operators across the Midwest and Southeast deploy random case sealers to handle mixed-SKU omnichannel shipments without line stoppages. OSHA lockout/tagout regulations mandate specific guarding and emergency stop configurations that add engineering cost to equipment imports. Chicago and Atlanta distribution corridors anchor capital expenditure on automated sealing systems.
China
E-commerce fulfillment centers in the Yangtze River Delta and Pearl River Delta drive adoption of high-speed automatic sealers as warehouse labor costs rise. GB standards and SAMR equipment safety protocols shape domestic certification requirements for machinery deployment. Shenzhen and Shanghai logistics hubs concentrate demand for vision-guided dimensioning systems.
Japan
Precision electronics manufacturers in the Kanto and Kansai regions specify anti-static pressure-sensitive systems for semiconductor shipment protection. METI industrial automation incentives support equipment upgrades in aging warehouse facilities. The Nagoya automotive belt sustains replacement demand for heavy-duty automatic sealers with predictive maintenance capabilities.
Netherlands
Rotterdam port logistics operators and Belgian cross-border distributors deploy random case sealers to accommodate variable European export packaging requirements. REACH restrictions on adhesive chemical constituents force reformulation mandates affecting seal integrity specifications. The Randstad logistics cluster leads adoption of equipment-as-a-service contracting models.
Carton Sealer Market Vendor Landscape
Concentration sits with diversified industrial conglomerates and specialized packaging machinery fabricators competing across distinct technology vectors. The vendor base spans three tiers: pharmaceutical-grade validation specialists, adhesive chemistry integrators, and regional fabrication houses serving cost-sensitive wholesale operations. Strategic differentiation runs through M&A activity consolidating tape supply with equipment manufacturing, and technology licensing agreements bridging servo-drive engineering with legacy mechanical platforms.
Among adhesive-integrated equipment suppliers, 3M exemplifies the chemistry-driven archetype through proprietary pressure-sensitive formulations. Syntegon occupies a position within the pharmaceutical-grade validation tier, leveraging regulated environment protocols. Intertape Polymer anchors the tape supply integration archetype through backward control over adhesive formulation. These three represent distinct competitive positions rather than overlapping market contests.
| Leading Market Players |
|---|
| Syntegon |
| Intertape Polymer |
| 3M |
| Lantech |
| Clearpack |
| Hamrick |
| Pearson Packaging Systems |
| Combi |
| Signode |
| Others |
Supply Flow & Price Mechanics
Hot melt adhesive substitution for petroleum-derived pressure-sensitive tapes is redrawing raw material sourcing maps from the Gulf Coast to European bio-refineries while compressing margin structures for equipment bundling these consumables.
Pricing Analysis
CE marking under the EU Machinery Directive dictates the pricing tier structure across European installations. Three-tier pricing structure across pharmaceutical-grade validation, industrial-performance, and entry-level mechanical tiers separates Syntegon-protocol systems from standard servo-driven units from semi-automatic equipment. Cost compression in entry-level segments is intensifying because Chinese manufacturers are exporting GB-certified machines at reduced engineering overhead. Distributor and wholesaler channels exhibit highest price sensitivity; pharmaceutical packers show least sensitivity due to validation protocol requirements.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes are forcing equipment fabricators to hold larger servo motor and precision bearing inventories. Manufacturing concentrates in Germany, China, and Japan for complete systems; Italy and Taiwan supply secondary automation components. Raw material feeds draw from Swedish specialty steel for corrosion-resistant frames, German servo drives, and Korean precision sensors. Single-source vulnerability sits with semiconductor-dependent vision systems for random case sealers. Distribution runs through OEM-direct channels for large manufacturers and specialized packaging machinery distributors for mid-market accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment specification fragmentation is accelerating as e-commerce fulfillment operators demand mixed-SKU handling capabilities that legacy semi-automatic sealers cannot address, opening niches for modular retrofit specialists and random case sealer pure-plays.
For Market Incumbents: Consolidate adhesive chemistry capabilities through backward integration into hot melt formulation to offset petroleum price volatility. Acquire regional service networks in Poland and the Netherlands where third-party logistics density is highest. CE marking compliance investments filter smaller competitors from regulated tenders.
For New Entrants and Emerging Players: ISO 9001 fast-track certification opens qualification pathways with multinational consumer packaged goods procurement programs. Target semi-automatic retrofit automation kits for Spain and Italy where mid-volume manufacturers seek capital-efficient throughput gains without full line replacement. Lead with equipment-as-a-service contracting to convert fixed capital objections into variable cost acceptance.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed packaging machinery roll-ups holding fragmented regional service networks. Long-term viability hinges on software-defined performance differentiation rather than mechanical durability ratings. Watch for extended producer responsibility framework implementation in Germany and France as inflection indicator for biodegradable sealing consumable compatibility demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Formulation | Captures margin from petroleum volatility while securing REACH-compliant hot melt supply for food-contact applications. |
| Random Case Sealer Technology Licensing | Enables legacy equipment manufacturers to compete in e-commerce fulfillment without full R&D reinvention. |
| Equipment-as-a-Service Contracting Expansion | Converts seasonal demand fluctuations into recurring revenue streams for third-party logistics operators. |
| CE Marking Fast-Track Certification Investment | Accelerates supplier qualification timelines with EMA-regulated pharmaceutical packagers in Switzerland and Ireland. |
| Vision-Guided Dimensioning System Development | Compresses manual changeover delays that bottleneck omnichannel distribution center throughput specifications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with packaging machinery maintenance directors, plant engineers at automotive and food processing facilities, OEM procurement teams specifying line integration, and aftermarket service heads managing servo motor diagnostics. Secondary validation drew from EU Machinery Directive implementation guidance, SEC filings of adhesive-integrated equipment suppliers, customs data on packaging machinery trade flows, and ISO 9001 certification registry records. Bottom-up equipment shipment tracking and top-down industrial capital expenditure analysis were triangulated against facility-level automation investment surveys.
Across the analysis window, forecasts model product type segmentation across automatic, random case, semi-automatic, and manual sealers; application segmentation spanning food, pharmaceutical, beverage, and electronics packaging; and technology segmentation across pressure-sensitive, hot melt, tape, and cold glue systems. CAGRs were derived from installed base replacement cycles, e-commerce fulfillment center expansion pipelines, and regulatory compliance-driven equipment refresh mandates. Forecast inputs incorporate REACH adhesive reformulation timelines and extended producer responsibility framework progression.
The analysis sits within stated boundaries; outcomes outside sustained e-commerce order volume growth, stable petrochemical feedstock availability, and CE marking regulatory continuity would require recalibration. Forecasts reflect documented assumptions regarding labor cost trajectories and warehouse automation adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
GCC Folding Carton Market
Cartons
Wax Boxes Market
Cartons
Interlocking Boxes Market
Cartons
Pizza Cartons Market
Cartons
Pulp Roll Cradles Market
Cartons
Carton Display Market
Cartons
Beverage Cartoners Market
Cartons
Folding Carton in Healthcare Market
Cartons
Mono Carton Market
Cartons
Foldable/Compressible Beverage Carton Market
Cartons
Shaped Liquid Cartons Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
Round Corrugated Box Market
Cartons
Carton Liners Market
Cartons
Global Hand Carton Sealers Market
Cartons
Liquid Packaging Cartons Market