
 Pick and Place Carton Packers Market | 2026-2036
Pick and Place Carton Packers Market Size, Share, and Industry Trends Forecast 2026-2036
Pick and Place Carton Packers Market Outlook
Direct OEM sales channels is narrowing as systems integrators and regional distributors capture mid-market accounts in emerging economies. ProMach Inc. leverages its broad portfolio to anchor North American beverage packaging lines. Krones AG dominates European high-speed installations through captive engineering services. Bosch Packaging Technology competes on precision motion control for pharmaceutical-grade carton handling.
Pick and place carton packers are electromechanical systems employing delta robots or articulated arms with vacuum end-effectors to transfer products from conveyor belts into corrugated containers at speeds exceeding 150 cycles per minute. Fully automatic packagers lead capital deployment in high-volume food and beverage plants where throughput consistency determines line economics. Vision systems integration represents the fastest-expanding technology segment as defect rejection and format changeover automation reduce unplanned downtime. Manual packagers retain share in contract packaging operations with volatile SKU mixes and limited capital budgets.
FDA validation requirements for pharmaceutical packaging equipment shape product development cycles and documentation burdens for vendors serving US installations. EU machinery directives and CE marking standards enforce safety interlocks and ergonomic access protocols that add engineering cost but create barrier to entry for non-compliant imports. Stakeholders must weigh total cost of ownership against speed specifications as energy efficiency regulations from Germany's KBA and analogous bodies tighten operational cost structures.
Market Dynamics
Vision-guided delta robots are collapsing changeover times on multi-SKU packaging lines, forcing OEMs to reengineer mechanical architectures around software-defined format flexibility rather than fixed tooling.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic record mandates for pharmaceutical packagers drive validated automation upgrades across US contract manufacturing organizations.
- Stuttgart machinery cluster:Concentrated engineering talent and component suppliers in southern Germany accelerate prototype-to-deployment cycles for European OEMs.
- Electrification of end-effectors:Servo-driven gripper mechanisms replace pneumatic systems, cutting compressed air consumption and maintenance intervals on high-speed lines.
Market Restraints
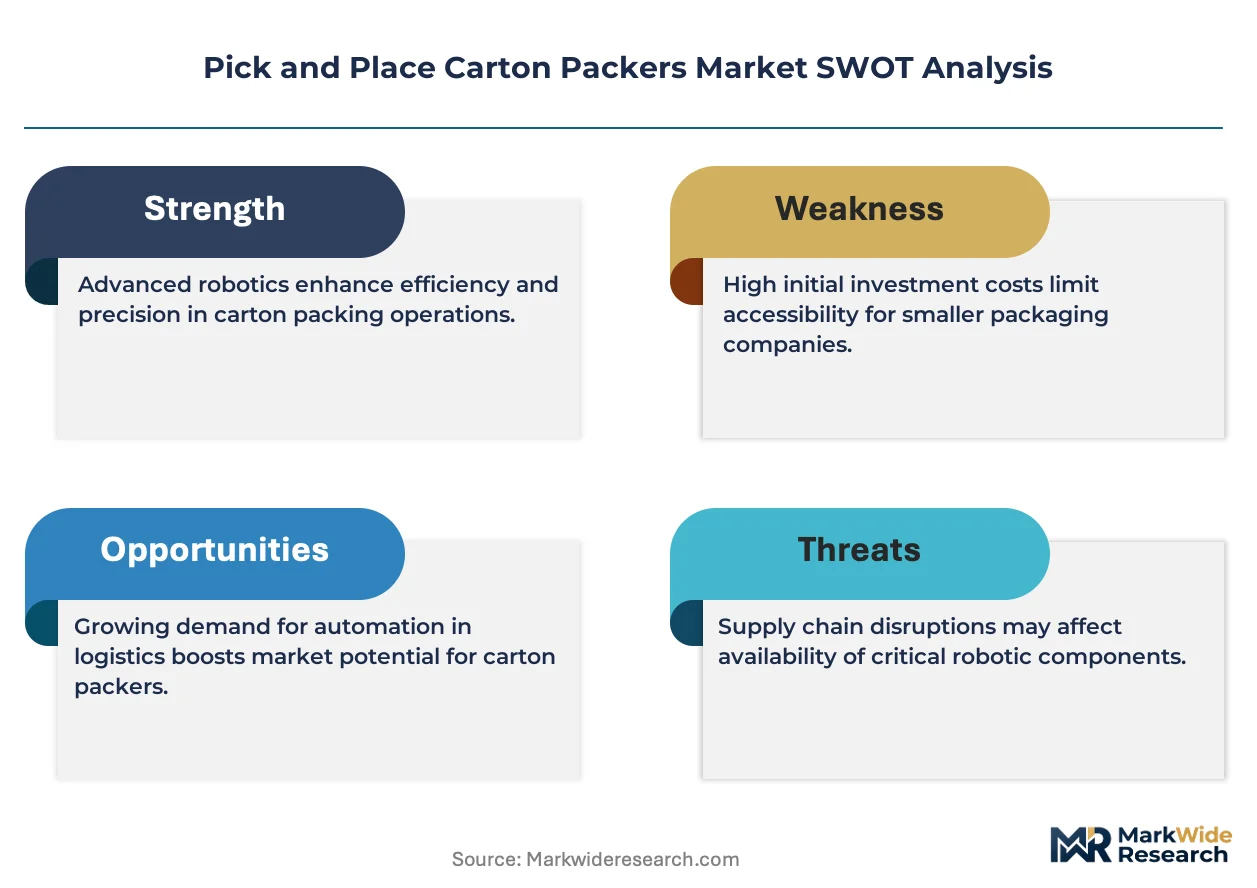
- Stainless steel price volatility:Food-grade 316L enclosure costs swing with nickel futures, compressing margin on hygienic-design systems.
- Single-source linear actuator supply:Precision ball screw production concentrates in Japan and Germany, exposing lead time risk for non-integrated packager builders.
- CE marking documentation burden:EU machinery directive compliance requires third-party notified body review, adding six-to-eight month certification delays for Asian entrants.
Strategic Opportunities
- India FSSAI modernization:Packaged food safety enforcement creates first-mover advantage for validated traceability systems in emerging dairy and snack processing hubs.
- Collaborative robot convergence:Force-limited articulated arms paired with delta robots enable mixed human-robot cells in mid-volume beverage operations.
- Direct-to-manufacturer channel expansion:E-commerce platforms for spare parts and retrofit kits bypass traditional distributor markups for maintenance-heavy installed bases.
Industry Challenges
- Mechatronics technician scarcity:Packaging machinery maintenance requires combined mechanical, electrical, and software diagnostics skills that vocational pipelines undersupply.
- Legacy PLC integration friction:Brownfield sites running proprietary control architectures face protocol translation costs when retrofitting modern vision systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pick and Place Carton Packers Market |
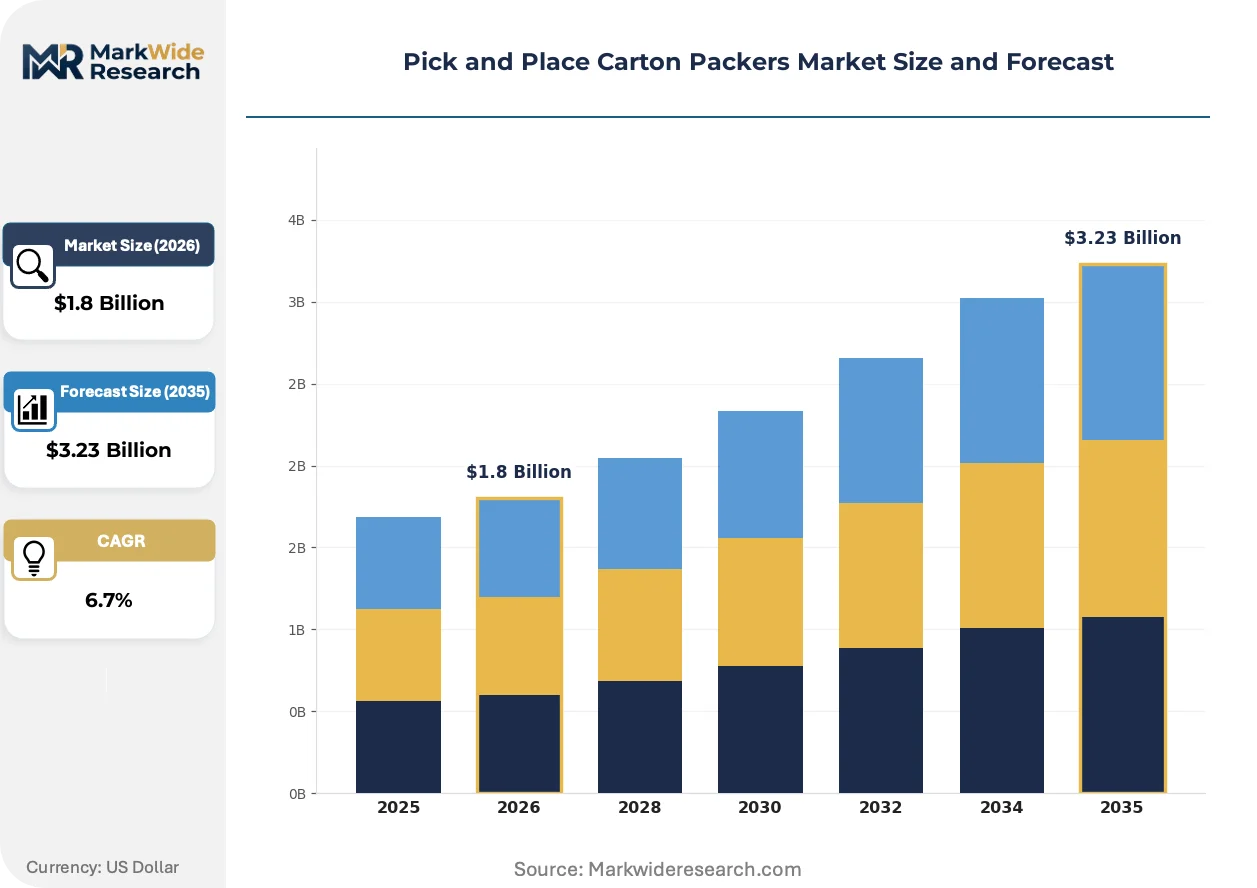
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Packagers, Manual Packagers, Semi-Automatic Packagers, Fully Automatic Packagers Application: Food Packaging, Beverage Packaging, Pharmaceutical Packaging, Consumer Goods Packaging End User: Manufacturers, Distributors, Retailers, E-commerce Technology: Vision Systems, AI Integration, Machine Learning, Sensor Technologies |
| Companies Covered | ProMach Inc., Tetra Pak, Schneider Packaging Equipment Company, Inc., Brenton LLC, Krones AG, MULTIVAC, Bosch Packaging Technology, BluePrint Automation, Marchesini Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pick and Place Carton Packers Market Strategic Shifts
Software-defined automation architectures are displacing hardware-centric designs across the carton packaging value chain, compressing commissioning timelines and enabling remote diagnostic business models.
Edge-deployed machine learning is collapsing defect detection latency on high-speed lines. Convolutional neural networks running on GPU-accelerated industrial PCs now classify package anomalies in sub-50-millisecond windows. Beverage bottlers in Germany and the Netherlands are retrofitting existing delta cells with these vision modules rather than replacing entire robotic subsystems. The technology is collapsing the economic viability of standalone mechanical rejection gates.
EU machinery directive updates enforcing cybersecurity-by-design requirements are reshaping control system architectures. OEMs must now document secure boot processes and encrypted communications for CE marking on networked packagers. Pharmaceutical installations in Ireland and Switzerland face the steepest compliance ramps as they interconnect serialization databases with line-level automation.
After-sales contracting is fragmenting from bundled maintenance toward unbundled performance guarantees. Large beverage groups now negotiate throughput-based service fees separate from hardware procurement, transferring operational risk to integrators. This shift is most advanced in North American dairy processing, where plant managers prioritize OEE commitments over capital expenditure ownership.
Pick and Place Carton Packers Market Segmentation
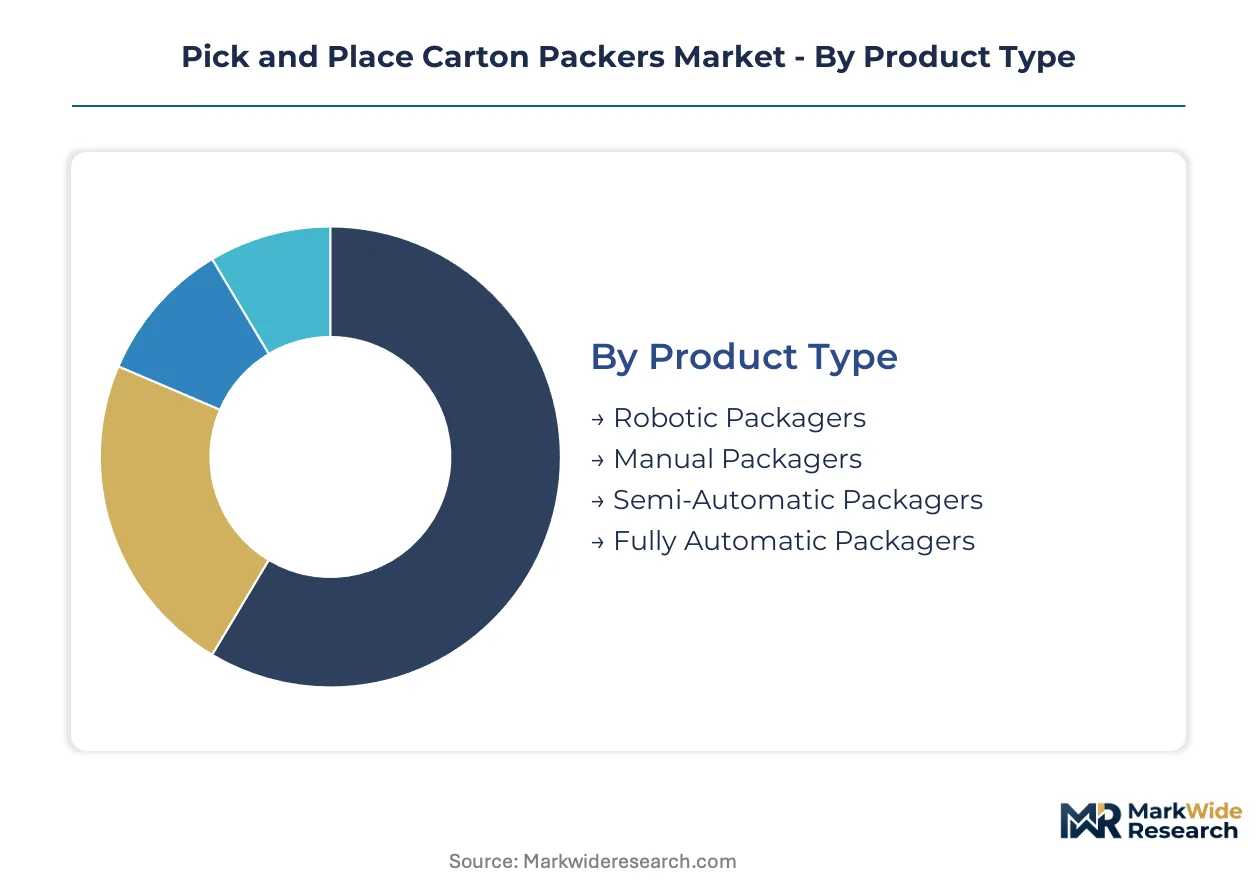
Segmentation in carton packaging machinery reveals divergent investment priorities across automation maturity levels and regulatory exposure. Product type and application dimensions capture the bulk of capital deployment variance, while technology integration patterns separate premium system architectures from commodity configurations.
Product Type:
Mature electromechanical platforms anchor installed bases, while emerging robotic architectures capture greenfield investment in high-mix operations.
- Fully Automatic Packagers:Delta robot cells with servo-driven end-effectors execute 150-plus cycles per minute on dedicated high-volume lines. German beverage bottlers and North American dairy processors specify these systems where FDA validation and OEE guarantees dominate procurement criteria.
- Robotic Packagers:Articulated arm configurations with force-limited collaborative modes enable mixed human-robot cells in mid-volume contract packaging. Stuttgart-area OEMs are converging delta speed with collaborative safety for European pharmaceutical serialization lines.
- Semi-Automatic Packagers:Operator-fed systems with automated case erecting and sealing stages suit regional snack processors in India and Brazil with moderate throughput requirements and FSSAI or ANVISA compliance timelines.
- Manual Packagers:Basic pneumatic workstations persist in volatile-SKU contract operations and emerging market microbreweries where capital constraints outweigh labor cost pressures.
Fully automatic configurations retain volume leadership; robotic packagers hold the steepest expansion curve.
Application:
Regulatory intensity and throughput consistency requirements stratify demand across end-use verticals.
- Food Packaging:Hygienic-design 316L enclosures with CIP-compatible surfaces dominate meat, dairy, and ready-meal lines. EU machinery directive compliance and Germany's KBA energy efficiency standards shape system specifications for continental European processors.
- Beverage Packaging:High-speed glass and PET bottle handling into wraparound cartons drives delta robot density in Germany, the Netherlands, and North American craft brewing clusters. Vision-guided format changeover is collapsing downtime between SKU rotations.
- Pharmaceutical Packaging:FDA 21 CFR Part 11 validation and EU MDR traceability requirements enforce documented electronic records and secure boot architectures. Irish and Swiss serialization hubs interconnect line-level automation with national verification databases.
- Consumer Goods Packaging:Cosmetic and personal care contract packagers balance flexibility against capital efficiency, favoring semi-automatic platforms with rapid tooling changeover for seasonal volume spikes.
Beverage packaging retains volume leadership; pharmaceutical packaging holds the steepest expansion curve.
End User:
Procurement authority and operational risk allocation distinguish customer archetypes in machinery sourcing.
- Manufacturers:Captive engineering teams specify integrated lines with MES connectivity and predictive maintenance architectures. German automotive-tier suppliers backward-integrating into component packaging represent emerging demand.
- Distributors:Independent packaging service providers prioritize format flexibility and rapid commissioning to serve fragmented brand portfolios across food and consumer goods verticals.
- Retailers:Private-label supply chain control is driving direct investment in automated carton forming for store-brand packaged goods in North American and European grocery networks.
- E-commerce:Fulfillment center operators are piloting robotic packagers for mixed-carton consolidation, though throughput economics still favor manual or semi-automatic configurations for non-fragile goods.
Manufacturers retain volume leadership; e-commerce holds the steepest expansion curve.
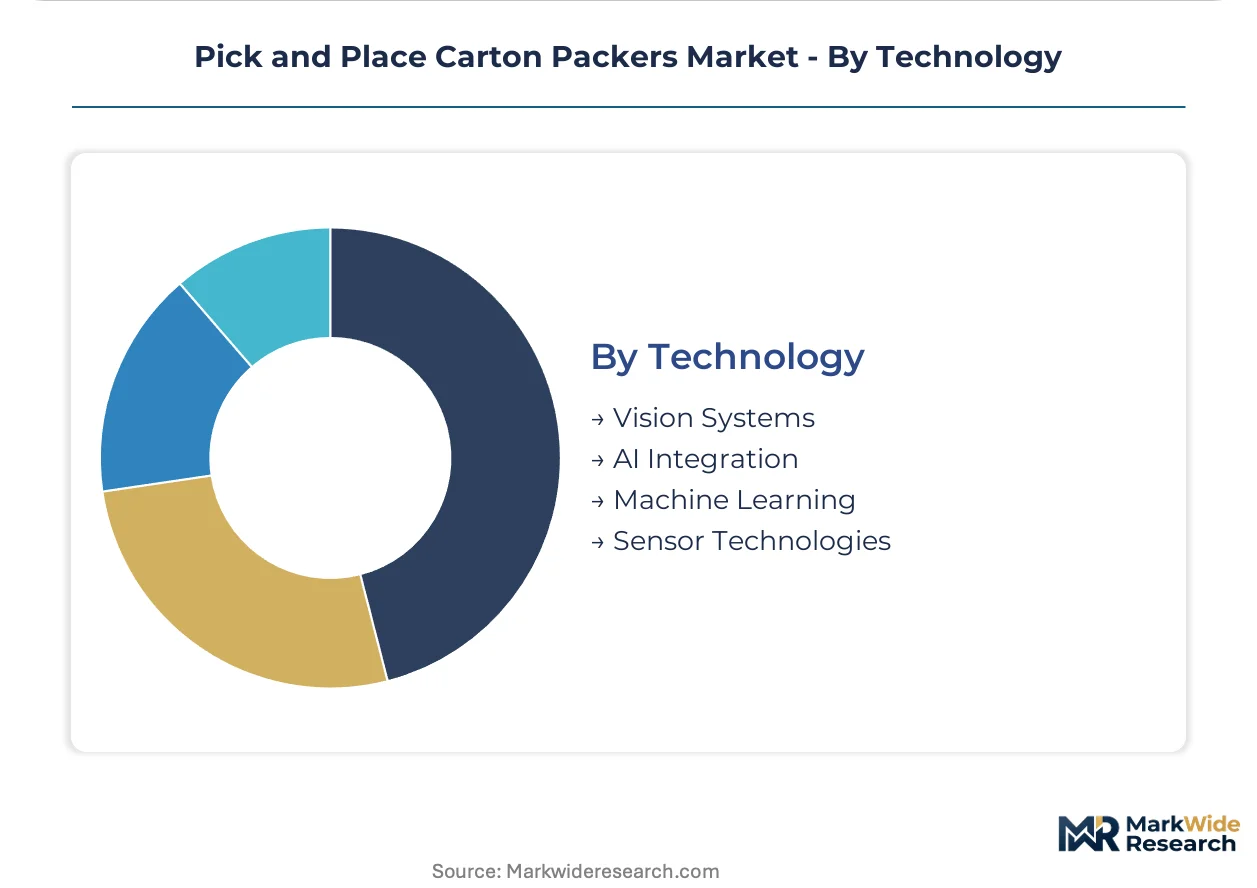
Technology:
Software-defined capabilities are displacing hardware-centric differentiation across control and sensing layers.
- Vision Systems:GPU-accelerated industrial PCs with convolutional neural networks classify package defects in sub-50-millisecond windows. Dutch and German bottlers retrofit existing delta cells rather than replacing entire robotic subsystems.
- AI Integration:Edge-deployed machine learning optimizes pick trajectories and predictive maintenance scheduling. Pharmaceutical installations in Switzerland face cybersecurity-by-design documentation burdens for CE marking on networked packagers.
- Machine Learning:Pattern recognition algorithms reduce unplanned downtime through anomaly detection in servo motor current signatures and vacuum system pressure decay rates.
- Sensor Technologies:Force-torque sensing in collaborative end-effectors enables safe human-robot coexistence, while smart vacuum sensors with flow monitoring prevent product drops in high-speed beverage handling.
Vision systems retain volume leadership; AI integration holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 21 CFR Part 11 validation requirements anchor the United States as the dominant geography for pharmaceutical-grade carton packaging automation, while Germany's machinery cluster and China's manufacturing scale shape complementary demand centers across the value chain.
United States
Beverage bottlers in Wisconsin and dairy processors in California deploy delta robot cells for high-speed wraparound carton handling. FDA electronic record mandates for contract pharmaceutical manufacturers drive validated automation upgrades. Chicago-area systems integrators anchor North American distribution channels for mid-market food packaging lines.
Germany
Stuttgart's concentrated engineering talent accelerates prototype-to-deployment cycles for European OEMs serving beverage and pharmaceutical verticals. KBA energy efficiency regulations tighten operational cost structures for hygienic-design systems. The Nuremberg packaging machinery cluster specializes in precision motion control for serialization-compliant installations.
China
Domestic dairy and snack processors in Jiangsu and Zhejiang provinces expand automated carton forming capacity under SAMR food safety enforcement. GB standards for packaging machinery safety reshape import substitution dynamics. The Yangtze River Delta concentration of contract manufacturers drives demand for flexible robotic packagers with rapid format changeover.
India
FSSAI modernization of packaged food safety rules creates first-mover openings for validated traceability systems in Maharashtra and Gujarat dairy hubs. DGFT machinery import policies influence technology sourcing patterns for regional snack processors. The Pune industrial corridor attracts systems integrators targeting mid-volume contract packaging operations.
Netherlands
Dutch beverage bottlers retrofit existing delta cells with GPU-accelerated vision modules rather than replacing entire robotic subsystems. EU machinery directive cybersecurity-by-design requirements reshape control system architectures for CE marking compliance. The Eindhoven region's industrial automation ecosystem supports edge-deployed machine learning integration for defect detection.
Pick and Place Carton Packers Market Competitive Environment
Integrated packaging conglomerates and specialized robotics fabricators split the market along capital intensity and application complexity vectors. Tier-one OEMs with captive engineering services dominate high-speed beverage and pharmaceutical installations where validation documentation and OEE guarantees determine procurement outcomes. Mid-market specialists compete on format flexibility and commissioning speed for contract packaging operations with volatile SKU mixes. Consolidation pressure intensifies as systems integrators capture distributor margins and direct-to-manufacturer spare parts platforms erode traditional aftermarket revenue streams.
Within the integrated systems tier, ProMach Inc. and Krones AG occupy positions defined by geographic anchoring and vertical scope breadth. ProMach leverages its North American portfolio density to anchor beverage packaging lines across Wisconsin and California dairy processing clusters. Krones exemplifies the European high-speed installation model through Stuttgart-captive engineering services and serialization-compliant pharmaceutical line integration. Bosch Packaging Technology represents precision motion control specialization for FDA-validated pharmaceutical-grade carton handling, with documentation capabilities aligned to Irish and Swiss serialization hub requirements.
| Leading Market Players |
|---|
| ProMach Inc. |
| Tetra Pak |
| Schneider Packaging Equipment Company, Inc. |
| Brenton LLC |
| Krones AG |
| MULTIVAC |
| Bosch Packaging Technology |
| BluePrint Automation |
| Marchesini Group |
| Others |
Value Chain & Pricing Dynamics
Single-source linear actuator dependency on Japanese and German precision ball screw manufacturers compresses both margin structures and pricing tier spreads, forcing OEMs to absorb input volatility or pass through costs to validated-system buyers. This concentration shapes procurement strategies across food-grade stainless steel enclosures and servo-driven end-effector subassemblies.
Pricing Analysis
Configured-to-order pricing for FDA-validated pharmaceutical systems commands substantial premiums over standard beverage-handling configurations. Three-tier pricing structure across premium, standard, and economy levels separates serialization-compliant installations with documentation packages from basic delta robot cells. Price differentiation rests on certification grade and after-sales service bundling. Pricing pressure stems from stainless steel 316L cost volatility tied to nickel futures. Contract packaging operations in emerging economies exhibit highest price sensitivity, while Irish and Swiss pharmaceutical serialization hubs prioritize throughput guarantees over capital expenditure.
Supply Chain Analysis
Export-control restrictions on precision motion control components limit flows from Germany and Japan to non-integrated packager builders in Asia. Geographic supply concentrates in Germany's Stuttgart machinery cluster, Japan's precision actuator manufacturers, and China's domestic enclosure fabricators. Raw material dependencies include food-grade stainless steel, rare-earth servo magnets, and vacuum system elastomers. Single-source vulnerability in linear actuator supply exposes lead time risk. Distribution runs through captive engineering services for high-speed beverage installations and regional systems integrators for mid-market food packaging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pick and place carton packers market sits in early-cycle recovery as capital expenditure releases from North American dairy processors and European beverage bottlers accelerate replacement demand for aging pneumatic systems.
For Market Incumbents: Harden installed base retention through predictive maintenance platform subscriptions that transfer operational risk from plant managers. Deepen backward integration into servo-driven end-effector production to offset Japanese ball screw supply vulnerability. Secure captive engineering talent in Stuttgart and Nuremberg clusters against integrator poaching. Prioritize FDA 21 CFR Part 11 documentation capabilities as contract pharmaceutical manufacturers consolidate vendor panels. For New Entrants and Emerging Players: Establish a beachhead in India's FSSAI modernization wave by targeting Maharashtra and Gujarat dairy processors with validated traceability systems. White-space opportunity concentrates in mid-volume collaborative robot cells for contract packaging operations with volatile SKU mixes. Leverage direct-to-manufacturer spare parts e-commerce platforms to bypass traditional distributor markups on maintenance-heavy installed bases. For Investors and Strategic Acquirers: EU machinery directive cybersecurity-by-design requirements reshape the acquisition landscape toward OEMs with documented secure boot processes and encrypted communications architectures. Long-term viability favors vertically integrated specialists with captive motion control engineering and pharmaceutical validation capabilities. Target acquisition archetype: mid-cap European packager builders with Stuttgart-area engineering density and serialization-compliant reference installations. Signal to watch: beverage group consolidation into throughput-based service fee contracting that transfers operational risk to integrators.| Strategic Initiative | Industry Significance |
|---|---|
| Vision System Retrofit Integration | Dutch and German bottlers upgrade existing delta cells with GPU-accelerated defect detection modules. |
| Servo-Driven End-Effector Development | Electrification of grippers cuts compressed air consumption on KBA-regulated high-speed lines. |
| Pharmaceutical Validation Documentation | FDA 21 CFR Part 11 compliance packages secure contract manufacturing organization upgrade cycles. |
| Direct Spare Parts E-Commerce Platform | Aftermarket revenue protection against distributor margin erosion in maintenance-heavy installed bases. |
| Collaborative Robot Safety Certification | Force-limited articulated arms unlock mixed human-robot cells in mid-volume beverage operations. |
Study Parameters
A standing panel of packaging machinery maintenance directors, plant engineers at dairy and beverage processors, OEM procurement teams, and aftermarket service heads provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC filings of integrated packaging conglomerates, EU machinery directive CE marking databases, FDA 21 CFR Part 11 guidance documents, and German KBA energy efficiency standards. Bottom-up unit deployment estimates triangulated against top-down capital expenditure surveys from food and beverage trade associations.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include automation level, application vertical, end-user procurement authority, and technology integration intensity. CAGRs derived from machinery shipment data correlated with line-level OEE benchmarking and regulatory compliance timeline assumptions. Forecast inputs incorporated FSSAI enforcement trajectories in India and SAMR food safety modernization in China.
Sensitivities concentrate around stainless steel commodity volatility, linear actuator supply disruptions, and CE marking documentation delays for Asian entrants. Forecasts reflect documented assumptions on capital expenditure release timing and regulatory compliance phase-in schedules. Material shifts in EU machinery directive cybersecurity requirements or FDA validation scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Japan Corrugated Boxes Market
Cartons
Carton Display Market
Cartons
Mailers Market
Cartons
Digital Folding Cartons Market
Cartons
Braille Cartons Packaging Market
Cartons
Child-Resistant Carton Box Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Carton Bottle Market
Cartons
Fluted Carton Trays Market
Cartons
Carton Serialization Machine Market
Cartons
Tuck Top Box Market
Cartons
Interlocking Boxes Market
Cartons
Twist Opening Cartons Market
Cartons
Liquid Packaging Cartons Market
Cartons
Indonesia Folding Carton Packaging Market
Cartons
Foldable/Compressible Beverage Carton Market