
 Indonesia Folding Carton Packaging Market | 2026-2036
Indonesia Folding Carton Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Folding Carton Packaging Market Foresight
Asset-light leasing arrangements for corrugating and die-cutting equipment is fragmenting competitive barriers among mid-tier converters. PT Fajar Surya Wisesa Tbk leverages integrated pulp-to-board operations across East Java to sustain cost advantages against smaller entrants. Rengo Co Ltd anchors premium pharmaceutical and personal care contracts through Japanese-standard quality protocols. Asia Pulp and Paper (APP) Sinar Mas competes on massive economies of scale in coated paperboard supply.
Indonesia folding carton packaging denotes paperboard containers manufactured through cutting, creasing, folding, and gluing processes, typically using 200–400 gsm solid bleached or unbleached sulfate board to protect and display consumer goods. Die-cut cartons lead value contribution due to complex custom geometries demanded by cosmetics and electronics brands, while assembled cartons dominate volume throughput in bulk food distribution. Recycled paperboard captures expanding share as BIS-equivalent national standards and buyer sustainability mandates tighten virgin fiber tolerance. Food and beverage applications concentrate the largest demand pool, though pharmaceuticals posts the fastest structural growth as cold-chain and serialization requirements multiply.
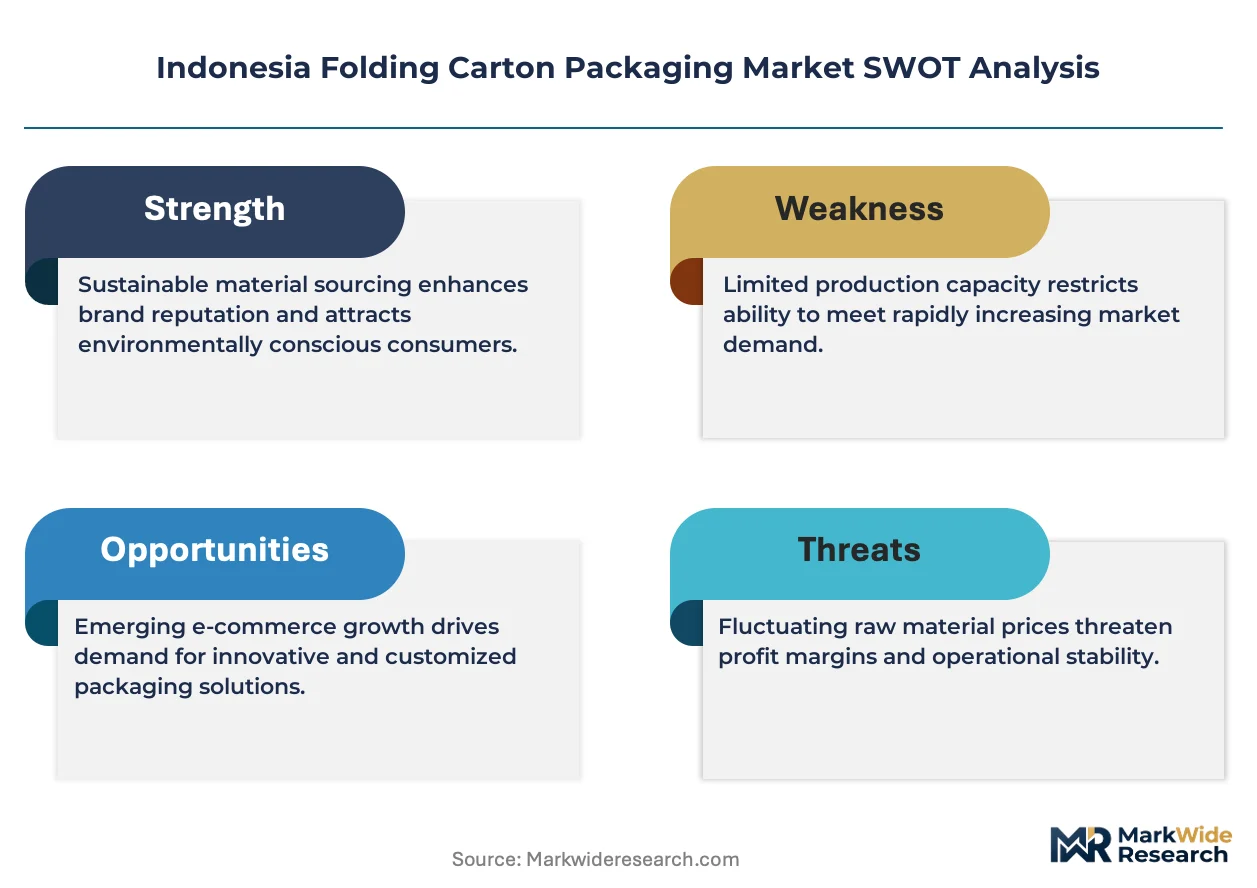
Indonesia's Ministry of Industry, the National Standardization Agency (BSN), and the Ministry of Environment and Forestry collectively enforce packaging material standards, extended producer responsibility obligations, and deforestation-linked sourcing audits that reshape board procurement patterns. These frameworks elevate compliance costs for imports while creating preferential market access for domestic integrated producers. Stakeholders must monitor regulatory calibration between waste reduction targets and domestic paperboard capacity expansion timelines.
Market Dynamics
Extended producer responsibility mandates from Indonesia's Ministry of Environment and Forestry are forcing converters to re-engineer material flows and waste recovery systems ahead of domestic capacity expansion timelines. This regulatory compression is reshaping procurement patterns across Java's industrial corridor.
Growth Catalysts
- Food and beverage export protocols:Cold-chain serialization requirements for palm oil derivatives and instant noodle shipments to ASEAN markets are expanding demand for barrier-coated folding cartons with integrated tracking features.
- Extended Producer Responsibility (EPR) frameworks:Indonesia's Ministry of Industry mandates are accelerating domestic recycling infrastructure investment, creating preferential sourcing relationships for integrated pulp-to-board producers.
- Pharmaceutical serialization:Track-and-trace regulations for vaccine distribution are multiplying specification complexity for folding cartons serving Indonesia's expanding generic drug manufacturing base.
Market Restraints
- Pulp price volatility:Imported bleached hardwood kraft pulp from Brazilian and Chilean suppliers exposes margin compression for non-integrated converters lacking captive fiber supply.
- Board supply concentration:East Java's integrated pulp mills control critical mass in coated paperboard output, creating bottleneck risk for Sumatra-based converters dependent on inter-island logistics.
- Flexible packaging substitution:Stand-up pouches and multilayer films are capturing shelf-stable food segments previously served by folding cartons, particularly in instant coffee and seasoning sachets.
Strategic Opportunities
- Sulawesi and Papua penetration:Underdeveloped converting infrastructure in eastern Indonesia creates first-mover advantage for portable die-cutting equipment deployments serving emerging consumer markets.
- Recycled-content mandates:BSN-equivalent national standards tightening virgin fiber tolerance are elevating demand for high-recycled-content board grades where domestic integrated producers hold technical lead.
- Digital print convergence:Hybrid inkjet-flexo systems enabling run-length flexibility are opening short-order customization contracts for cosmetics and electronics brands previously locked into offset minimums.
Industry Challenges
- Die-making precision gap:Shortage of CNC machinists capable of maintaining Japanese-standard tolerances for pharmaceutical and personal care contracts limits premium segment access for mid-tier converters.
- Legacy ERP integration:Batch-oriented production scheduling systems at established Java converters resist real-time connectivity with customer EDI platforms, delaying order-to-delivery cycle compression.
- Halal certification complexity:MUI (Indonesian Ulema Council) board certification timelines for adhesive and coating chemistries extend new product qualification periods beyond customer launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Folding Carton Packaging Market |
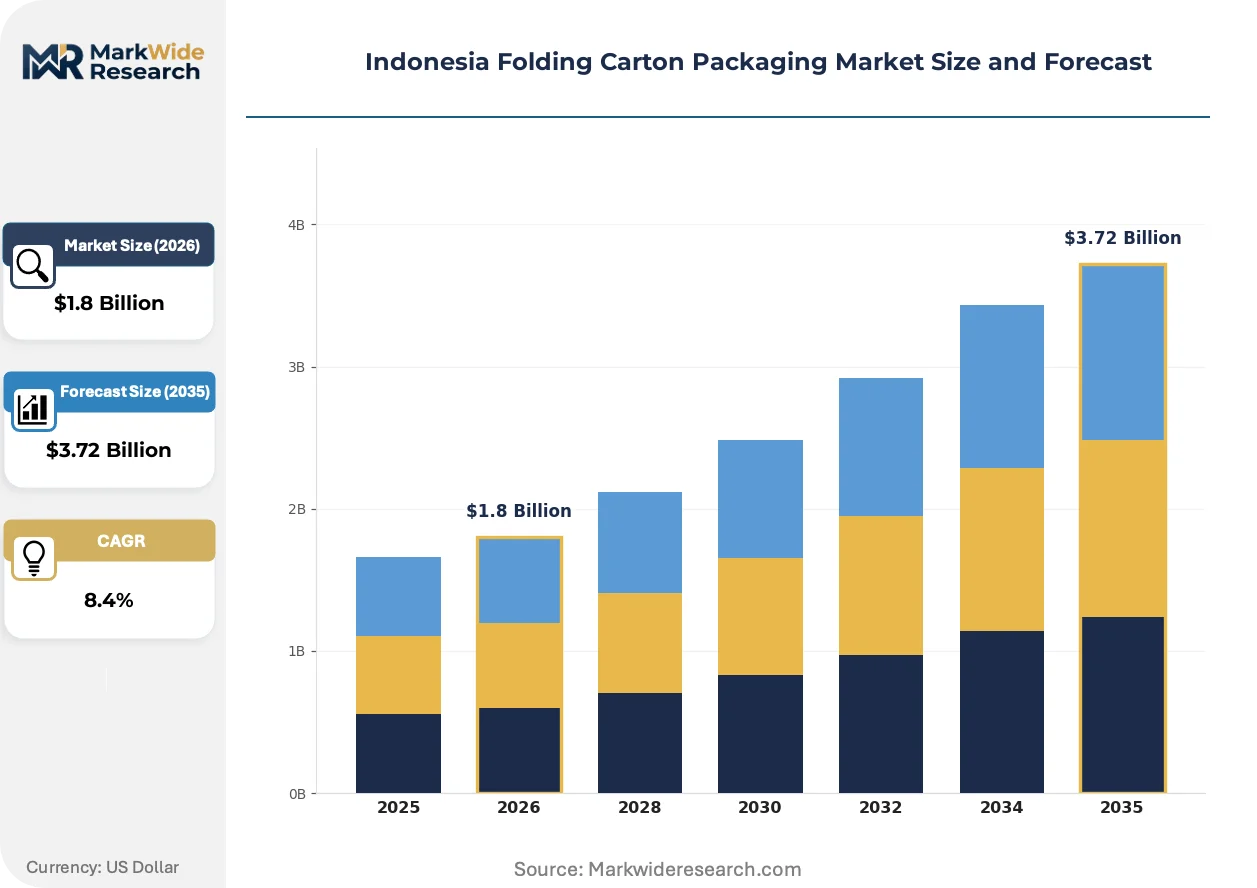
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
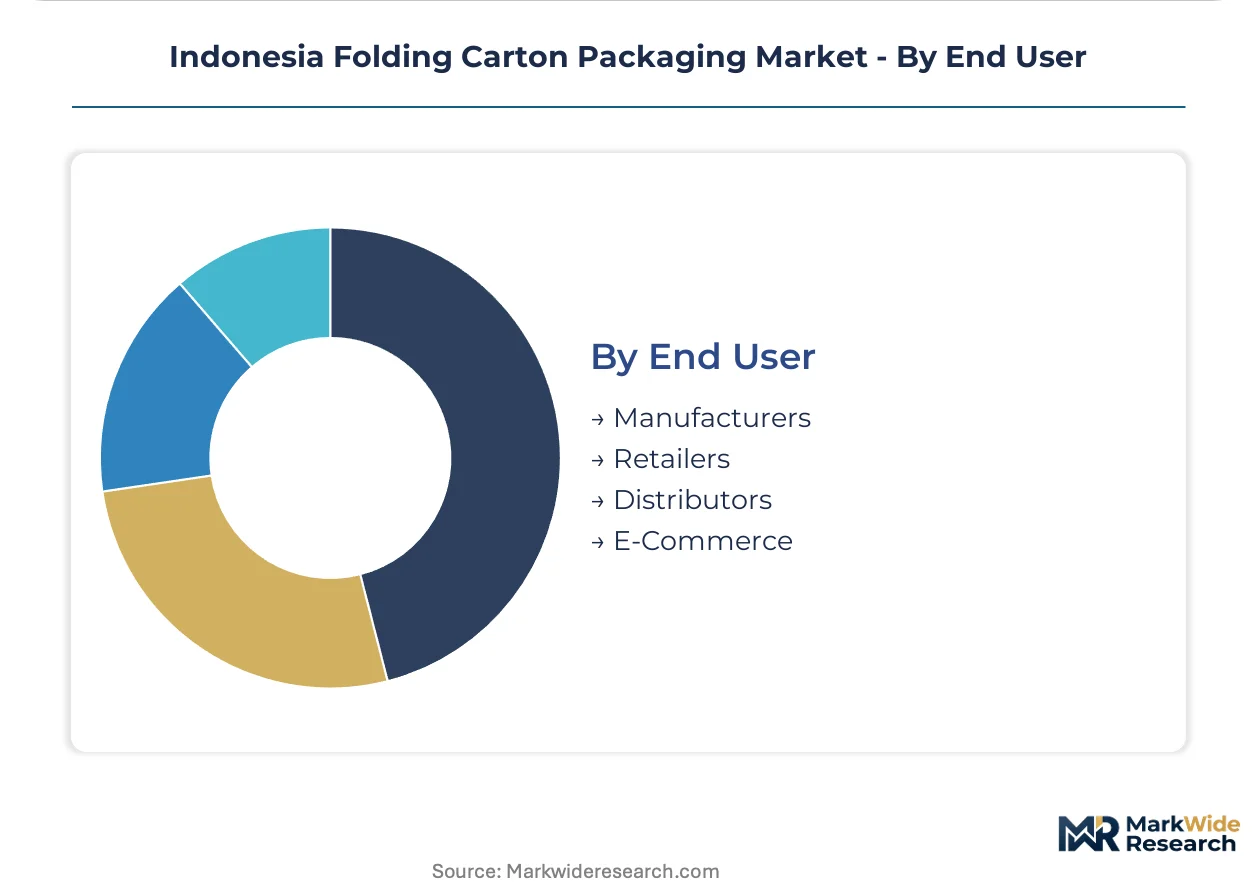
| Segmentation | Product Type: Standard Cartons, Die-Cut Cartons, Roll-End Boxes, Assembled Cartons Material: Recycled Paperboard, Kraft Paper, Coated Paperboard, Cardstock Application: Food & Beverage, Personal Care, Pharmaceuticals, Electronics End User: Manufacturers, Retailers, Distributors, E-Commerce |
| Companies Covered | PT Pabrik Kertas Indonesia (PT Pakerin), Rengo Co Ltd, PT Fajar Surya Wisesa Tbk, PT Kanepackage Indonesia, Pt Metaform (Kompas Gramedia), Asia Pulp and Paper (APP) Sinar Mas, AR Packaging, PT Asia Carton Lestari, Industri Pembungkus Internasional Pt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Folding Carton Packaging Market Shifts & Advancements
Water-based barrier coatings and digital print workflows are compressing run economics and sustainability profiles simultaneously, while regulatory serialization mandates restructure specification requirements across food and pharmaceutical end-uses.
High-performance water-based grease barriers derived from polysaccharide complexes are replacing polyethylene extrusion layers in food service applications. Quick-service restaurant chains and ready-meal distributors are specifying these coatings for microwaveable carton formats at accelerating pace. Conventional extrusion lamination equipment is rendering obsolete across Java's converting corridor as brands prioritize fiber-based recyclability claims.
Indonesia's Ministry of Environment and Forestry deforestation-linked sourcing audits are tightening chain-of-custody documentation requirements for imported pulp and paperboard. Integrated domestic producers with certified plantation fiber access are securing preferential supplier status against import-dependent competitors. Pharmaceutical and personal care brands with multinational parent companies are most affected, accelerating qualification shifts toward APP Sinar Mas and APRIL Group supply.
Consolidated procurement desks at multinational fast-moving consumer goods parent companies are compressing supplier rosters and demanding vendor-managed inventory arrangements. Regional distribution hubs in Cikarang and Surabaya are displacing direct mill-to-plant deliveries for mid-sized food manufacturers. This concentration is most visible in instant noodle and biscuit categories, where Indofood and Mayora are centralizing carton sourcing through nominated converting partners with national footprint coverage.
Indonesia Folding Carton Packaging Market Segmentation
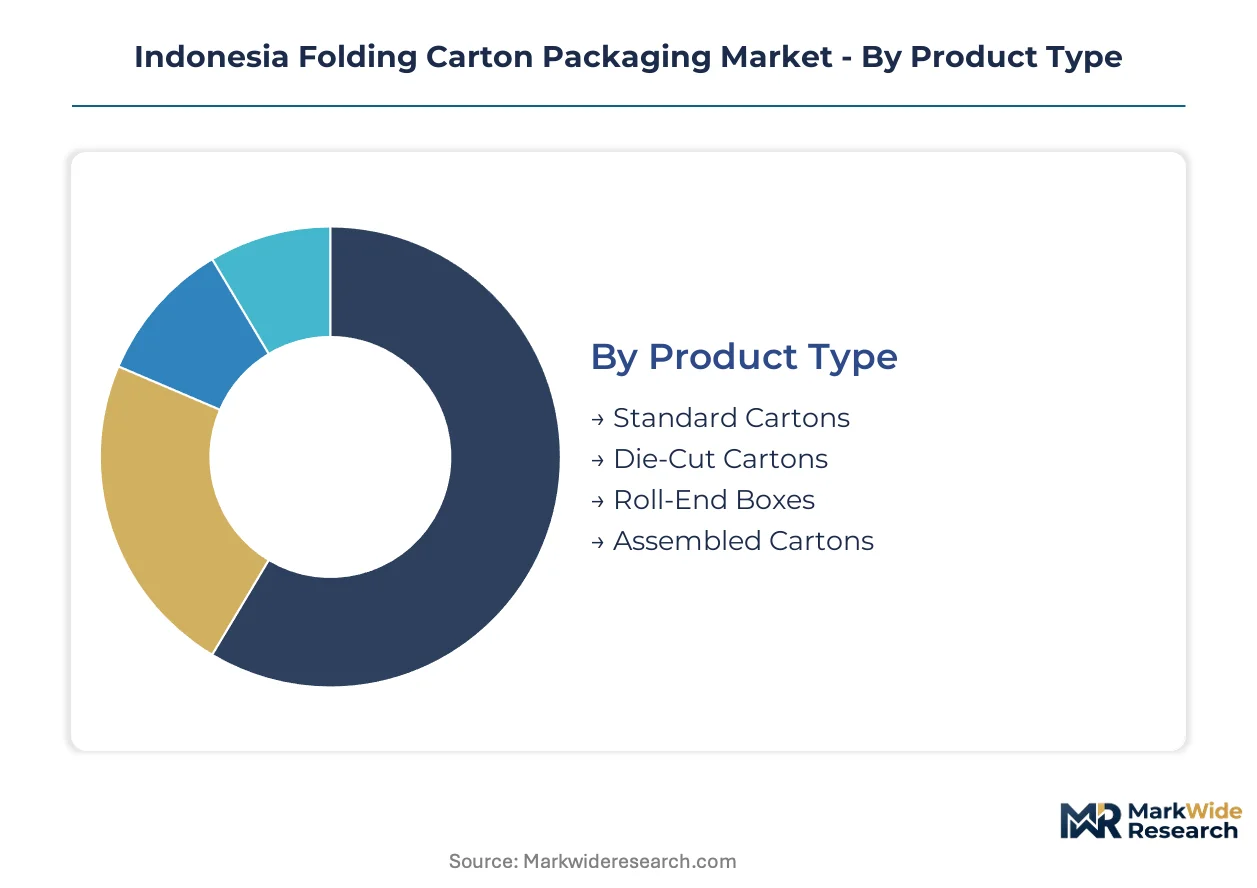
Folding carton segmentation in Indonesia reflects divergent technical requirements across Java's industrial corridor and emerging eastern markets. Specification complexity varies sharply between commodity food packaging and pharmaceutical serialization mandates.
Product Type:
Use-case spectrum spans from bulk commodity distribution to precision-engineered consumer presentation formats.
- Die-Cut Cartons:Complex custom geometries produced through steel-rule die and rotary die-cutting processes, typically 250–400 gsm coated board with window patching and foil stamping. Cosmetics brands across Jakarta and Surabaya specify these for shelf differentiation, though CNC machinist shortages constrain capacity expansion for Japanese-standard pharmaceutical contracts.
- Assembled Cartons:Pre-scored and glued formats delivered flat for manual or automated erection, dominating instant noodle and biscuit distribution through Indofood and Mayora supply chains. Volume throughput concentrates in East Java converting clusters where integrated board mills eliminate inter-island logistics risk.
- Standard Cartons:Basic six-panel designs with tuck or lock closures for generic dry goods packaging. Mid-tier converters in Central Java deploy these for regional food manufacturers lacking serialization requirements.
- Roll-End Boxes:Telescoping lid designs for premium gift and electronics applications. Limited domestic die-making precision restricts penetration against Thai and Malaysian import competition.
Established volume favors assembled cartons; emerging adoption favors die-cut cartons with barrier coating integration.
Material:
Raw material stratification tracks BSN-equivalent standards tightening and multinational sustainability audit protocols.
- Coated Paperboard:Clay-coated solid bleached sulfate board delivering high-resolution print receptivity and moisture resistance. APP Sinar Mas and APRIL Group control critical supply mass through East Java pulp-to-board integration, securing preferential status under Ministry of Environment and Forestry deforestation audit frameworks.
- Recycled Paperboard:Post-consumer fiber grades meeting emerging virgin fiber tolerance thresholds in extended producer responsibility mandates. PT Fajar Surya Wisesa Tbk leverages captive deinking capacity to supply corrugated medium and folding carton substrates for quick-service restaurant chains prioritizing recyclability claims.
- Kraft Paper:Unbleached sulfate board for organic and natural-positioned food brands. Limited domestic kraftliner capacity forces reliance on imported Indonesian pulp processed through Malaysian mills.
- Cardstock:Heavyweight uncoated or cast-coated grades for greeting cards and rigid box applications. Narrow demand pool restricts dedicated production lines, forcing converters to schedule on multi-purpose sheeters.
Supply concentration favors coated paperboard; regulatory pressure favors recycled paperboard.
Application:
End-use requirements diverge across temperature stability, barrier performance, and track-and-trace integration.
- Food & Beverage:Palm oil derivatives, instant noodles, and ready-to-drink beverages drive largest absolute demand. Cold-chain serialization for ASEAN export protocols is expanding barrier-coated specifications with integrated RFID and QR coding.
- Pharmaceuticals:Generic drug manufacturing expansion and vaccine distribution mandates are multiplying specification complexity. Track-and-trace regulations from Indonesia's national pharmaceutical regulator demand tamper-evident cartons with unique serial numbering.
- Personal Care:Premium positioning requirements from Unilever and L'Oreal parent companies favor high-impact visual design with metallic effects and soft-touch coatings.
- Electronics:Anti-static and cushioning-integrated formats for smartphone accessories and consumer electronics. Limited domestic ESD coating formulation capability constrains local sourcing.
Volume concentration remains with food and beverage; steepest expansion trajectory belongs to pharmaceuticals.
End User:
Procurement patterns stratify by scale, technical capability, and inventory management sophistication.
- Manufacturers:Integrated food and pharmaceutical producers with direct mill relationships and vendor-managed inventory arrangements. Consolidated procurement desks at multinational FMCG parents are compressing supplier rosters toward nominated converting partners with national footprint coverage.
- E-Commerce:Platform sellers and third-party logistics providers specifying ship-ready formats with damage-resistant corner construction and return-friendly opening features. Tokopedia and Shopee fulfillment center expansion is driving demand for right-sized carton optimization.
- Retailers:Hypermarket and convenience store chains with private-label packaging programs. Indomaret and Alfamart centralize sourcing through designated converters with just-in-time delivery to distribution centers.
- Distributors:Independent trading houses serving fragmented regional food processors. Price-sensitive procurement favors standard carton formats with extended payment terms.
Contract scale favors manufacturers; flexibility requirements favor e-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in East Java's integrated pulp-to-board corridor while Sumatra-based converters absorb inter-island logistics premiums. Java's industrial density sustains vendor-managed inventory contracts with multinational FMCG parents. Eastern Indonesia's underdeveloped converting infrastructure leaves price-setting to importers from Malaysian and Thai mills.
Java
Instant noodle and biscuit manufacturers Indofood and Mayora centralize procurement through nominated converting partners. Indonesia's Ministry of Industry enforces extended producer responsibility frameworks that favor integrated domestic producers with certified fiber supply. Surabaya and Gresik host captive board mills supplying coated paperboard to die-cutting clusters within 50-kilometer radii.
Sumatra
Palm oil derivative exporters drive demand for barrier-coated cartons with ASEAN cold-chain serialization. The Ministry of Environment and Forestry deforestation-linked sourcing audits tighten chain-of-custody documentation for imported pulp. Medan and Palembang converters rely on inter-island logistics from Java mills, elevating landed board costs against local competitors.
Sulawesi
Emerging consumer markets in Makassar and Manado attract portable die-cutting equipment deployments from Java-based operators. National standardization agency BSN-equivalent recycled-content mandates create technical barriers for import-dependent entrants. Local food processors lack scale for direct mill relationships, forcing distributor-mediated procurement at 12-18% premiums.
Papua
Remote logistics constrain carton availability to high-value pharmaceutical and personal care shipments. Halal certification timelines from Indonesia's Ulema Council extend qualification periods beyond typical customer launch windows. Jayapura's limited converting capacity forces reliance on Jakarta-based suppliers with air-freight cost passthrough.
Kalimantan
Coal and timber industry payrolls sustain consumer goods demand in Balikpapan and Samarinda. The Ministry of Environment and Forestry plantation fiber audits advantage APP Sinar Mas supply against import competitors. Converting infrastructure remains sparse, with most board arriving pre-cut from Surabaya sheeters.
Indonesia Folding Carton Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material supply and precision tooling. East Java's pulp-to-board integration creates a two-tier structure where captive fiber producers dictate terms to non-integrated converters. Three archetypes dominate: integrated pulp-to-board conglomerates with plantation certification, Japanese-standard quality specialists serving pharmaceutical contracts, and asset-light mid-tier operators leasing corrugating equipment. Capacity expansion and backward integration into captive fiber supply constitute the dominant competitive moves.
Among integrated producers, Asia Pulp and Paper (APP) Sinar Mas and PT Fajar Surya Wisesa Tbk exemplify the plantation-certified archetype with East Java board mill concentration. Rengo Co Ltd occupies a position representing Japanese-standard quality protocols for premium pharmaceutical and personal care segments. These three anchors illustrate how certification access and technical capability stratify competitive positioning across Java's industrial corridor.
| Leading Market Players |
|---|
| PT Pabrik Kertas Indonesia (PT Pakerin) |
| Rengo Co Ltd |
| PT Fajar Surya Wisesa Tbk |
| PT Kanepackage Indonesia |
| Pt Metaform (Kompas Gramedia) |
| Asia Pulp and Paper (APP) Sinar Mas |
| AR Packaging |
| PT Asia Carton Lestari |
| Industri Pembungkus Internasional Pt |
| Others |
Supply & Pricing Matrix
Pulp price volatility from Brazilian and Chilean hardwood kraft suppliers compresses margin spreads across non-integrated converters while simultaneously forcing supply chain consolidation toward East Java's captive fiber producers. This dual pressure widens pricing tiers between plantation-certified integrated mills and import-dependent competitors.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with volume-scale discounts and vendor-managed inventory premiums. Price differentiation rests on certification grade—Ministry of Environment and Forestry plantation fiber audits create preferential tiers—and geographic delivery cost from East Java mills versus Sumatra logistics. Pricing pressure intensifies in standard carton segments as flexible packaging substitutes capture instant coffee and seasoning sachet volumes. Distributor-mediated buyers in Sulawesi and Papua exhibit highest price sensitivity; multinational FMCG parents with consolidated procurement desks show lowest.
Supply Chain Analysis
Imported bleached hardwood kraft pulp from Brazil, Chile, and Scandinavian suppliers feeds East Java's integrated board mills alongside domestic plantation fiber from APP Sinar Mas and APRIL Group estates. Raw material dependencies center on coated paperboard grades, recycled post-consumer fiber, and water-based barrier coating chemistries. Single-source vulnerability concentrates in East Java's pulp-to-board corridor where captive producers control critical coated paperboard mass. Distribution runs through regional hubs in Cikarang and Surabaya displacing direct mill-to-plant deliveries for mid-tier food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flexible packaging substitution threatens folding carton incumbents across shelf-stable food segments, demanding active defense through barrier coating innovation and recyclability positioning.
For Market Incumbents: Build certification moats around Ministry of Environment and Forestry plantation fiber audits to lock in multinational pharmaceutical and personal care contracts against import-dependent challengers. Deepen backward integration into captive deinking capacity for recycled-content board grades as BSN-equivalent virgin fiber tolerance tightens. Deploy portable die-cutting equipment to Sulawesi and Papua to preempt emerging competitor footholds.
For New Entrants and Emerging Players: Build out Sulawesi and Papua converting infrastructure serving quick-service restaurant chains and regional food processors lacking direct mill relationships. Target e-commerce fulfillment optimization contracts with Tokopedia and Shopee platform sellers demanding right-sized ship-ready formats. Enter through digital print convergence offering short-order customization for cosmetics and electronics brands previously locked into offset minimums.
For Investors and Strategic Acquirers: Extended producer responsibility mandates from Indonesia's Ministry of Industry reshape the acquisition landscape toward integrated pulp-to-board assets with certified plantation fiber access. Long-term viability favors producers with technical lead in high-recycled-content grades and pharmaceutical serialization capability. Watch for Halal certification timeline compression from Indonesia's Ulema Council as signal of regulatory maturity enabling premium segment entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive fiber from APP Sinar Mas plantations eliminates imported pulp price exposure for East Java mills. |
| Water-Based Barrier Coating Scale-Up | Polysaccharide complex coatings replace polyethylene extrusion for microwaveable quick-service restaurant formats. |
| Digital Print Workflow Deployment | Hybrid inkjet-flexo systems unlock short-run cosmetics contracts from Jakarta and Surabaya brands. |
| Pharmaceutical Serialization Investment | Track-and-trace compliance with national pharmaceutical regulator mandates secures generic drug manufacturing base. |
| Eastern Indonesia Logistics Network | Portable die-cutting equipment deployments to Makassar and Manado capture emerging consumer market growth. |
Research Methodology
Cross-validation between primary interviews with converting plant managers, procurement leads at Indofood and Mayora, pharmaceutical packaging engineers, and Ministry of Industry regulatory officers anchors the qualitative findings. Secondary validation draws from customs and trade data, BSN-equivalent national standards documentation, Ministry of Environment and Forestry audit disclosures, and SEC filings from listed packaging producers. Bottom-up capacity assessments at East Java board mills triangulate against top-down demand modeling across food, pharmaceutical, and personal care end-uses.
Calibration against historical board production volumes and import substitution patterns shapes the analytical framework across the analysis window. Segmentation dimensions span product type complexity, material grade certification, application barrier requirements, and end-user procurement sophistication. CAGRs derive from elasticity-adjusted demand projections incorporating cold-chain serialization mandates and flexible packaging substitution rates. Industry-specific inputs include pulp price futures curves and extended producer responsibility compliance cost estimates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated pulp-to-board conglomerates or sudden flexible packaging technology breakthroughs would shift outcomes. Cross-checking against Ministry of Industry domestic capacity expansion timelines and ASEAN export protocol adoption rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Foldable/Compressible Beverage Carton Market
Cartons
Reverse Tuck Cartons Market
Cartons
Digital Folding Cartons Market
Cartons
Thailand Folding Cartons and Corrugated Packaging Market
Cartons
Litho Laminated Cartons Market
Cartons
Box and Carton Overwrapping Machines Market
Cartons
Pizza Cartons Market
Cartons
Braille Cartons Packaging Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Carton Sealer Machine Market
Cartons
Self - Adhesive Carton Window Patch Machine Market
Cartons
Mono Carton Market
Cartons
Beverage Cartons Market
Cartons
Global Aseptic Paper Packaging for Flat Top Carton Market
Cartons
Luxury Folding Carton Market
Cartons
MET-PET Cartons Market