
 Shaped Corrugated Packaging Market | 2026-2036
Shaped Corrugated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Shaped Corrugated Packaging Market Analytics
Modular insert configurations is pivoting buyer preference away from one-size-fits-all shipping containers toward precision-fit protective systems. Smurfit Kappa leverages its European mill network to supply pre-cut insert kits at scale. WestRock anchors North American demand through integrated boxboard and converting operations. Mondi Group specializes in moisture-resistant laminated grades for perishable supply chains.
Shaped corrugated packaging denotes fiberboard structures engineered to non-rectilinear geometries through die-cutting, scoring, and folding processes, typically constructed from fluted medium sandwiched between linerboard facings in calipers ranging from E-flute to triple-wall configurations. The primary purpose is to immobilize irregular or fragile products during transit while minimizing void fill and dimensional weight charges. Boxes retain the largest volume share across product types, though inserts command superior unit margins due to engineering complexity and lower commoditization. Recycled fiber dominates material inputs, yet virgin kraft grades are expanding in pharmaceutical and electronics applications where particulate shedding must meet cleanroom thresholds.
EPA guidelines on recycled content thresholds, EU REACH restrictions on coatings and adhesives, and FDA food-contact substance notifications collectively determine which material formulations and surface treatments gain market access across major economies. Compliance with these overlapping frameworks is raising formulation costs but also creating qualification barriers that favor producers with dedicated regulatory affairs functions. Stakeholders must monitor evolving extended producer responsibility schemes, as fee structures and collection infrastructure investments will reshape cost allocation between converters and their brand-owner customers.
Market Dynamics
E-commerce fulfillment velocity is compressing design-to-delivery cycles for protective packaging, forcing converters to collapse prototyping lead times from weeks to days while maintaining structural integrity certification.
Growth Catalysts
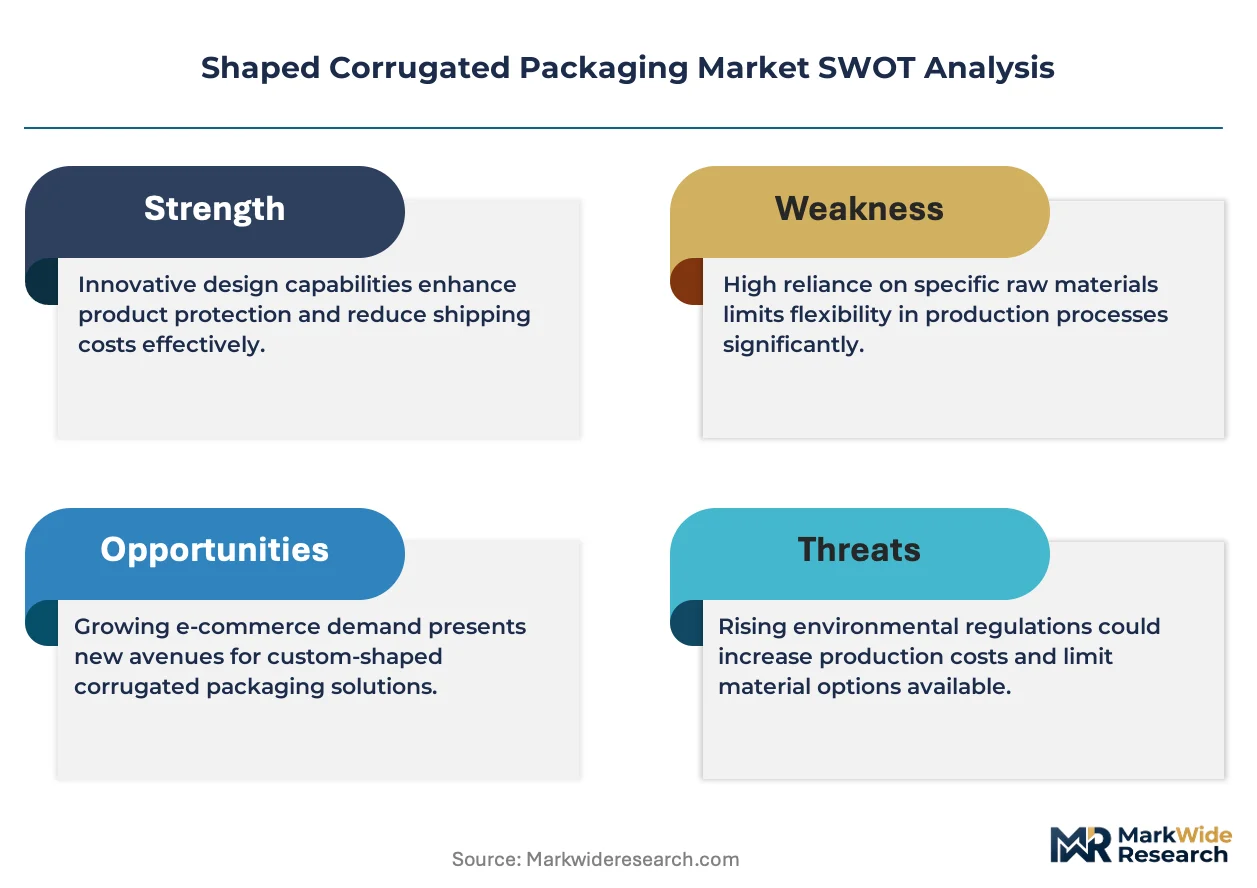
- EU Packaging and Packaging Waste Regulation:Recyclability mandates across member states are disqualifying plastic foam alternatives and redirecting demand toward fiber-based protective systems with verified closed-loop pathways.
- Pharmaceutical cold chain expansion:Temperature-sensitive biologics distribution is pulling moisture-resistant laminated corrugated into insulated shipper assemblies for last-mile integrity.
- Die-cutting automation:Servo-controlled rotary and flatbed systems are collapsing unit costs for short-run custom inserts, enabling economical production at volumes below five thousand units.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container pricing swings of forty percent within single quarters compress converter margins and destabilize contract pricing.
- German mill concentration:Three integrated producers control sixty percent of European kraftliner capacity, creating supply vulnerability during energy price spikes or maintenance outages.
- Dimensional weight arbitrage limits:Parcel carriers have compressed the penalty threshold for oversized lightweight packages, narrowing the cost advantage of optimized void reduction.
Strategic Opportunities
- India pharmaceutical export corridor:Contract manufacturing expansion around Hyderabad and Ahmedabad is generating demand for cleanroom-qualified protective packaging with particulate certification.
- Returnable e-commerce loops:Reusable corrugated shipper systems with integrated return labels are penetrating premium apparel and cosmetics subscription channels.
- Digital print integration:Single-pass inkjet systems are converging with die-cutting lines to enable lot-specific branding and regulatory marking without plate changeover delays.
Industry Challenges
- Structural simulation talent scarcity:Finite element analysis expertise for predictive cushioning design concentrates among senior engineers nearing retirement, constraining converter R&D bandwidth.
- Extended producer responsibility fee uncertainty:Variable fee structures across German, French, and Italian collection schemes complicate multi-country contract pricing and margin forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shaped Corrugated Packaging Market |
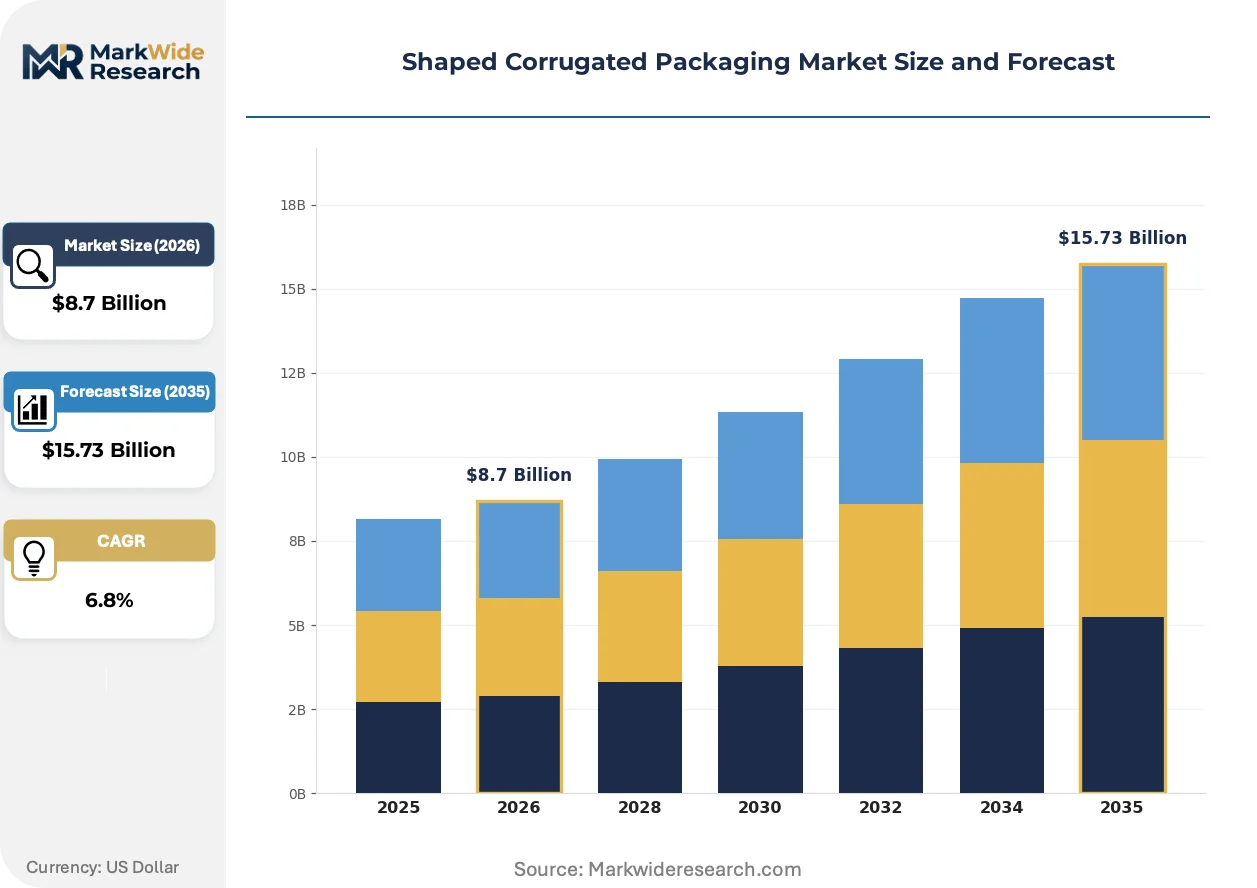
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Trays, Pouches, Inserts Material: Recycled Paper, Virgin Fiber, Kraft Paper, Laminated Material End User: Food & Beverage, Consumer Electronics, Pharmaceuticals, E-Commerce Design Type: Custom Design, Standard Design, Eco-Friendly Design, Functional Design |
| Companies Covered | Smurfit Kappa, DS Smith, WestRock, Mondi Group, International Paper, Rengo Co., Packaging Corporation of America, Georgia-Pacific, Oji Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shaped Corrugated Packaging Market Evolving Landscape
Digital manufacturing integration is collapsing the traditional separation between structural design, production scheduling, and quality verification. Three converging developments are redefining how protective packaging moves from concept to fulfillment line.
Generative design software is unifying topology optimization with fluted board material constraints, enabling algorithms to propose rib geometries and fold patterns that human engineers would not intuit. Medical device manufacturers in Minnesota and Massachusetts are piloting these tools for implantable device trays, compressing prototype iteration from twelve cycles to three. The structural consequence is unifying performance specifications with manufacturing constraints at the earliest design stage, eliminating downstream tooling conflicts.
REACH restrictions on perfluorinated coatings are forcing reformulation of grease-resistant treatments for food-contact corrugated. The industrial consequence is accelerating migration toward bio-based barrier coatings derived from lignin and chitosan. Bakery and ready-meal segments in France and Benelux are most affected, with converters qualifying new treatments through EFSA food-contact notifications.
Direct-to-consumer brand owners are consolidating packaging specifications across product lines to reduce SKU complexity and inventory carrying costs. This consolidation is displacing fragmented legacy specifications that varied by product manager preference. Electronics and personal care verticals in California and Shenzhen are most visible, with procurement teams mandating platform-based insert families adaptable across multiple product dimensions.
Shaped Corrugated Packaging Market Segmentation
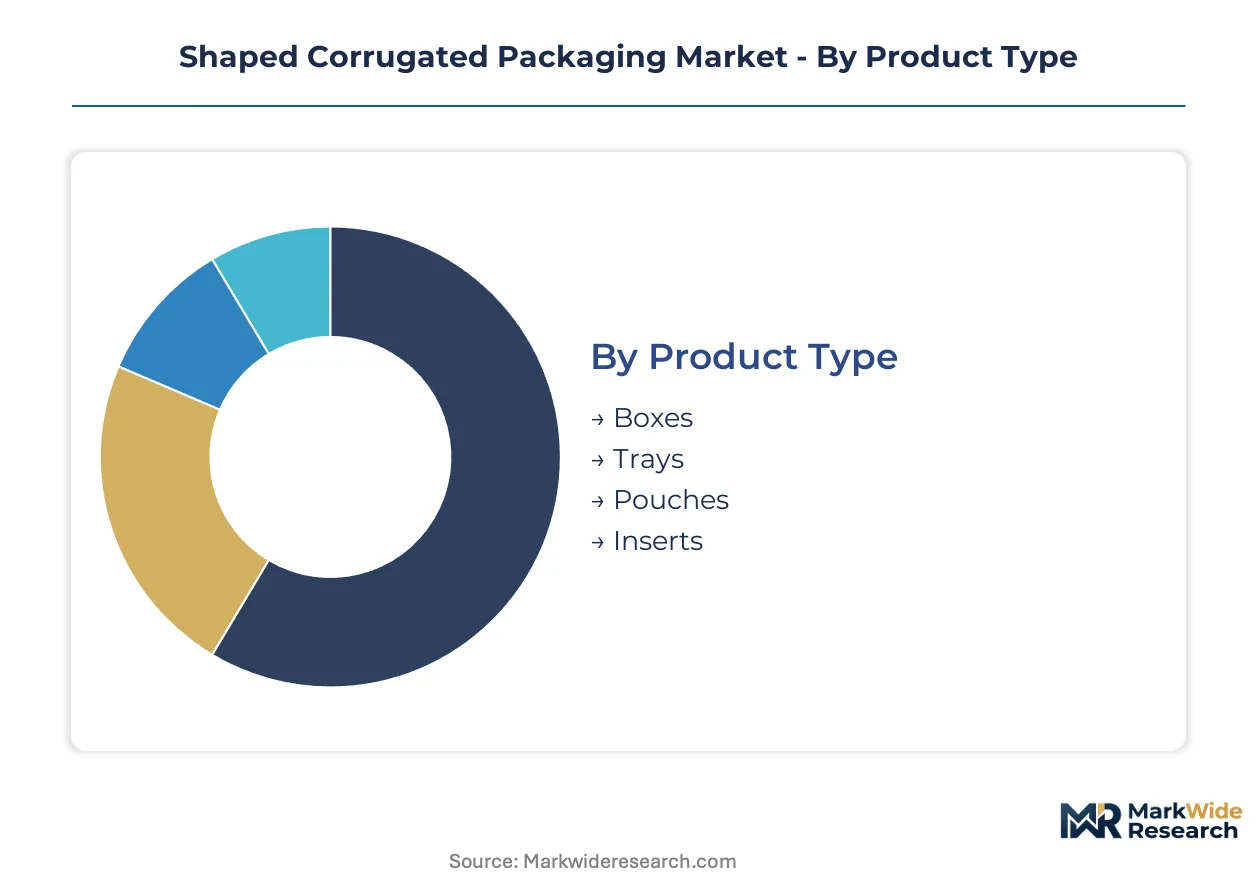
Segmentation in shaped corrugated packaging determines which regulatory pathways converters must navigate and where margin premiums concentrate. Product geometry, fiber grade, and end-use sterility requirements create distinct qualification barriers that reshape competitive positioning across each slice.
Product Type:
FDA food-contact substance notifications apply to all four formats, yet pharmaceutical trays and medical inserts face additional USP Class VI and ISO 11607 validation burdens that boxes rarely trigger.
- Boxes:Rectilinear containers constructed from single-wall to triple-wall flute configurations dominate volume throughput across e-commerce fulfillment networks. Amazon's North American sortation centers and Alibaba's Cainiao hubs in Hangzhou and Dongguan are standardizing on automated erectable formats with pre-scored tear strips for returns processing.
- Inserts:Die-cut lattice structures and molded pulp alternatives immobilize irregular products within outer containers. German automotive suppliers around Stuttgart and Munich are driving demand for precision-fit foam replacements that satisfy VDA packaging standards without tooling amortization penalties at volumes below ten thousand units.
- Trays:Shallow formed structures with locking corners serve display-ready produce and prepared meal applications. French retail chains Carrefour and E.Leclerc mandate recyclable tray formats under extended producer responsibility schemes that penalize multi-material constructions.
- Pouches:Flexible corrugated sleeves and wraparound formats protect cylindrical and elongated products. Italian wine exporters in Tuscany and Piedmont utilize pouches for bottle shipping that reduce dimensional weight charges versus rigid alternatives.
Boxes sits at the top of the volume ranking, with Inserts climbing the fastest.
Material:
Cost tiers stratify sharply between commodity recycled grades and certified virgin fibers, with pharmaceutical and electronics applications commanding three-to-five-fold premiums for particulate-controlled kraft.
- Recycled Paper:Post-consumer reclaimed fiber processed through OCC pulping systems supplies cost-sensitive e-commerce and grocery applications. China's State Administration for Market Regulation enforces GB/T standards for recycled content claims that exporters must document for cross-border shipments.
- Virgin Fiber:Unbleached softwood kraft pulp delivers tear strength and cleanliness thresholds for medical device and semiconductor packaging. Minnesota-based Medtronic and Massachusetts-based Boston Scientific specify virgin fiber trays for implantable device kits that must pass particulate shedding tests under USP <788> methodology.
- Kraft Paper:Unbleached linerboard with high tear resistance serves heavy-duty industrial applications. German steel and machinery exporters in the Ruhr corridor specify kraft-based triple-wall constructions for export shipments to India and Southeast Asian markets.
- Laminated Material:Moisture-barrier films bonded to corrugated substrates protect temperature-sensitive biologics. Cold chain expansion by Pfizer and Moderna is pulling laminated grades into insulated shipper assemblies for last-mile vaccine distribution.
Recycled Paper commands the greatest tonnage, while Laminated Material gains share fastest in value terms.
End User:
Customer procurement maturity varies dramatically, with pharmaceutical buyers imposing lot-level traceability requirements that food and beverage purchasers rarely match.
- Food & Beverage:Bakery, dairy, and ready-meal segments drive high-volume demand for grease-resistant treatments. EFSA notifications for bio-based barrier coatings are accelerating in France and Benelux as REACH restrictions displace perfluorinated chemistries.
- Pharmaceuticals:Temperature-sensitive biologics and implantable devices require particulate certification and cold chain integrity. India's CDSCO is tightening packaging documentation for export shipments from Hyderabad and Ahmedabad contract manufacturing zones.
- Consumer Electronics:Smartphones, laptops, and wearables demand anti-static and shock-absorbing configurations. Shenzhen and Dongguan assembly plants are consolidating insert specifications across product lines to reduce SKU complexity.
- E-Commerce:Direct-to-consumer fulfillment prioritizes dimensional weight optimization and returns-ready designs. California-based apparel and cosmetics brands are piloting reusable shipper systems with integrated return labels.
E-Commerce leads in shipment volume, with Pharmaceuticals expanding most quickly on a value basis.
Design Type:
Engineering intensity separates standard catalog formats from custom-engineered solutions, with generative design tools collapsing the cost gap between the two categories.
- Custom Design:Topology-optimized geometries generated through finite element analysis match product contours precisely. Medical device manufacturers in Minnesota are compressing prototype iteration from twelve cycles to three using algorithmic rib pattern generation.
- Eco-Friendly Design:Minimized material usage and mono-material constructions satisfy EPR schemes and recyclability mandates. EU Packaging and Packaging Waste Regulation compliance is disqualifying plastic foam alternatives in favor of fiber-based protective systems.
- Standard Design:Catalog-specified die patterns with minimal modification serve predictable product dimensions. High-volume electronics assemblers in Shenzhen utilize platform-based insert families adaptable across multiple product dimensions.
- Functional Design:Integrated features such as handles, display windows, and tear-open apertures enhance usability. German retail chains specify functional designs for shelf-ready produce packaging that eliminates secondary handling.
Standard Design retains the largest installed base, with Custom Design showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The shaped corrugated packaging industry traces its modern scale to post-war European industrialization, where German machinery builders and Swedish forest products firms pioneered automated die-cutting and fluting technologies that remain foundational to contemporary production economics.
Germany
Automotive suppliers around Stuttgart and Munich drive precision-fit insert demand for sub-ten-thousand-unit production runs. The EU Packaging and Packaging Waste Regulation enforces recyclability mandates that disqualify plastic foam alternatives in favor of fiber-based systems. The Ruhr corridor hosts kraftliner production clusters supplying triple-wall constructions for machinery export shipments to India and Southeast Asia.
United States
Medical device manufacturers in Minnesota and Massachusetts require virgin fiber trays for implantable device kits with USP Class VI certification. FDA food-contact substance notifications govern barrier coating formulations for bakery and ready-meal applications. E-commerce fulfillment networks in California and the Pacific Northwest are piloting reusable shipper systems with integrated return labels for apparel and cosmetics channels.
China
Export manufacturing zones in Hangzhou and Dongguan standardize on automated erectable box formats with pre-scored tear strips for returns processing. The State Administration for Market Regulation enforces GB/T standards for recycled content claims that exporters must document for cross-border shipments. Shenzhen assembly plants are consolidating insert specifications across consumer electronics product lines to reduce SKU complexity.
India
Contract manufacturing expansion around Hyderabad and Ahmedabad generates demand for cleanroom-qualified protective packaging with particulate certification. The Central Drugs Standard Control Organization is tightening packaging documentation requirements for pharmaceutical export shipments. Domestic e-commerce growth is pulling corrugated investment toward fulfillment infrastructure in the Delhi-NCR corridor.
France
Retail chains Carrefour and E.Leclerc mandate recyclable tray formats under extended producer responsibility schemes that penalize multi-material constructions. EFSA notifications for bio-based barrier coatings are accelerating as REACH restrictions displace perfluorinated chemistries. The bakery and ready-meal segments in Benelux-bordering regions are most affected by reformulation timelines.
Shaped Corrugated Packaging Market Competitive Landscape
The competitive structure tilts toward integrated mill-to-converter operators with captive fiber supply and multi-country regulatory affairs capabilities. Three strategic archetypes dominate: European-based integrated producers with dense regional mill networks, North American converters with boxboard and converting integration, and Asia-Pacific specialists serving export manufacturing corridors. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with digital print integration emerging as a secondary differentiator for short-run customization.
Within the integrated European tier, Smurfit Kappa and DS Smith exemplify archetypes combining mill ownership with extensive converting footprints across member states. WestRock anchors North American positioning through integrated boxboard and converting operations. Mondi Group occupies a specialization position in moisture-resistant laminated grades for perishable supply chains.
| Leading Market Players |
|---|
| Smurfit Kappa |
| DS Smith |
| WestRock |
| Mondi Group |
| International Paper |
| Rengo Co. |
| Packaging Corporation of America |
| Georgia-Pacific |
| Oji Holdings |
| Others |
Value Network & Pricing Analysis
E-commerce procurement consolidation around automated erectable formats is compressing converter margins and forcing supply-side adaptation toward high-throughput die-cutting investments. This demand compression cascades through fiber sourcing decisions, amplifying exposure to old corrugated container price swings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates converter quotations, with virgin fiber pharmaceutical grades commanding multiples over recycled e-commerce grades. Price differentiation hinges on USP Class VI certification and lot-level traceability documentation. Pricing pressure stems from OCC volatility and energy cost pass-through disputes in German mill negotiations. Food and beverage buyers exhibit highest price sensitivity, while pharmaceutical procurement teams prioritize qualification stability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Amazon and Alibaba fulfillment networks, while distributor networks serve fragmented mid-market converters. Raw material supply concentrates in Germany, China, and the United States for kraftliner and recycled pulp. Manufacturing rests on OCC fiber streams, starch adhesives, and die-cutting tooling from Japanese and German equipment builders. Single-source vulnerability concentrates in German kraftliner capacity, where three integrated producers control majority European supply. Distribution runs through regional converting hubs co-located with major e-commerce sortation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shaped corrugated packaging has entered a late-cycle quality phase where premium specifications for pharmaceutical and medical device applications command sustainable margin premiums. Demand is concentrating toward certified cleanroom-qualified formats with particulate documentation.
For Market Incumbents: Extend captive fiber supply through backward integration into OCC collection networks or long-term mill offtake agreements. Defend against generative design software disruptors by acquiring finite element analysis talent pools before retirement attrition constrains R&D bandwidth. Prioritize certification investment for USP Class VI and ISO 11607 validation to lock in pharmaceutical contract stickiness. For New Entrants and Emerging Players: The mid-tier pricing gap between premium virgin fiber pharmaceutical grades and commodity recycled e-commerce grades offers white-space entry for hybrid fiber formulations with partial certification. Target India's Hyderabad-Ahmedabad pharmaceutical export corridor, where CDSCO documentation requirements are tightening faster than local converter qualification capacity. Pursue digital print integration partnerships as a go-to-market angle for short-run custom insert production below five thousand units. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap converters possessing regional mill relationships and dedicated regulatory affairs functions. Long-term viability favors operators with multi-country EPR scheme navigation capabilities and pharmaceutical certification portfolios. Watch for die-cutting automation adoption rates as an inflection indicator—servo-controlled rotary system penetration above threshold levels signals margin compression for laggard converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Collection | Secures fiber supply against German mill concentration and price volatility. |
| Generative Design Software Deployment | Compresses prototype iteration cycles for Minnesota medical device manufacturers. |
| Pharmaceutical Certification Investment | Unlocks USP Class VI and ISO 11607 contract stickiness with Boston Scientific. |
| Digital Print-Die-Cut Line Convergence | Enables lot-specific branding without plate changeover delays for California cosmetics brands. |
| India Pharmaceutical Corridor Expansion | Captures CDSCO documentation demand from Hyderabad contract manufacturing zones. |
Research Methodology
Direct dialogue with corrugated converters, e-commerce fulfillment procurement managers, pharmaceutical packaging engineers, and die-cutting equipment manufacturers grounded the qualitative foundation. Secondary validation drew from EPA recycled content guidelines, EU REACH restriction updates, FDA food-contact substance notifications, and OCC pricing indices. Bottom-up demand modeling across end-use segments triangulated against top-down capacity assessments from major mill networks.
Segment-level outputs across product type, material grade, end-user vertical, and design complexity were generated across the analysis window. CAGRs were derived from regression analysis of historical volume trends against e-commerce penetration rates and pharmaceutical cold chain expansion trajectories. Model inputs incorporated die-cutting automation adoption curves, EPR fee structure evolution, and generative design software penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for bio-based barrier coatings or reusable shipper systems would alter the outlook. Forecasts reflect documented assumptions regarding recycled fiber cost stability and regulatory timeline adherence. Periodic stress-testing of base assumptions against OCC price volatility and EPR scheme implementation delays is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Carton Sealer Market
Cartons
Global Cartonboard Market
Cartons
XXL Packaging Market
Cartons
Brick Carton Packaging Market
Cartons
North America Corrugated and Folding Carton Packaging Market
Cartons
Tetrahedron Carton Market
Cartons
Cardboard Crates Market
Cartons
Twist Opening Cartons Market
Cartons
Folding Carton in Healthcare Market
Cartons
Asia Pacific Folding Carton Market
Cartons
Round Corrugated Box Market
Cartons
Liquid Packaging Cartons Market
Cartons
Global Open Top Cartons Market
Cartons
Beverage Cartons Market
Cartons
GCC Corrugated Box Packaging Market
Cartons
Japan Corrugated Boxes Market