
 Cardboard Crates Market | 2026-2036
Cardboard Crates Market Size, Share, and Industry Trends Forecast 2026-2036
Cardboard Crates Market Outlook
Modular crate configurations are decoupling bulk procurement from standardized unit economics, letting buyers mix single-wall and double-wall panels within unified orders. Smurfit WestRock leverages its European mill network to anchor regional supply for automotive tier suppliers. DS Smith competes through circular-design services that extend customer retention beyond commodity board sales. Mondi Group specializes in moisture-resistant coatings that dominate fresh-produce export lanes from Southern Europe.
Cardboard crates are rigid containers fabricated from corrugated fiberboard, typically combining linerboard facings with fluted medium in wall constructions ranging from 3 mm to 15 mm thickness, engineered to protect goods through stacking strength and cushioning during transit. Double-wall and triple-wall grades concentrate margin pools where palletized machinery and electronics require crush resistance beyond single-wall capability. Food & Beverage end users generate volume leadership in display and shipping applications, while pharmaceutical cold-chain expansion pushes demand for insulated hybrid crate formats.
EU REACH and F-Gas Regulation constrain adhesive and coating chemistries, while the EU Green Deal mandates recycled-content thresholds that reshape supplier qualification criteria. FDA food-contact standards govern export-bound crates entering US distribution, adding compliance layers for European and Asian manufacturers. Stakeholders must monitor how Ecodesign for Sustainable Products Regulation definitions absorb packaging within scope, as this determines whether recycled-content verification becomes a market-access gate or merely a procurement preference.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles across the corrugated value chain, forcing mills and converters to requalify board grades against recyclability thresholds before the mandates take effect.
Growth Catalysts
- E-commerce fulfillment density:Automated storage and retrieval systems in German and Dutch distribution centers require standardized crate footprints that corrugated suppliers now engineer with precision-cut die lines.
- REACH chemical compliance:Reformulated water-based adhesives and mineral oil-free inks are unlocking food-contact applications that previously required plastic alternatives.
- Automotive export packaging:Heavy-duty triple-wall crates protect powertrain components shipped from Stuttgart and Wolfsburg to assembly plants in Mexico and the United States.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container prices fluctuate with municipal collection rates, squeezing converter margins when post-consumer supply tightens.
- Energy-intensive production:Natural gas dependency in European linerboard mills exposes cost structures to carbon border adjustment mechanisms.
- Plastic crate substitution:Returnable plastic containers in closed-loop automotive supply chains displace single-trip cardboard for high-frequency routes.
Strategic Opportunities
- Polish manufacturing expansion:Greenfield corrugator investments near Poznan and Wroclaw capture overflow demand from saturated German capacity.
- Smart packaging integration:NFC-enabled crates are converging with warehouse management systems to provide real-time location tracking through last-mile networks.
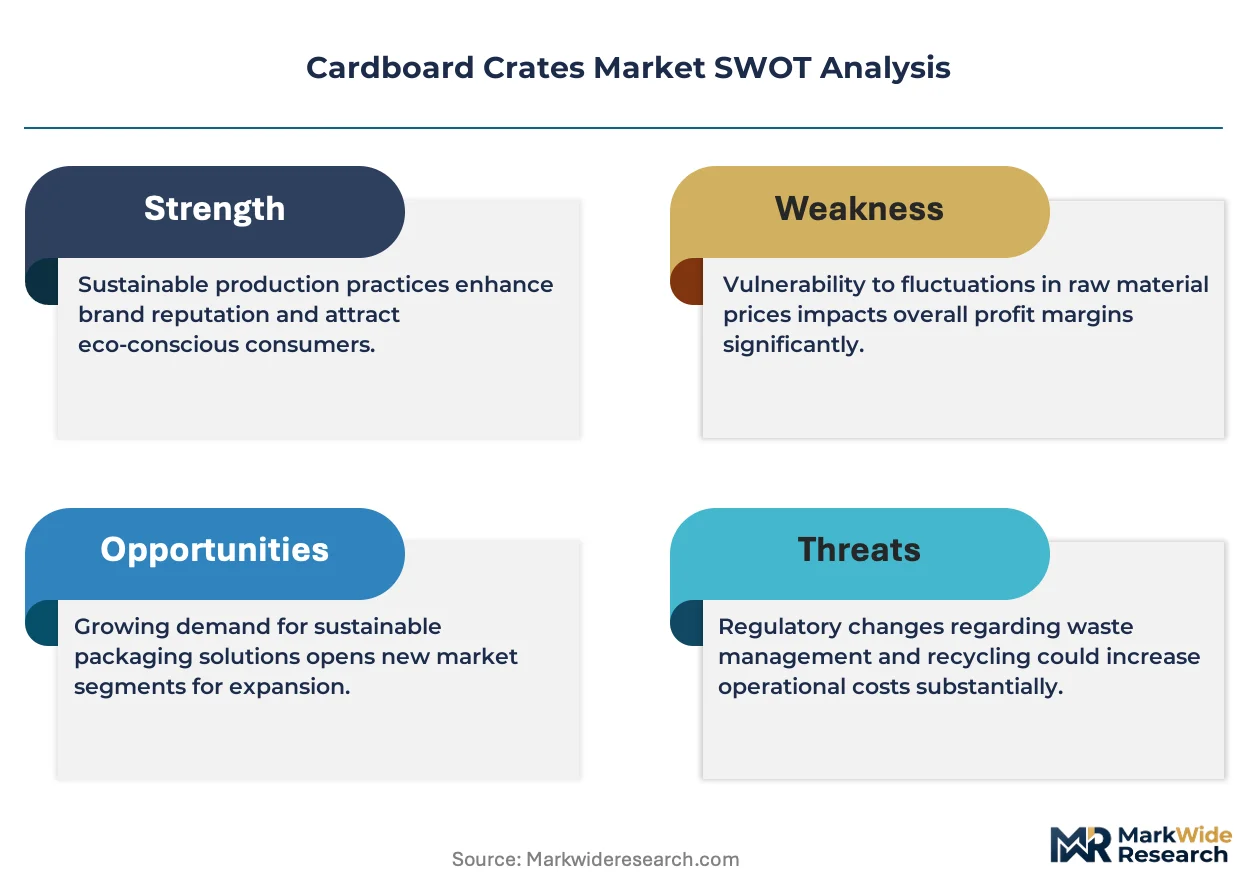
- EU Green Deal recycled-content mandates:Early certification against forthcoming thresholds positions suppliers for preferred-vendor status with multinational FMCG procurement teams.
Industry Challenges
- Structural engineer talent scarcity:Finite-element modeling expertise for custom crush-resistant designs concentrates among aging specialists in Bavaria and Baden-Württemberg.
- Legacy ERP integration:Smaller converters struggle to connect quoting engines with customer EDI platforms for just-in-time automotive supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardboard Crates Market |
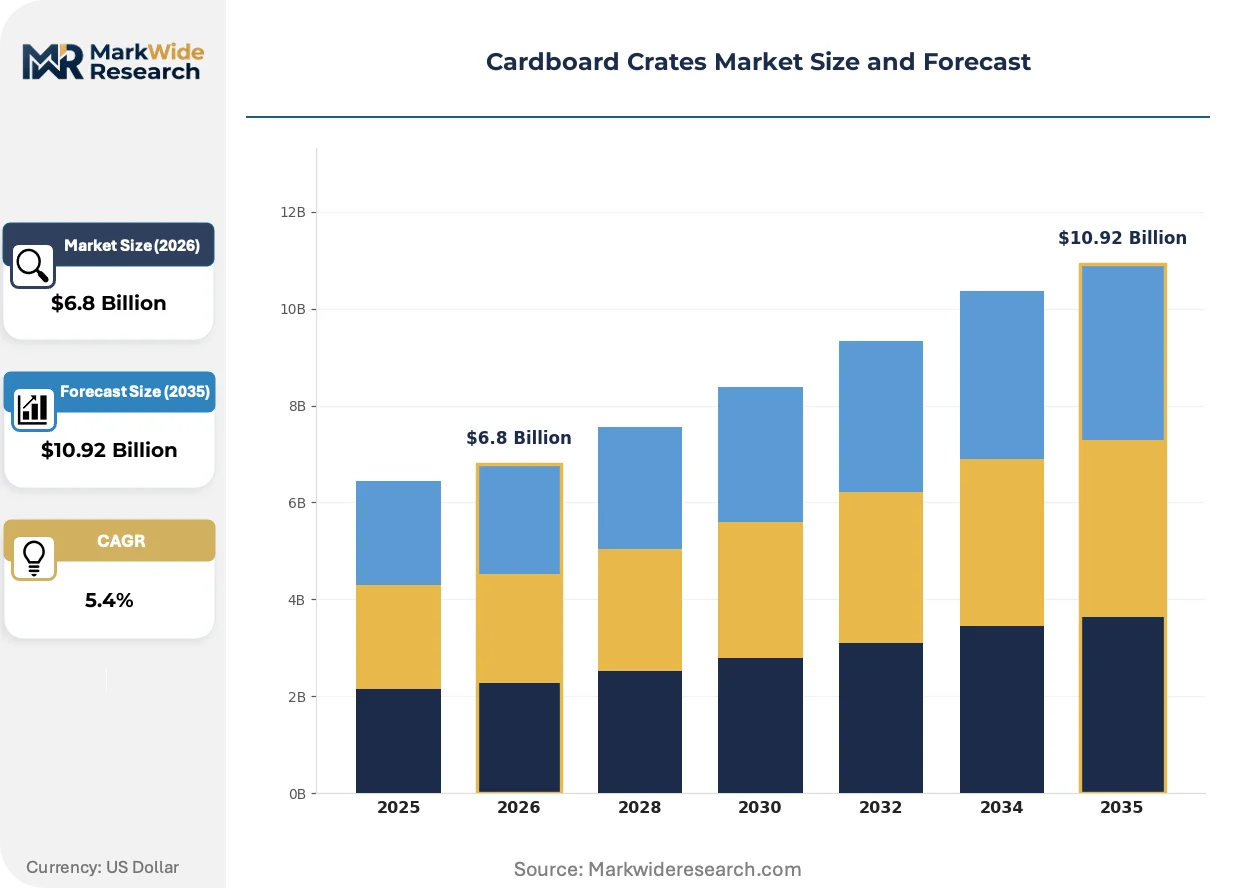
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-wall, Double-wall, Triple-wall, Heavy-duty End User: Food & Beverage, Electronics, Consumer Goods, Pharmaceuticals Application: Storage, Shipping, Packaging, Display Distribution Channel: Direct Sales, Online Retail, Distributors, Retail Stores |
| Companies Covered | Smurfit WestRock, DS Smith, Mondi Group, International Paper, Stora Enso, Nine Dragons Paper, Rengo Co., Oji Holdings, Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardboard Crates Market Strategic Shifts
Active R&D investment is redirecting toward barrier coatings and digital printing integration, shifting competitive advantage away from commodity board tonnage toward specification-driven contract manufacturing.
Moisture-resistant bio-based coatings are converging with conventional fluting lines to extend cardboard crate viability in fresh-produce cold chains. Spanish citrus exporters and Italian vegetable cooperatives are piloting these grades for trans-Mediterranean routes. The technology is converging with existing corrugator assets without requiring greenfield capital, compressing adoption timelines for mid-tier converters.
REACH and F-Gas Regulation constraints are eliminating solvent-based adhesive chemistries from European production. Mills in the Rhine-Ruhr industrial corridor are retrofitting starch kitchens to meet ECHA substance restrictions. Food-contact crate manufacturers face compressed reformulation deadlines that favor integrated suppliers with captive adhesive blending capabilities.
Consolidated buying desks at multinational retailers are unbundling crate specification from logistics procurement. German grocery chains now source direct from board mills for private-label packaging, bypassing traditional distributor networks. This pattern concentrates most visibly in the discount retail segment, where Aldi and Lidl procurement teams negotiate multi-year corrugated supply agreements covering multiple national markets.
Cardboard Crates Market Segmentation
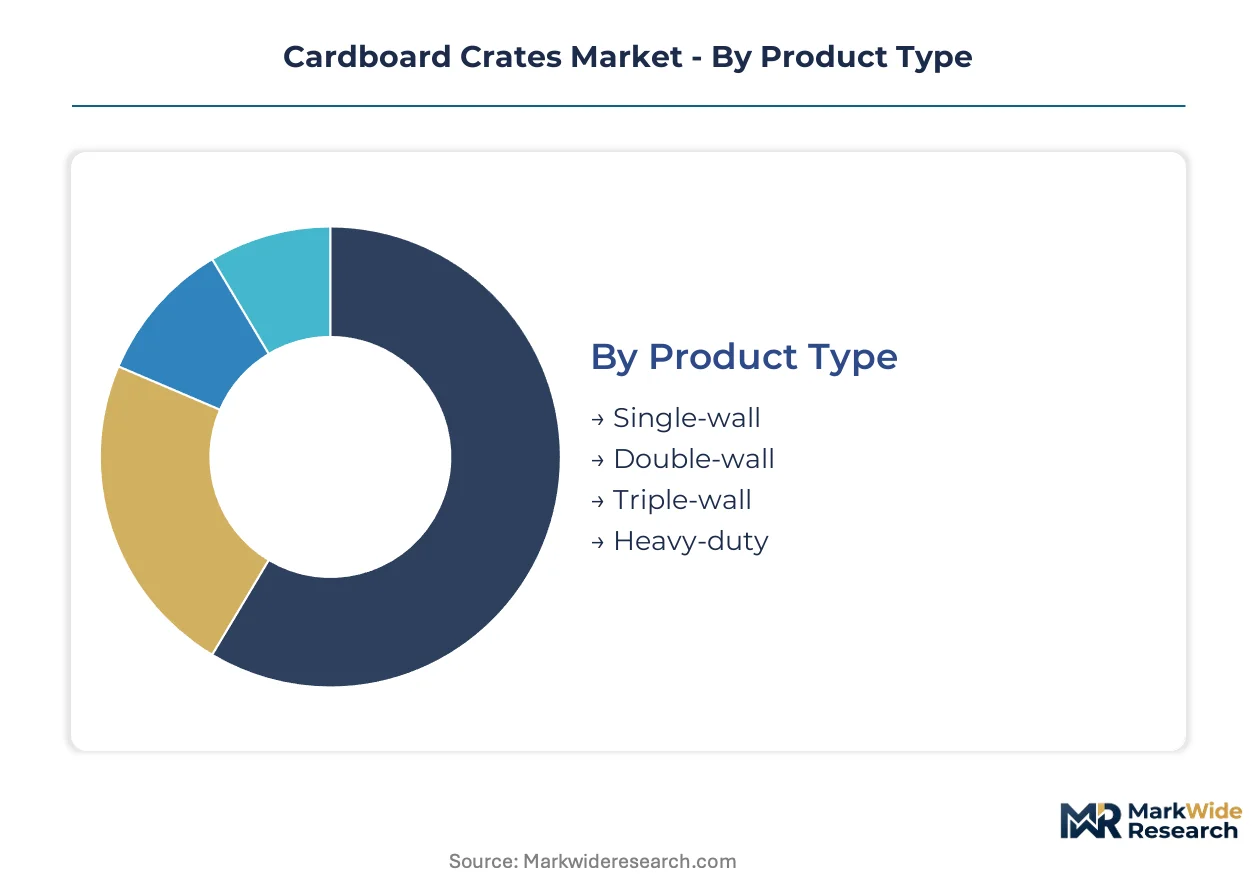
Segmentation in cardboard crates reveals how wall construction, end-use requirements, and channel economics create distinct margin pools. Procurement teams optimize specifications against handling intensity, transit distance, and shelf-life demands.
Product Type:
Volume leadership concentrates in single-wall grades, while premium margins accumulate in multi-wall and heavy-duty formats engineered for export rigor.
- Single-wall:Constructed from one fluted medium sandwiched between linerboard facings, typically 3-5 mm thickness. German e-commerce fulfillment centers specify these for parcels under 15 kg, balancing cube utilization with automated sortation compatibility.
- Double-wall:Two fluted layers separated by intermediate linerboard deliver 7-9 mm stack strength. Stuttgart automotive tier suppliers deploy these for powertrain components crossing Atlantic routes, where compression resistance determines damage rates.
- Triple-wall:Three fluted layers achieve 12-15 mm rigidity for machinery and industrial equipment. REACH-compliant adhesives are mandatory for these grades entering food-contact applications.
- Heavy-duty:Custom-engineered constructions with reinforced corners and moisture barriers for extreme handling cycles.
Mature deployment sits with single-wall grades in domestic parcel networks. Newer deployment is concentrated in triple-wall formats for transcontinental automotive supply chains.
End User:
Application-driven specifications diverge sharply between temperature-sensitive logistics and standard ambient distribution.
- Food & Beverage:Cold-chain expansion drives insulated hybrid formats combining corrugated shells with thermal liners. Italian vegetable cooperatives and Spanish citrus exporters pilot moisture-resistant bio-based coatings for Mediterranean routes.
- Electronics:Electrostatic discharge requirements and precision-fit cushioning dominate procurement criteria. Dutch distribution centers specify die-cut double-wall configurations for automated storage retrieval compatibility.
- Consumer Goods:Display-ready graphics and shelf-ready packaging merge shipping and retail functions.
- Pharmaceuticals:GDP compliance and temperature validation protocols govern qualification. EU Green Deal recycled-content thresholds are reshaping supplier audits for cold-chain crate vendors.
Procurement consolidation is most advanced in food and beverage, where Aldi and Lidl buying desks negotiate multi-year mill-direct agreements. Pharmaceutical qualification cycles remain the longest, with EMA documentation requirements extending vendor onboarding timelines.
Application:
Functional requirements separate static storage from dynamic transit, with display applications demanding print quality incompatible with rough handling.
- Storage:Long-duration stacking in warehouse racking requires edge crush test ratings above 32 ECT.
- Shipping:Multi-modal transit exposes crates to humidity cycling and mechanical shock. Polish manufacturing expansion near Poznan targets overflow demand for export-grade shipping specifications.
- Packaging:Product containment and protection during single-trip distribution.
- Display:Retail-ready graphics and structural integrity for shelf presentation without repacking.
Margin compression is steepest in pure shipping applications where commoditization pressures dominate. Display and protective packaging retain pricing power through specification complexity.
Distribution Channel:
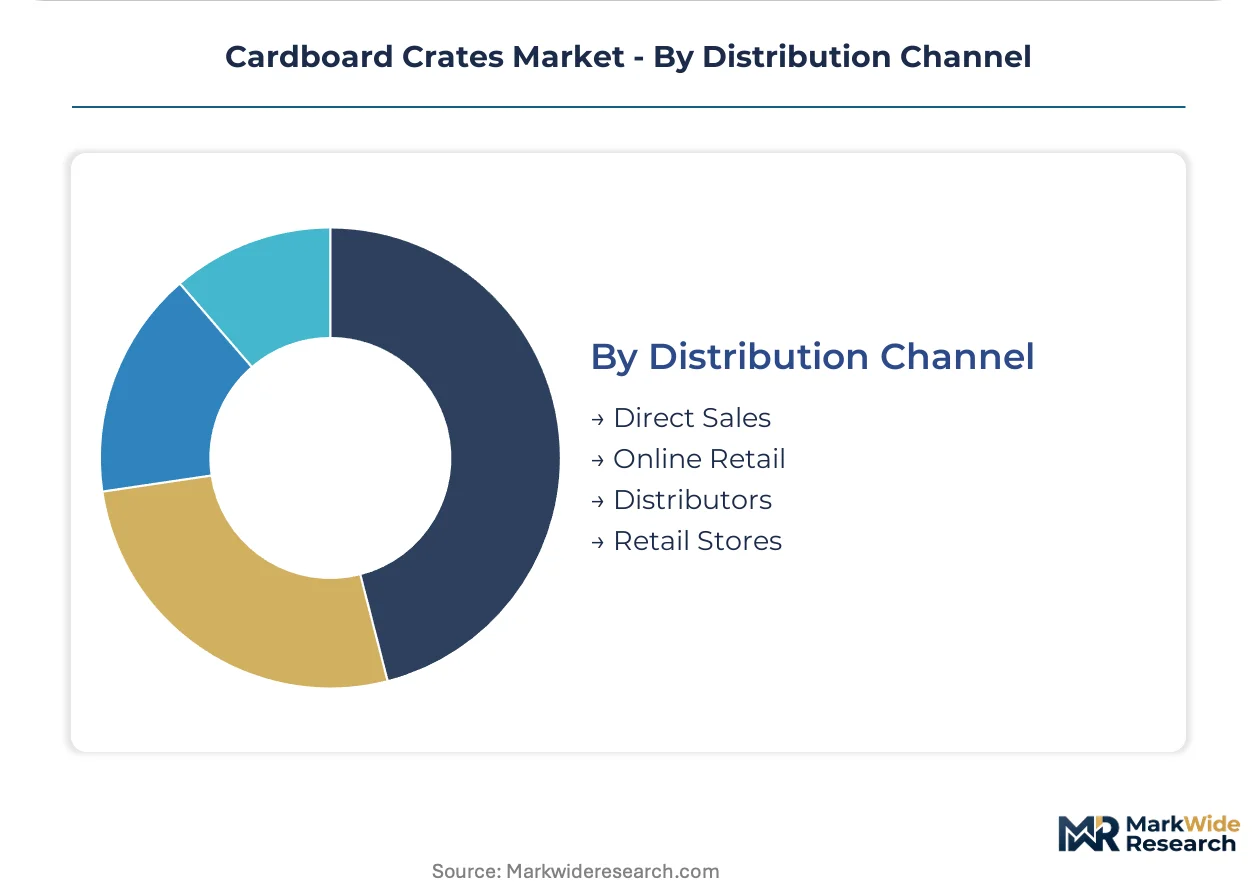
Channel selection reflects order scale, customization depth, and inventory velocity requirements across customer segments.
- Direct Sales:Mill-direct procurement by consolidated retail buying desks eliminates distributor margins. German grocery chains now source corrugated specifications directly from Rhine-Ruhr mills.
- Online Retail:Digital platforms enable small-batch ordering with rapid specification turnaround.
- Distributors:Stock-and-serve models support fragmented demand from mid-tier manufacturers.
- Retail Stores:Point-of-purchase availability for immediate-need replacement and small-volume buyers.
Direct sales channels are gaining share fastest among multinational FMCG procurement teams seeking recycled-content certification transparency. Distributor relevance concentrates in geographic markets with fragmented manufacturing bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and Poland while consumption spreads across Western European distribution networks. Mills in the Rhine-Ruhr corridor supply converted board to fulfillment centers in the Netherlands and Belgium. Energy costs and recycled fiber availability drive locational decisions more than end-market proximity.
Germany
Automotive component exports from Stuttgart and Wolfsburg generate concentrated demand for triple-wall protective crating. The EU Packaging and Packaging Waste Regulation forces mills to requalify board grades against recyclability thresholds before mandates take effect. Corrugator investments in Bavaria and Baden-Württemberg focus on heavy-duty formats for trans-Atlantic powertrain shipments.
Poland
Greenfield corrugator installations near Poznan and Wroclaw capture overflow demand from saturated German capacity. EU Green Deal recycled-content mandates reshape supplier qualification criteria for FMCG procurement teams. Manufacturing expansion targets export-grade shipping specifications for Central European distribution networks.
Netherlands
Automated storage and retrieval systems in Dutch distribution centers require precision-cut die lines for standardized crate footprints. REACH chemical compliance drives reformulation of water-based adhesives for food-contact applications. Rotterdam logistics clusters anchor demand for moisture-resistant coatings in trans-shipment cold chains.
Spain
Citrus exporters and vegetable cooperatives pilot bio-based barrier coatings for trans-Mediterranean fresh-produce routes. ECHA substance restrictions eliminate solvent-based adhesive chemistries from corrugated production. Valencia and Murcia agricultural clusters drive adoption of insulated hybrid crate formats for temperature-sensitive logistics.
Italy
Vegetable cooperatives in Southern Europe test moisture-resistant grades for extended shelf-life shipping. F-Gas Regulation constraints reshape coating chemistry selection for cold-chain applications. Northern Italian industrial districts concentrate display-ready packaging demand from consolidated retail buying desks.
Cardboard Crates Market Competitive Environment
The competitive structure tilts toward integrated mill-to-converter operators with captive fiber supply and regional logistics networks. Tier-one suppliers combine linerboard production with downstream corrugator assets, while mid-tier converters compete on specification agility and short-run customization. Strategic moves concentrate on capacity relocation to lower-cost energy jurisdictions and early certification against EU Green Deal recycled-content thresholds.
Among European-integrated packaging groups, Smurfit WestRock, DS Smith, and Mondi Group occupy distinct competitive positions. Smurfit WestRock anchors regional supply through its European mill network for automotive tier suppliers. DS Smith exemplifies the circular-design service archetype that extends customer retention beyond commodity board sales. Mondi Group represents the specialized coating segment with moisture-resistant technologies for fresh-produce export lanes from Southern Europe.
| Leading Market Players |
|---|
| Smurfit WestRock |
| DS Smith |
| Mondi Group |
| International Paper |
| Stora Enso |
| Nine Dragons Paper |
| Rengo Co. |
| Oji Holdings |
| Packaging Corporation of America |
| Others |
Value Chain & Pricing Dynamics
Water-based adhesive reformulation under REACH mandates is compressing converter margins while simultaneously concentrating supply among integrated mills with captive chemical blending capabilities. This dual squeeze reshapes procurement economics as smaller converters face qualification barriers that favor operators with Rhine-Ruhr production assets.
Pricing Analysis
Cost-down pressure on single-wall grades accelerates because German e-commerce fulfillment centers negotiate multi-year mill-direct contracts that bypass distributor markups. Three-tier pricing structure across heavy-duty, double-wall, and single-wall levels reflects ECT rating and moisture-barrier certification. Procurement consolidation at Aldi and Lidl buying desks intensifies pricing pressure through volume aggregation. Automotive tier suppliers prove least price-sensitive, prioritizing damage-rate guarantees over per-unit crate costs.
Supply Chain Analysis
Old corrugated container collection flows and mill broke streams form the reverse-logistics backbone feeding recycled fiber supply. Production gravity centers on Germany, Poland, and the Netherlands, with greenfield corrugators near Poznan capturing overflow from saturated German capacity. Supply chains draw from linerboard mills in the Rhine-Ruhr corridor, starch adhesive kitchens, and mineral oil-free ink suppliers. Single-source vulnerability concentrates in natural gas-dependent drying operations. Distribution runs through mill-direct channels for consolidated retail buyers and distributor networks for fragmented mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Moisture-resistant bio-based coatings are displacing conventional wax barriers in fresh-produce cold chains, creating qualification windows for suppliers with Southern European logistics networks.
For Market Incumbents: To counter Polish manufacturing expansion eroding German market share, Smurfit WestRock and DS Smith should anchor regional supply through captive linerboard production in Bavaria while accelerating EU Green Deal recycled-content certification ahead of mandate deadlines. Backward integration into starch adhesive blending insulates against ECHA reformulation timelines. For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical cold-chain crates offers white-space entry for specialists with GDP-compliant hybrid formats. Target Italian vegetable cooperatives and Spanish citrus exporters with moisture-resistant bio-based coatings. Pursue direct sales to consolidated retail buying desks seeking certification transparency bypassing traditional distributors. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated packaging groups seeking Southern European coating capabilities. Mid-term viability hinges on EU Ecodesign scope definitions determining whether recycled-content verification becomes market-access gate or procurement preference. Monitor ECHA substance restriction timelines for adhesive chemistry inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Polish greenfield corrugators near Poznan capture German overflow demand. |
| Backward Integration | Captive starch adhesive blending accelerates REACH compliance timelines. |
| Green Certification Program | Early EU Green Deal recycled-content positioning secures FMCG preferred-vendor status. |
| Long-term Supply Agreement | Multi-year mill-direct contracts with Aldi and Lidl eliminate distributor margins. |
| Joint Venture | Coating technology partnerships extend cardboard viability in Mediterranean cold chains. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with corrugator plant managers, automotive tier supplier procurement leads, FMCG category buyers, and starch adhesive technical directors. ECHA substance restriction databases, EU Packaging and Packaging Waste Regulation impact assessments, and Rhine-Ruhr mill production disclosures provided validation layers. Bottom-up capacity modeling and top-down consumption estimates were triangulated against cross-referenced sources.
Reconciling production capacity data with end-use consumption patterns required segment-level disaggregation across wall construction grades, application functions, and channel structures. The analytical framework projected volume and value trajectories across the modeling period by linking linerboard output trends to fulfillment center automation deployment and automotive export packaging specifications. CAGRs were derived from trend extrapolation of corrugator investment cycles and recycled fiber availability curves.
Inputs from ECHA regulatory consultations and EU member state implementation guidance were available through the study window; gaps in real-time Old Corrugated Container pricing transparency introduce uncertainty bands around margin forecasts. Practitioners should monitor Ecodesign for Sustainable Products Regulation scope determinations and municipal collection rate fluctuations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cartons
Global Open Top Cartons Market
Cartons
GCC Folding Carton Market
Cartons
Metallized Folding Cartons Market
Cartons
Thailand Folding Cartons and Corrugated Packaging Market
Cartons
Foldable/Compressible Beverage Carton Market
Cartons
Carton Sealer Market
Cartons
Braille Cartons Packaging Market
Cartons
Indonesia Folding Carton Packaging Market
Cartons
Tuck Top Box Market
Cartons
Carton Form Fill Seal Machine Market
Cartons
Thailand Folding Carton Packaging Market
Cartons
Cupcake Box Market
Cartons
Brick Carton Packaging Market
Cartons
Horizontal Cartoning Machines Market
Cartons
Carton Liners Market
Cartons
Microwaveable Carton Market