
 Insulated Bin Market | 2026-2036
Insulated Bin Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Bin Market Insights
North American rotational molding capacity is consolidating around specialty cold-chain producers. Bonar Plastics leverages deep expertise in polyurethane foam injection to sustain its position in pharmaceutical-grade containers. Pelican BioThermal anchors the high-performance segment with advanced phase-change material integration. Cold Chain Technologies competes through extensive rental fleet networks serving courier services and logistics providers.
An insulated bin is a thermally engineered container employing polyurethane foam, vacuum insulation panels, or expanded polystyrene cores to maintain stable internal temperatures between minus 80 degrees Celsius and plus 25 degrees Celsius for sensitive cargo. These units serve as critical nodes in temperature-controlled distribution, protecting payload integrity across multimodal transit from manufacturing sites to end-user facilities. Polystyrene foam dominates volume production due to cost efficiency, while vacuum insulation panels command premium positioning in pharmaceutical transport where extended hold times justify higher unit economics. Medium-capacity bins between 11 and 50 liters represent the fastest-expanding category, driven by last-mile vaccine delivery and direct-to-patient pharmaceutical distribution models.
The EPA regulates refrigerant emissions in transport equipment, while FDA guidelines mandate continuous temperature documentation for pharmaceutical shipments, jointly elevating compliance costs for non-validated bin designs. ISO standards for thermal packaging qualification further tighten market access for uncertified suppliers. Stakeholders must monitor evolving F-Gas Regulation amendments and state-level cold-chain energy codes as these frameworks will determine which insulation technologies retain commercial viability in regulated corridors.
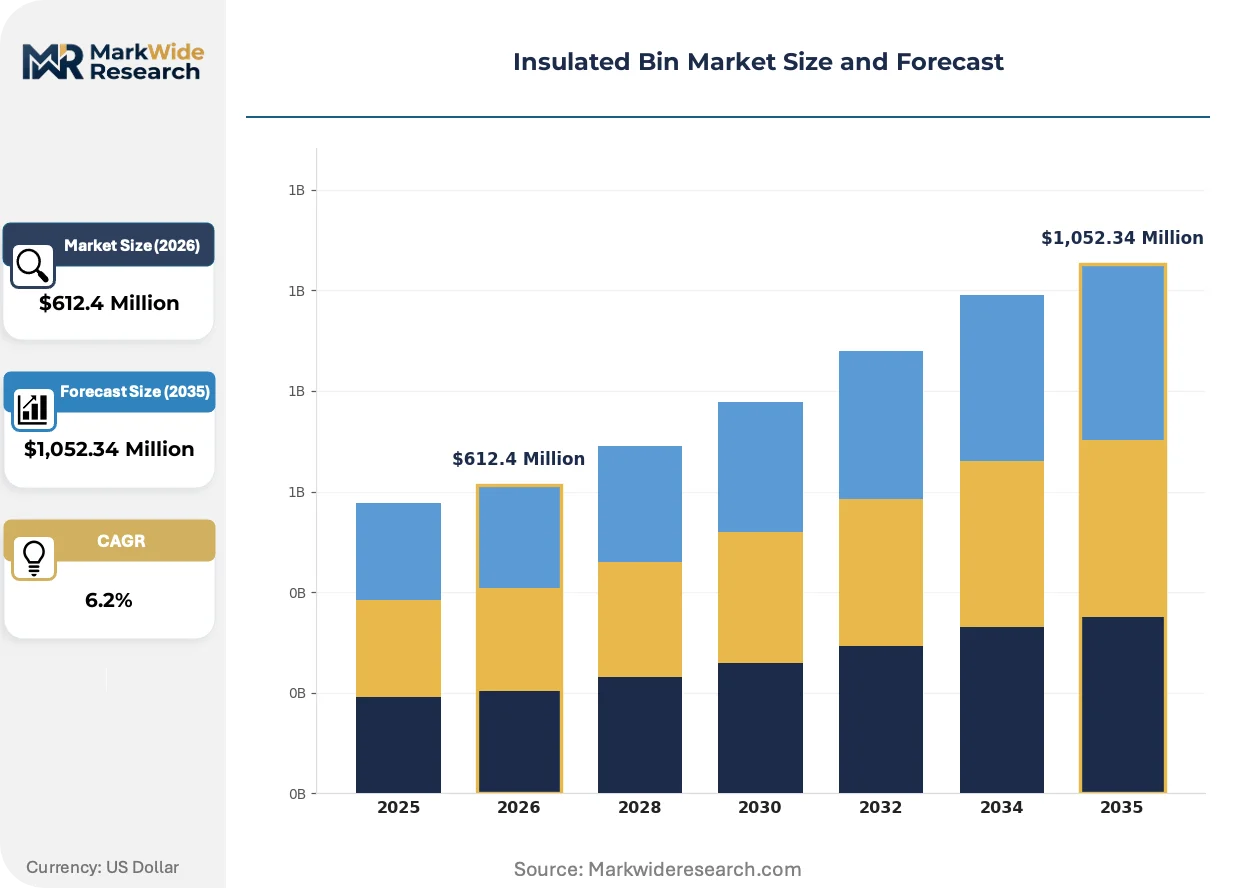
Market Dynamics
Pharmaceutical cold-chain compliance is compressing procurement cycles as biologics manufacturers demand validated thermal protection from manufacturing sites through last-mile delivery nodes.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for high-global-warming-potential refrigerants are accelerating vacuum insulation panel adoption in temperature-controlled logistics corridors across Germany and France.
- Biologics manufacturing clusters:Concentrated pharmaceutical production in Bavaria and Baden-Württemberg generates sustained demand for medium-capacity validated bins serving direct-to-patient distribution.
- Phase-change material integration:Advanced thermal mass technologies are extending passive hold times beyond 96 hours, reducing active refrigeration dependency for intercontinental vaccine shipments.
Market Restraints
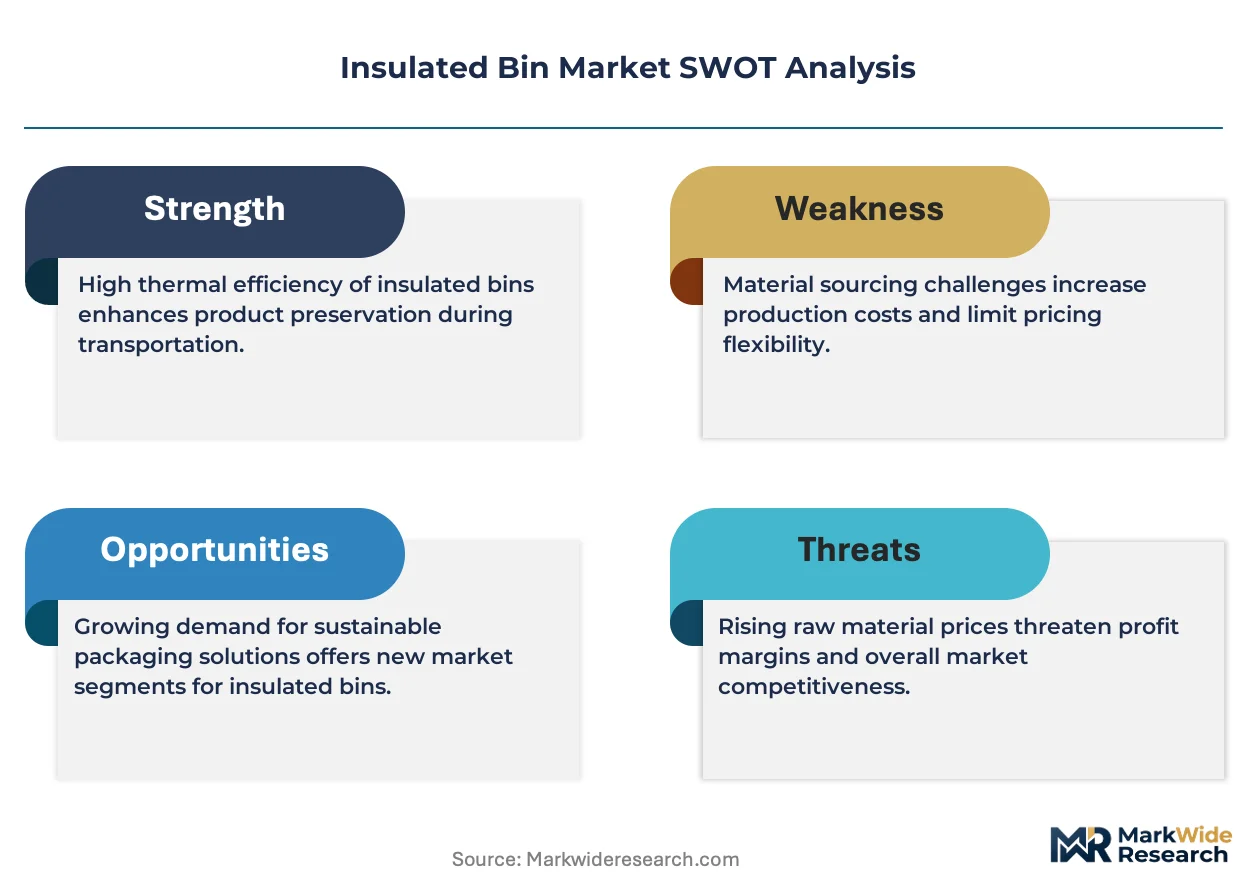
- Polyurethane foam input volatility:Isocyanate and polyol feedstock price swings compress margin structures for rotational molders serving the standard bin segment.
- Specialty resin supply concentration:North American rotational molding compound availability tightens around a limited producer base, constraining capacity expansion timelines.
- Validation protocol rigidity:ISO 17025 thermal qualification requirements create multi-month certification barriers for modified designs or new material formulations.
Strategic Opportunities
- Cell and gene therapy logistics:Cryogenic (-150°C) distribution requirements for CAR-T treatments are opening premium positioning for vacuum-insulated dewar-style containers in specialized courier networks.
- India cold-chain infrastructure:PLI scheme incentives for pharmaceutical manufacturing are generating first-mile insulated bin demand from Mumbai and Hyderabad production hubs.
- Reusable rental fleet models:Asset-light logistics providers are shifting from purchase-to-own toward pooled container programs, creating recurring revenue streams for fleet operators.
Industry Challenges
- Thermal engineer scarcity:Specialized expertise in computational fluid dynamics modeling for passive container design concentrates among a limited cohort of consultants and in-house specialists.
- Multi-modal integration complexity:Seamless temperature documentation across air, road, and sea handoffs requires API interoperability that legacy ERP systems in developing logistics corridors cannot support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Bin Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,052.34 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyurethane Foam, Polystyrene Foam, Vacuum Insulation Panels, Expanded Polystyrene, Fiberglass, Aerogel Application: Cold Chain Logistics, Food Storage, Pharmaceutical Transport, Chemical Containment, Beverage Distribution, Floral Preservation End User Industry: Logistics Providers, Food Processing Firms, Pharmaceutical Manufacturers, Beverage Companies, Courier Services, Agriculture Producers Bin Capacity: Small (up to 10 liters), Medium (11-50 liters), Large (51-150 liters), Extra Large (above 150 liters) |
| Companies Covered | Bonar Plastics, Pelican BioThermal, Sonoco ThermoSafe, Cold Chain Technologies, Csafe Global LLC, Cascades Inc., Cryopak, Polarplas, DACO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Bin Market Trends and Innovations
Material science advances and regulatory stringency are converging to reshape insulation performance standards, with passive thermal protection systems gaining ground against active refrigeration in pharmaceutical distribution.
Smart sensor integration is automating temperature documentation workflows throughout the supply chain. Embedded IoT loggers with real-time cellular connectivity are replacing manual data extraction processes at destination facilities. Pharmaceutical 3PL providers in Germany and Switzerland are deploying these systems across their qualified container fleets, compressing documentation labor and reducing excursion investigation timelines.
The EPA's refrigerant management regulations under Section 608 are tightening leak detection and repair requirements for transport refrigeration units. This regulatory pressure elevates total cost of ownership for mechanically refrigerated containers versus advanced passive alternatives. Vaccine distributors in the United States are responding by expanding validated passive bin procurement for domestic distribution lanes under 48 hours.
Direct-to-patient pharmaceutical delivery is fragmenting order sizes and compressing batch economics for insulated bin utilization. Specialty pharmacies and home infusion providers are replacing bulk hospital shipments with single-dose thermal protection requirements. This pattern concentrates demand growth in the 11-50 liter capacity band across North American and Western European urban corridors.
Insulated Bin Market Segmentation
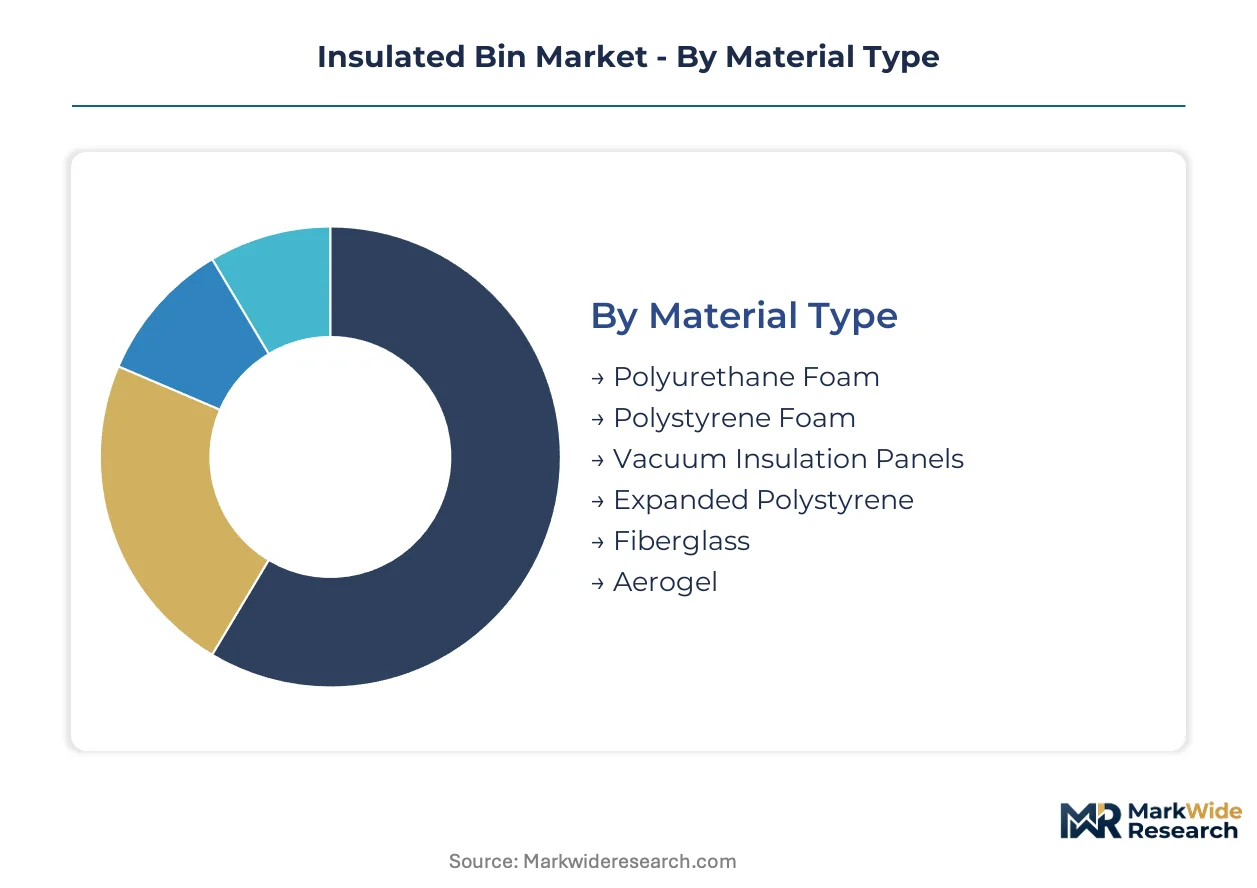
Insulated bin procurement patterns diverge sharply across material grades and thermal performance tiers. Pharmaceutical validation requirements and food safety mandates create distinct specification clusters that reshape manufacturing priorities and margin structures.
Material Type:
Supply concentration in rotational molding compounds favors processors with captive foam chemistry partnerships or long-term polyol supply agreements.
- Polyurethane Foam:Open-cell or closed-cell formulations injected between rotational-molded polyethylene shells deliver customizable R-values and impact resistance. Demand clusters in standard cold-chain logistics serving food distributors in Germany and France where cost efficiency outweighs extended hold-time requirements.
- Vacuum Insulation Panels:Microporous cores sealed under vacuum achieve thermal conductivity below 0.005 W/m·K, enabling 96-hour passive protection in sub-5°C ranges. Pharmaceutical courier networks in Switzerland and specialized CAR-T therapy distributors absorb premium unit economics for cryogenic-grade specifications.
- Polystyrene Foam:Expanded bead structures dominate single-use vaccine distribution in developing corridors.
- Expanded Polystyrene:Molded block insulation serves floral preservation and short-cycle food delivery applications.
- Fiberglass:Batt and rigid board formats address industrial chemical containment with fire-rated specifications.
- Aerogel:Silica-based nanoporous materials command niche positioning in ultra-lightweight pharmaceutical containers.
Polyurethane foam absorbs the bulk of installed capacity; vacuum insulation panels are expanding most quickly.
Application:
Application-driven specification splits mirror the compliance burden differential between regulated pharmaceutical corridors and standard food distribution.
- Pharmaceutical Transport:Validated thermal packaging for biologics, vaccines, and cell therapies demands continuous temperature documentation and ISO 17025 qualification. EU F-Gas Regulation phase-down mandates accelerate vacuum panel adoption for intercontinental shipments originating from manufacturing clusters in Bavaria.
- Cold Chain Logistics:Multi-modal temperature-controlled distribution for perishables integrates passive bins with active refrigeration handoffs. Food retailers and third-party logistics providers in France prioritize medium-capacity units for urban last-mile delivery.
- Food Storage:Commercial and institutional catering applications specify polystyrene-dominated cost-optimized units.
- Chemical Containment:Hazardous material transport regulations drive fiberglass and composite-shell specifications.
- Beverage Distribution:Brewery and winery direct-to-trade channels utilize branded medium-capacity bins.
- Floral Preservation:Horticultural exporters in the Netherlands deploy expanded polystyrene solutions for transcontinental rose and tulip shipments.
Pharmaceutical transport commands premium pricing tiers; cold chain logistics delivers volume scale.
End User Industry:
Customer-type segmentation reveals divergent procurement models between asset-heavy pharmaceutical manufacturers and asset-light logistics intermediaries.
- Pharmaceutical Manufacturers:In-house cold-chain operations at biologics production sites in Baden-Württemberg specify validated, reusable bins with embedded IoT temperature logging. Direct ownership models dominate given batch integrity liability and FDA documentation requirements.
- Logistics Providers:Asset-light third-party operators are shifting toward pooled rental fleets to reduce capital deployment and obsolescence risk. German pharmaceutical 3PLs contract specialized fleet operators for qualified container access.
- Food Processing Firms:Dairy and protein processors in northern Germany procure medium-capacity units for plant-to-distribution-center movements.
- Courier Services:Express delivery networks prioritize lightweight, stackable designs for high-velocity sorting environments.
- Beverage Companies:Craft brewery direct-to-consumer channels drive small-capacity insulated packaging demand.
- Agriculture Producers:Specialty crop exporters utilize seasonal bin leasing for harvest-period peak requirements.
Pharmaceutical manufacturers absorb the bulk of installed capacity; logistics providers are expanding most quickly.
Bin Capacity:
Capacity tier preferences track the fragmentation of order sizes in direct-to-patient pharmaceutical delivery and urban food service consolidation.
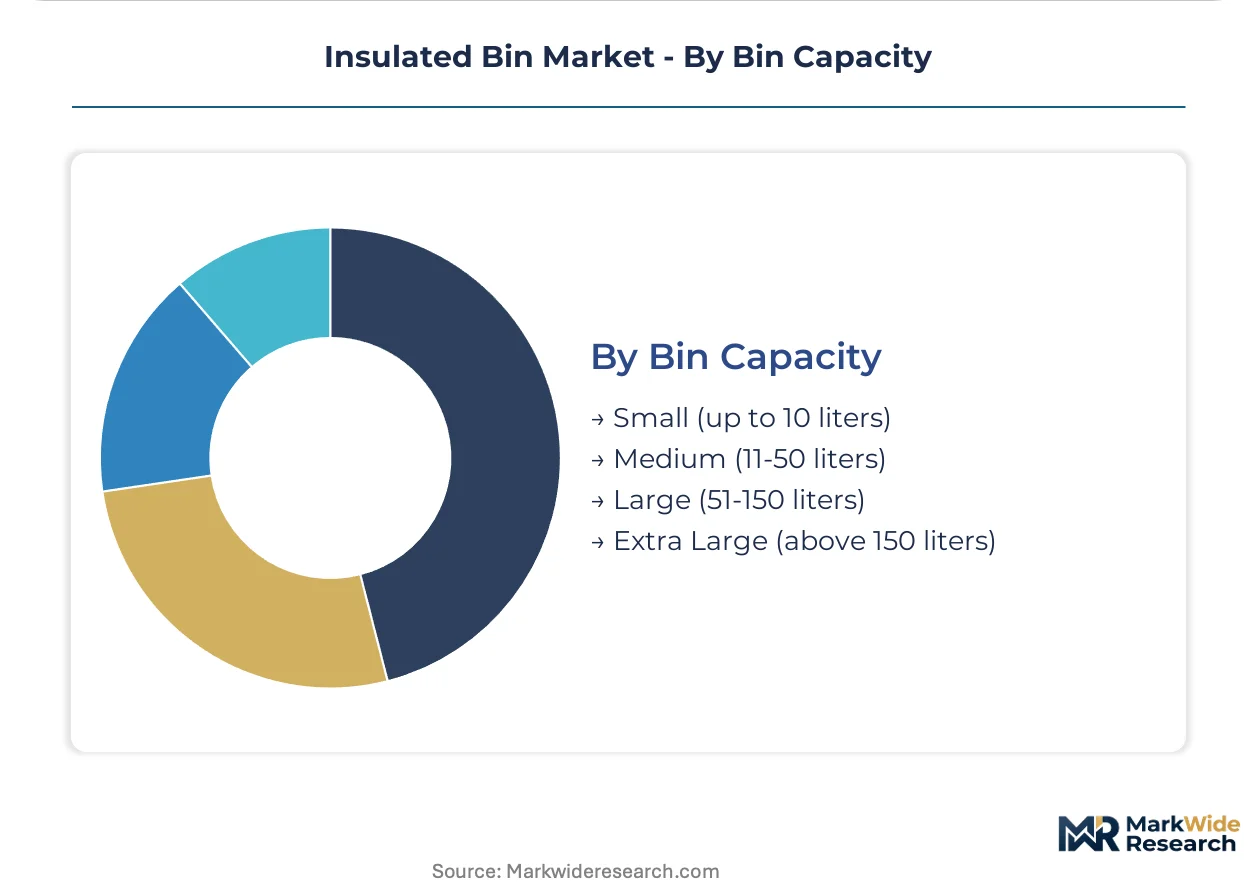
- Medium (11-50 liters):This capacity band captures last-mile vaccine delivery, home infusion therapy shipments, and meal-kit distribution. Swiss specialty pharmacies and German direct-to-patient couriers drive specification intensity for validated units with 48-72 hour hold times.
- Small (up to 10 liters):Single-dose biologics and temperature-sensitive diagnostic kits require compact, courier-friendly dimensions. Cell therapy logistics providers in specialized networks absorb premium positioning for cryogenic dewar-style containers.
- Large (51-150 liters):Hospital and clinic bulk shipments dominate this tier, though order consolidation is compressing utilization rates.
- Extra Large (above 150 liters):Pallet-scale passive containers serve intercontinental air freight consolidation and pharmaceutical manufacturing site transfers.
Medium capacity absorbs the bulk of installed capacity; small capacity is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyurethane foam feedstock concentration in the US Gulf Coast and polyol production clusters in northwestern Europe anchor insulated bin manufacturing geography. Pharmaceutical distribution requirements and cold-chain infrastructure investments are reshaping regional demand patterns.
United States
FDA validation protocols and EPA refrigerant regulations under Section 608 are elevating specification intensity for pharmaceutical-grade containers. Rotational molding capacity concentrates in the Ohio River Valley and Texas Gulf Coast corridors. Bonar Plastics leverages regional foam chemistry partnerships to sustain supply security for standard cold-chain applications.
Germany
Bavarian biologics manufacturing clusters and centralized distribution hubs in Baden-Württemberg drive premium bin procurement for direct-to-patient channels. EU F-Gas Regulation phase-down mandates accelerate vacuum insulation panel adoption across pharmaceutical logistics corridors. Frankfurt and Munich anchor specialized courier networks serving temperature-sensitive cell therapies.
India
PLI scheme incentives for pharmaceutical manufacturing are generating first-mile insulated bin demand from Mumbai and Hyderabad production hubs. CDSCO cold-chain compliance requirements are tightening qualification standards for export-bound vaccine shipments. Cold Chain Technologies is expanding rental fleet presence to serve emerging logistics corridors.
Switzerland
Swissmedic regulations and specialized CAR-T therapy distribution requirements sustain premium positioning for cryogenic-grade containers. Basel and Zurich anchor pharmaceutical 3PL networks deploying IoT-integrated qualified container fleets. Pelican BioThermal anchors the high-performance segment with advanced thermal mass technologies for intercontinental shipments.
France
ANSM pharmaceutical transport guidelines and urban last-mile consolidation are concentrating medium-capacity bin demand in the Île-de-France corridor. ECHA chemical safety frameworks influence insulation material specifications for hazardous cargo applications. Lyon and Marseille serve as multimodal consolidation nodes for southern European distribution.
Insulated Bin Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart-sensor integration and rental fleet services. The vendor base stratifies across three performance tiers: validated pharmaceutical-grade specialists, standard cold-chain fabricators, and single-use disposables producers. Consolidation pressures concentrate among rotational molders facing feedstock volatility. Dominant competitive moves include strategic partnerships with pharmaceutical 3PLs and geographic expansion into Indian manufacturing corridors.
Among North American specialists, Bonar Plastics and Pelican BioThermal exemplify divergent positioning archetypes. Bonar Plastics represents the integrated rotational molder with captive foam chemistry capabilities. Pelican BioThermal occupies the premium-tier position through phase-change material specialization. Cold Chain Technologies anchors the asset-light rental fleet model serving courier networks. These three patterns illustrate how competitive strategy fragments across manufacturing integration, technology differentiation, and service model innovation vectors.
| Leading Market Players |
|---|
| Bonar Plastics |
| Pelican BioThermal |
| Sonoco ThermoSafe |
| Cold Chain Technologies |
| Csafe Global LLC |
| Cascades Inc. |
| Cryopak |
| Polarplas |
| DACO Corporation |
| Others |
Pricing and Supply Chain Analysis
Thermal engineer scarcity in the Ohio River Valley and southwestern Germany widens pricing-tier spreads, as labor-cost differentials between rotational molding centers and vacuum panel fabrication sites compound material-grade premiums.
Pricing Analysis
Warranty and validation-service bundling separates pharmaceutical-grade procurement from standard cold-chain transactions, with ISO 17025 qualification and embedded IoT logging commanding substantial premiums over unvalidated units. Pricing stratifies across certified pharmaceutical, standard cold-chain, and single-use economy tiers, with certification level and geographic delivery cost as primary differentiation drivers. Cost compression in the standard polyurethane segment is intensifying because isocyanate feedstock volatility squeezes rotational molder margins. Food distributors and agricultural exporters exhibit the highest price sensitivity, while CAR-T therapy couriers and biologics manufacturers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Dual-sourcing mandates from German pharmaceutical 3PLs and Swiss courier networks require qualification of multiple foam chemistry suppliers and rotational molding partners, constraining single-source dependencies. Manufacturing concentrates in the United States, Germany, and China, with polyurethane foam systems drawing from Gulf Coast petrochemical complexes and northwestern European polyol clusters. Isocyanate and specialty resin dependencies create vulnerability to commodity price swings and logistics chokepoints at Rotterdam and Hamburg. Distribution runs through qualified container fleet operators and direct manufacturer sales to pharmaceutical producers, with rental pool models expanding across European logistics corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The insulated bin market has become a vertical-integration race, with players pursuing captive polyurethane foam chemistry capabilities to secure supply and compress cost structures in the standard tier.
For Market Incumbents: Anticipate margin compression from Indian rental fleet entrants and phase-change material specialists by securing backward integration into polyol formulation and expanding validation laboratory capacity in Baden-Württemberg. Prioritize certification pre-qualification for EU F-Gas Regulation amendments to defend positioning in German pharmaceutical corridors.
For New Entrants and Emerging Players: Direct-to-patient pharmacy platforms offer the most penetrable route for smart-sensor-integrated small-capacity units, bypassing established hospital procurement gatekeepers. Target Swiss and German urban last-mile vaccine delivery networks with 11-50 liter validated designs, leveraging API interoperability as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Re-rating potential sits with vacuum insulation panel specialists given EU refrigerant phase-down mandates and cryogenic logistics expansion. Long-term viability hinges on qualification moats and pharmaceutical 3PL fleet integration depth. Monitor CDSCO enforcement tightening in India as the inflection signal for export-qualification demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Chemistry | Captive foam formulation secures supply and compresses input cost volatility for rotational molders. |
| IoT Sensor Platform Integration | Embedded temperature logging automates FDA documentation workflows for pharmaceutical 3PLs. |
| Vacuum Panel Manufacturing Scale-Up | EU F-Gas Regulation phase-down elevates demand for extended hold-time passive protection systems. |
| Indian Rental Fleet Expansion | PLI scheme pharmaceutical manufacturing growth generates first-mile qualified container demand from Mumbai hubs. |
| Cryogenic Dewar Qualification | CAR-T therapy distribution requirements open premium positioning in specialized Swiss and German courier networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with rotational molding plant managers, pharmaceutical cold-chain executives, logistics procurement leads, and thermal packaging R&D directors. FDA 483 observations, EMA qualification databases, EU F-Gas Regulation implementation reports, and insulated container import manifests provided validation benchmarks. Bottom-up unit economics and top-down industry sizing were triangulated across material-grade production estimates and end-use demand segmentation.
Data-stream reconciliation across shipment volumes, capacity utilization surveys, and pharmaceutical distribution spend patterns informed the analytical framework. Segmentation dimensions modeled include material type, application tier, bin capacity band, and regional regulatory cluster. CAGRs were derived from fitted growth curves against validated base-year estimates, with phase-change material adoption curves and F-Gas Regulation compliance timelines as industry-specific forecast inputs.
Inputs from German trade associations and Swiss pharmaceutical logistics consortia were available through the study window; gaps in Indian cold-chain infrastructure investment data introduce uncertainty bands for first-mile demand projections. Deviation in EU F-Gas Regulation amendment timing or CDSCO enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Global Industrial Wooden Crates Market
Industrial Packaging
Industrial Packaging Market
Industrial Packaging
Rigid IBC Market
Industrial Packaging
Transport Racks Market
Industrial Packaging
Corrugated Bulk Bins Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Global Dunnage Packaging Market
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Overpack Drum Market
Industrial Packaging
Industrial Filling Machine Market
Industrial Packaging
Dunnage Trays Market
Industrial Packaging
Corrugated Automotive Packaging Market
Industrial Packaging
MENA Industrial Packaging Market
Industrial Packaging
Industrial Plastic Bags Market
Industrial Packaging
Dunnage Air Bags Market