
 North America Conveyor Belt Market | 2026-2036
North America Conveyor Belt Market Size, Share, and Industry Trends Forecast 2026-2036
North America Conveyor Belt Market Intelligence
E-commerce fulfillment operators are redrawing demand patterns across the North America conveyor belt landscape. Fenner Dunlop Americas dominates underground mining applications with specialized fire-resistant constructions. Intralox L.L.C. differentiates through modular plastic belting systems that reduce sanitation downtime in protein processing. Continental AG leverages its integrated rubber compounding operations to control input costs across heavy-duty product lines.
A conveyor belt is a continuous moving band of fabric, rubber, or metal that transports materials between fixed points, typically specified by tensile strength measured in pounds per inch width, operating temperature range, and coefficient of friction. Flat belts occupy the largest installed base across manufacturing and distribution facilities, though modular belts command premium positioning in food processing where USDA and FDA sanitation protocols require frequent washdown compatibility. Steel-cord constructions sustain extreme tension loads in Canadian oil sands and Appalachian coal operations where nylon or polyester carcasses would fail.
OSHA workplace safety mandates, MSHA fire-resistance certifications for underground applications, and FDA food-contact material regulations collectively determine product eligibility and replacement schedules across US and Canadian installations. The EPA's evolving emissions frameworks for mining and bulk handling operations indirectly shape belt specification trends through equipment upgrade cycles. Stakeholders must weigh MSHA compliance timelines against modular belt migration paths when refreshing aging underground infrastructure.
Market Dynamics
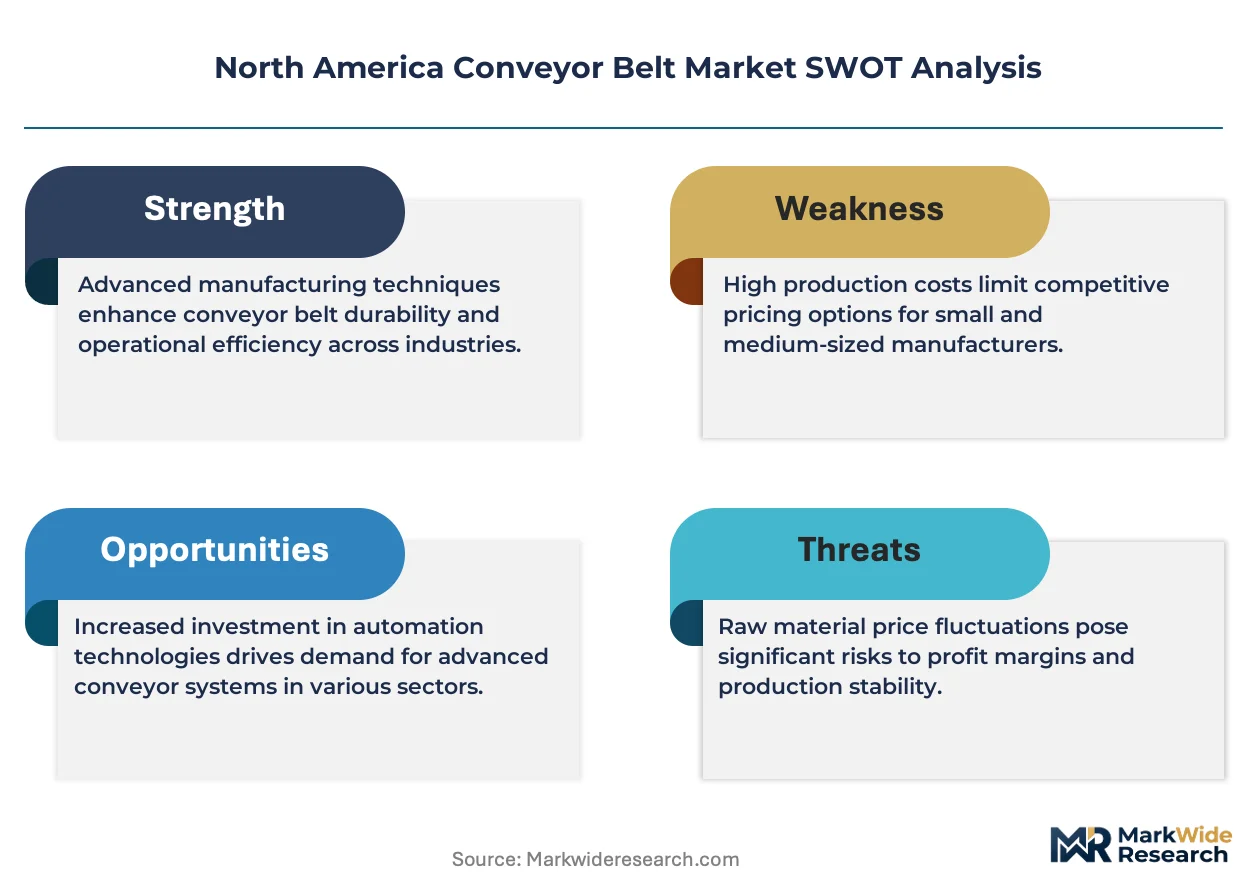
E-commerce fulfillment velocity requirements are compressing replacement cycles across distribution networks, while MSHA fire-resistance mandates force specification upgrades in underground mining corridors. These dual pressures are restructuring procurement priorities between speed-to-deploy and compliance durability.
Growth Catalysts
- MSHA Fire-Resistance Mandates:Underground coal and metal mining operations in Appalachia must upgrade to flame-resistant belt constructions, accelerating replacement demand in legacy installations.
- Protein Processing Sanitation Protocols:USDA washdown requirements in poultry and beef facilities are driving modular plastic belt conversions that reduce sanitation downtime.
- Southeast Automotive Cluster Expansion:Tennessee and Alabama assembly plants are adding conveyor capacity for electric vehicle battery module handling.
Market Restraints
- Natural Rubber Price Volatility:Thai and Indonesian supply disruptions transmit directly to compound costs for heavy-duty fabric belt producers.
- Steel-Cord Supply Concentration:Appalachian and Canadian oil sands operators depend on limited domestic sources for high-tensile cord constructions.
- Technical Limitation in Extreme Cold:Standard elastomer compounds stiffen below minus forty degrees Celsius, restricting belt performance in northern Canadian oil sands and Alaska mining.
Strategic Opportunities
- Mexico Nearshoring Corridor:Automotive and appliance manufacturers in Querétaro and Nuevo León are expanding greenfield facilities requiring complete conveyor infrastructure.
- IRA Clean Energy Manufacturing Credits:Solar panel and battery production incentives are stimulating conveyor demand in new domestic gigafactory locations.
- RFID-Enabled Predictive Maintenance:Embedding sensors in belt carcasses allows condition-based replacement scheduling, creating aftermarket service attach opportunities.
Industry Challenges
- MSHA Certification Timeline Compression:Underground operators face eighteen-month approval queues for new fire-resistant belt constructions, delaying infrastructure refresh schedules.
- Legacy System Integration Friction:Food processors with decades-old fabric belt installations encounter mechanical incompatibility when retrofitting modular plastic alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Conveyor Belt Market |
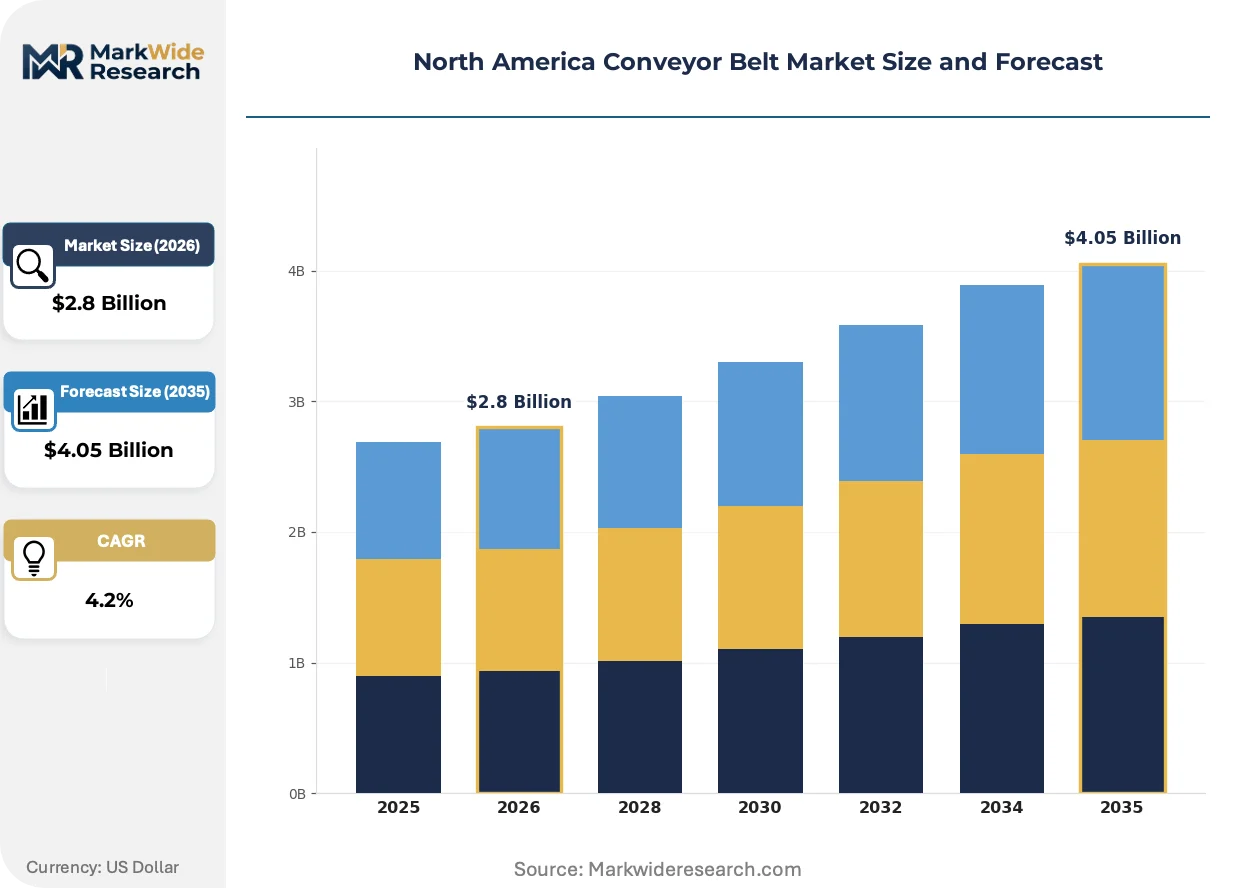
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.05 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Belts, Modular Belts, Cleated Belts, Timing Belts Material: Polyester, Nylon, Rubber, Steel End User: Manufacturing, Mining, Food Processing, Retail Installation: On-Site, Factory-Based, Field Installation, Pre-Installed |
| Companies Covered | Continental AG, Fenner Dunlop Americas, Bridgestone Corporation, Intralox L.L.C., Habasit America, Dorner Mfg. Corp., Hytrol Conveyor Company, Beltservice Corporation, Ashworth Bros. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Conveyor Belt Market Strategic Shifts & Innovations
Material science advances and regulatory tightening are converging to reshape belt specification patterns. Three developments are altering competitive positioning and procurement behavior across the North American installed base.
Modular thermoplastic belting is decomposing the traditional flat belt dominance in food processing and parcel handling. Major poultry processors in Georgia and Arkansas are converting entire washdown lines within twelve-month windows. This shift compresses replacement revenue into shorter cycles while elevating upfront equipment spend.
OSHA silica exposure limits are forcing mining operators to enclose bulk handling systems, which elevates specification requirements for heat-resistant and abrasion-rated constructions. Underground coal applications in West Virginia and Kentucky are retrofitting sealed transfer points that demand compatible belt profiles. Equipment OEMs are responding with integrated system packages that bundle belting with enclosure hardware.
Buyer consolidation among third-party logistics providers is compressing supplier negotiation cycles and unbundling after-sales service contracts. Large fulfillment operators in California and Texas are demanding direct manufacturer relationships that bypass traditional distribution channels. This channel disintermediation pressures regional belting distributors to develop installation and maintenance capabilities or exit the market.
North America Conveyor Belt Market Segmentation
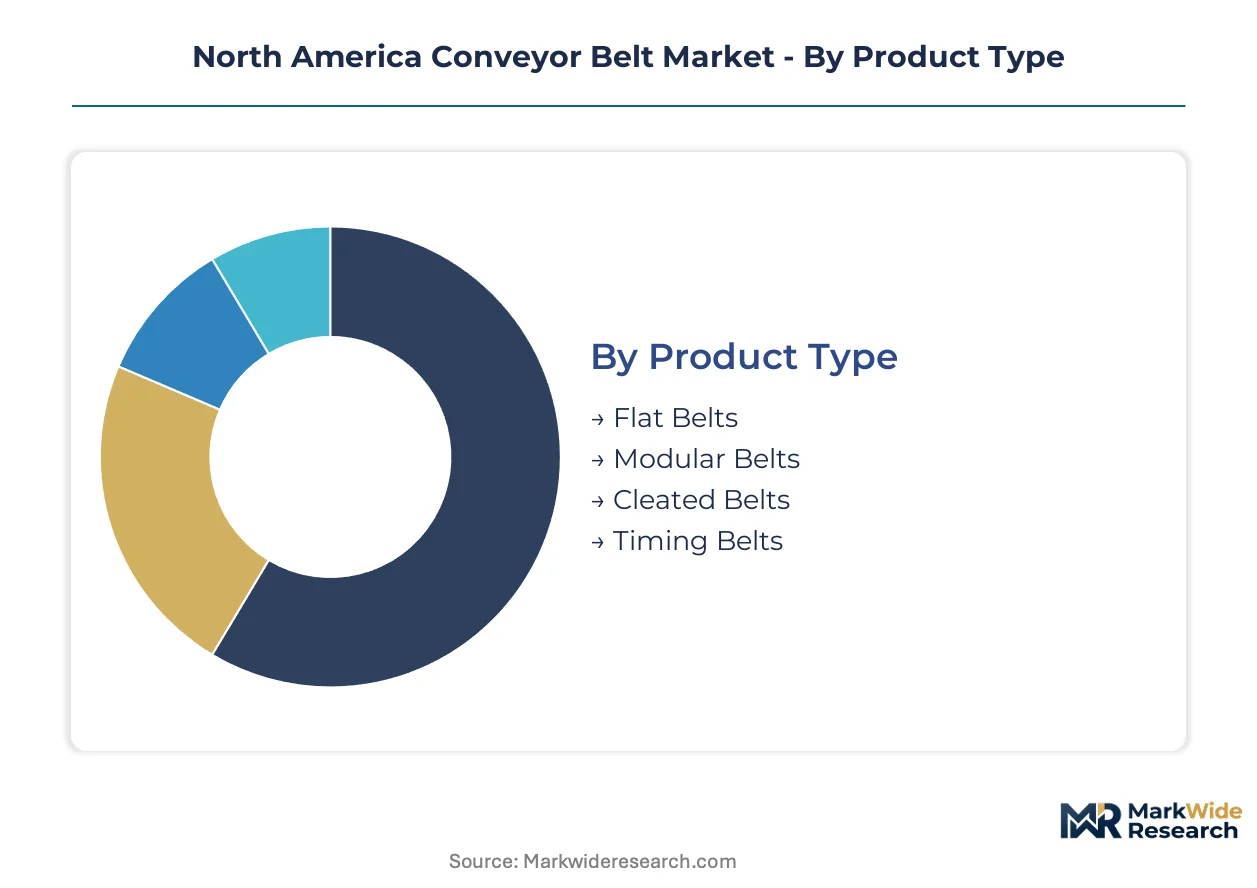
Conveyor belt specification patterns diverge sharply across product construction, material chemistry, and deployment context. Procurement behavior clusters around compliance mandates in underground mining, sanitation protocols in protein processing, and velocity requirements in e-commerce fulfillment.
Product Type:
Margin pools concentrate in specialized constructions that command specification premiums over commodity flat belt alternatives.
- Flat Belts:Woven fabric carcasses bonded to rubber or PVC covers dominate manufacturing and distribution footprints. Tennessee automotive assembly plants and California fulfillment centers drive replacement volume through high-duty cycle operations.
- Modular Belts:Interlocking thermoplastic segments enable rapid section replacement and pressure-wash compatibility. Georgia and Arkansas poultry processors are converting entire production lines to reduce sanitation downtime and comply with USDA washdown mandates.
- Cleated Belts:Molded profiles prevent bulk material rollback on inclined conveying paths.
- Timing Belts:Positive-drive tooth profiles synchronize movement in precision assembly and packaging machinery.
Flat belts hold installed capacity. Modular belts are rotating up the share rankings.
Material:
Input cost volatility and performance requirements segment procurement behavior across carcass and cover chemistry choices.
- Polyester:Dimensionally stable synthetic fabric resists moisture absorption and stretching under load. General manufacturing applications in the US Midwest favor polyester carcasses for their predictable tension maintenance and moderate cost position.
- Nylon:High-tenacity polyamide fibers deliver superior impact resistance and troughing flexibility. Underground mining corridors in West Virginia and Kentucky specify nylon carcasses for their ability to absorb shock at transfer points.
- Rubber:Natural and synthetic elastomer compounds form covers and solid belts for abrasion-heavy environments.
- Steel:High-tensile cord constructions sustain extreme tension loads in Canadian oil sands and Appalachian coal operations where fabric carcasses would fail.
Rubber maintains volume leadership. Steel is climbing the fastest as operators push deeper into high-tension extraction zones.
End User:
Customer concentration and replacement cycle velocity determine contract structure and service attach rates.
- Manufacturing:Assembly line integration demands predictable belt life and rapid changeout protocols. Michigan and Ohio automotive suppliers specify heavy-duty constructions with documented mean-time-between-failure metrics.
- Mining:MSHA fire-resistance certifications and abrasion ratings dominate underground procurement in Appalachia. Eighteen-month approval queues for new belt constructions compress operator flexibility and accelerate pre-buying behavior.
- Food Processing:USDA and FDA material contact regulations drive specification hygiene. Modular plastic conversions are decomposing traditional fabric belt dominance in washdown environments.
- Retail:E-commerce fulfillment velocity requirements compress replacement cycles across distribution networks. Third-party logistics consolidation is unbundling after-sales service contracts and forcing direct manufacturer relationships.
Manufacturing anchors installed base. Food processing is expanding most quickly through sanitation-driven retrofits.
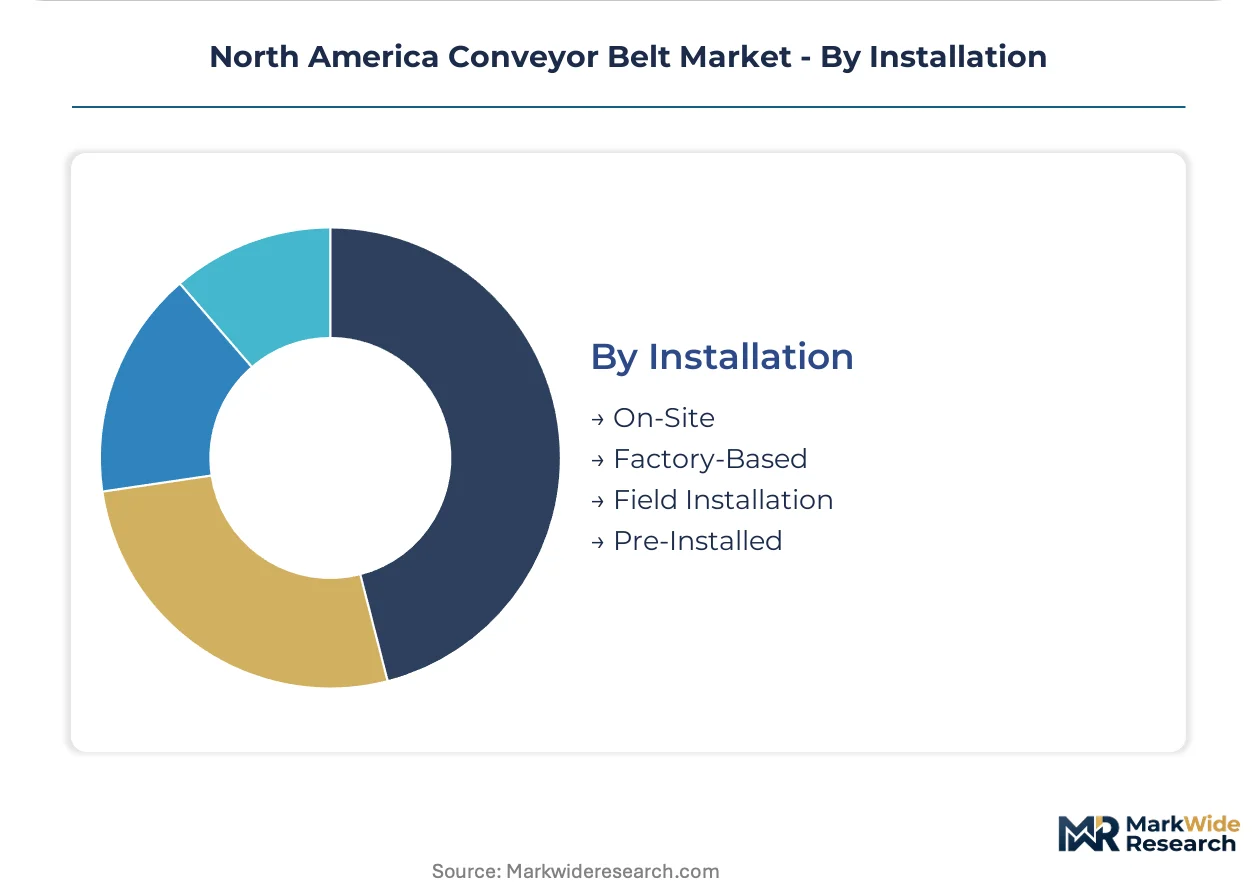
Installation:
Deployment method shapes total cost of ownership calculations and supplier capability requirements.
- On-Site:Vulcanized splicing and mechanical fastening performed at operating location minimize transport logistics. Large mining and bulk handling operations in the US Southwest favor on-site installation for continuous production schedules.
- Factory-Based:Precision splicing under controlled conditions ensures optimal joint integrity. High-specification steel-cord and specialty constructions ship factory-spliced to Canadian oil sands operators.
- Field Installation:Mobile crews perform emergency replacements and scheduled maintenance turnarounds.
- Pre-Installed:Complete conveyor modules arrive with belts tensioned and tracked at OEM facilities.
On-site methods retain volume share. Pre-installed systems are gaining share fastest through modular equipment packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mississippi River inland waterway system and the Port of Houston's bulk material terminals anchor North American conveyor belt demand through agricultural export corridors and petrochemical feedstock handling.
United States
Appalachian coal operations and Tennessee automotive assembly plants drive specification diversity. MSHA fire-resistance mandates compel underground mining operators in West Virginia and Kentucky to upgrade flame-resistant belt constructions. Georgia and Arkansas poultry processors are converting entire washdown lines to modular plastic systems.
Canada
Alberta oil sands extraction and Saskatchewan potash mining sustain demand for extreme-tension steel-cord constructions. Health Canada and provincial occupational regulators enforce cold-climate performance standards that restrict standard elastomer compounds below minus forty degrees Celsius. Edmonton and Fort McMurray serve as procurement hubs for northern mining infrastructure.
Mexico
Querétaro and Nuevo León automotive clusters are expanding greenfield assembly facilities requiring complete conveyor infrastructure for electric vehicle component handling. Mexican federal labor safety regulations align with US OSHA frameworks for cross-border manufacturing integration. Mexico City Metro area distribution centers are deploying high-velocity sortation systems for North American e-commerce fulfillment.
North America Conveyor Belt Market Key Industry Players
Concentration sits with integrated rubber compounders and specialized belting fabricators who control input costs and certification pathways. The vendor base spans three tiers: multinational industrial conglomerates with captive compounding operations, mid-scale regional specialists focused on MSHA-certified mining applications, and modular plastic innovators serving food processing washdown environments. Dominant competitive moves include backward integration into rubber compounding to offset natural price volatility, and geographic expansion into Mexico's nearshoring corridor through local fabrication partnerships.
Among Germany-based industrial conglomerates, Continental AG exemplifies the integrated compounder archetype through captive rubber operations. Fenner Dunlop Americas and Intralox L.L.C. represent contrasting specialization vectors—underground mining fire-resistance expertise versus modular thermoplastic innovation for protein processing sanitation protocols. These three anchors demonstrate how competitive positioning diverges across compliance-driven mining, hygiene-critical food processing, and velocity-optimized distribution end uses.
| Leading Market Players |
|---|
| Continental AG |
| Fenner Dunlop Americas |
| Bridgestone Corporation |
| Intralox L.L.C. |
| Habasit America |
| Dorner Mfg. Corp. |
| Hytrol Conveyor Company |
| Beltservice Corporation |
| Ashworth Bros. Inc. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at integrated rubber compounding facilities in the US Southeast and Germany anchors price floors across heavy-duty belt constructions, concentrating supply leverage among compounders with captive polymer operations while squeezing margin at distributors dependent on spot resin purchases.
Pricing Analysis
Volume-discount tiering structures separate MSHA-certified mining constructions from commodity flat belts used in distribution centers. Price differentiation hinges on fire-resistance certification grade and after-sales service bundling. Cost compression in standard fabric belts is intensifying because third-party logistics providers are consolidating procurement into direct manufacturer relationships. E-commerce fulfillment operators show highest price sensitivity, while Appalachian mining operations prioritize compliance durability over unit cost.
Supply Chain Analysis
Inbound logistics costs from Thai and Indonesian natural rubber ports through Los Angeles and Houston container terminals transmit directly to compound cost volatility. Raw material sourcing draws from Southeast Asian latex plantations, domestic steel-cord producers in Ohio and Pennsylvania, and German synthetic polymer operations. Single-source vulnerability concentrates in high-tensile steel-cord constructions for Canadian oil sands. Distribution runs through regional belting distributors with installation capabilities and direct OEM relationships to large mining and automotive accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with modular plastic belt conversions and Mexico nearshoring corridors, as sanitation-driven retrofits and greenfield automotive expansion create supplier niches outside incumbent mining and heavy-industrial strongholds.
For Market Incumbents: Shield MSHA-certified product lines through backward integration into rubber compounding and captive steel-cord supply. Capacity addition in Querétaro and Nuevo León secures Mexico automotive corridor positioning against Asian import competition. Certification investment in RFID-enabled predictive maintenance creates aftermarket service attach opportunities that resist price-only procurement. For New Entrants and Emerging Players: MSHA certification fast-track capabilities open underground mining retrofit windows currently constrained by eighteen-month approval queues. White-space targets include USDA-compliant modular thermoplastic systems for Georgia and Arkansas poultry processors, and pre-installed conveyor modules for IRA-stimulated battery gigafactories. Go-to-market through direct relationships with consolidating third-party logistics providers bypasses entrenched distribution channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular plastic innovators with sanitation protocol expertise over legacy fabric belt manufacturers facing replacement compression. Long-term viability hinges on regulatory compliance capabilities and geographic proximity to e-commerce fulfillment clusters. Acquisition target archetype: regional specialists with MSHA fire-resistance certifications and installation service infrastructure. Signal to watch: channel disintermediation velocity as large fulfillment operators bypass distributors for direct manufacturer contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Captive polymer operations insulate Continental AG from Thai supply disruption volatility. |
| MSHA Certification Fast-Track Investment | Eighteen-month approval queues create first-mover advantage for compliant underground constructions. |
| Mexico Manufacturing Footprint Expansion | Querétaro and Nuevo León greenfield facilities capture automotive nearshoring conveyor demand. |
| RFID-Enabled Predictive Maintenance Launch | Embedded belt sensors create aftermarket service revenue from condition-based replacement scheduling. |
| Modular Plastic Product Line Conversion | USDA washdown compatibility captures Georgia and Arkansas poultry processor retrofit cycles. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with plant engineers at Tennessee automotive assembly facilities, MSHA compliance officers in West Virginia mining corridors, and procurement leads at California third-party logistics providers; and secondary validation through MSHA certification databases, USGS mineral commodity summaries, and SEC filings from integrated rubber compounders. Bottom-up volume triangulation across product construction, material chemistry, and end-use deployment was cross-checked against top-down value estimates derived from replacement cycle velocity and specification premium analysis.
Across the projection horizon, the analytical framework modeled demand through segmentation dimensions including belt construction type, carcass material chemistry, installation method, and regional regulatory cluster. CAGRs were derived from replacement cycle compression rates in e-commerce fulfillment and MSHA-mandated upgrade schedules in underground mining. Industry-specific forecast inputs incorporated natural rubber futures volatility patterns and steel-cord domestic production capacity utilization.
Underlying assumptions cover MSHA certification timeline stability and Mexican automotive investment continuity, with deviation risk concentrated in Thai supply disruption severity and IRA credit extension decisions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Debris Loaders Market
Material Handling Equipment
Scissor Lift Market
Material Handling Equipment
Chute Liners Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Overhead Hoist Transport (OHT) Market
Material Handling Equipment
Compaction Machines Market
Material Handling Equipment
Rolling Mill Machine Market
Material Handling Equipment
Loaded Container Handler Market
Material Handling Equipment
Roll Handling Machine Market
Material Handling Equipment
Loader Crane Market
Material Handling Equipment
North America Forklift Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Global Elevator Market