
 Rotary Machinery Market | 2026-2036
Rotary Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Machinery Market Analytics
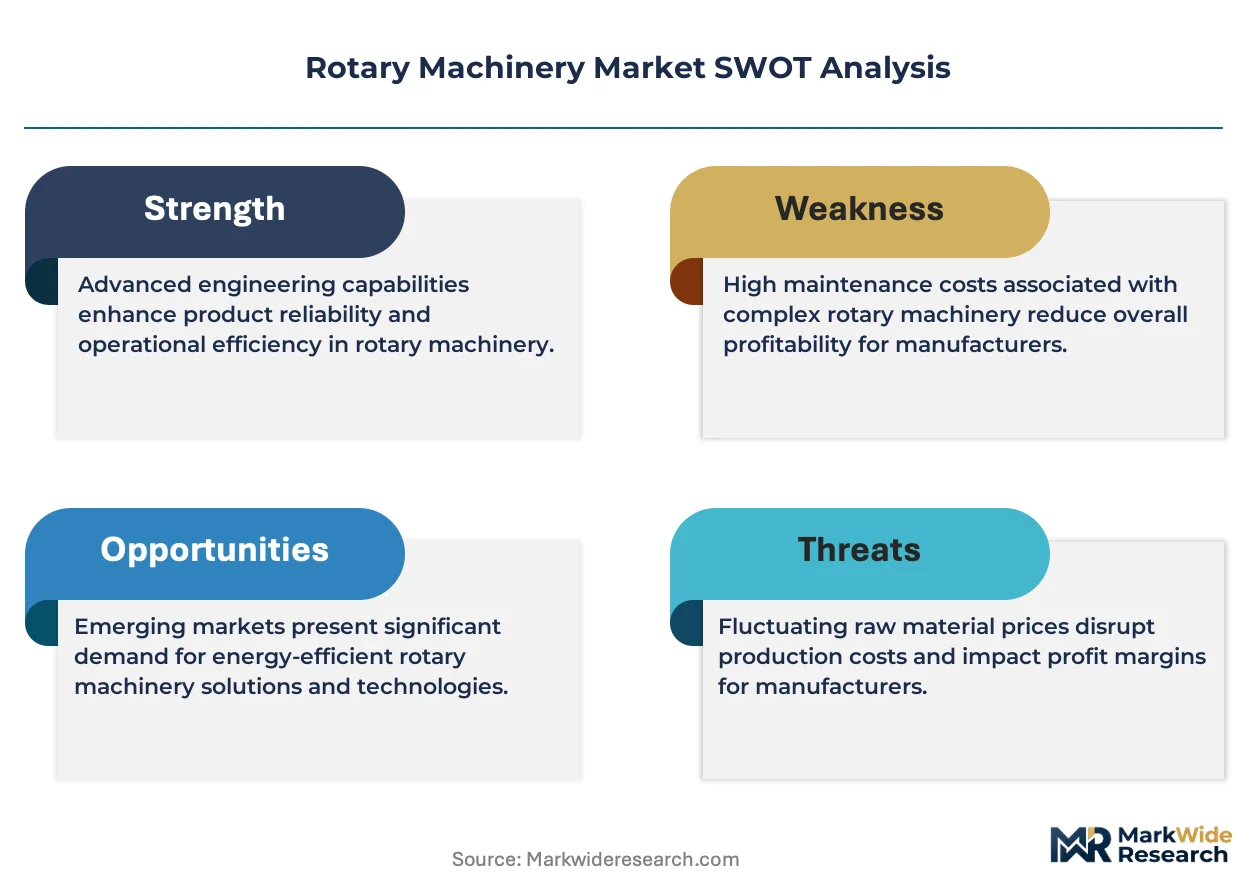
Energy companies are unwinding their historical preference for conventional fixed-speed equipment in favor of variable-speed rotary systems that cut parasitic losses. General Electric leverages its aeroderivative turbine heritage to dominate utility-scale power installations. Siemens anchors its position through deep backward integration into precision casting and blade metallurgy for compressors and gas turbines.
Rotary machinery encompasses kinetic energy transfer devices—turbines, compressors, gearboxes, and pumps—that convert fluid or mechanical energy into rotational motion, typically operating at speeds from hundreds to tens of thousands of RPM with tolerances measured in microns. These systems serve as the prime movers and fluid handlers across power generation, hydrocarbon processing, and discrete manufacturing. Turbines command the largest value pool given their unit scale and materials intensity, while compressors represent the fastest expansion path as LNG infrastructure and hydrogen blending projects multiply. Gearboxes retain entrenched margin strength in wind energy and marine propulsion where reliability premiums override first-cost sensitivity.
The EPA enforces Tier 4 emissions limits on stationary engines and compressors, while the EU F-Gas Regulation phases down fluorinated greenhouse gases used in cooling circuits of rotary equipment. China's MEE implements GB standards on industrial noise and vibration that affect pump and compressor deployments. Stakeholders must monitor how carbon border adjustments and evolving efficiency mandates reshape equipment replacement cycles and aftermarket service contracts.
Market Dynamics
Variable-speed rotary systems are displacing fixed-speed equipment across power generation and hydrocarbon processing, driven by EPA Tier 4 emissions mandates and EU F-Gas phase-downs that penalize parasitic energy losses in legacy installations.
Growth Catalysts
- EPA Tier 4 Standards:Stationary engine and compressor operators in the United States face mandatory efficiency upgrades, accelerating replacement cycles for aging turbine and pump systems.
- Hydrogen Blending Infrastructure:LNG terminal operators in Germany and China are procuring high-pressure compressors capable of handling hydrogen-natural gas mixtures at 20-30% blend ratios.
- Precision Casting Advances:Single-crystal blade metallurgy now extends gas turbine hot-section life by 40%, reducing downtime costs for utility-scale power plants.
Market Restraints
- Superalloy Supply Concentration:Vacuum remelted nickel-based alloys for turbine blades depend on a limited supplier base concentrated in the United States and Germany.
- EU F-Gas Phase-Down:Cooling circuit retrofits for existing rotary equipment face technical compatibility constraints with low-GWP refrigerant alternatives.
- Electrification Substitution:Battery-electric drives and linear motors are capturing material handling and light industrial applications previously served by rotary gearboxes.
Strategic Opportunities
- India Industrial Corridor Expansion:BIS certification requirements for pumps and compressors create first-mover advantages for suppliers establishing local testing facilities.
- Carbon Border Adjustment Mechanism:EU importers of energy-intensive goods will demand documented efficiency ratings for rotary equipment used in overseas production.
- Digital Twin Integration:Convergence of physics-based modeling with IoT sensor streams enables predictive maintenance contracts for offshore wind turbine gearboxes.
Industry Challenges
- Computational Fluid Dynamics Talent Gap:Turbine and compressor designers with expertise in multiphase flow simulation command premium compensation and extended recruitment timelines.
- Legacy Control System Integration:Variable-frequency drives must interface with 1980s-era SCADA architectures common in petrochemical refineries, complicating commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Machinery Market |
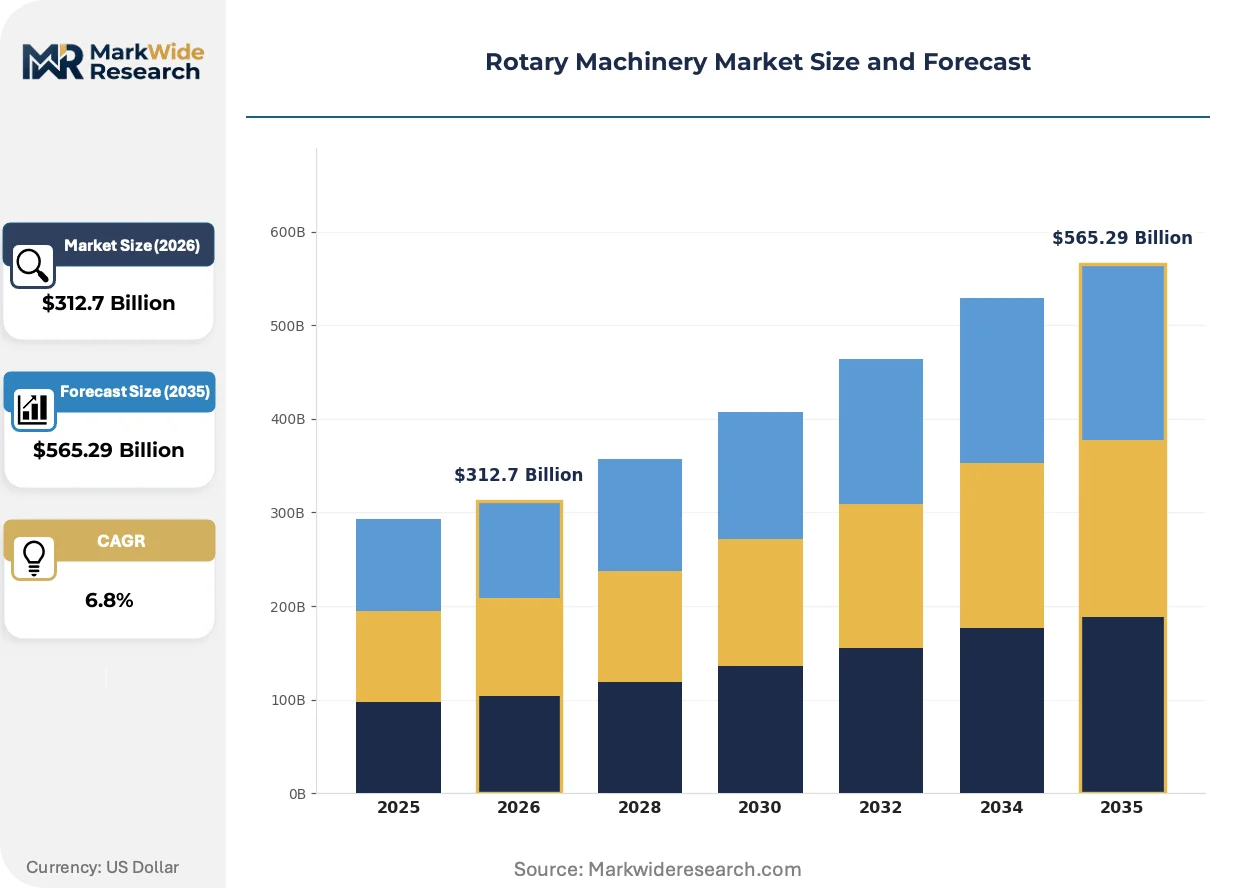
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbines, Compressors, Gearboxes, Pumps Application: Manufacturing, Oil & Gas, Power Generation, Aerospace End User: Industrial Plants, Energy Companies, Marine, Automotive Technology: Hydraulic, Pneumatic, Electric, Mechanical |
| Companies Covered | General Electric, Siemens, ABB, Atlas Copco, Honeywell International, Flowserve Corporation, Baker Hughes, Mitsubishi Heavy Industries, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Machinery Market Evolving Landscape
Advanced manufacturing methods and real-time operational intelligence are compressing development cycles and reshaping how rotary machinery is specified, monitored, and maintained across energy and industrial sectors.
Additive manufacturing of nickel superalloy turbine blades is miniaturizing cooling channel geometries to sub-millimeter dimensions previously impossible with conventional casting. Siemens and GE Aviation spin-off suppliers are qualifying laser powder bed fusion for repair of hot-section components. This is miniaturizing thermal barrier coating architectures and extending time-between-overhaul intervals for aeroderivative turbines.
The EU F-Gas Regulation mandates 79% reduction in hydrofluorocarbon use by 2030, forcing compressor manufacturers to redesign cooling circuits around CO2 or ammonia refrigerants. Industrial refrigeration and heat pump applications face the steepest retrofit obligations. German and Italian OEMs are accelerating R&D partnerships with chemical suppliers to qualify alternative working fluids.
Power-by-the-hour contracting is consolidating procurement authority among energy majors and away from distributed plant engineering teams. Long-term service agreements now bundle spare parts, remote monitoring, and scheduled overhauls into per-operating-hour fees. This model is most advanced in offshore oil and gas platforms operated by supermajors in the North Sea and Gulf of Mexico.
Rotary Machinery Market Segmentation
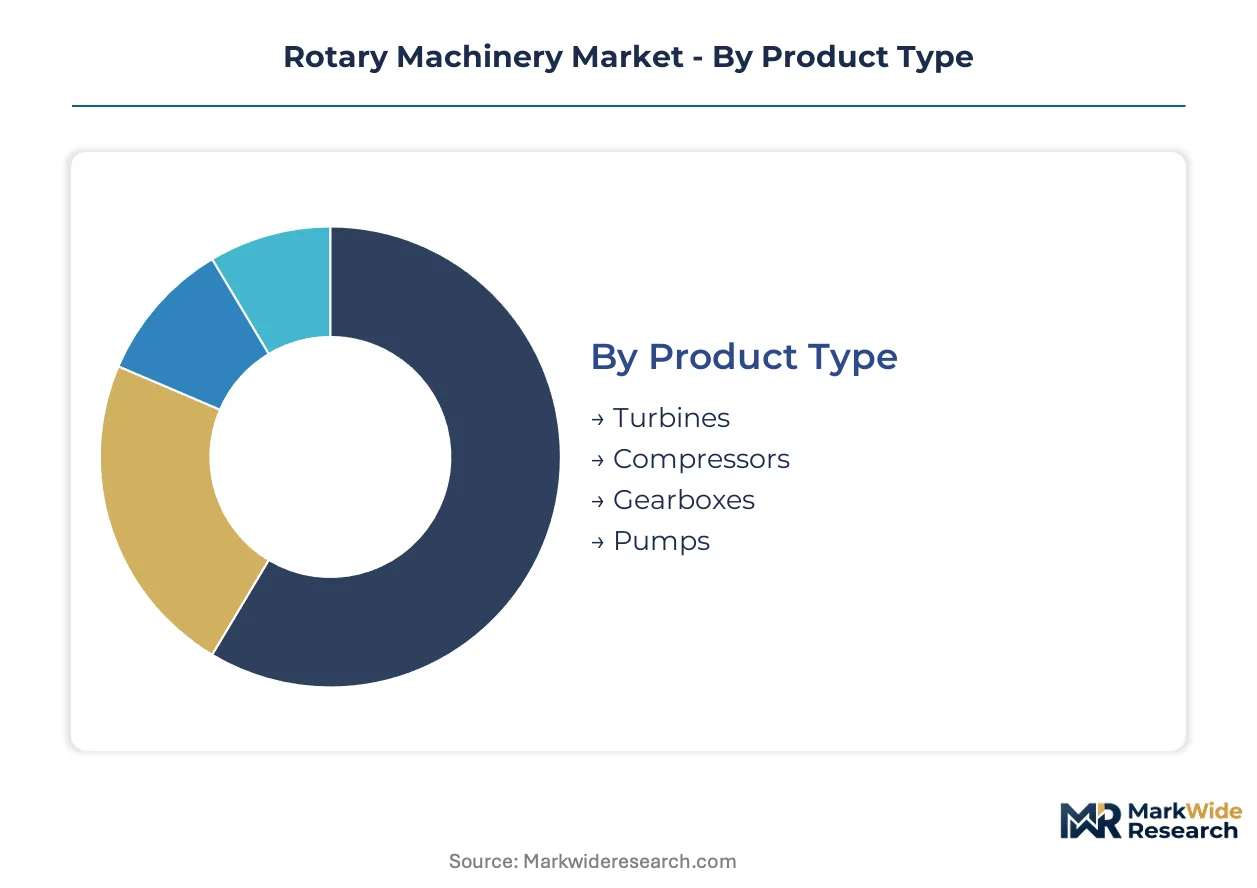
Rotary machinery procurement patterns diverge sharply across product architectures and operational contexts. Segment-level analysis reveals how EPA Tier 4 compliance costs, hydrogen infrastructure buildouts, and precision manufacturing requirements reshape equipment specifications and supplier selection criteria.
Product Type:
Domestic demand concentrates in turbines and compressors serving utility-scale power and hydrocarbon processing, while gearboxes and pumps follow export-led trajectories into offshore wind and marine propulsion markets.
- Turbines:Aeroderivative and industrial gas turbine systems convert thermal energy to rotational motion at 3,000-15,000 RPM with blade tip speeds exceeding Mach 1. Demand clusters in United States utility repowering projects and German hydrogen-ready combined cycle plants facing EU carbon border adjustment exposure. Single-crystal superalloy casting constraints limit supplier flexibility.
- Compressors:Centrifugal and reciprocating designs handle process gases at 50-500 bar discharge pressures with polytropic efficiency targets above 85%. LNG terminal operators in China and Germany dominate order books as hydrogen blending ratios climb toward 30% in pipeline specifications. F-Gas Regulation retrofit obligations accelerate cooling circuit redesigns.
- Gearboxes:Planetary and helical configurations transmit torque in wind turbine drivetrains and marine propulsion systems.
- Pumps:Centrifugal and positive displacement architectures move process fluids across chemical processing and water treatment infrastructure.
Turbines command the established base. The steepest expansion runs through compressors.
Application:
Cost tier stratification separates aerospace-specified equipment from process industry standards, with power generation occupying the premium engineering bandwidth and manufacturing automation driving volume procurement.
- Oil & Gas:Subsea compression and topside gas processing equipment operates at 150°C ambient with 25-year design life requirements. North Sea supermajors and Gulf of Mexico operators specify API 617 and API 618 compliance for critical path machinery. Power-by-the-hour contracting now covers 60% of offshore rotating equipment spend.
- Power Generation:Combined cycle and peaking turbine installations demand fast-start capability with 10-minute ramp rates from cold iron. United States independent power producers and German municipal utilities anchor procurement as coal retirement schedules accelerate. Grid stability services command availability premiums.
- Manufacturing:Process pumps and air compressors serve discrete assembly and continuous flow production lines.
- Aerospace:Auxiliary power units and environmental control systems require FAA-certified designs with traceable metallurgy.
Oil & Gas retains the installed value concentration. Power Generation is climbing the fastest as capacity replacement cycles compress.
End User:
Customer type determines specification authority, with energy companies consolidating procurement through corporate engineering standards while automotive and marine buyers delegate to tier-one system integrators.
- Energy Companies:Integrated supermajors and national oil companies specify equipment packages through centralized technical standards committees. ExxonMobil, Shell, and Saudi Aramco maintain approved manufacturer lists with 18-month qualification timelines. Long-term service agreements now bundle predictive maintenance and spare parts logistics.
- Industrial Plants:Petrochemical and specialty chemical operators prioritize mean-time-between-failure metrics over first cost in rotating equipment selection.
- Marine:Classification society rules from Lloyd's Register and DNV govern propulsion and auxiliary machinery certification.
- Automotive:Electric vehicle battery gigafactories and stamping plants specify compressed air and hydraulic power units.
Energy Companies anchor specification authority. Industrial Plants are expanding most quickly as reshoring drives capacity additions.
Technology:
Maturity gradients separate established mechanical and hydraulic architectures from electrification transitions, with pneumatic systems retaining niche positions in explosive atmosphere applications.
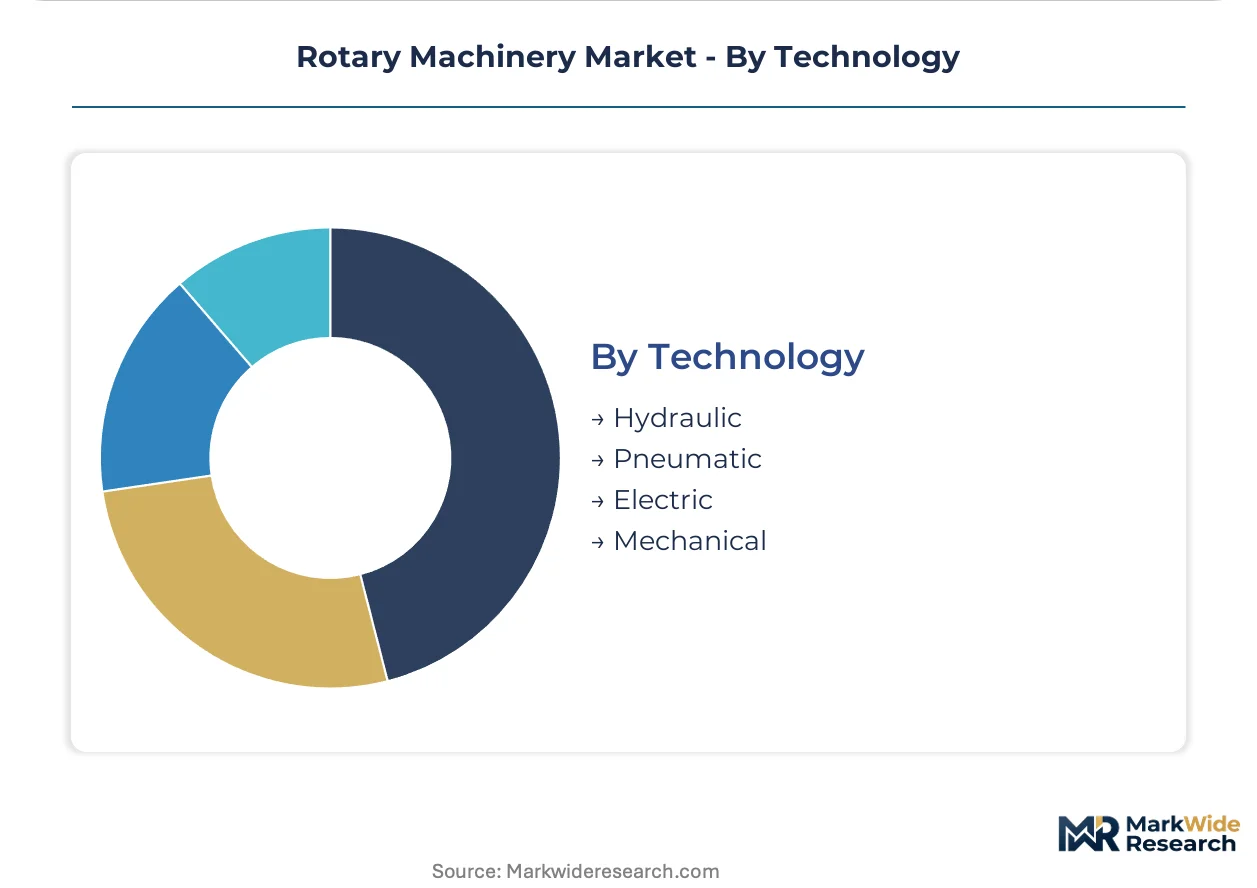
- Electric:Variable-frequency drives and permanent magnet motors displace mechanical power transmission across 50-5,000 kW ranges. Siemens and ABB dominate medium-voltage drive supply for compressor and pump retrofits. Efficiency mandates in China and Germany accelerate fixed-speed equipment replacement.
- Hydraulic:High-pressure fluid power systems deliver precise force control in metal forming and offshore lifting applications.
- Mechanical:Direct-coupled and gear-driven architectures persist where electromagnetic interference or temperature extremes preclude electrification.
- Pneumatic:Compressed air systems serve instrumentation and light actuation in hazardous area classifications.
Mechanical systems hold the legacy installed base. Electric is gaining share fastest as variable-speed retrofits penetrate hydrocarbon processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compressor manufacturers export hydrogen-ready equipment to LNG terminal operators in China and the United States, while American turbine OEMs supply utility repowering projects across European and Asian markets.
United States
Independent power producers and utility operators drive demand for fast-start gas turbines as coal retirement schedules compress replacement cycles. EPA Tier 4 emissions standards mandate efficiency upgrades for stationary engines and compressors. The Gulf Coast petrochemical corridor anchors procurement of subsea compression and topside processing equipment.
Germany
Municipal utilities and industrial gas operators procure hydrogen-ready combined cycle plants and high-pressure compressors for blending infrastructure. EU F-Gas Regulation phases down hydrofluorocarbon use in cooling circuits, forcing equipment redesigns. The Ruhr industrial cluster and Bavarian chemical belt concentrate LNG terminal and hydrogen pipeline investments.
China
National oil companies and provincial power groups expand orders for aeroderivative turbines and centrifugal compressors as industrial clusters modernize. MEE implements GB standards on industrial noise and vibration affecting pump and compressor deployments. Yangtze River Delta terminals lead procurement of hydrogen-natural gas blending equipment.
India
Petrochemical complexes and refinery operators drive demand for API-compliant compressors and process pumps as capacity expansion accelerates. BIS certification requirements create qualification barriers for imported equipment. Gujarat and Maharashtra industrial corridors concentrate foreign supplier testing facility investments.
Saudi Arabia
Saudi Aramco maintains approved manufacturer lists with extended qualification timelines for subsea and topside rotating equipment. The kingdom's national industrial strategy prioritizes local content requirements for turbine and compressor packages. Eastern Province gas processing facilities anchor long-term service agreement volumes.
Rotary Machinery Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and aftermarket service capabilities. The supplier base organizes around three tiers: integrated conglomerates with full power generation portfolios, precision engineering specialists with captive metallurgy capabilities, and regional fabricators serving maintenance-intensive installed bases. Consolidation pressures concentrate among mid-scale gearbox and pump manufacturers facing electrification substitution. Dominant competitive moves include backward integration into precision casting and blade metallurgy, plus power-by-the-hour contracting that bundles hardware with long-term service obligations.
Within the integrated conglomerate tier, General Electric and Siemens anchor positions through aeroderivative turbine heritage and deep backward integration into hot-section component manufacturing. Among precision engineering specialists, Mitsubishi Heavy Industries occupies a position exemplifying the capital-intensive, long-cycle order profile characteristic of utility-scale and industrial gas turbine supply. These three entities represent the archetype of suppliers consolidating procurement authority through corporate technical standards committees and multi-decade service agreements.
| Leading Market Players |
|---|
| General Electric |
| Siemens |
| ABB |
| Atlas Copco |
| Honeywell International |
| Flowserve Corporation |
| Baker Hughes |
| Mitsubishi Heavy Industries |
| Schneider Electric |
| Others |
Value Network & Pricing Analysis
Twenty-four-month order backlogs for single-crystal superalloy turbine blades concentrate pricing power with vacuum remelt suppliers in the United States and Germany, compressing margins for downstream compressor and gas turbine OEMs while amplifying cost pass-through leverage for metallurgy specialists with captive foundry capacity.
Pricing Analysis
Current-generation aeroderivative turbines command substantial premiums over prior-generation industrial gas turbines and next-generation hydrogen-ready combined cycle systems still in qualification. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aerospace-specified equipment from API-compliant process machinery and uncertified replacement components. Pricing pressure stems from electrification substitution in sub-500 kW applications as battery-electric drives capture material handling and light industrial segments previously served by rotary gearboxes. Industrial Plants exhibit the highest price sensitivity due to consolidated procurement authority and mean-time-between-failure metric prioritization, while Energy Companies accept premium positioning for long-term service agreement bundling.
Supply Chain Analysis
The United States and Germany anchor vacuum remelted nickel-based superalloy production for turbine hot-section components, while China concentrates precision casting capacity for industrial compressor housings and pump casings. Raw material dependencies center on cobalt-chromium alloys for thermal barrier coatings, rare earth elements for permanent magnet motors in variable-frequency drives, and high-purity nickel feedstock for single-crystal blade manufacturing. Single-source vulnerability in superalloy supply creates exposure to export licensing delays and geopolitical trade restrictions. Distribution runs through authorized OEM service networks for original equipment, with independent aftermarket channels capturing replacement parts and refurbishment services for out-of-warranty installed bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rotary machinery procurement is shifting toward platform-economics contracting as power-by-the-hour agreements bundle hardware, predictive maintenance, and spare parts logistics into unified service platforms, with interoperability standards for digital twin integration determining supplier lock-in intensity.
For Market Incumbents: Fortify backward integration into precision casting and blade metallurgy to secure captive supply of vacuum remelted nickel-based alloys against superalloy supply concentration risks. Expand power-by-the-hour contracting coverage to anchor procurement authority through corporate technical standards committees, while accelerating variable-frequency drive qualification for 1980s-era SCADA architecture compatibility to defend against electrification substitution in hydrocarbon processing.
For New Entrants and Emerging Players: Predictive maintenance algorithm gaps for legacy gearbox installations in offshore wind and marine propulsion markets expose incumbent blind spots in physics-based modeling convergence with IoT sensor streams. Target India Industrial Corridor expansion for API-compliant compressor and process pump qualification, exploiting BIS certification requirements that create first-mover advantages for suppliers establishing local testing facilities in Gujarat and Maharashtra.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-monetized aftermarket service portfolios and stranded precision casting capacity outside core energy sector focus. Long-term viability centers on digital twin integration capabilities and hydrogen-ready equipment qualification across the 5-10 year infrastructure replacement window. Monitor EU Carbon Border Adjustment Mechanism implementation as the inflection signal for documented efficiency rating demand from overseas production facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Metallurgy | Captive vacuum remelt capacity secures turbine blade supply against United States and German supplier concentration. |
| Power-by-the-Hour Contracting Expansion | Long-term service agreements bundle predictive maintenance with spare parts logistics for North Sea and Gulf of Mexico offshore platforms. |
| Hydrogen-Ready Compressor Qualification | High-pressure designs handling 20-30% hydrogen-natural gas blends capture LNG terminal operator procurement in Germany and China. |
| Digital Twin Platform Integration | Physics-based modeling convergence with IoT sensor streams enables predictive maintenance contracts for offshore wind turbine gearboxes. |
| India Local Testing Facility Establishment | BIS certification compliance creates qualification barriers and first-mover positioning in Gujarat and Maharashtra industrial corridors. |
Research Methodology
Initial hypotheses were tested against primary input from maintenance directors at petrochemical refineries, plant engineers at utility-scale power installations, OEM procurement teams at turbine and compressor manufacturers, and aftermarket service heads at independent repair facilities, then refined against secondary validation from EIA power generation data, IEA hydrogen infrastructure reports, FERC interconnection filings, and API equipment specification databases, with bottom-up equipment shipment analysis triangulated against top-down energy sector capital expenditure tracking.
Variance decomposition across the projection horizon isolates volume, price, and mix effects within product type segmentation across turbines, compressors, gearboxes, and pumps, application segmentation across oil and gas, power generation, manufacturing, and aerospace, technology segmentation across electric, hydraulic, mechanical, and pneumatic architectures, and end user segmentation across Energy Companies, Industrial Plants, Marine, and Automotive buyers, with CAGRs derived from equipment replacement cycle analysis and regulatory mandate compliance timelines.
Underlying assumptions cover EPA Tier 4 emissions standard enforcement continuity, EU F-Gas Regulation phase-down schedules, and superalloy supply chain stability, with deviation risk concentrated in electrification substitution acceleration, carbon border adjustment mechanism implementation timing, and computational fluid dynamics talent scarcity extending turbine and compressor design recruitment timelines. Recalibration cycles align with material shifts in stationary engine efficiency mandates, hydrogen blending infrastructure deployment, and precision manufacturing technology qualification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mechanical and Electrical Services
MEP Services in US Market
Mechanical and Electrical Services
Diaphragm Coupling in Turbo Machinery Market
Mechanical and Electrical Services
Spur Gear Market
Mechanical and Electrical Services
Air Conditioning Repair Market
Mechanical and Electrical Services
Global Mechanical Electrical and Plumbing (MEP) Services Market
Mechanical and Electrical Services
US Electrical Services Market
Mechanical and Electrical Services
Pneumatic Cylinder Market
Mechanical and Electrical Services
Pressure Pumping Services Market